
 Citrus Molasses Market | 2026-2036
Citrus Molasses Market Size, Share, and Industry Trends Forecast 2026-2036
Citrus Molasses Market Outlook
Food-grade specification upgrades across the citrus molasses category is unwinding new premiumization pathways for processors. Citrosuco S.A. leverages its integrated crushing and refining footprint in Brazil to sustain high-purity output for pharmaceutical and food clients. Louis Dreyfus Company B.V. anchors global trading liquidity through its bulk handling infrastructure in Santos and Rotterdam. Cargill, Incorporated differentiates via backward integration into citrus peel oil and molasses co-processing, capturing value from waste streams that competitors leave unexploited.
Citrus molasses is a viscous, dark syrup produced as a byproduct of citrus juice extraction, containing fermentable sugars typically in the range of 45-60 percent total dissolved solids, and serves primarily as a cost-effective carbohydrate source for animal feed, industrial fermentation, and biofuel production. The product-type dimension shows orange molasses occupying the dominant volume position due to the scale of orange processing relative to lemon and lime, while lemon molasses commands tighter supply and correspondingly firmer pricing in flavoring-agent applications. Feed-grade material leads tonnage offtake but food-grade specifications concentrate margin pools, particularly where pharmaceutical and nutritional-supplement buyers enforce heavy-metal and pesticide-residue thresholds that few processors consistently meet.
The EPA's Renewable Fuel Standard and the FDA's food-additive safety frameworks jointly shape product qualification pathways for U.S.-bound shipments, with the former governing biofuel eligibility and the latter dictating permissible contaminants in food-grade lots. Brazil's Ministry of Agriculture (MAPA) enforces export-health certification that determines which crushing facilities may ship molasses to the European Union under EFSA-aligned import protocols. Stakeholders must monitor how tightening mycotoxin and pesticide-maximum-residue limits across overlapping jurisdictions will filter eligible suppliers and redirect procurement toward vertically integrated processors with in-house laboratory verification.
Market Dynamics
EPA's Renewable Fuel Standard classification of citrus molasses-derived ethanol as an advanced biofuel has locked in refinery offtake commitments, while São Paulo's processing cluster dominance concentrates supply-side leverage with Brazilian crushers.
Growth Catalysts
- Animal Feed Pelletization:Brazilian compounders are scaling citrus molasses purchases as a binding agent and carbohydrate source in pelleted rations for poultry and cattle operations.
- Advanced Biofuel Mandates:The EPA's Renewable Fuel Standard sustains refinery demand by granting advanced biofuel status to citrus molasses ethanol, qualifying it for compliance credits.
- Pharmaceutical-Grade Purity Standards:Food-grade specification upgrades are opening premium pathways for processors who meet heavy-metal and pesticide-residue thresholds enforced by FDA and EFSA-aligned protocols.
Market Restraints
- Sugar Price Volatility:Fermentable sugar feedstock costs fluctuate with Brazilian ethanol-sugar arbitrage decisions, compressing processor margins during cane harvest peaks.
- São Paulo Supply Concentration:Over seventy percent of global citrus molasses originates from orange processing clusters in a single Brazilian state, creating geographic single-point vulnerability.
- Lemon Molasses Supply Tightness:Limited lemon processing scale relative to orange crush volumes restricts flavoring-agent supply, constraining food manufacturers seeking citrus-derived alternatives to synthetic flavorants.
Strategic Opportunities
- European Union Import Protocols:MAPA-certified Brazilian facilities that align with EFSA mycotoxin standards can capture premium positioning in EU animal feed and fermentation markets.
- Co-Processing Integration:Citrus peel oil and molasses joint extraction technologies enable processors to monetize waste streams through backward integration into essential oil and pectin production.
- Direct-to-Pharma Distribution:Nutritional supplement manufacturers are bypassing commodity traders to contract directly with verified processors for heavy-metal-tested pharmaceutical-grade material.
Industry Challenges
- Laboratory Verification Capacity:Few crushing facilities maintain in-house pesticide and mycotoxin testing labs capable of meeting overlapping FDA, EFSA, and MAPA certification requirements simultaneously.
- Multi-Jurisdictional Compliance Timelines:Export-health certification processes for EU-bound shipments face procedural delays when Brazilian facilities lack pre-approved status under EFSA-aligned import protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Citrus Molasses Market |
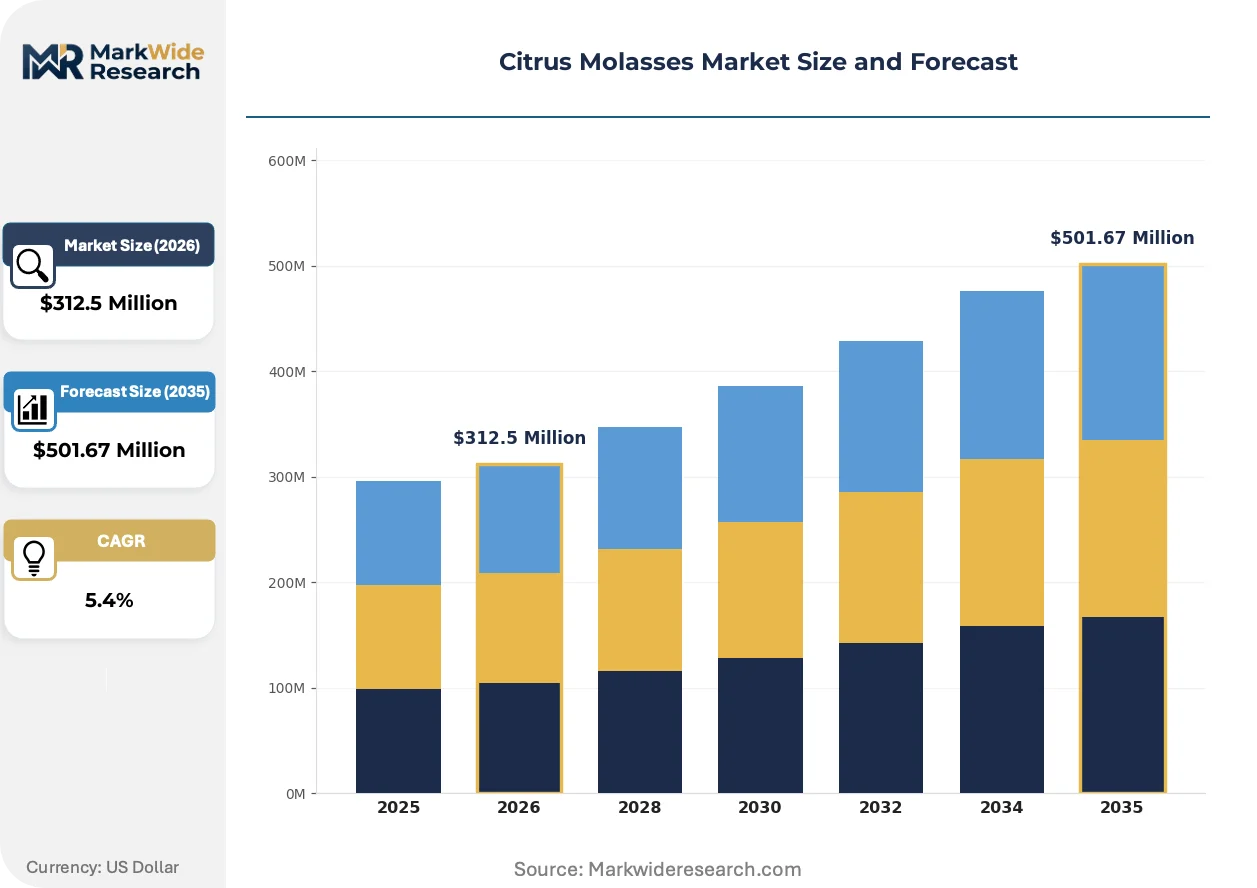
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citrus Molasses, Lemon Molasses, Orange Molasses, Lime Molasses End User: Food & Beverage, Pharmaceuticals, Agriculture, Cosmetics Grade: Food Grade, Feed Grade, Industrial Grade, Technical Grade Application: Sweeteners, Flavoring Agents, Nutritional Supplements, Preservatives |
| Companies Covered | Lemon Concentrate S.L., Louis Dreyfus Company B.V., Citrosuco S.A., Citromax Group, Sucocitrico Cutrale Ltd., Florida Crystals Corporation, Citrus and Allied Essences Ltd., Cargill, Incorporated, ADM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Citrus Molasses Market Strategic Shifts
Membrane filtration and enzymatic refining technologies are decomposing traditional separation methods, while regulatory tightening across biofuel and food-additive frameworks is redrawing qualification boundaries for market access.
Enzymatic hydrolysis systems for residual pectin and polysaccharide recovery are decomposing conventional waste-treatment economics in citrus processing facilities. Pharmaceutical and high-purity food manufacturers in Germany and Switzerland are adopting these systems to extract additional value from molasses streams. The technology is compressing unit costs for processors who previously discarded carbohydrate fractions to wastewater treatment.
REACH and EFSA are tightening pesticide maximum residue limits for imported feed and food additives entering European markets. Brazilian exporters must now demonstrate compliance with chlorpyrifos and glyphosate thresholds below legacy levels to maintain market access. Orange molasses shipments to Rotterdam and Hamburg are increasingly accompanied by third-party laboratory certificates verifying multi-residue screening.
Pharmaceutical buyers are consolidating supplier lists around vertically integrated processors with captive laboratory verification and direct shipping capabilities. Commodity traders in Santos and Rotterdam are losing share to processor-direct contracts as heavy-metal and mycotoxin documentation requirements intensify. This pattern is most pronounced in Swiss and German pharmaceutical procurement, where buyers now require batch-level certificates of analysis rather than annual compliance statements.
Citrus Molasses Market Segmentation
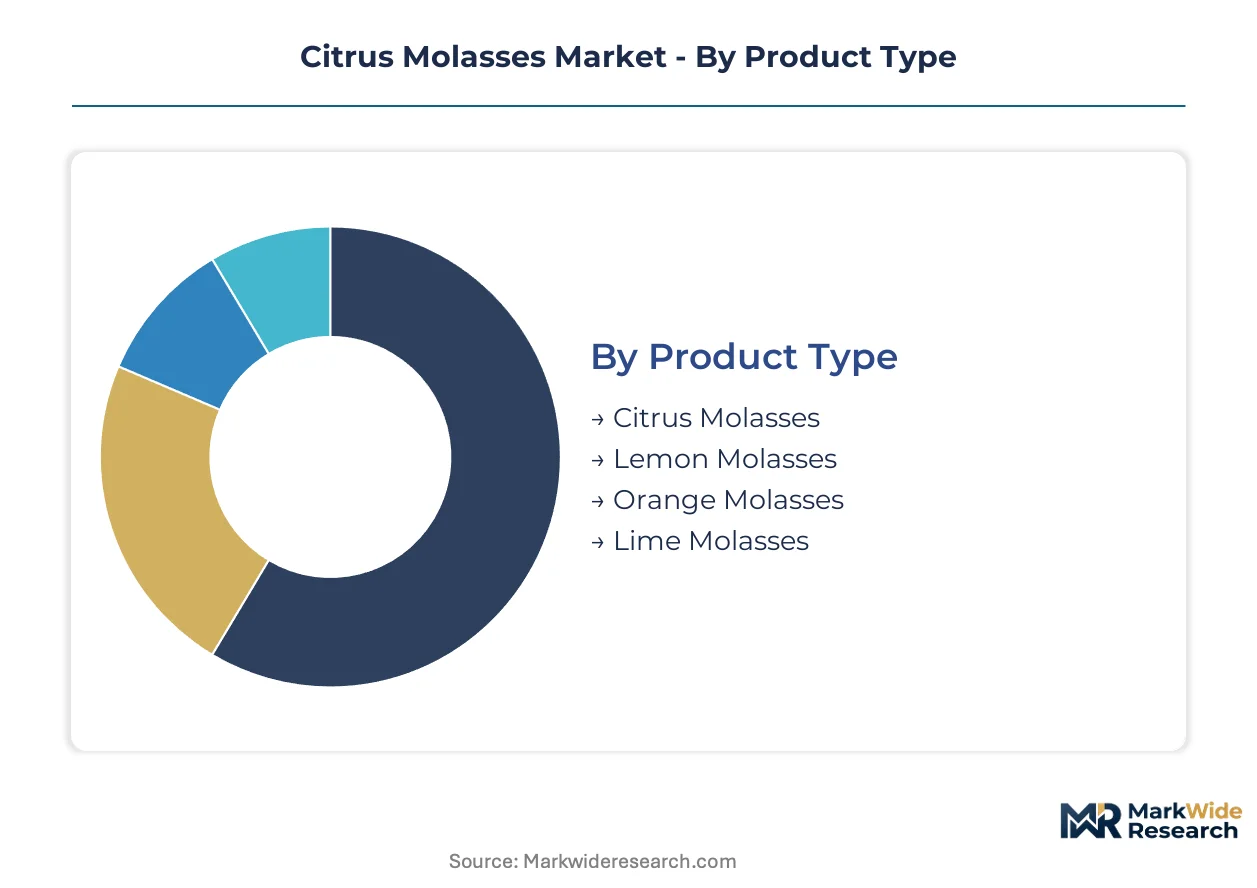
Segmentation in citrus molasses hinges on regulatory thresholds that partition commodity streams into distinct value pools. FDA food-additive safety frameworks and EPA biofuel classifications create qualification boundaries that determine which processors can access premium pricing tiers versus bulk feedstock markets.
Product Type:
EPA advanced biofuel eligibility and EFSA pesticide residue limits apply differentially across citrus varieties based on processing scale and contaminant profiles.
- Orange Molasses:Fermentable sugars range from 45-60 percent total dissolved solids in this viscous dark syrup derived from juice extraction byproduct. São Paulo processing clusters in Brazil generate the dominant global volume, with refinery offtake sustained by EPA Renewable Fuel Standard compliance credits for advanced biofuel production.
- Lemon Molasses:Tighter supply relative to orange crush volumes creates firmer pricing dynamics for this flavoring-agent feedstock. Swiss and German pharmaceutical manufacturers concentrate procurement here for heavy-metal-tested batches that meet batch-level certificates of analysis requirements.
- Lime Molasses:Restricted processing scale limits commercial availability to niche flavoring applications in beverage formulations.
- Citrus Molasses:Generic blended specification serves bulk industrial fermentation and animal feed pelletization where purity thresholds remain less stringent.
Established volume favors orange-derived material; emerging adoption favors lemon-derived material for pharmaceutical-grade applications.
End User:
Customer procurement patterns reveal a shift from commodity traders toward processor-direct contracts as documentation intensity escalates.
- Agriculture:Brazilian compounders scale purchases as binding agents and carbohydrate sources in pelleted poultry and cattle rations. MAPA-certified facilities capture premium positioning in EU feed markets through EFSA-aligned mycotoxin compliance.
- Pharmaceuticals:Nutritional supplement manufacturers bypass traders to contract directly with verified processors for heavy-metal-tested material. German and Swiss buyers now require batch-level certificates rather than annual compliance statements.
- Food & Beverage:Flavoring-agent applications face supply constraints from limited lemon processing scale relative to synthetic flavorant substitution demand.
- Cosmetics:Essential oil co-processing integration enables backward capture of value from waste streams in personal care formulations.
Feed-grade tonnage dominates current offtake; pharmaceutical-grade margins concentrate value capture fastest.
Grade:
Specification upgrades are unwinding new premiumization pathways as overlapping jurisdictions tighten permissible contaminant thresholds.
- Feed Grade:Standard carbohydrate source for animal nutrition where pesticide and heavy-metal thresholds remain less restrictive than food-additive frameworks. Brazilian export-health certification under MAPA determines EU market access eligibility.
- Food Grade:Heavy-metal and pesticide-residue thresholds enforced by FDA and EFSA-aligned protocols concentrate margin pools among processors with in-house laboratory verification. Few crushing facilities maintain simultaneous compliance capability across jurisdictions.
- Industrial Grade:Fermentation feedstock for biofuel production qualifies for EPA Renewable Fuel Standard advanced biofuel credits.
- Technical Grade:Non-consumable applications in industrial processes where purity specifications fall below pharmaceutical or food-additive requirements.
Feed-grade material leads current tonnage; food-grade specifications command expanding margin premiums.
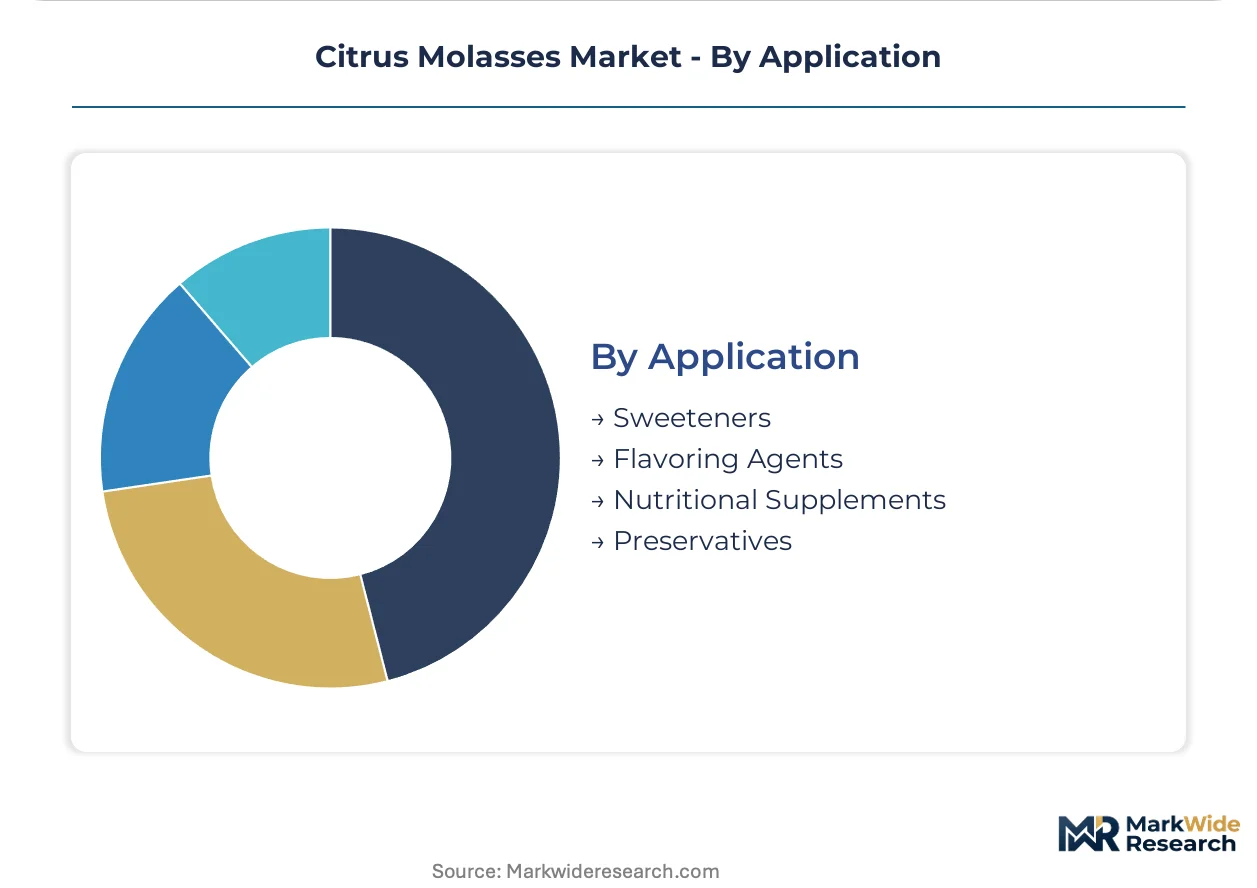
Application:
Functional use cases stratify across sweetness intensity, flavor profile specificity, and nutritional density requirements.
- Flavoring Agents:Lemon molasses supply tightness constrains food manufacturers seeking citrus-derived alternatives to synthetic flavorants. REACH and EFSA tightening of chlorpyrifos and glyphosate maximum residue limits demands third-party laboratory certificates for Rotterdam and Hamburg shipments.
- Nutritional Supplements:Pharmaceutical buyers consolidate supplier lists around vertically integrated processors with captive laboratory verification and direct shipping capabilities. Enzymatic hydrolysis systems for residual pectin recovery compress unit costs for high-purity manufacturers.
- Sweeteners:Cost-effective carbohydrate substitution in food formulations competes with cane sugar and corn syrup on fermentable sugar content.
- Preservatives:Natural antimicrobial properties from citrus-derived compounds find application in clean-label food preservation systems.
Flavoring applications face supply headwinds; nutritional supplement applications gain share fastest in premium procurement channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances tilt heavily toward Brazilian surplus, with São Paulo state crushing facilities supplying over seventy percent of internationally traded volume. Refinery offtake in the United States and pharmaceutical procurement in Switzerland and Germany absorb the bulk of seaborne shipments, while tightening EU residue standards filter eligible suppliers.
Brazil
São Paulo state processing clusters generate the dominant global supply of orange-derived molasses for animal feed pelletization and advanced biofuel production. MAPA export-health certification determines which crushing facilities may ship to European Union markets under EFSA-aligned import protocols. Citrosuco S.A. and Sucocitrico Cutrale Ltd. anchor supply concentration in the Araraquara and Bebedouro processing corridors.
United States
EPA Renewable Fuel Standard compliance credits sustain refinery demand for citrus molasses ethanol as an advanced biofuel classification. FDA food-additive safety frameworks dictate permissible contaminant thresholds for imported food-grade material entering pharmaceutical and nutritional supplement channels. Florida Crystals Corporation processes domestic citrus streams in the southern Florida growing belt for regional feed and fermentation markets.
Germany
Pharmaceutical and nutritional supplement manufacturers in Baden-Württemberg and Bavaria consolidate procurement around verified processors with batch-level certificates of analysis. REACH and EFSA tightening of chlorpyrifos and glyphosate maximum residue limits demands third-party laboratory verification for Rotterdam and Hamburg shipments. Enzymatic hydrolysis adoption concentrates in Swiss-border chemical processing zones for residual pectin recovery.
Switzerland
Nutritional supplement buyers in Basel and Zurich pharmaceutical corridors now require batch-level heavy-metal documentation rather than annual compliance statements. Swissmedic-aligned quality frameworks filter supplier eligibility toward vertically integrated processors with captive laboratory verification. Direct-to-pharma distribution contracts bypass commodity traders in Rotterdam and Santos.
Netherlands
Rotterdam bulk handling infrastructure anchors European trading liquidity for feed-grade citrus molasses entering continental animal feed compounders. Louis Dreyfus Company B.V. leverages port storage and blending capabilities to intermediate between Brazilian export terminals and EU destination markets. EFSA-aligned mycotoxin standards increasingly redirect procurement toward MAPA-certified facilities with pre-approved import protocol status.
Citrus Molasses Market Competitive Environment
Listed leaders compete with private specialists across integrated processing and trading dimensions, producing a tiered structure where scale-driven crushers coexist with niche flavoring-agent suppliers. Publicly held agribusiness conglomerates anchor volume positions in bulk feed and biofuel channels, while family-controlled citrus processors capture premium margins in pharmaceutical-grade segments. Three archetypes dominate: vertically integrated Brazilian crushers with captive laboratory verification, global trading houses with port infrastructure control, and specialty processors focused on lemon-derived flavoring agents. Competitive intensity centers on backward integration into peel oil co-processing and direct-to-pharma distribution bypassing commodity intermediaries.
Within the integrated Brazilian crusher tier, Citrosuco S.A. and Sucocitrico Cutrale Ltd. exemplify processors capturing value from waste streams through in-house refining and laboratory verification capabilities. Louis Dreyfus Company B.V. anchors trading liquidity archetypes with bulk handling infrastructure spanning Santos and Rotterdam. Cargill, Incorporated occupies a position representing agribusiness conglomerates with backward integration into citrus peel oil and molasses co-processing. Lemon Concentrate S.L. sits within specialty flavoring-agent suppliers serving constrained lemon molasses demand in European beverage and pharmaceutical formulations.
| Leading Market Players |
|---|
| Lemon Concentrate S.L. |
| Louis Dreyfus Company B.V. |
| Citrosuco S.A. |
| Citromax Group |
| Sucocitrico Cutrale Ltd. |
| Florida Crystals Corporation |
| Citrus and Allied Essences Ltd. |
| Cargill, Incorporated |
| ADM |
| Others |
Value Chain & Pricing Dynamics
Corn syrup substitution in Brazilian ethanol-gasoline blending mandates simultaneously redraws São Paulo processing economics and redirects citrus molasses toward premium feed and pharmaceutical channels. This input displacement tightens fermentable sugar feedstock arbitrage windows while elevating geographic concentration risk for buyers dependent on orange crush byproduct streams.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across feed-grade and pharmaceutical-grade tiers. Price differentiation separates MAPA-certified facilities with EFSA-aligned mycotoxin documentation from commodity spot suppliers lacking batch-level certificates. Cost compression in feed-grade segments is intensifying because Brazilian ethanol-sugar arbitrage decisions during cane harvest peaks squeeze processor margins. Animal feed compounders exhibit highest price sensitivity due to volume scale and carbohydrate substitutability, while Swiss and German pharmaceutical manufacturers show lowest sensitivity given heavy-metal certification requirements.
Supply Chain Analysis
Brazil, the United States, and the Netherlands anchor global citrus molasses supply through São Paulo crushing clusters, Florida processing corridors, and Rotterdam bulk handling infrastructure. Raw material flows draw from orange peel waste streams, lemon crush byproduct, and enzymatic hydrolysis recovery systems for residual pectin. Single-source vulnerability concentrates in São Paulo state, where over seventy percent of internationally traded volume originates from processing facilities within a narrow geographic corridor. Distribution runs through Santos export terminals to Rotterdam and Hamburg for European pharmaceutical and feed compounder offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The citrus molasses market is recovering from cyclical lows in sugar feedstock pricing, with Brazilian ethanol-gasoline arbitrage dynamics now stabilizing processor margin structures across the value chain.
For Market Incumbents: Secure backward integration into peel oil co-processing to capture value from waste streams that commodity traders leave unexploited. Deepen in-house laboratory verification capabilities for simultaneous FDA, EFSA, and MAPA compliance to defend against emerging processor-direct distribution threats from verified Brazilian facilities.
For New Entrants and Emerging Players: Lead with lemon molasses supply tightness as a white-space entry point, targeting Swiss and German pharmaceutical manufacturers seeking batch-level heavy-metal documentation. Exploit underinvestment in enzymatic hydrolysis systems for residual pectin recovery among legacy Brazilian crushers, positioning enzymatic refining technology as a differentiated cost-compression offering.
For Investors and Strategic Acquirers: EPA Renewable Fuel Standard reclassification risk reshapes the acquisition landscape for advanced biofuel eligibility assets. Long-term viability favors vertically integrated processors with captive laboratory verification and direct-to-pharma shipping capabilities rather than commodity trading intermediaries. Watch for EFSA chlorpyrifos and glyphosate maximum residue limit tightening as the signal indicating accelerated supplier consolidation toward MAPA-certified facilities with pre-approved import protocol status.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Peel Oil Co-Processing | Citrosuco and Cargill already monetize waste streams through joint extraction technologies that competitors forfeit. |
| Enzymatic Hydrolysis System Deployment | Residual pectin recovery compresses unit costs for German and Swiss pharmaceutical-grade manufacturers. |
| MAPA-Certified Laboratory Investment | In-house pesticide and mycotoxin testing enables simultaneous FDA, EFSA, and Brazilian export-health compliance. |
| Direct-to-Pharma Distribution Contracts | Nutritional supplement manufacturers in Basel and Zurich bypass Rotterdam commodity traders for verified processor relationships. |
| Long-Term Supply Agreement with Refinery Offtakers | EPA Renewable Fuel Standard advanced biofuel credits lock in predictable demand from U.S. fuel ethanol producers. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of MAPA export-health certification records, EFSA pesticide residue limit documentation, and EPA Renewable Fuel Standard classification filings. Interviews with Brazilian crushing facility plant managers, animal feed procurement leads at European compounders, pharmaceutical quality assurance directors in Germany and Switzerland, and Rotterdam bulk handling operators combined with customs trade data and SEC 10-K disclosures from listed agribusiness conglomerates. Bottom-up volume estimates from São Paulo processing clusters triangulate against top-down demand aggregation from refinery offtake and pharmaceutical procurement channels.
Segmentation dimensions modeled include citrus variety, end-use application, grade specification, and geographic regulatory cluster across the projection horizon. CAGRs derive from historical crush volume trends, ethanol-gasoline arbitrage elasticity, and pharmaceutical certification adoption curves. Forecast inputs incorporate Brazilian orange processing yield coefficients and enzymatic hydrolysis technology diffusion rates among European pharmaceutical manufacturers.
The analysis sits within stated boundaries; outcomes outside stable EPA advanced biofuel classification and EFSA residue limit trajectories would require recalibration. Forecasts reflect assumptions regarding São Paulo supply concentration persistence and pharmaceutical buyer consolidation toward verified processors. Recalibration cycles align with material shifts in Brazilian ethanol-sugar arbitrage decisions and EFSA chlorpyrifos and glyphosate threshold revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
D Psicose Market
Sweeteners
Non Sugar Sweeteners Market
Sweeteners
Turbinado Sugar Market
Sweeteners
Sugar Market
Sweeteners
Sweeteners Market
Sweeteners
Spain Food Sweetener Market
Sweeteners
Saccharin Market
Sweeteners
Brown Rice Syrup Market
Sweeteners
Canada Food Sweetener Market
Sweeteners
Monk Fruit Sugar Market
Sweeteners
Glucose Syrup Market
Sweeteners
Invert Sugar Market
Sweeteners
United States Food Sweetener Market
Sweeteners
India Food Sweetener Market
Sweeteners
Sugar Polyols Market
Sweeteners
China Food Sweetener Market