
 Spasticity Treatment Market | 2026-2036
Spasticity Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Spasticity Treatment Market Intelligence
Good Manufacturing Practice (GMP) certification, mandated by regulators like the US FDA and Europe's EMA, is reorganizing market access for spasticity treatments. This quality standard governs the production of both pharmaceuticals and medical devices, creating high entry barriers. Medtronic specializes in device-based solutions, notably its intrathecal baclofen pumps. Meanwhile, Ipsen leverages its deep expertise in botulinum toxin formulations for targeted muscle relaxation.
Spasticity treatment involves therapies aimed at reducing muscle stiffness and involuntary spasms caused by damage to the central nervous system. Interventions range from oral medications like Diazepam to targeted neurotoxins that inhibit nerve signals at a specific dosage. Botulinum toxin injections represent the fastest-growing product segment due to their efficacy and duration of action. Neurology clinics and specialty hospitals remain the primary end-user channels, capturing the majority of high-value procedures.
The US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) enforce stringent clinical trial protocols for new drug approvals. Concurrently, Health Canada and Australia's TGA set specific reimbursement and market access criteria for both drugs and devices. These regulations shape the competitive landscape by defining evidence requirements for market authorization. Success now depends on developing therapies that demonstrate clear clinical and economic value to payers and providers.
Market Dynamics
The convergence of stringent regulatory standards and a deeper understanding of neurological pathways is the central force shaping the spasticity treatment market. Quality mandates like Good Manufacturing Practice (GMP) are raising entry barriers, while clinical evidence requirements from the FDA and EMA prioritize therapies with demonstrable efficacy and safety profiles.
Growth Catalysts
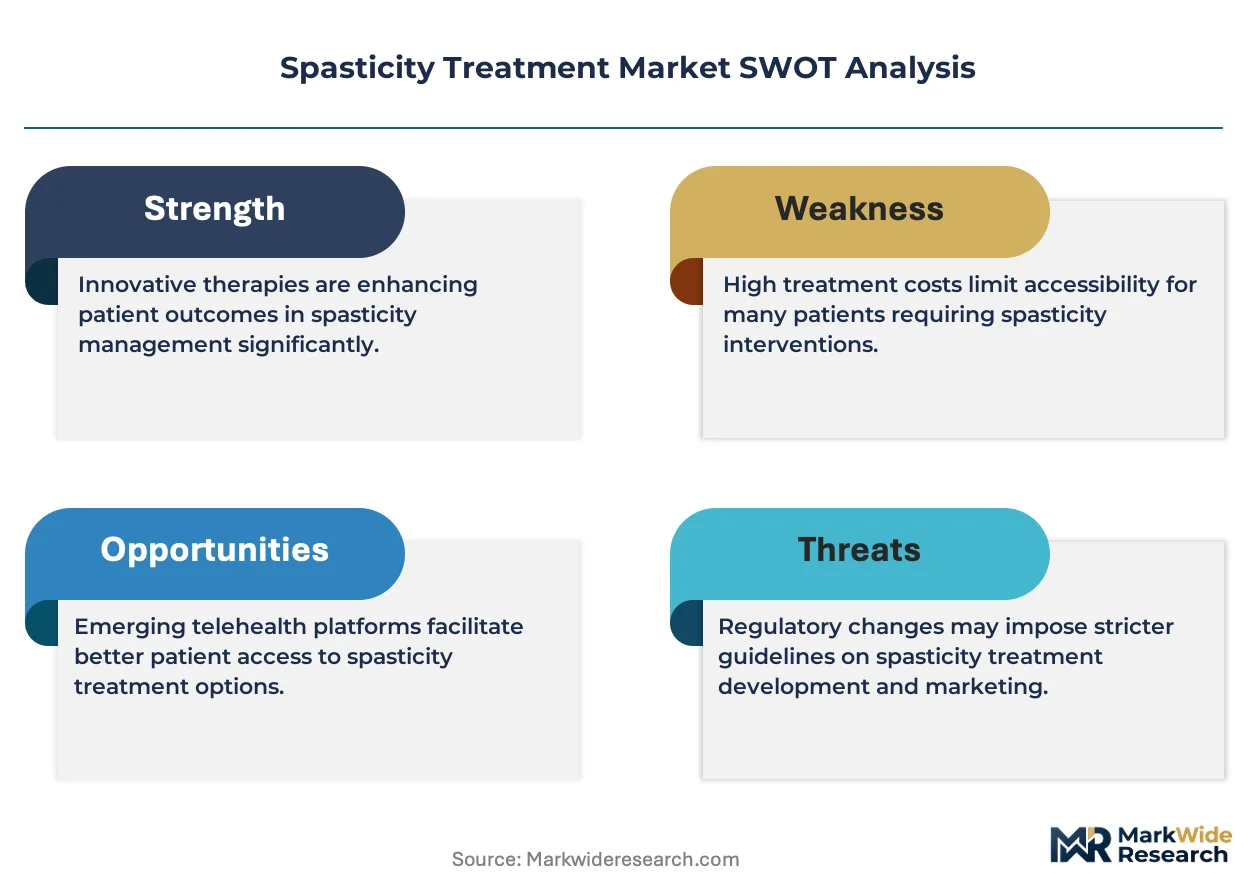
- Favorable Regulatory Incentives:The European Medicines Agency's orphan drug designation for certain spasticity-related conditions accelerates development timelines and provides market exclusivity, encouraging investment in treatments for smaller patient populations.
- Aging Demographics:An increasing elderly population in developed nations, particularly Germany, elevates the incidence of strokes and other neurological conditions, directly expanding the patient base requiring spasticity management in rehabilitation centers.
- Advancements in Rehabilitation Care:The growing network of specialized rehabilitation centers and neurology clinics is adopting more sophisticated treatment protocols, including targeted botulinum toxin injections and device-assisted therapies for post-stroke recovery.
Market Restraints
- High Treatment Costs:The significant expense associated with botulinum toxin therapies and implantable drug delivery systems, such as intrathecal baclofen pumps, restricts access for patients in markets with limited insurance coverage or reimbursement frameworks.
- Side Effects of Systemic Drugs:Oral medications like Diazepam can cause systemic side effects such as drowsiness and weakness, limiting their suitability for long-term spasticity management and creating a clinical need for more targeted alternatives.
- Stringent Clinical Protocols:Extensive and costly clinical trial requirements enforced by regulators like the US FDA delay the introduction of new drugs and devices, creating a substantial barrier for emerging companies.
Strategic Opportunities
- Emerging Market Penetration:Developing economies across Asia and Latin America represent significant growth potential as their healthcare infrastructure improves and awareness of advanced spasticity treatments increases among clinicians and patients.
- Combination Therapies:Integrating digital health tools for remote monitoring with implantable drug pumps offers a pathway to personalized, data-driven dosing regimens, improving patient outcomes and creating value for providers.
- Targeted Neurotoxin Development:Research into novel botulinum toxin serotypes and formulations presents an opportunity to develop products with unique diffusion characteristics and durations of action tailored to specific muscle groups or clinical scenarios.
Industry Challenges
- Specialized Clinician Training:The effective use of advanced treatments, including the precise administration of neurotoxin injections and surgical implantation of baclofen pumps, demands specialized skills, creating a training bottleneck for healthcare systems.
- GMP Compliance Burden:Achieving and maintaining GMP certification for pharmaceutical and device manufacturing facilities is a complex, capital-intensive process that can pose a significant operational challenge, particularly for smaller firms.
- Reimbursement Heterogeneity:Navigating the diverse and often complex reimbursement criteria for drugs and devices set by national payers, such as Health Canada and Australia's TGA, creates administrative hurdles for market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spasticity Treatment Market |
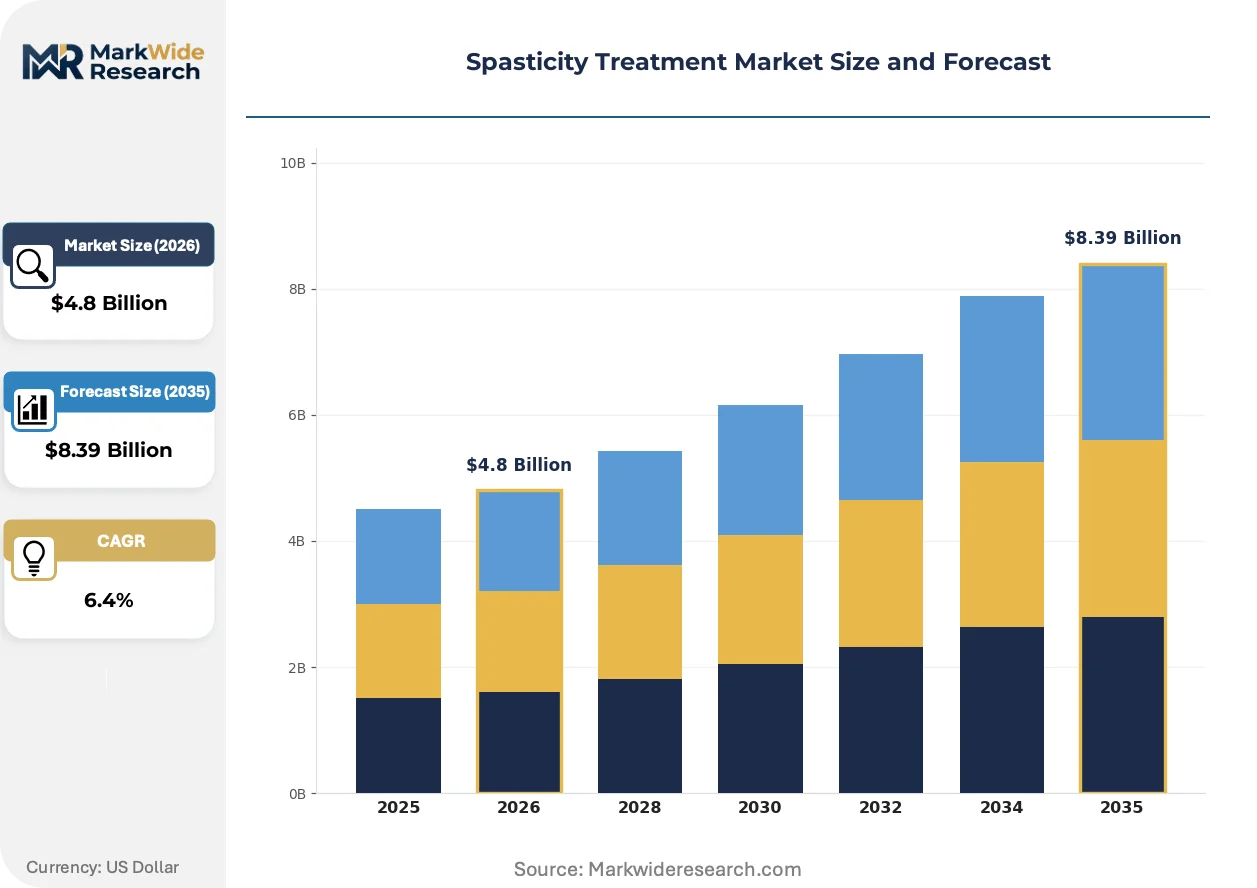
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Baclofen, Botulinum Toxin Injections, Intrathecal Baclofen Therapy, Diazepam, Tizanidine Therapy Area: Multiple Sclerosis, Cerebral Palsy, Stroke, Spinal Cord Injury, Traumatic Brain Injury End User: Neurology Clinics, Rehabilitation Centers, Home Care Settings, Specialty Hospitals, Outpatient Facilities Delivery Mode: Oral Administration, Intramuscular Injection, Intrathecal Pump, Physical Therapy, Occupational Therapy |
| Companies Covered | Ipsen, Allergan, Merz Pharma, Medtronic, AbbVie, F. Hoffmann-La Roche Ltd, Teva Pharmaceutical Industries Ltd, Sun Pharmaceutical Industries Ltd, Piramal Enterprises Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spasticity Treatment Market Strategic Shifts & Innovations
The market is pivoting from broad, systemic interventions toward highly specific and personalized therapeutic strategies. This evolution is propelled by advances in neurotoxin formulation and device-based delivery, which enable more precise targeting of affected neuromuscular junctions and better management of treatment outcomes.
Next-generation botulinum toxin formulations incorporate modified proteins to achieve unique clinical profiles. These agents are designed to offer differentiated diffusion patterns and durations of action for enhanced safety and efficacy. Neurology clinics are adopting these specialized neurotoxins for more precise treatment of focal spasticity in specific patient subgroups. This development of tailored biologics is fragmenting the previously uniform market for botulinum toxin into distinct segments based on clinical application.
The European Union's Medical Device Regulation (MDR) introduces more rigorous standards for market approval and surveillance. This policy mandates that manufacturers of devices like intrathecal baclofen pumps provide a higher level of clinical evidence and conduct more robust post-market follow-up. Device companies are most impacted, as they must now allocate significant resources to update technical documentation and conduct new studies to maintain CE marking for their products.
A clear shift toward value-based healthcare models is influencing treatment selection and provider compensation. This trend disrupts traditional fee-for-service reimbursement by rewarding therapies that demonstrate superior long-term patient outcomes and reduce overall healthcare utilization. The move is most visible within integrated care systems in the United States and parts of Europe, where payers increasingly tie financial incentives to clinical efficacy and cost-effectiveness.
Spasticity Treatment Market Segmentation
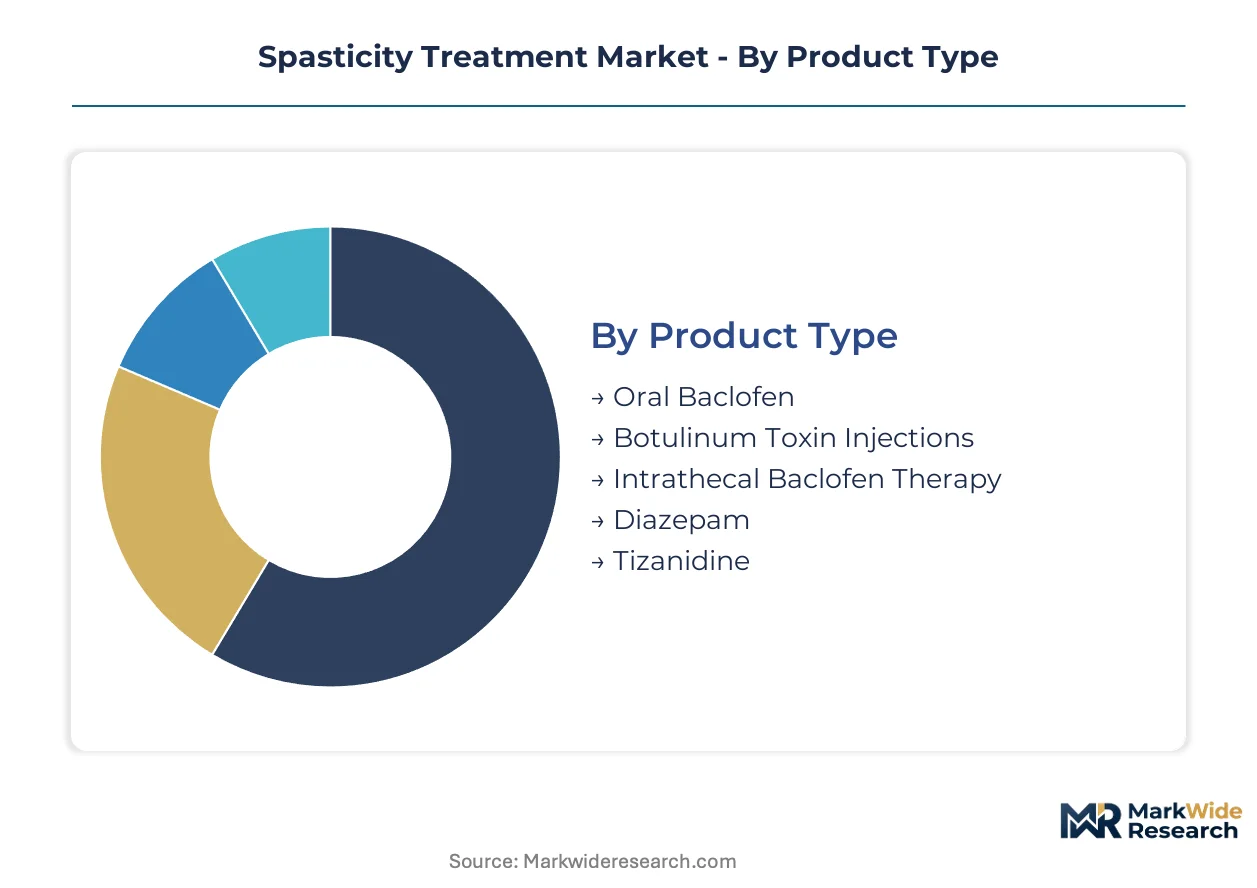
Segmentation reveals distinct therapeutic approaches and patient needs in spasticity treatment. This analysis highlights how product innovation and end-user preferences shape market dynamics. Understanding these segments is crucial for stakeholders to tailor strategies effectively across different care settings.
Product Type:
Margin pools within the product type segment often concentrate around specialized, high-efficacy interventions.
- Botulinum Toxin Injections:These neurotoxin formulations precisely target neuromuscular junctions, reducing focal spasticity. Demand for these injections is rapidly expanding in neurology clinics across Germany due to their proven efficacy and duration of action.
- Intrathecal Baclofen Therapy:This advanced treatment involves surgically implanting a pump that delivers baclofen directly into the spinal fluid. It is increasingly utilized in rehabilitation centers for severe, generalized spasticity, particularly for post-stroke patients in the United States.
- Oral Baclofen:This systemic medication reduces muscle tone by acting on GABA receptors in the central nervous system.
- Diazepam:A benzodiazepine, Diazepam offers muscle relaxant and sedative properties, commonly used for acute spasticity management.
- Tizanidine:This alpha-2 adrenergic agonist reduces spasticity by increasing presynaptic inhibition of motor neurons.
Oral Baclofen holds installed capacity. Botulinum Toxin Injections are rotating up the share rankings.
Therapy Area:
Application-specific demand drives innovation and resource allocation across different spasticity-related conditions.
- Stroke:Spasticity resulting from stroke often manifests as impaired motor control and muscle stiffness, particularly in upper and lower limbs. Rehabilitation centers in the United Kingdom prioritize targeted interventions for post-stroke patients to improve functional recovery.
- Cerebral Palsy:This neurological disorder, often diagnosed in childhood, causes persistent spasticity that affects movement and posture. Specialized pediatric neurology clinics in Canada focus on long-term management strategies for these patients.
- Multiple Sclerosis:Spasticity is a common symptom of multiple sclerosis, impacting mobility and quality of life for patients.
- Spinal Cord Injury:Spasticity below the level of injury is a significant challenge for individuals with spinal cord injuries.
- Traumatic Brain Injury:Patients recovering from traumatic brain injuries frequently experience spasticity, requiring comprehensive rehabilitation.
Treatment protocols for Stroke spasticity show significant maturity. Spinal Cord Injury treatments are expanding most quickly.
End User:
Volume of high-value procedures dictates the revenue distribution across different end-user channels.
- Neurology Clinics:These specialized outpatient facilities manage complex neurological conditions, including the precise administration of botulinum toxin injections. They capture a significant portion of high-value spasticity treatment procedures across Europe.
- Rehabilitation Centers:Focused on restoring function and improving patient independence, these centers are crucial for post-stroke and spinal cord injury patients. They integrate various therapies, including device-assisted solutions, in countries like Australia.
- Home Care Settings:Home care provides ongoing support and medication management for patients with chronic spasticity.
- Specialty Hospitals:These hospitals offer comprehensive inpatient care for severe spasticity, often involving surgical interventions.
- Outpatient Facilities:General outpatient facilities handle initial diagnoses and routine follow-up for less complex spasticity cases.
Neurology Clinics represent the largest segment by patient volume. Home Care Settings are gaining share fastest.
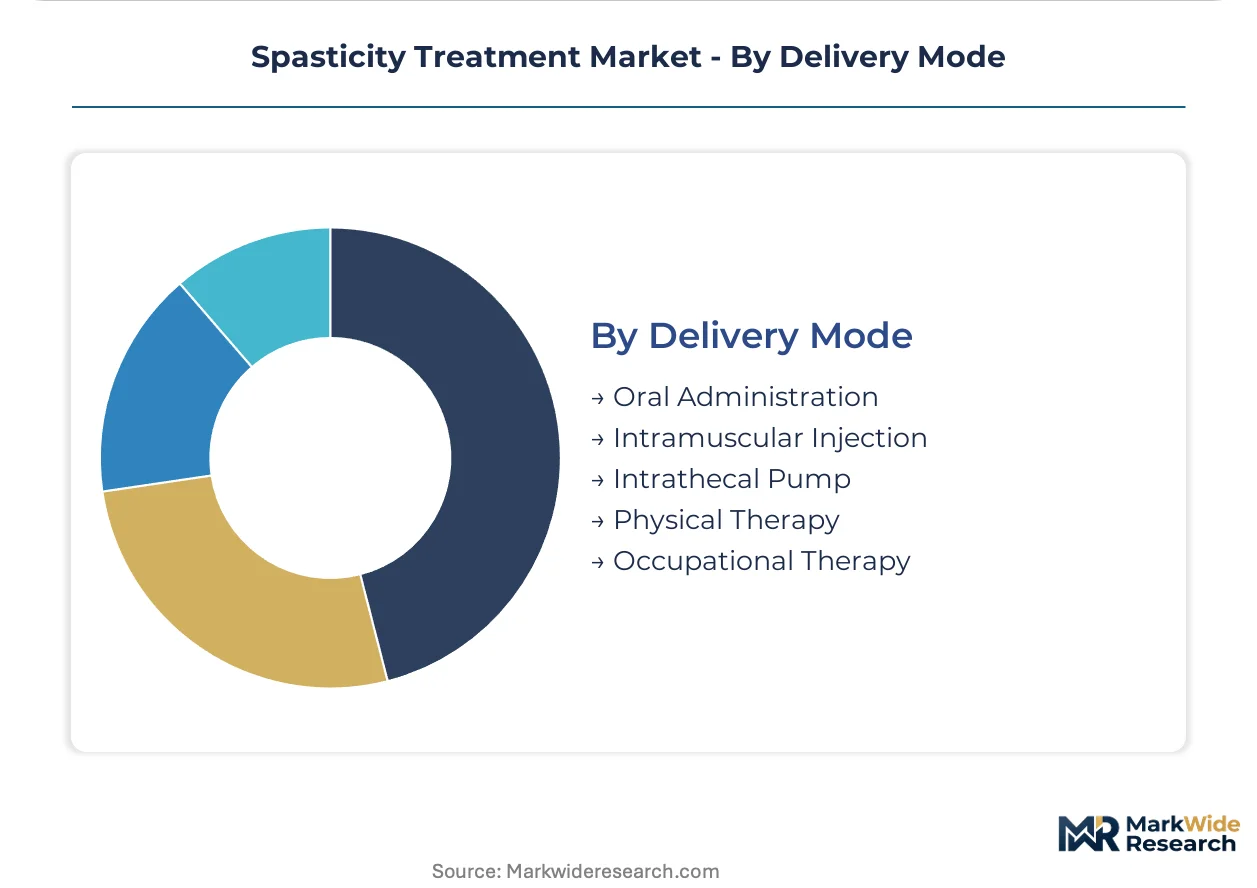
Delivery Mode:
The maturity of delivery modes influences patient convenience and therapeutic efficacy across the spasticity treatment continuum.
- Intramuscular Injection:This direct delivery method is primarily used for botulinum toxin, targeting specific spastic muscles with high precision. Its widespread use in clinics across France underscores its efficacy for focal spasticity.
- Intrathecal Pump:This advanced implantable device provides continuous, localized drug delivery to the spinal cord, offering superior control for severe generalized spasticity. It is a critical option for patients in the United States and Germany.
- Oral Administration:Oral medications offer systemic relief from spasticity, providing convenience for long-term management.
- Physical Therapy:Physical therapy plays a fundamental role in spasticity management, focusing on stretching, strengthening, and mobility.
- Occupational Therapy:Occupational therapy helps patients adapt to spasticity by teaching compensatory strategies for daily activities.
Oral Administration maintains a broad patient base. Intrathecal Pump delivery is climbing the fastest in adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neurology clinics and rehabilitation centers drive significant demand for spasticity treatments across developed economies. These specialized facilities focus on managing neurological conditions and post-stroke recovery, requiring advanced therapeutic solutions. Aging demographics and robust healthcare infrastructure further amplify patient volume in key markets.
United States
The United States exhibits strong demand for advanced spasticity treatments, particularly intrathecal baclofen therapy for severe generalized spasticity in post-stroke patients. The US FDA enforces stringent clinical trial protocols for new drug approvals, shaping market access. Integrated care systems in major metropolitan areas increasingly tie financial incentives to clinical efficacy and cost-effectiveness.
Germany
Germany demonstrates concentrated demand for spasticity treatments, driven by its advanced healthcare infrastructure and an aging demographic. The European Medicines Agency's orphan drug designation provides significant development incentives for certain conditions. Rehabilitation centers in Bavaria and North Rhine-Westphalia prioritize sophisticated treatment protocols, including targeted botulinum toxin injections.
United Kingdom
United Kingdom rehabilitation centers prioritize targeted interventions for post-stroke patients to improve functional recovery from spasticity. EMA regulations influence market approval and surveillance for drugs and devices within the European economic area. London and the Southeast feature numerous specialized clinics adopting advanced treatment protocols for neurological conditions.
Canada
Canada's market for spasticity treatment focuses on conditions like Cerebral Palsy, requiring long-term management strategies, especially in pediatric neurology clinics. Health Canada sets specific reimbursement and market access criteria for both drugs and devices. Specialized pediatric neurology clinics in Toronto and Montreal focus on comprehensive care for these patients.
Australia
Australia's rehabilitation centers are crucial for post-stroke and spinal cord injury patients, integrating various therapies including device-assisted solutions. Australia's TGA sets specific reimbursement and market access criteria for drugs and devices. Rehabilitation centers in Sydney and Melbourne adopt sophisticated treatment protocols for spasticity management.
Spasticity Treatment Market Key Industry Players
Player mix skews toward established pharmaceutical companies and specialized medical device manufacturers in the spasticity treatment market. The market structure exhibits a tiered approach, with a few large entities dominating key product segments. Strategic archetypes include neurotoxin specialists, implantable device innovators, and generic oral medication providers. Portfolio diversification and strategic partnerships represent dominant competitive moves among these players.
Within the neurotoxin specialist archetype, Ipsen and AbbVie exemplify companies leveraging deep expertise in botulinum toxin formulations for targeted muscle relaxation. Ipsen, with its established presence, focuses on expanding its formulations for diverse clinical scenarios. AbbVie, a significant player, also contributes to the botulinum toxin segment, supporting its broad pharmaceutical portfolio. Medtronic, on the other hand, anchors the implantable device innovator segment, specializing in solutions like intrathecal baclofen pumps. This Medtronic offering addresses severe, generalized spasticity, providing continuous drug delivery. These companies represent distinct yet complementary approaches to spasticity management, from targeted biologics to advanced device-based drug delivery systems, influencing the market's pivot towards specific and personalized therapeutic interventions.
| Leading Market Players |
|---|
| Ipsen |
| Allergan |
| Merz Pharma |
| Medtronic |
| AbbVie |
| F. Hoffmann-La Roche Ltd |
| Teva Pharmaceutical Industries Ltd |
| Sun Pharmaceutical Industries Ltd |
| Piramal Enterprises Ltd |
| Others |
Cost & Logistics Intelligence
Good Manufacturing Practice (GMP) certification gates both supply qualification and price differentiation for spasticity treatments. This stringent regulatory requirement ensures product quality, influencing market access and allowing premium pricing for compliant manufacturers. The complexity of production processes and the need for specialized facilities directly affect cost structures.
Pricing Analysis
Contract-based pricing, often indexed to clinical outcomes, dominates high-value spasticity treatments. Price differentiation stems from proven clinical efficacy and the duration of action for botulinum toxin injections, alongside the advanced technology and after-sales support for implantable pumps. Pricing pressure stems from integrated care systems and payers increasingly demanding value-based models. Patients with limited insurance coverage represent the most price-sensitive segment, while specialized neurology clinics prioritize clinical outcomes.
Supply Chain Analysis
Lead times for specialized components and active pharmaceutical ingredients are critical in the spasticity treatment supply chain. Supply concentrates in regions with advanced pharmaceutical manufacturing capabilities, such as Europe for neurotoxins and the United States for medical devices. Raw material dependencies include botulinum toxin strains and precision-engineered pump components. Regulatory hurdles for new formulations present a significant supply chain risk. Distribution runs through a network of specialty distributors and direct-to-hospital channels, ensuring controlled delivery of high-value products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spasticity treatment market is undergoing a platform-economics inflection, driven by the integration of digital health tools within integrated care systems. This shift enables personalized treatment protocols and remote patient monitoring, enhancing therapeutic outcomes.
For Market Incumbents:Consolidate market position by acquiring smaller biotech firms possessing novel neurotoxin formulations or advanced drug delivery technologies. Expand existing device-based therapy portfolios to counter emerging targeted therapies and regulatory scrutiny on systemic drugs. Invest heavily in R&D for combination therapies and specialized clinician training programs to maintain a competitive edge.
For New Entrants and Emerging Players:Service-layer gaps exist in personalized digital health platforms for remote spasticity monitoring and data-driven dosing adjustments. Target the underpenetrated home care settings and specific orphan conditions requiring highly specialized interventions. Partner with regional rehabilitation centers to develop integrated solutions, leveraging technology for improved patient access and adherence.
For Investors and Strategic Acquirers:The European Union's Medical Device Regulation (MDR) reshapes the acquisition landscape, favoring companies with robust clinical evidence and post-market surveillance capabilities. Focus on long-term viability by targeting niche biotech firms with strong intellectual property in next-generation neurotoxins or device manufacturers with established reimbursement pathways. A key signal to watch is the increasing number of EMA orphan drug designations for spasticity-related conditions.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market access for novel formulations, demonstrating enhanced efficacy and safety. |
| Regulatory Approval Pathway | Streamlines market entry for new devices and drugs, particularly with orphan designations. |
| Hospital System Partnership | Secures preferred provider status and expands patient reach for high-value procedures. |
| Software Companion Development | Enhances personalized dosing and remote monitoring for device-based therapies. |
| Reimbursement Strategy | Optimizes market penetration by aligning with value-based healthcare models and payer criteria. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted during the primary research phase. Interviews included neurologists, rehabilitation specialists, hospital administrators, and device engineers to gather qualitative insights and validate quantitative data. Secondary research encompassed analysis of FDA, EMA, and TGA filings, clinical trial registries, healthcare expenditure reports, and company annual reports, triangulating data points for accuracy.
The analytical framework modeled market dynamics across the analysis window using a blend of demand-supply forecasting and scenario analysis. Segmentation dimensions included product type, therapy area, end-user, delivery mode, and regional regulatory clusters. Compound annual growth rates were derived from historical trends, projected patient demographics, and anticipated technological adoption rates, with key inputs like stroke incidence and cerebral palsy prevalence.
Underlying assumptions cover healthcare policy stability and the pace of technological innovation, with deviation risk concentrated in unforeseen regulatory changes or shifts in reimbursement policies. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
CNS Treatment and Therapy Market
Neurology
Global Neuromarketing Market
Neurology
Moyamoya Disease Market
Neurology
Global Diabetic Neuropathy Treatment Market
Neurology
Hepatic Encephalopathy Market
Neurology
Multiple Sclerosis Therapies Market
Neurology
Vocal Cord Paralysis Market
Neurology
Arachnoiditis Treatment Market
Neurology
Neurological Biomarkers Market
Neurology
North America Traumatic Brain Injuries Assessment Market
Neurology
US Optic Neuritis Market
Neurology
Tourette Syndrome Market
Neurology
Nerve Repair Market
Neurology
Argentina Neurology Devices Market
Neurology
Central Nervous System (CNS) Therapeutics Market
Neurology
China Neurology Devices Market