
 Europe Pasta Sauce Market | 2026-2036
Europe Pasta Sauce Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pasta Sauce Market Intelligence
EU Green Deal packaging mandates is pivoting the cost-of-entry calculus toward recyclable jar and Tetra Pak formats. Barilla S.p.A. leverages its Parma production base to anchor premium tomato sauce supply across Southern Europe. Saclà differentiates through specialized pesto manufacturing using Genovese DOP basil. Premier Foods plc sustains UK retail shelf presence through broad distribution channel control.
Europe pasta sauce comprises cooked and emulsified vegetable, dairy, or oil-based preparations with acidity levels typically below pH 4.6 for ambient stability, serving as the primary flavor and moisture component in pasta dishes across retail and food service channels. Tomato sauce occupies the largest volume share given its universal menu application, while pesto commands premium positioning through protected-origin ingredient requirements. The food service distribution channel generates concentrated margin pools as restaurant chains standardize procurement around bulk pouch formats.
EFSA sodium-reduction benchmarks, EU Packaging and Packaging Waste Regulation, and Italy's DOP certification framework collectively shape reformulation priorities and label claims across the category. REACH compliance for food-contact materials adds testing layers for glass jar coatings and pouch laminates. Stakeholders must monitor how Ecodesign for Sustainable Products Regulation implementation redefines acceptable packaging formats before compliance deadlines crystallize.
Market Dynamics
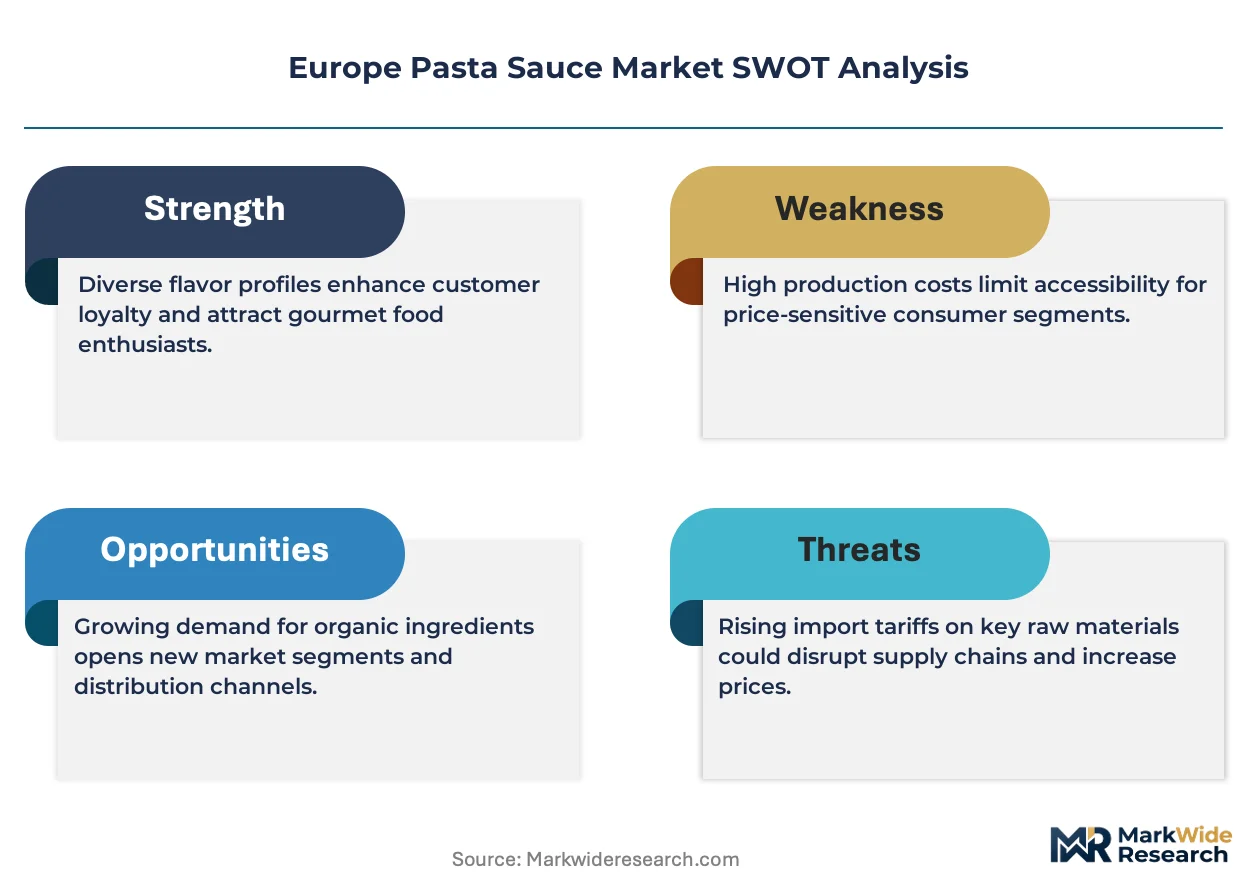
Private-label expansion by German and French supermarket chains is compressing branded shelf space while EFSA sodium-reduction mandates force simultaneous reformulation investment, creating margin pressure across mid-tier producers.
Growth Catalysts
- EU Green Deal packaging mandates:Recyclable jar and Tetra Pak formats are unlocking retail listings previously restricted to conventional glass, expanding format-accessible channels for compliant manufacturers.
- Italy's DOP certification framework:Protected-origin basil and tomato designations command price premiums in export markets, incentivizing supply-base investment in Genoa and Parma growing regions.
- Food service bulk pouch adoption:Restaurant chain procurement standardization around ambient-stable pouch formats is displacing frozen sauce alternatives in institutional catering contracts.
Market Restraints
- Tomato input cost volatility:Southern European drought cycles and energy-intensive greenhouse heating in Northern Europe create margin unpredictability for sauce producers dependent on fresh paste supply.
- Glass jar supply concentration:Container manufacturing clusters in Italy and Spain face energy cost spikes under EU ETS carbon pricing, transmitting cost pressure downstream to sauce packagers.
- REACH compliance friction:Food-contact material testing requirements for jar coatings and pouch laminates extend new product development timelines by 8-12 months for reformulated packaging.
Strategic Opportunities
- Eastern European retail underpenetration:Poland and Romania exhibit per-capita pasta sauce consumption at 40% of Italian levels, presenting volume expansion potential for ambient-stable premium formats.
- Ecodesign for Sustainable Products Regulation preparation:Early compliance investment in mono-material pouches positions manufacturers for 2030 mandatory recyclability thresholds before competitors adapt.
- Plant-based dairy sauce convergence:Cashew-based Alfredo and oat-cream formulations are capturing lactose-intolerant and flexitarian segments previously served only by conventional dairy sauces.
Industry Challenges
- Clean-label formulation expertise scarcity:Sodium reduction without potassium chloride aftertaste requires flavor chemistry specialization that outpaces current food science graduate pipeline capacity.
- Legacy retort line retrofitting:Transitioning from glass to pouch formats demands seven-figure capex for aseptic filling equipment that conflicts with depreciation schedules on existing jar lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pasta Sauce Market |
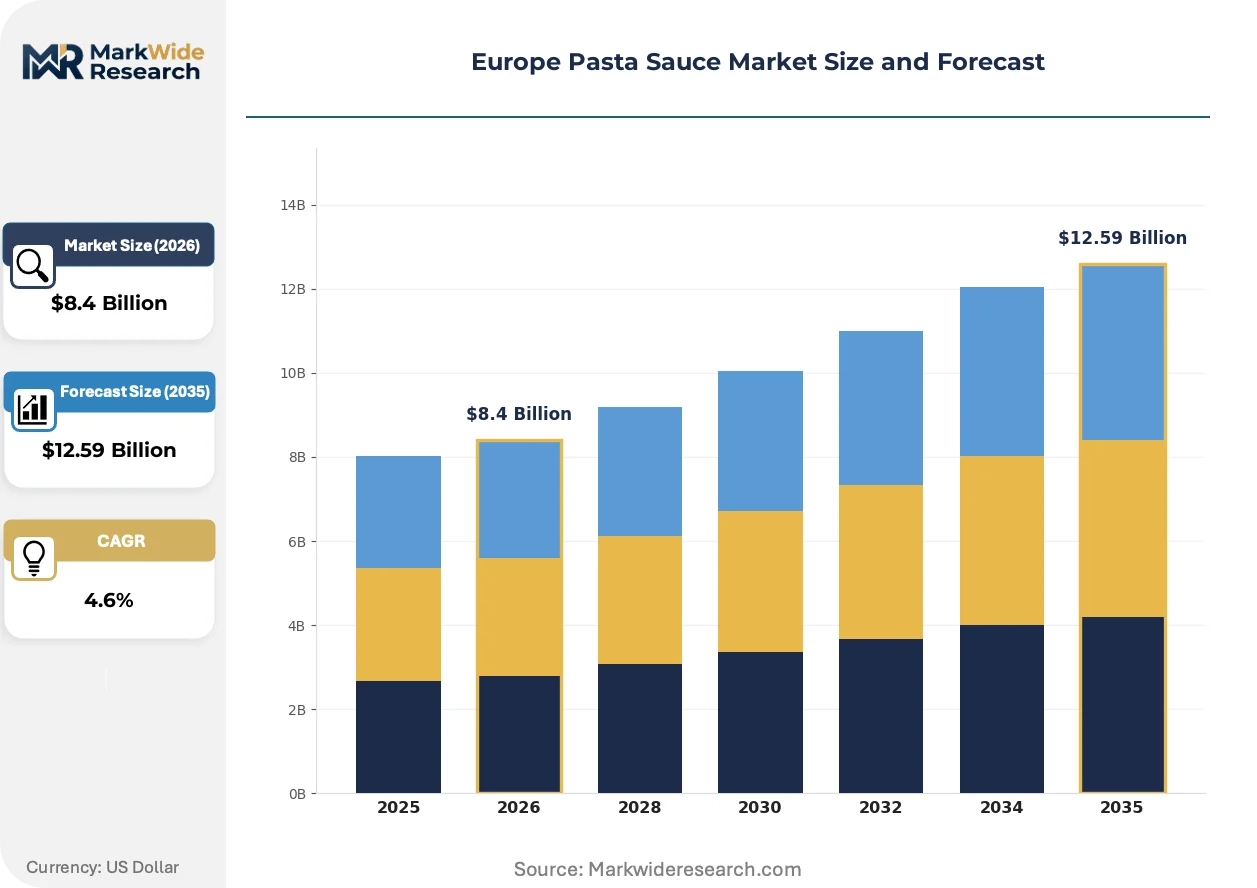
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.59 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tomato Sauce, Pesto, Cream Sauce, Alfredo Sauce Packaging Type: Jar, Bottle, Pouch, Tetra Pak Distribution Channel: Supermarket, Online Retail, Convenience Store, Food Service Price Tier: Premium, Mid-Range, Budget, Organic |
| Companies Covered | Premier Foods plc, Ebro Foods S.A., Barilla S.p.A., Saclà, Del Monte Foods Inc., The Kraft Heinz Company, Conagra Brands Inc., Mars Incorporated, Mizkan Holdings Co. Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pasta Sauce Market Strategic Shifts & Innovations
High-pressure processing and aseptic cold-fill technologies are extending clean-label sauce shelf life without thermal degradation, enabling premium positioning that thermal processing previously compromised.
HPP technology is integrating into pesto and fresh sauce manufacturing to preserve volatile aromatic compounds in Genovese basil. Premium Italian producers are adopting cold-chain distribution partnerships with Northern European retailers. This technology is integrating premium fresh sauces into supermarket refrigerated sections previously dominated by ambient jarred alternatives.
EFSA sodium-reduction benchmarks are mandating reformulation across all tomato sauce SKUs above 400mg sodium per 100g. Manufacturers are deploying umami-enhancing yeast extracts and tomato concentrate blending to maintain palatability. Southern European producers face the steepest compliance curves given traditional recipe salt levels.
Direct-to-restaurant procurement platforms are displacing traditional food service distributors for mid-size independent pasta chains. Digital ordering portals with dynamic pricing are capturing 15-20% volume share in urban UK and French markets. This channel shift concentrates most rapidly in metropolitan areas with high restaurant density and established last-mile cold-chain infrastructure.
Europe Pasta Sauce Market Segmentation
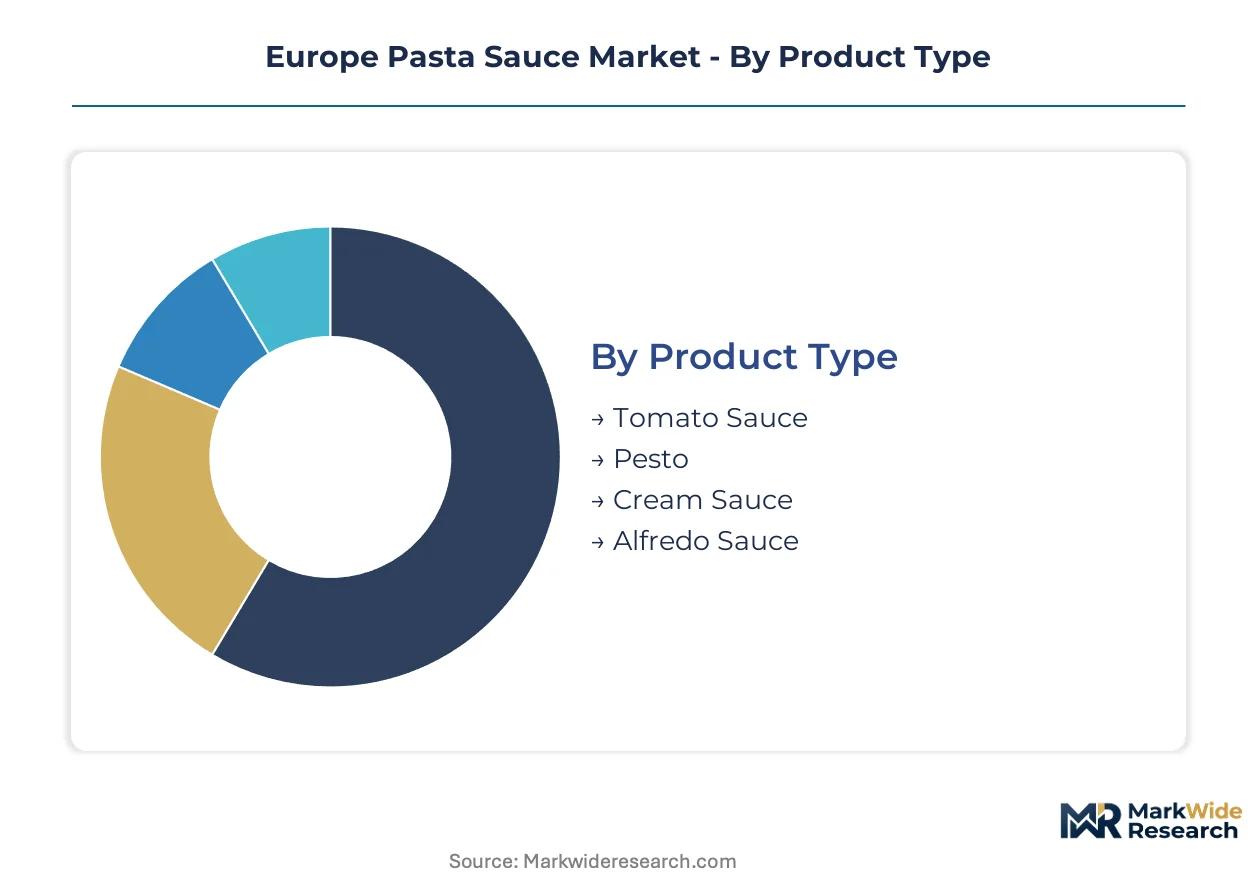
Segmentation in the Europe Pasta Sauce Market reveals how regulatory frameworks and distribution economics partition value capture. EFSA sodium thresholds, EU Green Deal packaging mandates, and DOP certification requirements create divergent compliance burdens across product and packaging configurations.
Product Type:
EFSA clean-label guidelines and Italy's DOP certification framework impose distinct reformulation and sourcing obligations on each product category, with protected-origin designations requiring documented supply chain traceability.
- Tomato Sauce:Acidified vegetable preparation typically below pH 4.6 for ambient stability, formulated from tomato paste, olive oil, and aromatics. Demand concentrates in Italian retail and food service channels where per capita pasta consumption sustains category depth; EFSA sodium-reduction benchmarks force umami-enhancing ingredient investments.
- Pesto:Emulsified sauce of Genovese DOP basil, pine nuts, Parmigiano-Reggiano, and olive oil requiring documented provenance for protected-origin claims. Export markets in Germany and France absorb premium-priced SKUs; DOP certification mandates create supply-base concentration around Ligurian growing regions.
- Cream Sauce:Dairy-based emulsion with butter, cream, and cheese requiring refrigerated or UHT processing for safety.
- Alfredo Sauce:Parmesan and butter-based preparation popular in Northern European markets with lower traditional pesto penetration.
Leading the category by volume: Tomato Sauce. Growing fastest: Pesto.
Packaging Type:
EU Packaging and Packaging Waste Regulation and Ecodesign for Sustainable Products Regulation are redefining acceptable formats, with recyclability thresholds elevating capex requirements for jar and pouch lines differently.
- Jar:Glass container with metal lug closure, dominant in Italian retail for premium positioning and traditional consumption rituals. Container manufacturing clusters in Italy and Spain face EU ETS carbon pricing pressure; energy cost spikes transmit downstream to sauce packagers.
- Pouch:Multi-layer or mono-material flexible format displacing frozen alternatives in food service procurement. Restaurant chain standardization around ambient-stable bulk pouches drives institutional catering adoption; REACH compliance for food-contact laminates extends development timelines.
- Bottle:PET or glass format common in German and French mass-market retail.
- Tetra Pak:Aseptic carton format gaining retail listings under EU Green Deal recyclability mandates.
Highest volume concentration: Jar. Steepest expansion trajectory: Pouch.
Distribution Channel:
Channel economics fragment by service level requirements, with food service demanding bulk formats and direct-to-restaurant platforms compressing traditional distributor margins.
- Supermarket:Branded and private-label shelf presence across Italy, Germany, and France with expanding retailer-controlled ranges. German and French chains compress branded space while capturing budget-conscious shoppers; slotting fees and promotional calendars dominate trade terms.
- Food Service:Bulk procurement by restaurant chains and institutional caterers standardizing around pouch formats. Digital ordering portals capture urban UK and French metropolitan volume; last-mile cold-chain infrastructure requirements concentrate growth in high restaurant-density cities.
- Online Retail:Direct-to-consumer and marketplace fulfillment gaining share in premium and subscription segments.
- Convenience Store:Small-format urban retail for immediate consumption and emergency replenishment.
Deepest volume: Supermarket. Gaining share fastest: Food Service.
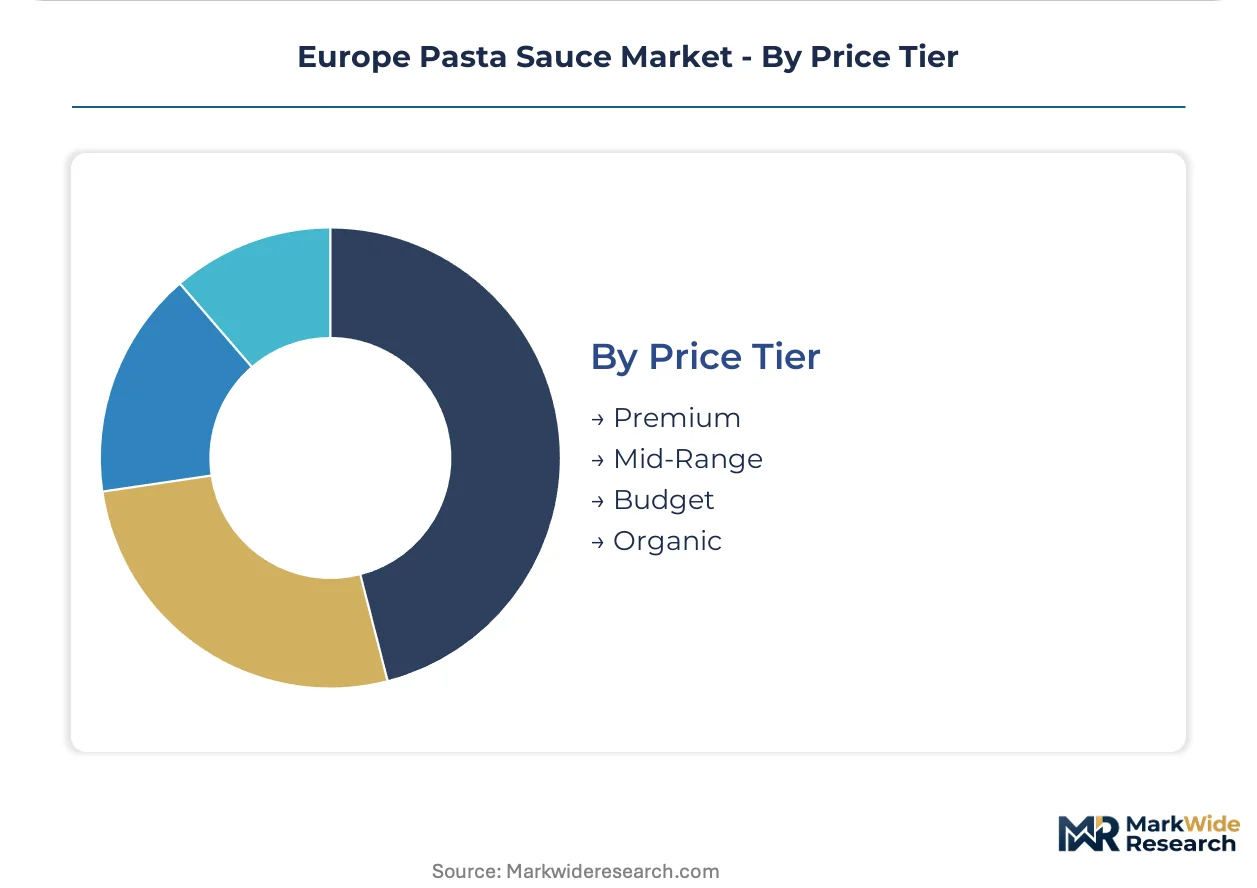
Price Tier:
Pricing stratification reflects ingredient provenance, certification status, and packaging format premiums, with organic and DOP designations commanding shelf price multiples.
- Premium:DOP-certified pesto, small-batch tomato sauces, and specialty regional recipes. Genovese basil and Parma tomato provenance justify price positioning; export markets in Northern Europe absorb transport cost premiums.
- Organic:EU organic regulation-compliant ingredients with documented supply chain audit trails. Consumer willingness to pay certification premiums sustains margin pools; input cost volatility in organic tomato supply creates pricing instability.
- Mid-Range:Mass-market branded offerings balancing quality cues with accessibility.
- Budget:Private-label and economy formulations competing on unit price in promotional cycles.
Largest revenue pool: Premium. Expanding most quickly: Organic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Parma's agro-industrial zone concentrates tomato processing capacity under Italy's DOP certification framework, drawing sauce manufacturers toward Emilia-Romagna's established supply chains. EFSA sodium-reduction mandates and EU Green Deal packaging rules reshape investment priorities across the region's production clusters.
Italy
Per capita pasta consumption sustains the deepest sauce category penetration in Europe, with Parma and Naples anchoring tomato paste production. EFSA clean-label guidelines force reformulation of traditional recipes toward reduced-sodium profiles. Genoa's basil-growing cooperatives supply DOP-certified raw material for premium pesto exports to Northern Europe.
Germany
Discount supermarket chains expand private-label ranges to capture budget-conscious shoppers across Bavaria and North Rhine-Westphalia. EU Packaging and Packaging Waste Regulation accelerates adoption of recyclable Tetra Pak formats in Berlin and Hamburg retail channels. Stuttgart-based food technologists develop umami-enhancing yeast extracts for sodium-reduced formulations.
France
Premium pesto demand concentrates in Paris and Lyon metropolitan retail, absorbing Ligurian DOP supply at price multiples above mass-market tomato sauces. ANSM food-contact material standards extend testing timelines for glass jar coatings. Marseille's port infrastructure handles bulk tomato paste imports from Southern European processing zones.
United Kingdom
Premier Foods plc maintains retail shelf presence through broad distribution channel control across England and Scotland. Food Standards Agency salt-reduction targets align with EFSA benchmarks, pressuring reformulation of mid-tier tomato sauce SKUs. London's food service procurement platforms capture 15-20% volume share in urban restaurant chains.
Poland
Per-capita pasta sauce consumption runs at 40% of Italian levels, presenting volume expansion potential for ambient-stable premium formats. EU structural funds support cold-chain infrastructure development in Warsaw and Kraków retail networks. Poznań's food processing clusters attract Italian manufacturers seeking Eastern European manufacturing footholds.
Europe Pasta Sauce Market Key Industry Players
Italian producers anchor one tier through DOP-certified heritage positioning; Anglo-Dutch conglomerates hold scale-driven mass-market penetration. The vendor base fragments across three tiers: protected-origin specialists, multinational branded portfolios, and retailer-controlled private labels. Strategic archetypes include provenance-anchored premium players, private-label contract manufacturers, and food service bulk suppliers. Competitive moves concentrate on format diversification toward pouches and direct-to-restaurant platform partnerships.
Within the heritage-provenance tier, Barilla S.p.A. and Saclà exemplify DOP-anchored positioning, while Premier Foods plc occupies a position bridging branded retail and private-label contract supply. These three entities represent distinct competitive archetypes: Parma-based tomato sauce heritage, Genovese pesto specialization, and UK-centric distribution control. Their collective presence illustrates how geographic origin certification, regional ingredient sourcing, and channel dominance create defensible market positions under EFSA and EU Green Deal compliance frameworks.
| Leading Market Players |
|---|
| Premier Foods plc |
| Ebro Foods S.A. |
| Barilla S.p.A. |
| Saclà |
| Del Monte Foods Inc. |
| The Kraft Heinz Company |
| Conagra Brands Inc. |
| Mars Incorporated |
| Mizkan Holdings Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Tomato paste input costs cascade through three distinct pricing tiers, with Parma and Naples processing clusters transmitting energy and agricultural volatility downstream to German discount retailers and French premium buyers. EFSA sodium-reduction mandates and EU ETS carbon pricing on Italian glass manufacturing compound reformulation and packaging expenses that concentrate margin pressure on mid-range branded producers.
Pricing Analysis
Short lead-time premiums attach to DOP-certified pesto shipments from Genoa, while spot inventory of conventional tomato sauce clears at discounted rates through Eastern European wholesale channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification status, provenance documentation, and packaging format premiums. Pricing pressure stems from private-label expansion compressing branded shelf space in German and French supermarket chains. Budget private-label buyers exhibit highest price sensitivity; DOP-certified premium purchasers show lowest elasticity.
Supply Chain Analysis
EFSA clean-label certification and Italy's DOP framework gate supplier qualification, concentrating approved basil and tomato sources around Ligurian and Emilia-Romagna growing regions. Geographic supply concentrates in Italy, Spain, and Germany for processing and packaging inputs. Raw material dependencies include Genovese DOP basil, San Marzano tomatoes, and pine nuts from Mediterranean suppliers. Single-source vulnerability runs through concentrated glass jar manufacturing clusters facing EU ETS energy cost spikes. Distribution runs through supermarket central warehouses, food service procurement platforms, and direct-to-restaurant digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aseptic cold-fill and high-pressure processing technologies are displacing legacy thermal retort systems, forcing capital reallocation toward extended shelf-life capabilities without thermal degradation.
For Market Incumbents: Deploy backward integration into Genovese DOP basil cooperatives to secure supply-base control against emerging premium competitors. Accelerate mono-material pouch line investments ahead of Ecodesign for Sustainable Products Regulation deadlines. Saclà's pesto specialization and Barilla's Parma production base demonstrate how provenance-anchored positioning defends margin pools against private-label encroachment. For New Entrants and Emerging Players: Capture Eastern European retail underpenetration in Poland and Romania where per-capita consumption trails Italian benchmarks. Plant-based dairy sauce segments present white-space opportunity for cashew-based Alfredo and oat-cream formulations targeting lactose-intolerant demand. Direct-to-restaurant procurement platforms in London and Paris offer channel entry with lower slotting-fee barriers than supermarket retail. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier branded manufacturers in Italy facing simultaneous private-label compression and reformulation capex burdens. Long-term viability hinges on format diversification toward pouches and HPP-enabled fresh sauce capabilities. Watch Ecodesign regulation enforcement timelines as inflection indicator for packaging format winners.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Pouch Conversion | Early compliance with EU Ecodesign thresholds secures retail listings before mandatory deadlines crystallize. |
| HPP Technology Integration | Cold-fill capabilities preserve volatile aromatic compounds in Genovese basil for premium refrigerated positioning. |
| DOP Supply-Base Investment | Documented provenance traceability commands price multiples in German and French export markets. |
| Direct-to-Restaurant Platform Partnership | Digital procurement portals capture urban food service volume with compressed distributor margins. |
| Sodium-Reduced Reformulation | Umami-enhancing yeast extracts maintain palatability under EFSA benchmark compliance without potassium chloride aftertaste. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with Italian sauce manufacturers, German supermarket category buyers, French food service procurement directors, and EFSA regulatory affairs specialists. Secondary sources included EU Packaging and Packaging Waste Regulation implementation documents, EFSA sodium-reduction benchmark guidelines, Italy's DOP certification registry, and customs import records for tomato paste and pine nut flows. Bottom-up volume builds across product and packaging segments triangulated against top-down category expenditure estimates.
Data-stream reconciliation aligned production capacity disclosures from Emilia-Romagna processing clusters with retail audit movement from German and French supermarket channels. Segmentation dimensions modeled encompassed product type, packaging format, distribution channel, and price tier across the projection horizon. CAGRs derived from trend extrapolation of per-capita consumption patterns, regulatory compliance timelines, and format substitution elasticities. Forecast inputs included Ecodesign implementation schedules, REACH food-contact material testing timelines, and cold-chain infrastructure development in Eastern European markets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal packaging mandate enforcement, tomato input cost volatility from Southern European drought cycles, and food service procurement platform adoption rates. Forecasts reflect documented assumptions on regulatory compliance deadlines and technology substitution curves. A model refresh is warranted upon material change in Ecodesign secondary legislation or EFSA sodium threshold revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Barbecue Sauce Market
Condiments & Sauces
Compound Condiments Market
Condiments & Sauces
Mayonnaise Market
Condiments & Sauces
Egg-Free Mayonnaise Market
Condiments & Sauces
Vegan Pasta Sauce Market
Condiments & Sauces
Sauces, Condiments, and Dressings Market
Condiments & Sauces
Cooking Sauces Market
Condiments & Sauces
Pesto Sauces Market
Condiments & Sauces
Latin America Pasta Sauce Market
Condiments & Sauces
Hoisin Sauce Market
Condiments & Sauces
Sauce Market
Condiments & Sauces
Table Sauce Market
Condiments & Sauces
Europe Hot Sauce Market
Condiments & Sauces
Salad Dressings Market
Condiments & Sauces
Mayonnaise Sauce Market
Condiments & Sauces
Sour Dressings Market