
 Mayonnaise Market | 2026-2036
Mayonnaise Market Size, Share, and Industry Trends Forecast 2026-2036
Mayonnaise Market Intelligence
Recipe licensing and co-manufacturing partnerships is consolidating how proprietary emulsion formulations reach regional markets. Unilever leverages its global procurement network to secure vegetable oil supply chains across multiple continents. Duke's Mayonnaise sustains brand loyalty through cult-following status in the southeastern United States. Ken's Foods competes in food service channels with portion-control packaging and institutional distribution.
Mayonnaise is an oil-in-water emulsion stabilized by egg yolk lecithin, typically containing 65-80% fat by weight, produced through high-shear mixing or colloid milling to achieve droplet sizes below 10 microns for shelf stability and mouthfeel. The emulsion serves as a condiment base, salad dressing precursor, and binding agent in commercial food manufacturing. Reduced-fat and organic product types are capturing margin pools as health-conscious consumers trade up from conventional formulations. Sachet and single-serve packaging types are expanding fastest in food service and institutional end-user segments where portion control and waste reduction drive procurement decisions.
FDA standards of identity for mayonnaise enforce minimum egg yolk and oil content, while USDA organic certification shapes premium positioning and supply chain auditing requirements for organic product lines. EFSA and national EU regulators enforce labeling thresholds for fat content claims and allergen declarations that constrain reformulation strategies. Stakeholders must monitor evolving plant-based emulsifier approvals and front-of-pack nutritional scoring systems that could recategorize mayonnaise within retail shelf sets and food service procurement frameworks.
Market Dynamics
Clean-label reformulations are compressing conventional mayonnaise margins as food manufacturers absorb higher input costs for organic oils and non-GMO emulsifiers while defending shelf positioning against private-label alternatives.
Growth Catalysts
- USDA Organic Certification:Premium positioning through certified organic supply chains is commanding price premiums in United States retail channels. Audit requirements are filtering out smaller competitors.
- Food Service Menu Expansion:Quick-service chains and casual dining operators are incorporating specialty mayonnaise as signature sauce bases. This application pull is expanding volume commitments from institutional distributors.
- Colloid Milling Advancements:High-shear processing equipment achieving sub-5-micron droplet sizes is improving mouthfeel consistency. Equipment upgrades are enabling cleaner label declarations without stabilizer additives.
Market Restraints
- Vegetable Oil Price Volatility:Sunflower and soybean oil markets are experiencing supply disruptions from Black Sea export constraints. Input cost swings are compressing gross margins for mid-tier producers.
- FDA Standards of Identity:Minimum egg yolk content requirements are blocking plant-based mayonnaise from using standardized nomenclature. Reformulated products must adopt alternative category names, creating consumer confusion.
- Allergen Labeling Burden:EFSA-mandated threshold declarations for egg and mustard residues are extending compliance timelines. Cross-contamination protocols are adding fixed costs to multi-product facilities.
Strategic Opportunities
- Sachet Packaging Penetration:Single-serve pouches remain underdeveloped in United States food service relative to European adoption. Portion-control formats align with waste-reduction procurement mandates.
- Plant-Based Emulsifier Convergence:Aquafaba and modified starch combinations are achieving functional parity with egg lecithin. Technology licensing agreements can accelerate regional market entry.
- Front-of-Pack Nutritional Scoring:Nutri-Score and equivalent systems are creating shelf-set recategorization in European retail. Reformulation to improve letter grades opens distribution in health-focused banners.
Industry Challenges
- Emulsion Stability Expertise Gap:Formulation chemists with oil-in-water stabilization experience are concentrated at legacy manufacturers. Talent acquisition is delaying clean-label product launches.
- Organic Supply Chain Certification:Multi-year transition periods for oilseed acreage are constraining certified organic volume. Ingredient procurement is competing with broader food category demand.
- Co-Manufacturing IP Protection:Proprietary emulsion formulations shared with third-party producers are creating enforcement complexity. Contract disputes are increasing in regional partnership arrangements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mayonnaise Market |
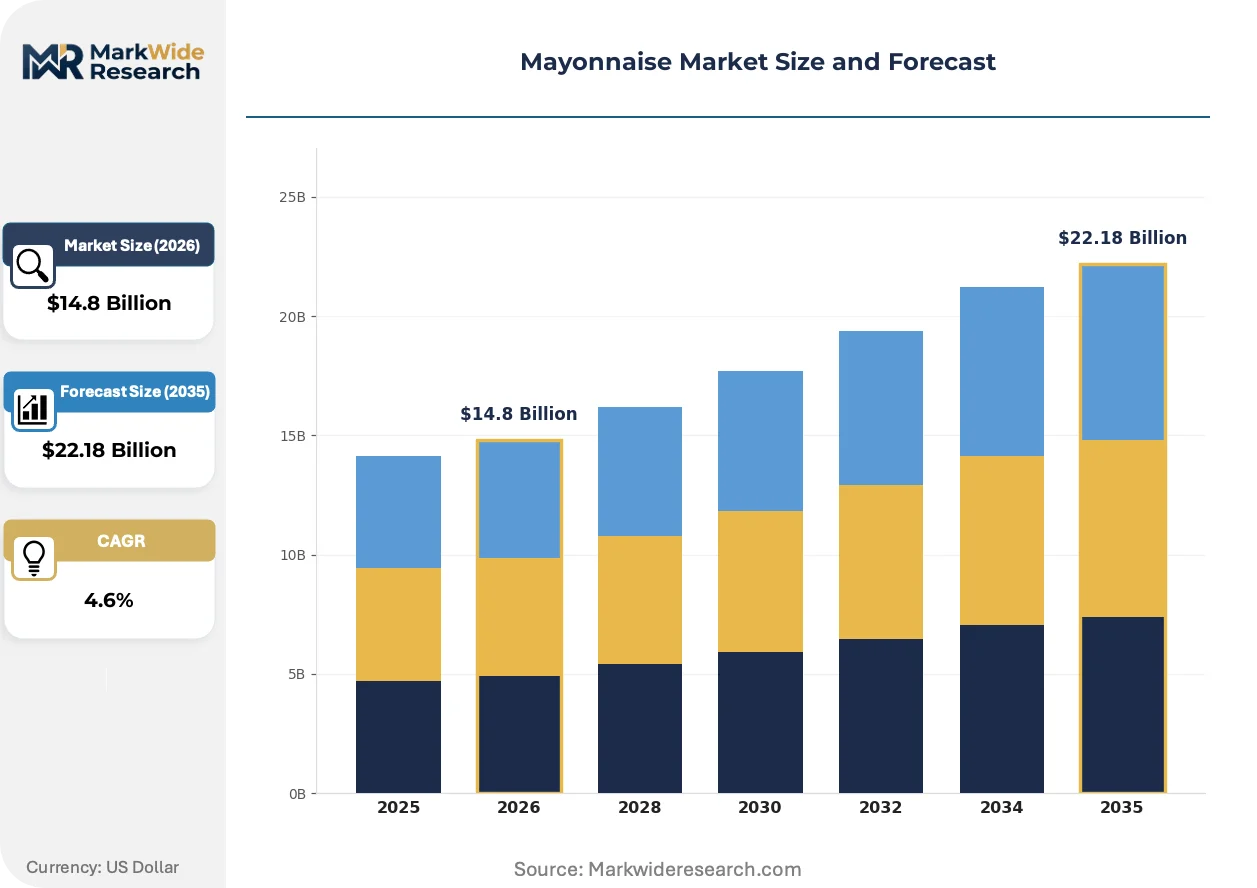
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Reduced-Fat, Organic, Gluten-Free Packaging Type: Glass Jar, Plastic Bottle, Sachet, Bulk Container End User: Household, Food Service, Retail, Industrial Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesalers |
| Companies Covered | Duke's Mayonnaise, Chosen Foods, Unilever, Paradise Food Ltd, Marina Foods Inc., Heinz, Graza, Ken's Foods, McCormick & Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mayonnaise Market Strategic Shifts & Innovations
Processing technology and regulatory labeling frameworks are simultaneously enabling product differentiation and constraining formulation freedom across conventional and alternative mayonnaise categories.
High-pressure processing is overtaking thermal pasteurization for refrigerated mayonnaise extensions. Premium deli and food service operators are adopting cold-press stabilization to preserve fresh flavor profiles. This technology is overtaking conventional heat treatment in applications where clean-label positioning commands price premiums.
EU Green Deal farm-to-fork targets are tightening pesticide residue limits on oilseed crops. EFSA is revising maximum residue levels for sunflower and rapeseed inputs, forcing upstream agricultural contracting changes. Organic and IP-certified supply chains are absorbing compliance costs while conventional sourcing faces exclusion from sustainable procurement frameworks.
Direct-to-food-service distribution is displacing broadline distributor intermediation for mid-size regional brands. Specialty mayonnaise producers are building captive salesforces to serve independent restaurant groups. This channel compression is most visible in United States metropolitan clusters where chef-driven concepts prioritize local supplier relationships.
Mayonnaise Market Segmentation
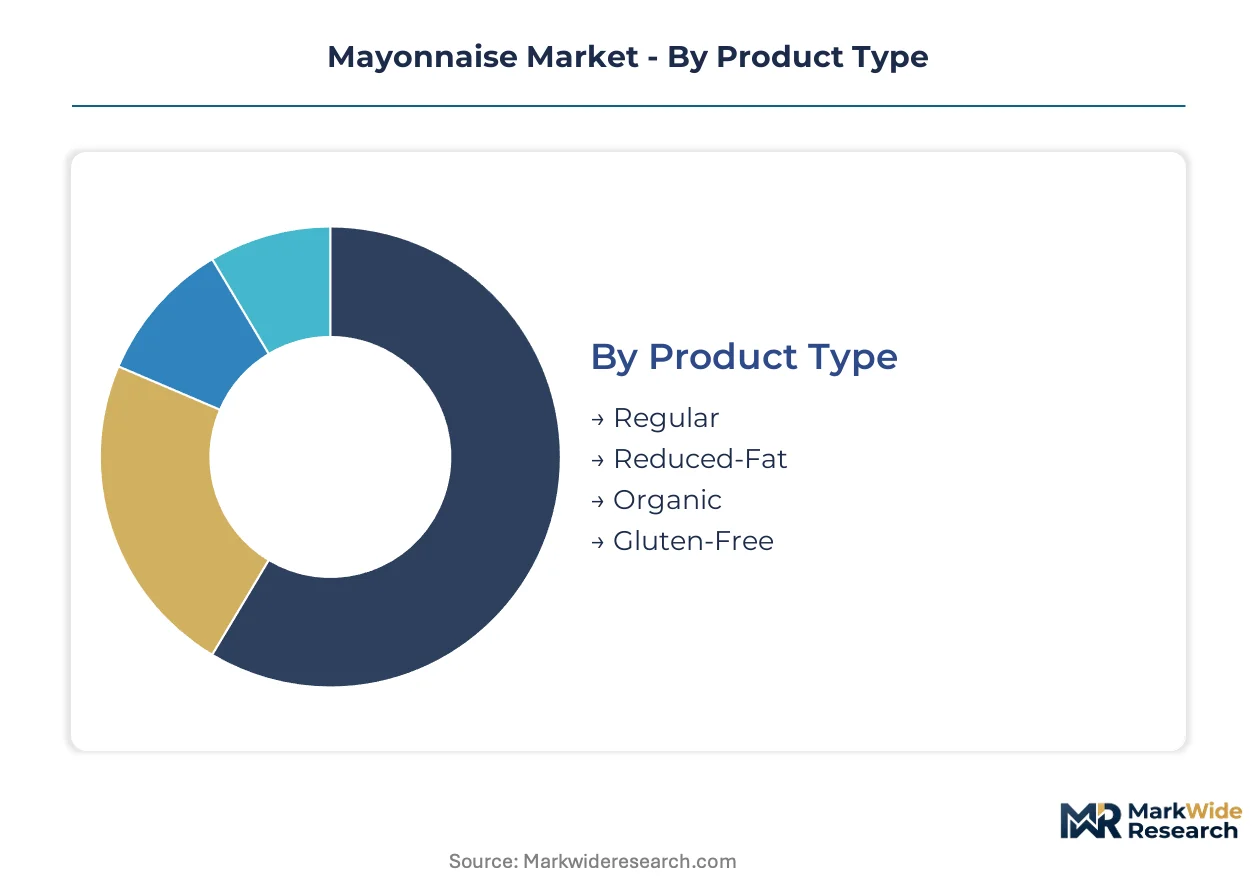
Mayonnaise segmentation tracks divergent technical requirements across shelf-stable retail, refrigerated food service, and industrial bulk applications. Specification thresholds for fat content, emulsion stability, and packaging integrity vary sharply by end-use environment.
Product Type:
Reformulation chemistry distinguishes each tier's positioning against clean-label and health-positioned competition.
- Regular:Standard oil-in-water emulsion at 70-80% fat content delivers the creamy mouthfeel baseline for sandwich spreads and salad dressings. Household penetration in the United States remains concentrated in conventional formulations despite health trend pressure.
- Reduced-Fat:Water-phase extension and modified starch stabilization achieve 25-50% fat reduction while maintaining droplet integrity. Food service operators specify these formulations for calorie-conscious menu labeling compliance.
- Organic:Certified organic supply chains command audit-verified oilseed sourcing and non-GMO emulsifiers. USDA certification filters out smaller competitors through multi-year acreage transition requirements.
- Gluten-Free:Dedicated production lines prevent cross-contamination for celiac-safe positioning. Manufacturing protocol costs limit this segment to premium pricing tiers.
Regular leads on scale; organic leads on momentum.
Packaging Type:
Barrier properties and portion economics shape procurement decisions across retail shelf and institutional channels.
- Glass Jar:Oxygen and light barrier preservation supports premium positioning and extended ambient shelf life. European retail channels maintain higher glass penetration than North American markets.
- Plastic Bottle:Polyethylene terephthalate and high-density polyethylene formats dominate mass-market retail through lightweight logistics and squeeze dispensing. Recycled content mandates are reshaping resin specifications.
- Sachet:Single-serve laminated film pouches enable precise portion control and waste reduction. United States food service adoption lags European penetration where procurement mandates favor portion-controlled formats.
- Bulk Container:Food-grade totes and drums serve industrial mayonnaise users and high-volume food service commissaries. Pump dispensing systems require specialized viscosity engineering.
Plastic bottle dominates volume; sachet climbs the fastest.
End User:
Application environment dictates emulsion durability requirements from refrigerated deli cases to ambient shelf storage.
- Household:Retail-purchased jars and bottles for home consumption prioritize convenience and refrigerator stability after opening. Specialty and organic variants are capturing trade-up behavior in United States households.
- Food Service:Quick-service chains and casual dining operators use mayonnaise as signature sauce bases and binding ingredients. Portion-control packaging and institutional distribution networks shape procurement specifications.
- Retail:Branded and private-label products sold through grocery channels compete on shelf positioning and clean-label claims. Front-of-pack nutritional scoring systems are recategorizing placement in European banners.
- Industrial:Bulk mayonnaise supplies commercial food manufacturers producing salad dressings, sauces, and prepared salads. Consistent emulsion specifications support automated processing lines.
Household anchors absolute volume; food service shows steepest expansion trajectory.
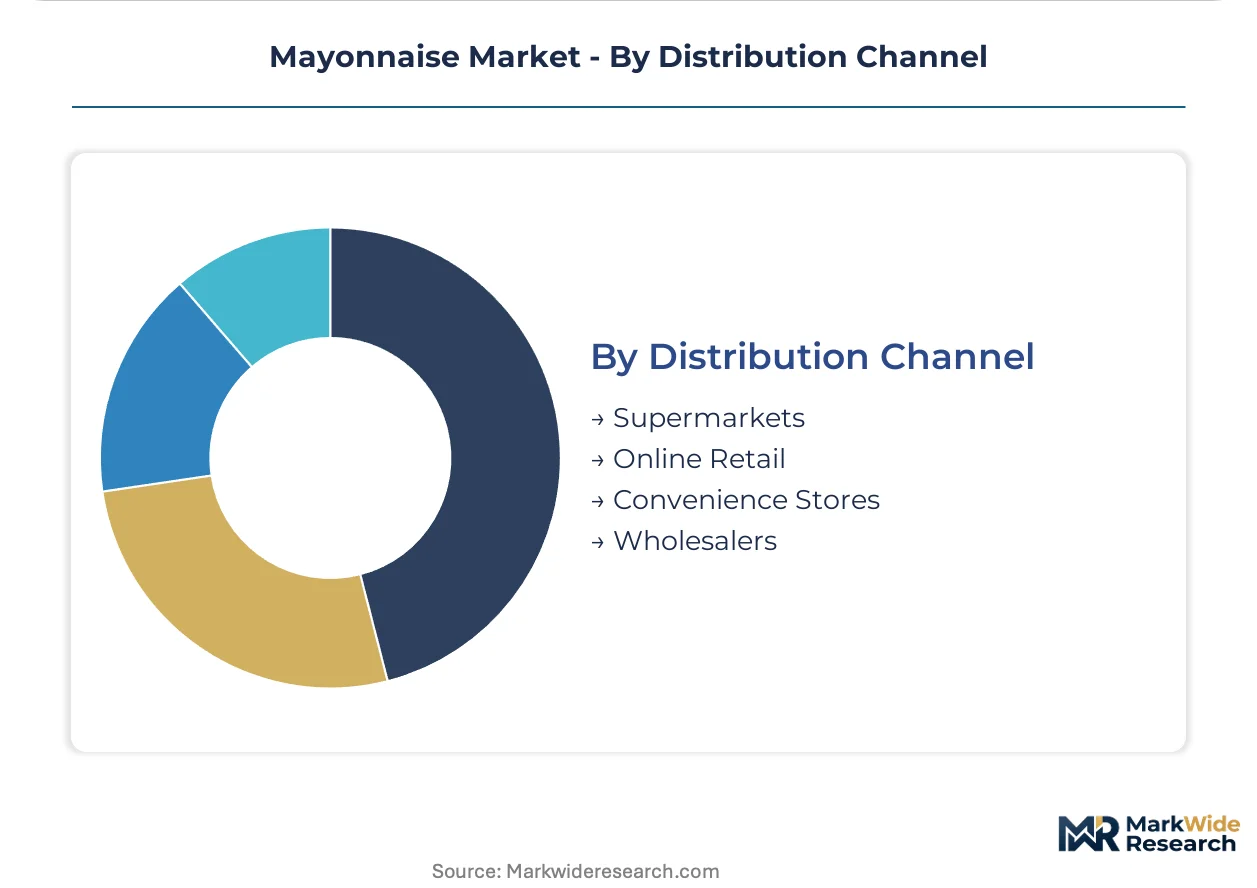
Distribution Channel:
Channel selection determines margin structure and brand control intensity across the value chain.
- Supermarkets:Multi-banner retail chains command slotting fees and promotional calendar access for shelf-stable mayonnaise. Clean-label positioning competes for space against private-label alternatives.
- Online Retail:Direct-to-consumer and third-party marketplace sales are expanding for specialty and subscription-format mayonnaise. Cold-chain logistics requirements constrain refrigerated product expansion.
- Convenience Stores:Grab-and-go sachet and small-format packaging targets immediate consumption and travel occasions. Urban cluster density supports distribution economics.
- Wholesalers:Broadline and specialty distributors serve food service and institutional accounts with volume pricing and delivery consolidation. Direct-to-food-service disintermediation is compressing wholesaler relevance for mid-size brands.
Supermarkets retain volume leadership; online retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands higher household penetration of specialty mayonnaise than Germany, yet German food service channels demonstrate faster adoption of portion-controlled sachet formats. Regulatory divergence between FDA standards and EFSA labeling thresholds is fragmenting formulation strategies across these anchor markets.
United States
Specialty and organic variants capture trade-up behavior in southeastern households where Duke's Mayonnaise sustains cult-following loyalty. FDA standards of identity enforce minimum egg yolk content that blocks plant-based products from standardized nomenclature. Atlanta and Charlotte metropolitan clusters anchor food service menu expansion for signature sauce applications.
Germany
Industrial bulk procurement from commercial salad dressing manufacturers concentrates demand in Baden-Württemberg and Bavaria. EU Green Deal farm-to-fork targets tighten pesticide residue limits on oilseed crops through EFSA revisions. The Eindhoven-Rotterdam-Antwerp corridor channels refined oils into German processing facilities.
France
Nutri-Score front-of-pack labeling recategorizes mayonnaise placement in health-focused retail banners across Île-de-France. ANSM-aligned enforcement of allergen threshold declarations extends compliance timelines for multi-product facilities. Lyon and Marseille food service clusters drive procurement of clean-label emulsions for casual dining concepts.
United Kingdom
Private-label alternatives compress branded margins in supermarket channels where slotting fees determine shelf positioning. Trading Standards enforcement of EFSA-mandated fat content claims constrains reformulation marketing. Greater London's independent restaurant groups accelerate direct-to-food-service disintermediation for specialty suppliers.
Japan
Kewpie-style mayonnaise variants dominate household preference in Kanto and Kansai metropolitan belts. METI guidelines on food additive declarations shape clean-label positioning for premium retail tiers. Osaka-based food manufacturers specify consistent emulsion stability for automated processing lines.
Mayonnaise Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with retail concentration exceeding food service fragmentation. The vendor base organizes around three archetypes: multinational CPG conglomerates leveraging global procurement networks, regional heritage brands commanding geographic loyalty, and private-label suppliers competing on operational efficiency. Dominant competitive moves include co-manufacturing partnerships for proprietary emulsion formulations and direct-to-food-service channel compression bypassing broadline distributors.
Within the heritage-brand tier, Duke's Mayonnaise exemplifies regional cult-following defensibility, while Ken's Foods occupies a position in institutional distribution. Unilever anchors the multinational conglomerate archetype through vegetable oil supply chain integration across multiple continents.
| Leading Market Players |
|---|
| Duke's Mayonnaise |
| Chosen Foods |
| Unilever |
| Paradise Food Ltd |
| Marina Foods Inc. |
| Heinz |
| Graza |
| Ken's Foods |
| McCormick & Company |
| Others |
Cost & Logistics Intelligence
Formulation chemists with oil-in-water stabilization expertise concentrate in legacy manufacturing hubs across the United States and Germany, and their scarcity widens labor-cost spreads between premium clean-label tiers and conventional economy formulations. This workforce bottleneck compresses margins for mid-tier producers attempting clean-label transitions while defending shelf positioning against private-label alternatives.
Pricing Analysis
Capacity additions in Southeast Asian oilseed processing are reshaping price floors for conventional mayonnaise tiers. Three-tier pricing structure across premium organic, standard conventional, and economy private-label levels dominates procurement frameworks, with USDA certification and colloid milling precision as primary differentiation drivers. Pricing pressure stems from Black Sea sunflower oil supply disruptions forcing input cost absorption. Food service operators show least price sensitivity due to menu-margin pass-through, while institutional bulk buyers anchor economy-tier procurement.
Supply Chain Analysis
Domestic-content mandates in EU Green Deal farm-to-fork procurement frameworks are reshaping sourcing toward certified organic acreage within member states. Vegetable oil supply concentrates in Ukraine, Argentina, and Indonesia, with egg yolk lecithin drawing from United States and Brazilian poultry processing clusters. Single-source vulnerability runs through Black Sea export corridors for high-oleic sunflower varieties. Distribution runs through broadline wholesalers for mass-market tiers, while specialty brands compress channels via direct-to-food-service captive salesforces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between United States FDA-standardized conventional formulations and EU EFSA-regulated clean-label tiers, with organic certification cost differentials favoring integrated supply chain control in North American sourcing basins.
For Market Incumbents: Hedge against plant-based emulsifier disruption by securing aquafaba and modified starch technology licenses before functional parity achieves scale. Backward integration into organic oilseed acreage defends margin position against multi-year transition bottlenecks filtering smaller competitors.
For New Entrants and Emerging Players: Capture underdeveloped sachet penetration in United States food service where European procurement mandates have already validated portion-control economics. Direct-to-food-service channel compression bypassing broadline distributors offers the most penetrable go-to-market angle for chef-driven metropolitan clusters.
For Investors and Strategic Acquirers: Food service distribution conglomerates are the most active acquirer in this space, consolidating regional specialty brands for institutional network leverage. Acquisition targets with proprietary emulsion IP and captive organic supply chains present long-term viability through clean-label transition windows. Watch EFSA plant-based emulsifier approval timelines as inflection signal for category nomenclature recategorization.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | Colloid milling upgrades enable stabilizer-free declarations that command retail shelf premiums. |
| Organic Supply Chain Integration | USDA-certified acreage locks out competitors through multi-year transition barriers. |
| Direct-to-Food-Service Channel Buildout | Captive salesforces disintermediate broadline distributors in chef-driven metropolitan clusters. |
| Plant-Based Emulsifier Technology Licensing | Aquafaba patents accelerate regional entry before FDA standards of identity relax. |
| Sachet Packaging Capacity Expansion | Single-serve formats align with waste-reduction mandates in institutional procurement frameworks. |
Research Approach
Direct dialogue with mayonnaise plant managers, food service procurement directors, retail category buyers, and colloid mill equipment specialists grounded primary intelligence, cross-referenced with FDA standards filings, USDA organic certification databases, EFSA pesticide residue limit revisions, and trade customs records for oilseed and egg product flows. Bottom-up volume triangulation against top-down value estimates validated segment-level outputs.
Segmented projections across product type, packaging format, end-user environment, and distribution channel density produced volume and value trajectories across the analysis window. CAGRs derived from historical elasticity modeling against input cost indices and clean-label adoption curves, with sunflower oil price volatility and organic acreage transition timelines as key forecast inputs.
Black Sea export corridor disruptions, EFSA emulsifier approval delays, and front-of-pack nutritional scoring recategorizations are the dominant revision risks to modeled outputs. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Dips and Spreads Market
Condiments & Sauces
Sauce Market
Condiments & Sauces
Curry Cube Market
Condiments & Sauces
Europe Pasta Sauce Market
Condiments & Sauces
Soups and Sauces Market
Condiments & Sauces
Asia Pacific Hot Sauce Market
Condiments & Sauces
United States Pasta Sauce Market
Condiments & Sauces
Low Salt Soy Sauce Market
Condiments & Sauces
Vegan Sauces, Dressings and Spreads Market
Condiments & Sauces
Organic Condiments Market
Condiments & Sauces
Low Fat Mayo Market
Condiments & Sauces
Europe Hot Sauce Market
Condiments & Sauces
Vegan Cheese Sauce Market
Condiments & Sauces
Sauces and Condiments Market
Condiments & Sauces
Low Fat Pasta Sauce Market
Condiments & Sauces
Pesto Sauces Market