
 Sandwich Spread Market | 2026-2036
Sandwich Spread Market Size, Share, and Industry Trends Forecast 2026-2036
Sandwich Spread Market Analytics
The sandwich spread category is repositioning around a stark split between clean-label premium formulations and cost-optimized commodity bases. Kraft Heinz Company leverages its condiment manufacturing scale to dominate mainstream retail shelf space. The J.M. Smucker Company anchors its portfolio in nut-based spreads with extended distribution into foodservice channels. Unilever PLC differentiates through plant-forward formulations targeting health-conscious European consumers.
Sandwich spreads encompass viscous or semi-solid condiments applied to bread substrates, typically comprising emulsified oils, acidulants, stabilizers, and flavoring systems with water activity below 0.85 for ambient stability; their primary commercial purpose is moisture retention, flavor delivery, and textural contrast in prepared foodservice and retail sandwich products. Mayo and mustard variants occupy mature volume positions with thin margin pools, while hummus and pesto segments attract premium positioning through Mediterranean flavor profiles and chickpea or basil ingredient stories. Squeeze bottle and pouch packaging formats are gaining structural share against traditional tubs and jars as on-the-go consumption rises in transit-oriented urban markets.
The FDA governs standard of identity rules for mayonnaise in the United States, while the EU Green Deal and EFSA oversight shape clean-label additive restrictions across European formulations; these frameworks compel manufacturers to reformulate emulsifier systems and document supply chain provenance. India's FSSAI is tightening vegetable oil blending disclosure requirements for packaged spreads, adding compliance layers for exporters. Stakeholders must monitor evolving front-of-pack labeling mandates and decide whether to regionalize formulation platforms or pursue unified global recipes.
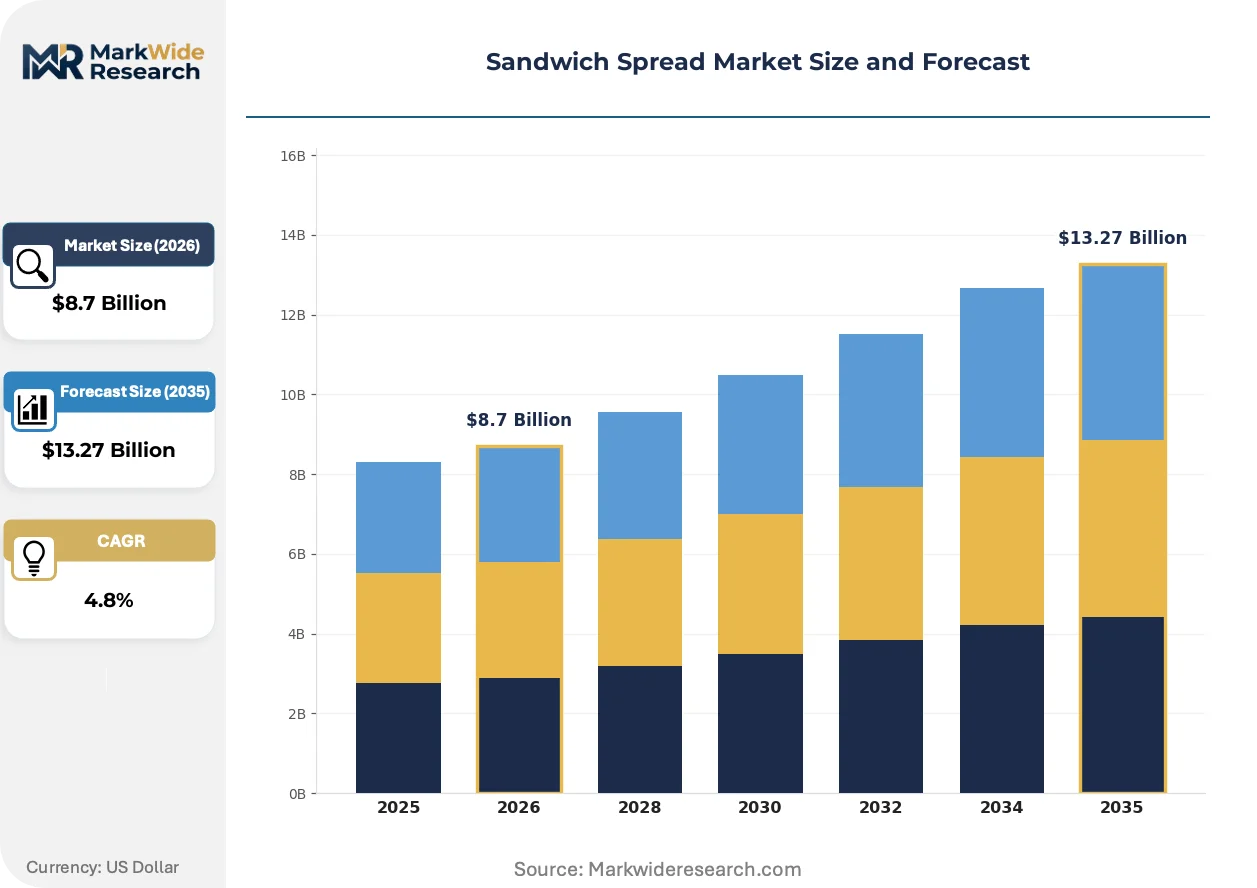
Market Dynamics
The sandwich spread sector is bifurcating around the EU Green Deal's additive disclosure mandates, which force manufacturers to choose between reformulating emulsifier systems or exiting premium European retail channels entirely.
Growth Catalysts
- Clean-label reformulation:EFSA oversight of titanium dioxide and artificial colorants pushes manufacturers toward plant-derived stabilizers, opening premium shelf space for compliant brands.
- Foodservice expansion:Quick-service restaurant chains across Indonesia, Vietnam, and the Philippines are adding cold-sandwich SKUs, pulling ambient-stable spread volumes into Southeast Asian urban corridors.
- Convenience retail penetration:Indonesia's minimart operators are expanding into secondary cities, creating new cold-chain endpoints for single-serve squeeze formats.
Market Restraints
- Input cost volatility:Sunflower and rapeseed oil prices fluctuate with Black Sea supply disruptions, compressing margin pools on mayonnaise variants.
- Supply concentration risk:Three Indonesian palm oil processors control the majority of Southeast Asian emulsifier feedstock, creating single-source vulnerability for regional formulators.
- Regulatory friction:India's FSSAI vegetable oil blending disclosure rules add compliance layers that deter small exporters from entering the market.
Strategic Opportunities
- Underpenetrated geography:Vietnam's urban sandwich culture remains nascent outside Ho Chi Minh City and Hanoi, presenting first-mover positioning for ambient-stable formats.
- Regulatory tailwind:The EU Green Deal's Farm to Fork Strategy rewards documented supply chain provenance, favoring vertically integrated manufacturers with captive ingredient sourcing.
- Distribution innovation:Direct-to-foodservice platforms in Indonesia's secondary cities bypass traditional wholesale layers, capturing margin that retail channels erode.
Industry Challenges
- Emulsifier reformulation timeline:Replacing synthetic stabilizers with clean-label alternatives requires 18-24 month sensory validation cycles that delay product launches.
- Certification complexity:Dual compliance with FDA standard-of-identity rules and EFSA additive restrictions forces manufacturers to maintain parallel formulation platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sandwich Spread Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mayo, Mustard, Hummus, Pesto Ingredient Type: Vegetable-based, Dairy-based, Nut-based, Organic Packaging Type: Tub, Jar, Squeeze Bottle, Pouch Distribution Channel: Supermarket, Online, Specialty Store, Foodservice |
| Companies Covered | The Hershey Company, Kraft Heinz Company, The J.M. Smucker Company, General Mills, Conagra Brands, Unilever PLC, Hormel Foods LLC, Mondelez International, Ferrero International S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sandwich Spread Market Evolving Landscape
Squeeze bottle and pouch packaging formats are capturing structural share from rigid tubs as on-the-go consumption patterns reshape urban foodservice procurement. This shift compresses traditional supply chain configurations while opening new manufacturing partnerships.
High-pressure processing (HPP) is electrifying clean-label shelf-stable spread production by eliminating thermal degradation of volatile flavor compounds. Southeast Asian contract manufacturers are adopting HPP lines at accelerating rates to serve European export demand. The technology is compressing the historical trade-off between ambient stability and ingredient simplicity.
The EU Green Deal's tightening additive disclosure rules under EFSA oversight are forcing systematic emulsifier replacements across European formulations. Manufacturers face 12-18 month reformulation cycles to maintain retail distribution. Plant-based and Mediterranean-origin spreads face the steepest compliance burden due to their premium positioning.
Urban transit-oriented consumption is fragmenting bulk procurement into single-serve and on-the-go formats across Jakarta, Manila, and Bangkok. Convenience retail operators are displacing traditional grocery wholesale as the primary volume channel for sandwich spreads. This pattern is most visible in Indonesia, where minimart density in secondary cities now exceeds supermarket penetration.
Sandwich Spread Market Segmentation
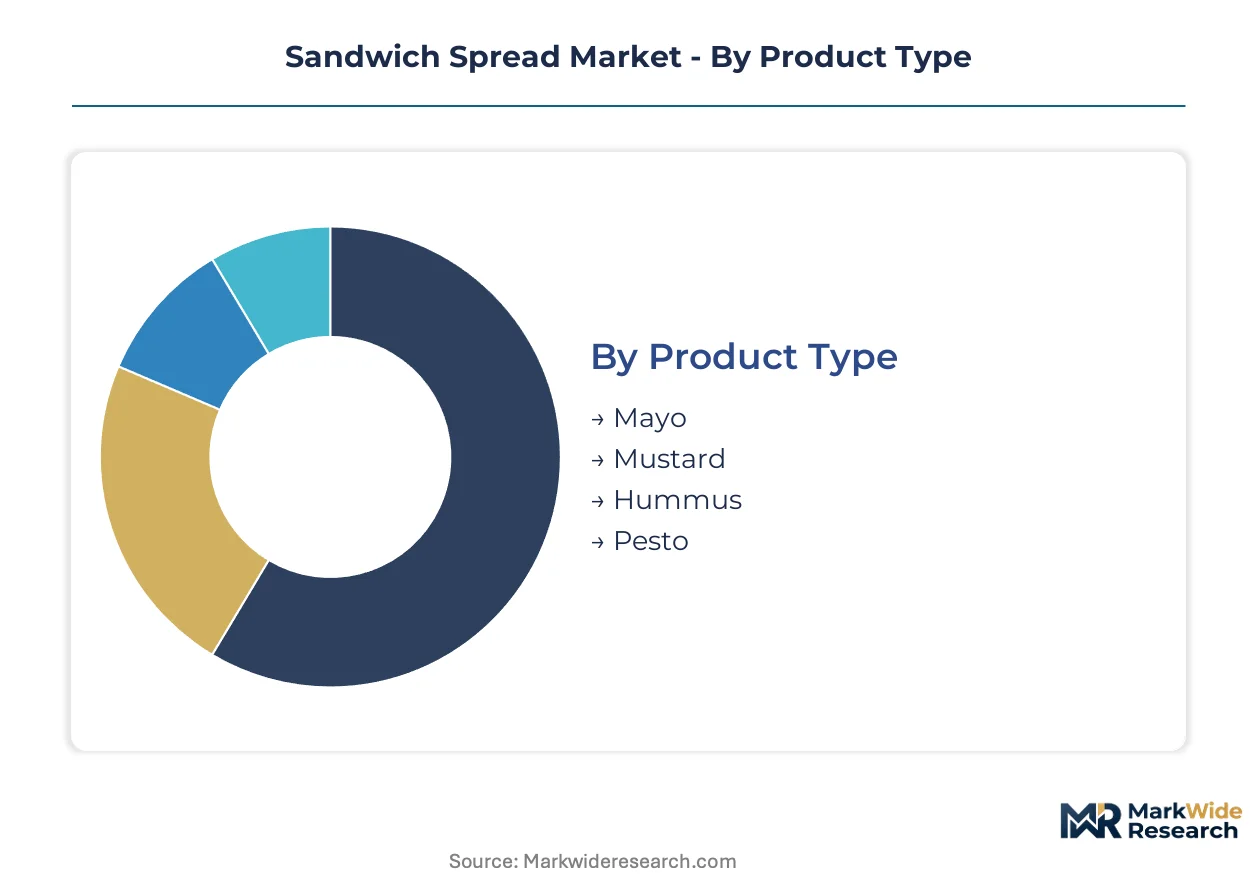
Segmentation in sandwich spreads reveals divergent margin architectures across formulation chemistry, packaging physics, and channel economics. Manufacturers must align production assets with the specific technical and logistical requirements of each slice.
Product Type:
Buyers in this category sort by flavor intensity tolerance and meal occasion rather than price alone.
- Mayo:Emulsified oil-in-water systems with egg yolk lecithin stabilizers, typically 70-80% vegetable oil by weight. Demand concentrates in Southeast Asian quick-service restaurant chains expanding cold-sandwich menus, where ambient stability and bulk procurement economics dominate supplier selection.
- Mustard:Acidulated seed-paste formulations with vinegar or wine acidulants, water activity controlled through salt and sugar solids. European retail channels drive reformulation urgency as EFSA additive disclosure rules force synthetic colorant replacements in traditional yellow varieties.
- Hummus:Chickpea-tahini emulsions with citric acid preservation, protein content 4-6%.
- Pesto:Basil-pine nut oil suspensions requiring thermal protection to preserve volatile terpenes.
Mayo leads volumes today; hummus is gaining share fastest.
Ingredient Type:
Cost tier separation determines procurement behavior more than brand loyalty in this category.
- Vegetable-based:Sunflower, rapeseed, or palm oil emulsions with modified starch or gum stabilizers. Southeast Asian foodservice operators prioritize these formulations for fryer-oil compatibility and extended holding stability in tropical climates.
- Nut-based:Almond, cashew, or peanut protein suspensions with natural oil separation resistance. European health-positioned retail segments concentrate demand here, driven by clean-label protein claims and Mediterranean diet associations.
- Dairy-based:Cream cheese or yogurt acidified spreads with live culture preservation.
- Organic:Certified ingredient supply chains with documented provenance and restricted additive lists.
Vegetable-based formulations dominate tonnage; nut-based spreads show the steepest expansion trajectory.
Packaging Type:
Volume throughput and breakage rates separate procurement decisions across formats.
- Squeeze Bottle:Multi-layer HDPE or PET structures with silicone valve dispensing, designed for single-handed operation. Indonesian minimart operators in secondary cities are displacing traditional grocery wholesale with this format, matching on-the-go consumption patterns in transit corridors.
- Pouch:Flexible laminate structures with spout fitments, 40-60% lighter than rigid alternatives for freight economics. Southeast Asian contract manufacturers are adding pouch lines to serve European export demand for reduced-plastic packaging claims.
- Tub:PP or PS thermoformed containers with snap-fit lids, standard for deli-counter service.
- Jar:Glass or PET wide-mouth containers with metal lug closures, residual share in premium gifting segments.
Tub configurations retain the largest installed base; squeeze bottles are climbing the fastest.
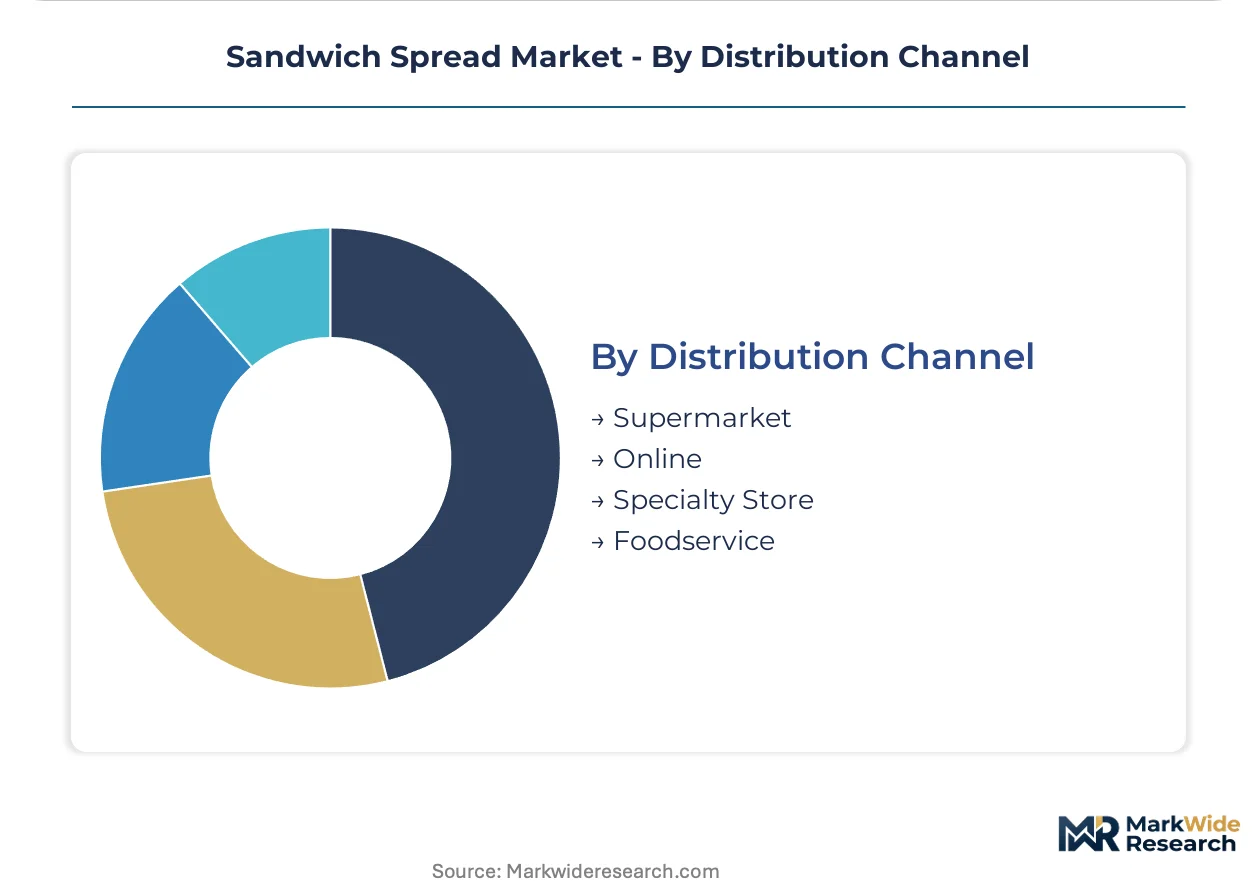
Distribution Channel:
Customer type and purchase frequency dictate margin structure more than geographic coverage.
- Foodservice:Bulk tote and pail procurement with specification-controlled consistency, often under annual contract. Quick-service chains across Indonesia, Vietnam, and the Philippines are pulling ambient-stable volumes through direct distribution platforms that bypass traditional wholesale layers.
- Online:Direct-to-consumer fulfillment with temperature-controlled last-mile requirements. European clean-label brands use this channel to test reformulated SKUs before retail distribution, compressing sensory validation feedback loops.
- Supermarket:Shelf-ready case packs with promotional display allowances, still the default for household stock-up trips.
- Specialty Store:Curated assortment with staff-assisted sampling, concentrated in urban premium corridors.
Supermarket channels move the most units; foodservice is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's minimart density in secondary cities now exceeds supermarket penetration, while Germany's reformulation cycles stretch 18-24 months under EFSA oversight. These divergent rhythms illustrate how geography dictates competitive tempo in sandwich spreads.
United States
Quick-service restaurant chains are expanding cold-sandwich menus, pulling ambient-stable spread volumes through direct distribution platforms. FDA standard-of-identity rules for mayonnaise govern formulation compliance, forcing parallel recipe maintenance for export-bound production. Chicago and Dallas-Fort Worth anchor foodservice procurement clusters where bulk tote specifications dominate supplier selection.
Germany
Health-positioned retail segments concentrate demand for nut-based spreads with clean-label protein claims. EFSA oversight of titanium dioxide and artificial colorants compels systematic emulsifier replacements in traditional mustard varieties. The Rhine-Ruhr metropolitan region houses reformulation laboratories serving pan-European export demand.
Indonesia
Minimart operators in Jakarta, Surabaya, and Bandung are displacing traditional grocery wholesale with single-serve squeeze formats. FSSAI-aligned vegetable oil blending disclosure requirements add compliance layers for imported formulations. Three palm oil processors control the majority of regional emulsifier feedstock, creating single-source vulnerability for formulators.
Vietnam
Urban sandwich culture remains nascent outside Ho Chi Minh City and Hanoi, presenting first-mover positioning for ambient-stable formats. Quick-service chains are adding cold-sandwich SKUs, pulling spread volumes through direct-to-foodservice platforms. Da Nang and Can Tho represent emerging secondary-city endpoints where convenience retail penetration is accelerating.
India
FSSAI is tightening vegetable oil blending disclosure requirements for packaged spreads, adding compliance layers that deter small exporters from entering the market. Convenience retail operators in Mumbai, Delhi-NCR, and Bangalore are testing squeeze-bottle formats for transit-oriented consumption. Domestic formulators face input cost volatility as sunflower and rapeseed oil prices fluctuate with Black Sea supply disruptions.
Sandwich Spread Market Competitive Landscape
Top-tier vendors anchor mainstream retail shelf space, while mid-scale specialists occupy clean-label premium niches. The market structure reflects consolidation around condiment manufacturing scale and fragmentation across Mediterranean-origin specialty segments. Three archetypes dominate: multinational conglomerates with captive ingredient sourcing, nut-based spread specialists with extended foodservice distribution, and plant-forward formulators targeting health-conscious European consumers. Competitive moves center on emulsifier reformulation partnerships and direct-to-foodservice platform expansion in Southeast Asian secondary cities.
Within the scale-driven tier, Kraft Heinz Company and Unilever PLC exemplify manufacturing breadth that spans commodity mayonnaise and plant-forward premium lines. The J.M. Smucker Company anchors the nut-based specialist archetype with extended distribution into foodservice channels. These three entities represent the dominant competitive anchors against which regional formulators position clean-label alternatives.
| Leading Market Players |
|---|
| The Hershey Company |
| Kraft Heinz Company |
| The J.M. Smucker Company |
| General Mills |
| Conagra Brands |
| Unilever PLC |
| Hormel Foods LLC |
| Mondelez International |
| Ferrero International S.A. |
| Others |
Value Network & Pricing Analysis
Captive palm oil sourcing across Indonesian processing clusters anchors both supply security and margin control for regional formulators. This backward integration into emulsifier feedstock buffers pricing power against sunflower and rapeseed volatility while compressing landed costs for Southeast Asian foodservice channels.
Pricing Analysis
Capacity additions in Vietnam and the Philippines are reshaping price floors for ambient-stable mayonnaise variants. Three-tier pricing structure across premium clean-label, standard foodservice, and economy bulk tiers separates procurement by certification grade and volume scale. Price differentiation hinges on EFSA compliance documentation and tropical-climate stability guarantees. Cost compression in standard-tier vegetable-based spreads is intensifying as Black Sea oil supply disruptions persist; quick-service chains show highest price sensitivity while European retail buyers absorb premiums for additive-free formulations.
Supply Chain Analysis
Freight economics from Southeast Asian manufacturing hubs to European retail channels favor flexible pouch formats over rigid glass jars. Supply concentrates in Indonesia, Malaysia, and Thailand for palm-derived emulsifiers; the sector draws from Black Sea sunflower oil, European rapeseed, and Mediterranean olive oil for premium variants. Single-source vulnerability runs through three Indonesian palm oil processors controlling regional feedstock. Distribution runs through direct-to-foodservice platforms in Jakarta and Manila that bypass traditional wholesale layers, capturing margin that retail channels erode.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sandwich spread market reads as a late-cycle quality story where clean-label premium specifications are displacing commodity volumes in European retail and Southeast Asian urban corridors.
For Market Incumbents: Lock in captive palm oil supply through long-term offtake agreements with Indonesian processors before feedstock concentration tightens further. Prioritize EFSA-compliant emulsifier reformulation to defend shelf space against plant-forward entrants; channel control through direct-to-foodservice platforms in Vietnam's secondary cities anchors volume retention against regional challengers. For New Entrants and Emerging Players: Indonesian minimart operators in Surabaya and Bandung represent an underserved buyer archetype seeking single-serve squeeze formats with localized flavor profiles. Vietnam's nascent cold-sandwich culture outside Ho Chi Minh City and Hanoi offers first-mover positioning for ambient-stable hummus and pesto variants. A go-to-market angle pairing HPP clean-label production with European export certification compresses the traditional 18-24 month sensory validation cycle. For Investors and Strategic Acquirers: Consolidation pressure builds where clean-label formulation capability overlaps with captive ingredient sourcing and Southeast Asian foodservice distribution. Mid-scale specialists with HPP lines and EFSA-ready portfolios present acquisition targets as multinational conglomerates seek reformulation speed. The signal to watch is minimart density penetration in Indonesian secondary cities exceeding supermarket coverage, indicating channel shift inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Partnership | EFSA-compliant emulsifier replacements open premium European retail shelf space for compliant brands. |
| Direct-to-Foodservice Platform Expansion | Bypassing wholesale layers in Jakarta and Manila captures margin erosion from traditional retail channels. |
| HPP Manufacturing Line Investment | High-pressure processing compresses the ambient stability versus ingredient simplicity trade-off for export demand. |
| Captive Palm Oil Supply Agreement | Long-term Indonesian feedstock offtakes buffer margin pressure from Black Sea oil price volatility. |
| Single-Serve Packaging Format Launch | Squeeze bottles and pouches match transit-oriented consumption patterns in Southeast Asian urban corridors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build segment-level demand estimates. Primary fieldwork engaged R&D directors at condiment manufacturers, category buyers at Indonesian minimart chains, procurement leads at quick-service restaurant operators, and regulatory affairs specialists navigating EFSA additive disclosure rules. Secondary validation drew from FSSAI filing databases, EU Farm to Fork Strategy documentation, customs trade records for vegetable oil imports, and Nielsen retail audit data for Southeast Asian convenience channels. Bottom-up volume builds and top-down macro anchoring were cross-checked for consistency.
Historical reference periods anchored the projection horizon to observed elasticity patterns across reformulation cycles and channel shifts. The analytical framework modeled demand across product type, ingredient chemistry, packaging physics, and distribution channel economics, with additional segmentation for regulatory compliance tier. CAGRs were derived from fitted growth curves incorporating input cost trajectories and penetration saturation limits. Forecast inputs included Black Sea sunflower oil supply scenarios, Indonesian minimart expansion rates, and EFSA enforcement timelines for titanium dioxide replacements.
Underlying measurement precision varies by segment; clean-label premium and foodservice bulk tiers carry tighter precision than nascent organic and pouch-format categories. Forecasts reflect documented assumptions about regulatory enforcement intensity and commodity price normalization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Sauces and Condiments Market
Condiments & Sauces
GCC Condiment Sauces (for Hospitality Sector) Market
Condiments & Sauces
Low Fat Pasta Sauce Market
Condiments & Sauces
Ketchup Concentrates Market
Condiments & Sauces
Global Hot Pot Condiment Market
Condiments & Sauces
Table Sauce Market
Condiments & Sauces
Vegan Fish Sauce Market
Condiments & Sauces
Curry Cube Market
Condiments & Sauces
Dry Cooking Sauces Market
Condiments & Sauces
Hot Sauce Market
Condiments & Sauces
Latin America Pasta Sauce Market
Condiments & Sauces
Horseradish Sauce Market
Condiments & Sauces
Asia Pacific Hot Sauce Market
Condiments & Sauces
Ketchup Market
Condiments & Sauces
Salad Dressings Market
Condiments & Sauces
Europe Gluten-Free Soups and Sauces Market