
 GCC Biopsy Devices Market | 2026-2036
GCC Biopsy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Biopsy Devices Market Intelligence
Software-defined imaging compatibility is broadening what device manufacturers bundle with core biopsy instruments. Becton Dickinson and Company leverages its integrated informatics infrastructure to anchor recurring service contracts across Gulf health systems. Hologic, Inc. specializes in breast biopsy platforms with proprietary specimen radiography, while Medtronic plc competes through robotic-assisted delivery systems that command premium placement in Saudi Arabia's largest hospital networks.
GCC biopsy devices comprise precision-engineered needles, vacuum-assisted collection systems, and image-guided positioning instruments designed to extract tissue samples for histopathological analysis with minimal patient trauma; stainless steel cannulae with gauge ranges from 8 to 20 and vacuum pressures between 20-25 inHg define core performance parameters for reliable specimen yield. Vacuum-assisted biopsy systems lead product type demand due to superior tissue volume retrieval in breast cancer screening programs, while robotic-assisted delivery mode represents the fastest-expanding segment as Gulf hospitals prioritize procedural standardization and radiologist ergonomics. Cancer care centers constitute the highest-margin end user channel given bundled service contracts and dedicated pathology workflows.
SFDA, MOHAP, and Saudi Central Board for Accreditation of Healthcare Institutions collectively govern device registration, clinical evidence requirements, and facility procurement standards across the GCC, with SFDA's medical device interim regulation mandating local authorized representative presence for market entry. These frameworks elevate compliance costs for new entrants while reinforcing incumbents with established regulatory affairs teams. Stakeholders must monitor harmonization timelines between Saudi and Emirati regulatory pathways to anticipate centralized purchasing shifts.
Market Dynamics
SFDA's interim medical device regulations and MOHAP's tightened Class II/III registration pathways are forcing manufacturers to establish local authorized representative presence, compressing market entry timelines while elevating compliance infrastructure costs across Saudi Arabia and the United Arab Emirates.
Growth Catalysts
- SFDA Registration Mandates:Saudi Arabia's requirement for local authorized representatives creates captive service relationships that lock in recurring revenue streams for established device vendors.
- Oncology Hub Concentration:Tertiary care centers in Riyadh and Jeddah are consolidating breast cancer screening programs, concentrating procurement volume for vacuum-assisted biopsy systems.
- Robotic-Assisted Delivery:Radiologist ergonomics demands across Qatar's Hamad Medical Corporation network are accelerating placement of automated positioning instruments.
Market Restraints
- Stainless Steel Input Volatility:Gauge-specific cannulae production faces raw material price swings from specialty steel mills in Germany and Japan.
- Single-Source Vacuum Pump Dependency:Gulf health systems rely on three dominant suppliers for 20-25 inHg pressure systems, creating concentration risk in maintenance networks.
- Histopathology Bottleneck:Specimen processing capacity constraints in Saudi Arabia's regional laboratories limit throughput for high-volume screening programs.
Strategic Opportunities
- Kuwait Underpenetration:The country's nascent minimally invasive diagnostic infrastructure offers first-mover positioning before MOH-equivalent regulations mature.
- Software-Defined Imaging Convergence:Integration of AI-assisted specimen radiography with core needle systems creates bundled value propositions for cancer care centers.
- Direct Hospital Contracting:Bypassing traditional distributor markups through SFDA-authorized local entities enables margin capture in Saudi Arabia's centralized purchasing shifts.
Industry Challenges
- Interventional Radiologist Scarcity:Gulf medical schools produce insufficient specialists trained in image-guided tissue extraction, constraining procedural expansion.
- Legacy PACS Integration:Biopsy device informatics must interface with heterogeneous imaging archives across Emirates Health Services and Ministry of National Guard Health Affairs networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Biopsy Devices Market |
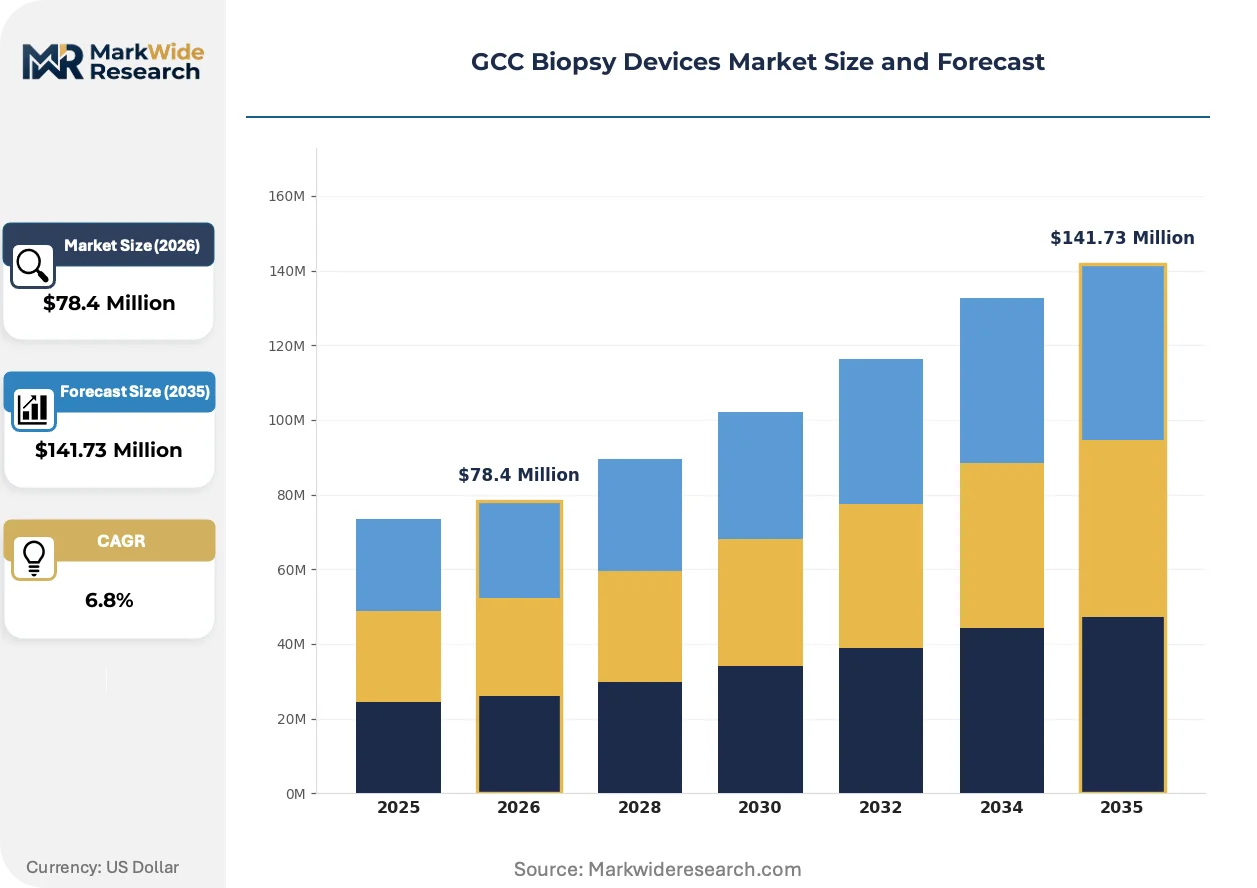
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $141.73 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Needle Biopsy, Vacuum-Assisted Biopsy, Core Needle Biopsy, Fine-Needle Aspiration End User: Hospitals, Diagnostic Labs, Ambulatory Surgical Centers, Cancer Care Centers Application: Breast Biopsy, Liver Biopsy, Prostate Biopsy, Lung Biopsy Delivery Mode: Image-Guided, Manual, Robotic-Assisted, Others |
| Companies Covered | Becton Dickinson and Company, Boston Scientific Corporation, Cardinal Health, Inc., Cook Medical, Inc., Danaher Corporation, Hologic, Inc., Medtronic plc, Argon Medical Devices, Inc., CONMED Corporation, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Biopsy Devices Market Strategic Shifts & Innovations
Device architecture is fragmenting into interoperable subsystems as Gulf hospitals demand flexibility across mixed-vendor imaging environments. Three forces are compressing traditional bundled offerings.
Disposable needle cartridges with embedded RFID tracking are modularizing procurement workflows across Saudi Arabia's Ministry of Health facilities. Procurement directors in Riyadh's King Faisal Specialist Hospital now specify cartridge compatibility across multiple vacuum-assisted platforms. This standardization is compressing vendor lock-in and enabling mixed-fleet deployments.
MOHAP's 2024 technical documentation requirements for Class III devices are extending clinical evidence submission timelines. Manufacturers must now submit Gulf-specific usability studies alongside ISO 13485 certificates. Breast biopsy platforms with proprietary specimen radiography face the steepest compliance ramps in Dubai's private hospital sector.
Service contract unbundling is disrupting traditional capital-equipment sales in Qatar's Hamad Health system. Cancer care centers now separately negotiate maintenance, software updates, and consumable replenishment. This disaggregation favors vendors with localized technical service teams in Doha over distant European headquarters.
GCC Biopsy Devices Market Segmentation
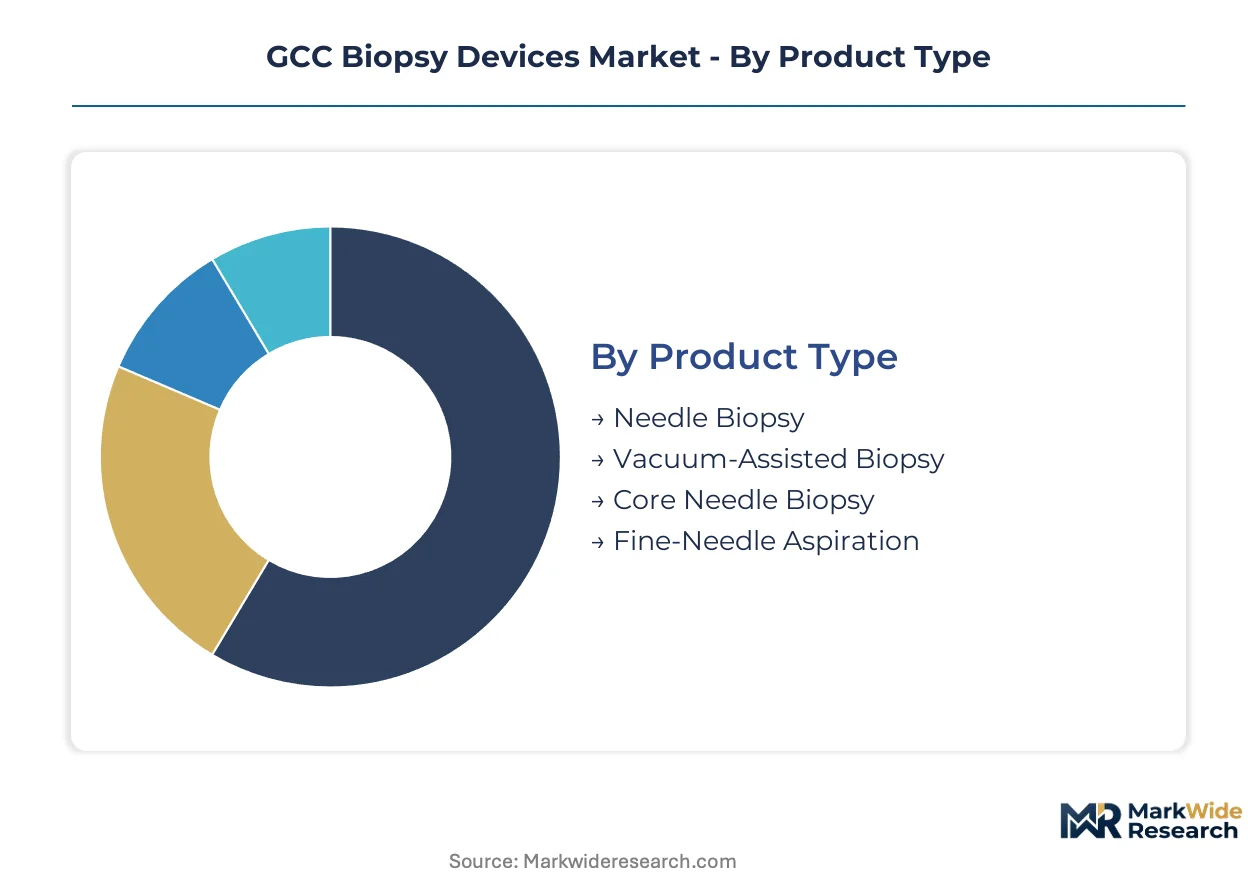
Segmentation in GCC biopsy devices reveals how procurement priorities diverge across clinical settings and regulatory environments. Understanding these splits enables vendors to align product configurations with specific facility workflows and compliance pathways.
Product Type:
Replacement cycles vary sharply across biopsy instrument categories, with vacuum platforms refreshing every 4-6 years versus 8-10 years for conventional needle systems.
- Vacuum-Assisted Biopsy:Automated tissue acquisition systems deploy controlled negative pressure between 20-25 inHg to extract contiguous core specimens. Demand clusters in Saudi Arabia's King Faisal Specialist Hospital and Dubai's private oncology towers, where breast screening program volumes strain manual extraction throughput.
- Core Needle Biopsy:Spring-loaded or vacuum-assisted cannulae with 8-20 gauge stainless steel construction retrieve tissue cores for histopathological staging. Procurement concentrates in Qatar's Hamad Medical Corporation network, where SFDA-equivalent technical standards elevate quality benchmarks for reusable instrument sterilization cycles.
- Needle Biopsy:Conventional percutaneous instruments for superficial lesion access.
- Fine-Needle Aspiration:Low-gauge needles for cytological sampling without core preservation.
Vacuum-assisted systems sit at the top of the volume ranking, with robotic-compatible platforms climbing the fastest.
End User:
Margin structures diverge across facility types, with cancer care centers capturing bundled pathology service premiums unavailable to general hospitals.
- Cancer Care Centers:Dedicated oncology facilities with integrated histopathology laboratories and dedicated interventional radiology suites. Procurement in Riyadh's tertiary hubs bundles device placement with long-term service contracts, locking in consumable replenishment revenue streams.
- Hospitals:General acute care facilities across Saudi Arabia's Ministry of Health network and Emirates Health Services. Centralized purchasing in Jeddah and Abu Dhabi prioritizes multi-system compatibility to reduce training overhead across rotating clinical staff.
- Diagnostic Labs:Independent pathology service providers without procedural capabilities.
- Ambulatory Surgical Centers:Same-day procedure facilities with limited imaging infrastructure.
Hospitals dominate absolute procurement tonnage, though cancer care centers deliver the steepest expansion trajectory as Gulf health systems consolidate oncology services.
Application:
Procedure complexity and reimbursement differentiation shape device specification requirements across anatomical targets.
- Breast Biopsy:Stereotactic or ultrasound-guided tissue extraction for mammographic abnormality confirmation. Saudi Arabia's national screening program expansion drives vacuum-assisted system deployment in Jeddah and Riyadh clusters, where specimen radiography integration reduces false-negative rates.
- Prostate Biopsy:Transrectal or transperineal needle access for oncological staging. Adoption in Dubai's private hospital sector accelerates around MRI-ultrasound fusion platforms, though interventional urologist scarcity constrains procedural volume growth.
- Liver Biopsy:Percutaneous or transjugular access for hepatic pathology diagnosis.
- Lung Biopsy:CT-guided percutaneous or bronchoscopic tissue sampling for pulmonary nodule characterization.
Breast applications command the largest installed base, with prostate procedures gaining share fastest amid MRI-targeting technology diffusion.
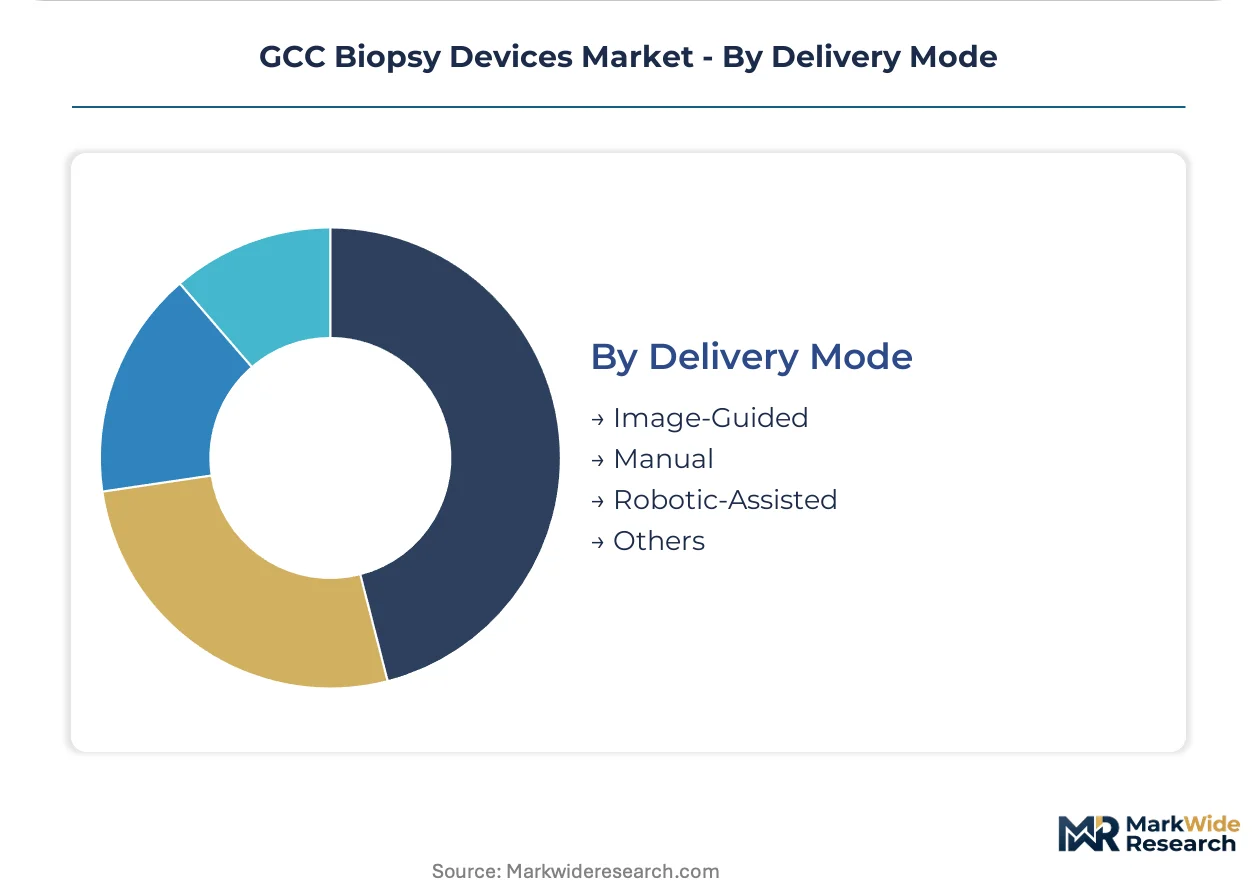
Delivery Mode:
Capital intensity and radiologist ergonomics create sharp segmentation in how tissue extraction is performed across Gulf health systems.
- Robotic-Assisted:Automated needle positioning systems with pre-programmed trajectory planning and real-time imaging feedback. Qatar's Hamad Medical Corporation prioritizes these platforms to reduce radiologist repetitive strain injury and standardize procedural outcomes across its multi-site network.
- Image-Guided:Ultrasound, CT, or MRI-directed manual needle placement with real-time visualization. This modality dominates Saudi Arabia's regional hospitals where capital constraints limit robotic system acquisition, though maintenance networks for legacy imaging integration create vendor stickiness.
- Manual:Palpation-directed or anatomical landmark-based needle insertion without real-time imaging.
- Others:Emerging navigation technologies including electromagnetic tracking and augmented reality overlay systems.
Image-guided delivery holds the dominant position by procedure count, with robotic-assisted configurations expanding most quickly as Gulf health systems prioritize workforce retention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia commands the largest procurement volume in the GCC biopsy devices landscape, while the United Arab Emirates operates the most diversified private hospital procurement channels. Qatar concentrates the highest robotic-assisted system density per capita among Gulf health systems.
Saudi Arabia
King Faisal Specialist Hospital and the Ministry of Health's tertiary network drive vacuum-assisted biopsy system demand through consolidated breast screening programs. SFDA's interim medical device regulations mandate local authorized representative presence, compressing market entry timelines for new entrants. Riyadh and Jeddah clusters anchor procurement concentration as oncology hubs expand minimally invasive diagnostic capacity.
United Arab Emirates
Dubai's private oncology towers and Abu Dhabi's Emirates Health Services network prioritize multi-system compatibility to reduce training overhead across rotating clinical staff. MOHAP's 2024 technical documentation requirements for Class III devices extend clinical evidence submission timelines with Gulf-specific usability studies. Dubai Healthcare City and Abu Dhabi's Sheikh Khalifa Medical City concentrate image-guided platform deployment.
Qatar
Hamad Medical Corporation's multi-site network prioritizes robotic-assisted delivery systems to reduce radiologist repetitive strain injury and standardize procedural outcomes. The country's national health strategy bundles device placement with long-term service contracts. Doha anchors maintenance network concentration as cancer care centers disaggregate procurement into separate maintenance, software, and consumable negotiations.
Kuwait
The country's nascent minimally invasive diagnostic infrastructure offers first-mover positioning before MOH-equivalent regulations mature. General hospitals currently rely on manual and image-guided delivery modes pending capital allocation for robotic systems. Kuwait City medical districts concentrate early vacuum-assisted system trials as pathology laboratory capacity expands.
Bahrain
King Hamad University Hospital and the Ministry of Health's centralized purchasing prioritize cost-efficient core needle systems for general diagnostic applications. The country's compact geography enables rapid maintenance response times from regional service hubs. Manama's Salmaniya Medical Complex concentrates interventional radiology training programs that feed procedural expansion across Gulf health systems.
GCC Biopsy Devices Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated device-informatics vendors capturing recurring service revenue while component suppliers compete on stainless steel cannulae specifications. The vendor base organizes around three archetypes: full-stack platform providers with proprietary imaging integration, precision needle specialists with gauge-specific manufacturing depth, and regional distributors with SFDA-authorized local entity status. Consolidation pressure intensifies as procurement directors specify cartridge compatibility across multiple vacuum-assisted platforms, compressing vendor lock-in. M&A activity targets localized technical service capabilities, while portfolio diversification into software-defined imaging bundles displaces pure hardware vendors.
Within the full-stack platform tier, Becton Dickinson and Company and Hologic, Inc. anchor competitive positioning through integrated informatics infrastructure and proprietary specimen radiography respectively. Medtronic plc occupies the robotic-assisted delivery vector where automated positioning systems command premium placement in Saudi Arabia's largest hospital networks. These three exemplify how Gulf health systems prioritize vendors with localized regulatory affairs teams and Doha-based technical service presence over distant European headquarters.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| Boston Scientific Corporation |
| Cardinal Health, Inc. |
| Cook Medical, Inc. |
| Danaher Corporation |
| Hologic, Inc. |
| Medtronic plc |
| Argon Medical Devices, Inc. |
| CONMED Corporation |
| Others |
Cost & Logistics Intelligence
SFDA-mandated local authorized representative requirements are compressing procurement timelines for Gulf health systems, forcing device vendors to absorb compliance infrastructure costs that reshape margin structures across Saudi Arabia and the United Arab Emirates. This regulatory pressure concentrates pricing power with incumbents who have already deployed Doha-based technical service teams and Riyadh-registered legal entities.
Pricing Analysis
Capacity additions in Germany and Japan for specialty stainless steel cannulae are reshaping price floors for gauge-specific needle production across the GCC. Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with robotic-assisted platforms commanding premiums based on ISO 13485 certification tiers and bundled software maintenance. Price differentiation stems from after-sales service depth and vacuum pump compatibility guarantees. Cost compression in standard-tier core needle systems is intensifying because procurement directors in Saudi Arabia's Ministry of Health network now specify cartridge interoperability across multiple platforms. Cancer care centers show least price sensitivity due to bundled pathology service premiums, while general hospitals in Bahrain's centralized purchasing system drive hardest bargain negotiations.
Supply Chain Analysis
SFDA and MOHAP domestic-content mandates are reshaping sourcing strategies, compelling manufacturers to establish regional assembly presence or absorb elevated import duties. Manufacturing concentrates in Germany, Japan, and the United States for precision cannulae and vacuum pump assemblies. Raw material dependencies include specialty stainless steel alloys, medical-grade silicone tubing, and high-precision pressure sensors. Single-source vulnerability pervades the 20-25 inHg vacuum pump segment where three dominant suppliers feed Gulf maintenance networks. Distribution runs through SFDA-authorized local entities in Riyadh and MOHAP-registered distributors in Dubai, with direct hospital contracting emerging as an alternative channel in Saudi Arabia's tertiary care centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC biopsy devices market compounds steadily as oncology hub consolidation across Riyadh, Jeddah, and Doha locks in recurring consumable revenue streams for established vendors. This structural demand driver insulates participants from cyclical procurement volatility.
For Market Incumbents: Cement service contract unbundling capabilities across Qatar's Hamad Medical Corporation network before competitors replicate Doha-based technical presence. Deepen backward integration into stainless steel cannulae production to offset input volatility from German and Japanese specialty mills. Defend against emerging software-defined imaging specialists by accelerating AI-assisted specimen radiography development for breast biopsy platforms.
For New Entrants and Emerging Players: Begin with Kuwait's nascent minimally invasive diagnostic infrastructure before MOH-equivalent regulations mature and compliance costs escalate. Target diagnostic labs and ambulatory surgical centers in Kuwait City medical districts where vacuum-assisted system penetration remains minimal. Pursue direct hospital contracting through SFDA-authorized local entity formation rather than traditional distributor markups.
For Investors and Strategic Acquirers: Asymmetric upside sits with precision needle specialists possessing gauge-specific manufacturing depth and existing ISO 13485 certification. Long-term viability favors vendors who can bridge hardware placement with software-defined imaging bundles across the projection horizon. Acquisition focus should center on regional distributors with established SFDA-authorized local entity status. Monitor harmonization timelines between Saudi and Emirati regulatory pathways as the signal for centralized purchasing consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Local Authorized Representative Establishment | Mandatory market entry pathway compresses timelines for Saudi Arabia device registration. |
| Software-Defined Imaging Bundle Development | AI-assisted specimen radiography integration creates differentiated value for cancer care centers. |
| Stainless Steel Cannulae Backward Integration | Captive supply of gauge-specific needles insulates margins from German and Japanese mill volatility. |
| Direct Hospital Contracting Capability | Bypassing distributor markups captures margin in Saudi Arabia's centralized purchasing shifts. |
| Robotic-Assisted Delivery Platform Deployment | Automated positioning systems command premium placement in Qatar's Hamad Medical Corporation network. |
Research Approach
Multiple input streams — primary interviews with interventional radiologists and hospital procurement committees, secondary validation through SFDA registration databases and GPO contract repositories, and trade data reconciliation — were synthesized to construct market estimates. Conversations with biomedical engineers, GPO contracts managers, and regulatory affairs specialists at device manufacturers informed procurement workflow dynamics. Secondary sources included hospital procurement databases, MOHAP technical documentation filings, and customs records for medical device imports. Bottom-up installation base modeling and top-down healthcare expenditure triangulation anchored volume and value projections.
Data-stream reconciliation across product type, delivery mode, end user facility tier, and application anatomy enabled segmentation-level forecasting throughout the projection horizon. CAGRs were derived from installed base refresh cycles, procedure volume growth assumptions, and technology substitution curves. Industry-specific inputs encompassed breast screening program expansion timelines in Saudi Arabia, interventional radiologist training pipeline outputs from Bahrain's Salmaniya Medical Complex, and MRI-ultrasound fusion platform adoption rates in Dubai's private hospital sector.
Caveats apply where interventional radiologist scarcity constraints, histopathology laboratory bottlenecks, or stainless steel input volatility could materially shift the outlook. Forecasts reflect assumptions regarding regulatory harmonization progress and procurement centralization trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cyclotron Market
Medical Devices
Chile Extracorporeal Shock Wave Lithotripsy Market
Medical Devices
Solar Surgical Light Market
Medical Devices
Small Bone and Joint Devices Market
Medical Devices
Global Patient Warming Systems Market
Medical Devices
France Spinal Surgery Devices Market
Medical Devices
Saudi Arabia Aesthetic Devices Market
Medical Devices
Medical Device Films Market
Medical Devices
Life Science and Chemical Instruments Market
Medical Devices
Medical Hydrophilic Coatings Market
Medical Devices
Cardiac Catheters and Guidewires Market
Medical Devices
Global Uterine Manipulation Devices Market
Medical Devices
US Medical Device Outsourcing Market
Medical Devices
Latin America Insulin Delivery Devices Market
Medical Devices
Arthroscopy Market
Medical Devices
Needle-Free Injectors Market