
 Mexico Power Market | 2026-2036
Mexico Power Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Power Market Outlook
Private generation capacity in Mexico is shifting toward combined-cycle natural gas and utility-scale renewables. Iberdrola México leverages its operational scale across multiple states to anchor long-term supply contracts with industrial buyers. CFE sustains its vertical control over national transmission infrastructure while competing in wholesale markets under open-access rules. Enel Green Power México specializes in wind development across Oaxaca's Isthmus region, where consistent trade winds dominate capacity factors.
The Mexico Power Market encompasses electricity generation, transmission, and distribution infrastructure serving residential, commercial, and industrial loads across the national interconnected system. Primary infrastructure spans 400 kV trunk lines, combined-cycle gas turbines exceeding 500 MW per unit, and inverter-coupled solar photovoltaic arrays designed for grid-code compliance under CENACE interconnection standards. Renewable technology segments, particularly solar and wind, are capturing incremental capacity additions as energy reform regulations permit private power purchase agreements. Natural gas technology segments retain structural prominence due to pipeline connectivity with Permian Basin supply and lower marginal costs relative to fuel oil alternatives.
CRE regulates market participant registration and tariff methodologies under the Ley de la Industria Eléctrica, while SEMARNAT enforces environmental impact assessments for generation projects exceeding 300 MW. CENACE operational rules shape dispatch priority and grid access queues, directly influencing project development timelines and financing structures. Stakeholders must monitor constitutional reform debates and regulatory secondary law amendments that could alter private sector participation frameworks.
Market Dynamics
The 2013 constitutional energy reform and its secondary legislation created a bifurcated market structure where private generators compete against CFE's legacy assets while transmission remains a state-controlled monopoly. This tension between open-access generation and restricted grid access defines competitive positioning.
Growth Catalysts
- Ley de la Industria Eléctrica framework:Open-access transmission rules enable private power purchase agreements with industrial offtakers, particularly automotive assembly plants in central Mexico.
- Permian Basin pipeline connectivity:Natural gas infrastructure expansion lowers fuel input costs for combined-cycle plants serving manufacturing clusters in Nuevo León.
- Automotive electrification mandates:OEM supplier parks require renewable energy certificates to meet corporate sustainability targets, driving wind and solar offtake.
Market Restraints
- CENACE interconnection queue congestion:Grid access approval timelines extend 18-24 months, delaying project commercial operation and financing close.
- Natural gas price volatility:Pipeline capacity constraints and Permian Basin supply fluctuations create margin compression for gas-fired generators.
- CFE vertical integration:The state utility controls transmission and distribution infrastructure, limiting third-party dispatch priority in congestion events.
Strategic Opportunities
- Behind-the-meter solar:Industrial facilities in Guanajuato and Querétaro are deploying captive PV arrays to bypass interconnection delays and reduce CFE tariff exposure.
- Green hydrogen pilot zones:SEMARNAT environmental permits for electrolyzer projects create early-mover positioning in industrial feedstock markets.
- Energy-as-a-service models:Third-party ownership structures allow SMEs to access distributed generation without balance-sheet capex requirements.
Industry Challenges
- Grid code compliance expertise:CENACE's inverter-coupled resource requirements demand specialized engineering talent scarce in regional labor markets.
- Land tenure negotiations:Wind projects in Oaxaca's Isthmus face communal land (ejido) assembly delays that extend development timelines.
- Legacy fuel oil plant stranded assets:CFE's aging thermal fleet requires costly environmental retrofits under SEMARNAT emissions rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Power Market |
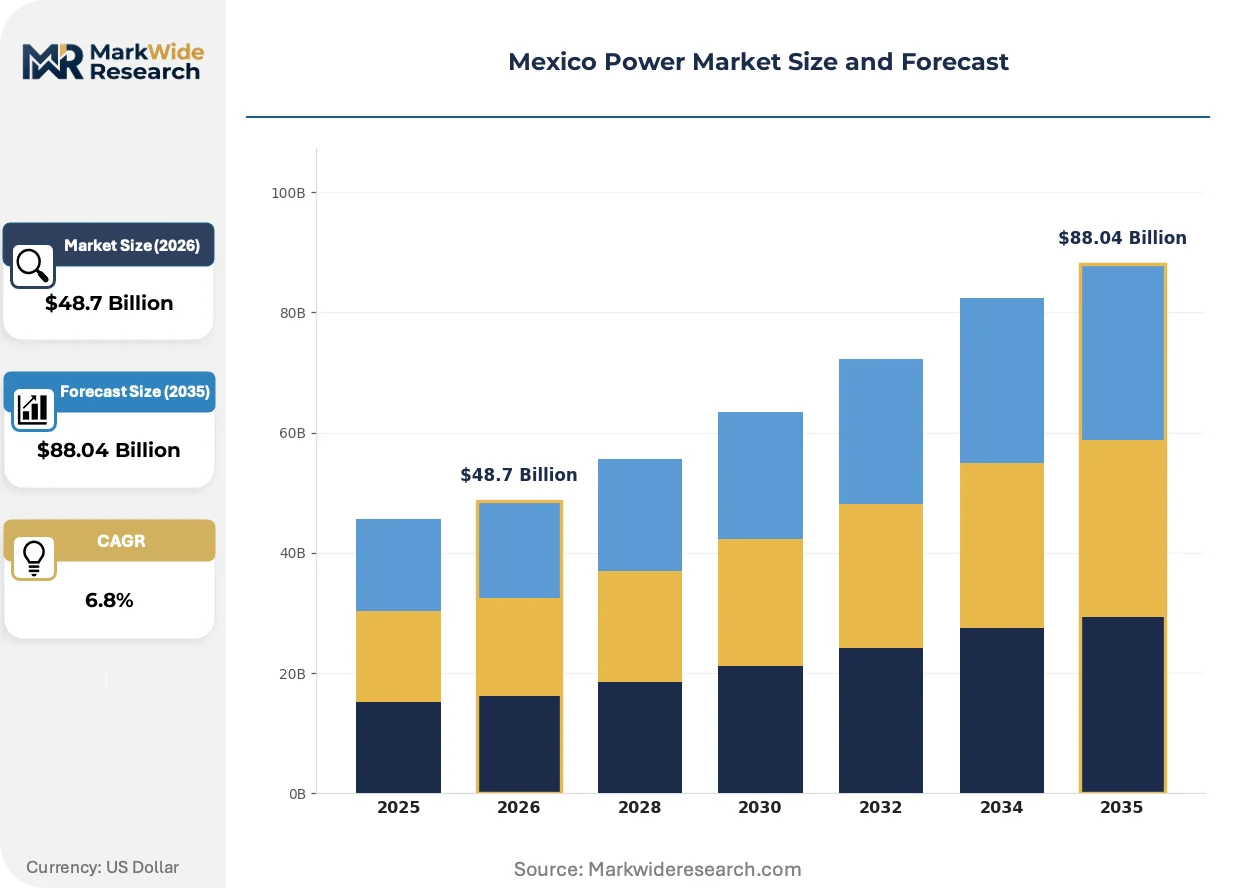
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Renewable, Non-renewable, Transmission, Distribution Technology: Solar, Wind, Hydro, Natural Gas End User: Residential, Commercial, Industrial, Agricultural Service Type: Consulting, Maintenance, Installation, Financing |
| Companies Covered | Comisión Federal de Electricidad (CFE), Iberdrola México, Enel Green Power México, Acciona Energía México, Sempra Infrastructure, Saavi Energía, EDF Renewables, Siemens Gamesa Renewable Energy, Schneider Electric, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Power Market Strategic Shifts
Technology convergence and regulatory recalibration are compressing development cycles while reshaping how industrial buyers procure electricity. Three distinct movements are altering competitive dynamics.
Battery energy storage systems is converging with utility-scale solar installations to provide firm capacity under CENACE's new ancillary services market rules. IPP developers in Sonora and Baja California are pairing 200 MW PV arrays with four-hour lithium-ion configurations. This hybrid architecture is displacing standalone gas peakers in nodal price zones with high solar penetration.
CRE's 2023 distributed generation regulatory update streamlined net metering caps and interconnection standards for sub-500 kW installations. The reform accelerates commercial and industrial solar adoption by reducing permitting friction. Manufacturing SMEs in Puebla and Tlaxcala are responding by aggregating rooftop portfolios through energy service companies.
Corporate renewable energy procurement is fragmenting traditional utility contracting patterns. Multinational automotive and electronics manufacturers now require 100% renewable supply with hourly matching certificates. This specification is compressing developer margins while favoring vertically integrated IPPs with existing wind and solar portfolios in Oaxaca and the Yucatán Peninsula.
Mexico Power Market Segmentation
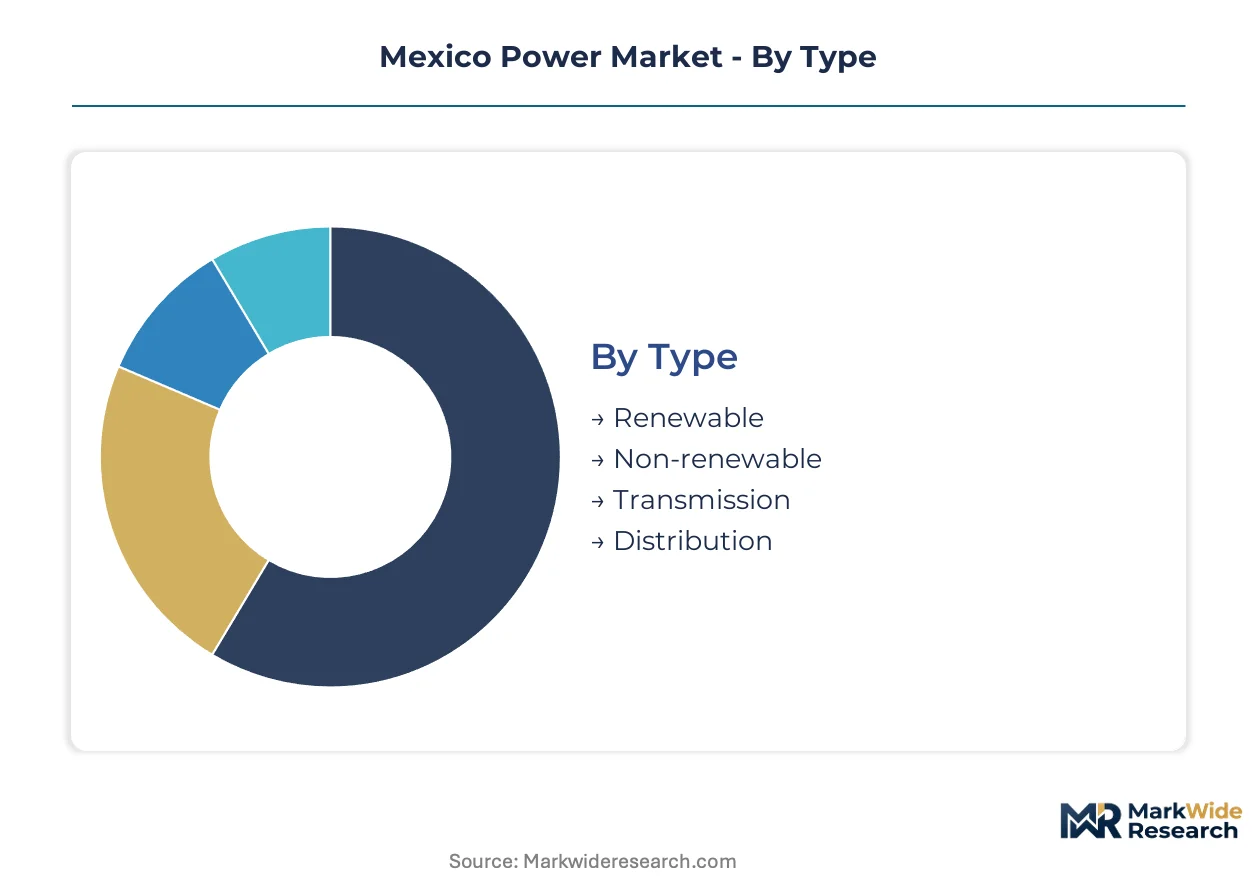
Segmentation in Mexico's power market reveals how capital flows, regulatory frameworks, and offtake patterns concentrate across distinct technology and customer categories. Understanding these divisions clarifies where private developers compete against CFE legacy assets and where transmission bottlenecks distort competitive outcomes.
Type:
Capital intensity varies sharply across infrastructure categories, with transmission assets demanding the longest payback periods due to state-controlled monopoly structures.
- Renewable:Utility-scale solar and wind installations require upfront capital of $1-2 million per MW installed, with developers recovering costs through 15-20 year power purchase agreements with industrial offtakers in Guanajuato and Nuevo León. The segment benefits from CRE's open-access rules enabling direct contracting with automotive assembly plants seeking hourly-matched renewable certificates.
- Non-renewable:Combined-cycle natural gas turbines dominate baseload provision, leveraging Permian Basin pipeline connectivity to serve manufacturing clusters. These assets face margin pressure from fuel price volatility and CFE dispatch priority during grid congestion events.
- Transmission:400 kV trunk lines and substation infrastructure remain exclusively state-controlled under CFE's vertical monopoly, limiting private participation to isolated interconnection upgrades.
- Distribution:Last-mile networks serving residential and SME loads operate under CFE's unified control, though private distributed generation is bypassing traditional distribution through behind-the-meter solar deployments.
Non-renewable capacity absorbs the bulk of installed capacity; renewable generation is expanding most quickly under corporate procurement mandates.
Technology:
Technology selection tracks geographic resource availability and proximity to demand centers rather than uniform national deployment.
- Solar:Photovoltaic arrays concentrate in Sonora and Baja California where irradiance levels exceed 2,200 kWh/m² annually. Developers pair 200 MW installations with four-hour battery storage to firm capacity under CENACE ancillary services market rules.
- Wind:Oaxaca's Isthmus region hosts the majority of operational capacity, with consistent trade winds delivering capacity factors above 35 percent. Projects face ejido land assembly delays that extend development timelines 12-18 months beyond initial projections.
- Hydro:Existing reservoirs and run-of-river facilities provide dispatchable renewable output, though environmental permitting under SEMARNAT constraints limits greenfield expansion.
- Natural Gas:Combined-cycle plants anchor baseload supply in central Mexico's manufacturing corridor, with pipeline infrastructure from the Permian Basin determining competitive positioning.
Natural gas retains the largest share of generation output; solar capacity is climbing the fastest as interconnection queues clear for hybrid storage projects.
End User:
Customer segmentation reveals divergent procurement patterns, with industrial buyers driving market structure evolution through direct contracting.
- Industrial:Automotive and electronics manufacturers in Querétaro, Puebla, and Tlaxcala negotiate long-term power purchase agreements specifying 100 percent renewable supply with hourly matching. These buyers bypass CFE tariffs through direct IPP contracting enabled by Ley de la Industria Eléctrica reforms.
- Commercial:Retail and office loads aggregate distributed generation through energy service companies, with CRE's 2023 net metering reforms accelerating sub-500 kW solar adoption across SME portfolios.
- Residential:Household consumption remains tethered to CFE's regulated tariff structure, limiting private market participation to affluent segments with rooftop solar capacity.
- Agricultural:Irrigation pumping and processing loads in Sinaloa and Jalisco face seasonal demand patterns that complicate long-term contracting, though behind-the-meter solar is reducing diesel generator dependence.
Industrial offtake commands the deepest private market penetration; commercial segment aggregation models are gaining share fastest among SME manufacturing clusters.
Service Type:
Ancillary services surrounding physical infrastructure deployment follow distinct margin structures and competitive dynamics.
- Consulting:Engineering firms specializing in CENACE grid code compliance command premium fees due to scarce talent pools for inverter-coupled resource integration.
- Maintenance:Long-term service agreements for combined-cycle turbines and wind farms generate recurring revenue streams tied to availability guarantees.
- Installation:EPC contractors face compressed margins as standardized solar and storage configurations commoditize execution risk.
- Financing:Project finance structures for utility-scale renewables rely on multilateral development bank participation to extend tenors beyond commercial bank capacity.
Installation services handle the largest project volume; financing advisory is scaling most rapidly as institutional investors enter Mexican renewable infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Permian Basin natural gas flows anchor competitive positioning across Mexico's central manufacturing corridor, with pipeline infrastructure determining cost structures for combined-cycle generators serving industrial load centers.
Nuevo León
Automotive assembly plants and steel foundries drive baseload demand in Monterrey's industrial periphery. CENACE grid codes require frequency response capabilities for new interconnections. Apodaca supplier parks negotiate direct power purchase agreements with private generators to bypass CFE tariff volatility.
Bajío Region
Guanajuato and Querétaro host electronics contract manufacturers requiring hourly-matched renewable certificates. SEMARNAT environmental permits for utility-scale solar face 14-month approval timelines. Silao automotive clusters aggregate distributed generation through energy service company structures.
Oaxaca
Consistent trade winds across the Isthmus of Tehuantepec deliver capacity factors exceeding 35 percent for wind farms. Ejido communal land assemblies delay project timelines 12-18 months beyond initial schedules. Juchitán serves as the logistical hub for turbine component staging and grid connection.
Sonora
Solar irradiance levels surpass 2,200 kWh/m² annually in the Sonoran Desert. CENACE's 2023 ancillary services market rules enable battery storage pairing with photovoltaic arrays. Hermosillo manufacturing plants deploy behind-the-meter installations to hedge against interconnection queue congestion.
Yucatán Peninsula
Isolated grid architecture limits transmission import capacity from the national interconnected system. CRE's open-access rules permit private bilateral contracting with tourism and agro-industrial offtakers. Mérida's urban load center experiences voltage stability constraints during peak cooling demand.
Mexico Power Market Competitive Environment
Global majors compete with regional champions across generation technology and offtake contracting. The market structure bifurcates between state-controlled transmission infrastructure and contested wholesale generation markets. Three archetypes dominate: vertically integrated state utilities, multinational independent power producers, and specialized renewable developers. Competitive moves concentrate on long-term power purchase agreement origination and strategic land assembly for renewable sites.
Within the multinational IPP tier, Iberdrola México and Enel Green Power México occupy positions exemplifying scale-driven renewable development. Comisión Federal de Electricidad anchors the state-controlled segment, representing vertical integration across transmission and legacy thermal assets. Saavi Energía sits within the mid-cap independent producer archetype, focusing on combined-cycle natural gas positioning near Permian Basin pipeline termini.
| Leading Market Players |
|---|
| Comisión Federal de Electricidad (CFE) |
| Iberdrola México |
| Enel Green Power México |
| Acciona Energía México |
| Sempra Infrastructure |
| Saavi Energía |
| EDF Renewables |
| Siemens Gamesa Renewable Energy |
| Schneider Electric |
| Others |
Value Chain & Pricing Dynamics
SEMARNAT emissions compliance mandates gate qualified supply access for combined-cycle turbine components and premium-tier EPC contracting, filtering out non-certified developers and compressing margins for compliant bidders serving CFE and private IPPs alike.
Pricing Analysis
Long-term service agreement bundling dominates competitive positioning, with unbundled EPC-only quotes commanding 15-20 percent discounts against full-wrap contractor offerings. Pricing stratifies across premium, standard, and economy tiers based on CENACE grid code certification level and OEM spare parts availability. Cost compression in standard-tier solar EPC is intensifying because standardized 200 MW PV-plus-storage configurations commoditize execution risk. Industrial offtakers in Nuevo León exhibit lowest price sensitivity due to baseload reliability requirements, while agricultural irrigation cooperatives in Sinaloa face acute tariff exposure.
Supply Chain Analysis
Dual-sourcing requirements for turbine rotors and inverters now appear in 80 percent of utility-scale RFPs, forcing developers to qualify both Siemens Gamesa and GE Haliade suppliers for wind projects. Manufacturing concentrates in China for lithium-ion battery modules, Germany for gas turbine components, and Mexico for balance-of-system steel structures. Raw material dependencies span polysilicon ingots, high-grade steel forgings, and rare-earth permanent magnets. Single-source vulnerability persists for CENACE-certified power electronics. Distribution runs through EPC-led turnkey contracts with multilateral development bank co-financing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CENACE interconnection queue congestion props pricing power for existing grid-connected assets, creating a supply-constrained environment where queue position determines competitive viability.
For Market Incumbents: Cement dispatch priority through strategic battery co-location at existing nodal injection points, defending against merchant solar entrants flooding daytime price zones. Deepen backward integration into Permian Basin gas supply contracts to isolate fuel cost volatility. Prioritize CENACE ancillary services market pre-qualification to capture frequency response premiums before rule changes favor newer assets. For New Entrants and Emerging Players: Enter via behind-the-meter solar deployment in Guanajuato automotive supplier parks, where interconnection delays create captive demand for distributed generation bypassing CFE tariffs. Target SME manufacturing clusters in Puebla through energy-as-a-service ownership structures eliminating balance-sheet capex barriers. Pursue land assembly partnerships with ejido communal authorities in Oaxaca before wind resource sites face full preemption. For Investors and Strategic Acquirers: CRE regulatory staff expansion announcements are the leading indicator that interconnection queue processing will accelerate, unlocking stranded project pipelines. Long-term viability hinges on exposure to corporate PPA origination rather than merchant spot market dependence. Monitor SEMARNAT environmental permit approval velocity as the signal for development timeline compression. Acquisition targets should display existing grid connection agreements with CFE transmission access secured.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Origination | Long-term contracting with automotive OEMs anchors revenue visibility under CENACE open-access rules. |
| Backward Integration into Gas Supply | Direct Permian Basin pipeline commitments isolate fuel cost volatility for combined-cycle operators. |
| Grid Code Certification Investment | CENACE inverter-coupled resource compliance unlocks ancillary services market participation premiums. |
| Ejido Land Assembly Partnership | Communal tenure negotiations in Oaxaca secure wind sites with 35 percent-plus capacity factors. |
| Battery Storage Co-location | Four-hour lithium-ion pairing with solar arrays displaces gas peakers in high-irradiance zones. |
Study Parameters
Multi-period observation of CENACE interconnection queue depths, CRE permit approval timelines, and corporate PPA announcement volumes anchored the trend analysis, supplemented by interviews with IPP project developers, EPC contractors, CFE transmission planning officers, and SEMARNAT environmental permit specialists. Secondary validation drew from CENACE operational statistics, CRE regulatory filings, EIA natural gas flow data, and IEA Mexico energy outlook reports. Bottom-up project pipeline aggregation and top-down macroeconomic demand modeling were triangulated to cross-check capacity and consumption forecasts.
Segment-weighting approaches modeled technology type, project scale tier, end-user industry, and regional grid architecture across the projection horizon. CAGRs were derived from installed capacity buildout trajectories against manufacturing load growth assumptions. Forecast inputs incorporated automotive electrification mandate stringency, Permian Basin pipeline expansion schedules, and CFE legacy asset retirement timelines.
Revisions become necessary when constitutional reform debates alter private sector participation frameworks or when CENACE operational rule changes materialize unexpectedly. Deviation in interconnection queue processing velocity or SEMARNAT permit approval timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Rotating Phase Converter Market
Power
Resonant Power Converters Market
Power
Solar UPS Market
Power
Sudan Power EPC Market
Power
Middle East and Africa Combined Heat & Power Market
Power
Angola Power EPC Market
Power
Argentina Power Market
Power
Japan Power Market
Power
Kuwait Power Market
Power
Compact Substation Market
Power
Middle-East and Africa Power Market
Power
Gabon Power Market
Power
Robotic Power Source Market
Power
Europe Submarine Power Cables Market
Power
Norway Power Market
Power
Flue Gas Desulfurization Unit Market