
 Power Purchase Agreement Market | 2026-2036
Power Purchase Agreement Market Size, Share, and Industry Trends Forecast 2026-2036
Power Purchase Agreement Market Analysis
Battery storage co-location with solar photovoltaic arrays is expanding PPA value stacking and capacity factor economics. NextEra Energy leverages its vertically integrated development platform to control interconnection timelines and EPC costs across Florida and Texas markets. Engie anchors its competitive position through European offshore wind expertise now migrating into U.S. corporate procurement channels. Google sustains market leadership through its 24/7 carbon-free energy matching protocol, which differentiates standard annual renewable energy credits from hourly dispatch-aligned structures.
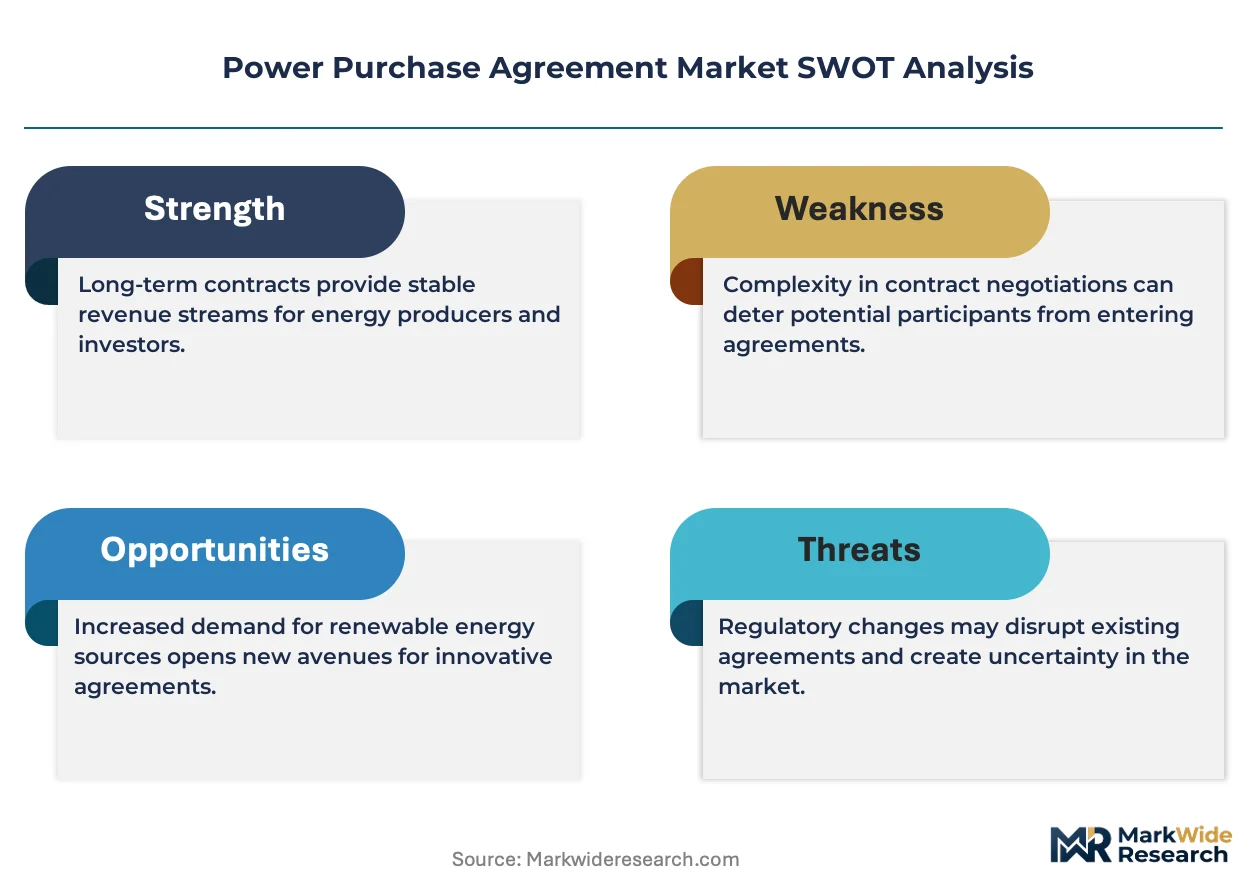
A power purchase agreement constitutes a long-term contractual arrangement, typically spanning 10 to 25 years, wherein an electricity buyer commits to purchasing power from a generator at a predetermined price or indexed formula, with contract structures varying by whether energy and renewable energy credits transfer physically or financially. Physical PPAs dominate procurement volumes for on-site and direct-wired installations where the buyer receives title to electrons, while virtual PPAs function as financial hedges that fix electricity cost exposure without altering retail utility relationships. Corporate PPAs represent the fastest-growing buyer category as Scope 2 emissions accounting under GHG Protocol standards drives direct contractual relationships with new-build renewable assets. Utility-scale solar farms command the largest share of contracted capacity additions, though wind farms retain margin advantages in regions with sustained capacity factors above 35 percent.
The Federal Energy Regulatory Commission's Order 2023 reforms to interconnection queue processes, combined with Internal Revenue Service guidance on Inflation Reduction Act bonus credit eligibility, are reshaping project development timelines and financing structures. State-level renewable portfolio standards in California, New York, and Illinois create mandatory demand pools that underpin long-term contract pricing visibility. Stakeholders must monitor interconnection cost allocation rulings and hourly carbon accounting methodologies as these determine which PPA structures retain premium pricing power versus commodity treatment.
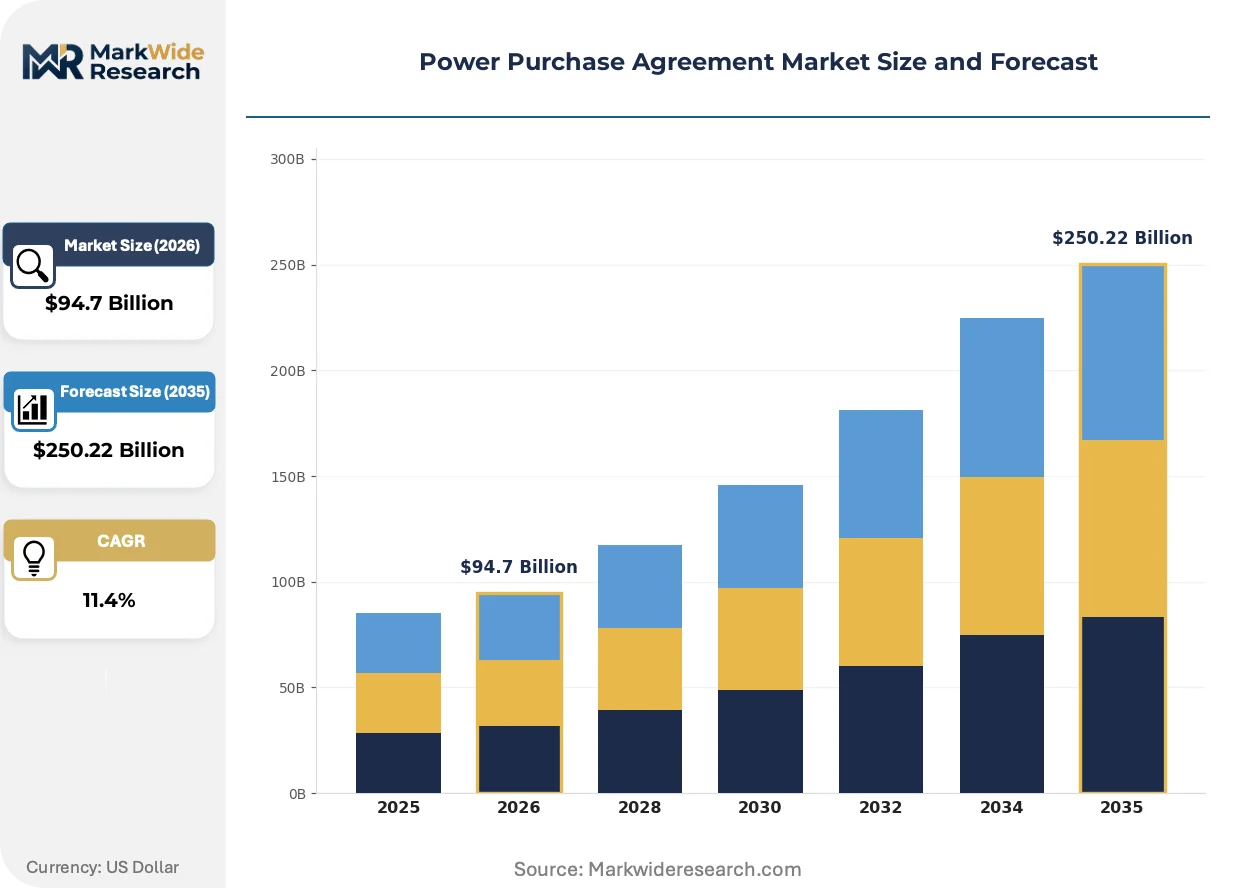
Market Dynamics
Interconnection queue reform is compressing project development timelines and redistributing capital risk between developers and offtakers across the Power Purchase Agreement Market.
Growth Catalysts
- Production Tax Credit Expansion:The Inflation Reduction Act's bonus credit structures for domestic content are reshaping project finance structures and accelerating new-build renewable commitments from corporate buyers.
- Data Center Load Growth:Hyperscale computing facilities in Texas and Virginia are driving unprecedented demand for 24/7 carbon-free energy matching through long-term contractual arrangements.
- Hourly Carbon Accounting:Emerging GHG Protocol standards for Scope 2 emissions measurement are forcing buyers toward dispatch-aligned renewable energy credits rather than annual averaging.
Market Restraints
- Grid Interconnection Costs:Network upgrade allocation disputes under FERC Order 2023 are creating capital uncertainty for projects in queue-heavy regions like PJM Interconnection.
- Transformer and Switchgear Supply:Lead times for high-voltage electrical equipment from concentrated Asian manufacturing bases are extending construction schedules.
- Interest Rate Sensitivity:Floating-rate construction debt exposure is compressing developer equity returns and tightening offtaker pricing negotiations.
Strategic Opportunities
- Battery Storage Co-location:Pairing lithium-ion systems with solar photovoltaic arrays is enabling capacity value stacking and firming services that command premium contract pricing.
- Green Hydrogen Offtake:Electrolyzer projects in Texas and California are creating new demand corridors for dedicated renewable energy supply with 15-20 year tenors.
- Virtual PPA Structuring:Financial hedging instruments are opening procurement channels for buyers without physical interconnection access or direct retail utility relationships.
Industry Challenges
- Interconnection Engineering Talent:Specialized transmission planning and grid modeling expertise is scarce relative to pipeline volume, delaying feasibility studies.
- Revenue Put Complexity:Tax equity partnership flips and back-leverage arrangements are requiring sophisticated structuring capabilities that outpace standard legal templates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Purchase Agreement Market |
| Market Size in 2026 | $94.7 Billion |
| Market Size in 2035 | $250.22 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Contract Type: Physical PPA, Virtual PPA, Synthetic PPA, Corporate PPA Utility Scale: Solar Farms, Wind Farms, Hydroelectric Plants, Biomass Facilities Buyer Type: Corporations, Utilities, Government Agencies, NGOs Sourcing Method: Direct Negotiation, Competitive Auction, Brokered Deals, Others |
| Companies Covered | Google, NextEra Energy, Amazon, Vistra, Constellation, Microsoft, TotalEnergies, Engie, Meta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Purchase Agreement Market Emerging Trajectories
Contract structures are evolving from annual renewable energy credit aggregation toward granular dispatch matching, while financing mechanisms adapt to capture Inflation Reduction Act incentive stacking.
Hybrid solar-plus-storage configurations are consolidating project economics by capturing multiple value streams through a single interconnection point. Corporate offtakers in manufacturing and data center verticals are requiring firm capacity guarantees alongside energy volume commitments. This technology convergence is compressing standalone solar PPA pricing power and rewarding developers with integrated engineering capabilities.
FERC Order 2023 reforms to interconnection queue cluster studies are accelerating timeline predictability for projects in early-stage development. The rule changes impose cost allocation transparency requirements that reduce speculative network upgrade exposure. Developers in California and Texas markets are restructuring milestone payment schedules to align with reformed study phases.
Buyers are renegotiating contract tenors and indexation clauses to manage basis risk between wholesale hub settlement and retail load obligations. Traditional annual renewable energy credit structures are losing favor to 24/7 carbon-free energy matching protocols that align hourly generation with consumption patterns. This behavioral shift is most visible among technology sector procurement teams with public net-zero commitments and sophisticated sustainability accounting functions.
Power Purchase Agreement Market Segmentation
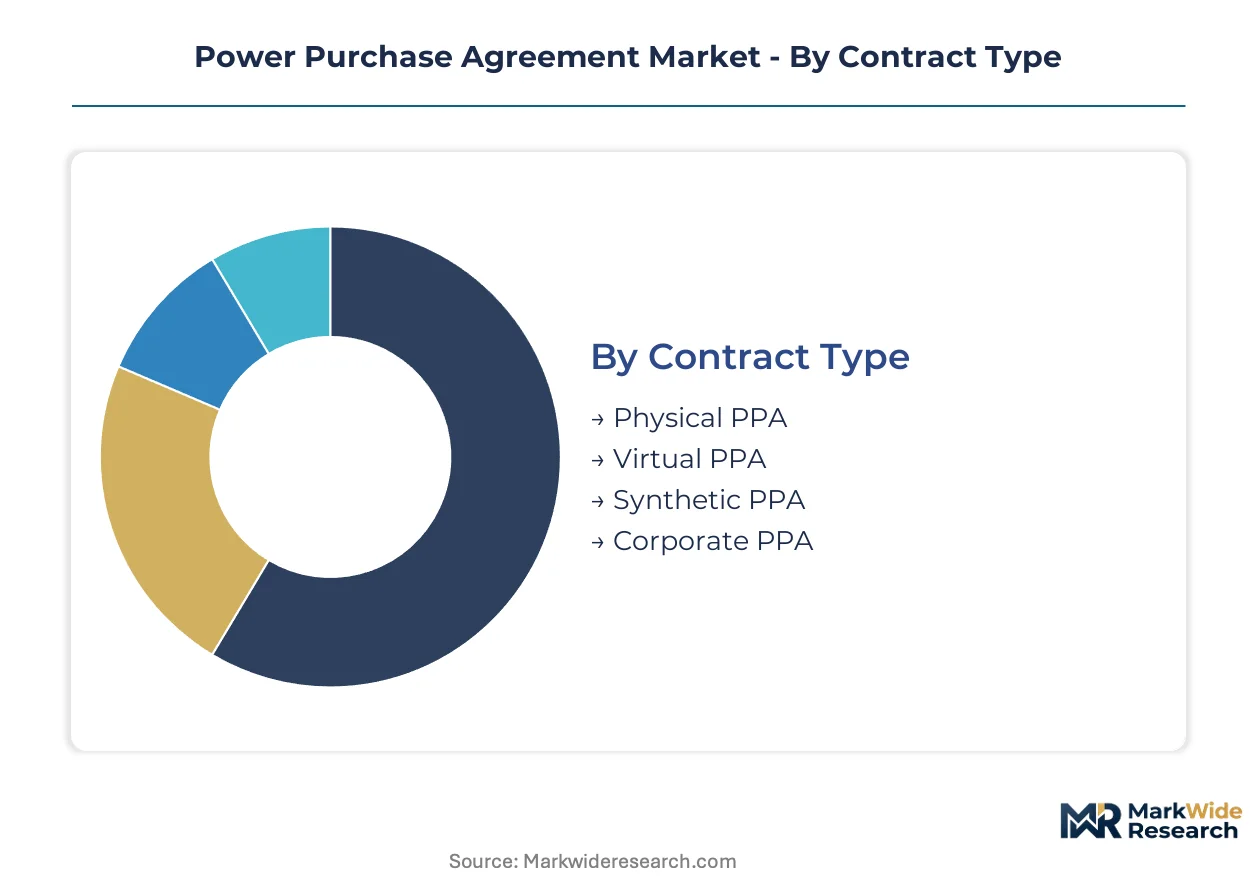
PPA segmentation reveals how contract structures, generation technologies, and procurement channels align capital deployment with buyer risk profiles. Each dimension carries distinct implications for tenor length, pricing mechanisms, and credit requirements.
Contract Type:
Standalone financial instruments operate independently of physical grid access, while embedded structures require direct interconnection and title transfer of electrons.
- Physical PPA:Direct wire arrangements transfer electricity and renewable energy credits to buyers with co-located or transmission-linked facilities. Data centers in Texas and Virginia favor this structure for 24/7 carbon-free energy claims under evolving GHG Protocol standards.
- Virtual PPA:Financial hedges fix electricity cost exposure through contract-for-difference settlements without altering retail utility relationships. Corporate buyers without direct interconnection access use these instruments to manage basis risk between wholesale hub prices and retail obligations.
- Synthetic PPA:Structured derivatives combining fixed-price energy swaps with REC purchases, appealing to buyers seeking simplified accounting without physical delivery complexity.
- Corporate PPA:Bilateral agreements between non-utility buyers and new-build renewable assets, driven by Scope 2 emissions reduction targets under science-based commitments.
Volume placements concentrate in Physical PPA structures; the faster expansion belongs to Corporate PPA channels as sustainability-linked financing proliferates.
Utility Scale:
Technology selection hinges on capacity factor economics, land availability, and interconnection queue positioning across ISO territories.
- Solar Farms:Photovoltaic arrays dominate contracted capacity additions due to modularity and declining module costs. California and Texas project pipelines favor solar for its construction speed and IRA domestic content bonus eligibility.
- Wind Farms:Onshore turbines retain margin advantages in regions with sustained capacity factors above 35 percent, particularly the Great Plains and offshore Atlantic lease areas where Engie and Orsted anchor development.
- Hydroelectric Plants:Run-of-river and pumped storage facilities provide firm capacity with multi-decade asset lives, though limited greenfield development constrains new PPA availability.
- Biomass Facilities:Organic waste-to-energy and agricultural residue plants serve localized industrial heat and power demand, particularly in Midwestern states with established agricultural supply chains.
Solar Farms command the deepest procurement queues; Wind Farms show the steepest expansion trajectory in offshore zones with streamlined permitting.
Buyer Type:
Creditworthiness tiers and procurement sophistication determine contract tenors, collateral requirements, and developer offtake risk pricing.
- Corporations:Technology and manufacturing entities with investment-grade ratings and public net-zero commitments. Google, Microsoft, and Amazon Web Services drive 24/7 carbon-free energy matching protocols that reshape standard contract structures.
- Utilities:Investor-owned and public power entities procuring under state renewable portfolio standards. California IOUs and Texas municipal utilities anchor baseload replacement strategies as coal retirements accelerate.
- Government Agencies:Federal, state, and municipal entities leveraging sovereign credit to secure below-market pricing through long-dated contracts, particularly for defense installations and water treatment facilities.
- NGOs:Universities, hospital systems, and cooperative purchasing alliances aggregating smaller loads into viable offtake blocks through master agreements with developer portfolios.
Corporations dominate headline contract volumes; Government Agencies provide the most stable counterparty risk profiles for tax equity structuring.
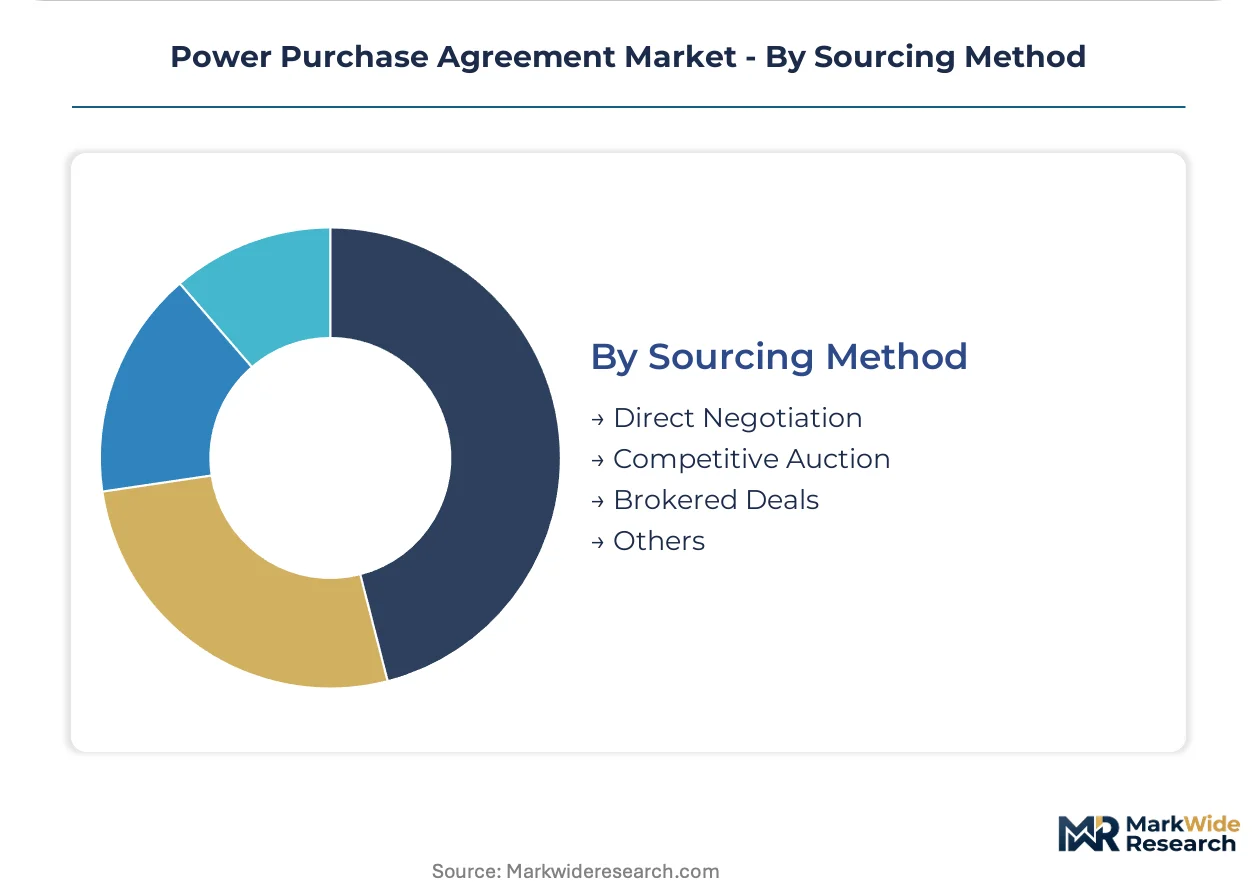
Sourcing Method:
Channel selection reflects information asymmetry, timeline urgency, and buyer internal procurement capabilities.
- Direct Negotiation:Bilateral discussions between experienced buyers and established developers, common for repeat counterparties with standardized term sheets and precedent transactions.
- Competitive Auction:Structured RFP processes run by utilities, corporate procurement teams, or aggregation platforms, compressing developer margins through transparent price discovery.
- Brokered Deals:Intermediary-facilitated matching of buyers with project pipelines, valuable for first-time corporate entrants lacking direct developer relationships.
- Others:Consortium arrangements, green tariffs, and sleeved structures where retail utilities intermediate between wholesale generators and end-use customers.
Competitive Auction channels capture the largest transaction flow; Brokered Deals are climbing fastest as mid-market corporate participation expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate procurement concentrates in the United States where data center load growth and IRA tax credit expansion drive contract velocity. Texas, California, and PJM Interconnection states anchor development pipelines through interconnection queue positioning and renewable portfolio standards.
United States
Hyperscale computing facilities in Virginia and Texas demand 24/7 carbon-free energy matching through long-term tenors. FERC Order 2023 reforms interconnection queue cluster studies to accelerate timeline predictability. ERCOT and CAISO territories concentrate solar-plus-storage development where domestic content bonus eligibility shapes project finance.
Germany
Industrial manufacturers seek firm capacity guarantees alongside renewable energy certificates under evolving EU Green Deal implementation. The country's national energy regulator advances grid modernization timelines for corporate offtake. North Rhine-Westphalia industrial clusters anchor procurement through direct wire arrangements with offshore wind interconnectors.
China
State-owned enterprises and multinational manufacturing affiliates contract under dual carbon goals and provincial renewable consumption mandates. The Ministry of Ecology and Environment tightens emissions accounting standards for Scope 2 reporting. Yangtze River Delta data center corridors drive virtual PPA structuring for buyers lacking direct grid access.
United Kingdom
Corporate renewable procurement accelerates under Contract for Difference auction mechanisms and private wire arrangements. The national electricity regulator implements grid connection reforms to reduce queue delays for new-build assets. London and Southeast industrial zones concentrate demand from financial services and technology sector sustainability commitments.
India
Manufacturing and IT sector buyers scale open access procurement under state-level renewable purchase obligations. The Central Electricity Authority streamlines interstate transmission scheduling for corporate offtakers. Gujarat and Karnataka industrial corridors host concentrated solar and wind development with captive use and third-party sale structures.
Power Purchase Agreement Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated developers controlling interconnection timelines and EPC costs while financial intermediaries capture virtual PPA structuring. The market concentrates around three archetypes: utility-scale developers with captive construction platforms, technology-sector procurement aggregators with 24/7 carbon-free energy protocols, and European energy majors migrating offshore wind expertise into corporate channels. M&A activity targets development pipelines with advanced interconnection positions. Strategic partnerships between data center operators and renewable developers lock in decade-long offtake commitments.
Within the technology-procurement tier, Google exemplifies hourly dispatch-aligned contract structures that differentiate standard renewable energy credits from granular carbon accounting. NextEra Energy occupies a position as a vertically integrated developer controlling EPC and interconnection timelines across Florida and Texas markets. Engie anchors the European-major segment through offshore wind expertise now migrating into U.S. corporate procurement channels.
| Leading Market Players |
|---|
| NextEra Energy |
| Amazon |
| Vistra |
| Constellation |
| Microsoft |
| TotalEnergies |
| Engie |
| Meta |
| Others |
Supply Flow & Price Mechanics
Interconnection engineering talent scarcity in California and Texas widens pricing spreads between premium developer-led PPAs and commodity brokered structures, as labor-cost differentials in specialized transmission planning feed directly into contract rate negotiations for corporate offtakers seeking firm capacity guarantees.
Pricing Analysis
Volume concentrates in standardized virtual PPA structures with compressed margins, while premium pricing accrues to physical PPAs with 24/7 carbon-free energy matching and battery co-location services. Price differentiation hinges on domestic content bonus eligibility under IRA provisions and firm capacity guarantees versus energy-only contracts. Cost compression in virtual PPA tiers intensifies because floating-rate construction debt exposure squeezes developer equity returns. Mid-market corporate entrants without direct developer relationships exhibit highest price sensitivity; hyperscale technology buyers with investment-grade ratings and repeat transaction history demonstrate lowest.
Supply Chain Analysis
Reverse-logistics flows for transformer refurbishment and switchgear remanufacturing from decommissioned fossil plants are extending equipment lifecycles and moderating capital intensity for solar-plus-storage developers facing Asian manufacturing lead time constraints. Supply concentrates in China for lithium-ion battery cells, South Korea for power electronics, and domestic U.S. assembly for module integration. Raw material dependencies span polysilicon, lithium carbonate, and high-grade electrical steel. Single-source vulnerability in high-voltage transformer manufacturing creates supply chain risk. Distribution runs through vertically integrated developers with captive EPC platforms and specialized renewable energy aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around developers with advanced interconnection positions and captive construction capabilities, as FERC Order 2023 cost allocation disputes force weaker capitalized players into distressed offtake renegotiations or pipeline divestitures.
For Market Incumbents: To counter margin compression from floating-rate construction debt exposure, deepen interconnection queue positioning through early-stage site control in ERCOT and CAISO territories, and secure tax equity partnership capacity with repeat counterparty relationships to reduce back-leverage structuring complexity. For New Entrants and Emerging Players: Enter via green hydrogen offtake corridors in Texas and California where electrolyzer projects create dedicated renewable energy demand with limited incumbent competition, targeting mid-market manufacturing entities lacking sophisticated procurement functions as the most penetrable buyer segment. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated developers possessing captive EPC platforms given IRA domestic content bonus eligibility and interconnection timeline control; monitor FERC interconnection cost allocation rulings and hourly carbon accounting methodology adoptions as inflection indicators for premium PPA structure viability.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | NextEra Energy's solar-plus-storage development in Florida and Texas anchors market share through interconnection control. |
| Power Purchase Agreement | Google's 24/7 carbon-free energy matching protocol differentiates hourly dispatch-aligned structures from annual REC aggregation. |
| Technology Licensing | Engie's European offshore wind expertise migration into U.S. corporate channels captures premium pricing in Atlantic lease areas. |
| Vertical Integration into Storage | Battery co-location with photovoltaic arrays enables capacity value stacking and firming services commanding premium contract terms. |
| Green Certification Program | GHG Protocol Scope 2 emissions standards drive corporate buyers toward dispatch-aligned renewable energy credit structures. |
Methodological Framework
Multi-period observation of interconnection queue progression, tax credit monetization structures, and corporate offtake announcement velocity anchored the trend analysis, supplemented by interviews with IPP project developers, utility planning officers, EPC contractors, and grid operators. Secondary validation drew from EIA generation capacity databases, FERC interconnection filing records, IEA renewable energy market reports, and project finance transaction databases. Bottom-up capacity addition modeling and top-down policy impact assessment were triangulated against primary field intelligence.
Input-output matrices mapped contract structure types, generation technology categories, and buyer creditworthiness tiers across the projection horizon. CAGRs were derived from regression analysis of historical PPA execution volumes against macroeconomic and regulatory variables. Forecast inputs incorporated IRA bonus credit eligibility pathways, FERC Order 2023 implementation timelines, and hourly carbon accounting adoption curves.
Revisions become necessary when interconnection cost allocation rulings diverge from baseline assumptions, domestic content bonus eligibility thresholds shift, or corporate Scope 2 accounting standards accelerate beyond modeled adoption rates. Practitioners should monitor FERC cluster study phase completion rates and state renewable portfolio standard tightening proposals for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Argentina Power Market
Power
Direct Current Power System Market
Power
Compact Substation Market
Power
Europe Power Purchase Agreement Market
Power
Single-Phase Microinverter Market
Power
Vietnam Power Market
Power
Equatorial Guinea Power Market
Power
Flue Gas Desulfurization Unit Market
Power
Australia Power Market
Power
Global UPS Market
Power
Gabon Power Market
Power
Power Sled Market
Power
Global Power Line Communication (PLC) Systems Market
Power
HVDC Capacitor Market
Power
Malaysia Power EPC Market
Power
North America Micro CHP Market