
 Over-The-Air (OTA) Testing Market | 2026-2036
Over-The-Air (OTA) Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Over-The-Air (OTA) Testing Market Intelligence
CE marking under the EU Radio Equipment Directive is repositioning the cost-of-entry calculus for OTA testing vendors seeking European market access. Keysight Technologies leverages its software-defined instrumentation architecture to sustain R&D intensity across 5G and Wi-Fi 7 validation workflows. Rohde & Schwarz anchors its position through integrated test systems that dominate cellular conformance testing for automotive and telecom applications. Bureau Veritas competes via its global laboratory network, extending accredited OTA testing capacity across multiple regulatory jurisdictions.
Over-The-Air testing measures wireless device radiated performance in free-space conditions using anechoic chambers, probe arrays, and channel emulators to characterize total isotropic sensitivity and total radiated power across defined frequency ranges. The primary industrial purpose centers on certifying that antennas and radio modules meet regulatory emission limits and operator interoperability requirements before commercial deployment. Testing platforms command the deepest margin pools due to their capital-intensive chamber infrastructure and long replacement cycles, while software tools represent the fastest-growing segment as virtualized test sequences displace manual calibration routines. Automotive wireless systems and telecommunications applications absorb the majority of platform demand, driven by massive MIMO beamforming validation and vehicle-to-everything protocol certification.
The FCC in the United States, ETSI in Europe, and MIIT in China each enforce distinct OTA measurement methodologies that shape product standards and create region-specific test equipment demand. ISO and CTIA standards further harmonize certain procedures, though national deviations in mmWave band allocation continue to fragment certification requirements. Stakeholders must monitor how 6G research programs and satellite-terrestrial integration reshape chamber specifications and measurement bandwidth needs.
Market Dynamics
The OTA testing market is being fundamentally restructured by the collision of 5G NR beamforming complexity with automotive C-V2X certification mandates, forcing chamber infrastructure to accommodate wider frequency ranges and dynamic channel emulation.
Growth Catalysts
- 5G NR Massive MIMO:Base station and UE manufacturers require spherical near-field scanning to validate beam-steering accuracy across sub-6 GHz and mmWave bands, expanding chamber utilization rates.
- EU Radio Equipment Directive:CE marking enforcement tightens radiated spurious emission limits for connected devices, compelling European-bound products through accredited OTA workflows.
- Automotive V2X protocols:DSRC and C-V2X module certification for vehicle-to-everything communication is embedding OTA testing into tier-1 supplier validation gates.
Market Restraints
- Chamber infrastructure costs:Compact antenna test range facilities for mmWave validation require precision reflectors and absorber materials that strain mid-tier laboratory capital budgets.
- Probe array supply concentration:High-precision field probes for spherical near-field systems concentrate among specialized German and Japanese component suppliers, creating procurement bottlenecks.
- Regulatory fragmentation:Divergent FCC, ETSI, and MIIT measurement methodologies force redundant test campaigns for multi-region product launches, extending time-to-certification.
Strategic Opportunities
- India telecom expansion:Reliance Jio and Bharti Airtel 5G rollouts are creating demand for domestic OTA capacity as TRAI pushes local certification requirements.
- Satellite-terrestrial integration:NTN-enabled devices combining cellular and non-terrestrial links require hybrid channel emulation that extends chamber specifications into satellite bands.
- Virtualized test sequences:Software-defined measurement automation is compressing calibration cycles and enabling remote diagnostics that reduce on-site engineering presence.
Industry Challenges
- Electromagnetic simulation talent scarcity:Finite-difference time-domain modeling for chamber design and probe compensation requires specialized RF engineering expertise that outpaces university pipeline output.
- Multi-standard certification timelines:Simaneous CTIA, GCF, and PTCRB validation for a single 5G device creates parallel workflow complexity that strains laboratory scheduling systems.
- Legacy 4G test asset stranding:Existing LTE MIMO chambers face functional obsolescence as beamforming architectures shift from fixed to dynamic codebook designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Over-The-Air (OTA) Testing Market |
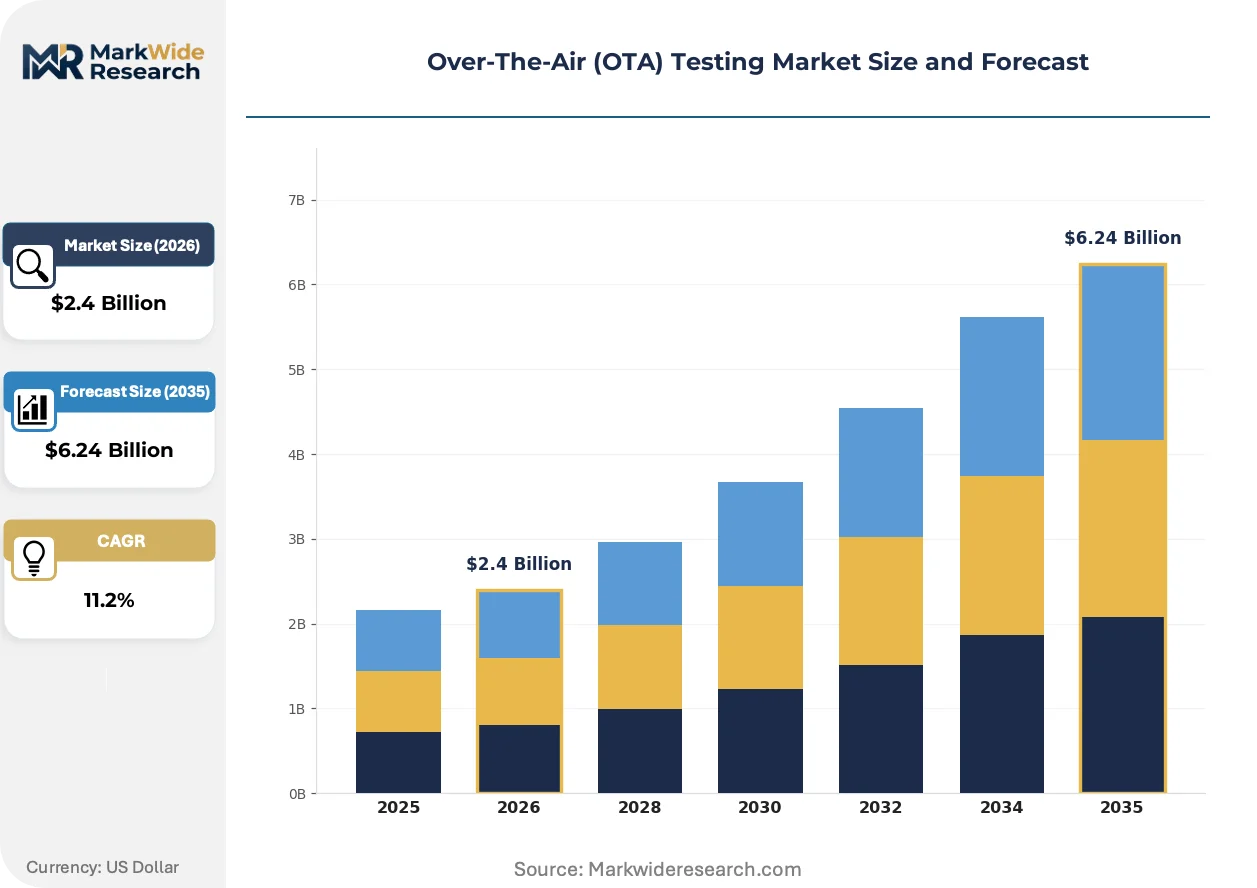
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.24 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
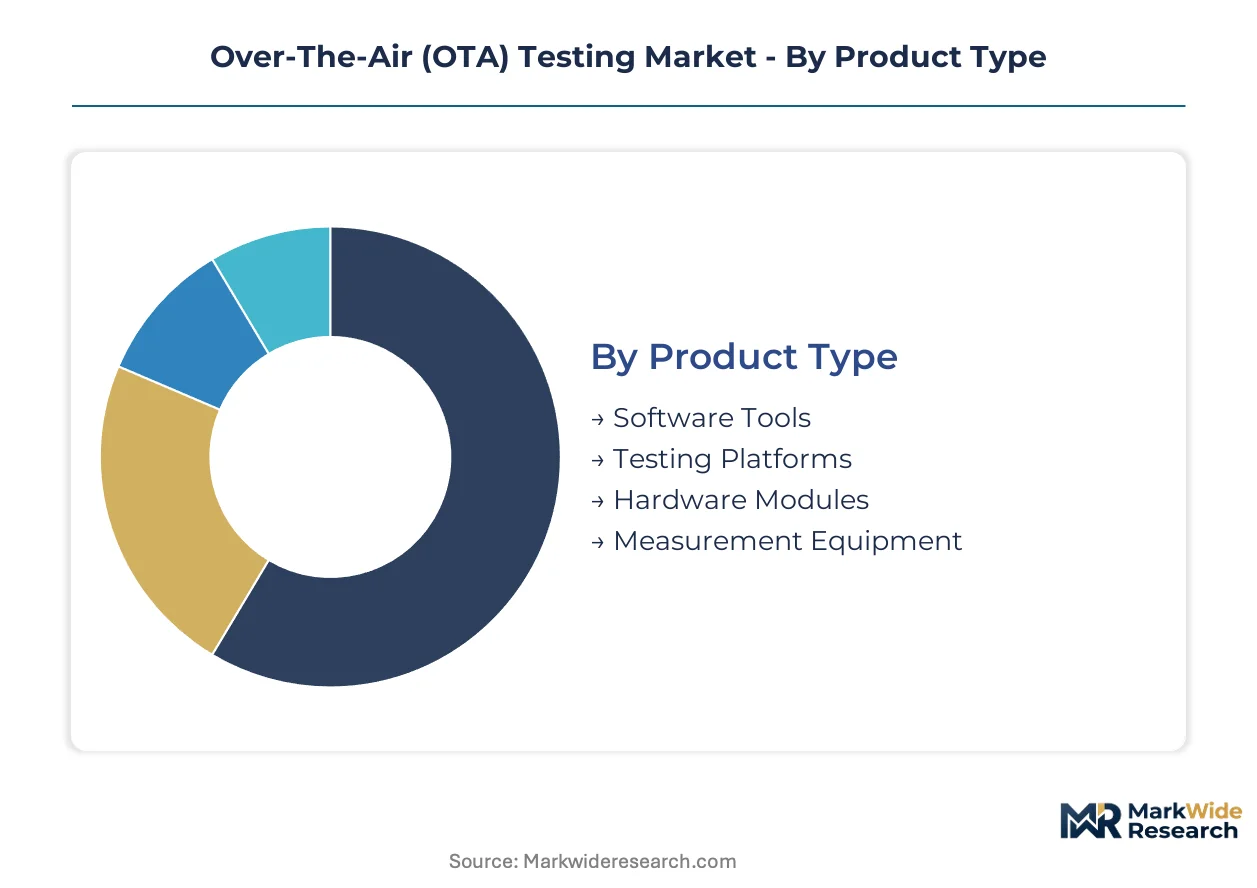
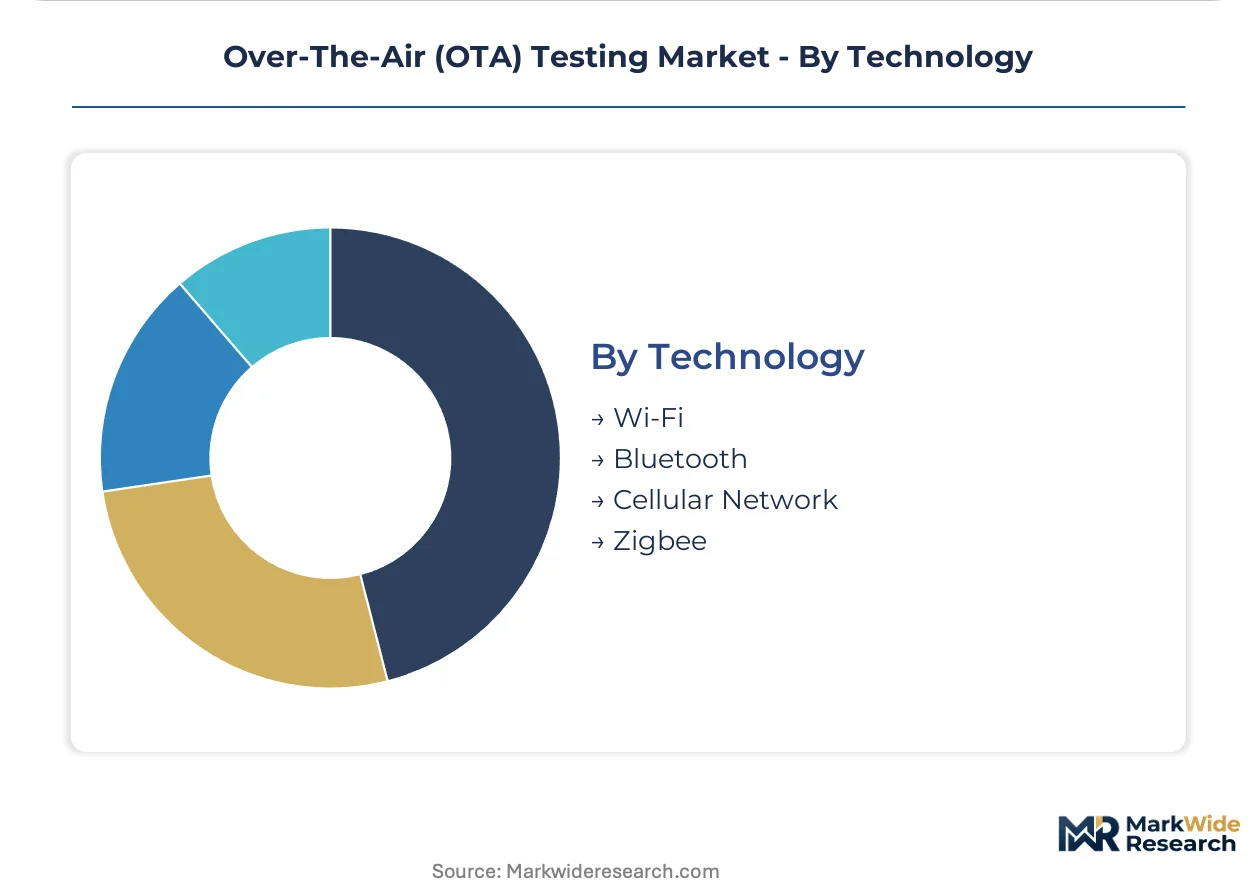
| Segmentation | Product Type: Software Tools, Testing Platforms, Hardware Modules, Measurement Equipment Application: Automotive Wireless Systems, IoT Devices, Telecommunications, Consumer Electronics End User: OEMs, Service Providers, Telecom Operators, Research Institutions Technology: Wi-Fi, Bluetooth, Cellular Network, Zigbee |
| Companies Covered | Rohde & Schwarz, Keysight Technologies, Anritsu, Intertek Group plc, SGS SA, Bureau Veritas, National Instruments, ETS-Lindgren, Microwave Vision Group (MVG), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Over-The-Air (OTA) Testing Market Strategic Shifts & Innovations
OTA testing workflows are converging toward software-centric architectures that decouple measurement algorithms from fixed hardware configurations, enabling faster adaptation to evolving radio standards.
Multi-probe spherical near-field systems are integrating real-time channel emulation capabilities that previously required separate baseband instrumentation. Automotive OEMs in Germany and the United States are adopting these unified platforms to compress validation cycles for connected vehicle modules. This hardware convergence is integrating RF and protocol testing into single-chamber workflows, reducing capital deployment footprints for tier-1 suppliers.
ETSI's evolving harmonized standards for 5G NR OTA measurement uncertainty are tightening documentation requirements for laboratory accreditation. Test houses must now demonstrate traceable calibration chains for probe positioning systems and anechoic chamber quiet zones. European notified bodies are responding by mandating third-party witness testing for mmWave device certification, elevating compliance costs for manufacturers targeting CE marking.
Device makers are unbundling OTA testing from traditional design-validation-manufacturing sequences, instead contracting accredited laboratories on per-campaign bases. This spot-purchasing pattern favors test houses with multi-site footprints that can schedule urgent certification slots across time zones. The shift is most pronounced among IoT module vendors in Shenzhen and Seoul, where product iteration cycles compress certification windows to weeks rather than months.
Over-The-Air (OTA) Testing Market Segmentation
OTA testing procurement patterns diverge sharply across buyer types, with capital-intensive chamber infrastructure attracting fundamentally different evaluation criteria than software-centric validation tools. Understanding these fault lines reveals where margin pools concentrate and which segments command pricing power.
Product Type:
Capital deployment thresholds separate buyers in this category, with chamber infrastructure demanding multi-year amortization against software tools that compress payback periods.
- Testing Platforms:Anechoic chambers with spherical near-field scanning capabilities anchor the capital base for 5G NR and mmWave validation. Automotive OEMs in Germany absorb the majority of chamber utilization for C-V2X certification workflows.
- Software Tools:Virtualized test sequences and automated calibration algorithms displace manual measurement routines. Shenzhen-based IoT module vendors drive spot-purchasing patterns for compressed certification windows.
- Hardware Modules:Probe arrays and channel emulators integrate into unified RF-protocol testing workflows.
- Measurement Equipment:Field probes and positioning systems require traceable calibration chains for laboratory accreditation.
Volume sits with Testing Platforms; growth tilts toward Software Tools.
Application:
Regulatory complexity and beamforming validation intensity determine where testing hours accumulate across end-use sectors.
- Automotive Wireless Systems:C-V2X and DSRC module certification embeds OTA testing into tier-1 supplier validation gates. KBA in Germany and NHTSA in the United States enforce distinct protocol requirements that fragment test campaign specifications.
- Telecommunications:Massive MIMO base stations and UE devices demand spherical near-field scanning across sub-6 GHz and mmWave bands. FCC, ETSI, and MIIT methodologies force redundant certification cycles for multi-region launches.
- IoT Devices:Low-power wide-area modules in Shenzhen and Seoul compress iteration cycles to weeks.
- Consumer Electronics:Wi-Fi 7 and Bluetooth validation concentrates among handset and wearable manufacturers.
Revenue concentrates in Automotive Wireless Systems; expansion accelerates most quickly in Telecommunications.
End User:
Ownership of certification risk and in-house R&D intensity shape whether buyers build captive capacity or contract accredited laboratories.
- OEMs:Automotive and device manufacturers maintain internal chambers for design validation while outsourcing final certification to notified bodies. Tier-1 suppliers in Germany favor integrated test systems that dominate cellular conformance workflows.
- Telecom Operators:Network equipment procurement mandates drive OTA validation for base station antenna performance. Reliance Jio and Bharti Airtel 5G rollouts in India create demand for domestic accredited capacity.
- Service Providers:Test houses with multi-site footprints capture spot-purchasing from IoT module vendors.
- Research Institutions:6G research programs and satellite-terrestrial integration reshape chamber specifications.
Spending dominance rests with OEMs; contract laboratory growth favors Telecom Operators.
Technology:
Frequency range and beamforming architecture determine chamber specification requirements and measurement bandwidth needs.
- Cellular Network:5G NR sub-6 GHz and mmWave bands drive spherical near-field system demand with dynamic channel emulation. ETSI harmonized standards tighten documentation requirements for laboratory accreditation.
- Wi-Fi:Wi-Fi 7 validation workflows require software-defined instrumentation architectures that sustain R&D intensity across evolving standards.
- Bluetooth:Low-energy protocol testing concentrates in consumer electronics and wearable segments.
- Zigbee:Smart home and industrial IoT applications absorb probe-based measurement routines.
Certification hours pool in Cellular Network; Wi-Fi climbs the fastest on enterprise and residential bandwidth demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's special economic zone status has concentrated OTA testing demand from IoT module vendors, while Germany's automotive corridor drives chamber infrastructure investment. Regulatory divergence across FCC, ETSI, and MIIT methodologies fragments certification workflows. Demand clusters in three distinct manufacturing geographies.
United States
FCC Part 15 and Part 27 mandates drive chamber utilization for 5G NR and mmWave device certification. NHTSA protocols for C-V2X modules embed OTA validation into automotive supplier gates. The Detroit-Warren corridor anchors automotive wireless testing, while Silicon Valley clusters concentrate handset and IoT module validation.
Germany
KBA enforcement of C-V2X and DSRC certification requirements compresses tier-1 supplier validation cycles. CE marking under the EU Radio Equipment Directive tightens radiated spurious emission limits for European-bound products. Stuttgart and Munich host the densest concentration of automotive OTA capacity, serving BMW, Mercedes-Benz, and Volkswagen supplier networks.
China
MIIT certification mandates for 5G NR and satellite-terrestrial integration expand chamber specifications into non-terrestrial bands. GB standards for wireless device radiated performance create domestic test equipment demand. Shenzhen and Beijing clusters absorb the majority of IoT module and consumer electronics validation, with Huawei and ZTE supplier ecosystems driving utilization.
India
TRAI local certification requirements for Reliance Jio and Bharti Airtel 5G rollouts create demand for domestic accredited OTA capacity. BIS standards for telecom equipment safety and interoperability tighten import compliance. Mumbai-Pune and Bengaluru corridors concentrate emerging test house infrastructure, though capacity lags Chinese and German benchmarks.
South Korea
MFDS and RRA protocols for 5G device certification sustain spherical near-field system demand across sub-6 GHz and mmWave bands. Samsung and LG supplier ecosystems compress iteration cycles to weeks. Seoul Capital Area clusters anchor the majority of domestic OTA capacity, with Suwon and Pangyo hosting concentrated validation infrastructure.
Over-The-Air (OTA) Testing Market Key Industry Players
German producers anchor one tier; US specialists hold another through software-defined architectures. The market structures around three tiers: integrated test system vendors, global laboratory networks, and component specialists. Archetypes include chamber infrastructure providers, accreditation-focused test houses, and probe array manufacturers. Competitive moves center on multi-site laboratory expansion and software automation licensing.
Within the integrated test system tier, Rohde & Schwarz and Keysight Technologies occupy positions exemplifying hardware-software convergence. Bureau Veritas sits within the global laboratory network archetype, extending accredited capacity across regulatory jurisdictions. These three entities represent distinct strategic postures: German engineering-intensive instrumentation, US software-centric validation workflows, and French-headquartered multi-site compliance services.
| Leading Market Players |
|---|
| Rohde & Schwarz |
| Keysight Technologies |
| Anritsu |
| Intertek Group plc |
| SGS SA |
| Bureau Veritas |
| National Instruments |
| ETS-Lindgren |
| Microwave Vision Group (MVG) |
| Others |
Cost & Logistics Intelligence
Family-owned German instrumentation specialists anchor chamber manufacturing, exercising pricing discipline through captive production of precision reflectors and absorber materials while resisting margin compression from Asian component suppliers.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent certification campaigns from scheduled validation slots, with automotive OEMs in Stuttgart paying premiums for compressed C-V2X test windows while Shenzhen IoT vendors exploit spot-purchasing for economy-tier software tools. Project-based contracting dominates chamber utilization, though subscription SaaS models are displacing perpetual licenses for calibration automation. Price differentiation hinges on ISO 17025 accreditation tier and mmWave band coverage, with CE-marking readiness commanding brand premiums. Pricing pressure stems from probe array supply concentration among Japanese and German component houses. Tier-1 automotive suppliers exhibit lowest price sensitivity; IoT module vendors in Seoul and Shenzhen drive hardest bargain hunting.
Supply Chain Analysis
Workforce availability for finite-difference time-domain modeling concentrates in Munich, Stuttgart, and Boston metropolitan clusters, constraining chamber design capacity despite equipment demand from Reliance Jio and Bharti Airtel 5G rollouts. Manufacturing draws from Germany, Japan, and the United States for precision positioning systems, anechoic absorbers, and RF instrumentation. Raw material dependencies include carbon-loaded polyurethane foam, aluminum reflector substrates, and GaAs field probes. Single-source vulnerability runs through specialized German probe array suppliers. Distribution runs through direct sales for integrated test systems and accredited laboratory networks for outsourced validation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration races are accelerating as chamber vendors pursue backward control over probe array manufacturing to escape supply bottlenecks and defend margin structures against software-defined competitors.
For Market Incumbents: To counter software-centric challengers like Keysight Technologies, Rohde & Schwarz and ETS-Lindgren should deepen captive production of spherical near-field probe arrays in Germany and expand multi-site laboratory accreditation across TRAI-mandated Indian corridors. Certification investment in 6G and NTN-enabled hybrid chambers represents the critical defensive lever. For New Entrants and Emerging Players: AI-native test sequence automation offers entry wedge against legacy calibration workflows, with highest penetrability in Shenzhen and Seoul IoT module vendor segments where iteration cycles compress certification windows to weeks. White-space targets include satellite-terrestrial integration validation for NTN devices and remote diagnostics platforms reducing on-site engineering presence. Go-to-market should anchor on per-campaign spot-purchasing contracts with accredited test house partnerships. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap European test houses with ISO 17025 accreditation and underutilized mmWave capacity in Germany and South Korea, where automotive C-V2X validation demand outpaces chamber utilization. Long-term viability hinges on software-defined architecture migration and 6G research program capture. Signal to watch: ETSI harmonized standard releases tightening measurement uncertainty documentation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Probe Arrays | Captive supply of high-precision field probes escapes Japanese and German supplier bottlenecks straining mid-tier laboratories. |
| Multi-Site Laboratory Expansion | Accredited capacity across Mumbai-Pune and Bengaluru corridors captures TRAI-mandated domestic certification for Reliance Jio 5G. |
| Software-Defined Test Sequence Licensing | Virtualized calibration automation displaces manual routines among Shenzhen IoT vendors compressing iteration cycles. |
| NTN-Enabled Chamber Specification Extension | Hybrid channel emulation for satellite-terrestrial integration addresses 6G research programs reshaping measurement bandwidth needs. |
| CE Marking Fast-Track Partnerships | European notified body collaboration accelerates radiated spurious emission compliance for automotive OEM supplier networks. |
Research Approach
Independent corroboration across chamber infrastructure procurement managers, RF test engineers at automotive tier-1 suppliers, regulatory affairs leads at notified bodies, and calibration laboratory directors underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation from FCC Part 15 and Part 27 dockets, ETSI harmonized standard drafts, MIIT GB standard publications, and CTIA certification program documentation. Bottom-up equipment shipment aggregation and top-down end-user spending analysis triangulate market sizing.
Rate-of-change decomposition across the projection horizon segments volume and value by testing platform, software tool, hardware module, and measurement equipment categories, further split by automotive wireless systems, telecommunications, IoT devices, and consumer electronics applications. Modeled dimensions include frequency band coverage, beamforming architecture complexity, and regional regulatory cluster. CAGRs derive from equipment replacement cycle analysis and certification throughput elasticity to 5G NR and C-V2X mandate timing. Forecast inputs incorporate spherical near-field system utilization rates and probe array lead time fluctuations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MIIT satellite-terrestrial band allocation shifts or ETSI measurement uncertainty standard acceleration. Forecasts reflect assumptions on chamber infrastructure depreciation schedules and software automation adoption curves. Material deviation in KBA or NHTSA C-V2X protocol timing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Capacitance Meter Market
Test and Measurement
Production Testing Market
Test and Measurement
In-Circuit Test Market
Test and Measurement
Semiconductor Assembly and Testing Services Market
Test and Measurement
Vibration Analyzer Market
Test and Measurement
Compression Testers Market
Test and Measurement
Global Conductivity Meters Market
Test and Measurement
Smart Contact Lens Optical and Telemetry Test Equipment Market
Test and Measurement
Clamp Meters Market
Test and Measurement
Tribometer Market
Test and Measurement
Simulation and Test Data Management Market
Test and Measurement
Global Non-Destructive Testing and Inspection Market
Test and Measurement
Noise Vibration Harshness (NVH) Testing Market
Test and Measurement
Cell Balancing Algorithm Hardware-in-the-Loop Test Platforms Market
Test and Measurement
AI-Assisted NDT Data Analytics and Defect Characterization Platforms Market
Test and Measurement
Moisture Analyzer Market