
 Tribometer Market | 2026-2036
Tribometer Market Size, Share, and Industry Trends Forecast 2026-2036
Tribometer Market Outlook
Direct sales channels between tribometer manufacturers and automotive OEMs is rewriting how equipment procurement contracts are structured across Europe and Asia. Bruker Corporation leverages its spectroscopy heritage to anchor premium positioning in surface analysis configurations. Anton Paar GmbH sustains dominance in rheology-adjacent tribology systems through tight integration with Austrian research networks. Rtec Instruments competes aggressively on test-speed versatility across North American aerospace supply chains.
A tribometer is an instrument that quantifies friction, wear, and lubrication behavior between interacting surfaces under controlled load, speed, and temperature conditions, typically resolving forces in the millinewton range and operating across boundary to hydrodynamic lubrication regimes. Pin-on-disk configurations retain the largest installed base due to their ASTM G99 standardization and repeatability in coating qualification workflows. Digital tribometers represent the fastest-expanding technology segment as embedded sensors and real-time data acquisition displace manual readout systems in high-throughput materials screening. Research institutions command disproportionate margin pools because their procurement emphasizes multi-modal capability over unit cost.
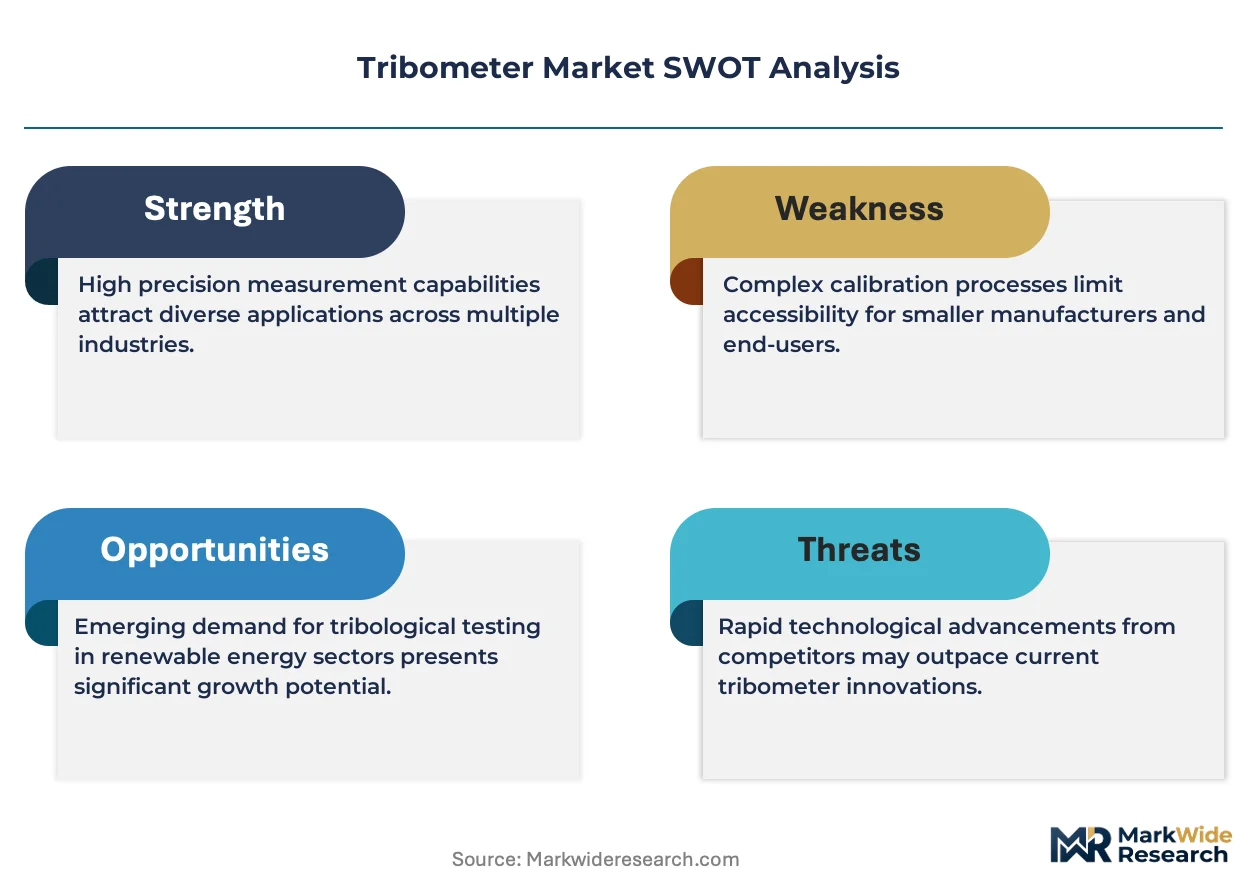
ISO 20808 and ASTM G133 govern ball-on-disk and reciprocating sliding test protocols that shape product development roadmaps for every listed manufacturer. Japan's METI enforces energy efficiency benchmarks that push automotive tribometer users toward lower-friction coating validation, while REACH compliance in Europe restricts certain lubricant chemistries used in reference testing. Stakeholders must track how evolving AI Act documentation requirements in Europe could reshape data governance for connected digital tribometer platforms.
Market Dynamics
Automotive OEMs in Germany and Japan are rewriting procurement specifications to prioritize multi-modal tribometers capable of simultaneous friction, wear, and lubrication analysis under ISO 20808 and ASTM G133 protocols, compressing vendor qualification cycles and favoring integrated platform suppliers over specialized component vendors.
Growth Catalysts
- EU Ecodesign durability mandates:Updated surface engineering requirements for powertrain components are forcing coating suppliers to validate friction coefficients across boundary and mixed lubrication regimes, expanding tribometer deployment in Stuttgart and Munich automotive clusters.
- Japan METI energy efficiency benchmarks:Lower-friction coating validation requirements are accelerating tribometer procurement by Japanese transmission manufacturers seeking to reduce mechanical losses in hybrid drivetrains.
- Pin-on-disk standardization:ASTM G99 repeatability in coating qualification workflows continues to anchor equipment selection decisions across North American aerospace supply chains.
Market Restraints
- High-purity sensor input concentration:Millinewton-resolution force transducers rely on specialized Japanese and German component suppliers, creating vulnerability to lead-time volatility and currency exposure.
- Technical limitation in high-temperature oxidation:Standard tribometer configurations struggle to maintain measurement stability above 600°C, restricting validation of advanced ceramic coatings for turbine applications.
- REACH lubricant chemistry restrictions:European reference testing protocols face reformulation costs as certain sulfur-phosphorus additive packages become non-compliant, complicating cross-laboratory data comparability.
Strategic Opportunities
- Swiss precision engineering underpenetration:Geneva and Basel micro-manufacturing clusters show latent demand for tabletop tribometers configured for MEMS-scale friction characterization.
- Digital tribometer platform convergence:Embedded sensor arrays combined with real-time data acquisition architectures are creating white space for equipment-as-a-service models in high-throughput materials screening facilities.
- US aerospace reshoring tailwind:Domestic supply chain reconstitution under IRA-linked manufacturing incentives is expanding qualification laboratory buildouts in Ohio and Texas.
Industry Challenges
- Tribology-software integration complexity:Legacy LIMS architectures at established research institutions resist seamless data pipeline integration with modern digital tribometer output formats, extending commissioning timelines.
- Multi-modal calibration skill scarcity:Technicians capable of simultaneous force, temperature, and acoustic emission channel validation remain concentrated in German and Austrian technical universities, constraining field service expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tribometer Market |
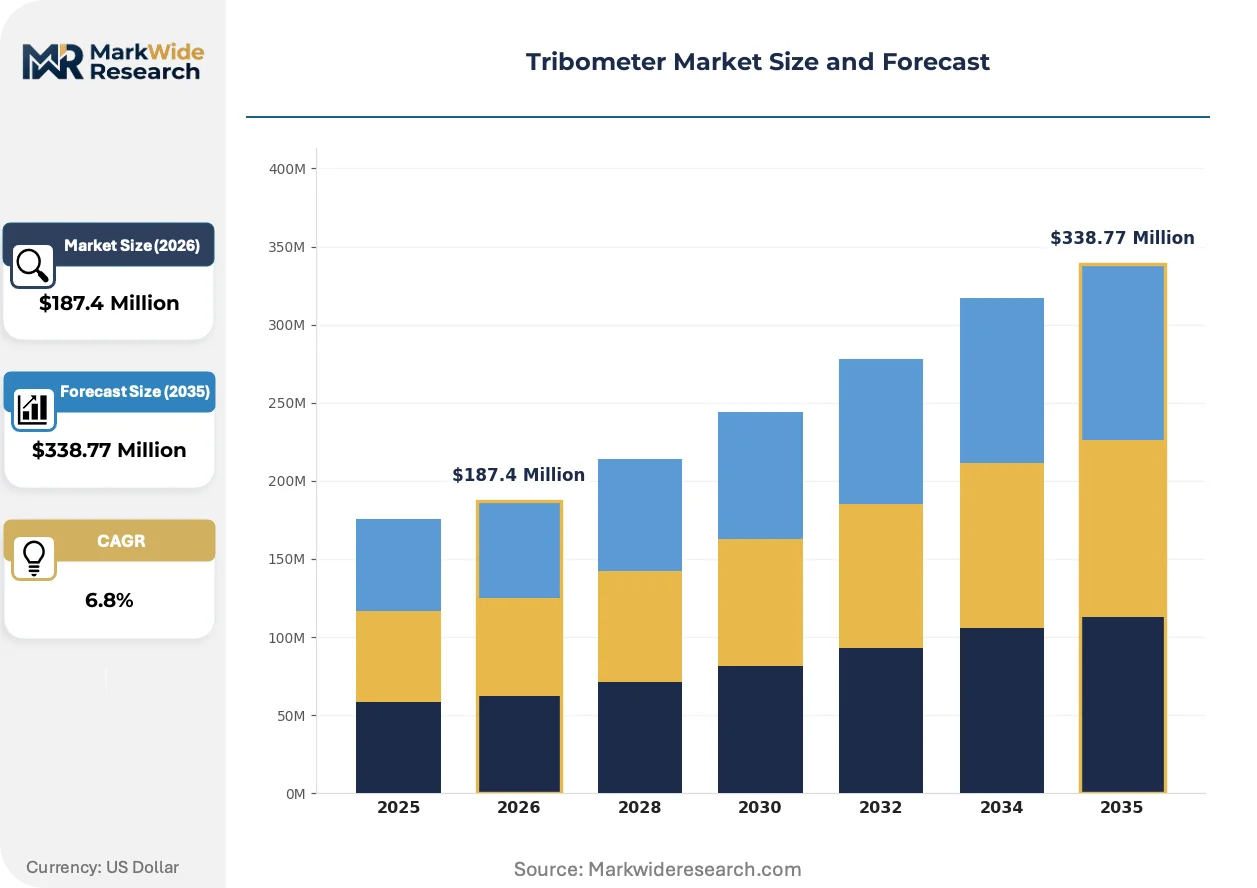
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball-on-Disk, Pin-on-Disk, Reciprocating Sliding, Micro-Tribometer Application: Friction Testing, Wear Testing, Coefficient Measurement, Surface Analysis End User: Aerospace, Automotive, Consumer Electronics, Research Institutions Technology: Digital Tribometers, Analytical Instruments, Lab Equipment, Portable Devices |
| Companies Covered | Nanovea, Bruker Corporation, Anton Paar GmbH, Rtec Instruments, Advanced Mechanical Technology, Ducom Instruments Inc., EXCEL TRIBOMETERS, Falex Tribology, CSM Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tribometer Market Strategic Shifts
Real-time tribological data architectures are compressing materials development cycles from months to weeks. Three interconnected developments are restructuring how friction and wear characterization equipment is specified, sold, and operated.
Digital tribometer platforms are migrating from manual readout systems to embedded sensor networks with automated coefficient-of-friction tracking. Automotive tier-one suppliers in Germany are adopting these configurations for overnight batch testing of transmission coating candidates. The technology is migrating from laboratory benchtop units toward production-adjacent quality control stations, collapsing the physical distance between R&D validation and manufacturing release.
EU AI Act documentation requirements are reshaping data governance for connected tribometer platforms. Equipment vendors must now architect audit trails for algorithmic friction prediction models used in high-stakes coating qualification decisions. Research institutions with existing ISO 17025 frameworks are adapting fastest, while smaller commercial laboratories face compliance timeline compression.
Direct manufacturer-OEM contracting is displacing traditional distributor-mediated equipment sales in European and Asian automotive markets. Bruker Corporation and Anton Paar GmbH have established dedicated account teams for Volkswagen Group and Toyota Motor procurement divisions. This channel restructuring is most visible in Germany, where multi-year service-integrated contracts now dominate premium tribometer transactions.
Tribometer Market Segmentation
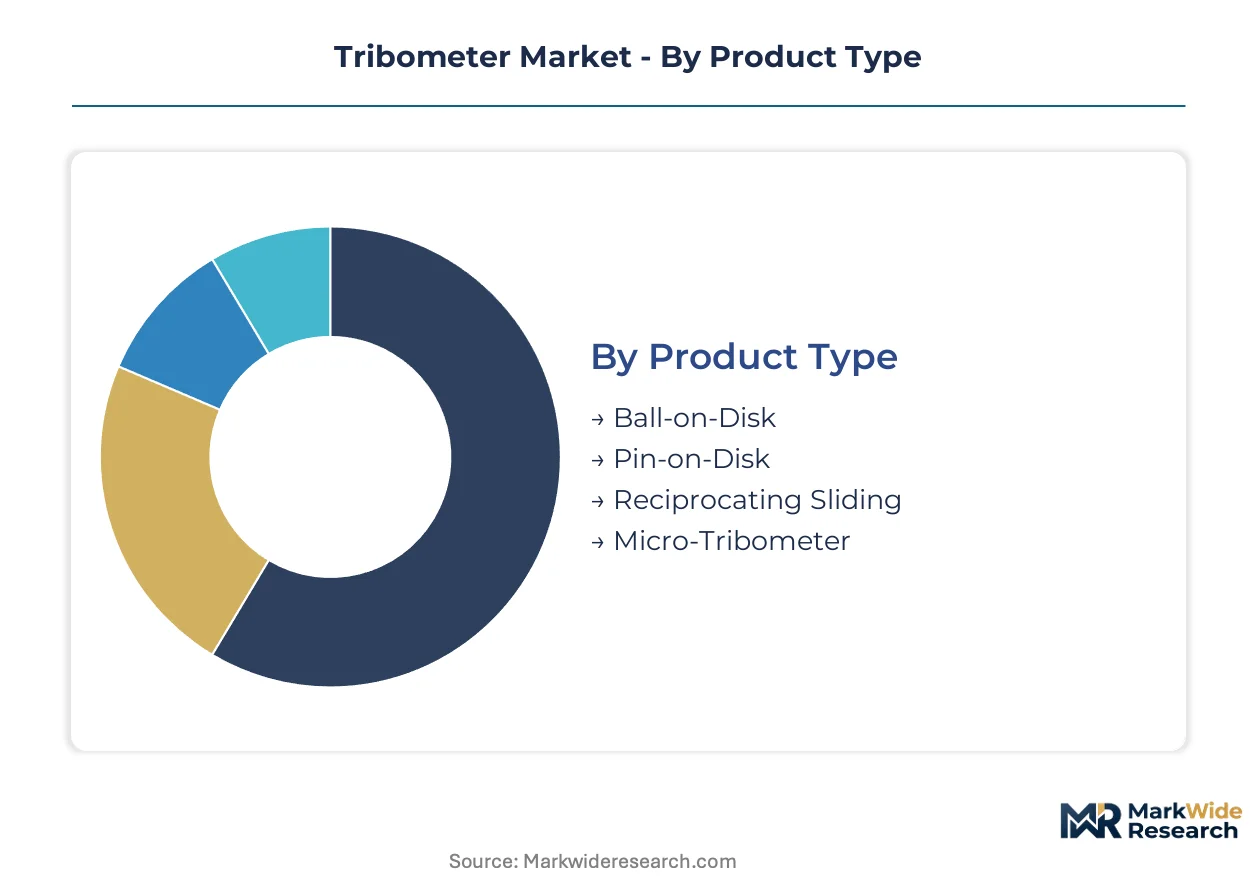
Tribometer procurement patterns diverge sharply by end-use sophistication, with aerospace and automotive OEMs demanding multi-modal platforms while research institutions prioritize configurability. Understanding these segment boundaries clarifies why vendor positioning strategies vary dramatically across product categories.
Product Type:
Cost tier stratification separates standardized entry-level configurations from premium multi-axis systems capable of simultaneous force and acoustic emission capture.
- Pin-on-Disk:ASTM G99 standardization anchors this configuration in coating qualification workflows across North American aerospace supply chains. Stuttgart and Munich automotive clusters specify these units for overnight batch testing of transmission coating candidates under ISO 20808 protocols.
- Ball-on-Disk:Superior contact geometry control suits this variant for boundary lubrication regime studies in Japanese transmission manufacturing. METI energy efficiency benchmarks push hybrid drivetrain suppliers toward lower-friction validation using these platforms.
- Reciprocating Sliding:ASTM G133 compliance drives adoption in European reference laboratories facing REACH lubricant chemistry reformulation requirements.
- Micro-Tribometer:MEMS-scale friction characterization demand concentrates in Geneva and Basel precision engineering clusters seeking tabletop configurations.
Pin-on-Disk holds installed capacity. Micro-Tribometer is rotating up the share rankings.
Application:
Application focus determines whether procurement prioritizes throughput velocity or measurement resolution depth.
- Wear Testing:Volume displacement quantification under controlled load cycles dominates turbine blade coating validation where standard configurations struggle above 600°C oxidation thresholds. German research networks specify these systems for ceramic matrix composite development.
- Friction Testing:Real-time coefficient tracking via embedded sensor networks is displacing manual readout systems in high-throughput materials screening facilities. Automotive tier-one suppliers deploy these configurations for production-adjacent quality control stations.
- Coefficient Measurement:Millinewton-resolution force transducer dependency creates supply vulnerability to Japanese and German component lead-time volatility.
- Surface Analysis:Multi-modal capability requirements command disproportionate margin pools at research institutions emphasizing spectroscopy integration over unit cost.
Wear Testing anchors current procurement volume. Friction Testing is climbing the fastest as digital architectures compress development cycles.
End User:
Customer type dictates whether procurement contracts emphasize service-integrated multi-year frameworks or capital expenditure minimization.
- Automotive:Direct manufacturer-OEM contracting is restructuring European and Asian procurement, with dedicated account teams from major vendors now serving Volkswagen Group and Toyota Motor divisions. EU Ecodesign durability mandates for powertrain components expand deployment in German automotive clusters.
- Research Institutions:Legacy LIMS architecture resistance to modern digital tribometer output formats extends commissioning timelines at established universities. ISO 17025 frameworks accelerate EU AI Act compliance for algorithmic friction prediction audit trails.
- Aerospace:US supply chain reshoring under IRA-linked manufacturing incentives expands qualification laboratory buildouts in Ohio and Texas. ASTM G99 repeatability requirements anchor equipment selection decisions.
- Consumer Electronics:Miniaturization trends drive demand for compact configurations in Asian manufacturing hubs validating surface treatments for portable device hinges and connectors.
Automotive commands current contract value. Research Institutions are gaining share fastest as multi-modal capability premiums expand.
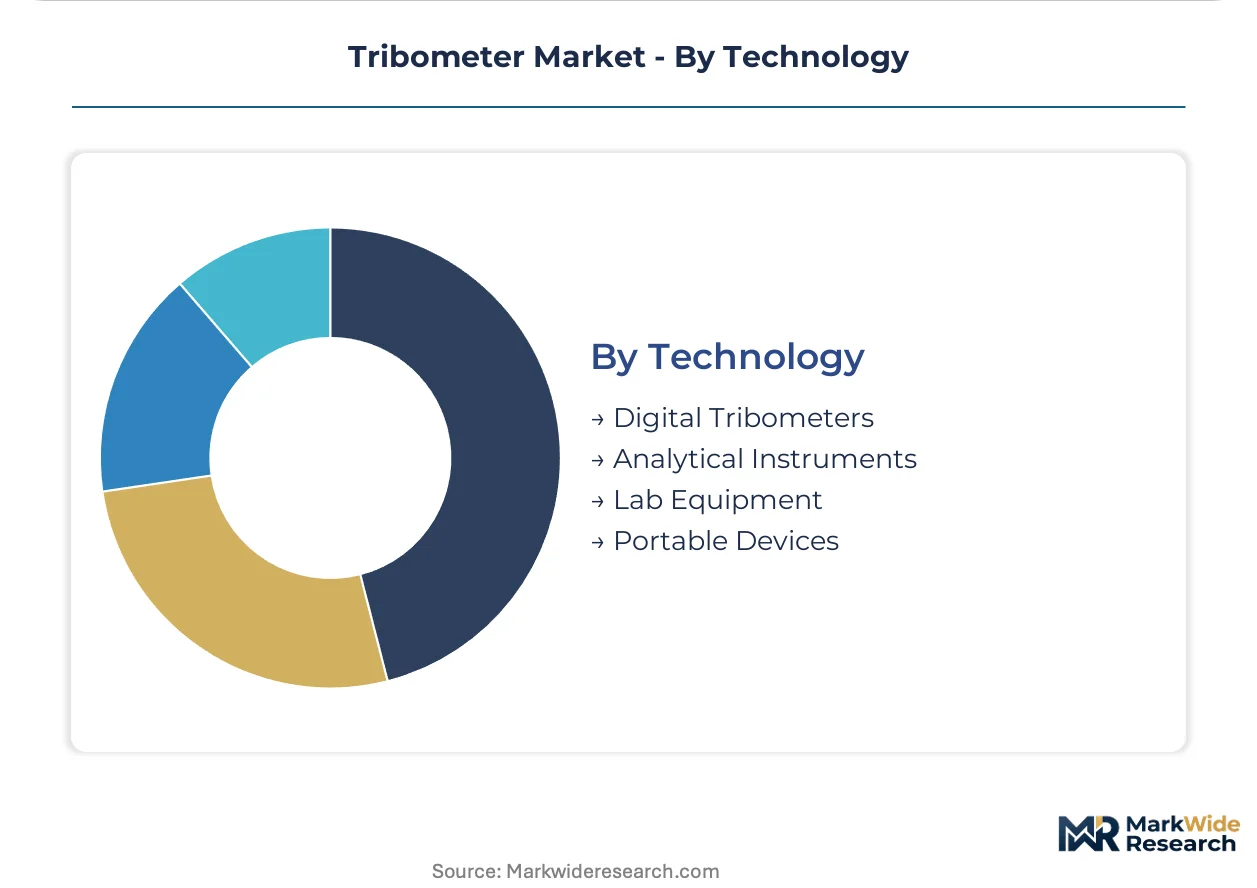
Technology:
Technology maturity separates legacy analog architectures from connected platforms facing emerging data governance requirements.
- Digital Tribometers:Embedded sensor arrays with real-time data acquisition architectures create white space for equipment-as-a-service models. EU AI Act documentation requirements reshape audit trail architecture for algorithmic coating qualification decisions.
- Analytical Instruments:Spectroscopy heritage integration positions premium vendors in surface analysis configurations requiring simultaneous tribological and chemical characterization.
- Lab Equipment:Conventional benchtop units serve cost-sensitive commercial laboratories facing compliance timeline compression for connected platform migration.
- Portable Devices:Field-deployable friction characterization addresses maintenance monitoring applications in distributed manufacturing environments.
Analytical Instruments maintains legacy installed base. Digital Tribometers represents the steepest expansion trajectory as embedded architectures displace manual systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central Europe's dominance in precision tribology equipment distribution, connecting Stuttgart and Munich automotive clusters to Basel research networks.
Germany
Automotive OEMs in Stuttgart and Munich are expanding multi-modal tribometer procurement to meet EU Ecodesign durability mandates for powertrain components. KBA vehicle certification requirements now embed surface engineering validation into type approval workflows. The Baden-Württemberg precision engineering corridor anchors coating qualification laboratory buildouts for transmission manufacturers.
Japan
Hybrid drivetrain suppliers are accelerating lower-friction coating validation to satisfy METI energy efficiency benchmarks for mechanical loss reduction. JIS standards govern tribological test protocols across Nagoya and Tokyo manufacturing basins. The Chubu region concentrates transmission R&D facilities deploying ball-on-disk configurations for boundary lubrication studies.
United States
Domestic aerospace supply chain reshoring under IRA-linked manufacturing incentives is expanding qualification laboratory capacity in Ohio and Texas. FAA material certification requirements anchor ASTM G99 repeatability specifications in coating validation workflows. The Dallas-Fort Worth metroplex hosts emerging tribology service centers serving reshoring tier-one suppliers.
Switzerland
Geneva and Basel micro-manufacturing clusters are driving latent demand for tabletop tribometers configured for MEMS-scale friction characterization. Swissmedic medical device surface requirements extend tribological validation to implant coating workflows. The Swiss Federal Institutes of Technology network supplies calibration expertise scarce elsewhere in Europe.
China
Domestic electric vehicle powertrain manufacturers are localizing tribometer procurement to reduce dependency on European metrology imports. MIIT new energy vehicle standards incorporate surface durability testing for battery thermal management coatings. The Yangtze River Delta concentrates domestic equipment assembly operations serving BYD and CATL supply chains.
Tribometer Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in force transducer and sensor supply. The vendor base separates into three strata: spectroscopy-heritage conglomerates with surface analysis integration, rheology-adjacent specialists leveraging academic network proximity, and test-speed versatile independents serving aerospace qualification chains. Consolidation pressure concentrates at the mid-tier where multi-modal capability requirements favor integrated platform suppliers over point-solution vendors. Dominant competitive moves include direct manufacturer-OEM contracting displacing distributor channels and service-integrated multi-year framework agreements.
Within the spectroscopy-integrated tier, Bruker Corporation and Anton Paar GmbH occupy positions anchored by heritage instrumentation portfolios. Rtec Instruments exemplifies the test-speed versatile archetype competing across North American aerospace supply chains. These three entities represent distinct strategic postures: conglomerate-backed platform breadth, academically networked rheology adjacency, and specialized speed-configuration agility.
| Leading Market Players |
|---|
| Nanovea |
| Bruker Corporation |
| Anton Paar GmbH |
| Rtec Instruments |
| Advanced Mechanical Technology |
| Ducom Instruments Inc. |
| EXCEL TRIBOMETERS |
| Falex Tribology |
| CSM Instruments |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Main-Danube waterway corridor channels freight cost volatility directly into tribometer landed pricing, amplifying margin compression for European distributors while rewarding manufacturers with captive calibration facilities in Stuttgart and Munich. Supply concentration in millinewton-resolution force transducers creates tiered pricing power that separates spectroscopy-integrated platform vendors from component-assemblers serving cost-sensitive commercial laboratories.
Pricing Analysis
Three-tier pricing structure across premium multi-modal systems, standard pin-on-disk configurations, and economy tabletop units anchors the market. Price differentiation rests on ISO 17025 certification tier and embedded sensor array sophistication, with research institutions absorbing premium positioning while automotive tier-two suppliers drive standard-tier volume. Cost compression in the economy segment is intensifying as Chinese domestic equipment gains traction in battery thermal management coating validation. Research institutions demonstrate lowest price sensitivity due to grant-funded procurement cycles; commercial testing laboratories face acute budget constraints.
Supply Chain Analysis
Tariff exposure between Germany and Japan dominates supply chain risk planning for force transducer procurement. Component sourcing concentrates in Japan, Germany, and the United States, with piezoelectric sensor substrates and high-purity ceramic bearings drawing from specialized regional suppliers. Single-source vulnerability in millinewton-resolution transducer manufacturing creates lead-time volatility that ripples through coating qualification schedules. Distribution runs through direct manufacturer-OEM contracting channels in European automotive clusters, displacing traditional distributor mediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-integrated multi-year framework agreements now expand faster than hardware shipments, with calibration subscription revenue and field service attach rates outpacing unit sales growth in German automotive procurement channels.
For Market Incumbents: Entrench platform dominance by deepening backward integration into force transducer manufacturing and securing exclusive service contracts with Volkswagen Group and Toyota Motor procurement divisions. Digital tribometer platform convergence threatens specialized component vendors; anchor defensive positioning through ISO 17025-accredited calibration networks that resist smaller competitor replication. For New Entrants and Emerging Players: Build out tabletop micro-tribometer offerings targeting Geneva and Basel MEMS-scale friction characterization demand, where Swiss precision engineering clusters show latent equipment need. Swissmedic medical device surface requirements extend addressable market into implant coating workflows. Pursue equipment-as-a-service models for high-throughput materials screening facilities seeking to convert capital expenditure into operating budgets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors spectroscopy-heritage conglomerates with surface analysis integration capabilities over point-solution vendors facing consolidation pressure. Long-term viability across the projection horizon hinges on AI Act compliance architecture for algorithmic friction prediction audit trails. Monitor EU AI Act enforcement timelines as inflection indicator for digital tribometer platform valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Manufacturer-OEM Contracting | Volkswagen Group procurement restructuring eliminates distributor margins and locks in multi-year service attach revenue. |
| Backward Integration into Force Transducers | Captive supply of millinewton-resolution components insulates Bruker and Anton Paar from Japanese supplier lead-time volatility. |
| Equipment-as-a-Service Launch | Real-time data acquisition architectures enable recurring revenue conversion in high-throughput materials screening facilities. |
| AI Act Compliance Architecture Investment | Audit trail capabilities for algorithmic coating qualification decisions differentiate premium vendors in European research procurement. |
| Swiss Precision Engineering Channel Expansion | Geneva and Basel micro-manufacturing clusters offer underpenetrated entry point for MEMS-scale friction characterization systems. |
Study Parameters
A spread of perspectives from tribometer platform engineers, automotive OEM procurement managers, research institution laboratory directors, and aftermarket calibration service heads converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against ASTM G133 protocol documentation, ISO 20808 standard filings, KBA vehicle certification records, and METI energy efficiency benchmark disclosures. Bottom-up unit deployment tracking across Stuttgart, Munich, Nagoya, and Ohio manufacturing clusters was triangulated against top-down equipment vendor revenue segmentation.
Demand-supply-balance framing anchored the analytical approach across the analysis window, modeling tribometer procurement by product type, application focus, end-user sophistication, and technology architecture. Segmentation dimensions included pin-on-disk versus micro-tribometer configurations, wear versus friction testing emphasis, and digital versus analog platform generations. CAGRs were derived from installed base replacement cycles and greenfield laboratory buildouts, with EU Ecodesign mandate compliance timelines and IRA-linked aerospace reshoring incentives serving as industry-specific demand inputs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by spectroscopy-heritage conglomerates or rapid Chinese domestic equipment scaling would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Product Design Verification and Validation Solution Market
Test and Measurement
Duct Integrity Tester (DIT) Market
Test and Measurement
Metrology and Inspection Equipment Market
Test and Measurement
Air Leak Testing Market
Test and Measurement
Circuit Breaker Test Devices Market
Test and Measurement
Metrology Services Market
Test and Measurement
Lithium Metal Anode Dendrite Growth Visualization Test Platforms Market
Test and Measurement
Power Semiconductor Wafer-Level Reliability Test Equipment Market
Test and Measurement
Bit Error Rate Tester Market
Test and Measurement
Tensile Testing Machine Market
Test and Measurement
Satellite Communications and Direct-to-Device RF Test Platforms Market
Test and Measurement
IoT Testing Equipment Market
Test and Measurement
Ultrasonic Thickness Gauge Market
Test and Measurement
5G Testing Devices Market
Test and Measurement
Ethernet Test Equipment Market
Test and Measurement
North America Electronic Test and Measurement Market