
 Compression Testers Market | 2026-2036
Compression Testers Market Size, Share, and Industry Trends Forecast 2026-2036
Compression Testers Market Analysis
REACH compliance is hardening the cost-of-entry calculus for European compression tester suppliers, forcing investments in traceable calibration chains and material safety documentation. Instron leverages its North American service network to sustain long-term contracts with aerospace certification labs. ZwickRoell anchors its position through deep specialization in German automotive testing protocols. MTS Systems Corporation dominates high-force hydraulic segments for infrastructure materials research.
Compression testers are precision instruments that apply controlled axial loads to specimens, measuring compressive strength, yield point, and deformation characteristics through load cells with capacities ranging from newtons to meganewtons. These devices serve as gatekeeping tools across construction, automotive, and packaging industries where material failure prediction prevents catastrophic field performance. Digital compressors command the widest installed base due to their integration with laboratory information management systems, while wireless monitoring technology represents the fastest-expanding capability layer as remote construction sites demand real-time data transmission without tethered setups. Hydraulic testers retain entrenched positions in high-capacity structural analysis where electronic alternatives face thermal and electromagnetic constraints.
ISO 17025 accreditation requirements shape purchasing criteria for quality control labs across multiple jurisdictions, while FDA 21 CFR Part 11 influences electronic data integrity standards for pharmaceutical packaging compression studies. OSHA workplace safety rules in the United States and China's GB standards for construction materials collectively expand mandatory testing frequencies. Stakeholders must weigh captive calibration investments against third-party laboratory outsourcing as regulatory granularity intensifies across end-use sectors.
Market Dynamics
The Compression Testers Market is undergoing a fundamental recalibration as embodied carbon tracking mandates force construction firms to deploy portable, field-deployable compression units rather than centralized laboratory testing. This shift from fixed-site to distributed testing infrastructure is rewiring procurement patterns, service networks, and equipment specifications across multiple jurisdictions.
Growth Catalysts
- EU Green Deal embodied carbon protocols:German construction sites must now document material compressive strength at point-of-use, accelerating demand for battery-powered portable testers with integrated data logging.
- China's GB standards tightening:Infrastructure quality protocols in the eastern manufacturing corridor now mandate third-party witnessed compression testing for structural concrete, expanding certified laboratory capacity requirements.
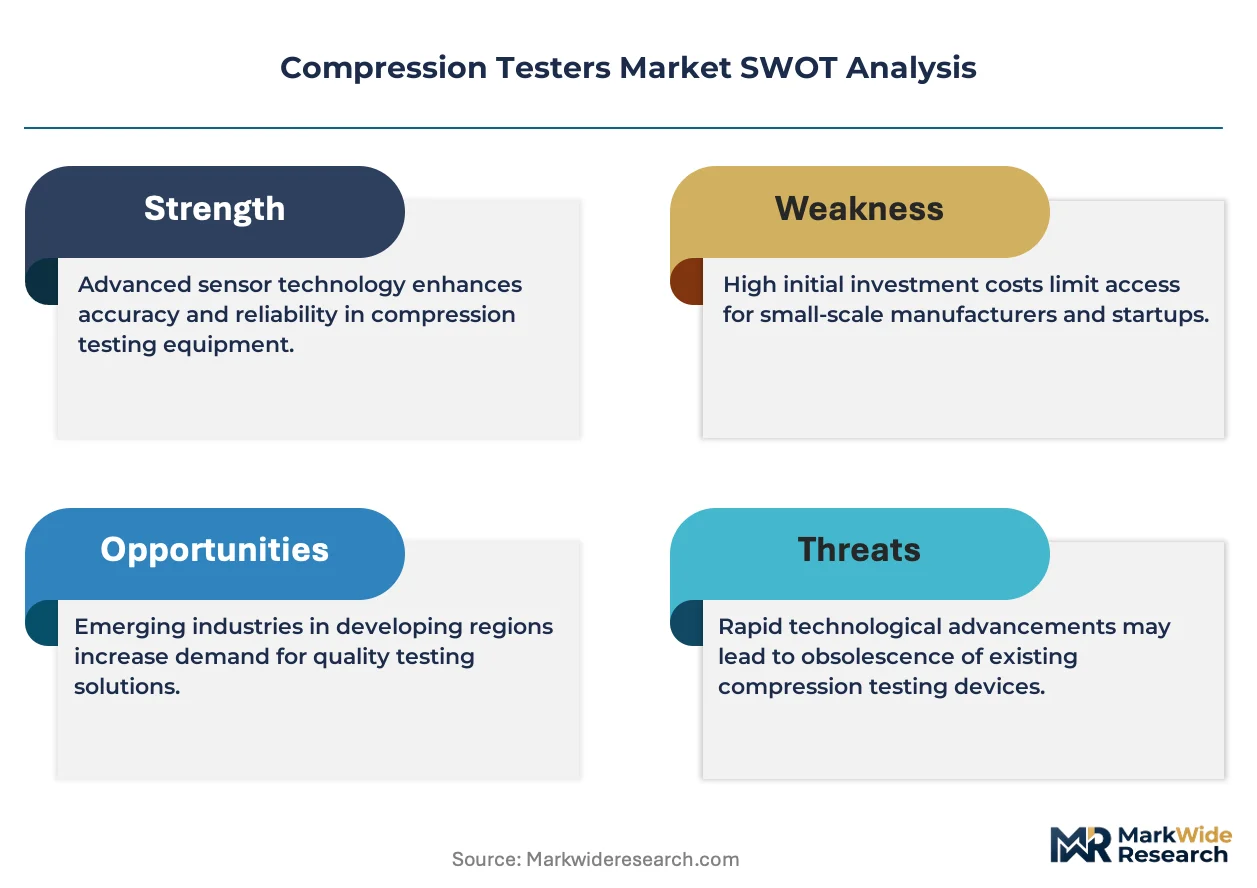
- Wireless telemetry integration:Real-time load cell data transmission to cloud-based quality management systems eliminates manual transcription errors and accelerates certification workflows for remote project sites.
Market Restraints
- Calibration chain traceability costs:REACH compliance and ISO 17025 accreditation requirements force European suppliers to maintain documented metrological traceability back to national standards laboratories, elevating fixed cost structures.
- High-force hydraulic component concentration:Precision servo valves and high-capacity load cells for meganewton-range testing remain concentrated among a limited supplier base in Germany and Japan, creating supply vulnerability.
- Electromagnetic interference constraints:Electronic compression testers face thermal and electromagnetic limitations in high-capacity structural analysis applications where hydraulic alternatives retain entrenched positions.
Strategic Opportunities
- India's PLI scheme for infrastructure equipment:Domestic manufacturing incentives for construction quality assurance equipment create localized production opportunities for mid-range digital compression testers.
- Battery-electric construction equipment convergence:Integration of compression testing units with electric vehicle charging infrastructure at job sites enables shared power management and reduced diesel generator dependency.
- Pharmaceutical packaging validation expansion:FDA 21 CFR Part 11 compliance requirements for electronic data integrity are extending compression testing demand into blister pack and medical device packaging lines.
Industry Challenges
- Metrology technician scarcity:Qualified personnel capable of maintaining ISO 17025-compliant calibration procedures for load cells and displacement transducers are in short supply across quality control laboratories.
- Legacy LIMS integration complexity:Digital compression testers must interface with entrenched laboratory information management systems through proprietary protocols, extending deployment timelines and customization costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compression Testers Market |
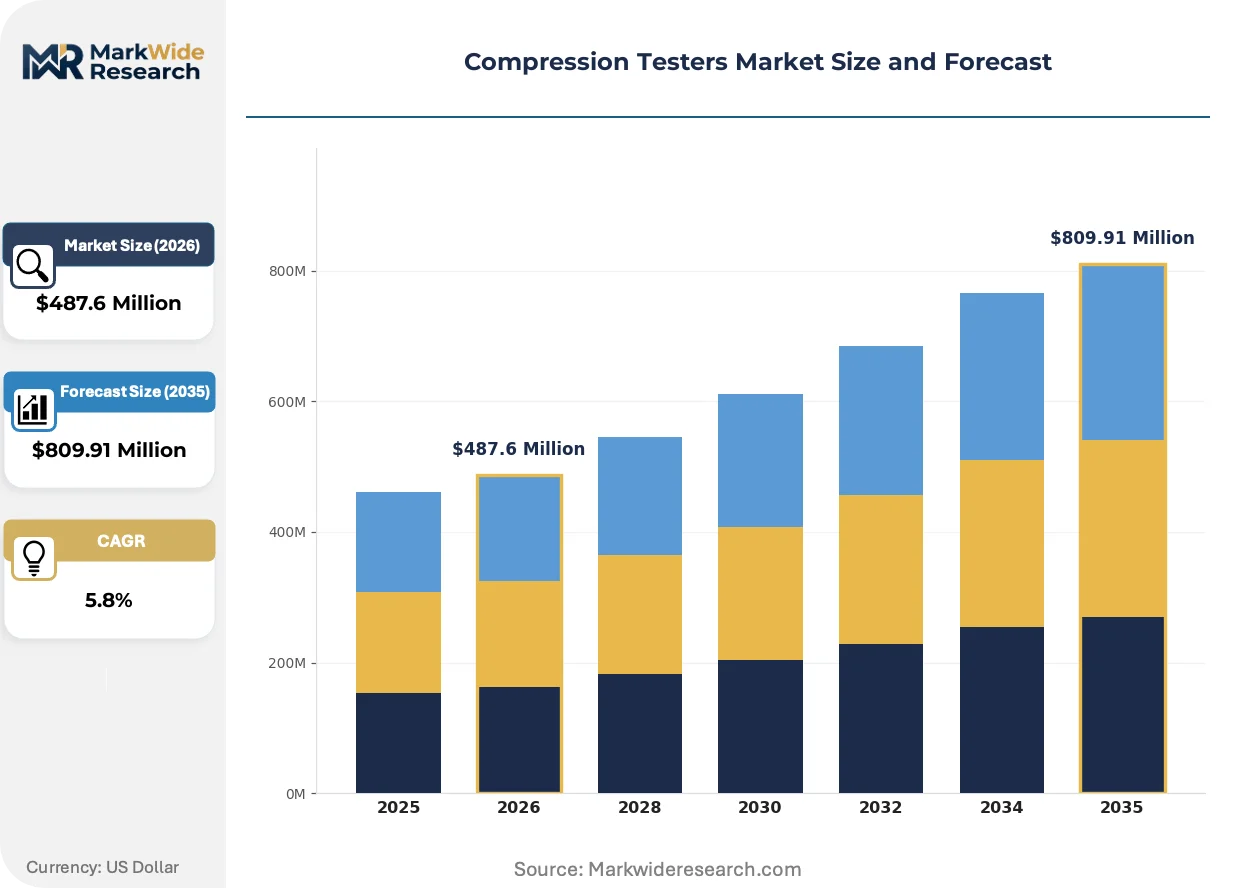
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Compressors, Mechanical Gauge Testers, Hydraulic Testers, Portable Units End User: Manufacturing Plants, Quality Control Labs, Construction Sites, Research Institutions Application: Material Testing, Equipment Calibration, Structural Analysis, In-Field Testing Technology: Hydraulic Technology, Electronic Measurement, Wireless Monitoring, Data Acquisition Systems |
| Companies Covered | Instron, MTS Systems Corporation, ZwickRoell, Shimadzu Corporation, Tinius Olsen, Lloyd Instruments, Aimil Ltd, ADMET, EIE Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compression Testers Market Emerging Trajectories
Wireless connectivity architectures and embedded sensor intelligence are transforming compression testers from isolated measurement devices into networked nodes within distributed quality assurance systems. These innovations are compressing the gap between field testing and laboratory-grade documentation.
Embedded edge computing modules within digital compression testers are integrating real-time statistical process control algorithms directly at the point of measurement. Construction quality managers in Germany are deploying these units to flag out-of-specification concrete batches before final curing. The technology is integrating predictive maintenance alerts based on load cell drift patterns, reducing unplanned downtime at remote infrastructure sites.
REACH substance restrictions are compelling European manufacturers to reformulate hydraulic fluids and eliminate specific polymer formulations in seals and gaskets. Equipment suppliers serving the German automotive testing sector are accelerating material substitution programs to maintain CE marking eligibility. The regulatory pressure is compressing product development cycles while elevating documentation burdens for material safety data sheets across the supply chain.
Construction firms are unbundling after-sales service contracts from equipment purchases, preferring third-party calibration providers with multi-brand capabilities. This procurement fragmentation is pressuring original equipment manufacturers to open their diagnostic protocols or risk margin erosion. The shift is most pronounced in China's eastern provinces where independent metrology laboratories are consolidating service capacity for multiple tester brands.
Compression Testers Market Segmentation
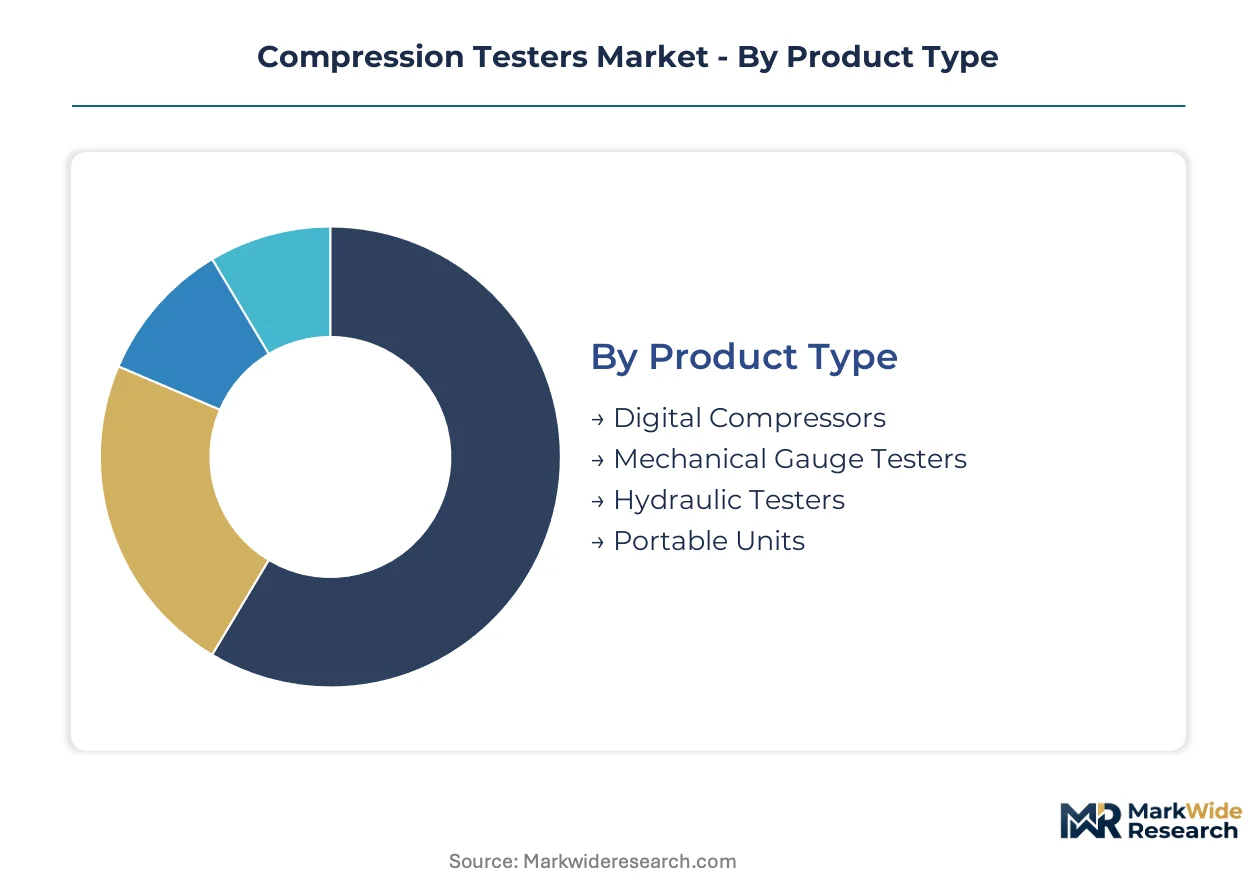
Compression tester procurement diverges sharply across end-use environments, with laboratory precision requirements clashing against field durability demands. Equipment specifications, connectivity architectures, and calibration protocols fragment into distinct product configurations that resist universal standardization.
Product Type:
Standardization pressures intensify at the high-capacity end while customization dominates portable and specialized applications.
- Digital Compressors:Microprocessor-controlled load cell systems with integrated data logging and LIMS compatibility. Demand concentrates in German automotive testing facilities under REACH-compliant calibration mandates, with ISO 17025 accreditation driving replacement cycles.
- Mechanical Gauge Testers:Analog dial-indicator systems requiring no electrical power, favored in electromagnetic-sensitive environments. Construction sites across China's eastern manufacturing corridor deploy these for concrete batch verification where power infrastructure remains unreliable.
- Hydraulic Testers:High-force systems utilizing precision servo valves for meganewton-range structural analysis.
- Portable Units:Battery-powered field-deployable systems with integrated wireless telemetry for point-of-use testing.
Leading the category by volume: Digital Compressors. Growing fastest: Portable Units.
End User:
Procurement authority shifts from centralized quality departments to distributed site managers as field testing expands.
- Manufacturing Plants:High-throughput production line integration with automated specimen handling and statistical process control feedback loops. German automotive suppliers anchor demand here, with ZwickRoell protocols dominating specification sheets.
- Quality Control Labs:Accreditation-dependent facilities requiring traceable calibration chains and FDA 21 CFR Part 11-compliant data integrity systems. US pharmaceutical packaging operations drive specialized compression validation equipment demand.
- Construction Sites:Harsh-environment deployment with dust ingress protection and battery operation.
- Research Institutions:Custom-configurable platforms for novel material characterization.
Procurement volume leader: Manufacturing Plants. Steepest expansion trajectory: Construction Sites.
Application:
Margin structures invert between routine compliance testing and specialized analytical services.
- Material Testing:Standardized compressive strength, yield point, and deformation characterization per ASTM and GB protocols. China's infrastructure quality tightening concentrates demand in third-party witnessed testing for structural concrete certification.
- Equipment Calibration:Metrological verification services for load cells and displacement transducers. Scarcity of ISO 17025-qualified technicians across European quality control laboratories elevates third-party service pricing.
- Structural Analysis:High-capacity testing for civil engineering load-bearing verification.
- In-Field Testing:Point-of-use concrete and soil compression verification without laboratory transport.
Revenue concentration: Material Testing. Climbing the fastest: In-Field Testing.
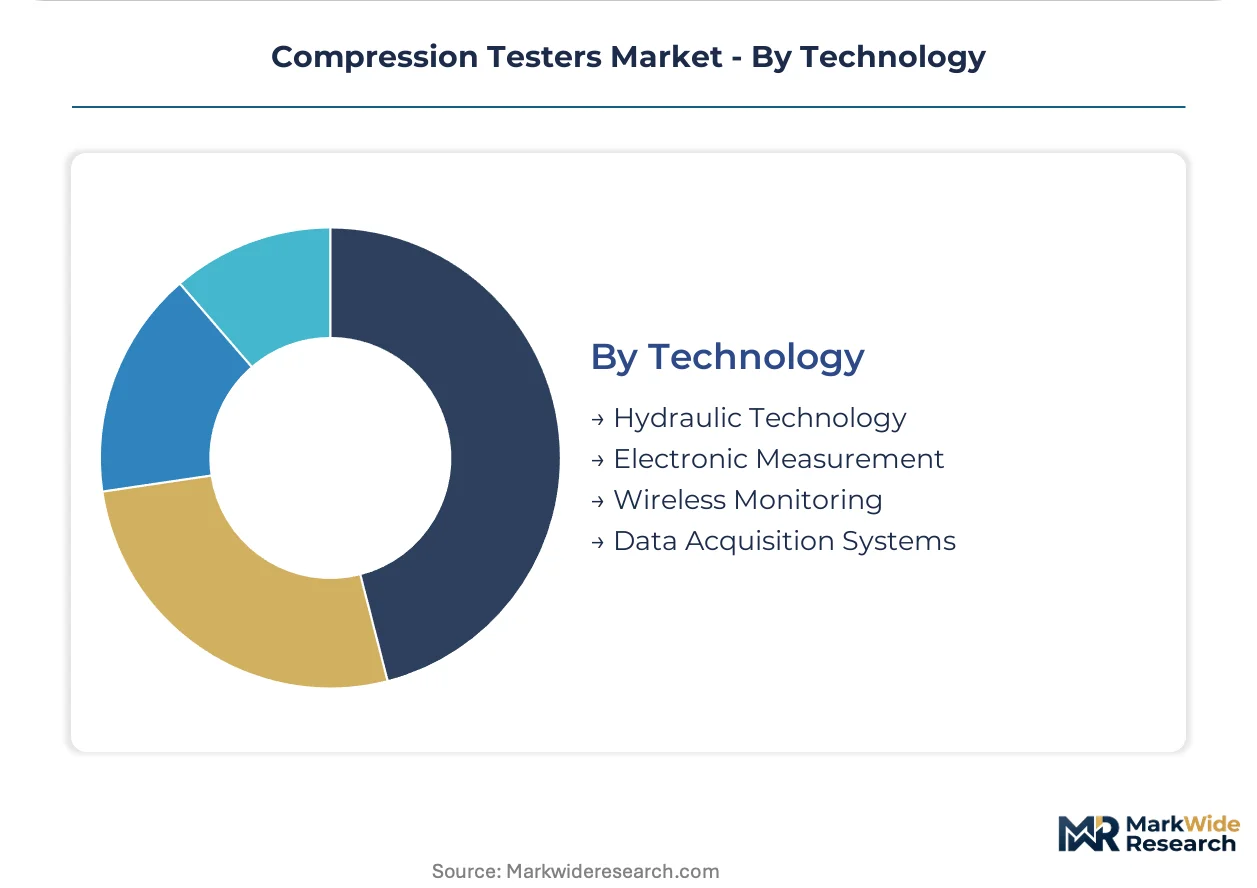
Technology:
Electronic architectures displace hydraulic systems in mid-range capacities while wireless layers retrofit across installed bases.
- Hydraulic Technology:Precision fluid power systems for thermal and electromagnetic immunity in high-force applications. German and Japanese component suppliers retain concentrated control over servo valves and high-capacity load cells.
- Electronic Measurement:Strain gauge and piezoelectric load cells with digital signal processing. REACH substance restrictions are forcing material substitutions in seal and gasket formulations across European manufacturing.
- Wireless Monitoring:Real-time telemetry eliminating manual data transcription at remote construction sites.
- Data Acquisition Systems:Multi-channel synchronized recording with cloud-based quality management integration.
Installed base leader: Electronic Measurement. Gaining share fastest: Wireless Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Lingang Special Area and Shenzhen's Qianhai zone concentrate battery-powered portable compression tester deployment for embodied carbon verification workflows.
United States
OSHA workplace safety rules and FAA aerospace certification standards drive demand for high-capacity hydraulic testers. Pharmaceutical packaging operations in New Jersey and North Carolina anchor FDA 21 CFR Part 11 compliance investment. Construction quality managers in Texas deploy wireless-enabled field units for real-time concrete batch verification.
Germany
EU Green Deal embodied carbon protocols force construction firms to document compressive strength at point-of-use. REACH compliance hardens calibration chain requirements for automotive testing facilities. Bavarian automotive suppliers under ZwickRoell protocol specifications dominate specification sheets for production line integration.
China
GB standards tightening in the eastern manufacturing corridor mandates third-party witnessed testing for structural concrete. MIIT infrastructure quality protocols expand certified laboratory capacity requirements. Yangtze River Delta construction clusters deploy portable units with integrated data logging for compliance documentation.
India
PLI scheme incentives for infrastructure equipment create localized production opportunities for mid-range digital testers. BIS construction material standards expand mandatory testing frequencies across quality control laboratories. Maharashtra and Gujarat manufacturing corridors concentrate domestic assembly capacity for export-oriented suppliers.
Japan
METI industrial standards and JIS certification requirements sustain precision instrument demand for automotive and electronics material testing. Precision servo valve suppliers in Nagoya retain concentrated control over high-capacity load cell components. Tokyo-based research institutions anchor custom-configurable platform demand for novel material characterization.
Compression Testers Market Vendor Landscape
German producers anchor the high-precision tier; Japanese specialists hold concentrated positions in hydraulic component supply. The vendor base stratifies across three tiers: integrated multinationals with captive service networks, mid-scale regional fabricators with sector-specific protocols, and emerging portable equipment specialists. Two dominant competitive moves define current positioning: unbundling of after-sales service contracts from equipment purchases, and acceleration of material substitution programs to maintain CE marking eligibility under REACH substance restrictions.
Within the integrated multinational tier, Instron and MTS Systems Corporation exemplify service-network-dependent positioning. ZwickRoell occupies a position as a protocol-specialist archetype anchored in German automotive testing standards. These three entities represent distinct competitive vectors: North American service density, high-force hydraulic dominance, and deep sector-specific calibration expertise respectively.
| Leading Market Players |
|---|
| Instron |
| MTS Systems Corporation |
| ZwickRoell |
| Shimadzu Corporation |
| Tinius Olsen |
| Lloyd Instruments |
| Aimil Ltd |
| ADMET |
| EIE Instruments |
| Others |
Supply Flow & Price Mechanics
Metrology technician scarcity in Germany's precision instrument corridor widens pricing-tier spreads between ISO 17025-certified premium units and uncertified economy alternatives, compressing margins for mid-range suppliers caught between REACH compliance costs and price-sensitive construction procurement in China's eastern provinces.
Pricing Analysis
Short lead-time premiums of 15-25% apply to battery-powered portable units with integrated wireless telemetry, while spot inventory of hydraulic servo valves commands discounts due to concentrated supply among Nagoya-based specialists. Pricing stratifies across premium, standard, and economy tiers based on calibration chain documentation depth and LIMS integration capability. Cost compression in the mid-range digital segment intensifies because construction firms unbundle after-sales service contracts, forcing OEMs to absorb diagnostic protocol opening costs. Quality control laboratories demonstrate lowest price sensitivity given accreditation mandates, while small-scale Indian infrastructure contractors under PLI scheme procurement exhibit highest elasticity.
Supply Chain Analysis
CE marking and ISO 17025 qualification gating restricts component sourcing to documented metrological traceability providers, concentrating precision load cell manufacturing in Germany and Japan while electronic measurement assemblies draw from South Korean and Taiwanese semiconductor suppliers. High-force hydraulic servo valves, strain gauge substrates, and lithium-ion battery packs constitute critical input dependencies. Single-source vulnerability persists for meganewton-range load cells where Nagoya specialists retain process knowledge concentration. Distribution runs through captive OEM service networks for accredited laboratory equipment, while construction-grade portable units penetrate via independent metrology laboratories with multi-brand calibration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Compression Testers Market functions as a cost-of-compliance arena where REACH substance restrictions and ISO 17025 accreditation requirements erect durable barrier-to-entry moats favoring incumbents with documented calibration chain investments.
For Market Incumbents: Extend captive calibration service networks into India's PLI scheme corridors to preempt third-party metrology laboratory consolidation. Deepen backward integration into precision servo valve sourcing through strategic partnerships with Nagoya component specialists, defending against supply disruption risks from Japan's concentrated hydraulic component base. For New Entrants and Emerging Players: Battery-electric construction equipment integrators represent an underserved buyer archetype seeking shared power management with compression testing units at job sites. Penetrate Germany's embodied carbon verification workflows through portable wireless-enabled field units priced below ZwickRoell protocol specifications. Pursue white-label partnerships with independent Chinese metrology laboratories consolidating service capacity across multiple tester brands. For Investors and Strategic Acquirers: Re-rating potential sits with calibration-specialist service platforms given EU Green Deal documentation mandates extending replacement cycles for legacy equipment. Long-term viability centers on providers with ISO 17025-qualified technician pipelines and cloud-based quality management integration capabilities. Monitor BIS construction material standard enforcement intensity across Maharashtra and Gujarat as inflection signal for Indian domestic manufacturing incentives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Servo Valves | Mitigates single-source vulnerability from Nagoya component concentration for high-force hydraulic segments. |
| Cloud-Based LIMS Integration Partnership | Accelerates deployment timelines by resolving proprietary protocol friction with entrenched laboratory systems. |
| Battery-Electric Construction Equipment Convergence | Enables shared charging infrastructure and reduces diesel generator dependency at remote German job sites. |
| Multi-Brand Calibration Service Consolidation | Captures procurement fragmentation as construction firms unbundle after-sales contracts from equipment purchases. |
| REACH-Compliant Material Substitution Program | Maintains CE marking eligibility through documented hydraulic fluid and polymer seal reformulation. |
Methodological Framework
Document review covered regulatory filings from ECHA, FDA, and MIIT, complemented by interviews with quality control laboratory managers, construction site engineers, automotive testing facility directors, and metrology service technicians. Secondary validation drew from ISO 17025 accreditation databases, REACH substance restriction updates, GB standards documentation, and customs trade records for precision instrument imports. Bottom-up equipment shipment analysis triangulated against top-down infrastructure spending projections.
Historical volume trajectories were cross-referenced against expert panel input from equipment procurement officers and aftermarket service heads. Segmentation modeling spanned product type, end-user environment, application protocol, and technology architecture across the projection horizon. CAGRs were derived from regression analysis of replacement cycle dynamics, regulatory mandate implementation timelines, and wireless telemetry adoption curves.
Revisions become necessary when REACH substance restriction scope expands, GB standards enforcement intensity shifts, or battery-electric construction equipment penetration accelerates beyond baseline assumptions. A model refresh is warranted upon material change in ISO 17025 accreditation renewal rates or PLI scheme localization thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Coaxial Profile Projectors Market
Test and Measurement
DSL Tester Market
Test and Measurement
Hipot Tester Market
Test and Measurement
Network Tester Market
Test and Measurement
Universal Testing Machine Market
Test and Measurement
Industrial Metrology Market
Test and Measurement
Circuit Tracer Market
Test and Measurement
Active Dosimeter Market
Test and Measurement
Wafer Testing Services Market
Test and Measurement
Microhardness Testing System Market
Test and Measurement
RF Test Equipment Market
Test and Measurement
Impact Testing Machine Market
Test and Measurement
Eddy Current Testing Market
Test and Measurement
Digital Battery Internal Resistance Tester Market
Test and Measurement
Global Conductivity Meters Market
Test and Measurement
Chiplet-Based System Thermal Cycling and Interconnect Fatigue Test Systems Market