
 Production Testing Market | 2026-2036
Production Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Production Testing Market Analytics
South Korea is rewriting the competitive map for production testing equipment as Samsung and SK Hynix expand domestic validation capacity for advanced memory nodes. Keysight Technologies dominates RF and signal integrity instrumentation for 5G and mmWave semiconductor validation. AMETEK, Inc. leverages its broad portfolio across environmental and materials testing to sustain positions in aerospace and automotive supply chains. Rohde & Schwarz anchors European demand with specialized vector network analyzers and spectrum monitoring systems for telecommunications equipment.
Production testing encompasses the systematic verification of manufactured components, assemblies, and finished goods against specified performance, reliability, and safety parameters using automated electrical, mechanical, and environmental stress protocols. Functional test systems execute pass-fail determinations on populated circuit boards at line rates exceeding thousands of units per hour, while boundary scan testers access internal node states through IEEE 1149.1-compliant test access ports when physical probe contact proves impractical. Automated test equipment captures the largest value pool in consumer electronics and semiconductor manufacturing where throughput and repeatability requirements are most stringent. Environmental testing is accelerating fastest as electric vehicle powertrain components and satellite payloads face expanded thermal cycling and vibration qualification regimes.
ISO 17025 accreditation requirements from the International Organization for Standardization shape third-party test lab competitiveness and OEM vendor qualification pathways. The EU AI Act and CE marking directives under the European Commission are introducing new conformity assessment obligations for autonomous systems and connected industrial equipment. In the United States, NHTSA safety validation protocols and FDA quality system regulations for medical device manufacturing impose additional testing documentation burdens. Stakeholders must monitor how converging functional safety standards across automotive, aerospace, and medical verticals reshape capital allocation priorities for multi-sector test service providers.
Market Dynamics
Advanced packaging architectures are forcing a complete reconfiguration of test floor layouts as heterogeneous integration multiplies probe interface requirements per wafer. Taiwan's foundry expansion and South Korea's memory cluster investments are concentrating capital equipment procurement among fewer buyers with steeper technical specifications.
Growth Catalysts
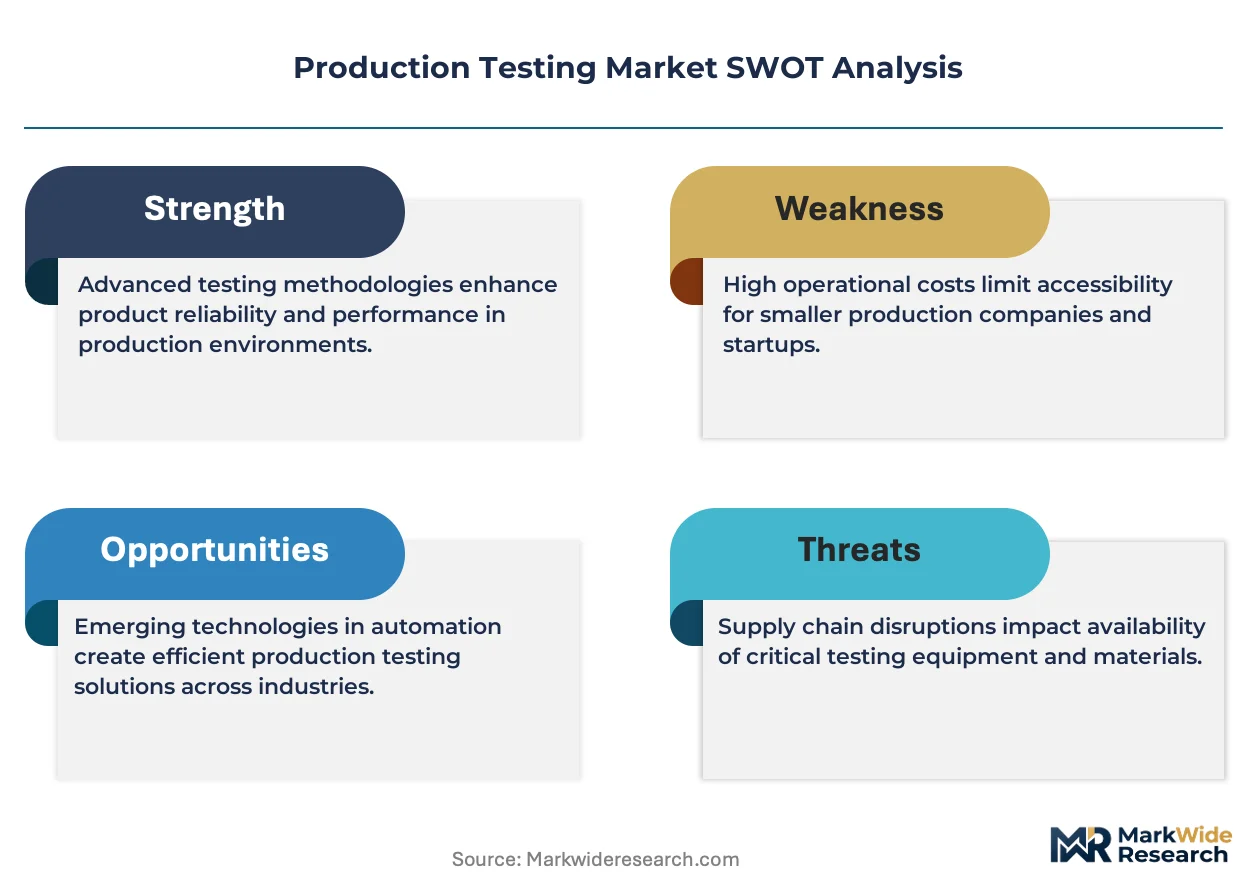
- EU Chips Act capital redirection:European domestic production testing infrastructure receives direct funding for capacity localization, pulling equipment demand toward Germany and France.
- Automotive functional safety mandates:ISO 26262 compliance requirements for electric vehicle powertrains expand environmental stress testing volumes across thermal cycling and vibration protocols.
- 5G mmWave commercialization:RF validation complexity at sub-6 GHz and mmWave frequencies multiplies test cell throughput requirements for baseband and antenna-in-package modules.
Market Restraints
- Probe card input concentration:Advanced MEMS probe manufacturing concentrates in Japanese and Korean suppliers, creating single-source vulnerability for sub-10μm pitch applications.
- Technical limitation in thermal management:High-power device testing at 500W+ dissipation exceeds conventional thermal chuck capabilities, forcing costly liquid-cooled handler retrofits.
- REACH substance restrictions:European chemical regulations constrain lead-free solder and specific flux chemistries used in test socket fabrication, extending qualification timelines.
Strategic Opportunities
- India semiconductor ecosystem emergence:PLI scheme incentives for domestic chip packaging create greenfield test capacity demand in Gujarat and Tamil Nadu.
- Space qualification protocols:Satellite constellation deployments expand radiation-hardened component testing requirements under NASA-STD-8739 and ESA ECSS standards.
- AI-driven predictive maintenance:Machine learning integration with test cell data streams enables shift from scheduled to condition-based equipment servicing.
Industry Challenges
- ATE software engineering scarcity:Test program development for complex SoC architectures requires rare expertise in C++ and Python automation frameworks.
- Multi-site probe card alignment:Parallel test configurations at 16-site and 32-site densities demand sub-micron planarity control that exceeds current handler mechanical tolerances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Production Testing Market |
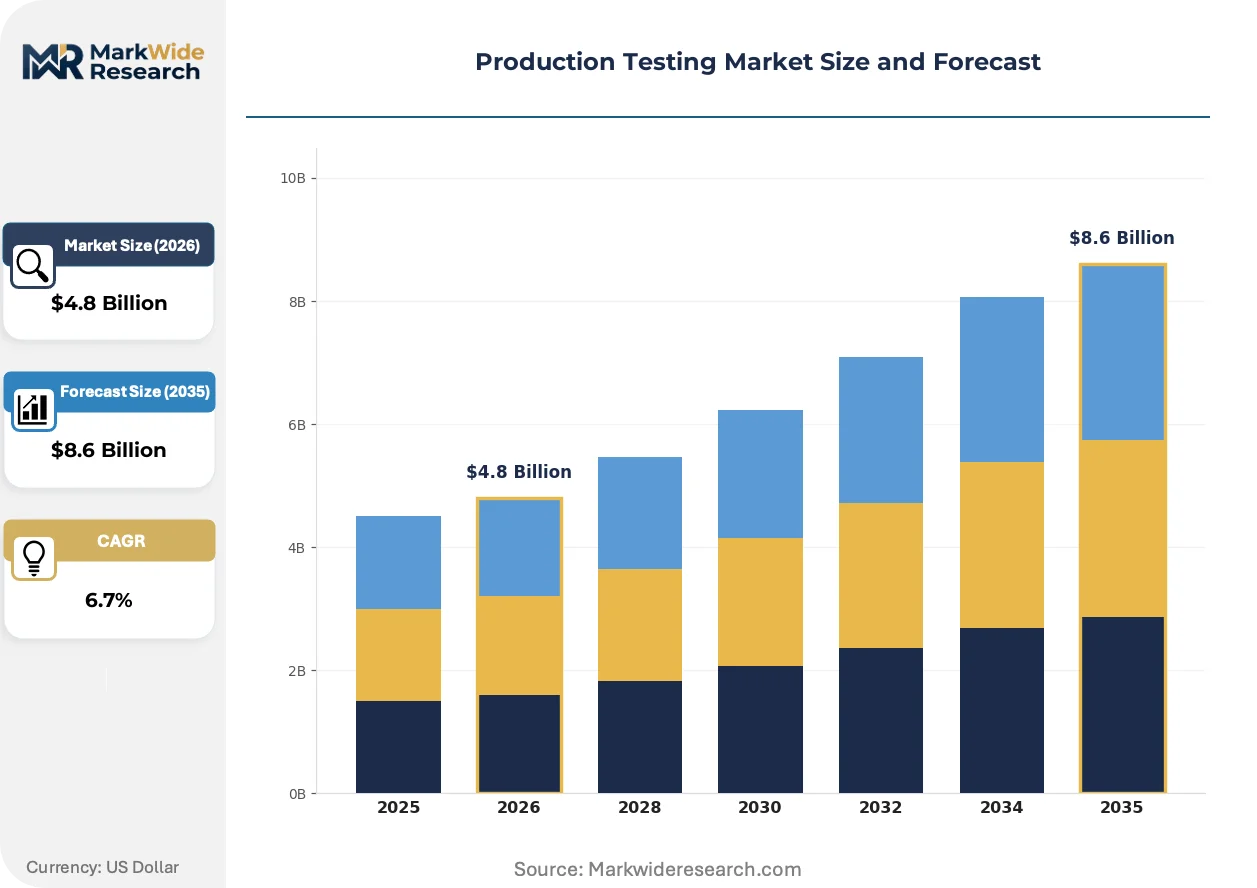
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Test Equipment, Functional Test Systems, In-Circuit Testers, Boundary Scan Testers Technology: RF Testing, Signal Integrity Testing, Optical Testing, Environmental Testing Application: Consumer Electronics, Automotive Components, Telecommunications Equipment, Aerospace Systems End User: Manufacturers, Third-Party Test Labs, Research Institutions, OEMs |
| Companies Covered | AMETEK, Inc., Zwick Roell Group, Keysight Technologies, Shimadzu Corporation, MTS Systems Corporation, Rohde & Schwarz, Instron (Illinois Tool Works), Bruker Corporation, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Production Testing Market Evolving Landscape
Test instrumentation architectures are converging around software-defined platforms that decouple hardware measurement engines from protocol-specific personality modules. This reconfiguration compresses capital depreciation cycles and forces incumbent vendors to defend installed bases through subscription licensing rather than hardware refresh.
Modular PXIe and AXIe chassis configurations are collapsing the traditional separation between digital, analog, and RF test domains within single programmable instruments. Aerospace and defense contractors in the United States adopt these consolidated platforms for radar and electronic warfare module validation, reducing test head count by integrating formerly discrete spectrum analyzers, arbitrary waveform generators, and high-speed digitizers. The consolidation is collapsing equipment vendor margin structures as hardware differentiation gives way to software licensing economics.
The EU AI Act conformity assessment obligations are mandating documented traceability for autonomous system validation data across training, verification, and deployment phases. Industrial equipment manufacturers must now maintain immutable test records for connected machinery CE marking, extending test data management infrastructure requirements. German automotive suppliers face the steepest compliance burden as their autonomous driving validation pipelines fall under both EU AI Act and UNECE WP.29 functional safety scopes.
Consolidated procurement by semiconductor foundries is compressing vendor negotiation cycles and unbundling after-sales service from equipment purchase contracts. Taiwan's leading-edge packaging houses now source test handlers through centralized technical purchasing teams that negotiate enterprise-wide frame agreements, displacing former site-level procurement autonomy. This concentration is most visible in Hsinchu Science Park where three buyers account for the majority of advanced probe station acquisitions.
Production Testing Market Segmentation
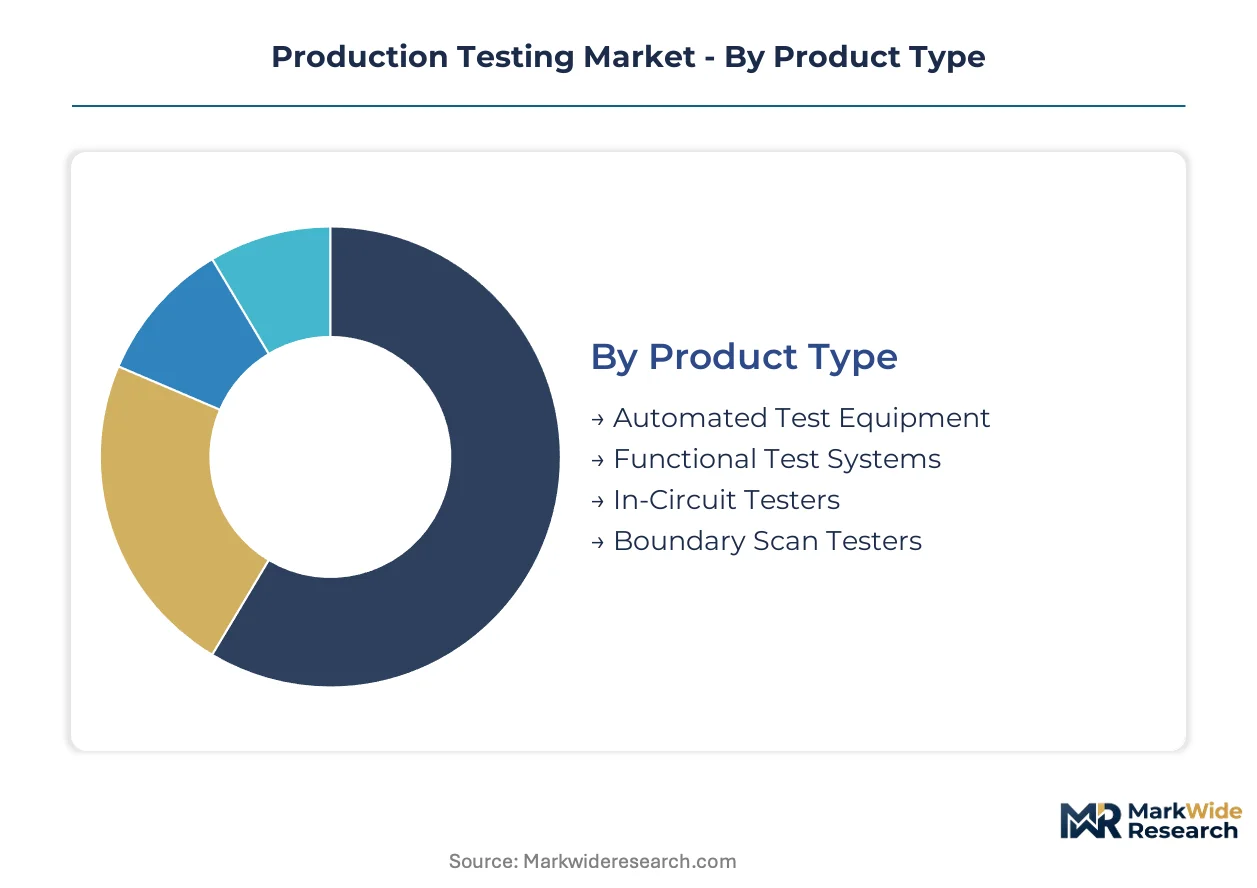
Production testing equipment segments diverge sharply in service intensity, with semiconductor ATE requiring continuous calibration contracts while environmental chambers demand episodic refurbishment. Understanding these operational rhythms shapes vendor profitability models and customer lifetime value calculations across the value chain.
Product Type:
After-sales service intensity varies dramatically across product categories, with automated test equipment generating recurring revenue through software maintenance and probe card replacement cycles while functional test systems rely on periodic hardware upgrades.
- Automated Test Equipment:High-throughput electrical validation platforms execute parametric and functional tests on wafers and packaged devices at line rates exceeding thousands of units per hour. Taiwan's foundry expansion concentrates procurement among Hsinchu Science Park buyers with enterprise-wide frame agreements that unbundle service contracts from hardware purchases. Keysight Technologies and Teradyne dominate this segment through subscription licensing models that defend installed bases against hardware refresh cycles.
- Functional Test Systems:Populated circuit board testers perform pass-fail determinations on assembled electronics using bed-of-nails fixtures and flying probe architectures. Automotive powertrain module validation in Germany's supplier corridor drives demand for systems compliant with ISO 26262 functional safety documentation requirements.
- In-Circuit Testers:Component-level verification systems access individual devices on loaded PCBs through fixed probe fixtures. These systems see steady replacement demand from contract manufacturers in South Korea's electronics clusters.
- Boundary Scan Testers:IEEE 1149.1-compliant systems access internal node states through test access ports when physical probe contact proves impractical for dense interconnects. Aerospace contractors in the United States adopt these for satellite payload validation under NASA-STD-8739 protocols.
By volume, Automated Test Equipment leads. By growth pace, Functional Test Systems is expanding most quickly.
Technology:
Technology selection tracks end-use performance thresholds, with RF and signal integrity testing commanding premium pricing for 5G infrastructure while environmental testing accelerates on electric vehicle qualification mandates.
- RF Testing:Vector network analyzers and spectrum monitoring systems validate sub-6 GHz and mmWave frequency performance for baseband and antenna-in-package modules. Rohde & Schwarz anchors European demand through specialized instrumentation for telecommunications equipment manufacturers.
- Signal Integrity Testing:High-speed digital validation systems characterize eye diagrams and jitter tolerance for multi-gigabit interconnects. Data center server and storage device manufacturers in the United States drive procurement of these systems for PCIe and DDR interface verification.
- Optical Testing:Photonic device characterization systems measure wavelength, power, and modulation quality for fiber optic transceivers. Telecom infrastructure deployment in India creates emerging demand as domestic data consumption expands.
- Environmental Testing:Thermal cycling chambers and vibration tables subject components to accelerated life stress protocols. Electric vehicle powertrain qualification under NHTSA safety validation protocols and expanded thermal cycling regimes for satellite payloads concentrate demand in automotive and aerospace verticals.
Environmental Testing gains share fastest as electrification expands qualification burdens. RF Testing retains the largest installed base.
Application:
Application segmentation reflects divergent compliance architectures, with automotive and aerospace imposing functional safety documentation that consumer electronics and telecommunications largely escape.
- Consumer Electronics:Smartphone, tablet, and wearable device validation at massive scale drives demand for highest-throughput test cell configurations. South Korea's memory and logic foundry clusters concentrate capital equipment procurement with steeper technical specifications than other geographies.
- Automotive Components:Electric vehicle powertrain, battery management system, and autonomous driving module testing requires ISO 26262-compliant documentation and environmental stress qualification. German automotive suppliers face overlapping EU AI Act and UNECE WP.29 compliance burdens that extend test data management infrastructure requirements.
- Telecommunications Equipment:Base station, router, and optical transport system validation spans RF, signal integrity, and protocol testing domains. 5G mmWave commercialization multiplies test cell throughput requirements as baseband complexity increases.
- Aerospace Systems:Radiation-hardened component and satellite payload qualification demands adherence to NASA-STD-8739 and ESA ECSS standards. Satellite constellation deployments expand testing volumes for space-grade semiconductor devices.
Consumer Electronics leads by unit volume. Aerospace Systems commands the highest average selling prices.
End User:
End user type determines procurement sophistication, with third-party test labs requiring multi-sector flexibility while captive manufacturer facilities optimize for single-vertical throughput.
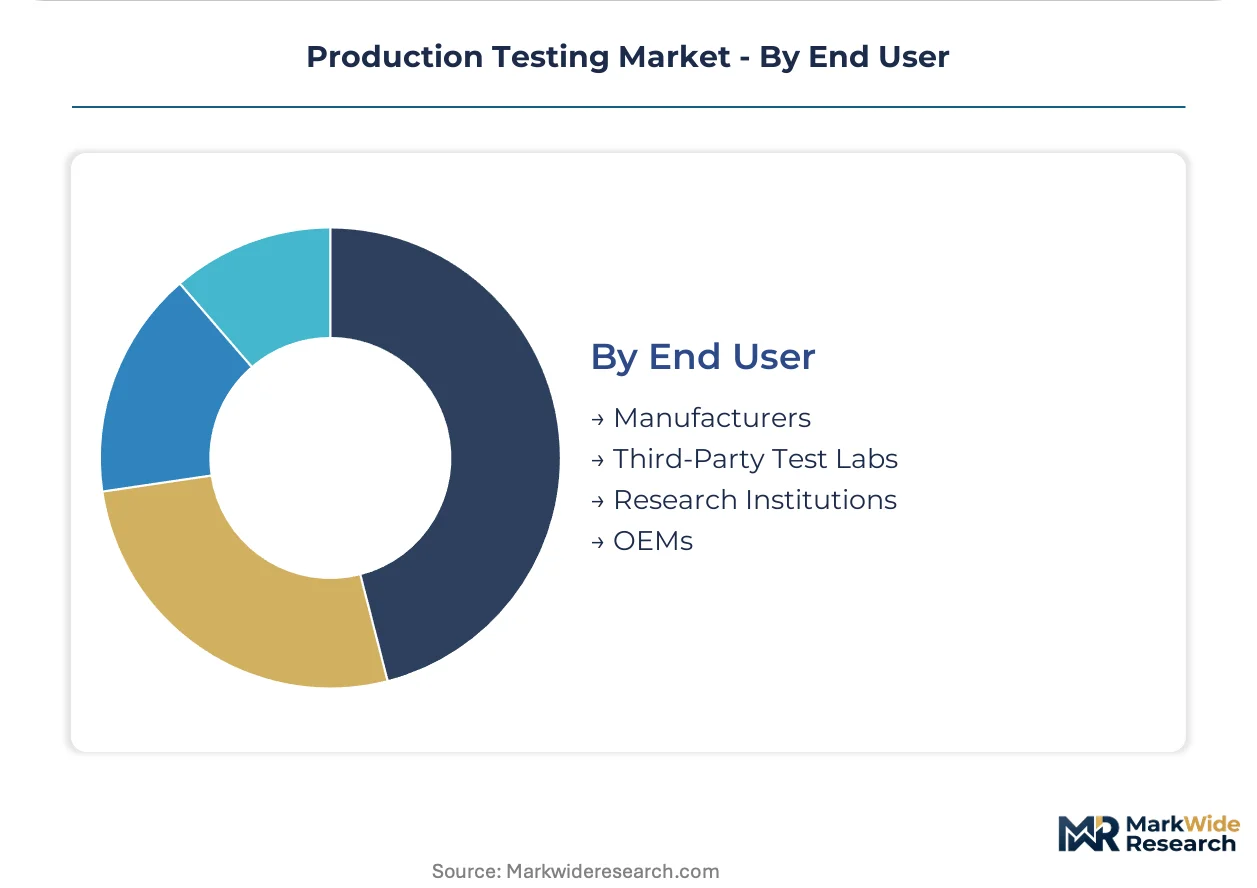
- Manufacturers:Captive test operations at semiconductor foundries, electronics assemblers, and automotive tier suppliers represent the largest equipment demand pool. Taiwan's leading-edge packaging houses source through centralized technical purchasing teams that negotiate enterprise-wide agreements.
- Third-Party Test Labs:Independent validation services must maintain ISO 17025 accreditation and multi-sector capability to serve OEM vendor qualification pathways. These facilities face converging functional safety standards across automotive, aerospace, and medical verticals that reshape capital allocation priorities.
- Research Institutions:University and government laboratory users prioritize measurement precision over throughput, adopting modular PXIe and AXIe platforms that integrate formerly discrete instruments. These buyers sustain niche demand for developmental test methodologies.
- OEMs:Original equipment manufacturers with in-house validation capabilities concentrate in aerospace and defense contracting, where ITAR and classified program requirements preclude outsourced testing. United States radar and electronic warfare module validation drives consolidated platform adoption.
Manufacturers account for the majority of equipment shipments. Third-Party Test Labs show the steepest expansion trajectory as outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kaohsiung-Taichung high-speed rail corridor underwrites Taiwan's dominance in semiconductor production testing infrastructure, shuttling precision equipment and engineering talent between foundry clusters. This connectivity anchors the island's position as the world's most concentrated test equipment procurement geography.
United States
NHTSA safety validation protocols for electric vehicle powertrains expand environmental stress testing volumes across thermal cycling and vibration qualification regimes. The FDA imposes quality system regulations for medical device manufacturing that extend testing documentation burdens. Greater Boston's aerospace corridor drives consolidated platform adoption for radar and electronic warfare module validation.
Taiwan
Hsinchu Science Park buyers negotiate enterprise-wide frame agreements that unbundle after-sales service from equipment purchase contracts, concentrating procurement among three dominant packaging houses. The National Development Council coordinates domestic production testing infrastructure investments. Taichung's precision machinery belt supplies automated handler retrofits for high-power device testing.
Germany
Automotive tier suppliers face overlapping EU AI Act conformity assessment obligations and UNECE WP.29 functional safety scopes that reshape test data management infrastructure requirements. The KBA enforces type approval protocols for autonomous driving systems. Stuttgart's supplier corridor drives ISO 26262-compliant documentation demand for electric powertrain modules.
South Korea
Samsung and SK Hynix expand domestic validation capacity for advanced memory nodes, concentrating capital equipment procurement with steeper technical specifications than other geographies. The MFDS regulates medical device testing standards that align with global export requirements. Yongin's memory cluster anchors RF and signal integrity instrumentation demand for 5G baseband modules.
India
PLI scheme incentives for domestic chip packaging create greenfield test capacity demand in Gujarat and Tamil Nadu as the semiconductor ecosystem emerges. The CEA mandates electrical safety testing protocols for power electronics. Sanand's special economic zone attracts probe card and test socket fabrication investments from multinational suppliers.
Production Testing Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the test instrumentation value chain. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with broad environmental and materials testing portfolios, pure-play measurement specialists with software-defined platform architectures, and precision mechanics fabricators serving probe card and handler subsystems. Consolidation pressures intensify as semiconductor foundries centralize procurement through technical purchasing teams, while licensing economics displace hardware refresh cycles as the primary revenue mechanism.
Among diversified industrial conglomerates, AMETEK, Inc. and Illinois Tool Works (Instron) exemplify the portfolio breadth archetype, spanning environmental chambers to mechanical load frames without concentration in single test modalities. Keysight Technologies and Rohde & Schwarz occupy positions within the RF and signal integrity measurement tier, anchoring European and North American demand for telecommunications validation equipment. These named entities represent competitive positioning patterns rather than specific strategic commitments, with each archetype facing distinct margin compression dynamics as hardware differentiation yields to software licensing and subscription servicing models.
| Leading Market Players |
|---|
| AMETEK, Inc. |
| Zwick Roell Group |
| Keysight Technologies |
| Shimadzu Corporation |
| MTS Systems Corporation |
| Rohde & Schwarz |
| Instron (Illinois Tool Works) |
| Bruker Corporation |
| Thermo Fisher Scientific |
| Others |
Value Network & Pricing Analysis
Japanese and Korean MEMS probe card manufacturing concentrates upstream, anchoring margin capture in sub-10μm pitch test interfaces while downstream equipment vendors absorb handler retrofit costs for high-power thermal management. This supplier concentration shifts pricing power toward precision mechanics fabricators and away from system integrators competing on software licensing economics.
Pricing Analysis
REACH substance restrictions dictate the pricing tier structure for European test socket procurement, forcing qualification cost absorption into premium tiers while standard offerings face extended compliance timelines. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17025-accredited validation systems from uncertified alternatives, with volume scale driving aggressive negotiation by Taiwan's centralized purchasing teams. Cost compression in mid-tier functional test systems is intensifying because automotive OEMs unbundle after-sales service from hardware contracts. Third-party test labs exhibit the highest price sensitivity due to multi-sector flexibility requirements, whereas captive semiconductor foundries prioritize throughput specifications over unit economics.
Supply Chain Analysis
Export controls on advanced semiconductor manufacturing equipment constrain probe station and precision handler flows between the United States and China, fragmenting procurement channels for leading-edge packaging houses. Taiwan, South Korea, and Japan anchor component supply for MEMS probe cards, thermal chucks, and precision motion stages, with raw material dependencies centering on beryllium copper alloys, ceramic substrates, and specialized solder chemistries. Single-source vulnerability in sub-10μm pitch probe manufacturing creates supply chain risk as advanced packaging architectures multiply interface requirements. Distribution runs through direct technical sales teams serving Hsinchu Science Park and Yongin memory clusters, supplemented by regional service hubs in Stuttgart and Greater Boston.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software maintenance and probe card replacement cycles expand faster than hardware depreciation, transforming production testing into a service-attach business where recurring revenue defends installed bases against competitive displacement.
For Market Incumbents: Build switching-cost moats through subscription licensing architectures that embed test program libraries and calibration protocols into long-term service contracts. Deepen backward integration into probe card refurbishment capabilities to capture replacement cycle economics. Defend against modular PXIe platform entrants by accelerating AI-driven predictive maintenance deployment that shifts customer value perception from hardware specifications to uptime guarantees. For New Entrants and Emerging Players: Establish a beachhead in India's greenfield test capacity installations across Gujarat and Tamil Nadu, where PLI scheme incentives reduce incumbent relationship advantages. Target environmental testing chambers for electric vehicle powertrain qualification, a segment where ISO 26262 documentation requirements create certification barriers that favor specialized entrants over diversified conglomerates. Lead with outcome-based service contracts that guarantee thermal cycling throughput rather than equipment specifications. For Investors and Strategic Acquirers: Capital is best deployed toward precision mechanics fabricators with captive probe card or thermal handler technologies, as these upstream positions capture margin pools that software-defined platforms compress at the system tier. Over the projection horizon, viability hinges on defensible IP in high-power thermal management or sub-micron alignment systems. Watch for inflection when Taiwan's foundry procurement teams consolidate test handler acquisitions into single-source frame agreements, signaling vendor rationalization acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Platform Migration | Decouples hardware engines from protocol modules, collapsing Keysight and Teradyne refresh cycles. |
| AI-Driven Predictive Maintenance Integration | Enables Rohde & Schwarz to shift German automotive customers from scheduled to condition-based servicing. |
| Backward Integration into Probe Card Manufacturing | Reduces Japanese supplier vulnerability for AMETEK's aerospace and automotive test socket lines. |
| ISO 17025 Accreditation Expansion | Qualifies third-party labs for EU AI Act conformity assessment obligations across autonomous systems. |
| Geographic Manufacturing Footprint in India | Positions Zwick Roell and MTS Systems to serve PLI-driven demand in Sanand's special economic zone. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with test floor managers at Taiwan packaging houses, calibration service directors at third-party labs, procurement leads at German automotive tier suppliers, and aftermarket heads at ATE vendors. Secondary validation drew from SEC 10-K filings, ISO 17025 accreditation registries, EU AI Act implementation guidance, and NHTSA safety validation protocol documentation. Bottom-up equipment shipment tallies by product category and top-down semiconductor capital expenditure projections were triangulated to constrain estimate variance.
Calibration against historical capacity expansion announcements and foundry frame agreement disclosures anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type, technology domain, application vertical, and end-user procurement sophistication, with additional stratification by regional regulatory cluster. CAGRs were derived from slope-consistency checks against semiconductor equipment spend patterns and electric vehicle production ramp assumptions, incorporating probe card replacement cycle frequencies and thermal chamber utilization rates as industry-specific inputs.
Sensitivities concentrate around EU Chips Act funding disbursement timing, REACH substance restriction enforcement severity, and foundry procurement centralization velocity. Forecasts reflect documented assumptions about memory node migration timelines and autonomous vehicle validation pipeline expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Torsion Tester Market
Test and Measurement
Calibration Management Software Market
Test and Measurement
Impact Testing Machine Market
Test and Measurement
Global Video Extensometer Market
Test and Measurement
High Rate Discharge Test Machine Market
Test and Measurement
Hearing Aid and True Wireless Earbud Acoustic Performance Test Systems Market
Test and Measurement
5G Testing Equipment Market
Test and Measurement
Reverberation Chambers Market
Test and Measurement
Cell Balancing Algorithm Hardware-in-the-Loop Test Platforms Market
Test and Measurement
Brightness Meter Market
Test and Measurement
Voltage Calibrator Market
Test and Measurement
Electronic Measuring Device Market
Test and Measurement
Radiation Tester Market
Test and Measurement
Millimeter-Wave and Sub-THz Semiconductor Device Characterization Platforms Market
Test and Measurement
EMC Shielding and Test Equipment Market
Test and Measurement
In-Circuit Test Market