
 AI-Assisted NDT Data Analytics and Defect Characterization Platforms Market | 2026-2036
AI-Assisted NDT Data Analytics and Defect Characterization Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
AI-Assisted NDT Data Analytics and Defect Characterization Platforms Market Insights
The EU AI Act is expanding compliance obligations for automated defect classification systems deployed in European manufacturing facilities. Waygate Technologies leverages its industrial inspection heritage to anchor cloud-based analytics deployments across energy and aerospace clients. Hexagon competes through metrology-integrated AI pipelines that extend digital-twin capabilities into real-time NDT workflows. Eddyfi Technologies specializes in eddy-current data interpretation algorithms that dominate niche electromagnetic inspection segments.
AI-assisted NDT data analytics and defect characterization platforms combine machine learning inference engines with ultrasonic, radiographic, and electromagnetic signal processing to automate flaw detection in critical infrastructure components. These systems typically process gigabyte-scale inspection datasets through convolutional neural networks trained on annotated defect libraries, reducing manual interpretation cycles from hours to minutes while standardizing detection consistency across operator skill levels. Deep learning analytics algorithms command premium pricing due to computational intensity and proprietary training data requirements, while cloud-based platform types capture expanding share among mid-sized inspection service providers seeking scalable subscription economics. Edge computing deployments remain concentrated in offshore oilfield services and marine engineering, where connectivity constraints mandate localized inference.
The EU AI Act, FDA device-software guidance, and ISO/IEC 23053 framework collectively shape validation requirements for AI-driven defect characterization, forcing vendors to document algorithmic transparency and performance drift monitoring. Germany's KBA enforces specific traceability standards for automotive safety-critical component inspection that filter into platform procurement specifications. Stakeholders must evaluate how emerging algorithm audit mandates will reshape R&D resource allocation between model accuracy advancement and regulatory documentation infrastructure.
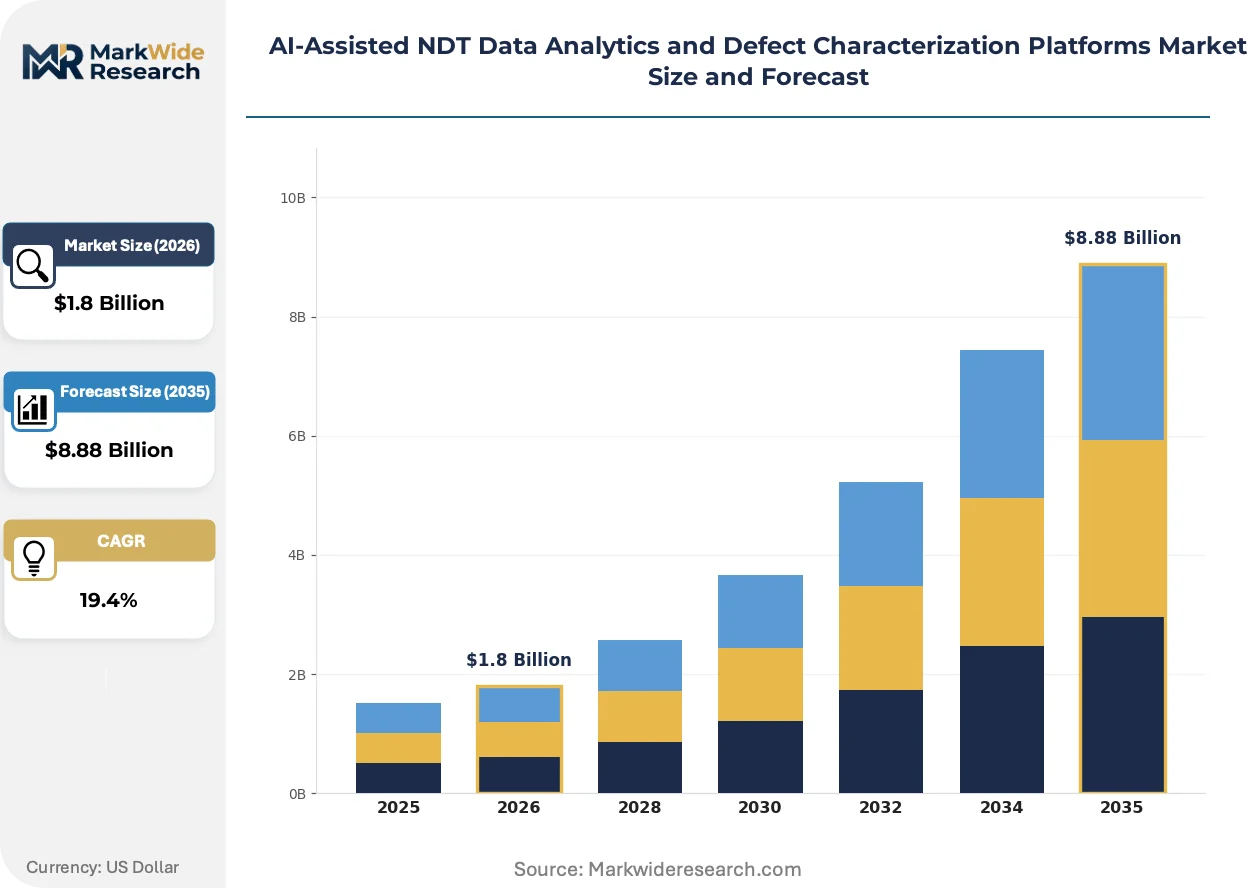
Market Dynamics
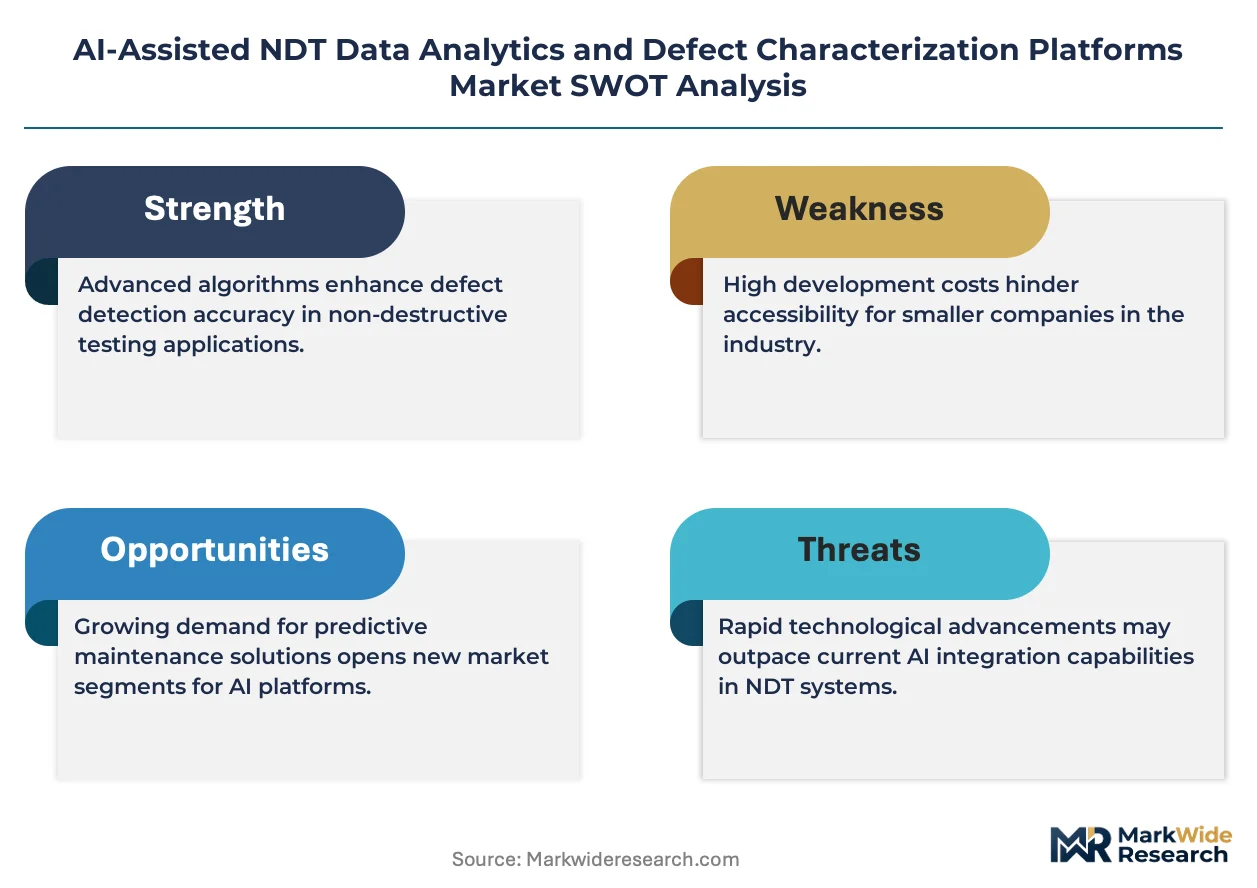
The EU AI Act's algorithmic transparency mandates are compressing vendor R&D timelines as engineering teams redirect resources from model refinement to audit documentation infrastructure.
Growth Catalysts
- Automotive Safety Mandates:Germany's KBA enforces traceability standards for safety-critical component inspection that filter directly into platform procurement specifications across Tier-1 suppliers.
- REACH Compliance Complexity:European chemical processing facilities deploy automated defect characterization to maintain pressure vessel integrity documentation required under evolving ECHA inspection protocols.
- Ultrasonic Phased Array Convergence:Aerospace turbine blade manufacturers integrate convolutional neural networks with phased array data streams to compress interpretation cycles from hours to minutes.
Market Restraints
- GPU Compute Cost Volatility:Training runs for proprietary defect libraries require sustained access to high-performance compute clusters whose pricing fluctuates with semiconductor foundry capacity constraints.
- Annotated Dataset Scarcity:Rare defect morphologies in critical infrastructure components limit training sample availability, forcing vendors into expensive manual curation cycles.
- CE Marking Friction:The EU MDR's software-as-medical-device classification creates validation bottlenecks for platforms targeting healthcare equipment inspection workflows.
Strategic Opportunities
- India Infrastructure Buildout:The country's PLI scheme for capital goods manufacturing creates procurement pull for automated inspection systems in steel and power transmission component production.
- F-Gas Regulation Tailwind:European refrigeration and HVAC equipment manufacturers face mandatory leak detection protocols that favor AI-enhanced ultrasonic monitoring over conventional methods.
- Digital Twin Integration:Convergence between real-time NDT analytics and physics-based simulation models enables predictive maintenance contracts in offshore wind turbine installations.
Industry Challenges
- Interdisciplinary Talent Scarcity:Platform vendors compete for engineers possessing simultaneous expertise in ultrasonic signal processing and deep learning architecture design.
- ISO/IEC 23053 Validation Burden:Documentation of performance drift monitoring and algorithmic transparency consumes engineering cycles that previously focused on accuracy improvement.
- Legacy System Integration Friction:Brownfield manufacturing facilities operate decades-old inspection hardware lacking API connectivity, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI-Assisted NDT Data Analytics and Defect Characterization Platforms Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Cloud-Based, On-Premise, Hybrid, Edge Computing Analytics Algorithm: Machine Learning, Deep Learning, Computer Vision, Pattern Recognition, Anomaly Detection Industry Application: Aerospace, Oilfield Services, Power Generation, Marine Engineering, Electronics Manufacturing End User Type: Inspection Service Providers, Equipment Manufacturers, Quality Assurance Labs, Research Institutions |
| Companies Covered | Waygate Technologies, Hexagon, Comet Yxlon, Zetec, MISTRAS Group, VisiConsult, Olympus, Eddyfi Technologies, Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI-Assisted NDT Data Analytics and Defect Characterization Platforms Market Trends and Innovations
Foundation model architectures trained on multi-modal inspection data are compressing time-to-deployment for specialized defect detection workflows.
Vision transformers are absorbing the feature extraction burden previously handled by hand-engineered signal processing pipelines. Aerospace maintenance divisions in France and Germany adopt these architectures for turbine blade inspection, reducing dependency on operator-specific interpretation expertise. The technology is absorbing market share from conventional convolutional approaches by enabling transfer learning across defect categories with limited training samples.
The EU AI Act's risk-based classification system imposes documentation burdens on automated defect characterization systems deployed in safety-critical manufacturing. Industrial software vendors must now maintain algorithmic audit trails and performance monitoring dashboards that satisfy notified body scrutiny. German automotive suppliers face the steepest compliance ramps as KBA traceability requirements intersect with AI Act algorithmic transparency mandates.
Subscription-based platform licensing is displacing perpetual software sales among mid-sized inspection service providers seeking scalable economics. European energy infrastructure contractors favor consumption-priced analytics access over capital-intensive on-premise deployments. France and the Netherlands show the fastest behavioral shift toward cloud-hosted defect characterization, driven by offshore wind farm inspection contracts requiring distributed analyst access.
AI-Assisted NDT Data Analytics and Defect Characterization Platforms Market Segmentation
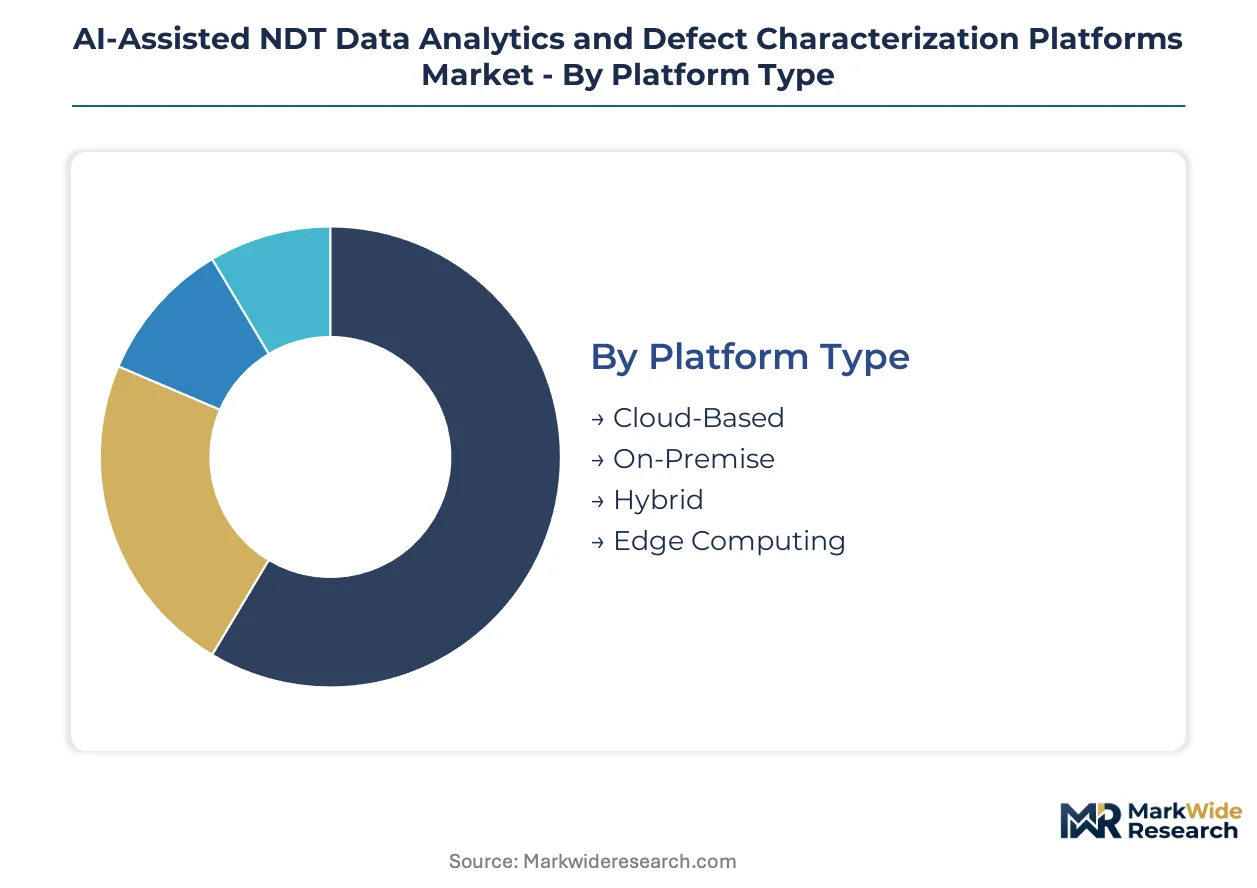
Platform procurement patterns diverge sharply across deployment architectures and analytical methodologies. Buyers weigh computational sovereignty against scalability economics when selecting system configurations for defect characterization workflows.
Platform Type:
Capital intensity and connectivity constraints drive buyer preference divergence across deployment models.
- Cloud-Based:Subscription licensing enables mid-sized inspection service providers to access enterprise-grade analytics without infrastructure investment. Procurement concentrates in France and the Netherlands among offshore wind farm contractors requiring distributed analyst access.
- On-Premise:Air-gapped deployments satisfy defense aerospace and nuclear facility security protocols. Demand clusters in Germany where KBA traceability mandates require localized data custody for automotive safety-critical component inspection.
- Hybrid:Federated architectures balance edge inference with centralized model training. European chemical processing facilities adopt these configurations to maintain pressure vessel integrity documentation under ECHA protocols.
- Edge Computing:Localized processing eliminates latency for real-time defect classification in bandwidth-constrained environments. Offshore oilfield services and marine engineering operations in the North Sea deploy these units where satellite connectivity remains intermittent.
Volume sits with Cloud-Based platforms; growth tilts toward Edge Computing.
Analytics Algorithm:
Algorithm selection hinges on defect library maturity and computational resource availability.
- Deep Learning:Convolutional neural networks and vision transformers process gigabyte-scale ultrasonic and radiographic datasets. Aerospace turbine blade manufacturers in France deploy these systems to compress interpretation cycles from hours to minutes.
- Machine Learning:Random forest and gradient boosting classifiers operate on structured feature vectors extracted from electromagnetic signals. Eddy-current inspection workflows in automotive manufacturing favor these lighter computational approaches.
- Computer Vision:Automated optical inspection pipelines detect surface anomalies in electronics manufacturing. Solder joint classification in PCB production lines represents the primary deployment vector.
- Pattern Recognition:Template-matching algorithms identify recurring defect morphologies in standardized components. Legacy infrastructure inspection in power generation leverages these interpretable methods for regulatory documentation.
- Anomaly Detection:Unsupervised architectures flag novel defect signatures absent from training libraries. Rare failure mode identification in critical infrastructure components drives niche adoption.
Commercial traction clusters around Deep Learning for high-value safety-critical applications; Anomaly Detection gains share fastest among research institutions exploring zero-shot defect classification.
Industry Application:
Sector-specific regulatory pressure and component criticality determine platform sophistication requirements.
- Aerospace:Turbine blade and airframe inspection demands sub-millimeter defect resolution. German and French maintenance divisions absorb the most advanced vision transformer deployments.
- Oilfield Services:Pipeline integrity management and subsea weld inspection require corrosion characterization under extreme pressure conditions. North Sea operators prioritize edge-deployable systems.
- Power Generation:Pressure vessel and steam turbine monitoring supports predictive maintenance contracts. European facilities align procurement with EU Green Deal asset longevity targets.
- Marine Engineering:Hull inspection and propulsion system analysis face saltwater corrosion acceleration factors. Classification society documentation requirements shape platform specification.
- Electronics Manufacturing:High-volume PCB and semiconductor packaging inspection prioritizes throughput over defect complexity. Surface-mount technology lines generate the densest deployment footprint.
Aerospace commands premium pricing; Electronics Manufacturing delivers volume scale.
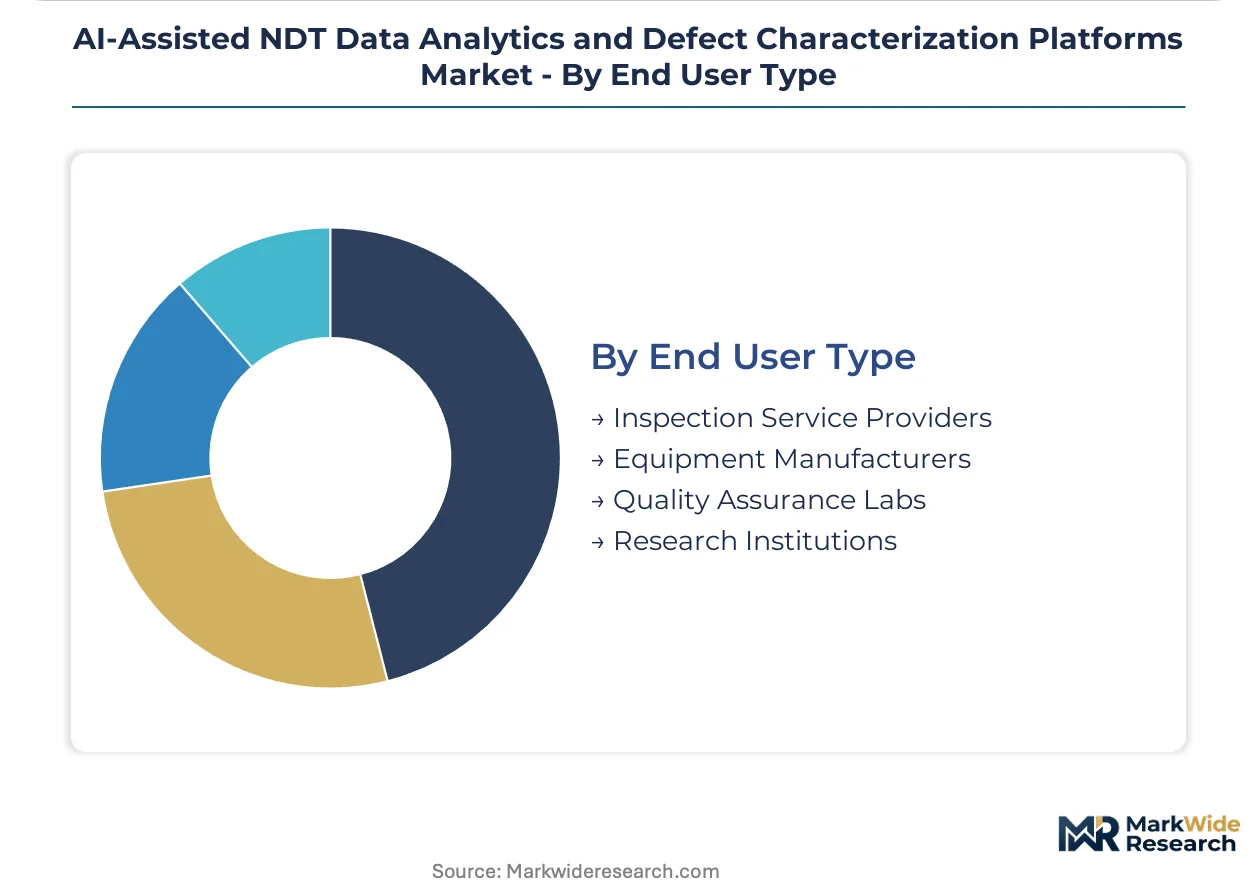
End User Type:
Organizational capability maturity and regulatory exposure differentiate procurement behavior.
- Inspection Service Providers:Third-party testing laboratories seek scalable subscription economics across diversified client portfolios. Cloud-based platform licensing dominates their procurement patterns.
- Equipment Manufacturers:In-house quality systems integrate analytics with production line PLCs for real-time feedback. German automotive Tier-1 suppliers embed these capabilities under KBA traceability mandates.
- Quality Assurance Labs:Accredited testing facilities require ISO/IEC 17025 compliant documentation trails. Audit-ready algorithmic transparency features command procurement priority.
- Research Institutions:University and national laboratory programs explore foundation model architectures and multi-modal inspection fusion. Grant-funded procurement tolerates longer deployment timelines.
Equipment Manufacturers anchor current revenue; Inspection Service Providers represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich's industrial corridor anchors European procurement for AI-assisted NDT platforms, with automotive and energy infrastructure investments driving concentrated demand across the continent's manufacturing belt.
Germany
Bavarian aerospace clusters and North Rhine-Westphalia automotive plants deploy vision transformer architectures for turbine blade and safety-critical component inspection. KBA traceability mandates intersect with EU AI Act algorithmic transparency requirements, compressing vendor R&D timelines toward audit documentation. Stuttgart's Tier-1 supplier ecosystem embeds cloud-based analytics under subscription licensing models.
France
Aerospace maintenance divisions in Toulouse and Paris-Saclay absorb advanced defect characterization systems for airframe integrity verification. ANSM documentation standards for healthcare equipment inspection create parallel compliance pathways for industrial software validation. Offshore wind farm contractors along the Atlantic coast favor consumption-priced platform access for distributed analyst coordination.
United States
Gulf Coast oilfield services and Great Lakes manufacturing corridors drive edge computing deployments where connectivity constraints mandate localized inference. FDA device-software guidance shapes validation protocols for platforms targeting medical equipment inspection workflows. Houston's energy infrastructure contractors prioritize corrosion characterization systems under extreme pressure conditions.
China
Yangtze River Delta steel production and Pearl River Delta electronics manufacturing generate dense deployment footprints for automated optical inspection. MIIT industrial internet policies accelerate platform adoption in capital goods production lines. Shenzhen's PCB assembly plants prioritize throughput-optimized computer vision pipelines for solder joint classification.
India
Maharashtra and Gujarat capital goods manufacturing clusters absorb automated inspection systems under the PLI scheme for industrial equipment production. CEA power sector mandates drive pressure vessel integrity monitoring in thermal generation facilities. Tamil Nadu's automotive component suppliers integrate machine learning classifiers with electromagnetic signal processing for eddy-current workflows.
AI-Assisted NDT Data Analytics and Defect Characterization Platforms Market Competitive Landscape
Premium-margin players sit above commodity-margin players across algorithmic sophistication and regulatory documentation depth, with tiered pricing separating proprietary training data holders from open-source framework deployers. The vendor base clusters around three strategic archetypes: industrial inspection heritage firms leveraging cloud migration, metrology-integrated platform builders extending digital-twin capabilities, and electromagnetic specialists dominating niche signal interpretation segments. Dominant competitive moves include federated architecture development for hybrid deployment configurations and strategic partnerships bridging legacy hardware connectivity gaps.
Within the industrial inspection heritage tier, Waygate Technologies and Baker Hughes occupy positions shaped by decades of energy and aerospace client relationships. Hexagon exemplifies the metrology-integrated archetype through its positioning at the convergence of measurement science and real-time analytics pipelines. Eddyfi Technologies anchors the electromagnetic specialization vector, with its focus on eddy-current data interpretation algorithms representing a distinct competitive position against broader multi-modal platform builders.
| Leading Market Players |
|---|
| Waygate Technologies |
| Hexagon |
| Comet Yxlon |
| Zetec |
| MISTRAS Group |
| VisiConsult |
| Olympus |
| Eddyfi Technologies |
| Baker Hughes |
| Others |
Pricing and Supply Chain Analysis
Deep learning engineers concentrated in Munich's Bavarian aerospace corridor and Stuttgart's automotive belt drive labor-cost differentials that widen pricing-tier spreads between premium vision transformer deployments and standard machine learning classifiers. German KBA traceability mandates and EU AI Act compliance documentation inflate engineering overhead for safety-critical applications, compressing margins at the mid-market tier while sustaining premium pricing for audit-ready platforms.
Pricing Analysis
Outcome-based pricing anchored to defect detection throughput dominates platform commercialization, with vendors charging per-inspection fees tied to component volume processed rather than perpetual licensing. Three-tier pricing structure across premium, standard, and economy levels separates vision transformer architectures with full EU AI Act documentation from lighter gradient-boosting classifiers and open-source framework deployments. Cost compression in the standard tier is intensifying because GPU compute rental volatility and annotated dataset curation expenses squeeze vendor margins. Inspection service providers exhibit the highest price sensitivity, favoring subscription SaaS models, while German automotive Tier-1 suppliers absorb premium pricing for localized on-premise deployments with KBA-compliant audit trails.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor hub-and-spoke patterns for platform hardware delivery, with software distribution running through cloud infrastructure nodes in Frankfurt and Amsterdam. GPU semiconductor supply concentrates in Taiwan and South Korea, while specialized ultrasonic transducer manufacturing clusters in Germany and the United States. The supply chain draws from rare earth elements for electromagnetic inspection probes, high-purity silicon for sensor arrays, and proprietary training datasets curated through manual annotation labor. Single-source vulnerability in NVIDIA GPU allocation for training runs poses structural risk. Distribution runs through direct enterprise sales teams for large aerospace contracts, with channel partners serving mid-sized inspection service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a technology-transition phase where vision transformer architectures displace conventional convolutional neural networks across aerospace and automotive inspection workflows.
For Market Incumbents: Anticipate margin compression from open-source foundation models by accelerating proprietary dataset accumulation and embedding audit documentation capabilities ahead of EU AI Act enforcement deadlines. Incumbents should deepen backward integration into sensor hardware manufacturing to control transducer supply for electromagnetic inspection segments, while investing in federated learning infrastructure to serve hybrid deployment demand from European chemical processing facilities under ECHA protocols. For New Entrants and Emerging Players: Cloud service provider partnerships offer the most penetrable channel for reaching mid-sized inspection service providers in France and the Netherlands seeking consumption-priced analytics access without capital investment. White-space targets include anomaly detection algorithms for rare failure mode identification in offshore wind turbine installations, and edge computing units for North Sea oilfield services where satellite connectivity constraints mandate localized inference. A vertical-specific go-to-market angle through offshore wind farm contractors yields faster traction than horizontal platform positioning. For Investors and Strategic Acquirers: The window for entry favors electromagnetic inspection specialists with proprietary eddy-current signal processing libraries and established relationships with automotive Tier-2 suppliers. Long-term viability rests on regulatory moat depth rather than pure algorithmic accuracy, as EU AI Act documentation requirements and KBA traceability standards create sticky vendor-switching costs. The signal to watch is foundation model licensing momentum—if aerospace maintenance divisions in Toulouse and Munich accelerate adoption of multi-modal pre-trained architectures, acquisition premiums for conventional CNN-focused platforms will erode.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Architecture Development | European chemical processors under ECHA protocols demand hybrid edge-cloud configurations for pressure vessel monitoring. |
| Proprietary Dataset Accumulation | Rare defect morphology libraries from German automotive blade inspection create algorithmic differentiation moats. |
| Audit Documentation Infrastructure | EU AI Act algorithmic transparency mandates require performance drift monitoring dashboards for notified body scrutiny. |
| Sensor Hardware Backward Integration | Captive transducer manufacturing secures supply chain control for electromagnetic inspection segment dominance. |
| Cloud Partnership Channel Development | Microsoft Azure and AWS marketplace listings accelerate reach into mid-sized French and Dutch inspection service providers. |
Research Methodology
Trade association filings from the American Society for Nondestructive Testing, EU industrial policy documents, and hyperscaler infrastructure deployment disclosures formed the secondary backbone, cross-referenced against primary interviews with NDT platform engineering directors, aerospace maintenance operations managers, automotive quality systems procurement leads, and European regulatory affairs specialists. Bottom-up segment sizing triangulated against top-down macroeconomic indicators anchored market estimates.
Bottom-up modeling of deployment architecture, analytics algorithm type, and industry application segments across the analysis window generated volume and value outputs, with CAGRs derived from regression against industrial automation investment cycles and AI software adoption curves. Forecast inputs incorporated GPU compute cost trajectories, EU AI Act implementation timelines, and KBA traceability mandate enforcement patterns.
Caveats apply where semiconductor foundry capacity constraints, annotated dataset scarcity for rare defect morphologies, or EU MDR software-as-medical-device reclassification could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Protective Earth Resistance Meter Market
Test and Measurement
Telecom Testing Equipment Market
Test and Measurement
3D Automatic Optical Inspection Machine Market
Test and Measurement
Production Testing Market
Test and Measurement
Shock Test Machines Market
Test and Measurement
EMC Shielding and Test Equipment Market
Test and Measurement
Next-Generation Industrial Metrology and Inspection Market
Test and Measurement
Dosimeter Market
Test and Measurement
Field Inspection Tester Market
Test and Measurement
Digital Inspection Market
Test and Measurement
High Rate Discharge Test Machine Market
Test and Measurement
Tensile Testers Market
Test and Measurement
Industrial X-Ray Inspection System Market
Test and Measurement
Diamond Tester Market
Test and Measurement
Calibration Management Software Market
Test and Measurement
Automated Calibration-as-a-Service Platforms for Test and Measurement Assets Market