
 United Kingdom Kitchen Appliances Market | 2026-2036
United Kingdom Kitchen Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Kitchen Appliances Market Analytics
Urban household refurbishment is recalibrating demand toward integrated, space-efficient appliance suites. BSH Hausgeräte GmbH leverages its portfolio depth across built-in ovens and refrigeration to anchor the premium renovation segment. SMEG UK LTD differentiates through design-led positioning that commands showroom presence in London and Manchester trade channels. Electrolux AB sustains volume leadership in the mid-market through broad distribution across online retailers and national retail partnerships.
United Kingdom kitchen appliances comprise electrically powered or gas-fueled equipment designed for food storage, preparation, cooking, and cleaning, typically operating at 220-240V/50Hz with energy efficiency ratings scaled from A to G under UKCA marking requirements. Their primary purpose spans domestic food service operations and light commercial catering environments. Refrigerators and dishwashers lead unit volume, while smart technology and induction segments capture disproportionate margin pools as replacement cycles shorten and connectivity becomes standard above mid-tier price points. Energy efficient technology occupies the fastest-growing structural position, driven by regulatory floor rises and utility cost sensitivity among households.
The UK's Ecodesign for Energy-Related Products Regulations and the BEIS minimum energy performance framework shape product eligibility and import compliance, while UKCA marking supersedes CE conformity for goods placed on the Great Britain market. The Office for Product Safety and Standards enforces recall protocols and electrical safety standards that manufacturers must navigate for continued market access. Stakeholders must monitor the trajectory of smart appliance interoperability standards and the potential for carbon-border adjustments to reshape sourcing economics for imported components.
Market Dynamics
The UK's Ecodesign for Energy-Related Products Regulations is compressing conventional appliance lines while amplifying demand for connected, low-consumption models. Refurbishment activity among urban households is recalibrating procurement patterns toward integrated, space-efficient suites.
Growth Catalysts
- BEIS minimum energy performance framework:Tightening standards are forcing replacement of aging refrigeration and cooking equipment. Premium renovation households in Greater London respond fastest to efficiency mandates.
- Induction cooking technology:Gas-to-electric switching accelerates in new-build and retrofit kitchens. South East England housing stock renewal drives disproportionate uptake.
- Smart appliance interoperability:Connectivity protocols are standardizing above mid-tier price points. Shorter replacement cycles concentrate margin in app-integrated refrigeration and dishwashing.
Market Restraints
- UKCA marking transition costs:CE supersedence for Great Britain creates dual certification burden for EU-imported components. Small importers face disproportionate compliance overhead.
- Copper and rare earth magnet volatility:Induction motor and compressor manufacturing depends on concentrated global supply. Price swings compress assembler margins unpredictably.
- Gas infrastructure lock-in:Existing pipework in Victorian housing stock slows full electrification. Hybrid cooktop adoption remains transitional compromise.
Strategic Opportunities
- Scotland's net-zero housing pathway:Devolved building standards mandate heat pump readiness and electric cooking in social housing retrofits. Early appliance specification partnerships secure multi-year replacement pipelines.
- Voice and gesture HMI convergence:Amazon Alexa and Google Assistant integration with oven and refrigeration controls creates differentiation. Premium kitchen studios in Manchester and Birmingham trade channels command showroom premiums for demonstrable connectivity.
- Subscription-based maintenance:Predictive diagnostics via connected appliances enable service revenue unbundling from hardware sale. Warranty extension models shift margin to recurring streams.
Industry Challenges
- Smart appliance cybersecurity certification:The Office for Product Safety and Standards recall protocols lack specific IoT vulnerability timelines. Manufacturers self-certify against shifting threat landscapes.
- Legacy housing electrical capacity:Pre-1980s wiring in Northern England and Midlands rental stock cannot support 7kW+ induction loads. Retrofit electrical upgrades delay appliance replacement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Kitchen Appliances Market |
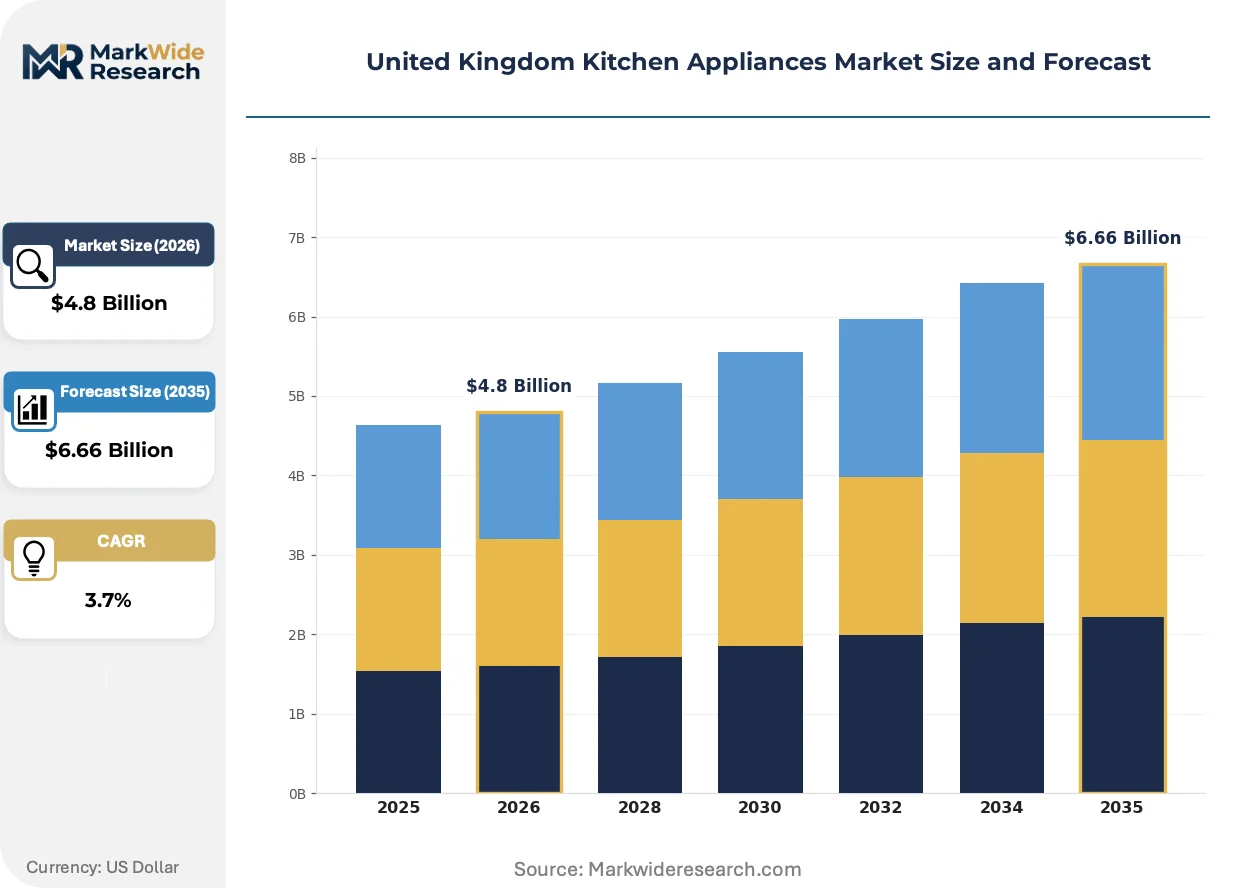
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Ovens, Dishwashers, Microwaves Technology: Smart Technology, Energy Efficient, Conventional, Induction End User: Households, Restaurants, Cafés, Catering Services Distribution Channel: Online Retailers, Showrooms, Hypermarkets, Specialty Stores |
| Companies Covered | Electrolux AB, SMEG UK LTD, Whirlpool Corporation, Miele & Cie. KG, Haier Smart Home, BSH Hausgeräte GmbH, LG Electronics, Dyson Ltd., Samsung Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Kitchen Appliances Market Evolving Landscape
Connectivity and modularity are redefining how UK households specify kitchen equipment. The convergence of energy efficiency mandates with smart home integration is compressing product development cycles.
Refrigeration compressor architecture is modularizing. Variable-speed inverter drives now enable capacity-matching to household size and usage patterns. Premium renovation buyers in Greater London specify scalable cold storage that expands with family formation. This modularity is compressing the traditional single-capacity SKU model.
BEIS minimum energy performance standards are tightening refrigeration efficiency floors. The 2024 framework removes G-rated models from sale and compresses D-E tier pricing. Mid-market assemblers are responding by accelerating inverter compressor adoption ahead of regulatory deadlines.
Urban household refurbishment is shortening appliance replacement cycles. Kitchen renovation timelines that once spanned fifteen years now compress to seven-to-ten. Trade channel buyers in South East England showrooms specify connected suites as single-project decisions rather than staggered replacements.
United Kingdom Kitchen Appliances Market Segmentation
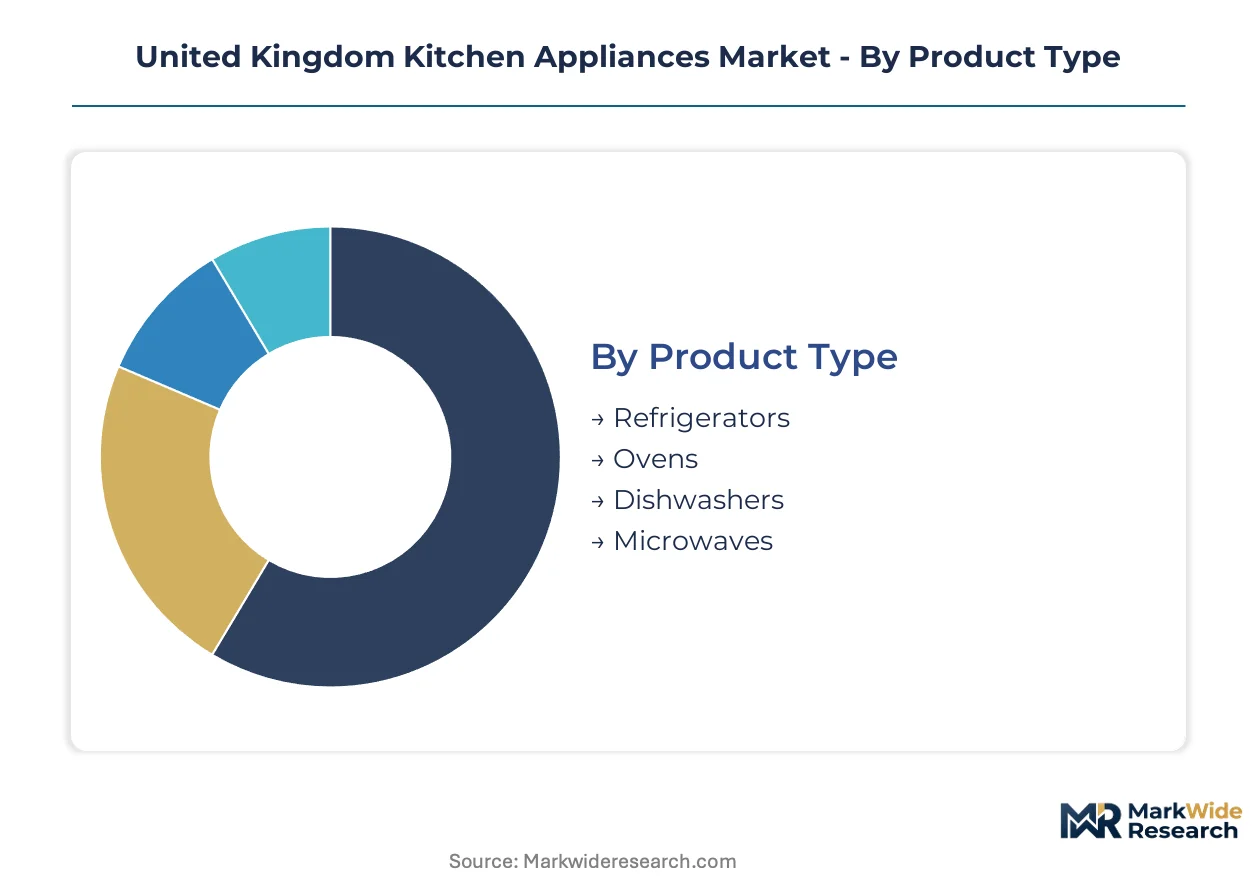
Segmentation in the United Kingdom kitchen appliances market reveals how capital deployment, regulatory pressure, and channel economics fragment procurement decisions. Manufacturers calibrate product architecture across four dimensions that each carry distinct margin profiles and compliance burdens.
Product Type:
Refrigeration and cooking equipment command the steepest upfront tooling investments due to compressor foundry requirements and thermal engineering complexity.
- Refrigerators:Variable-speed inverter compressors now dominate premium specifications, with modular capacity scaling from 200L to 500L+. Demand concentrates in Greater London renovation projects where BEIS efficiency mandates drive replacement of G-rated legacy units.
- Ovens:Pyrolytic self-cleaning linings and precision temperature controls define mid-tier and above. South East England housing stock renewal disproportionately specifies built-in electric models as gas-to-electric switching accelerates.
- Dishwashers:Water consumption below 10L per cycle now serves as the threshold for trade channel placement. Compact 45cm widths gain share in urban flats where kitchen footprints shrink.
- Microwaves:Inverter power delivery and sensor-based cooking cycles differentiate premium offerings. Replacement cycles remain shortest in this category.
Most installed capacity flows through refrigerators. Expansion is steepest in ovens as induction-compatible built-in units capture renovation specifications.
Technology:
Smart connectivity and energy efficiency now determine which products clear UKCA marking thresholds and qualify for retailer shelf space.
- Smart Technology:WiFi-enabled refrigeration and oven controls integrate with Amazon Alexa and Google Assistant protocols. Voice and gesture HMI convergence commands showroom premiums in Manchester and Birmingham trade channels.
- Energy Efficient:Inverter compressors and induction heating elements meet tightening BEIS minimum energy performance standards. The 2024 framework removes G-rated models from sale entirely.
- Conventional:Static compressor refrigeration and resistive heating elements face pricing compression as regulatory floors rise. Inventory clearance dominates this tier.
- Induction:Electromagnetic coil architecture requires rare earth magnet supply chains. Scotland's net-zero housing pathway mandates electric cooking in social housing retrofits, accelerating specification.
Energy efficient technology carries the heaviest compliance engineering burden. Smart technology is climbing the fastest as replacement cycles compress and connectivity becomes standard above mid-tier price points.
End User:
Procurement scale and replacement frequency diverge sharply between domestic households and foodservice operations.
- Households:Urban refurbishment in Greater London and the South East drives integrated suite purchases. Seven-to-ten year replacement cycles now prevail versus historical fifteen-year spans.
- Restaurants:Commercial-grade refrigeration and dishwashing equipment face intensive duty cycles. Health and safety inspection regimes enforce shorter replacement timelines than domestic settings.
- Cafés:Front-of-house display refrigeration and compact espresso machine integration shape specification. Aesthetic requirements override pure functional metrics.
- Catering Services:Mobile and event-based operations prioritize portability and rapid cycle times. Rental and lease structures dominate procurement.
Households absorb the greatest unit volume. Catering services are gaining share fastest as event-based foodservice expands post-pandemic.
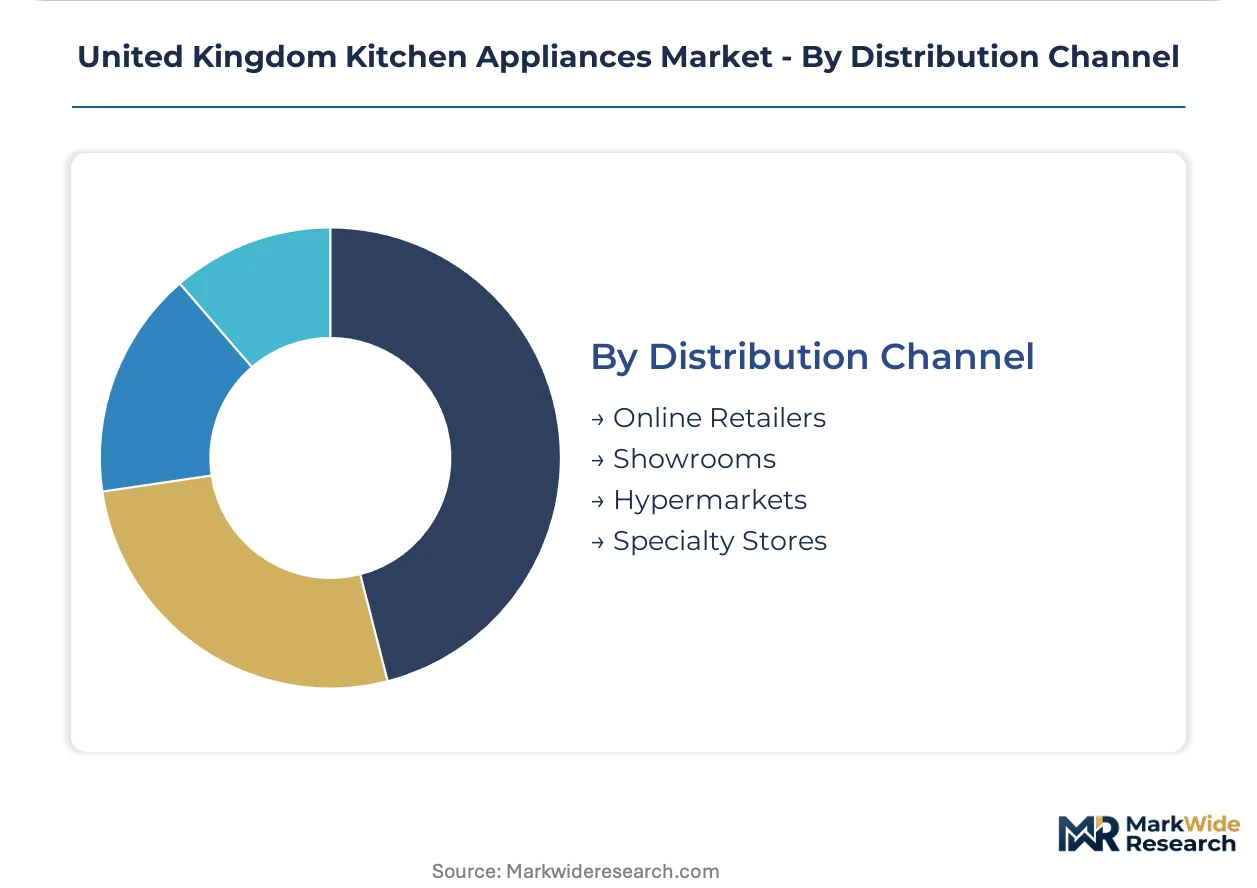
Distribution Channel:
Channel selection determines margin capture and customer acquisition cost structures across the value chain.
- Online Retailers:Electrolux AB and mid-market assemblers sustain volume leadership through broad e-commerce partnerships. Delivery logistics and return handling compress net margins.
- Showrooms:SMEG UK LTD and design-led brands command physical presence in London and Manchester. Demonstrable connectivity and aesthetic appeal drive conversion.
- Hypermarkets:Standard SKU breadth and promotional pricing dominate. Inventory turns prioritize velocity over margin.
- Specialty Stores:Independent kitchen studios offer specification consulting and installation coordination. Premium renovation buyers concentrate here.
Showrooms capture the highest margin per transaction. Online retailers are expanding most quickly as procurement patterns shift toward digital research and purchase.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater London anchors procurement intensity across the United Kingdom kitchen appliances market, with refurbishment cycles compressing replacement timelines and premium specifications concentrating in the capital's housing stock renewal corridors.
Greater London and South East England
Urban household refurbishment drives integrated suite purchases in Kensington, Chelsea, and Surrey renovation clusters. BEIS minimum energy performance standards mandate G-rated refrigeration removal from sale, accelerating inverter compressor adoption. South East England housing stock renewal disproportionately specifies built-in electric ovens as gas-to-electric switching accelerates.
Midlands
Birmingham and Manchester kitchen studios command showroom premiums for demonstrable smart appliance connectivity. The UK's Ecodesign for Energy-Related Products Regulations compress conventional product lines while amplifying demand for connected models. West Midlands trade channels show fastest uptake of voice and gesture HMI convergence in oven and refrigeration controls.
North England
Pre-1980s wiring in Northern England rental stock cannot support 7kW+ induction loads, delaying appliance replacement decisions. The Office for Product Safety and Standards enforces recall protocols that manufacturers must navigate for continued market access. Yorkshire and Lancashire refurbishment projects prioritize electrical upgrade coordination before appliance specification.
Scotland
Devolved building standards mandate heat pump readiness and electric cooking in social housing retrofits. Scotland's net-zero housing pathway creates multi-year replacement pipelines for early appliance specification partnerships. Glasgow and Edinburgh social housing authorities concentrate procurement volume for induction-compatible built-in units.
Wales and Northern Ireland
Smaller urban refurbishment markets in Cardiff and Belfast follow procurement patterns established in English metropolitan cores. UKCA marking supersedes CE conformity for goods placed on the Great Britain market, creating compliance coordination requirements. Northern Ireland's dual market access under the Windsor Framework maintains CE marking acceptance alongside UKCA requirements.
United Kingdom Kitchen Appliances Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers recalibrate around energy efficiency mandates and smart connectivity standards. The vendor base clusters into three tiers: premium design-led specialists, mid-market volume assemblers, and diversified electronics conglomerates. Two strategic archetypes predominate: heritage European appliance fabricators with refrigeration and cooking depth, and Asian consumer electronics groups leveraging display and semiconductor integration. Competitive moves concentrate on M&A for compressor foundry capacity and strategic partnerships for voice assistant protocol integration.
Within the heritage European tier, BSH Hausgeräte GmbH and Miele & Cie. KG exemplify premium positioning through built-in specialization and thermal engineering depth. SMEG UK LTD occupies a distinct design-led archetype, commanding showroom presence through aesthetic differentiation. Among diversified electronics groups, Samsung Electronics and LG Electronics represent scale-driven entries leveraging semiconductor and display integration for smart appliance convergence. Electrolux AB sits within the mid-market volume tier, sustaining broad distribution across online retailers and national retail partnerships.
| Leading Market Players |
|---|
| Electrolux AB |
| SMEG UK LTD |
| Whirlpool Corporation |
| Miele & Cie. KG |
| Haier Smart Home |
| BSH Hausgeräte GmbH |
| LG Electronics |
| Dyson Ltd. |
| Samsung Electronics |
| Others |
Value Network & Pricing Analysis
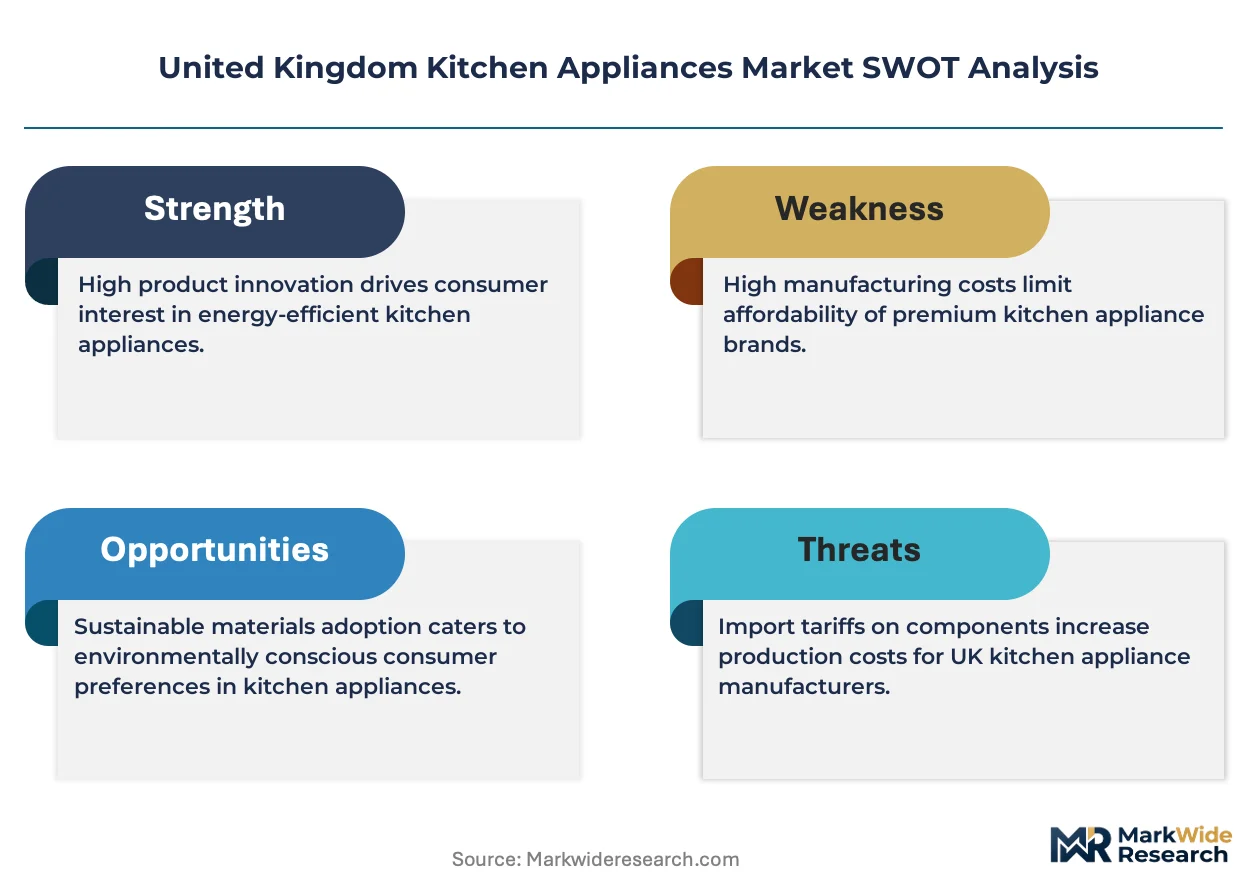
Copper and rare earth magnet price volatility cascades through UK kitchen appliance manufacturing, compressing assembler margins in induction motor and compressor production while amplifying cost differentials between premium inverter-equipped models and conventional static-compressor inventory. BEIS efficiency mandates and UKCA marking transition costs compound this pressure, forcing tiered pricing responses that separate connected, low-consumption specifications from clearance-tier conventional lines.
Pricing Analysis
Input-cost pass-through from copper and neodymium magnet supply chains intensifies pricing pressure across mid-market refrigeration and cooking equipment. Three-tier pricing structure across premium, standard, and economy levels stratifies by inverter compressor adoption and smart connectivity integration. Cost compression in the economy tier reflects inventory clearance of G-rated models banned under BEIS frameworks. Trade channel buyers in Greater London renovation clusters show least price sensitivity, while Northern England rental landlords face capital constraints from mandatory electrical upgrades.
Supply Chain Analysis
Rare earth magnet supply rests on concentrated Chinese and Vietnamese mining and refining operations, tethering induction cooktop and inverter compressor production to geopolitical exposure. Copper coil and steel enclosure sourcing draws from German and Italian metalworking centers, with compressor foundry capacity anchoring in Poland and Turkey. Single-source vulnerability in neodymium processing creates tariff exposure risk. Distribution runs through Rotterdam and Felixstowe port clusters into UK retail and trade channel warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom kitchen appliances market represents a late-cycle quality story as urban refurbishment in Greater London and South East England concentrates procurement toward integrated, connected suites with compressed replacement timelines.
For Market Incumbents: Deepen backward integration into inverter compressor foundry capacity to defend margin position against rare earth magnet price swings. Secure UKCA certification pipelines early to avoid dual-marking burden displacement by smaller EU importers. Channel control through Manchester and Birmingham kitchen studio partnerships anchors showroom premiums against online retail erosion. For New Entrants and Emerging Players: Scotland's net-zero housing pathway opens a window for induction-compatible built-in oven specification in social housing retrofits. Target Glasgow and Edinburgh local authority procurement frameworks with heat-pump-readiness bundling. Voice and gesture HMI convergence in premium refrigeration offers demonstrable differentiation for trade channel entry. For Investors and Strategic Acquirers: Asymmetric upside sits with design-led specialists possessing showroom presence in London and Manchester trade channels. Five-to-ten year viability hinges on smart appliance interoperability standard capture. Watch BEIS minimum energy performance framework trajectory for regulatory floor acceleration signals.| Strategic Initiative | Industry Significance |
|---|---|
| Voice Assistant Protocol Integration | Amazon Alexa and Google Assistant compatibility commands showroom premiums in Birmingham and Manchester kitchen studios. |
| Inverter Compressor Foundry Expansion | Captive supply of variable-speed refrigeration drives BEIS compliance and margin protection against copper volatility. |
| Subscription-Based Maintenance Launch | Predictive diagnostics via connected appliances unbundles service revenue from hardware transaction economics. |
| Scotland Social Housing Partnership | Net-zero pathway mandates create multi-year replacement pipelines for induction-compatible built-in specifications. |
| UKCA Certification Pre-Positioning | Early compliance with Great Britain marking requirements displaces dual-burdened EU importer competition. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with appliance manufacturer product directors, kitchen studio specification consultants, and trade channel procurement managers with secondary validation through BEIS regulatory filings, UKCA marking guidance documents, and Office for Product Safety and Standards recall databases. Customs and trade flow data from HMRC supplemented production volume estimates. Bottom-up SKU-level modeling and top-down category spend analysis provided triangulation.
Historical reference periods anchored the projection horizon to pre-pandemic replacement cycle baselines and post-regulatory-shift demand inflections. Segmentation modeling spanned product type, technology tier, end-user category, and distribution channel dimensions. CAGRs derived from installed base turnover rates and efficiency mandate compliance deadlines. Induction penetration curves and smart connectivity adoption thresholds served as industry-specific forecast inputs.
Revisions become necessary when BEIS regulatory floor trajectories accelerate, rare earth supply disruptions materialize, or smart appliance cybersecurity mandates harden. Forecasts reflect assumptions about housing stock renewal pace and electrical infrastructure upgrade coordination. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Egg Boiler/Cooker Market
Kitchen Appliances
Household Kitchen Appliances Market
Kitchen Appliances
Europe Built-In Coffee Machine Market
Kitchen Appliances
Europe Electric Vegetable Chopper Market
Kitchen Appliances
Global Baking Tools Market
Kitchen Appliances
Toast Maker Market
Kitchen Appliances
Commercial Induction Cooktops Market
Kitchen Appliances
China Kitchen Appliances Market
Kitchen Appliances
Induction Stove Market
Kitchen Appliances
Electric Grill Market
Kitchen Appliances
Switzerland Kitchen Appliances Product Market
Kitchen Appliances
Outdoor Cooking Equipment Market
Kitchen Appliances
United States Large Kitchen Appliances Market
Kitchen Appliances
Commercial Tabletop Kitchen Products Market
Kitchen Appliances
Cookware Accessories Market
Kitchen Appliances
Tabletop Kitchen Products Market