
 India Kitchen Appliances Market | 2026-2036
India Kitchen Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
India Kitchen Appliances Market Outlook
Premium-grade appliance tiers is rotating toward inverter-motor technology and stainless-steel chassis specifications that command higher shelf prices. TTK Prestige Ltd. leverages its pressure-cooker heritage to dominate stovetop-to-countertop transitions. Havells India Ltd. sustains R&D intensity in induction cooktop platforms. Bajaj Electricals Ltd. anchors its position through deep distribution into Tier-2 and Tier-3 towns.
India kitchen appliances comprise electrically or fuel-powered devices designed for food preparation, cooking, and storage, typically rated between 500W and 3000W and constructed from food-grade stainless steel, ABS plastic, or tempered glass. These appliances serve residential households, commercial kitchens, and institutional catering operations by automating manual cooking processes and improving energy efficiency. Blenders and mixers occupy the largest volume tier due to universal adoption across income segments, while induction technology represents the fastest-expanding category as urban households shift from LPG cylinders. The commercial end-user segment captures disproportionate margin pools from high-duty-cycle equipment sold to restaurant chains and cloud kitchens.
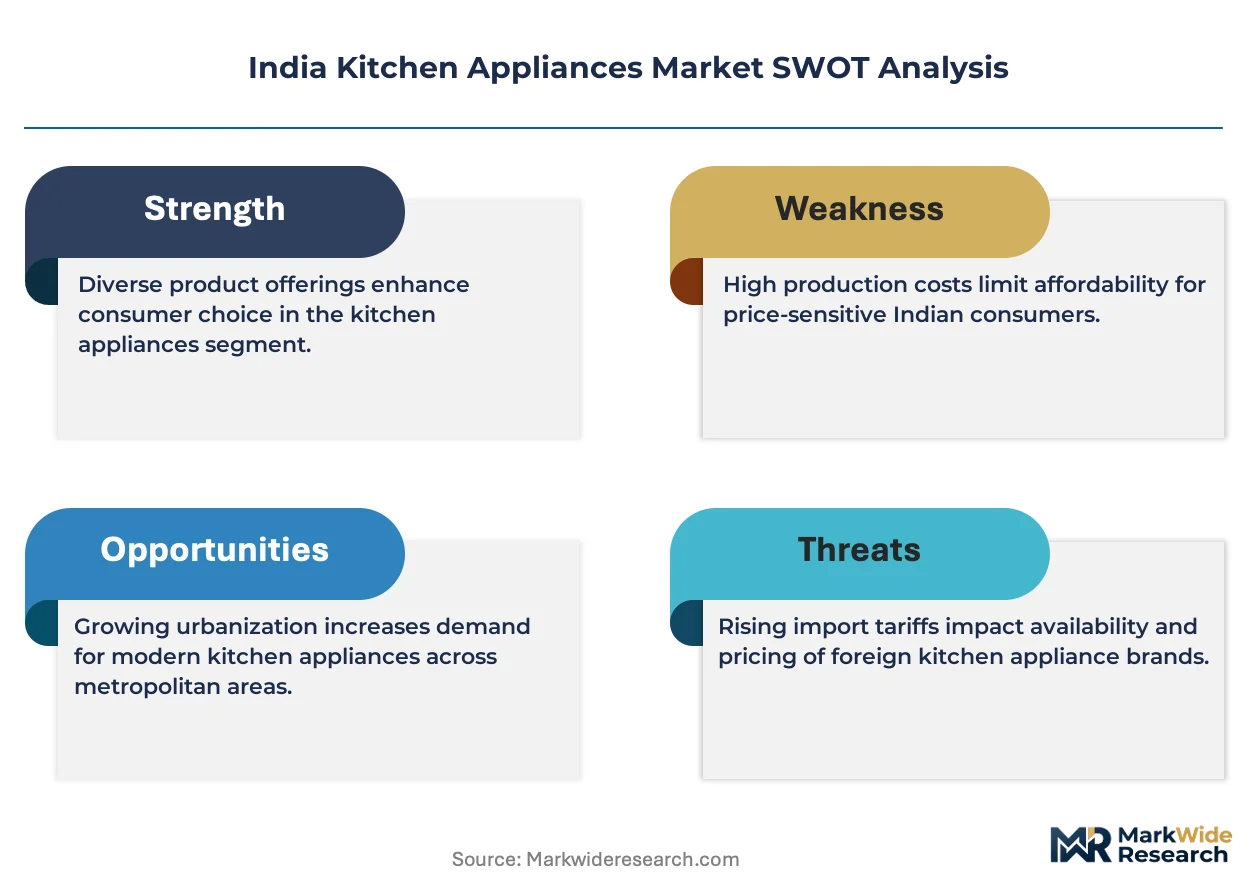
BIS mandates electrical safety certification for all domestic kitchen equipment, while the Bureau of Energy Efficiency enforces star-labeling standards that shape consumer purchase decisions and manufacturer design priorities. The PLI scheme for white goods manufacturing is drawing component suppliers to set up domestic production lines, reducing import dependency for compressor and motor assemblies. Stakeholders must monitor how state-level electricity tariff reforms affect the total cost of ownership for high-wattage appliances versus gas alternatives.
Market Dynamics
The India kitchen appliances market is being fundamentally restructured by the shift from LPG-based cooking to electric induction systems, a transition accelerated by state-level electricity tariff reforms and BIS safety mandates that are forcing product redesigns across the supply base.
Growth Catalysts
- BIS Electrical Safety Certification:Mandatory compliance requirements are filtering out substandard imports and creating captive demand for domestically certified manufacturers.
- Modular Kitchen Penetration:Maharashtra and Gujarat residential construction is embedding built-in appliance specifications into new housing stock.
- Induction Technology Maturation:Improved coil efficiency and glass-ceramic surface durability is converting skeptical urban households previously dependent on gas cylinders.
Market Restraints
- Copper and Cold-Rolled Steel Volatility:Motor winding and chassis input costs swing with commodity exchange rates, compressing margin predictability for mid-tier producers.
- Compressor Import Dependency:Domestic supply gaps for refrigeration compressors expose assemblers to currency fluctuation and shipping disruption risks.
- LPG Subsidy Persistence:Government cylinder pricing in rural belts sustains a cost advantage that electric alternatives cannot yet match.
Strategic Opportunities
- Tier-2 and Tier-3 Town Expansion:Distribution infrastructure gaps in Uttar Pradesh and Madhya Pradesh create first-mover advantages for organized players.
- Cloud Kitchen Equipment Demand:High-duty-cycle induction arrays and blast chillers serve restaurant chains scaling delivery-only operations.
- PLI Scheme Component Localization:White goods manufacturing incentives are pulling motor and controller suppliers to establish captive plants near assembly clusters.
Industry Challenges
- Skilled Technician Scarcity:Induction coil repair and inverter motor diagnostics require training pipelines that vocational institutes have not yet scaled.
- BIS Certification Timelines:Laboratory testing backlogs delay product launches by quarters, advantaging incumbents with established compliance teams.
- Legacy Gas Infrastructure Integration:Retrofit installations in existing Mumbai and Bangalore kitchens encounter spatial constraints that complicate sales closure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Kitchen Appliances Market |
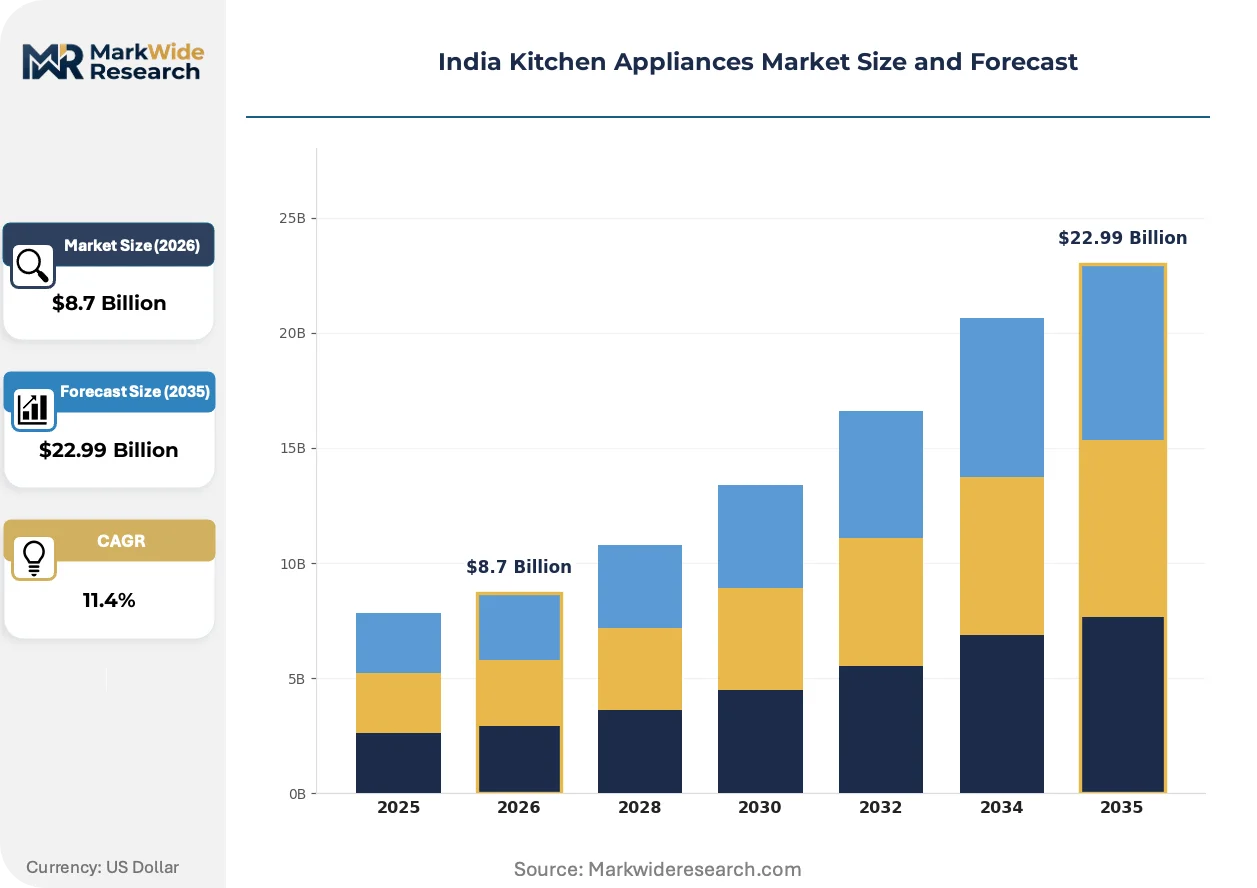
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blenders, Mixers, Toasters, Ovens End User: Residential, Commercial, Institutional, Catering Technology: Electric, Gas, Induction, Solar Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Whirlpool of India, Havells India Ltd., TTK Prestige Ltd., Electrolux India, Philips Domestic Appliances India, Samsung India Electronics, Bajaj Electricals Ltd., IFB Appliances Ltd., LG Electronics India, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Kitchen Appliances Market Strategic Shifts
Product architecture and procurement patterns in the India kitchen appliances market are diverging from legacy specifications as energy efficiency mandates and urban housing formats rewrite design priorities.
Inverter motor technology is supplanting universal motors in mixer-grinder and juicer categories by delivering variable speed control and thermal protection. Urban households in Mumbai and Bangalore are specifying these platforms for daily-use durability. The shift is compressing replacement cycles for economy-tier products while extending premium product lifespans.
Bureau of Energy Efficiency star-labeling standards are tightening minimum efficiency thresholds for induction cooktops and refrigerators. Manufacturers must redesign coil configurations and insulation systems to qualify for retail shelf placement. Maharashtra retailers report that star ratings now dominate consumer comparison behavior ahead of brand preference.
Direct-to-installer channel models are emerging alongside traditional distributor networks as modular kitchen contractors consolidate purchase authority. These contractors specify appliance packages for new residential towers in Bangalore and Pune, bypassing retail markup structures. The pattern concentrates volume with fewer decision-makers and compresses price negotiation windows for suppliers.
India Kitchen Appliances Market Segmentation
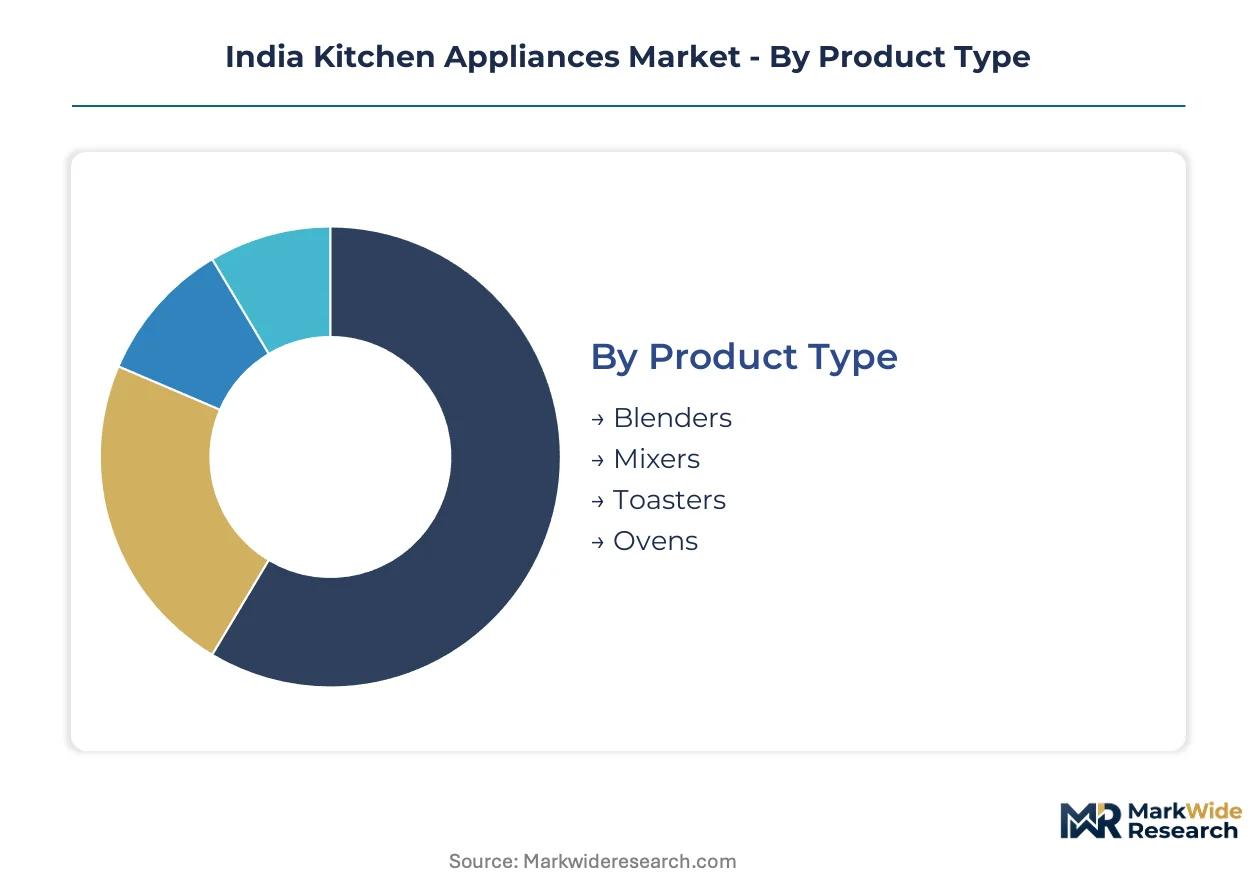
Kitchen appliance demand across India fragments along cooking modality, user environment, and energy source. Each segment carries distinct margin profiles and regulatory exposure that shape manufacturer portfolio priorities.
Product Type:
Domestic production clusters in Maharashtra and Gujarat supply blenders and mixers to nationwide retail networks. Toaster and oven assemblies draw more heavily on imported heating elements and control modules.
- Blenders:Stainless-steel jar assemblies with 500W to 1000W universal motors serve daily grinding operations in South Indian households. Demand concentrates in Tamil Nadu and Karnataka where wet-grinding for idli-dosa batter remains non-negotiable. BIS certification for blade safety and jar pressure resistance filters out unorganized competitors.
- Mixers:Multi-jar configurations with interlocking safety lids dominate urban replacement cycles in Mumbai and Delhi. Maharashtra retailers report that modular kitchen contractors now specify built-in mixer-grinder recesses in new residential towers, shifting purchase authority from end-users to installers.
- Toasters:Pop-up and conveyor variants rated 800W to 1500W serve breakfast-service operations in institutional canteens and quick-service restaurants.
- Ovens:Convection and microwave platforms face compressed margins from Korean and Chinese import competition in the large-capacity segment.
Blenders command the established base. The steepest expansion runs through mixers as modular kitchen penetration deepens.
End User:
Volume scales inversely with margin across user categories. Residential purchases drive unit economics through replacement cycles, while commercial and institutional buyers extract price concessions through centralized procurement.
- Residential:Urban households in Bangalore and Pune specify inverter-motor platforms for noise reduction and thermal protection. Star-labeling compliance from the Bureau of Energy Efficiency now dominates retail comparison behavior ahead of brand preference in Maharashtra showrooms.
- Commercial:Cloud kitchen operators in Mumbai and Hyderabad demand high-duty-cycle induction arrays with 8-hour continuous ratings. Equipment financing from non-banking financial companies enables rapid scaling for delivery-only restaurant chains.
- Institutional:School and hospital canteens in Gujarat prioritize NSF-equivalent food-contact certification and stainless-steel chassis durability for sanitization protocols.
- Catering:Event-service operators in Delhi NCR favor portable gas-powered equipment for outdoor deployment where electrical infrastructure is unreliable.
Residential claims the volume base. Commercial is climbing the fastest as cloud kitchen deployment accelerates.
Technology:
Energy source selection tracks state-level electricity tariff reform and LPG subsidy persistence. Urban coastal markets favor electric platforms, while interior districts retain gas dependency.
- Electric:Universal motor platforms in mixer-grinders and coil-based heating in toasters face efficiency mandates from the Bureau of Energy Efficiency. Star-labeling thresholds are tightening insulation and controller specifications.
- Gas:LPG-powered cooktops retain cost advantage in rural belts of Uttar Pradesh and Bihar where cylinder subsidies persist. BIS safety mandates for hose connectors and flame-failure devices are elevating product standards.
- Induction:Glass-ceramic surface technology with copper coil configurations is displacing gas in Mumbai and Bangalore apartments. Maharashtra electricity tariff reforms have compressed the total cost of ownership crossover point against subsidized LPG.
- Solar:Photovoltaic-powered DC appliances serve off-grid institutional kitchens in Rajasthan and Gujarat solar parks. Deployment remains constrained by battery storage costs and inverter reliability.
Electric retains the installed base. Induction is gaining share fastest as urban households abandon cylinder logistics.
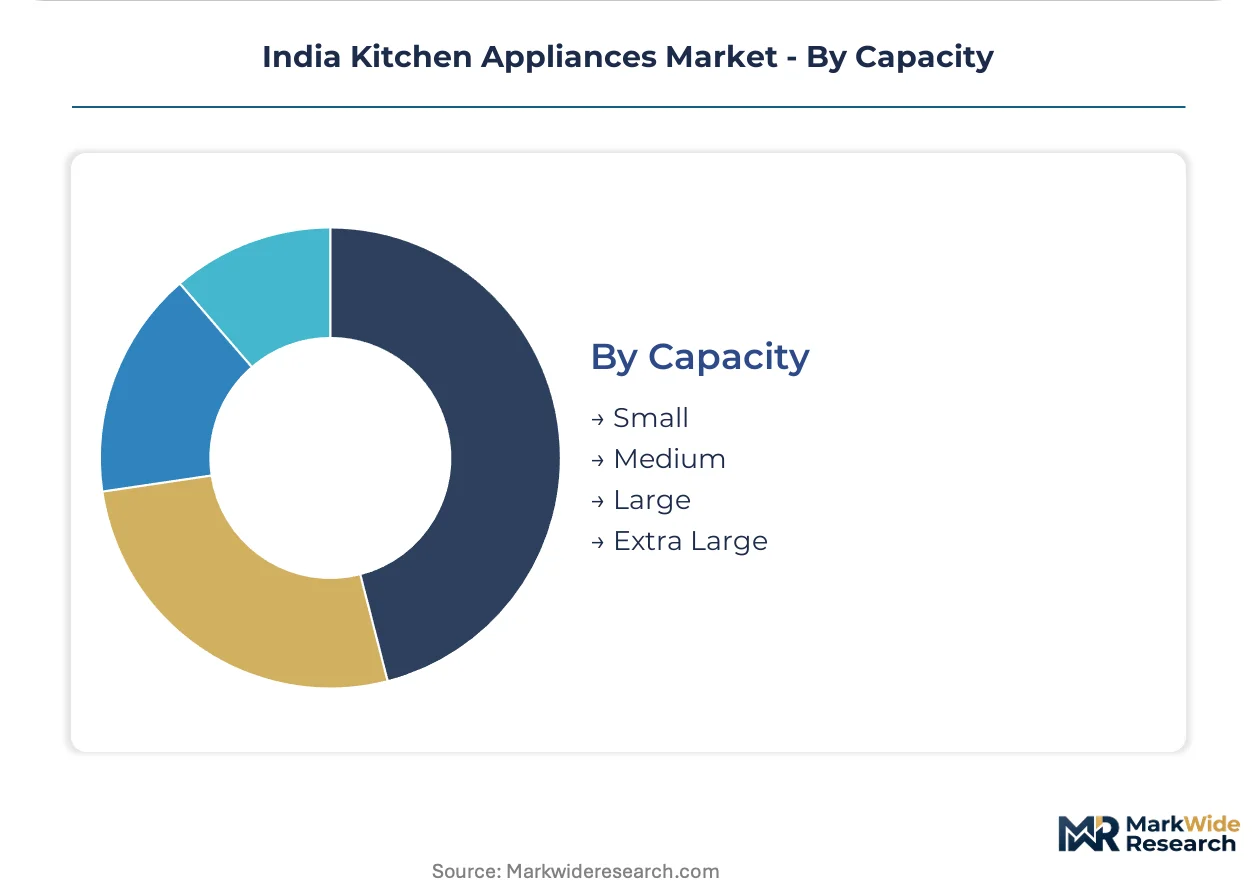
Capacity:
Size tiering correlates with household composition and commercial throughput requirements. Small and medium segments serve nuclear families, while large and extra-large platforms target food-service volume.
- Small:Single-jar mixer-grinders and 20-liter ovens serve one- and two-person households in Mumbai micro-apartments. Space constraints in older Bangalore residential stock favor compact footprints.
- Medium:Three-jar mixer configurations and 30-liter convection ovens dominate replacement demand in Pune and Ahmedabad nuclear families. This tier captures the deepest retail distribution in Tier-2 towns.
- Large:500W to 1000W blenders and 60-liter ovens serve joint-family households in Gujarat and small restaurant operations.
- Extra Large:Industrial-grade mixers and rack ovens target cloud kitchen central commissaries and institutional catering contracts in Delhi NCR and Hyderabad.
Medium capacity holds the volume core. Extra Large is expanding most quickly as centralized food production consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's kitchen appliances sector runs a modest trade surplus in finished goods while importing critical components like refrigeration compressors and induction coil assemblies. The domestic market absorbs nearly all production, with negligible export volumes. Regional demand patterns track electrification rates, LPG subsidy regimes, and modular kitchen penetration across state boundaries.
Maharashtra
Mumbai and Pune residential towers specify built-in induction arrays and inverter-motor mixer-grinders as standard fitments. BIS electrical safety certification mandates filter out unorganized suppliers from retail channels. The Thane-Aurangabad industrial corridor hosts assembly plants serving western India distribution networks.
Gujarat
Ahmedabad and Surat register the deepest modular kitchen penetration outside Maharashtra, driving specification-led procurement through contractor channels. The state's electricity tariff reforms have compressed total cost of ownership for high-wattage appliances versus subsidized LPG. Gandhinagar appliance clusters benefit from proximity to Mundra port for component imports.
Karnataka
Bangalore's apartment stock constrains kitchen footprints, favoring compact induction cooktops and multi-function mixer configurations. Bureau of Energy Efficiency star-labeling compliance dominates retail comparison behavior ahead of brand preference in Bengaluru showrooms. The Whitefield-Electronic City corridor concentrates cloud kitchen operations demanding high-duty-cycle equipment.
Tamil Nadu
Chennai and Coimbatore households sustain universal wet-grinding demand for idli-dosa batter, anchoring blender volume tiers. CDSCO-equivalent food-contact safety standards shape institutional procurement for school and hospital canteens. Sriperumbudur assembly clusters serve southern India replacement cycles.
Delhi-NCR
Gurgaon and Noida cloud kitchen operators drive commercial-grade induction array demand through equipment financing from non-banking financial companies. The region's air quality regulations accelerate electric cooking adoption in food-service segments. Faridabad manufacturing units supply northern India distribution infrastructure.
India Kitchen Appliances Market Competitive Environment
Concentration sits with diversified electrical goods conglomerates that leverage existing distribution infrastructure into kitchen-specific categories. The vendor base stratifies across three tiers: national brands with BIS-certified manufacturing, regional assemblers importing core components, and unorganized local fabricators. Two strategic archetypes dominate—heritage pressure-cooker manufacturers extending into countertop electric appliances, and wiring device specialists diversifying into induction platforms. Competitive moves center on distribution depth expansion into Tier-2 towns and backward integration into motor and controller assemblies.
Within the heritage-transition archetype, TTK Prestige Ltd. and Bajaj Electricals Ltd. occupy positions exemplifying stovetop-to-countertop portfolio extension. Havells India Ltd. sits within the electrical-specialist tier, representing wiring-device origin diversification into cooking platforms. These three companies anchor the organized sector's competitive structure, with each exemplifying distinct entry paths into kitchen appliance categories.
| Leading Market Players |
|---|
| Whirlpool of India |
| Havells India Ltd. |
| TTK Prestige Ltd. |
| Electrolux India |
| Philips Domestic Appliances India |
| Samsung India Electronics |
| Bajaj Electricals Ltd. |
| IFB Appliances Ltd. |
| LG Electronics India |
| Others |
Value Chain & Pricing Dynamics
BIS electrical safety certification gates both supplier qualification and price differentiation simultaneously, compressing unorganized competitors into economy tiers while rewarding certified manufacturers with premium positioning. Maharashtra and Gujarat buyers face tiered pricing structures where star-labeling compliance and inverter-motor specifications command measurable shelf price premiums over basic universal motor alternatives.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on BIS certification tier and Bureau of Energy Efficiency star ratings, with premium inverter-motor platforms separating from basic coil assemblies. Cost compression in mid-tier induction cooktops is intensifying because copper winding and cold-rolled steel input volatility compresses margin predictability. Cloud kitchen operators show least price sensitivity due to equipment financing availability, while Tier-3 residential replacement cycles exhibit highest sensitivity to absolute unit cost.
Supply Chain Analysis
Inventory lead times for refrigeration compressors and induction coil assemblies stretch procurement cycles, exposing assemblers to currency fluctuation and shipping disruption risks. Manufacturing concentrates in China, South Korea, and domestic Maharashtra-Gujarat clusters. Raw material dependencies center on copper motor windings, cold-rolled steel chassis, and imported controller modules. Single-source vulnerability for compressor imports represents the dominant structural risk. Distribution runs through modular kitchen contractors consolidating purchase authority alongside traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified induction coil repair technicians and inverter motor diagnostics specialists remain scarce across vocational training pipelines, constraining aftermarket service expansion and warranty cost management for scaling manufacturers.
For Market Incumbents: Secure backward integration into motor and controller assemblies to reduce import dependency exposure. Deepen certification investment ahead of tightening BIS timelines to filter emerging competitors. Channel control through direct-to-installer relationships with modular kitchen contractors defends against price erosion from distributor markup compression. For New Entrants and Emerging Players: Aftermarket service networks in Tier-2 towns represent the most penetrable white-space where incumbents under-serve. Cloud kitchen equipment financing partnerships offer a specific go-to-market angle bypassing retail channel establishment costs. Target Uttar Pradesh and Madhya Pradesh distribution infrastructure gaps before organized players consolidate shelf space. For Investors and Strategic Acquirers: PLI scheme component localization milestones reshape the acquisition landscape toward motor and controller suppliers establishing captive plants. Long-term viability favors vertically integrated assemblers with in-house BIS compliance teams and backward integration depth. The signal to monitor is state-level electricity tariff reform acceleration indicating induction adoption inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Assemblies | Reduces compressor import dependency and currency exposure for induction platform manufacturers. |
| Direct-to-Installer Channel Development | Bypasses retail markup structures where modular kitchen contractors consolidate purchase authority. |
| BIS Certification Pre-Investment | Accelerates product launch timelines ahead of laboratory testing backlogs filtering competitors. |
| Cloud Kitchen Equipment Financing Partnerships | Enables rapid scaling for delivery-only restaurant chains through non-banking financial company tie-ups. |
| Tier-2 Town Distribution Infrastructure Buildout | Captures first-mover advantages in Uttar Pradesh and Madhya Pradesh before organized consolidation. |
Study Parameters
The analysis maps induction cooktops, mixer-grinders, blenders, and refrigeration platforms, each validated through appliance design engineers, modular kitchen contractors, BIS certification specialists, and aftermarket service technicians. Primary interviews with these stakeholders combined with secondary validation from Bureau of Energy Efficiency star-labeling databases, BIS certification registries, customs import records, and PLI scheme disclosure filings. Bottom-up unit economics triangulated against top-down market sizing across the projection horizon.
Consistency checks validated volume and value outputs against external benchmarks including electricity tariff reform trajectories and LPG subsidy persistence patterns. Segmentation dimensions modeled encompass product type, end-user category, technology platform, and capacity tier alongside state-level regulatory cluster differentiation. CAGRs derived from installed base replacement cycles and new household formation rates. Industry-specific inputs include induction coil efficiency improvement curves and cloud kitchen deployment velocity.
Forecasts assume regulatory continuity in BIS electrical safety mandates and Bureau of Energy Efficiency star-labeling regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Global Portable Blenders Market
Kitchen Appliances
Smart Kitchen Appliances Market
Kitchen Appliances
Asia Pacific Induction Hobs Market
Kitchen Appliances
Commercial Tabletop Kitchen Products Market
Kitchen Appliances
India Mixer Grinder Market
Kitchen Appliances
Global Smart Ovens Market
Kitchen Appliances
Heavy Duty Mixer Grinder Market
Kitchen Appliances
Induction Hobs Market
Kitchen Appliances
Sandwich Maker Market
Kitchen Appliances
Asia-Pacific Air Fryers Market
Kitchen Appliances
Portable Sandwich Maker Market
Kitchen Appliances
Outdoor Kitchen Appliances Market
Kitchen Appliances
Cookware Accessories Market
Kitchen Appliances
Russia Household Electric Grill Market
Kitchen Appliances
Induction Stove Market
Kitchen Appliances
Smart Induction Cooktop Market