
 Single-Serve Coffee Containers Market | 2026-2036
Single-Serve Coffee Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Single-Serve Coffee Containers Market Analytics
REACH compliance is hardening the cost-of-entry calculus for new single-serve coffee container entrants, particularly around chemical safety disclosures for plastic and aluminum formats. Nestlé S.A. leverages its vertically integrated capsule supply chain to absorb these regulatory burdens without margin erosion. Keurig Dr Pepper, Inc. anchors its North American position through proprietary brewer-pod lock-in systems that competitors struggle to replicate. JDE Peet's N.V. navigates European sustainability mandates by accelerating paper-based pod development.
Single-serve coffee containers are individually portioned, sealed beverage delivery systems—typically 8–12 grams of ground coffee hermetically enclosed in plastic, aluminum, or compostable shells—designed for extraction under 15–19 bar pressure or gravity-drip mechanics in compatible brewing machines. The primary commercial purpose is to standardize portion control, reduce preparation time, and preserve aroma freshness in out-of-home and at-home environments. K-Cup formats dominate volume in North American households due to Keurig's installed brewer base, while Nespresso Capsule formats command premium positioning in European cafes and hotels through aluminum recyclability programs. Biodegradable materials represent the fastest-growing structural segment as EU member states implement extended producer responsibility schemes that penalize non-compostable packaging.
The EPA oversees municipal waste stream impacts of plastic pods in the United States, while the EU Green Deal and national packaging laws across France, Germany, and Italy mandate minimum recycled content thresholds and end-of-life collection infrastructure. These frameworks reshape demand toward aluminum and biodegradable formats while restricting conventional polypropylene access in regulated channels. Stakeholders must monitor diverging transatlantic compliance timelines to avoid stranded inventory in cross-border distribution networks.
Market Dynamics
EU Green Deal packaging waste directives are compressing demand timelines for biodegradable single-serve formats while aluminum recyclability programs capture stranded plastic demand in regulated channels.
Growth Catalysts
- Office breakroom procurement:Employers across Germany and France are upgrading beverage amenities to attract hybrid workers back to physical locations.
- REACH compliance maturation:Chemical safety disclosure standardization is filtering out subscale competitors and consolidating shelf access for compliant formats.
- Aluminum shell technology:Hermetic sealing improvements at 15–19 bar pressure ratings are extending aroma preservation windows for premium out-of-home channels.
Market Restraints
- Biodegradable resin input costs:Polylactic acid and starch-based polymer feedstock volatility constrains margin expansion for compostable pod specialists.
- German supply concentration:Per-capita consumption leadership in this market creates demand vulnerability to regional economic contraction or sustainability backlash.
- Gravity-drip mechanical limitation:Non-pressurized brewing systems fail to extract full flavor profiles from lighter roasts, restricting format compatibility.
Strategic Opportunities
- Italian hospitality underpenetration:Traditional espresso culture resistance presents conversion potential through aluminum capsule recyclability messaging.
- Extended producer responsibility tailwinds:France's mandatory compostable packaging thresholds for 2026 create first-mover certification advantages.
- Paper-based pod convergence:Cellulose barrier technology combined with water-soluble sealing adhesives is opening heat-sealed compostable architectures.
Industry Challenges
- Multilayer barrier certification timelines:EFSA novel food contact material approvals for biodegradable laminates extend product launch cycles by 18–24 months.
- Brewer-pod interoperability IP:Proprietary extraction system patents create licensing complexity for universal format entrants.
- Legacy polypropylene reconfiguration:Existing thermoforming lines require substantial retooling capex to transition toward compostable material flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single-Serve Coffee Containers Market |
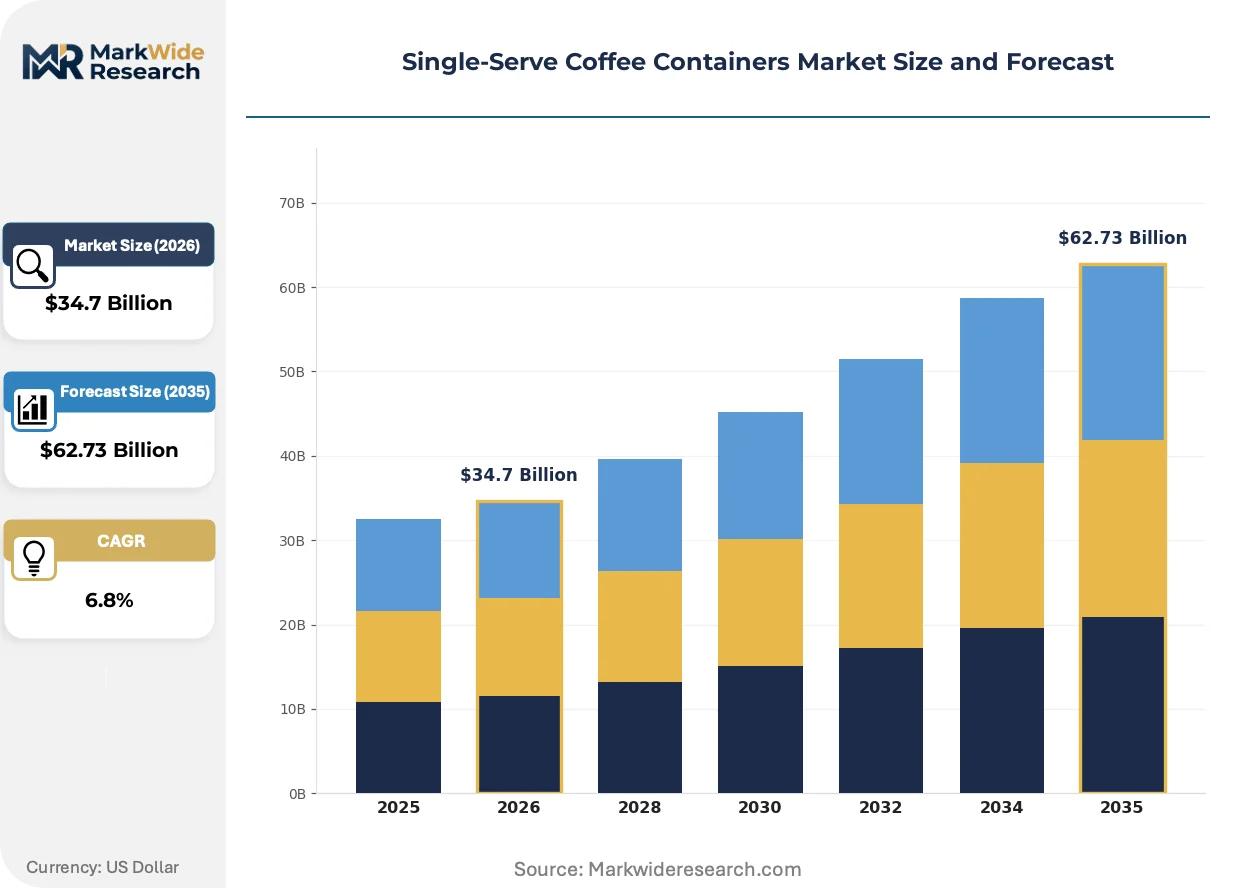
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $62.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: K-Cup, Nespresso Capsule, Dolce Gusto Pod, T-Disc Material: Plastic, Aluminum, Paper, Biodegradable End User: Households, Offices, Hotels, Cafes Flavor Profile: Dark Roast, Medium Roast, Flavored, Decaf |
| Companies Covered | Nestlé S.A., Keurig Dr Pepper, Inc., JDE Peet's N.V., Starbucks Corporation, The Kraft Heinz Company, The J.M. Smucker Company, illycaffè S.p.A., Luigi Lavazza S.p.A., Pod Pack International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single-Serve Coffee Containers Market Evolving Landscape
Material science breakthroughs and regulatory compliance automation are compressing the viable technology set for single-serve containers while reshaping competitive entry costs.
Compostable multilayer barrier films are unifying oxygen and moisture protection in plant-based shells. German roasters are piloting these formats for Q4 2025 retail launches. This unification is collapsing the performance gap between petroleum-based and biodegradable alternatives in regulated European markets.
REACH authorization requirements for plasticizers and colorants are hardening chemical safety documentation burdens. Manufacturers must now submit full substance dossiers for each laminate component. Aluminum capsule producers in Italy and France are capturing displaced polypropylene demand as brands preempt compliance uncertainty.
Direct-to-office subscription models are replacing traditional foodservice distribution for breakroom coffee procurement. Channel disintermediation is compressing distributor margins while rewarding brewer manufacturers with captive pod revenue streams. This shift is most visible in French corporate campuses and Dutch co-working clusters.
Single-Serve Coffee Containers Market Segmentation
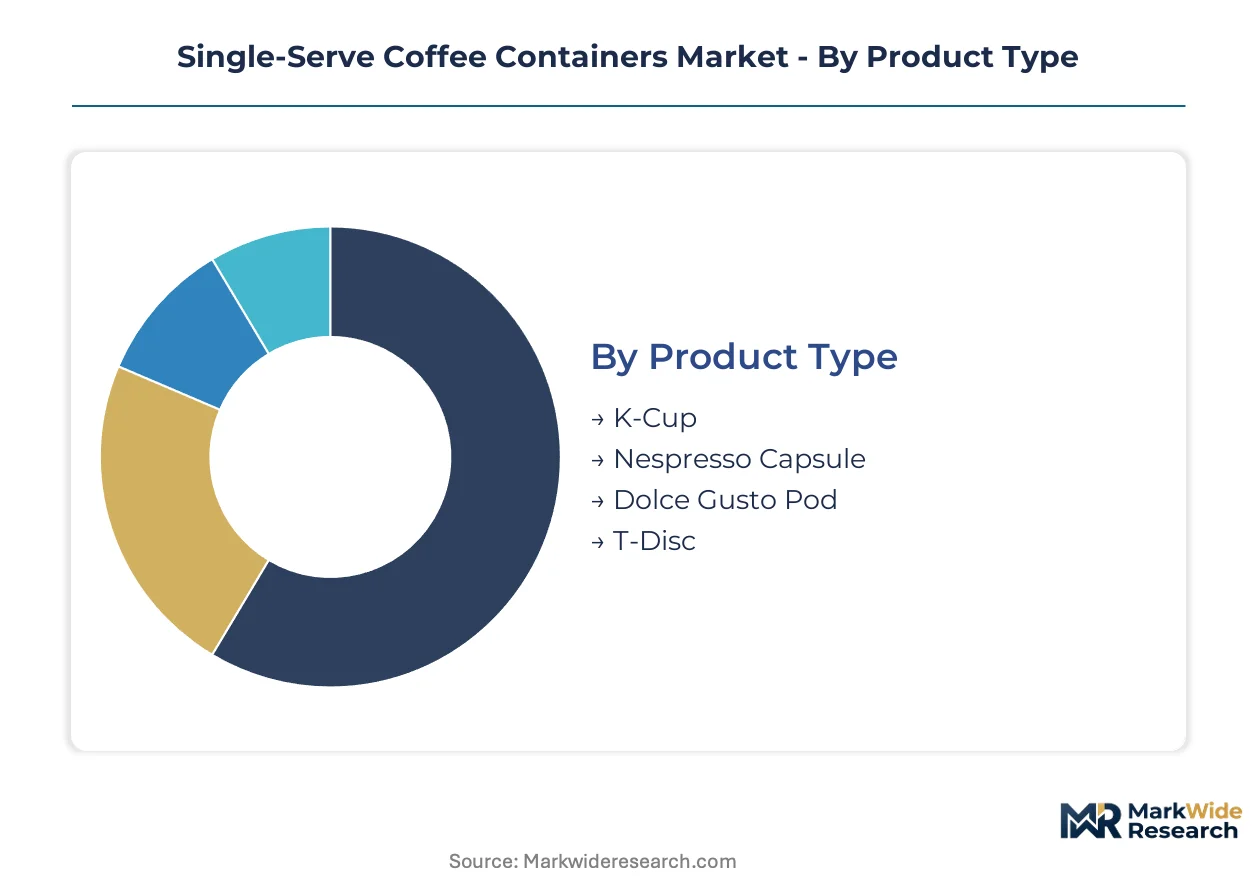
Segmentation in single-serve coffee containers reveals how brewing system compatibility, material compliance costs, and consumption occasion specificity fragment addressable demand. Manufacturers must align format specifications with regional regulatory timelines and installed brewer bases to avoid stranded capacity.
Product Type:
Customization-to-standardization tension runs deepest here—proprietary lock-in systems dominate volume while open-format alternatives fight for shelf space.
- K-Cup:Polypropylene or biodegradable shells with puncturable foil lids, engineered for gravity-drip extraction at low pressure. Demand concentrates in US households where Keurig's installed brewer base exceeds competing systems. Office breakroom procurement in Germany and France is accelerating K-Cup compatible format adoption despite Nespresso's premium positioning.
- Nespresso Capsule:Aluminum cylinders with hermetic crimped seals, designed for 19-bar centrifugal or pump-driven extraction. European cafes and hotels in Germany, France, and Italy anchor demand, driven by aluminum recyclability programs that preempt EU Green Deal compliance uncertainty.
- Dolce Gusto Pod:Dome-shaped multilayer plastic capsules supporting milk-based beverage preparation. Latin American and Southern European households represent primary adoption clusters.
- T-Disc:Tassimo-branded barcode-enabled plastic discs with integrated brewing parameters. German retail channels maintain residual distribution despite system decline.
Most installed capacity flows through K-Cup compatible formats. Expansion is steepest in Nespresso Capsule as aluminum recyclability captures regulatory-driven format switching.
Material:
Cost tier stratification separates commodity petroleum-based inputs from premium biodegradable alternatives facing volatile feedstock economics.
- Plastic:Polypropylene and polystyrene thermoformed shells dominate legacy production lines. REACH authorization requirements for plasticizers are compressing margin structures and extending compliance timelines for new entrants.
- Aluminum:Rolled and drawn alloy cylinders with polymer barrier linings. Demand is concentrating in Italian and French hospitality channels where EFSA-compliant recyclability messaging drives procurement decisions.
- Paper:Cellulose fiber shells with water-based barrier coatings. German roasters are piloting heat-sealed architectures for Q4 retail launches.
- Biodegradable:Polylactic acid and starch-based polymer laminates certified for industrial composting. France's mandatory compostable packaging thresholds are accelerating certification urgency.
Volume leadership remains with plastic. The steepest expansion trajectory belongs to biodegradable formats as extended producer responsibility schemes penalize conventional packaging.
End User:
Application-specific requirements for portion consistency, preparation speed, and waste handling infrastructure reshape format specifications across consumption occasions.
- Households:Convenience-oriented single-serve adoption with sensitivity to brewer acquisition cost and pod price per unit. US and German markets show highest per-capita penetration.
- Offices:Breakroom procurement emphasizing variety availability and minimal cleaning requirements. French corporate campuses and Dutch co-working clusters are displacing traditional foodservice distribution.
- Hotels:In-room amenity standardization with premium positioning through aluminum capsule formats. European boutique properties lead sustainable packaging requests.
- Cafes:Back-of-house efficiency and flavor consistency for non-espresso beverage preparation. Italian traditional espresso culture resistance limits conversion potential.
Households absorb the majority of unit volume. Offices are gaining share fastest as hybrid work policies drive employer amenity investment.
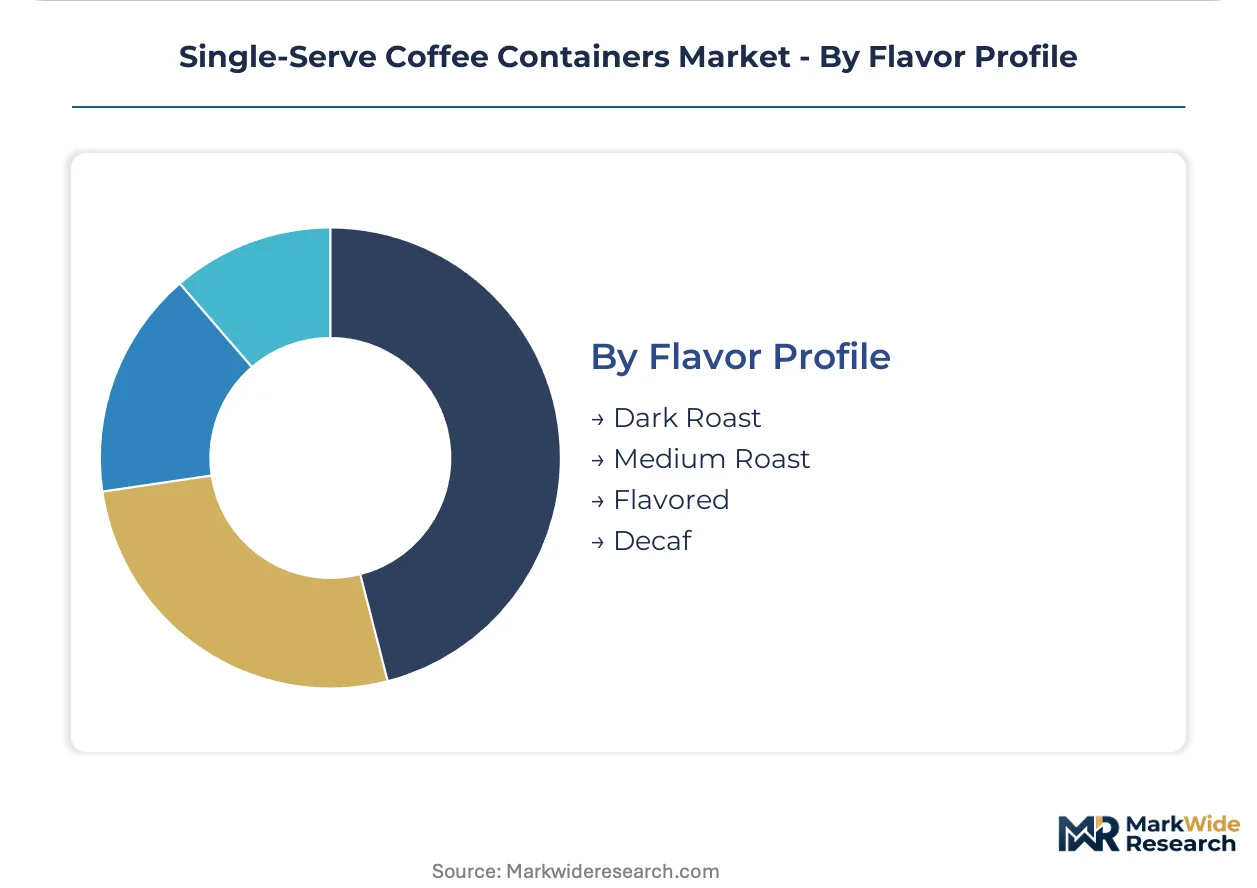
Flavor Profile:
Maturity gradients separate established roast categories from niche segments requiring specialized extraction parameter calibration.
- Dark Roast:High-temperature roasted profiles with reduced acidity, compatible with lower-pressure brewing systems. Standard offering across all format types.
- Medium Roast:Balanced acidity and body profiles requiring precise extraction temperature control. German and US households show strongest preference concentration.
- Flavored:Vanilla, hazelnut, and seasonal variants with added aromatic compounds. Younger demographic skew in North American office environments.
- Decaf:Solvent or water-processed caffeine reduction with flavor preservation challenges. Health-conscious segments in France and Switzerland sustain niche demand.
Dark and medium roasts command the majority of production allocation. Flavored varieties are climbing the fastest as format manufacturers expand variety portfolios to defend brewer ecosystem lock-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barista talent pools and coffee roasting expertise anchor geographic demand concentration for single-serve formats. Employer amenity investment and regulatory compliance timelines reshape procurement patterns across developed markets.
United States
Office breakroom procurement drives employer-sponsored single-serve adoption as hybrid return-to-office policies expand. EPA waste stream oversight pressures municipal composting infrastructure development. Seattle and San Francisco corporate campuses displace traditional foodservice distributors with direct-to-office subscription models.
Germany
Per-capita coffee pod consumption leadership sustains premium aluminum capsule demand in hospitality channels. EU Green Deal packaging waste directives accelerate biodegradable format certification requirements. Hamburg and Munich roaster clusters pilot compostable multilayer barrier films for Q4 retail launches.
France
Mandatory compostable packaging thresholds for 2026 create first-mover certification urgency among format manufacturers. Extended producer responsibility schemes penalize conventional polypropylene in regulated channels. Paris corporate campuses and Lyon co-working clusters lead breakroom procurement channel disintermediation.
Italy
Traditional espresso culture resistance limits single-serve conversion potential despite aluminum recyclability messaging. EFSA novel food contact material approvals extend biodegradable laminate launch cycles. Milan and Turin hospitality channels maintain capsule demand concentration through premium positioning.
Netherlands
Sustainability-forward procurement policies in corporate environments accelerate compostable pod adoption. REACH chemical safety disclosure standardization filters subscale competitors from shelf access. Amsterdam and Rotterdam co-working clusters represent dense demand nodes for variety-focused breakroom systems.
Single-Serve Coffee Containers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Nestlé and JDE Peet's leverage beverage portfolio breadth to absorb regulatory compliance costs, while Keurig anchors installed brewer ecosystems against format fragmentation. Three archetypes dominate: vertically integrated roaster-packagers, licensed private-label converters, and proprietary system licensors. Capacity reconfiguration toward biodegradable materials and strategic patent licensing agreements constitute the primary competitive moves.
Among European roaster-packagers, Nestlé S.A. and JDE Peet's N.V. exemplify diversified conglomerate positioning through captive supply chain control and multi-format portfolio breadth. Keurig Dr Pepper, Inc. represents the proprietary system licensor archetype, anchoring North American demand through brewer-pod lock-in architecture. These three entities occupy positions that illustrate the tension between regulatory absorption capacity and ecosystem control strategies.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Keurig Dr Pepper, Inc. |
| JDE Peet's N.V. |
| Starbucks Corporation |
| The Kraft Heinz Company |
| The J.M. Smucker Company |
| illycaffè S.p.A. |
| Luigi Lavazza S.p.A. |
| Pod Pack International |
| Others |
Value Network & Pricing Analysis
Aluminum-to-biodegradable material cost divergence separates premium hospitality channels from commodity household formats, with EU Green Deal compliance timelines forcing parallel supply chain reconfigurations and tiered procurement strategies across German roasters and North American distributors.
Pricing Analysis
Bundled brewer-pod subscription models dominate enterprise procurement, while unbundled transactional pod sales persist in retail. Three-tier pricing structure across premium aluminum, standard plastic, and economy private-label tiers reflects certification grade and recyclability program participation. Cost compression in biodegradable resin inputs is intensifying because polylactic acid feedstock volatility constrains margin expansion. Office breakroom buyers show lowest price sensitivity due to employer-sponsored amenity budgets, while household consumers in Germany and France exhibit highest sensitivity to per-unit pod costs.
Supply Chain Analysis
Dual-sourcing mandates from French and German retail buyers require multi-supplier qualification for both aluminum alloy and polylactic acid resin streams. Manufacturing concentrates in Germany, Italy, and the United States for aluminum drawing and thermoforming operations. Raw material dependencies center on bauxite-derived aluminum sheet, corn-based polylactic acid pellets, and barrier-grade polymer films. Single-source vulnerability in compostable multilayer barrier certification creates supply risk as EFSA approval timelines extend launch cycles. Distribution runs through direct-to-office subscription platforms and traditional foodservice distributors in parallel channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in biodegradable format transitions, where aluminum recyclability premiums and compostable certification first-mover positions capture regulatory-driven demand shifts.
For Market Incumbents: To counter proprietary brewer-pod lock-in erosion, Nestlé and JDE Peet's should deepen backward integration into compostable multilayer barrier film production and secure EFSA novel food contact approvals ahead of France's 2026 mandatory thresholds. Channel control through direct-to-office subscription platforms offers defensive positioning against distributor disintermediation. For New Entrants and Emerging Players: Paper-based pod technology with cellulose barrier coatings offers entry wedge into German Q4 retail pilot programs and Dutch co-working clusters where sustainability procurement policies override brand loyalty. Italian hospitality channels present white-space opportunity through aluminum capsule recyclability messaging that preempts traditional espresso culture resistance. Go-to-market execution should anchor on certified compostable formats with heat-sealed architectures. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance burdens filter subscale competitors from shelf access. Long-term viability favors vertically integrated roaster-packagers with captive supply chains and multi-format portfolios. Acquisition targets should demonstrate EFSA certification progress or established direct-to-office distribution infrastructure. The signal to watch is biodegradable resin input cost stabilization as industrial composting infrastructure scales.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Format Certification | EFSA novel food contact approvals unlock French and German regulated channel access ahead of compliance deadlines. |
| Direct-to-Office Subscription Launch | Channel disintermediation captures employer amenity budgets in Paris and Amsterdam corporate campuses. |
| Aluminum Recyclability Program Expansion | Italian hospitality penetration leverages EU Green Deal messaging to convert traditional espresso culture resistance. |
| Backward Integration into Barrier Films | In-house compostable multilayer production absorbs polylactic acid feedstock volatility and compresses certification timelines. |
| Brewer-Pod Interoperability Licensing | Patent cross-licensing agreements reduce IP friction for universal format entrants targeting Keurig-compatible demand. |
Research Methodology
Coverage spans Germany, France, Italy, the United States, and the Netherlands, with primary inputs from each market combining interviews with roaster-packager supply chain directors, EU regulatory affairs specialists, office procurement managers at French corporate campuses, and biodegradable material R&D leads. Secondary validation draws from EFSA novel food contact material filings, EU Green Deal packaging waste directive texts, EPA municipal waste stream reports, and customs trade data for aluminum and polylactic acid imports. Bottom-up pod volume modeling triangulates against top-down market value estimates across material and end-user segments.
Rate-of-change decomposition separates installed brewer base expansion, per-capita consumption intensity shifts, and format switching between plastic, aluminum, and biodegradable materials. The analytical framework models product type, material compliance tier, end-user occasion, and regional regulatory cluster across the projection horizon. CAGRs derive from segment-level volume trajectories weighted by pricing tier mix, with specific inputs including REACH authorization timelines, extended producer responsibility scheme implementation schedules, and office breakroom procurement survey data.
The model holds under steady EU Green Deal enforcement and stable polylactic acid feedstock availability; deviation in EFSA certification acceleration or German economic contraction would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Coffee Bags Market
Coffee
Latin America Coffee Market
Coffee
United Arab Emirates Coffee Roaster Market
Coffee
South America Coffee Market
Coffee
Raw Coffee Beans Market
Coffee
Green Coffee Market
Coffee
Cold Brew Coffee Pots Market
Coffee
Encapsulated Caffeine Market
Coffee
US Coffee Machine Market
Coffee
Espresso Powder Market
Coffee
Espresso Coffee Market
Coffee
Global Portable Coffee Makers Market
Coffee
Dairy-Free RTD Coffee Products Market
Coffee
Decaffeinated Coffee Market
Coffee
Single Origin Coffee Market
Coffee
Coffee Concentrate Market