
 North America Coffee Market | 2026-2036
North America Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
North America Coffee Market Outlook
Ready-to-drink beverage revenue is rewriting margin distribution across the North America coffee value chain, pulling profits from traditional roast-and-ground formats toward chilled single-serve formats. Starbucks Corporation leverages its coastal roasting infrastructure to dominate cold brew distribution. Keurig Dr Pepper Inc. anchors pod-system penetration in office and home channels through licensed brewing platforms. Dutch Bros. Coffee specializes in drive-through velocity, sustaining growth in suburban and interstate corridors where real estate costs favor small-footprint service models.
North America coffee comprises roasted, ground, or soluble preparations of Coffea arabica and Coffea canephora (robusta) beans, typically processed through drum or fluid-bed roasting to achieve specific moisture content and flavor development for hot or cold extraction. The primary commercial purpose spans home preparation, foodservice dispensing, and ready-to-drink manufacturing. Whole bean and cold brew segments command premium shelf positioning as consumers trade up toward origin-specific and convenience-oriented formats. Pod packaging sustains volume leadership in office and single-serve home applications where speed and consistency override cost sensitivity. Ground coffee occupies mature, price-competitive territory in mass retail.
FDA food labeling requirements, USDA organic certification standards, and Health Canada food safety regulations shape ingredient transparency, pesticide residue limits, and import documentation across the U.S.-Canada trade corridor. California's Proposition 65 warning mandates and Quebec's French-language labeling laws add state and provincial compliance layers that filter market access for smaller importers. Stakeholders must monitor how evolving single-use packaging restrictions in multiple jurisdictions reshape pod-format viability and drive investment in compostable or reusable alternatives.
Market Dynamics
Cold brew nitrogenation technology is compressing production timelines and redrawing capital allocation across roasting infrastructure, as coastal facilities retool for ambient-stable extraction rather than traditional heat-based processing.
Growth Catalysts
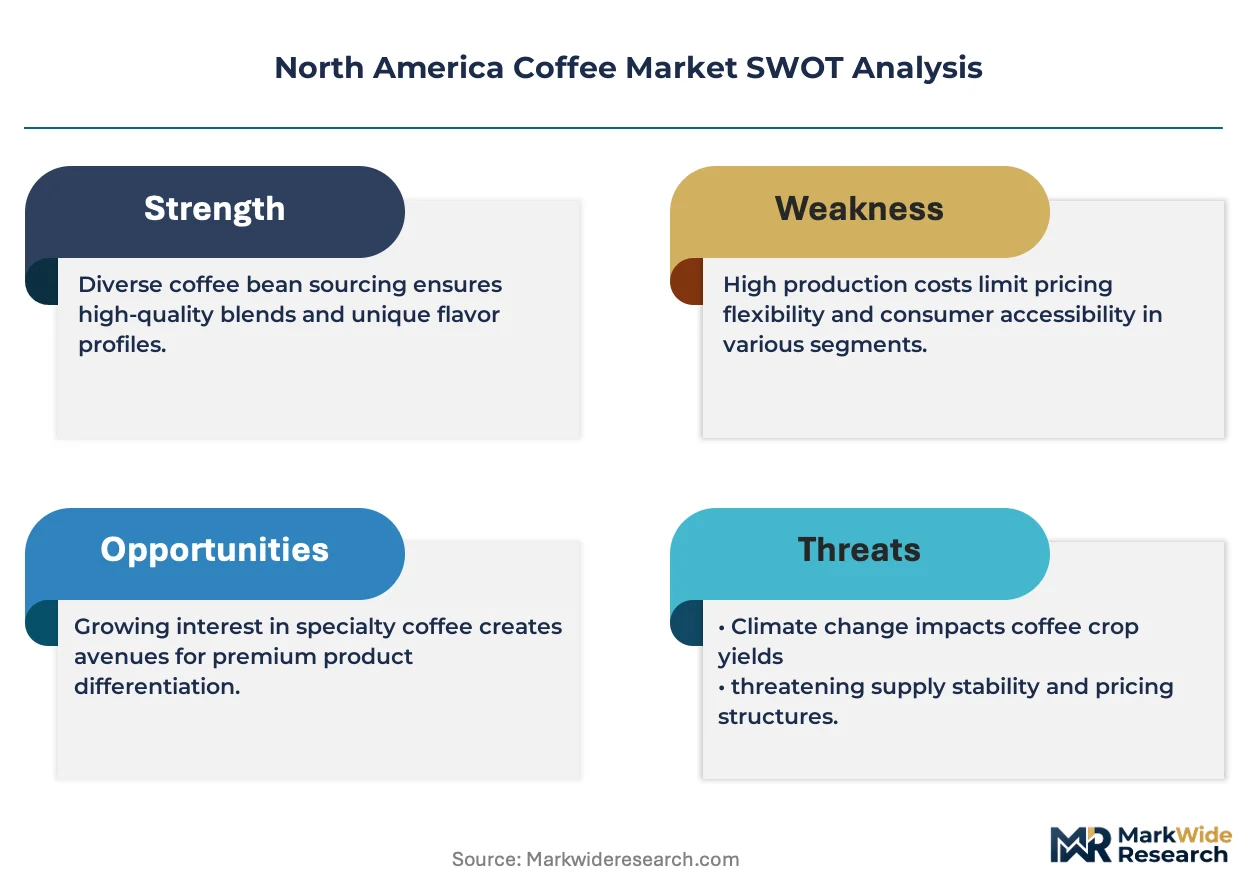
- California Proposition 65 enforcement:Warning label mandates for acrylamide exposure are accelerating clean-label roasting investments and third-party testing adoption among mid-size processors.
- Drive-through format expansion:Suburban interstate corridors in Texas and Arizona are absorbing new small-footprint outlets where real estate costs favor high-velocity service models over seated dining.
- Nitrogen flushing:Modified atmosphere packaging for cold brew is extending shelf stability without preservatives, opening convenience channel placement previously blocked by refrigeration requirements.
Market Restraints
- Arabica price volatility:Brazilian frost cycles and Colombian drought patterns are transmitting input cost spikes directly into roaster margin compression with limited hedging instruments available.
- Vietnamese robusta concentration:Soluble coffee manufacturing depends on single-origin sourcing that faces recurring logistics bottlenecks through Ho Chi Minh City port infrastructure.
- Pod-format plastic bans:Municipal single-use packaging restrictions in Vancouver, Seattle, and Portland are forcing immediate format transitions before compostable alternatives achieve cost parity.
Strategic Opportunities
- Quebec French-language labeling:Bilingual packaging compliance creates natural moats against US-only competitors in Canadian grocery channels where localization investment remains shallow.
- Office channel pod-system refresh:Hybrid work normalization has stalled but not reversed corporate coffee programs, creating upgrade windows for licensed brewing platforms with IoT consumption tracking.
- USDA Organic plus Fair Trade stacking:Dual certification commands shelf placement premiums in Pacific Coast metropolitan markets where origin transparency outweighs price sensitivity.
Industry Challenges
- Roast profile calibration talent:Fluid-bed and drum roasting automation requires technicians who bridge traditional cupping expertise with programmable logic controller operation, a skill intersection with shallow labor pools.
- Legacy ERP integration:Direct-to-consumer subscription platforms must reconcile with decades-old green coffee inventory systems that lack real-time traceability APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Coffee Market |
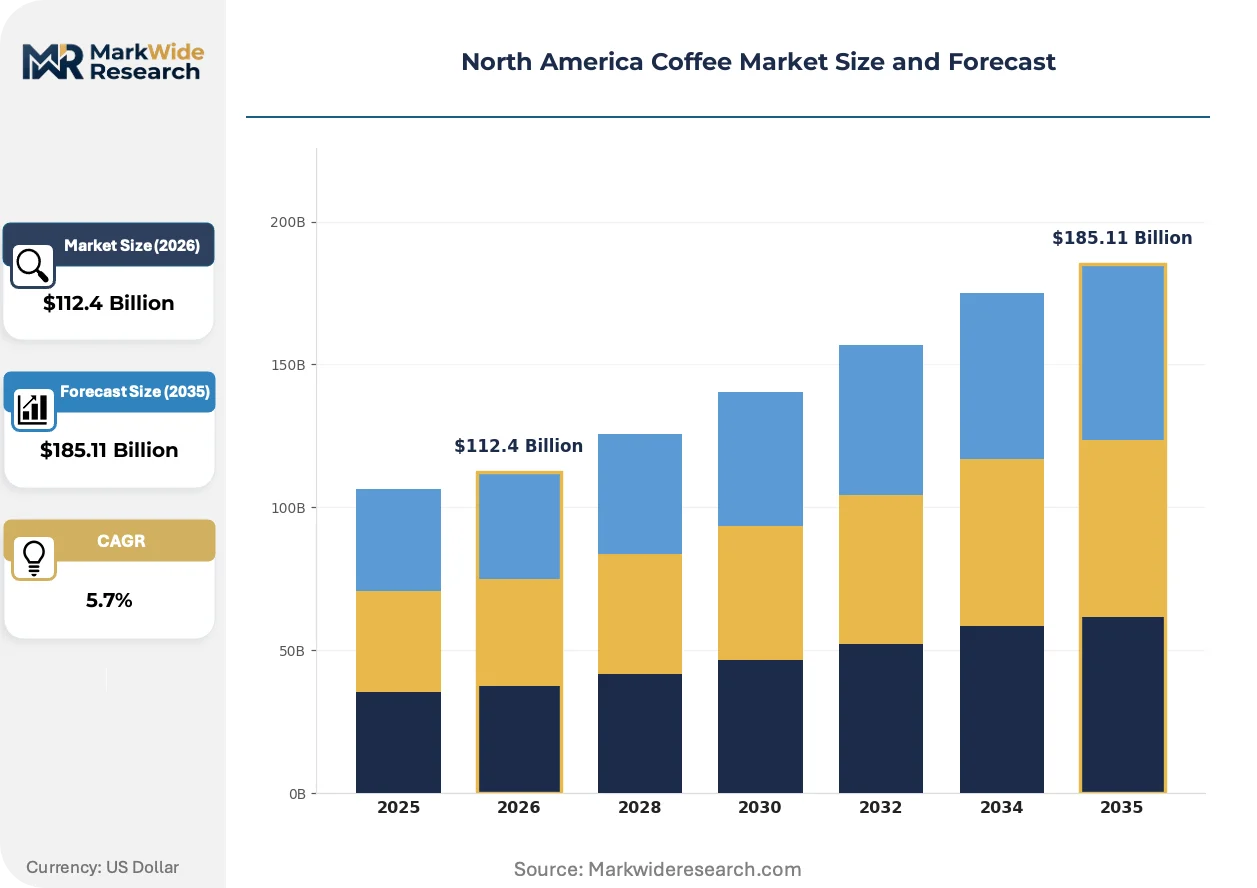
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $185.11 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Coffee, Instant Coffee, Whole Bean, Cold Brew Consumer Type: Home Users, Cafés, Restaurants, Office Roast Level: Light Roast, Medium Roast, Dark Roast, Espresso Packaging Type: Bags, Pods, Cans, Bottles |
| Companies Covered | Dunkin' Brands Group, McDonald's Corporation, Starbucks Corporation, Dutch Bros. Coffee, The Kraft Heinz Company, Keurig Dr Pepper Inc., Tim Hortons, Caribou Coffee, The J. M. Smucker Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Coffee Market Strategic Shifts
Extraction technology and packaging science are converging to collapse the distinction between cafe-quality and retail-ready coffee experiences, with implications for equipment manufacturers and roaster capital planning alike.
Cold brew nitrogen infusion systems are rendering obsolete the thermal pasteurization step that previously degraded volatile aromatic compounds. Third-wave roasters in Portland and Brooklyn are adopting ambient-stable formats at accelerating rates. The structural consequence is compressed distribution economics, enabling direct shipment to convenience stores without refrigerated logistics networks.
Health Canada's updated caffeine disclosure regulations for ready-to-drink beverages are mandating per-serving content labeling that exceeds US FDA baseline requirements. Cross-border processors face dual compliance burdens that favor domestic Canadian bottling investments. The Quebec market demonstrates strongest consumer response, with labeled products capturing preferential placement in provincial liquor board retail channels.
Subscription replenishment algorithms are replacing traditional wholesale ordering patterns among home brewers. Roasters deploying predictive shipping models based on consumption velocity data are displacing static auto-delivery schedules. This behavioral shift concentrates most visibly in Seattle and San Francisco metropolitan zones where smart home device penetration correlates with coffee subscription adoption rates.
North America Coffee Market Segmentation
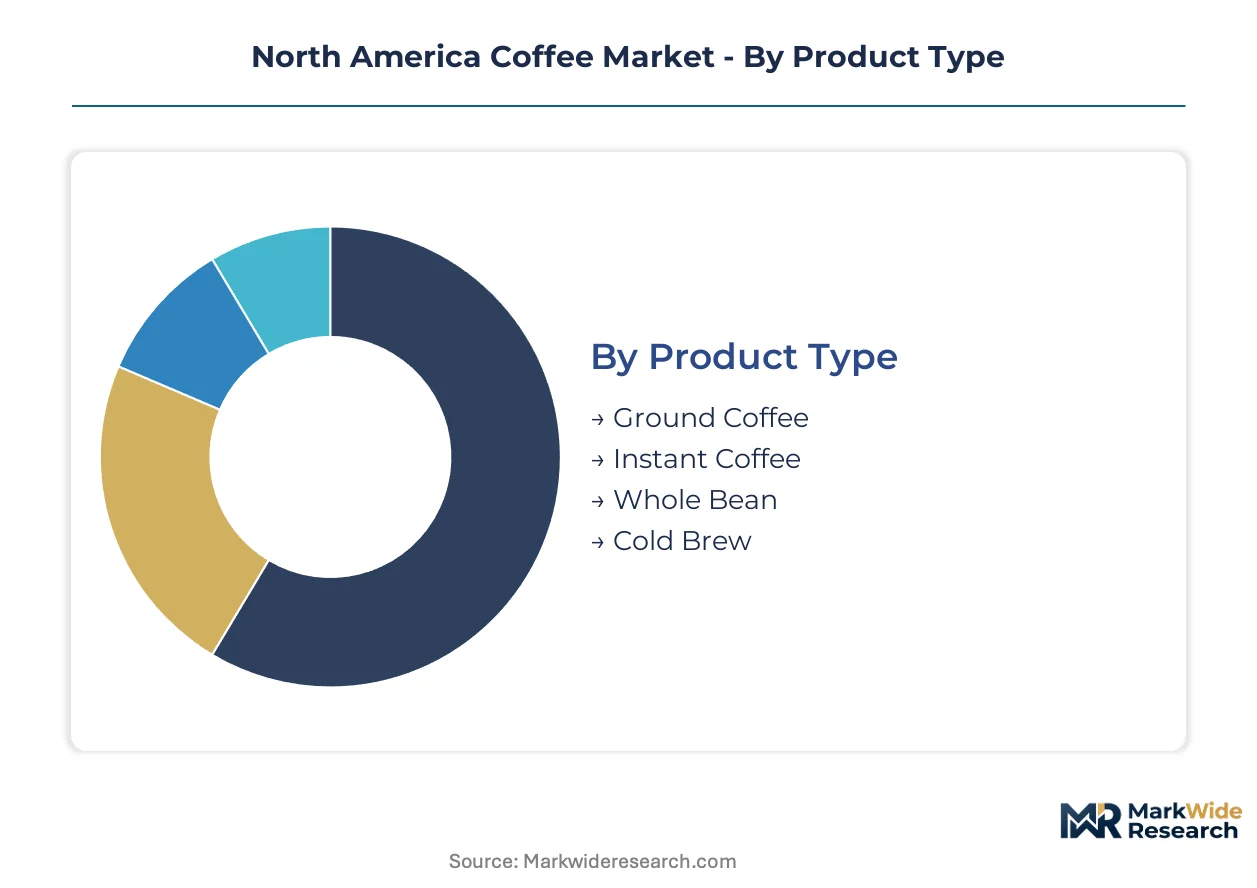
Segmentation in the North America coffee market determines capital allocation across roasting infrastructure, packaging lines, and distribution partnerships. Each dimension—product format, end-use channel, roast profile, and container type—carries distinct margin structures and regulatory exposure that shape competitive positioning.
Product Type:
After-sales service intensity varies sharply across product types, with equipment-dependent formats requiring ongoing technical support and replenishment systems.
- Ground Coffee:Pre-milled arabica or robusta blends packaged for immediate brewing through drip or French press methods. Demand concentrates in mass retail channels across the U.S. Midwest and Ontario suburbs where price sensitivity dominates purchase decisions and private-label competition compresses branded margins.
- Instant Coffee:Spray-dried or freeze-dried soluble granules reconstituted with hot water. Growth accelerates in Canadian remote communities and Alaska where logistical constraints favor shelf-stable formats over fresh bean logistics, though flavor limitations cap premium positioning.
- Whole Bean:Unmilled roasted coffee requiring consumer grinding equipment.
- Cold Brew:Ambient or refrigerated ready-to-drink extraction, often nitrogen-infused for texture.
Ground coffee holds the largest share; momentum sits with cold brew.
Consumer Type:
Cost tier stratification separates high-volume contract accounts from discretionary retail purchasers with divergent procurement cycles.
- Home Users:Individual consumers purchasing for residential preparation through retail or subscription channels. Pacific Coast metropolitan areas from Seattle to Vancouver demonstrate strongest subscription algorithm adoption, with smart home device correlation driving predictive replenishment models.
- Cafés:Independent and chain coffeehouses sourcing for on-premise espresso and manual brewing service. Concentration in Brooklyn and Portland sustains demand for single-origin traceability and small-batch roasting partnerships that command wholesale premiums.
- Restaurants:Foodservice operations integrating coffee into meal service.
- Office:Corporate and institutional brewing programs.
Home users dominate volume; cafés are climbing the fastest on per-unit value extraction.
Roast Level:
Application specificity drives roast selection, with extraction method compatibility determining technical specifications and flavor outcome.
- Light Roast:Short roasting cycles preserving origin-specific acidity and terroir characteristics. Third-wave roasters in Portland and San Francisco favor this profile for pour-over service, though narrow consumer familiarity outside coastal markets limits mass retail penetration.
- Medium Roast:Balanced development targeting broad palatability across brewing methods. Standard offering in U.S. grocery channels and Canadian mass retail, with Vermont and Quebec showing strongest regional preference for certified organic variants.
- Dark Roast:Extended roasting producing bold, bitter profiles with reduced origin distinction.
- Espresso:Specialized roast profiles optimized for high-pressure extraction equipment.
Medium roast commands shelf space leadership; light roast shows steepest expansion trajectory in premium channels.
Packaging Type:
Supply concentration in container manufacturing shapes format economics, with material cost volatility and regulatory pressure on single-use plastics redrawing competitive boundaries.
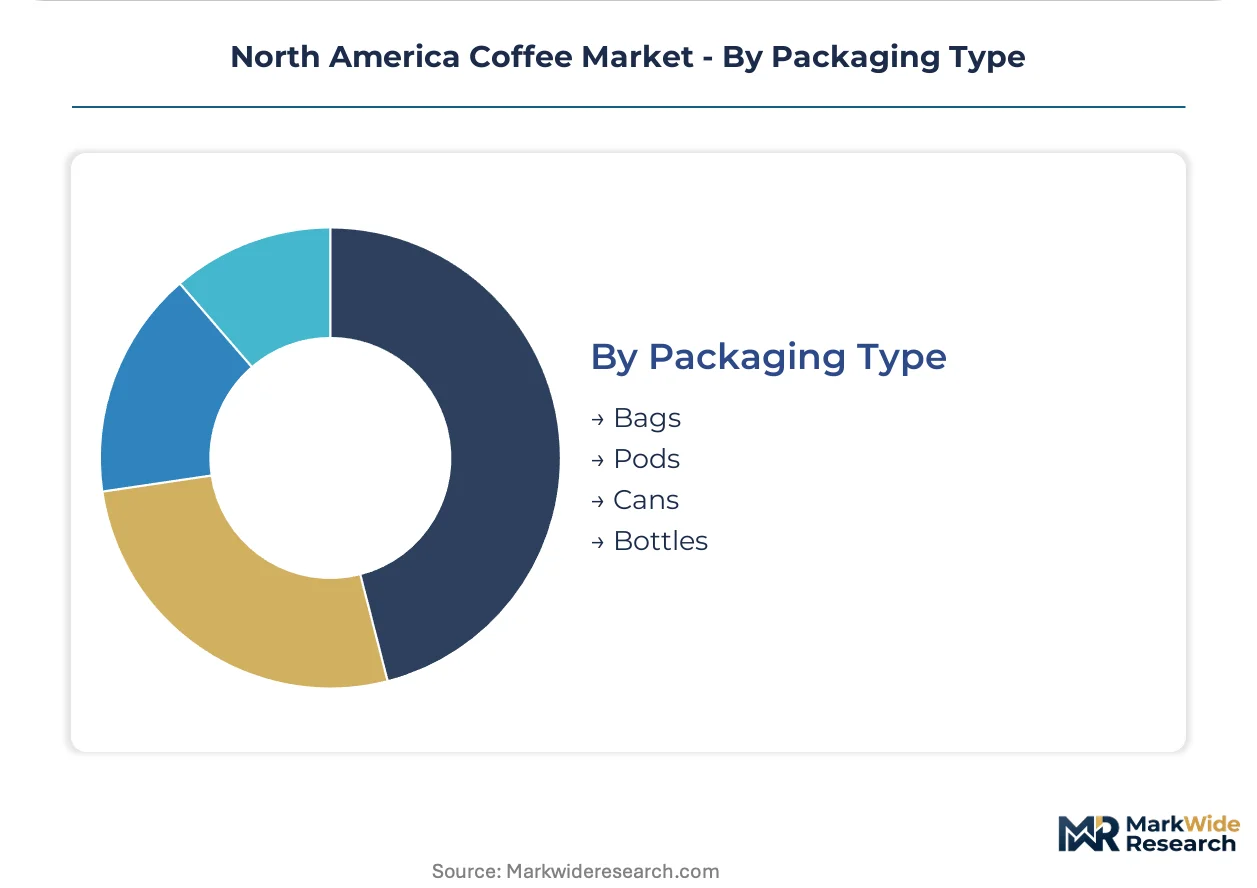
- Pods:Single-serve sealed containers for proprietary brewing systems. Office channel refresh cycles in Texas and Arizona suburban corridors sustain volume, though Vancouver and Seattle municipal bans on plastic variants force immediate compostable format transitions.
- Bottles:Ready-to-drink cold brew and iced coffee in PET or glass containers. California Proposition 65 labeling requirements and FDA disclosure mandates create compliance moats favoring domestic bottling investments over cross-border import.
- Bags:Flexible packaging for ground and whole bean coffee.
- Cans:Aluminum containers for ambient-stable and nitro-infused products.
Pods retain installed-base dominance; bottles gain share fastest on cold brew velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across North American coffee demand, with Pacific Coast metropolitan buyers absorbing premium cold brew markups while Midwest mass retail channels resist branded ground coffee premiums. The United States dominates absolute consumption volume; Canada concentrates higher per-capita spending on certified organic formats.
United States
Drive-through velocity and subscription algorithm adoption concentrate in Texas suburban corridors and Seattle metropolitan zones respectively. FDA food labeling requirements and California Proposition 65 acrylamide warning mandates create compliance moats favoring domestic bottling investments. Brooklyn and Portland anchor third-wave roasting clusters where single-origin traceability commands wholesale premiums.
Canada
Bilingual packaging compliance and remote community logistics shape distinct procurement patterns across Quebec and northern territories. Health Canada caffeine disclosure regulations for ready-to-drink beverages exceed US FDA baselines, favoring domestic Canadian bottling investments. Vancouver and Toronto metropolitan areas demonstrate strongest municipal single-use packaging restrictions, forcing immediate compostable pod format transitions.
Mexico
Cross-border soluble coffee processing and US-bound arabica re-export logistics concentrate activity in Chiapas and Veracruz growing regions. Mexican federal food safety regulations through COFEPRIS align with US FDA import documentation standards across the trade corridor. Mexico City metropolitan demand for premium café experiences sustains independent roasting partnerships with Oaxacan and Guatemalan origin suppliers.
North America Coffee Market Competitive Environment
Capability concentration sits with coastal roasting specialists; scale advantage sits with national beverage conglomerates. The market structures around three tiers: multinational CPG platforms with licensed brewing systems, regional drive-through chains with suburban real estate expertise, and third-wave roasters with origin-direct sourcing relationships. Dominant competitive moves include portfolio diversification into ambient-stable cold brew formats and strategic partnerships with convenience channel distributors.
Within the multinational CPG tier, Starbucks Corporation and Keurig Dr Pepper Inc. exemplify divergent scale strategies—one anchored in coastal roasting infrastructure and retail channel integration, the other in licensed pod-system penetration across office and home applications. Dutch Bros. Coffee occupies a position within the high-velocity drive-through archetype, sustaining growth in suburban and interstate corridors where small-footprint service models outperform seated dining economics.
| Leading Market Players |
|---|
| Dunkin' Brands Group |
| McDonald's Corporation |
| Starbucks Corporation |
| Dutch Bros. Coffee |
| The Kraft Heinz Company |
| Keurig Dr Pepper Inc. |
| Tim Hortons |
| Caribou Coffee |
| The J. M. Smucker Company |
| Others |
Value Chain & Pricing Dynamics
Port of Ho Chi Minh City freight corridors transmit Vietnamese robusta cost volatility directly into North American soluble coffee pricing, while Brazilian arabica futures through Santos port infrastructure concentrate margin pressure among mid-size roasters lacking forward-contract coverage. This logistics-cost asymmetry between origin points rewards coastal roasting facilities with direct container access and penalizes inland processors dependent on intermodal transfers.
Pricing Analysis
After-sales service revenue from equipment maintenance and pod-system replenishment contracts drives lifetime value extraction beyond initial hardware sales. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification stacking and origin traceability depth. Cost compression in economy-tier ground coffee intensifies because Brazilian frost damage has tightened arabica spot availability. Home subscription users demonstrate lowest price sensitivity; Midwest mass retail channels exhibit highest elasticity.
Supply Chain Analysis
Upstream green coffee feedstock draws from Brazil, Colombia, and Vietnam as the three dominant origin countries. Roasting infrastructure rests on drum and fluid-bed equipment manufactured in Italy, Germany, and the United States. Single-source vulnerability concentrates in Vietnamese robusta for soluble processing. Distribution runs through coastal roasting hubs with direct convenience-store and grocery channel placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluid-bed roasting automation expertise and nitrogen-infusion technical talent represent acute capability gaps that constrain format expansion timelines. Firms bridging traditional cupping knowledge with programmable logic controller operation command disproportionate competitive leverage.
For Market Incumbents: Harden coastal roasting infrastructure against Brazilian weather-driven input spikes through multi-origin contracting and captive inventory buffers. Deepen backward integration into Colombian and Guatemalan washing station partnerships to secure traceability premiums that justify shelf positioning against private-label encroachment.
For New Entrants and Emerging Players: Build out bilingual packaging capabilities for Quebec grocery channels where Health Canada disclosure requirements exceed US FDA baselines and US-only competitors retreat. Target Canadian remote communities and Alaska logistics-constrained markets with instant coffee formats that bypass fresh bean cold-chain requirements.
For Investors and Strategic Acquirers: Drive-through format specialists with proven suburban real estate models and nitrogen-flushing technical capabilities present asymmetric upside capture potential. Monitor municipal single-use packaging ban adoption rates in Pacific Coast metropolitan areas as inflection indicator for compostable format transition costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Nitrogen-Infused Cold Brew Scale-Up | Extends shelf stability without refrigeration, unlocking convenience channel placement previously blocked by logistics costs. |
| Compostable Pod Format Transition | Preempts Vancouver and Seattle municipal bans while capturing office channel refresh cycles in Texas suburban corridors. |
| Dual Certification Stacking Investment | USDA Organic plus Fair Trade credentials command Pacific Coast metropolitan premiums where origin transparency dominates purchase decisions. |
| Direct-to-Consumer Algorithm Deployment | Predictive replenishment models displace static auto-delivery schedules in Seattle and San Francisco smart home device households. |
| Coastal Roasting Hub Expansion | Retooled ambient-stable extraction infrastructure collapses distribution economics for direct convenience store shipment. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with roasting plant managers, green coffee procurement leads at multinational CPG platforms, convenience channel category buyers, third-wave café owners in Portland and Brooklyn, and fluid-bed equipment technicians. Secondary validation drew from FDA food labeling guidance documents, Health Canada caffeine disclosure regulations, USDA organic certification databases, California Proposition 65 enforcement records, and customs import documentation through the U.S.-Canada trade corridor. Bottom-up segment sizing triangulated against top-down macroeconomic consumption indicators.
Calibration against historical pod-format penetration curves and cold brew adoption velocity in Pacific Coast metropolitan areas anchored the analytical framework. Segmentation dimensions modeled include product format, end-use channel, roast profile, and packaging type across the projection horizon. CAGRs were derived from trend extrapolation moderated by regulatory inflection points and format substitution elasticities. Forecast inputs incorporated Brazilian frost cycle frequency and municipal single-use packaging restriction adoption patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by nitrogen-infusion technology specialists or compostable packaging innovators would shift outcomes beyond modeled ranges. Cross-checking against Health Canada enforcement discretion and FDA labeling rulemaking timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Global Coffee Machine Market
Coffee
Coffea Arabica (Coffee) Seed Oil Market
Coffee
Breakroom Refreshment and Coffee Services Market
Coffee
Coffee Roaster Market
Coffee
Global Automatic Coffee Machines Market
Coffee
Coffee and Tea Capsule Market
Coffee
Encapsulated Caffeine Market
Coffee
Adaptogen Coffee Market
Coffee
United Arab Emirates Coffee Roaster Market
Coffee
Japan Coffee and Tea Capsules Market
Coffee
India Ready-To-Drink (RTD) Coffee Market
Coffee
Coffee Bags Market
Coffee
Chewable Coffee Market
Coffee
Ethiopia Coffee Market
Coffee
Espresso Tamper Market
Coffee
Europe Coffee Market