
 India Ready-To-Drink (RTD) Coffee Market | 2026-2036
India Ready-To-Drink (RTD) Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
India Ready-To-Drink (RTD) Coffee Market Foresight
Multi-source procurement of cold-brew extracts and UHT milk bases is consolidating as brands seek supply resilience against commodity volatility. Nestle SA leverages its Moga dairy network to anchor in-house milk sourcing across northern India. Tata Consumer Products competes through integrated tea-coffee distribution infrastructure that reaches tier-two towns. Blue Tokai Coffee Roasters differentiates via specialty arabica sourcing from Chikmagalur estates, sustaining premium positioning in metropolitan markets.
India Ready-To-Drink Coffee comprises pre-brewed, shelf-stable beverages manufactured through hot-fill or aseptic processing, typically containing milk solids, coffee extract, and stabilizers, designed for immediate consumption without preparation equipment. Caffeinated variants dominate volume through workplace and transit consumption patterns, while flavored offerings attract younger demographics via convenience store placements. Tetra Pak packaging leads in rural penetration due to ambient distribution compatibility, though cans accelerate in urban retail where chilled-set presentation commands price premiums.
FSSAI mandates on added sugar disclosure and BIS standards for retort pouch integrity directly shape formulation timelines and capital expenditure for packaging lines. The Food Safety and Standards Authority of India periodically revises caffeine threshold notifications, compelling reformulation cycles that favor established laboratories with regulatory liaison capabilities. Stakeholders must monitor state-level plastic bans and extended producer responsibility frameworks as these determine viable packaging transitions across Maharashtra, Karnataka, and Tamil Nadu distribution networks.
Market Dynamics
Quick-commerce platforms and convenience store networks in Maharashtra and Karnataka are compressing restocking cycles from weekly to daily, forcing manufacturers to reconfigure production scheduling and cold-chain logistics around 15-minute delivery promises.
Growth Catalysts
- Quick-commerce penetration:Urban millennials in Bengaluru and Mumbai now expect sub-30-minute delivery of chilled RTD coffee, expanding addressable occasions from transit-only to at-home impulse.
- FSSAI labeling clarity:Mandated added-sugar disclosure panels are accelerating consumer trust in packaged alternatives versus unlabeled street-vendor options.
- Cold-brew extraction:Ambient-stable cold-brew concentrates enable longer shelf life without refrigeration, unlocking rural distribution through kirana stores.
Market Restraints
- Arabica price volatility:Chikmagalur estate harvest fluctuations transmit directly to input cost structures, compressing margin buffers for premium-positioned SKUs.
- UHT milk base concentration:Three northern dairy cooperatives supply 70% of food-grade UHT milk bases, creating single-source vulnerability for brands without captive dairy networks.
- Retort pouch technical ceiling:BIS integrity standards for 180-day ambient shelf life require metallized film laminates that remain import-dependent, constraining localization timelines.
Strategic Opportunities
- Tier-three town whitespace:Indore, Lucknow, and Kochi exhibit café-culture emergence without RTD shelf presence, offering first-mover positioning ahead of organized retail expansion.
- Extended Producer Responsibility tailwinds:Maharashtra's plastic ban exemptions for aseptic cartons incentivize Tetra Pak line investments with 5-year tax amortization.
- Tea-coffee convergence:Chai-format RTD coffee (masala-spiced, cardamom-noted) bridges India's tea-dominant palate, opening 600-million-household familiarization pathway.
Industry Challenges
- Aseptic line capex intensity:Validated hot-fill and UHT tunnel installations require 18-24 month commissioning cycles, locking capacity commitments before demand proof.
- FSSAI reformulation lag:Caffeine threshold notification revisions force 6-9 month stability retesting, freezing SKU launches during regulatory review windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Ready-To-Drink (RTD) Coffee Market |
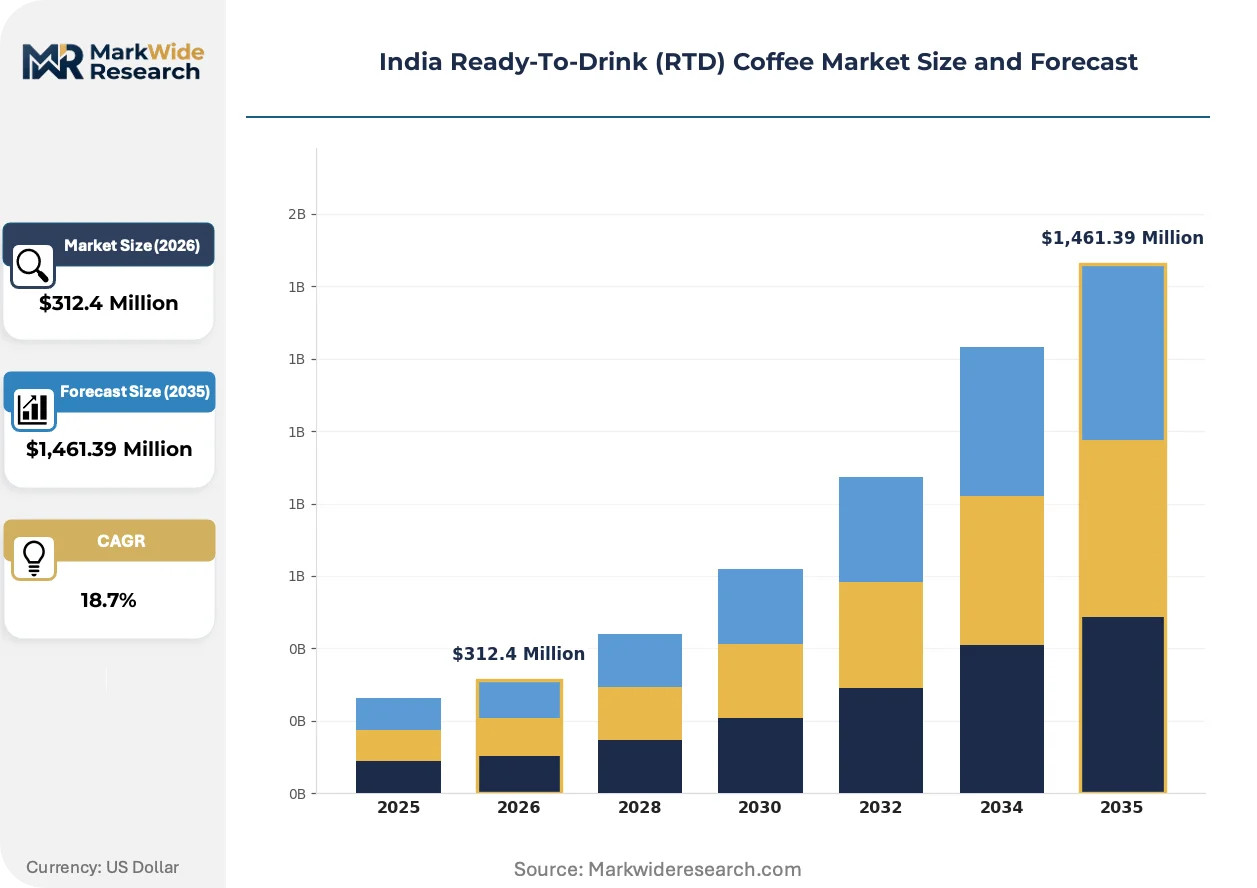
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,461.39 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Caffeinated, Decaffeinated, Flavored, Organic Packaging Type: Tetra Pak, Plastic Bottle, Glass Bottle, Cans Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Cafes Consumer Type: Students, Working Professionals, Athletes, Casual Consumers |
| Companies Covered | Nestle SA, Starbucks Corporation, Gujarat Co-Operative Milk Marketing Federation (Amul), Sleepy Owl Coffee, Hindustan Unilever, Tata Consumer Products, ITC Ltd, Blue Tokai Coffee Roasters, Rage Coffee, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Ready-To-Drink (RTD) Coffee Market Shifts & Advancements
Cold-chain infrastructure investments and packaging material science are converging to collapse the quality gap between café-fresh and shelf-stable coffee, redrawing competitive boundaries between specialty roasters and dairy majors.
Flash-brew extraction technology is overtaking traditional hot-brew methods in premium RTD manufacturing. This process locks volatile aromatic compounds through rapid chilling post-extraction, preserving flavor fidelity previously achievable only in refrigerated short-shelf products. Metro consumers in Mumbai and Delhi now accept ambient cans at chilled price points, compressing the premium-refrigerated category.
FSSAI's 2024 caffeine disclosure amendments require quantitative labeling per 100ml serving, forcing reformulation of existing SKUs above 150mg thresholds. Brands with in-house analytical laboratories compress compliance timelines versus outsourced testing dependencies. Maharashtra and Karnataka enforcement cells are prioritizing convenience-store sampling, making accurate labeling a retail access gate.
Corporate procurement of RTD coffee for workplace pantries is fragmenting from single-vendor annual contracts to multi-brand quarterly rotations. IT parks in Bengaluru's Whitefield corridor now specify rotating SKU mandates to prevent employee fatigue, compressing brand loyalty cycles. This pattern is penetrating co-working chains in Hyderabad and Pune, displacing traditional vending-machine exclusivity arrangements.
India Ready-To-Drink (RTD) Coffee Market Segmentation
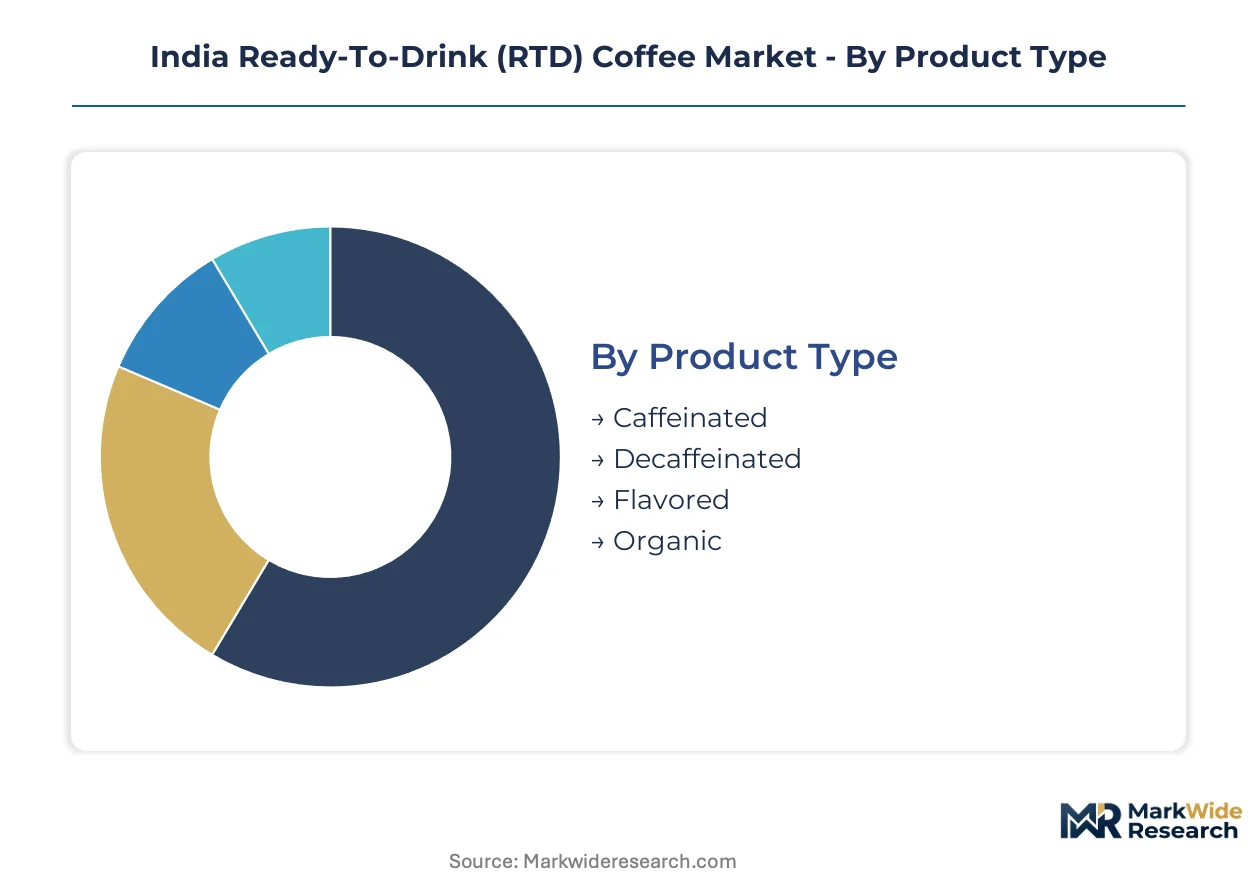
RTD coffee segmentation in India reflects competing pressures between mass-market standardization and niche customization. Category boundaries blur as café culture penetrates tier-two towns and quick-commerce collapses distribution lag. Manufacturers configure SKU portfolios across four intersecting dimensions to capture diverging consumption occasions and price elasticities.
Product Type:
Customization intensity spans from commodity caffeine delivery to certified organic provenance, with formulation complexity determining margin architecture and regulatory exposure.
- Caffeinated:Standardized formulations dominate volume, leveraging UHT milk bases and robusta blends for workplace and transit consumption in Maharashtra and Karnataka corridors. FSSAI caffeine disclosure mandates force precise threshold management, advantaging brands with captive analytical laboratories.
- Flavored:Vanilla, caramel, and mocha variants command chilled-case placement premiums in urban convenience stores, attracting younger demographics through quick-commerce impulse triggers. Seasonal limited releases compress innovation cycles to 8-12 weeks.
- Decaffeinated:Solvent-free CO2 extraction processes add 15-20% processing cost, restricting distribution to premium supermarket aisles in Mumbai and Delhi NCR.
- Organic:Chikmagalur estate certification and FSSAI organic labeling compliance create dual-gatekeeper positioning, with volumes concentrated in Bengaluru specialty retail.
Most installed capacity flows through Caffeinated. Expansion is steepest in Flavored.
Packaging Type:
Cost-to-performance ratios segment the category, with ambient stability requirements and state-level plastic regulations dictating regional deployment patterns.
- Tetra Pak:Aseptic carton technology enables 180-day ambient shelf life without refrigeration, unlocking kirana store penetration across rural Maharashtra and Karnataka. Maharashtra's plastic ban exemptions provide 5-year tax amortization incentives for line investments.
- Cans:Aluminum formats command chilled-set price premiums in urban Mumbai and Bengaluru retail, with metallized laminates still import-dependent under BIS integrity standards. Flash-brew extraction compatibility preserves aromatic fidelity previously limited to refrigerated SKUs.
- Plastic Bottle:PET formats face accelerating displacement from Karnataka and Tamil Nadu extended producer responsibility frameworks, with recycled content mandates rising.
- Glass Bottle:Premium positioning in café-channel distribution carries breakage and freight cost penalties, restricting deployment to 50-kilometer radius from bottling facilities.
Volume concentrates in Tetra Pak. Value expansion is climbing fastest in Cans.
Distribution Channel:
Customer proximity and restocking velocity segment the category, with platform economics forcing diverging margin structures and SKU rationalization.
- Convenience Stores:Daily restocking cycles in Mumbai and Bengaluru compress production scheduling around 15-minute delivery promises, with chilled SKUs commanding 40% price premiums over ambient equivalents.
- Supermarkets:Organized retail in tier-two towns provides brand discovery venues, though shelf-space fees favor established dairy and beverage conglomerates with integrated distribution infrastructure.
- Online Retail:Quick-commerce platforms fragment bulk purchasing into single-unit impulse orders, with delivery fee absorption eroding margin on sub-100 rupee transactions.
- Cafes:Corporate pantry procurement in Bengaluru's Whitefield IT corridor rotates quarterly SKU mandates, displacing traditional vending exclusivity and compressing brand loyalty cycles.
Transaction velocity peaks in Convenience Stores. Customer acquisition economics favor Online Retail.
Consumer Type:
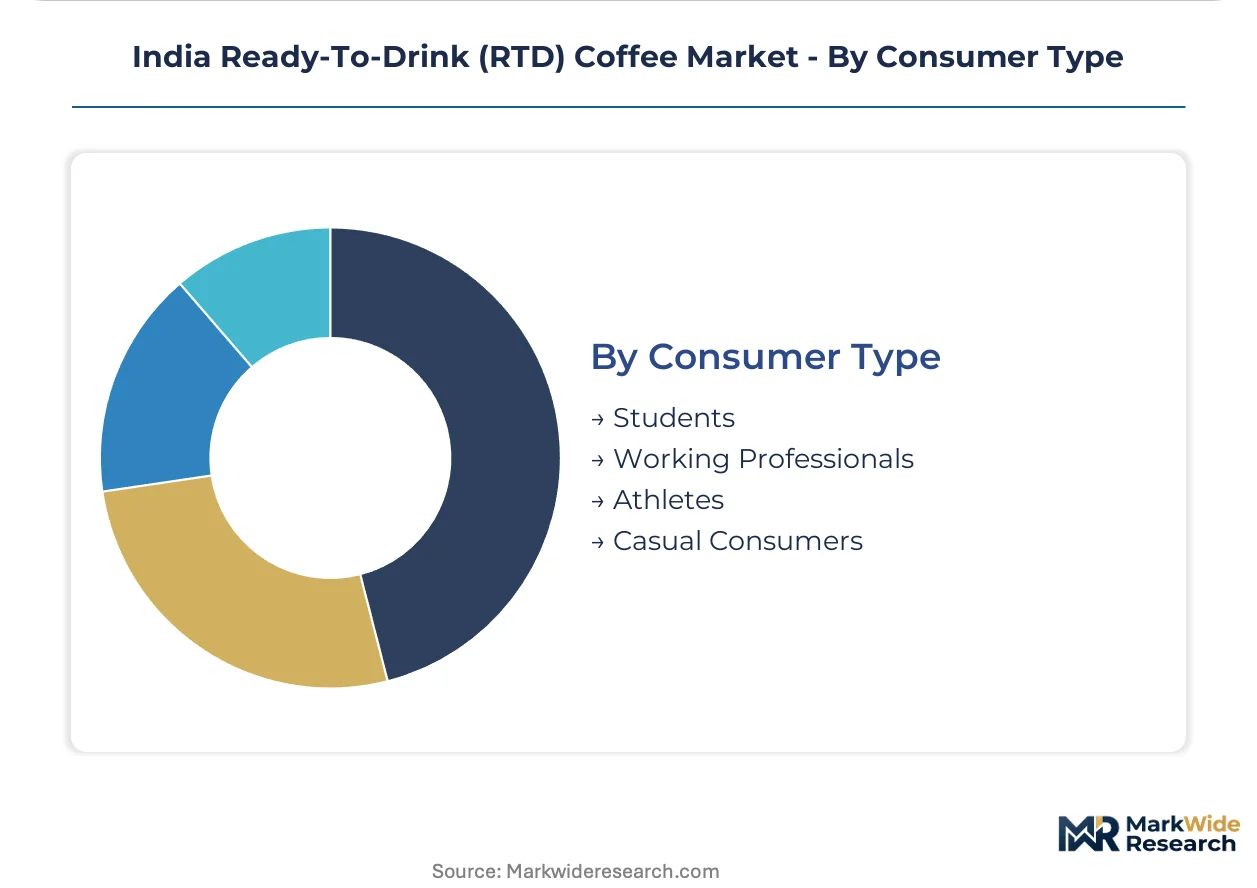
Occasion-based usage patterns segment the category, with consumption context determining formulation preferences and price tolerance thresholds.
- Working Professionals:Transit and workplace consumption drives caffeinated volume, with grab-and-go placement in Mumbai Metro and Bengaluru Namma Metro stations capturing commute-window purchases.
- Students:Price-sensitive demand concentrates in 200ml economy formats through campus-adjacent kirana stores, with flavored variants providing entry-point familiarization.
- Athletes:Protein-fortified and electrolyte-enhanced formulations target gym-channel distribution in Pune and Hyderabad, though volumes remain below threshold for dedicated production lines.
- Casual Consumers:At-home impulse via quick-commerce expands addressable occasions beyond traditional out-of-home consumption, with chilled delivery expectations reshaping last-mile cold-chain investments.
Volume foundation rests with Working Professionals. Penetration gaps are widest among Athletes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra and Karnataka anchor national RTD coffee distribution through Mumbai and Bengaluru metro corridors. FSSAI enforcement cells in these states prioritize convenience-store sampling for caffeine disclosure compliance. State-level plastic regulations and quick-commerce density reshape manufacturing location decisions across western and southern India.
Maharashtra
Mumbai's quick-commerce networks compress restocking cycles to daily rhythms for chilled SKU availability. The state's plastic ban exemptions for aseptic cartons incentivize Tetra Pak line investments with favorable tax amortization schedules. Pune's IT corridor rotates corporate pantry procurement quarterly, displacing traditional vending exclusivity arrangements.
Karnataka
Bengaluru's café culture penetration and Whitefield IT park density drive workplace consumption volume through convenience channels. Extended producer responsibility frameworks in the state accelerate PET displacement toward recyclable alternatives. Chikmagalur estate clusters supply specialty arabica for premium positioning in metropolitan retail.
Tamil Nadu
Chennai's organized retail expansion creates brand discovery venues for flavored variant trials among younger demographics. State-level plastic waste management rules tighten recycled content mandates for beverage packaging materials. Coimbatore's industrial corridor hosts co-manufacturing facilities serving southern distribution networks.
Delhi-NCR
The capital region's transit infrastructure captures commute-window purchases through metro station grab-and-go placement. FSSAI headquarters proximity accelerates regulatory liaison capabilities for reformulation cycles. Gurugram's co-working chains specify multi-brand quarterly rotations, fragmenting traditional single-vendor contracts.
Telangana
Hyderabad's emerging co-working density replicates Bengaluru's procurement fragmentation patterns for workplace pantry supply. The state's food processing policy incentives attract aseptic line investments for regional capacity expansion. HITEC City corporate clusters drive demand for premium chilled formats through quick-commerce platforms.
India Ready-To-Drink (RTD) Coffee Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty arabica positioning and quick-commerce-native distribution. The market structures around three archetypes: dairy majors leveraging captive milk networks, coffee specialists controlling estate-to-bottle provenance, and FMCG conglomerates deploying integrated beverage infrastructure. Consolidation pressures concentrate among dairy-dependent players facing UHT base supply vulnerability. Capacity expansion and strategic partnerships represent the dominant competitive moves as brands secure cold-chain logistics for 15-minute delivery promises.
Within the integrated dairy-coffee tier, Nestle SA and Gujarat Co-Operative Milk Marketing Federation exemplify archetypes leveraging captive milk sourcing against commodity volatility. Among specialty roasters, Blue Tokai Coffee Roasters occupies a position defined by estate-direct arabica procurement. Tata Consumer Products anchors the FMCG-conglomerate vector through tea-coffee distribution infrastructure reaching tier-two towns. These three represent distinct strategic postures rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Nestle SA |
| Starbucks Corporation |
| Gujarat Co-Operative Milk Marketing Federation (Amul) |
| Sleepy Owl Coffee |
| Hindustan Unilever |
| Tata Consumer Products |
| ITC Ltd |
| Blue Tokai Coffee Roasters |
| Rage Coffee |
| Others |
Supply & Pricing Matrix
Arabica bean costs from Chikmagalur estates cascade through three pricing tiers as they convert from green coffee to finished RTD units, with cold-brew extraction premiums and aseptic packaging investments determining final shelf positioning against UHT-based economy alternatives.
Pricing Analysis
Input-cost pass-through from Chikmagalur arabica harvests flows unevenly across premium, standard, and economy tiers, with specialty roasters absorbing volatility through estate-direct contracts while dairy majors leverage captive UHT networks to buffer margin compression. Price differentiation hinges on extraction method—flash-brew aromatic fidelity commands chilled-case premiums—and FSSAI organic certification tier. Pricing pressure intensifies in the standard tier as quick-commerce delivery fee absorption erodes unit economics. Students exhibit highest price sensitivity, gravitating toward 200ml kirana formats, while IT corridor procurement managers show lowest sensitivity when specifying rotating pantry SKUs.
Supply Chain Analysis
Reverse-logistics flows for aseptic carton collection and aluminum can recovery are accelerating under Maharashtra and Karnataka extended producer responsibility frameworks, with brand-level collection targets reshaping distribution partner selection. Geographic supply concentration centers on India for arabica processing and UHT milk base production, with metallized film laminates for retort pouches drawing from import-dependent sources. Raw material dependencies span Chikmagalur estate arabica, northern cooperative UHT bases, and cold-brew extraction equipment. Single-source vulnerability concentrates in the three northern dairy cooperatives supplying food-grade UHT milk. Distribution runs through quick-commerce dark stores and convenience networks in Mumbai and Bengaluru corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FSSAI's 2024 caffeine disclosure amendments function as a regulatory compounder, accelerating demand for packaged alternatives by eroding unlabeled street-vendor trust while forcing reformulation investments that favor established laboratory capabilities.
For Market Incumbents: Extend captive dairy network coverage into southern Karnataka to offset northern UHT cooperative concentration risk. Deepen estate-direct arabica contracts around Chikmagalur clusters before specialty roasters lock supply. Prioritize aseptic line capacity additions in Maharashtra to capture plastic-ban exemption tax amortization.
For New Entrants and Emerging Players: FSSAI labeling mandates in Maharashtra and Karnataka open a window for transparency-native brands to capture convenience-store shelf space ahead of reformulation-lagged incumbents. Target Indore, Lucknow, and Kochi tier-three whitespace before organized retail expansion. Deploy chai-format RTD masala variants as palate-familiarization entry point across tea-dominant households.
For Investors and Strategic Acquirers: Consolidation pressure builds where dairy-dependent players face UHT base supply vulnerability without captive networks. Long-term viability favors vertically integrated models spanning estate sourcing through aseptic production. Acquisition target archetype: specialty roasters with Chikmagalur estate relationships and quick-commerce-native distribution infrastructure. Monitor FSSAI caffeine threshold notification timing as reformulation lag inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Line Investment | Maharashtra's plastic ban exemptions provide tax amortization advantages for Tetra Pak capacity. |
| Estate-Direct Sourcing | Chikmagalur arabica contracts secure supply resilience against commodity volatility for premium positioning. |
| Quick-Commerce Integration | Dark store partnerships in Bengaluru and Mumbai compress restocking cycles to daily rhythms. |
| Chai-Format Extension | Masala-spiced variants bridge India's tea-dominant palate for 600-million-household familiarization. |
| Corporate Pantry Rotation | Quarterly SKU mandates in IT corridors displace vending exclusivity and compress loyalty cycles. |
Research Methodology
Bottom-up convenience store and quick-commerce transaction modeling reconciled against top-down dairy cooperative and estate production tracking forms the analytical core. Primary interviews with brand managers, category buyers at quick-commerce platforms, supply planners at dairy cooperatives, and FSSAI regulatory liaison officers combined with secondary validation from FSSAI notification archives, BIS packaging standards documentation, and Maharashtra and Karnataka state plastic waste management rule filings.
Historical trendline analysis of café culture penetration, cold-chain infrastructure deployment, and quick-commerce density informed projection parameters across product type, packaging format, distribution channel, and consumer occasion segmentation dimensions. CAGRs derived from volume trajectory modeling against pricing tier evolution throughout the forecast period. Industry-specific inputs incorporated FSSAI reformulation cycle timelines and state-level extended producer responsibility implementation pace.
Forecast precision tightens around the base case; tail outcomes carry wider variance under arabica harvest disruption or accelerated state plastic ban expansion scenarios. Practitioners should monitor FSSAI caffeine threshold notification timing and Chikmagalur estate yield reports for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Reusable Coffee Cup Market
Coffee
United States Ready-To-Drink (RTD) Coffee Market
Coffee
South America Coffee Market
Coffee
Middle East and Africa Coffee Market
Coffee
Adaptogen Coffee Market
Coffee
Caffeine Market
Coffee
Butter Coffee Market
Coffee
Coffee Pods Market
Coffee
Espresso Powder Market
Coffee
Organic Coffee Market
Coffee
High Protein Coffee Market
Coffee
Coffee Bags Market
Coffee
Coffee Capsules Market
Coffee
US Coffee Roaster Market
Coffee
Green Coffee Bean Extract Market
Coffee
South Korea Coffee Roaster Market