
 Next Generation Biometric Market | 2026-2036
Next Generation Biometric Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation Biometric Market Analysis
Platform licensing revenue is reshaping competitive economics in next-generation biometrics, pulling margin pools away from hardware-only transactions toward recurring software entitlement models. IDEMIA leverages its government credentialing heritage to dominate large-scale national identity programs across multiple continents. Thales Group anchors its position through deep integration of biometric modules into civil aviation and border infrastructure workflows. NEC Corporation specializes in facial recognition algorithms optimized for low-light and high-throughput public safety environments.
Next-generation biometrics encompasses multi-modal physiological and behavioral identification systems operating on match-on-card, liveness detection, and anti-spoofing parameters with false acceptance rates below 0.001 percent, deployed primarily for identity assurance in high-risk transactions and physical access scenarios. Facial recognition and iris recognition command premium pricing in border security deployments where accuracy thresholds exceed fingerprint alternatives under variable environmental conditions. Mobile authentication applications within the banking end-user segment are expanding fastest as financial institutions replace static passwords with continuous behavioral biometrics. Cloud-based deployment architectures are capturing share from on-premises installations by reducing capital intensity for mid-size healthcare and retail adopters.
The EU AI Act imposes strict conformity assessments on remote biometric identification systems, while the FDA regulates certain clinical authentication applications in U.S. healthcare settings and India's UIDAI governs Aadhaar ecosystem interoperability standards. These frameworks collectively elevate product certification costs but simultaneously disqualify non-compliant vendors from procurement pools. Stakeholders must monitor regulatory divergence between privacy-centric European restrictions and security-driven Asian authentication mandates to anticipate where standardization or fragmentation will govern cross-border system deployment.
Market Dynamics
Platform licensing revenue is pulling margin pools away from hardware-only transactions toward recurring software entitlement models, fundamentally restructuring how biometric vendors capture value across authentication ecosystems.
Growth Catalysts
- Aadhaar-linked authentication:India's UIDAI-governed ecosystem drives large-scale iris and fingerprint integration across government and private services, creating sustained procurement pipelines for multimodal systems.
- EU AI Act compliance mandates:The risk classification framework for biometric identification systems tightens requirements, elevating product certification costs but simultaneously disqualifying non-compliant vendors from procurement pools.
- Behavioral biometrics:Financial institutions are replacing static passwords with continuous authentication patterns, expanding mobile application deployment fastest within banking end-user segments.
Market Restraints
- Sensor hardware cost volatility:Specialized optical and capacitive sensor components face input price pressure from concentrated semiconductor foundry capacity in East Asian supply chains.
- Technical limitation in low-light facial recognition:Variable environmental conditions at border crossings and outdoor public safety deployments degrade accuracy thresholds below fingerprint alternatives without supplemental infrared illumination.
- Regulatory friction from GDPR:European data protection authorities impose strict purpose limitation and storage restriction requirements on biometric data processing, complicating cross-border authentication service architectures.
Strategic Opportunities
- Underpenetrated healthcare authentication:FDA-regulated clinical environments in the United States present expansion potential for patient identification systems that integrate with existing electronic health record infrastructure.
- Cloud-based deployment architectures:Mid-size healthcare and retail adopters are migrating from on-premises installations to reduce capital intensity, creating subscription revenue streams for platform providers.
- Technology convergence of liveness detection and match-on-card:Combining anti-spoofing parameters with decentralized credential verification addresses both security and privacy requirements in high-risk transaction scenarios.
Industry Challenges
- Algorithm bias certification:Demographic performance disparities in facial recognition systems require extensive testing protocols to meet emerging fairness standards from national regulators.
- Integration complexity with legacy physical access systems:Enterprise customers face friction retrofitting existing badge-and-reader infrastructure with multimodal biometric readers without full replacement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation Biometric Market |
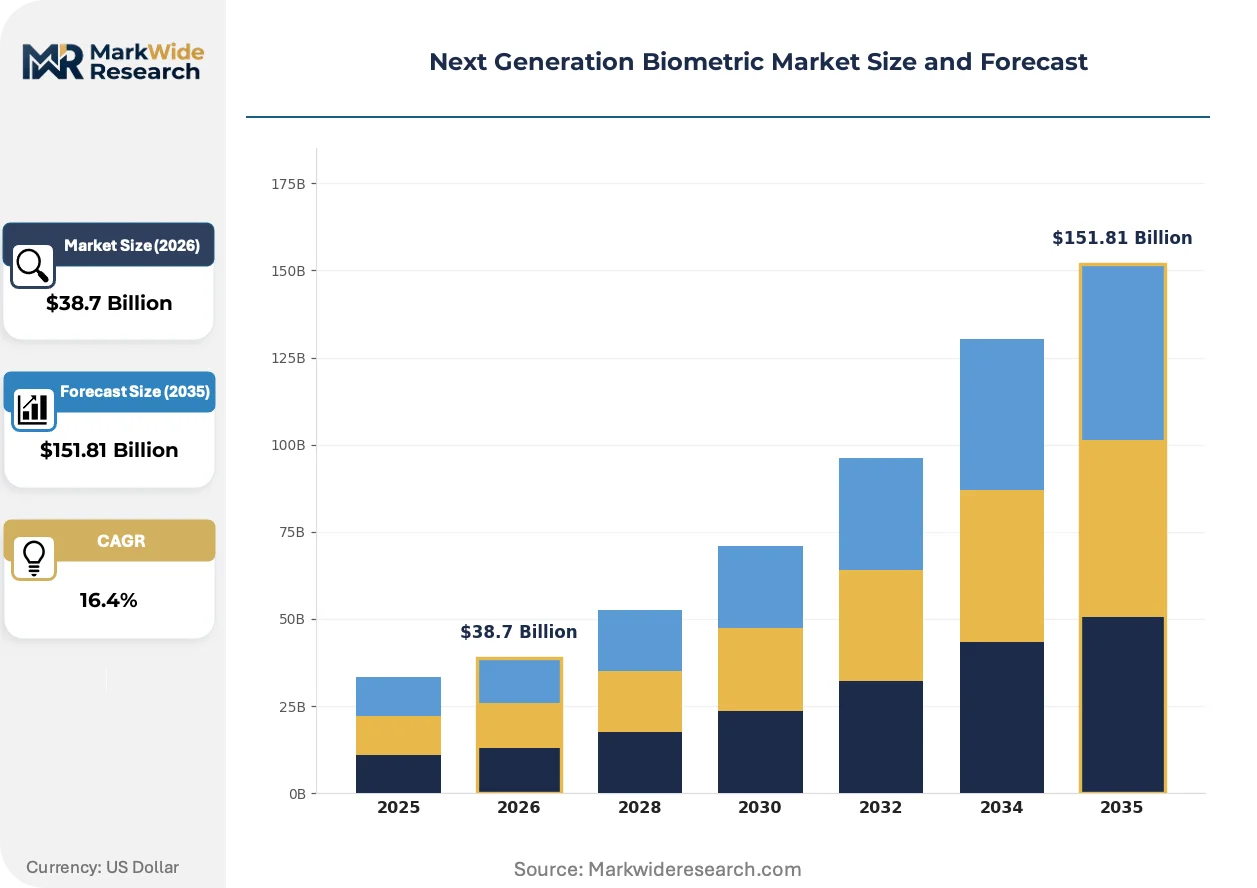
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fingerprint Recognition, Facial Recognition, Iris Recognition, Voice Recognition Application: Mobile Authentication, Access Control, Time Tracking, Border Security End User: Banking, Healthcare, Government, Retail Deployment: On-Premises, Cloud-Based, Hybrid, Embedded |
| Companies Covered | IDEMIA, Thales Group, NEC Corporation, Fujitsu, ASSA ABLOY, HID Global Corporation, Suprema Inc., Aware Inc., Synaptics Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation Biometric Market Emerging Trajectories
Continuous authentication architectures are displacing static one-time verification events, embedding biometric monitoring throughout user sessions rather than isolating identity proof to entry points.
Contactless fingerprint sensing is digitizing enrollment and matching workflows by capturing ridge patterns through airborne ultrasound or optical coherence tomography without surface contact. Banking customers in Asia-Pacific markets are adopting these sensors at accelerated pace for ATM and branch authentication. This modality is digitizing hygiene-sensitive deployment scenarios that previously relied on capacitive touch sensors.
The EU AI Act's conformity assessment requirements for remote biometric identification systems impose mandatory third-party auditing before market placement. Industrial consequence includes extended product development timelines and documentation burdens for algorithm transparency. Border security and law enforcement procurement pools in European Union member states are responding by pre-qualifying vendors with existing certification heritage.
Financial institutions are unbundling authentication from core banking software, procuring biometric capabilities through API-integrated best-of-breed specialists rather than monolithic platform suites. This procurement pattern disrupts traditional enterprise software licensing and concentrates purchasing authority with chief information security officers. The shift is most visible in North American and European retail banking verticals where regulatory pressure for strong customer authentication coincides with cloud-native infrastructure migration.
Next Generation Biometric Market Segmentation
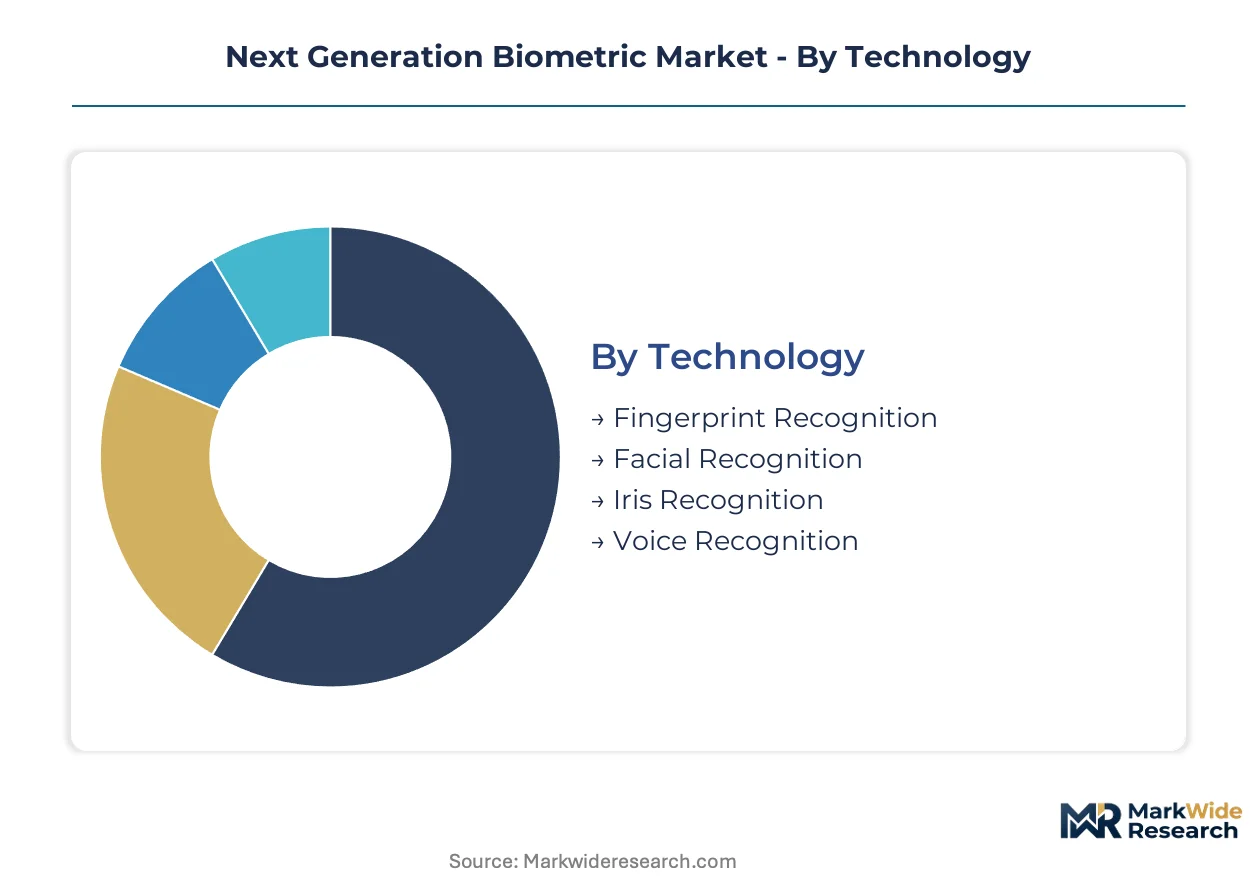
Biometric technology selection determines capital intensity, replacement cycles, and regulatory exposure across authentication ecosystems. Deployment architecture choices separate legacy infrastructure retrofit opportunities from greenfield cloud-native implementations. Understanding segment velocity helps vendors prioritize R&D investment and channel partnerships.
Technology:
Facial and iris systems refresh every 3-4 years as algorithm accuracy improves, while fingerprint hardware persists 7-10 years in physical access installations. Voice recognition sits between these poles with 5-6 year replacement cycles tied to natural language processing advances.
- Fingerprint Recognition:Capacitive, optical, and ultrasonic sensors capture ridge patterns with false acceptance rates below 0.001 percent in enterprise deployments. Banking ATM networks in India and Brazil concentrate procurement for contactless variants that eliminate hygiene concerns at high-touch surfaces. UIDAI mandates drive large-scale enrollment for Aadhaar-linked government services.
- Facial Recognition:Deep learning algorithms process 2D and 3D facial geometry under variable lighting conditions using infrared supplementation for liveness detection. Border security agencies in Germany, France, and the Netherlands deploy these systems at Schengen entry points where throughput demands exceed fingerprint alternatives. EU AI Act conformity assessments extend vendor qualification timelines.
- Iris Recognition:Pattern-matching from near-infrared imaging of the trabecular meshwork delivers the lowest false match rates among physiological modalities. India's national identity program maintains the largest installed base, with private sector adoption expanding into healthcare patient identification.
- Voice Recognition:Behavioral biometrics analyzing cadence, pitch, and pronunciation patterns enable continuous authentication during active sessions. North American financial institutions integrate these capabilities through API architectures for call center fraud prevention.
Fingerprint recognition dominates installed base. Facial recognition is where expansion concentrates.
Application:
Mobile authentication commands the shortest sales cycles at 6-12 months, while border security procurement extends 24-36 months through government tender processes. Access control and time tracking sit at intermediate durations reflecting enterprise capital budgeting rhythms.
- Mobile Authentication:Smartphone-integrated facial and fingerprint sensors enable app-based transaction authorization with FIDO2 compliance. Asia-Pacific banking customers drive volume as financial institutions replace SMS one-time passwords with biometric possession factors.
- Access Control:Multimodal readers for physical entry points combine card credentials with fingerprint or facial verification for high-security facilities. German industrial manufacturers and Saudi critical infrastructure operators lead retrofit demand.
- Time Tracking:Workforce management systems deploy fingerprint or facial terminals for hourly employee attendance verification. US healthcare networks and Brazilian manufacturing plants concentrate adoption where payroll precision carries regulatory weight.
- Border Security:Automated border control gates match traveler facial images against e-passport chips and watchlist databases. UAE's Smart Gates and Australia's Seamless Traveler programs represent flagship deployments with accuracy thresholds exceeding 99.9 percent.
Access control claims the largest legacy footprint. Mobile authentication is climbing the fastest.
End User:
Government procurement cycles span 3-5 years with budget volatility, while retail decisions compress to 12-18 months driven by competitive pressure. Banking and healthcare sit between these extremes with compliance requirements lengthening evaluation phases.
- Banking:Strong customer authentication mandates under PSD2 and equivalent frameworks push multimodal deployment across digital and branch channels. European and North American institutions prioritize behavioral biometrics for continuous session monitoring.
- Healthcare:Patient identification systems integrate with electronic health records to prevent medical errors and insurance fraud. US hospital networks face FDA oversight for certain clinical authentication applications, while India's Ayushman Bharat program drives fingerprint enrollment.
- Government:National identity programs, law enforcement databases, and voter registration systems require scalable enrollment and matching infrastructure. India's UIDAI, Nigeria's NIMC, and Indonesia's Dukcapil sustain multimodal procurement pipelines.
- Retail:Payment authentication and loss prevention applications deploy facial recognition for self-checkout verification and organized retail crime detection. Convenience store chains in Japan and South Korea lead frictionless checkout experimentation.
Government holds the deepest installed base. Banking is gaining share fastest.
Deployment:
Cloud-based architectures reduce time-to-value to 3-6 months versus 12-18 months for on-premises installations. Hybrid and embedded configurations occupy intermediate positions reflecting integration complexity with existing infrastructure.
- On-Premises:Dedicated hardware and software installations within customer data centers satisfy air-gapped security requirements for defense and intelligence agencies. German and French government facilities mandate these deployments for classified biometric processing.
- Cloud-Based:API-accessible biometric engines eliminate capital expenditure for mid-size healthcare and retail adopters. Subscription revenue models align vendor incentives with customer authentication volume growth across North American and European markets.
- Hybrid:Sensitive enrollment data remains on-premises while matching workloads shift to cloud infrastructure for elasticity. Australian financial institutions and Canadian healthcare networks favor this architecture for regulatory compartmentalization.
- Embedded:Biometric modules integrated directly into endpoint devices enable offline authentication without network dependency. Match-on-card implementations for national ID credentials in India and the Philippines exemplify this decentralized approach.
On-premises retains the largest legacy footprint. Cloud-based deployment shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India demonstrate the lowest price elasticity as Aadhaar-linked mandates sustain procurement regardless of cost fluctuations, while mid-size European healthcare providers exhibit acute sensitivity to capital expenditure thresholds.
India
UIDAI-governed Aadhaar authentication drives sustained iris and fingerprint system procurement across government and private services. The national identity program mandates multimodal enrollment standards that elevate vendor qualification barriers. Hyderabad and Bangalore host concentrated system integrator clusters serving state-level welfare distribution networks.
United States
FDA-regulated clinical authentication applications in hospital networks sustain demand for patient identification systems integrated with electronic health records. HIPAA compliance requirements impose strict biometric data handling protocols on healthcare technology vendors. The Boston-Washington corridor concentrates health-tech procurement authority for enterprise-scale deployments.
Germany
Schengen border security agencies deploy facial recognition at entry points where throughput demands exceed fingerprint alternatives. The EU AI Act's conformity assessment framework extends vendor qualification timelines for remote biometric identification systems. Frankfurt and Munich anchor industrial demand for multimodal physical access control in manufacturing and critical infrastructure.
Japan
Convenience store chains and financial institutions accelerate contactless fingerprint adoption for frictionless checkout and ATM authentication. METI standards govern interoperability between biometric modules and payment infrastructure. Tokyo and Osaka metropolitan areas concentrate retail technology procurement and pilot deployment programs.
United Arab Emirates
Smart Gates at Dubai International Airport and federal border infrastructure sustain premium-tier facial recognition procurement with accuracy thresholds exceeding 99.9 percent. The country's national identity regulator mandates biometric enrollment for resident visa and citizenship services. Abu Dhabi and Dubai host concentrated government technology procurement offices driving Gulf Cooperation Council deployment patterns.
Next Generation Biometric Market Vendor Landscape
Defense-heritage conglomerates and specialized biometric pure-plays split the market between large-scale national identity programs and agile commercial deployments. The vendor base concentrates around three strategic archetypes: government credentialing specialists with classified security clearances, semiconductor-integrated module suppliers, and cloud-native authentication platform builders. Competitive moves center on technology licensing partnerships that embed biometric engines into third-party enterprise software stacks, alongside API-first unbundling strategies that displace monolithic platform suites.
Within the government credentialing tier, IDEMIA and Thales Group exemplify archetypes anchored in national security heritage and civil aviation infrastructure integration respectively. NEC Corporation occupies a specialist position in algorithm-intensive facial recognition optimized for high-throughput public safety environments. These three entities collectively represent the premium-tier procurement pool where extended product development timelines and documentation burdens under EU AI Act conformity assessments disqualify non-compliant vendors from European border security and law enforcement contracts.
| Leading Market Players |
|---|
| IDEMIA |
| Thales Group |
| NEC Corporation |
| Fujitsu |
| ASSA ABLOY |
| HID Global Corporation |
| Suprema Inc. |
| Aware Inc. |
| Synaptics Incorporated |
| Others |
Supply Flow & Price Mechanics
East Asian semiconductor foundry clusters in Hsinchu and Seoul anchor optical sensor production, concentrating capacity for near-infrared imaging components that downstream biometric vendors convert into pricing power at the module level. This geographic concentration creates asymmetric leverage where foundry utilization rates directly transmit into sensor hardware cost volatility for fingerprint and iris system manufacturers.
Pricing Analysis
Platform licensing and extended service contracts now drive lifetime value beyond initial hardware transactions. Three-tier pricing structure across premium, standard, and economy levels separates government-grade certified systems from commercial deployments and entry-level access control hardware. Cost compression in mid-tier facial recognition modules is intensifying because cloud-native entrants are undercutting on-premises incumbents with API-based consumption models. Banking procurement teams in North America demonstrate the lowest price elasticity due to PSD2 compliance mandates, while mid-size European healthcare providers exhibit acute capital expenditure sensitivity.
Supply Chain Analysis
Export-control restrictions under Wassenaar Arrangement dual-use technology classifications limit flows of high-resolution infrared imaging sensors and liveness detection algorithms to certain national markets. Taiwan, South Korea, and Japan concentrate manufacturing for specialized optical components, CMOS image sensors, and biometric processor ASICs. Raw material dependencies include germanium substrates for thermal imaging, rare-earth elements for laser illumination modules, and high-purity silicon wafers. Single-source vulnerability persists for military-grade sensor packaging. Distribution runs through authorized system integrators serving national identity programs and direct OEM relationships with aviation infrastructure providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform licensing revenue layers are expanding faster than hardware transactions, transforming biometric markets into service-attach opportunities where recurring entitlement models displace one-time equipment sales.
For Market Incumbents: Entrench government credentialing relationships through accelerated EU AI Act conformity investments that disqualify emerging competitors from European procurement pools. Deepen backward integration into specialized optical sensor production to mitigate East Asian foundry concentration risk. Prioritize certification heritage as a defensive moat against cloud-native challengers unbundling authentication from core banking software. For New Entrants and Emerging Players: Establish a beachhead in cloud-based mobile authentication APIs for mid-size North American healthcare networks migrating from capital-intensive on-premises installations. Target FDA-regulated clinical environments where patient identification system integration with electronic health records remains underpenetrated. Lead with subscription pricing that eliminates upfront capital barriers for hospital procurement committees. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors algorithm-intensive specialists with demonstrated low-light facial recognition accuracy and existing border security deployment heritage. Long-term viability hinges on sustained R&D intensity through multiple refresh cycles as liveness detection and match-on-card capabilities converge. The signal to watch is pre-qualification velocity in EU member state law enforcement procurement pools, where extended conformity timelines favor incumbents with certification backlogs.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Investment | Extended vendor qualification timelines under EU AI Act mandates pre-qualify certified vendors for border security contracts. |
| Cloud-Native Platform Migration | API-first architectures displace monolithic suites in North American retail banking verticals undergoing infrastructure modernization. |
| Match-on-Card Technology Integration | Decentralized credential verification addresses privacy requirements in India's Aadhaar-linked authentication ecosystem. |
| Behavioral Biometrics Deployment | Continuous authentication patterns replace static passwords in Asia-Pacific financial institution mobile applications. |
| Contactless Fingerprint Sensor Adoption | Airborne ultrasound digitization eliminates hygiene concerns at Japanese convenience store frictionless checkout pilots. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with biometric system integrators, government procurement officers, chief information security officers at financial institutions, and semiconductor component suppliers. Secondary validation drew from UIDAI technical specifications, EU AI Act implementation guidance, FDA device classification databases, and national identity program tender documentation. Bottom-up enrollment and deployment volume estimates were triangulated against top-down market sizing derived from vendor revenue disclosures and government budget appropriations.
Calibration against historical adoption curves in India's Aadhaar ecosystem and Germany's Schengen border infrastructure anchored projection parameters across the analysis window. Segmentation modeling incorporated technology modality, deployment architecture, end-user vertical, and regional regulatory cluster dimensions. CAGRs were computed from fitted growth trajectories rather than simple endpoint averaging, with algorithm accuracy improvement cycles and hardware replacement rhythms serving as industry-specific forecast inputs.
Stress conditions across semiconductor foundry utilization, EU AI Act enforcement intensity, and Aadhaar ecosystem expansion rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about sustained government identity program investment and banking regulatory pressure for strong customer authentication. Material shifts in export-control regime stringency or UIDAI technical mandate revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
North America Enterprise Biometrics Market
Biometrics & Identity Management
Global Mobile User Authentication Market
Biometrics & Identity Management
Biometric ATM Market
Biometrics & Identity Management
FIDO Authentication Market
Biometrics & Identity Management
Global Biometric Identification Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Software Market
Biometrics & Identity Management
Biometrics Software Market
Biometrics & Identity Management
Out-Of-Band Authentication Market
Biometrics & Identity Management
Spain Mobile Biometrics Market
Biometrics & Identity Management
Biometric Bike Locks Market
Biometrics & Identity Management
Biometric Authentication Solution Market
Biometrics & Identity Management
Germany Identity Verification and Authentication Market
Biometrics & Identity Management
North America Biometrics in Government Market
Biometrics & Identity Management
Europe Decentralized Identity Market
Biometrics & Identity Management
ID Verification Market
Biometrics & Identity Management
Mobile Biometric Security and Services Market