
 Passive Fire Proofing System Market | 2026-2036
Passive Fire Proofing System Market Size, Share, and Industry Trends Forecast 2026-2036
Passive Fire Proofing System Market Analysis
Data center construction is pivoting toward higher fire-resistance ratings as hyperscale operators demand extended structural protection for critical infrastructure. AkzoNobel leverages its intumescent coating portfolio to anchor positions in European commercial retrofit programs. Sika AG sustains manufacturing scale across cementitious and gypsum-based systems for industrial end users. Rockwool International dominates mineral fiber board supply for infrastructure tunnels and transit corridors.
Passive fire proofing systems encompass boards, coatings, sprays, and mortars engineered to maintain structural integrity during fire exposure, typically rated by fire resistance duration measured in hours. These systems protect steel substrates, concrete, and compartmentalization assemblies from temperature-induced failure in commercial, industrial, and infrastructure settings. Coating applications lead product type demand due to retrofit flexibility on existing steel frameworks, while board systems occupy higher-margin new-build segments with integrated drywall assemblies. Intumescent materials are displacing traditional cementitious options in transportation and oil and gas applications where weight reduction and thin-film performance are prioritized.
The EU Construction Products Regulation and CE marking requirements shape product certification pathways across member states, while the US National Fire Protection Association standards and local building codes govern specification intensity in North American commercial construction. Germany's federal state building regulations and the UK Building Safety Regulator's gateway compliance framework are tightening third-party testing obligations for high-rise residential and infrastructure projects. Stakeholders must monitor evolving fire-test protocol harmonization between regional standards bodies and assess material substitution risks from emerging aerogel and ceramic fiber formulations.
Market Dynamics
EU Construction Products Regulation enforcement is compressing certification timelines and forcing manufacturers to restructure testing protocols around CE marking harmonization.
Growth Catalysts
- Data center fire-resistance mandates:Hyperscale operators in Germany and the Netherlands now specify two-hour ratings for structural steel, pulling demand for intumescent systems.
- REACH-compliant intumescent chemistry:Reformulated phosphorus-based expandables meet ECHA substance restrictions while maintaining 350°C activation thresholds.
- UK Building Safety Regulator gateway compliance:High-rise residential projects face mandatory third-party fire testing before construction commencement, accelerating specification upgrades.
Market Restraints
- Petrochemical input volatility:Epoxy resin and ammonium polyphosphate prices fluctuate with crude oil indices, squeezing coating formulation margins.
- Testing facility concentration:Only five EU-Notified Bodies certify intumescent coatings to EN 13381-8, creating bottlenecks for new product approvals.
- Cementitious system weight penalty:Dense spray-applied mortars exceed 35 kg/m² load limits for offshore platform decking retrofits.
Strategic Opportunities
- Polish commercial retrofit wave:Warsaw and Krakow office stock built 1990-2005 lacks compartmentalization, creating board system demand as EU energy renovation loans expand eligibility to fire safety.
- Electric vehicle battery enclosure fire barriers:OEMs specify aerogel-composite wraps alongside traditional intumescent mats for thermal runaway containment.
- Digital specification platforms:Building information modeling plugins now embed fire-resistance ratings directly into structural steel takeoffs, shortening consultant decision cycles.
Industry Challenges
- Applicator certification scarcity:EN 1090-2 execution class 3 welding inspectors with fireproofing specialization command 40% wage premiums across Central Europe.
- Multi-standard testing redundancy:Manufacturers seeking German, French, and UK market access must run separate furnace protocols despite harmonized EN base standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passive Fire Proofing System Market |
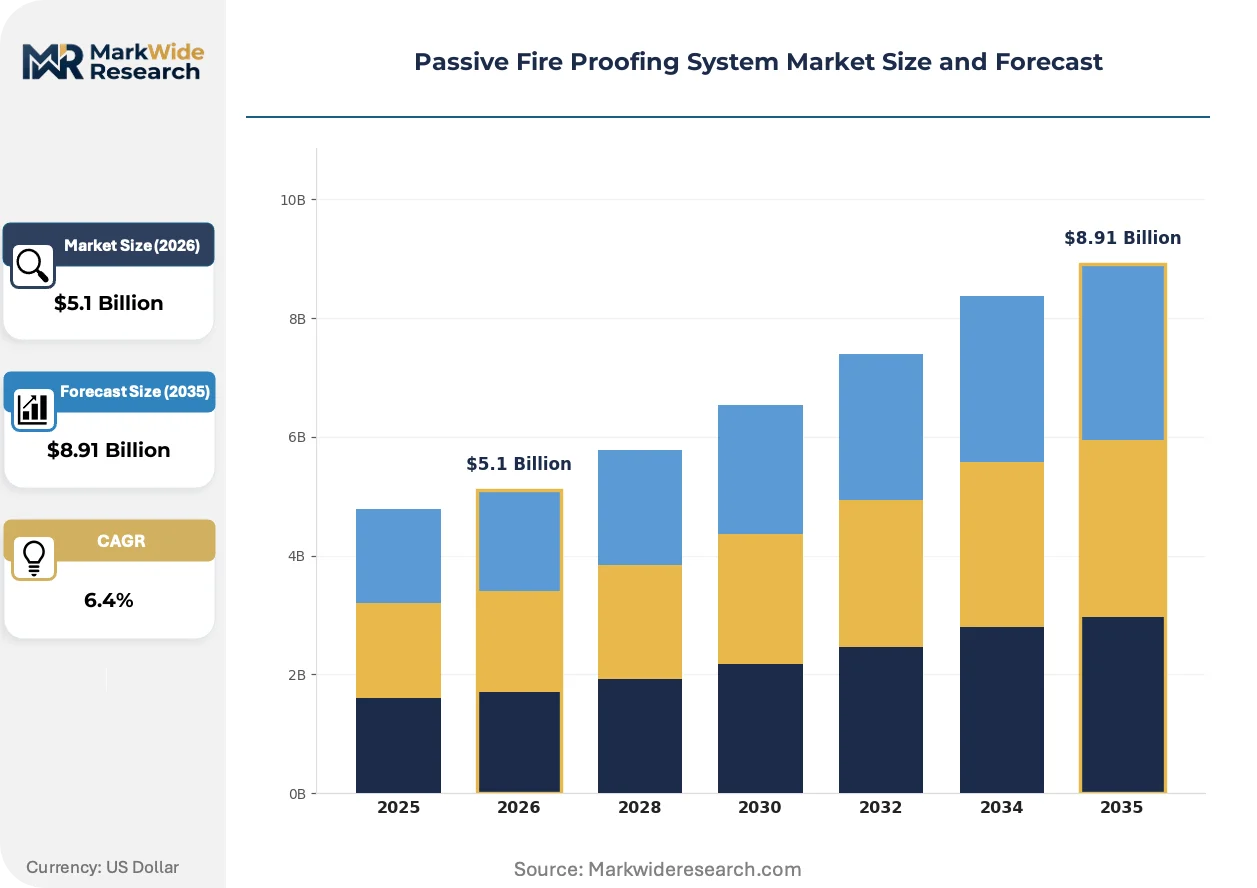
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $8.91 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Board, Coating, Spraying, Mortar Application: Industrial, Commercial, Residential, Infrastructure End User: Construction, Oil & Gas, Manufacturing, Transportation Material: Gypsum, Cementitious, Intumescent, Mineral Fiber |
| Companies Covered | AkzoNobel, Etex Group, 3M, PPG Industries, The Sherwin-Williams Company, Hilti Group, Sika AG, Specified Technologies Inc., Rockwool International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passive Fire Proofing System Market Emerging Trajectories
Material science advances and regulatory digitization are converging to compress product development cycles while expanding performance verification methods beyond traditional furnace testing.
Thin-film intumescent coatings with sub-3mm dry-film thickness are expanding into transportation infrastructure where weight constraints previously excluded passive fire protection. Rail operators in France and Spain now specify these systems for aluminum vehicle bodies. The technology is expanding into markets previously served by heavy cementitious sprays, enabling fuel efficiency gains alongside fire safety compliance.
CE marking digitalization under the EU Construction Products Regulation now permits electronic performance declarations linked to QR-coded product labels. Member state market surveillance authorities scan these codes during site inspections. German federal state building regulators have piloted blockchain-anchored test reports to combat documentation fraud in high-rise projects.
Asset owners increasingly bundle fireproofing specification with structural steel procurement packages, transferring material selection risk to fabricators. This consolidation concentrates decision authority with tier-one engineering contractors in the UK and Netherlands. Dutch infrastructure agencies now require design-build contractors to warrant fire-resistance performance for 25-year asset lifecycles.
Passive Fire Proofing System Market Segmentation
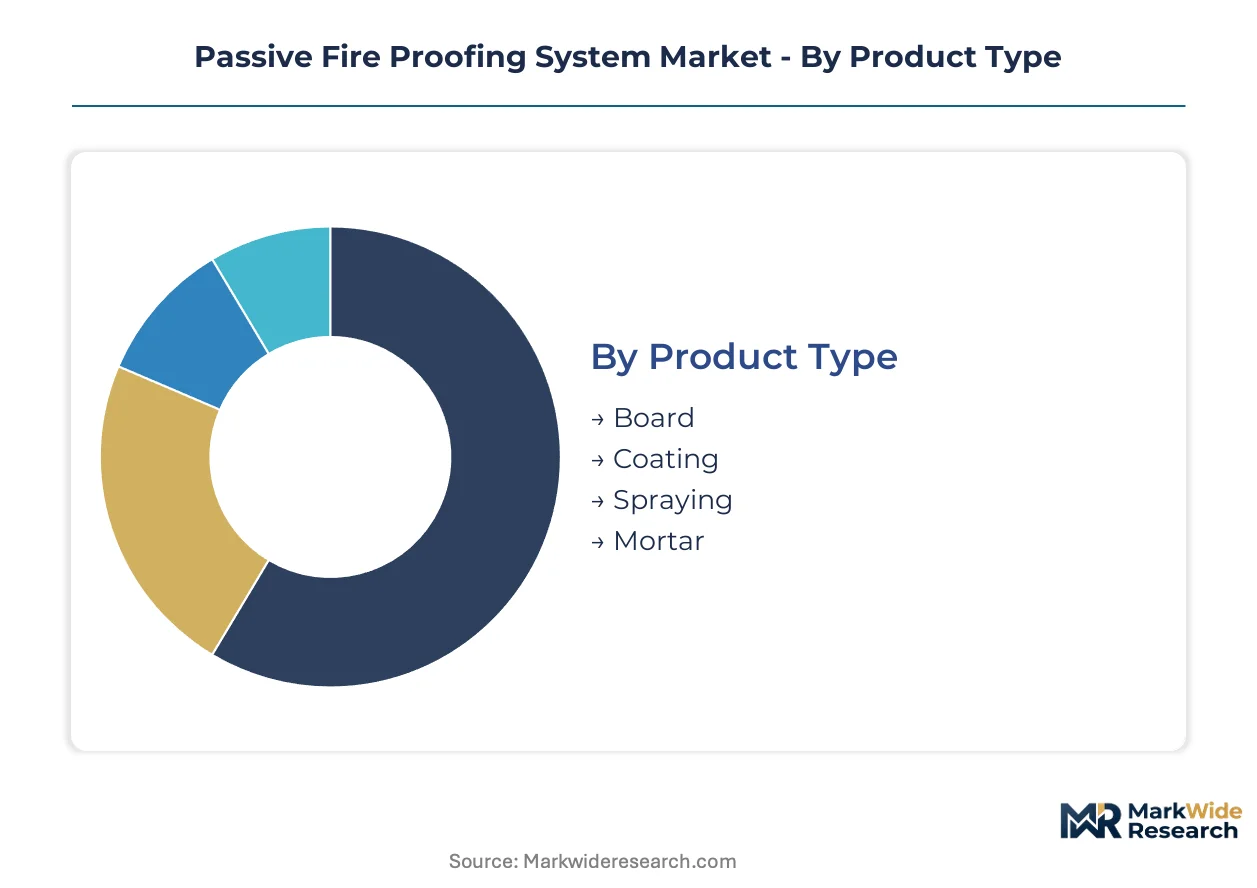
Segmentation in passive fire proofing reveals divergent margin profiles across material chemistry and application method. Coatings command retrofit premiums while board systems anchor new-build specifications. End-user concentration in data centers and infrastructure tunnels reshapes product mix priorities for manufacturers.
Product Type:
Coatings dominate retrofit volume at thinner margins, while boards capture integrated assembly premiums in commercial construction.
- Coating:Intumescent and cementitious formulations spray or roll onto structural steel substrates. Demand concentrates in German data center retrofits where hyperscale operators mandate two-hour fire ratings on existing frameworks. REACH-compliant phosphorus chemistry sustains activation thresholds despite ECHA substance restrictions.
- Board:Gypsum and mineral fiber panels affix to compartmentalization assemblies and steel encasements. UK high-rise residential projects under Building Safety Regulator gateway compliance drive specification intensity in London and Manchester. Digital specification platforms now embed fire-resistance ratings directly into structural steel takeoffs.
- Spraying:Wet-applied cementitious or fibrous materials form monolithic barriers on complex geometries.
- Mortar:Trowel-grade compounds fill penetrations and construction joints in concrete substrates.
Today's leader: Coating. Tomorrow's challenger: Board.
Application:
Industrial sites prioritize durability under mechanical stress, while infrastructure projects demand lightweight solutions for transit corridors.
- Industrial:Heavy manufacturing and petrochemical facilities specify thick-film cementitious systems for blast and abrasion resistance. Oil and gas platforms in the North Sea favor these materials despite weight penalties exceeding 35 kg/m² on offshore decking.
- Infrastructure:Tunnels, bridges, and transit corridors require thin-film intumescent coatings with sub-3mm dry-film thickness. French and Spanish rail operators now specify these systems for aluminum vehicle bodies where fuel efficiency gains matter alongside fire safety.
- Commercial:Office towers and retail complexes balance aesthetic concealment with code compliance.
- Residential:High-rise apartments face intensified third-party testing obligations before construction commencement.
Industrial maintains volume leadership. Infrastructure climbs fastest on transportation electrification.
End User:
Construction procurement consolidates decision authority with tier-one engineering contractors, while oil and gas retains specialized applicator networks.
- Construction:General contractors and steel fabricators bundle fireproofing with structural procurement packages. Dutch infrastructure agencies now require design-build contractors to warrant fire-resistance performance for 25-year asset lifecycles.
- Transportation:Electric vehicle OEMs specify aerogel-composite wraps alongside traditional intumescent mats for battery enclosure thermal runaway containment.
- Oil & Gas:Offshore and downstream facilities demand certified applicators with EN 1090-2 execution class 3 welding inspection credentials.
- Manufacturing:Automotive and aerospace plants require rapid-cure systems to minimize production downtime during facility upgrades.
Construction anchors current demand. Transportation reshapes material innovation priorities.
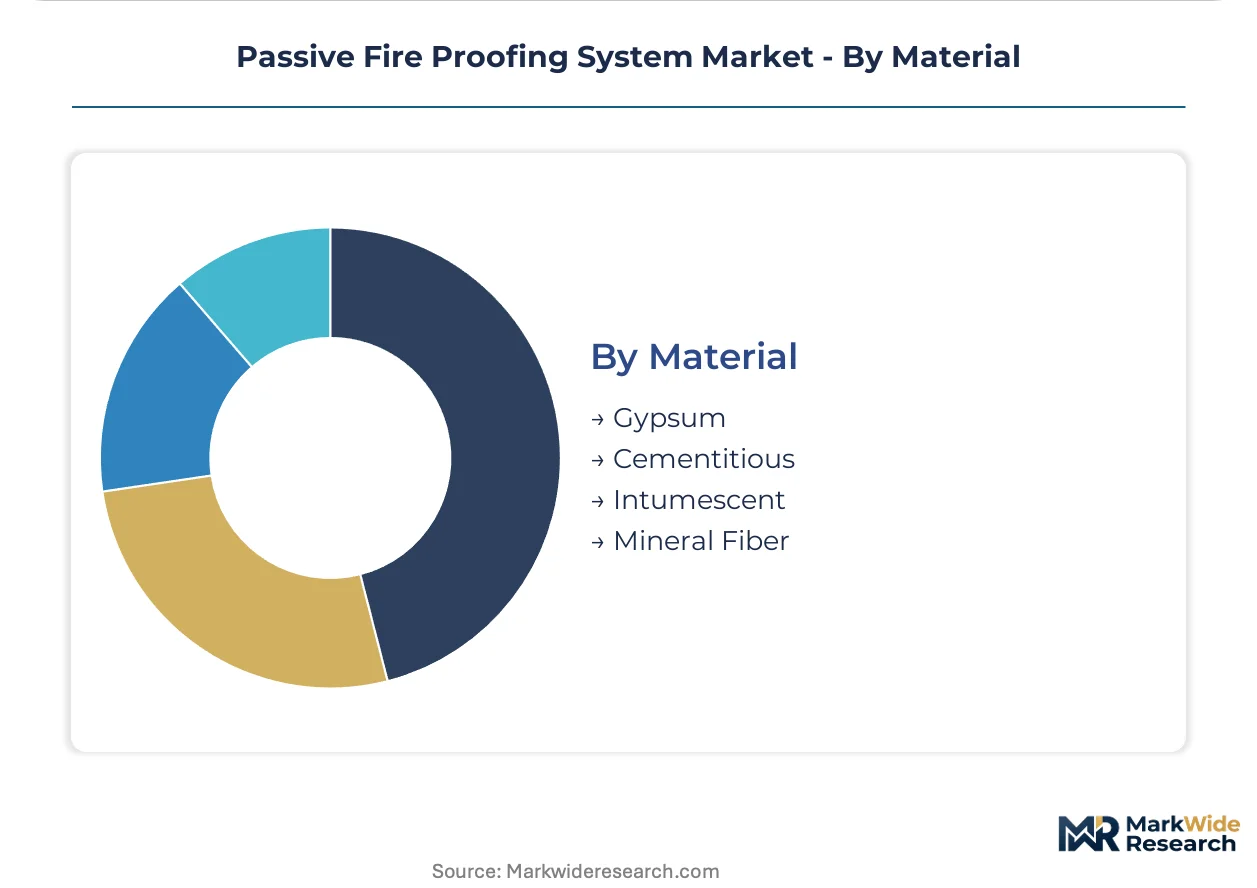
Material:
Intumescent chemistry commands R&D investment, while mineral fiber retains cost advantages in bulk infrastructure.
- Intumescent:Expandable coatings char and foam at 350°C activation thresholds to insulate steel. Reformulated phosphorus-based systems displace traditional cementitious options where weight reduction and thin-film performance are prioritized.
- Mineral Fiber:Rock wool and slag wool boards provide non-combustible insulation for tunnel linings and ductwork. Supply concentrates with specialized producers serving infrastructure corridors across Germany and the Benelux.
- Cementitious:Dense spray-applied mortars offer lowest material cost but impose structural load constraints.
- Gypsum:Calcium sulfate boards integrate with standard drywall assemblies in commercial interiors.
Intumescent captures specification upgrades. Mineral fiber defends volume in public infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production footprints as manufacturers relocate testing and formulation activities toward jurisdictions with streamlined CE marking pathways. Cost-of-compliance gaps between member states with divergent Notified Body densities are accelerating this migration.
Germany
Hyperscale data center construction in Frankfurt and Berlin drives specification intensity for two-hour fire-rated steel frameworks. The federal state building regulations mandate third-party verification for high-rise residential projects. Industrial clusters in North Rhine-Westphalia concentrate intumescent coating formulation capacity serving Dutch and Belgian cross-border demand.
United Kingdom
Gateway compliance under the Building Safety Regulator compresses project timelines for London and Manchester high-rise residential schemes. The UK Building Regulations Part B amendments intensify third-party testing obligations before construction commencement. Steel fabricators in the Midlands bundle fireproofing procurement with structural packages to transfer material selection risk.
France
Rail infrastructure electrification creates demand for thin-film intumescent systems on aluminum vehicle bodies. ANSM market surveillance protocols align with EU Construction Products Regulation enforcement timelines. Manufacturing activity clusters around Lyon and Grenoble serve Alpine transit corridor tunnel projects with sub-3mm dry-film specifications.
Netherlands
Design-build contractors face 25-year fire-resistance performance warranties on infrastructure assets awarded by Dutch transport agencies. REACH-compliant phosphorus chemistry reformulation sustains activation thresholds despite ECHA substance restrictions. The Randstad urban corridor concentrates specification authority with tier-one engineering contractors bundling fireproofing with steel procurement.
Poland
EU energy renovation loan eligibility expansion to fire safety upgrades unlocks Warsaw and Krakow commercial retrofit demand for board compartmentalization systems. The country's national building regulator harmonizes testing protocols with EN standards ahead of full CE marking alignment. Silesian industrial zones absorb manufacturing investment from German producers seeking labor cost advantages.
Passive Fire Proofing System Market Vendor Landscape
Portfolio diversification dominates the current landscape as incumbents extend from core coating or insulation platforms into adjacent fireproofing categories. The vendor base organizes around three strategic archetypes: diversified chemical conglomerates with intumescent R&D pipelines, specialized mineral fiber producers serving infrastructure tunnels, and construction-focused distributors with specification influence. Capacity expansion and M&A activity represent the primary competitive vectors, with players acquiring regional applicator networks to secure EN 1090-2 certified installation capacity.
Among diversified chemical conglomerates, AkzoNobel and Sika AG exemplify the R&D-intensive archetype, anchoring positions through formulation expertise and European commercial retrofit program participation. Rockwool International occupies the specialized mineral fiber tier, representing supply concentration for tunnel and transit corridor projects. These three entities illustrate the competitive structure: chemical-led innovation versus material-led infrastructure volume versus distribution-led specification capture.
| Leading Market Players |
|---|
| AkzoNobel |
| Etex Group |
| 3M |
| PPG Industries |
| The Sherwin-Williams Company |
| Hilti Group |
| Sika AG |
| Specified Technologies Inc. |
| Rockwool International |
| Others |
Supply Flow & Price Mechanics
Data center procurement consolidation in Germany and the Netherlands forces coating manufacturers to absorb certification cost inflation while defending specification slots against mineral fiber alternatives. This buyer-side leverage compresses formulation margins and accelerates backward integration into phosphorus-based chemistry supply.
Pricing Analysis
Distributor markups on intumescent coatings range between premium CE-marked formulations and economy-grade cementitious alternatives. Price differentiation hinges on EN 13381-8 certification tier and applicator training bundling. Cost compression in the cementitious segment is intensifying because dense mortar transport penalties erode landed costs. Tier-one engineering contractors in Dutch infrastructure tenders show lowest price sensitivity due to 25-year performance warranty requirements.
Supply Chain Analysis
Refurbishment flows for spent intumescent coatings remain minimal, though steel substrate recovery from decommissioned commercial buildings feeds secondary raw material channels. Supply concentrates in Germany, the Netherlands, and Poland for formulation and board fabrication. Raw material dependencies include ammonium polyphosphate, epoxy resins, and mineral wool feedstock. Single-source vulnerability sits with REACH-compliant phosphorus chemistry suppliers facing ECHA substance restriction timelines. Distribution runs through specialized construction distributors with EN 1090-2 certified applicator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder where regulatory ratchet effects in EU member states generate recurring retrofit demand and specification upgrade cycles.
For Market Incumbents: Anticipate substitution pressure from aerogel-composite thermal barriers in electric vehicle battery enclosures by securing early OEM validation partnerships. Deepen backward integration into phosphorus-based expandables to insulate margins from petrochemical input volatility. Prioritize EN 1090-2 certified applicator network acquisition in Central Europe where labor scarcity commands wage premiums. For New Entrants and Emerging Players: The UK Building Safety Regulator gateway compliance in England opens a window for third-party testing service bundling with coating supply. Target Polish commercial retrofit demand in Warsaw and Krakow where EU energy renovation loan eligibility expansion meets fire safety upgrade mandates. Pursue digital specification platform partnerships to embed fire-resistance ratings directly into structural steel takeoff workflows. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized mineral fiber producers serving Alpine and Scandinavian tunnel infrastructure corridors. Long-term viability rests on 25-year asset lifecycle warranty structures transferring from public agencies to design-build contractors. Monitor EN 13381-8 testing facility capacity expansion announcements as inflection indicators for certification bottleneck relief.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphorus Chemistry | Captive supply of REACH-compliant expandables insulates margins from ECHA restriction volatility. |
| EN 1090-2 Certified Applicator Network Acquisition | Execution class 3 welding inspectors with fireproofing specialization command 40% wage premiums in Central Europe. |
| Digital Specification Platform Partnership | Building information modeling plugins embedding fire-resistance ratings shorten consultant decision cycles. |
| Aerogel-Composite R&D Investment | Thermal runaway containment specifications from electric vehicle OEMs reshape material innovation priorities. |
| 25-Year Performance Warranty Structuring | Dutch infrastructure agency requirements transfer material selection risk to design-build contractors. |
Methodological Framework
Coverage spans Germany, the United Kingdom, France, the Netherlands, and Poland, with primary inputs from each market cluster. The analysis combines interviews with fireproofing applicators, structural steel fabricators, and regulatory compliance officers alongside secondary validation through EU Construction Products Regulation filings, EN standard test reports, and national building code amendments. Bottom-up project pipeline tracking triangulates with top-down construction spend forecasts.
Granularity extends to product type, application method, end-user industry, and material chemistry across the projection horizon. Segment-level CAGRs derive from installation volume modeling tied to data center construction permits, high-rise residential gateway approvals, and infrastructure tender awards. Industry-specific forecast inputs include EN 13381-8 certification queue lengths and REACH substance restriction implementation timelines.
Revisions become necessary when ECHA expands phosphorus-based chemistry restrictions or when EU member states accelerate CE marking harmonization beyond current enforcement trajectories. Forecasts reflect assumptions about testing facility capacity, applicator certification availability, and raw material supply continuity. Practitioners should monitor EN Notified Body expansion announcements and petrochemical index volatility for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Europe Fire-Resistant Glass Market
Fire Safety & Protection
China Thermal Protector Market
Fire Safety & Protection
Heptafluoropropane Fire Suppression System Market
Fire Safety & Protection
Wireless Fire Detection Systems Market
Fire Safety & Protection
Marine Fire Extinguishing System Market
Fire Safety & Protection
Fire and Rescue Helmets Market
Fire Safety & Protection
Global Portable Foam Fire Extinguisher Market
Fire Safety & Protection
Global Fire Barrier Sealant Market
Fire Safety & Protection
Smoke and Carbon Monoxide Alarm Market
Fire Safety & Protection
Fire Rated Cables Market
Fire Safety & Protection
Fire Alarm and Detection System Market
Fire Safety & Protection
Global Flame Detector Market
Fire Safety & Protection
Fire Resistant Silicone Sealant Market
Fire Safety & Protection
Fire Extinguisher Inspection Services Market
Fire Safety & Protection
Fire Suppression Market
Fire Safety & Protection
Fire Protection Systems for Industrial Cooking Market