
 Global Biometric Card Market | 2026-2036
Global Biometric Card Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biometric Card Market Foresight
Southeast Asia is fragmenting into multiple competing manufacturing clusters for biometric card assembly. Fingerprint Cards AB leverages its sensor miniaturization expertise to dominate thin-film fingerprint module supply. IDEX Biometrics anchors off-chip sensing architectures that reduce power draw for contactless transactions. Thales Group competes through end-to-end secure element integration from silicon to personalization.
Biometric cards embed live-scanned physiological identifiers into ISO/IEC 7810-compliant card bodies, typically combining a capacitive or ultrasonic fingerprint sensor with a secure microcontroller operating at sub-10 milliwatt power budgets for contactless NFC activation. The primary commercial purpose is to eliminate stolen-card fraud by binding possession to biometric verification at the point of transaction. Fingerprint recognition occupies the dominant authentication technology slot due to mature sensor cost curves and consumer familiarity. Contactless card types are capturing the fastest growth as transit and retail infrastructure migrates to tap-to-pay protocols. Payment security applications concentrate the deepest margin pools because issuers absorb premium unit costs to reduce chargeback liability.
FCC certification in the United States, CE marking under the EU Radio Equipment Directive, and BIS compliance mandates in India each shape product access by imposing electromagnetic compatibility and data security testing regimes. EBA guidelines on strong customer authentication under PSD2 compel European issuers toward biometric verification for remote transactions. Stakeholders must monitor how central bank digital currency pilots reshape card-based payment infrastructure and whether biometric data localization laws proliferate beyond current GDPR and Indian DPDP Act boundaries.
Market Dynamics
The migration from PIN-based to biometric authentication at point-of-sale terminals is compressing card issuance cycles and forcing secure element suppliers to reconfigure power architectures for sub-10 milliwatt NFC activation.
Growth Catalysts
- PSD2 Strong Customer Authentication:EBA guidelines compel European issuers to deploy biometric verification for remote transactions, accelerating replacement of legacy contact-only cards.
- South Korea Digital ID Infrastructure:National digital ID programs are driving contactless biometric card deployment through coordinated public-private pilot schemes.
- Ultrasonic Sensor Maturation:Advances in piezoelectric fingerprint sensing are enabling enrollment through card packaging without separate biometric terminals.
Market Restraints
- Secure Element Concentration:Three foundries in Taiwan and South Korea control advanced EEPROM fabrication for payment microcontrollers, creating single-source vulnerability.
- Biometric Data Localization:India's DPDP Act and GDPR Article 9 restrictions impose fragmented data residency requirements that multiply personalization facility costs.
- Cost Premium Over EMV:Biometric card bill-of-materials remains 4-6x standard chip cards, limiting issuer willingness to absorb unit costs for mass-market segments.
Strategic Opportunities
- Transit-Retail Convergence:Open-loop fare systems in London, Singapore, and Tokyo are creating dual-use biometric cards that merge transit credentials with payment rails.
- Central Bank Digital Currency Bridges:CBDC pilot programs in China and the European Union are testing biometric hardware wallets as offline-capable digital currency interfaces.
- ISO/IEC 24787 Compliance:New biometric data protection standards are creating first-mover certification advantages for card personalization bureaus.
Industry Challenges
- Enrollment Infrastructure Gap:Retail banks lack in-branch biometric capture terminals, forcing reliance on mailed activation kits with elevated failure rates.
- Legacy POS Integration:Older contactless readers in the United States and Germany require firmware updates to recognize biometric card authentication sequences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biometric Card Market |
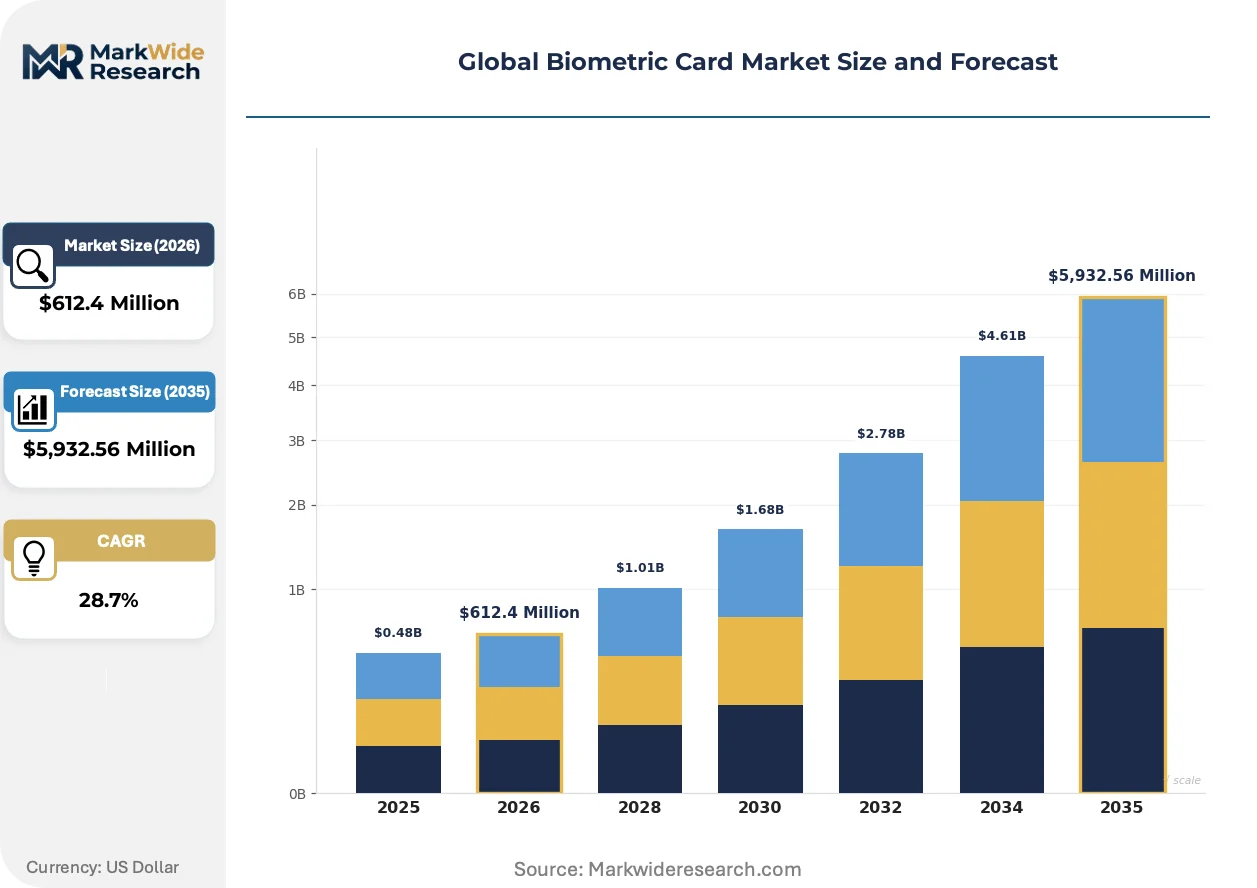
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $5,932.56 Million |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Authentication Technology: Fingerprint Recognition, Iris Scanning, Voice Recognition, Facial Recognition, Vein Pattern Card Type: Contact, Contactless, Hybrid, Dual Interface, Magnetic Stripe Application: Access Control, Payment Security, Identity Verification, Time & Attendance, Government ID End User: Financial Institutions, Secure Facilities, Telecom Providers, Educational Institutions, E-Government |
| Companies Covered | Visa Inc., Fingerprint Cards AB, IDEX Biometrics, IDEMIA Group, STMicroelectronics NV, Zwipe, Mastercard, KONA I Co. Ltd., Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biometric Card Market Shifts & Advancements
Sensor miniaturization and secure element integration are converging to enable biometric cards that function without battery augmentation, eliminating the last barrier to mass contactless deployment.
Ultrasonic fingerprint sensing is collapsing the enrollment barrier that previously required dedicated biometric terminals at bank branches. Transit authorities in London and Singapore are piloting dual-credential cards that authenticate riders through live-scanned fingerprints rather than prepaid balances. The technology is collapsing the distinction between transit and payment credentials, forcing card issuers to redesign secure element memory allocation for multi-applet architectures.
CE marking under the EU Radio Equipment Directive now mandates electromagnetic compatibility testing for biometric sensor modules alongside traditional payment chip certification. German and French regulators are interpreting biometric data processing through national data protection authorities with divergent consent requirements. This regulatory fragmentation is compelling module suppliers to maintain parallel firmware tracks for different European markets.
Corporate treasury departments are consolidating card issuance across travel, procurement, and fleet functions into unified biometric credential programs. Issuers in the United States are responding with volume-based pricing that undercuts per-card costs for enterprise accounts above ten thousand units. This concentration is most visible among Fortune 500 companies seeking to eliminate expense report fraud through biometric transaction binding.
Global Biometric Card Market Segmentation
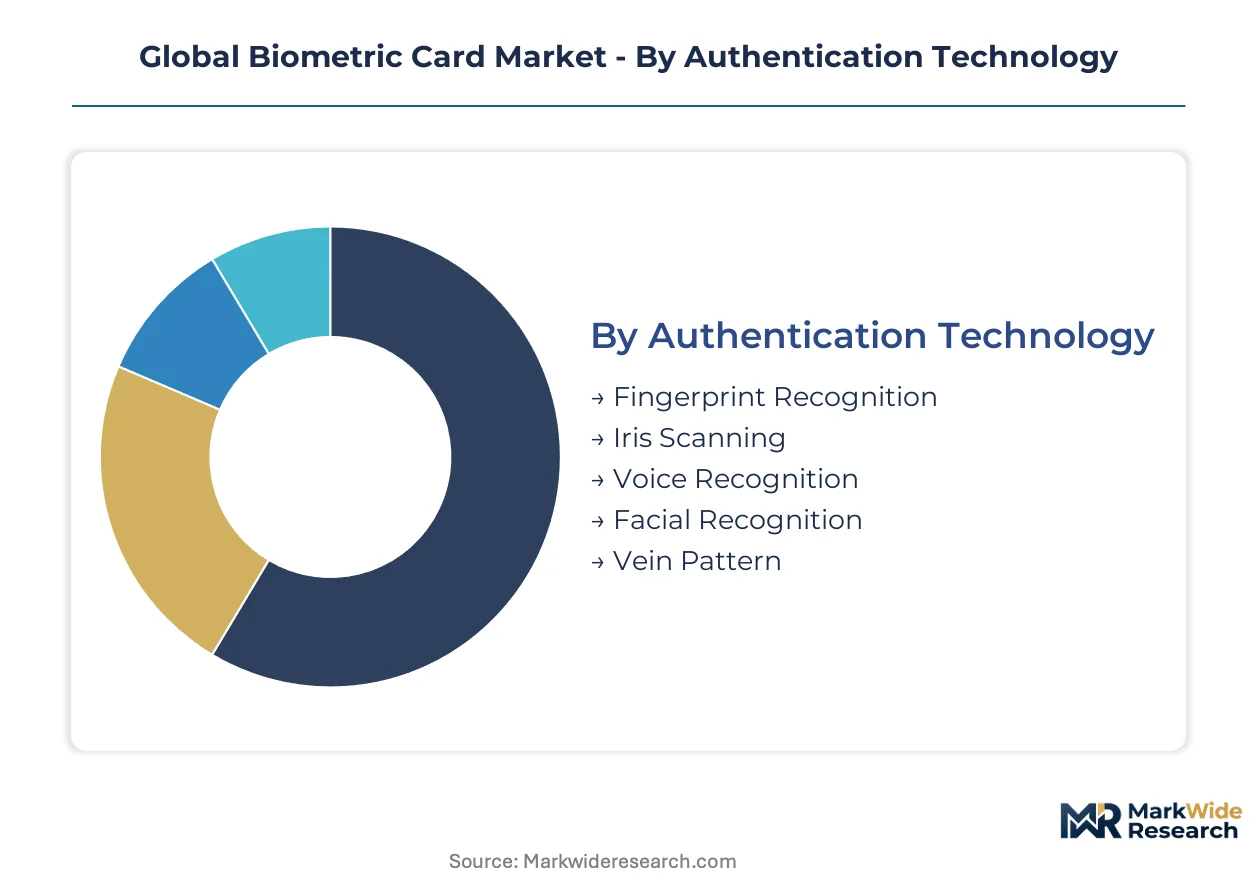
Biometric card segmentation reveals how authentication modalities, interface standards, and institutional procurement patterns fragment addressable demand across radically different cost structures and compliance regimes.
Authentication Technology:
Cost tier stratification separates mature capacitive fingerprint modules from emerging multimodal architectures requiring premium secure element integration.
- Fingerprint Recognition:Capacitive and ultrasonic sensors capture ridge patterns through ISO/IEC 7810 card substrates at sub-dollar unit economics. European payment issuers concentrate procurement here, driven by EBA PSD2 strong customer authentication mandates for remote transactions.
- Iris Scanning:Near-infrared cameras embedded in card bodies capture unique stromal patterns with false acceptance rates below one in one million. Demand clusters in Gulf Cooperation Council national ID programs where biometric data localization laws favor on-card template storage.
- Voice Recognition:Microphone arrays and neural processing engines authenticate users through spoken passphrases.
- Facial Recognition:Miniaturized camera modules and 3D structured light projectors enable contactless identity verification.
- Vein Pattern:Near-infrared transillumination maps subcutaneous vascular networks for liveness detection.
Fingerprint recognition commands the established base. The steepest expansion runs through iris scanning architectures.
Card Type:
Interface selection determines power budgets, antenna geometries, and backward compatibility requirements across legacy POS infrastructure.
- Contactless:NFC-enabled cards operating at 13.56 MHz with passive electromagnetic coupling eliminate battery dependence through harvested RF energy. South Korea's digital ID pilots and London transit open-loop fare systems drive volume procurement.
- Contact:ISO/IEC 7816-compliant cards with physical chip terminals persist in markets with high legacy ATM penetration.
- Hybrid:Dual-protocol cards supporting both contact and contactless interfaces through multiplexed secure elements.
- Dual Interface:Unified antenna and chip architectures with automatic protocol selection based on terminal capability.
- Magnetic Stripe:Legacy-backward cards incorporating biometric authentication alongside traditional magnetic encoding for transitional markets.
Contact cards retain the installed base. Contactless variants are climbing the fastest as transit-retail convergence accelerates tap-to-pay migration.
Application:
Maturity gradients separate regulated payment security from emerging government ID deployments with divergent certification timelines.
- Payment Security:EMV-compliant cards bind biometric verification to transaction authorization through integrated secure microcontrollers. Financial institutions in Germany and France absorb 4-6x unit cost premiums to reduce chargeback liability under PSD2.
- Government ID:National digital identity credentials with ICAO-compliant biometric data structures. India's BIS certification mandates and DPDP Act data localization requirements shape personalization facility location decisions.
- Access Control:Corporate and facility entry credentials with offline biometric matching.
- Identity Verification:Portable credentials for remote onboarding and KYC compliance.
- Time & Attendance:Workforce management cards with tamper-evident biometric logging.
Payment security commands the revenue concentration. Government ID applications are expanding most quickly through national digital infrastructure programs.
End User:
Customer type fragmentation reflects procurement scale disparities between centralized government tenders and distributed enterprise deployments.
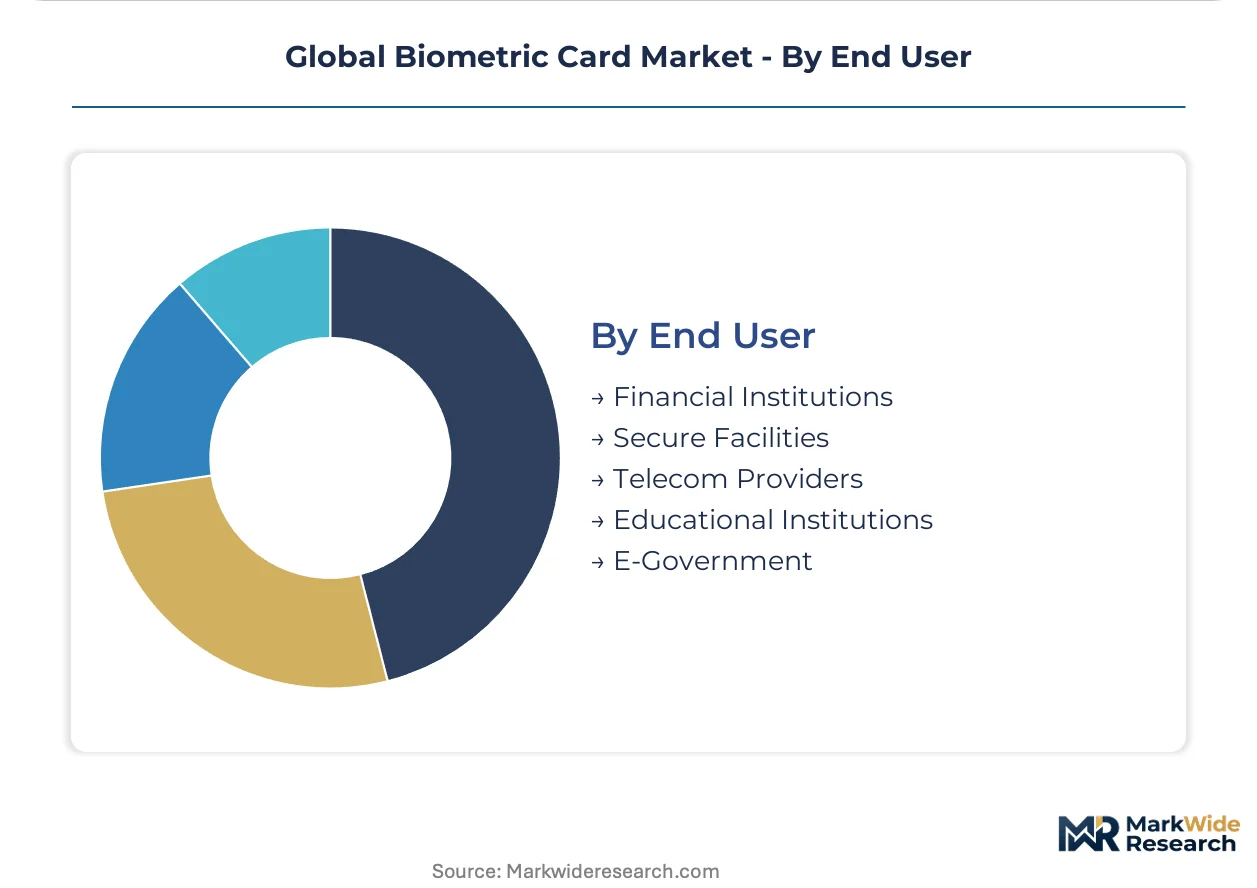
- Financial Institutions:Tier-1 banks and card networks issuing payment credentials with integrated biometric verification. Enterprise procurement consolidation across travel, procurement, and fleet functions drives volume-based pricing negotiations.
- E-Government:National digital ID authorities procuring citizen credentials at million-unit scale. South Korea's coordinated public-private pilot schemes establish deployment templates.
- Secure Facilities:Corporate campuses and critical infrastructure operators with custom access control requirements.
- Telecom Providers:Mobile network operators integrating biometric SIM and identity functions.
- Educational Institutions:Universities and school systems deploying campus-wide credential systems.
Financial institutions anchor procurement volume. E-government deployments are gaining share fastest through sovereign digital identity mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC certification requirements in the United States anchor the most stringent electromagnetic compliance regime for biometric card deployment. South Korea's national digital ID infrastructure and India's BIS mandates collectively shape procurement patterns across the three dominant deployment geographies.
United States
Financial institutions in New York and Chicago are consolidating enterprise card programs across travel and procurement functions. FCC Part 15 certification for NFC-enabled biometric modules imposes electromagnetic compatibility testing that extends product launch timelines by 8-12 weeks. Silicon Valley sensor developers are partnering with Atlanta-based personalization bureaus to streamline domestic enrollment infrastructure.
South Korea
Seoul's coordinated public-private pilot schemes are driving the fastest contactless biometric card deployment globally. The MFDS framework for biometric data protection aligns with national digital ID program requirements for on-card template storage. Busan-Ulsan manufacturing clusters are specializing in thin-film fingerprint module assembly for export markets.
Germany
Bundesbank oversight and KBA data protection interpretations are creating divergent consent requirements across federal states. Frankfurt payment processors are absorbing 4-6x unit cost premiums to satisfy PSD2 strong customer authentication mandates. Munich-based secure element integrators are reconfiguring power architectures for sub-10 milliwatt NFC activation thresholds.
India
BIS compliance mandates for electromagnetic compatibility and the DPDP Act's biometric data localization requirements are reshaping personalization facility location decisions. Mumbai and Bangalore card bureaus are expanding capacity to handle million-unit government ID tenders. Telangana's emerging electronics manufacturing corridor is attracting sensor module assembly investments.
United Kingdom
London transit authority open-loop fare systems are piloting dual-credential biometric cards merging transit credentials with payment rails. FCA guidelines on strong customer authentication are accelerating replacement of legacy contact-only cards. Cambridge sensor developers are advancing ultrasonic fingerprint sensing for enrollment through card packaging.
Global Biometric Card Market Competitive Landscape
Capability concentration sits with sensor miniaturization specialists; scale advantage sits with secure element integrators and payment network operators. The vendor base separates into three tiers: semiconductor foundries controlling EEPROM fabrication, module suppliers dominating thin-film sensor assembly, and end-to-end platform providers managing personalization at scale. Strategic moves center on backward integration into secure microcontroller supply and technology licensing agreements that bypass foundry concentration risks.
Among Nordic sensor specialists, Fingerprint Cards AB and IDEX Biometrics exemplify divergent technical approaches to biometric card architecture. Thales Group anchors the European tier of end-to-end secure element integrators. Visa Inc. and Mastercard occupy positions as payment network orchestrators that determine certification requirements and issuer procurement specifications.
| Leading Market Players |
|---|
| Visa Inc. |
| Fingerprint Cards AB |
| IDEX Biometrics |
| IDEMIA Group |
| STMicroelectronics NV |
| Zwipe |
| Mastercard |
| KONA I Co. Ltd. |
| Thales Group |
| Others |
Supply & Pricing Matrix
Overcapacity in Taiwanese secure element foundries is compressing wafer pricing and forcing EEPROM suppliers to absorb certification costs rather than pass them downstream, reshaping margin allocation across the biometric card value chain.
Pricing Analysis
European issuers absorb 4-6x unit cost premiums over standard EMV cards while Indian government tenders negotiate volume discounts below commercial banking rates. Three-tier pricing structure across premium, standard, and economy levels separates PSD2-compliant dual-interface cards from single-protocol transit credentials and legacy contact-only variants. Cost compression in the mid-tier is intensifying because South Korean module suppliers are flooding export markets with thin-film fingerprint sensors. Enterprise procurement teams at Fortune 500 companies show the lowest price sensitivity, while mass-market retail banks in Southeast Asia resist premium absorption.
Supply Chain Analysis
Tariff exposure between Taiwan and mainland China dominates supply chain risk planning for EEPROM fabrication, with module assemblers in South Korea and Vietnam positioning as alternative sourcing nodes. Secure microcontroller production draws from TSMC and Samsung foundries, while capacitive sensor supply rests on Fingerprint Cards AB and IDEX Biometrics wafer-level packaging capacity. Single-source vulnerability concentrates in advanced EEPROM nodes below 40nm. Distribution runs through certified personalization bureaus in Frankfurt, Mumbai, and Atlanta that handle enrollment infrastructure and EMV compliance testing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among tier-1 financial institutions consolidating enterprise card programs across travel, procurement, and fleet functions, compressing supplier margins and forcing volume-based pricing concessions.
For Market Incumbents: Entrench position through captive supply of secure microcontrollers by acquiring EEPROM design houses or forging exclusive foundry allocations, countering the threat of South Korean module suppliers backward integrating into chip design. Prioritize certification investment for ISO/IEC 24787 biometric data protection standards to create switching costs for European issuers. For New Entrants and Emerging Players: Transit-retail convergence in Southeast Asian open-loop fare systems represents the most penetrable entry point, with Bangkok and Jakarta authorities piloting dual-credential biometric cards lacking incumbent supplier relationships. Target corporate treasury departments seeking unified credential programs through direct SaaS-based enrollment platforms that bypass legacy bank branch infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-attachment play because biometric card deployment scales with national digital ID program mandates and CBDC hardware wallet pilots. Acquisition target archetype: sensor module specialists with ultrasonic fingerprint IP and existing EMV certification. The signal to watch is central bank digital currency pilot announcements specifying offline-capable biometric authentication.| Strategic Initiative | Industry Significance |
|---|---|
| Secure Element Backward Integration | Captive EEPROM supply insulates against Taiwan foundry concentration and enables margin capture. |
| Ultrasonic Sensor Certification | Enrollment-through-packaging capability eliminates branch infrastructure dependency for European issuers. |
| Transit Authority Partnership | Dual-credential pilot wins in London and Singapore establish reference architectures for open-loop fare systems. |
| CBDC Hardware Wallet Development | Offline-capable biometric authentication aligns with European Central Bank and People's Bank of China pilot specifications. |
| Personalization Bureau Expansion | DPDP Act compliance in India and GDPR Article 9 restrictions require localized enrollment facility investment. |
Research Methodology
Initial hypotheses were tested against primary input from secure element procurement directors, biometric sensor R&D leads, EMV certification engineers, and government ID program managers and refined through secondary validation against SEC filings from payment network operators, BIS compliance bulletins, and EBA PSD2 implementation reports. Bottom-up triangulation across module supplier bill-of-materials data and top-down reconciliation against card network shipment disclosures anchored volume estimates.
Demand-supply balance framing shaped the analytical framework, with segmentation dimensions spanning authentication technology, card interface protocol, application vertical, and end-user procurement scale across the analysis window. CAGRs were derived from logistic diffusion curves fitted to EMV compliance deadlines and national digital ID program timelines, with inputs from foundry capacity utilization rates and transit infrastructure upgrade cycles.
Macroeconomic conditions sit as an overlay; deviation in central bank interest rate trajectories or sovereign debt funding for digital ID programs would shift the trajectory of issuer procurement cycles. Forecasts reflect assumptions about EMV terminal penetration and biometric data localization law proliferation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Military Biometrics Market
Biometrics & Identity Management
Gait Biometrics Market
Biometrics & Identity Management
North America Biometrics in Government Market
Biometrics & Identity Management
Global Authentication and Brand Protection Market
Biometrics & Identity Management
Global Voice Biometrics Market
Biometrics & Identity Management
Automated Fingerprint Identification Systems (AFIS) Market
Biometrics & Identity Management
Latin America Biometrics Market
Biometrics & Identity Management
Biometric Data Encryption Device Market
Biometrics & Identity Management
Identity Verification Market
Biometrics & Identity Management
Global Biometric-As-A-Service Market
Biometrics & Identity Management
United States Biometrics Market
Biometrics & Identity Management
Global Personal Identity Management Market
Biometrics & Identity Management
Biometrics As a Service in Healthcare Market
Biometrics & Identity Management
Biometric Passport Market
Biometrics & Identity Management
ID Verification Market
Biometrics & Identity Management
Global Human Identification Market