
 Biometrics As a Service in Healthcare Market | 2026-2036
Biometrics As a Service in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Biometrics As a Service in Healthcare Market Intelligence
Asset-light subscription and leasing models for biometric infrastructure is narrowing the competitive field to vendors with cloud-native architectures and scalable API platforms. Thales leverages its defense-sector encryption heritage to anchor high-assurance healthcare deployments. Fujitsu competes through specialized palm-vein recognition systems that sustain superior liveness detection for clinical environments. Imprivata, Inc. dominates physician-workflow authentication, controlling privileged access to electronic health records across integrated delivery networks.
Biometrics As a Service in Healthcare denotes cloud-delivered identity verification systems employing physiological or behavioral characteristics—fingerprint minutiae templates, iris encoding, voiceprint spectrograms, or facial geometry vectors—processed via encrypted APIs rather than on-premise hardware, with primary purpose of authenticating patients and staff while maintaining audit trails for protected health information. Fingerprint recognition occupies the largest installed base due to mature sensor economics and interoperability with existing hospital access control systems, though facial recognition represents the fastest-expanding segment as telemedicine platforms demand contactless authentication for remote consultations. Identity verification services command the deepest margin pools because they integrate directly with payer billing systems and government credential databases, whereas patient monitoring applications remain nascent pending clinical validation of continuous biometric surveillance.
FDA oversight of clinical decision support software intersects with HIPAA security rule mandates from the Department of Health and Human Services, creating dual compliance obligations that shape vendor product roadmaps and hospital procurement criteria. The EU AI Act's risk classification for biometric identification systems will constrain how European health insurers deploy remote authentication, forcing architectural choices that segregate EU patient data processing from other regions. Stakeholders must monitor whether national health regulators begin requiring algorithmic impact assessments for biometric matching systems before granting reimbursement eligibility to providers using these platforms.
Market Dynamics
Cloud-native biometric architectures are compressing deployment timelines for hospital authentication systems while HIPAA audit requirements force providers to outsource identity verification infrastructure rather than maintain on-premise hardware.
Growth Catalysts
- HIPAA Security Rule enforcement:The Department of Health and Human Services mandates audit trails for protected health information access, driving hospital systems toward API-based biometric logging that outsourced platforms deliver more reliably than legacy on-site servers.
- Telemedicine platform expansion:Remote consultation networks require contactless patient verification without physical hardware distribution, creating pull for facial recognition and voiceprint services accessible through standard web browsers.
- Duplicate record elimination mandates:United States hospital systems face financial penalties from payers when billing encounters link to mismatched patient identities, accelerating biometric matching adoption at registration touchpoints.
Market Restraints
- Algorithmic bias liability exposure:Demographic performance variation in facial recognition systems creates malpractice risk for providers deploying unvalidated biometric matching across diverse patient populations.
- Encryption key management complexity:Cloud-based biometric templates require hardware security module integration that few healthcare IT departments possess competency to architect or audit independently.
- Cross-border data residency friction:The EU AI Act's risk classification for biometric identification systems forces architectural segregation of European patient data processing, raising operational costs for multi-region health networks.
Strategic Opportunities
- Continuous physiological monitoring integration:Wearable biometric streams for glucose, cardiac rhythm, and blood oxygenation create authentication-by-continuity models that eliminate explicit verification friction during telemedicine encounters.
- FDA software-as-a-medical-device pathway:The agency's evolving guidance on clinical decision support creates reimbursement eligibility for biometric platforms that demonstrate diagnostic augmentation beyond pure identity verification.
- Behavioral biometrics for opioid prescribing:Keystroke dynamics and gait analysis layered atop physiological verification can flag provider credential compromise in real-time, addressing DEA diversion monitoring requirements.
Industry Challenges
- Biometric template interoperability gaps:Proprietary minutiae encoding from competing vendors prevents template portability across hospital systems, locking providers into single-source relationships and complicating merger integration.
- Liveness detection arms race costs:Deepfake presentation attacks force continuous algorithm retraining and sensor hardware refresh cycles that strain capital planning for mid-sized health networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biometrics As a Service in Healthcare Market |
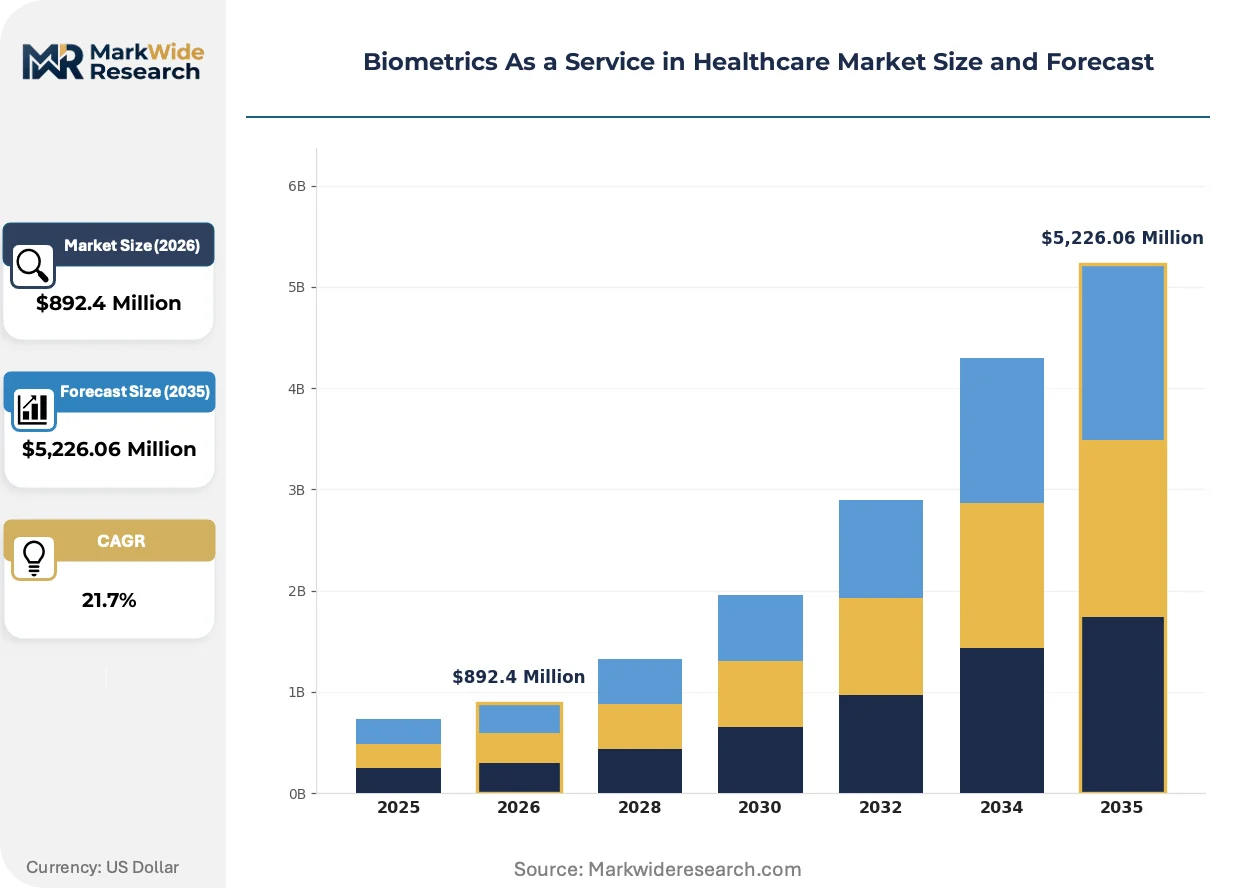
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $5,226.06 Million |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Identity Verification, Access Control, Patient Monitoring, Data Security Technology: Fingerprint Recognition, Facial Recognition, Iris Scanning, Voice Recognition End User: Hospitals, Clinics, Health Insurance Providers, Telemedicine Application: Patient Authentication, Staff Identification, Record Access, Compliance Management |
| Companies Covered | Thales, Fujitsu, Aware, Inc., BIO-key International, Imprivata, Inc., Suprema, NEC Corporation, IDEMIA, M2SYS Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biometrics As a Service in Healthcare Market Strategic Shifts & Innovations
Edge-computing biometric processing is redistributing authentication latency away from centralized cloud infrastructure while zero-trust security frameworks reclassify identity verification from perimeter defense to continuous session validation.
Multimodal biometric fusion is digitizing how hospital systems architect identity assurance. Platforms combining fingerprint minutiae with iris encoding and voiceprint spectrograms reduce false acceptance rates below single-modality thresholds. Integrated delivery networks in the United States are piloting these stacks for surgical suite access control. The technology is digitizing privileged access management by collapsing multiple authentication factors into unified API responses.
The EU AI Act's high-risk system classification for biometric identification is reshaping vendor product roadmaps. European health insurers must now maintain algorithmic impact assessments and human-in-the-loop override capabilities for remote patient authentication. German hospital procurement committees are inserting these compliance requirements into RFP scoring matrices ahead of contract renewals.
Subscription-based authentication service contracts are displacing perpetual license purchases across North American hospital systems. Chief information officers prefer operational expenditure treatment for biometric infrastructure that obsoletes within 36 months. This shift concentrates vendor relationships with cloud-native platform providers capable of absorbing hardware refresh cycles into monthly fees.
Biometrics As a Service in Healthcare Market Segmentation
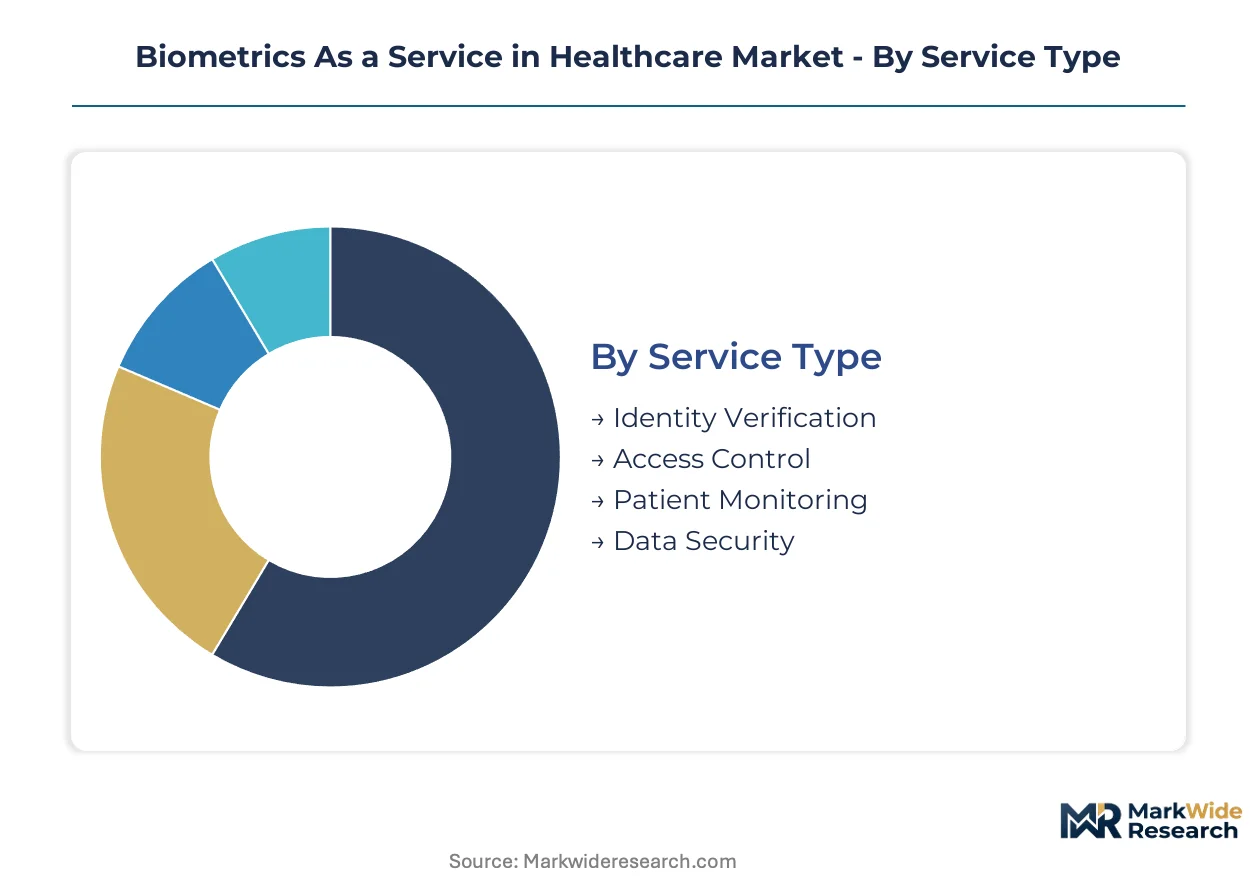
Healthcare organizations deploy biometric services across distinct operational layers, each demanding specialized authentication protocols and compliance architectures. Segmentation reveals how vendor specialization concentrates around high-margin identity workflows versus emerging monitoring applications.
Service Type:
Use cases span from one-time patient onboarding to continuous physiological surveillance, creating divergent margin structures and integration complexity.
- Identity Verification:Cloud-based matching of biometric templates against government credential databases and payer records anchors revenue concentration. United States hospital systems deploy these services at registration desks to eliminate duplicate medical records and prevent insurance fraud.
- Access Control:Privileged authentication for electronic health record systems commands premium pricing through integration with physician workflow platforms. Integrated delivery networks prioritize these deployments to satisfy HIPAA audit trail mandates from the Department of Health and Human Services.
- Patient Monitoring:Continuous biometric streams from wearables remain nascent pending FDA validation of diagnostic algorithms.
- Data Security:Encryption key management and template protection services address hardware security module complexity that healthcare IT departments struggle to architect independently.
The dominant share belongs to Identity Verification, while Patient Monitoring is closing the gap fastest.
Technology:
Modalities differentiate by sensor economics, liveness detection requirements, and compatibility with contactless telemedicine workflows.
- Fingerprint Recognition:Mature minutiae extraction algorithms and interoperable sensor hardware dominate installed base economics. Hospital access control systems leverage existing fingerprint infrastructure for staff authentication at surgical suites and pharmacy vaults.
- Facial Recognition:Contactless capture through standard web browsers enables remote patient verification without hardware distribution. Telemedicine platforms in the United States are driving fastest expansion despite algorithmic bias liability exposure across diverse patient populations.
- Iris Scanning:Superior false acceptance rates justify deployment in high-security clinical environments requiring sterile contactless authentication.
- Voice Recognition:Spectrogram analysis supports hands-free provider authentication during surgical procedures and remote consultation documentation.
Fingerprint Recognition holds the largest installed base, though Facial Recognition exhibits the steepest expansion trajectory.
End User:
Procurement authority and compliance obligations vary sharply across institutional settings, shaping contract structures and implementation timelines.
- Hospitals:Enterprise-scale deployments spanning registration, clinical access, and pharmacy control drive the deepest vendor relationships. United States health systems face mounting pressure from payers to eliminate identity-related billing errors.
- Telemedicine:Platform operators require API-native biometric services that scale across state jurisdictions without hardware logistics. Remote consultation networks prioritize facial and voice modalities for patient verification through consumer devices.
- Clinics:Smaller patient volumes and limited IT staff push these facilities toward fully managed subscription services.
- Health Insurance Providers:Fraud prevention at enrollment and claims processing creates demand for identity verification integrated with government databases.
Hospitals command the dominant procurement volume, while Telemedicine is gaining share fastest.
Application:
Workflow integration determines whether biometric deployments reduce friction or create administrative burden for clinical staff.
- Patient Authentication:Registration desk matching against master patient indices prevents duplicate records that trigger payer penalties. United States hospital systems prioritize these deployments to protect revenue cycle integrity.
- Compliance Management:Automated audit trails for protected health information access satisfy HIPAA Security Rule enforcement from the Department of Health and Human Services. Cloud-based logging outsources infrastructure that hospital IT departments struggle to maintain on-premise.
- Staff Identification:Privileged access management for electronic health records controls credential sharing and session hijacking risks.
- Record Access:Biometric gates at clinical workstation unlocks reduce password fatigue while maintaining granular access logging.
Patient Authentication generates the highest deployment volume, though Compliance Management is climbing the fastest as enforcement intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where HIPAA enforcement drives premium subscription rates, while European vendors absorb compliance cost premiums from the EU AI Act's high-risk system mandates without equivalent pricing recovery.
United States
Hospital systems in Texas and Florida deploy cloud-native biometric platforms to eliminate duplicate medical records triggering payer penalties. The Department of Health and Human Services intensifies HIPAA Security Rule audits on protected health information access trails. The Mayo Clinic in Rochester anchors multi-modal authentication pilots combining facial recognition with voiceprint verification for surgical suite access control.
Germany
University hospitals in Bavaria and North Rhine-Westphalia pilot palm-vein recognition systems for sterile contactless authentication in operating theaters. The EU AI Act forces algorithmic impact assessments and human-in-the-loop override capabilities into procurement scoring matrices. The Charité hospital network in Berlin mandates biometric audit trails for electronic health record access across its integrated delivery infrastructure.
United Kingdom
NHS trusts in London and Greater Manchester outsource identity verification to cloud platforms capable of NHS number matching against centralized patient demographic databases. The UK Information Commissioner's Office enforces GDPR-derived accountability frameworks on biometric data processing. The Francis Crick Institute in London deploys iris scanning for high-security laboratory access control.
Japan
Metropolitan hospital networks in Tokyo and Osaka integrate fingerprint recognition with existing access control infrastructure dating to early 2000s deployments. METI guidelines on medical device software classification intersect with PMDA oversight of clinical decision support systems. The University of Tokyo Hospital leads multimodal fusion pilots combining facial geometry with voiceprint spectrograms for telemedicine authentication.
India
Telemedicine platforms in Karnataka and Telangana deploy API-native facial recognition for patient verification across state jurisdictions without hardware logistics. The Digital Information Security in Healthcare Act creates data localization obligations for biometric template storage. Apollo Hospitals in Chennai anchors cloud-based authentication deployments linking Aadhaar biometric verification to electronic health record access.
Biometrics As a Service in Healthcare Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying sensor hardware and algorithmic modules to assembled solutions. The vendor base stratifies between defense-sector encryption heritage players and cloud-native API specialists. Three archetypes dominate: encryption-anchored platform providers, palm-vein recognition specialists, and physician-workflow authentication incumbents. Competitive moves concentrate on strategic partnerships with telemedicine operators and portfolio diversification into continuous physiological monitoring.
Within the encryption-anchored tier, Thales leverages its defense-sector heritage to anchor high-assurance healthcare deployments requiring hardware security module integration. Fujitsu occupies a specialized position through palm-vein recognition systems that sustain superior liveness detection for sterile clinical environments. Imprivata, Inc. exemplifies the physician-workflow archetype, controlling privileged access integration with electronic health record platforms across United States integrated delivery networks.
| Leading Market Players |
|---|
| Thales |
| Fujitsu |
| Aware, Inc. |
| BIO-key International |
| Imprivata, Inc. |
| Suprema |
| NEC Corporation |
| IDEMIA |
| M2SYS Technology |
| Others |
Cost & Logistics Intelligence
Trans-Pacific fiber-optic cable routes carry encrypted biometric template traffic between cloud regions, with latency-sensitive authentication workloads commanding premium routing that concentrates vendor margins in API-native platform providers while compressing pricing for hardware-dependent legacy architectures.
Pricing Analysis
Hospital systems anchor subscription-based pricing structures across three tiers: enterprise-grade deployments with hardware security module integration, standard API-accessible verification services, and economy-tier per-transaction models for smaller clinics. Price differentiation hinges on HIPAA audit trail granularity and FDA software-as-a-medical-device certification tier. Pricing pressure stems from telemedicine platforms demanding browser-native facial recognition without sensor hardware procurement. Smaller regional health networks exhibit highest price sensitivity, while integrated delivery networks prioritize compliance-grade service levels over cost minimization.
Supply Chain Analysis
Foxconn and Pegatron hold contract manufacturing concentration for biometric sensor hardware, with specialized foundries in Taiwan and South Korea producing liveness detection chipsets. Algorithm development clusters in the United States, Israel, and China supply matching engines and neural network training frameworks. The supply chain draws from CMOS image sensors, near-infrared emitters, and hardware security modules as critical inputs. Single-source vulnerability concentrates in advanced liveness detection silicon from Taiwanese foundries. Distribution runs through cloud API marketplaces and direct enterprise sales to hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in continuous physiological monitoring, where wearable biometric streams for cardiac rhythm and glucose tracking create authentication-by-continuity models that bypass explicit verification friction in telemedicine encounters.
For Market Incumbents: Entrench cloud-native API architectures through hardware security module integration that mid-sized health networks cannot architect independently. Deepen physician workflow lock-in via Imprivata-style privileged access management for electronic health record systems. Counter emerging palm-vein recognition specialists by certifying multimodal fusion stacks for surgical suite deployments under FDA software-as-a-medical-device guidance.
For New Entrants and Emerging Players: Build out behavioral biometrics capabilities for opioid prescribing monitoring, where keystroke dynamics and gait analysis address DEA diversion requirements that incumbent platforms have not prioritized. Target mid-sized telemedicine operators in state jurisdictions with fragmented credential verification infrastructure. Lead with API-native deployment models that eliminate hardware logistics friction.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors algorithmic liveness detection specialists with defense-sector heritage encryption capabilities. Long-term viability rests on vendors capable of absorbing hardware refresh cycles into subscription pricing while maintaining HIPAA audit trail compliance. Watch for FDA reimbursement eligibility rulings on continuous biometric surveillance as inflection signal for patient monitoring segment viability.
| Strategic Initiative | Industry Significance |
|---|---|
| HIPAA-Compliant Cloud Migration | Hospital systems outsource hardware maintenance to API platforms satisfying Department of Health and Human Services audit mandates. |
| Multimodal Biometric Fusion | Combined fingerprint-iris-voice stacks reduce false acceptance rates below single-modality thresholds for surgical access. |
| EU AI Act Compliance Architecture | Algorithmic impact assessments and human-in-the-loop overrides become mandatory for European health insurer deployments. |
| Telemedicine API Integration | Browser-native facial recognition eliminates hardware distribution logistics across state-jurisdictional telehealth networks. |
| Continuous Monitoring Validation | FDA software-as-a-medical-device pathway creates reimbursement eligibility beyond pure identity verification functions. |
Research Approach
The analysis maps identity verification services, access control platforms, patient monitoring applications, and data security architectures, each validated through hospital chief information officers, biomedical engineers, GPO contracts managers, and telemedicine platform operators. Primary interviews combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU AI Act implementation guidance. Bottom-up deployment counts triangulated against top-down healthcare IT expenditure estimates.
Assumptions held HIPAA enforcement intensity and telemedicine platform expansion as fixed baseline conditions, while varying FDA software-as-a-medical-device pathway progression and EU AI Act implementation timelines across sensitivity scenarios. Segmentation modeled service type, biometric modality, end-user institution scale, and application workflow integration. CAGRs derived from installed base growth rates and average revenue per deployment trends. Industry-specific inputs included hospital duplicate record penalty structures and biometric template interoperability standards evolution.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native entrants or regulatory acceleration beyond EU AI Act timelines would shift outcomes. Quarterly review of FDA guidance updates, HIPAA audit enforcement intensity, and telemedicine platform authentication API specifications is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Global Biometric Card Market
Biometrics & Identity Management
Global Personal Identity Management Market
Biometrics & Identity Management
Global Mobile User Authentication Market
Biometrics & Identity Management
United States Biometrics Market
Biometrics & Identity Management
Military Biometrics Market
Biometrics & Identity Management
Iris Recognition Market
Biometrics & Identity Management
Global Biometric Systems Market
Biometrics & Identity Management
Global Voice Biometrics Market
Biometrics & Identity Management
Flash Calling Authentication Market
Biometrics & Identity Management
Biometric Authentication Solution Market
Biometrics & Identity Management
Europe Decentralized Identity Market
Biometrics & Identity Management
Multi-Factor Authentication (MFA) Market
Biometrics & Identity Management
Spain Mobile Biometrics Market
Biometrics & Identity Management
North America Enterprise Biometrics Market
Biometrics & Identity Management
Fingerprint Biometrics Market
Biometrics & Identity Management
Global Biometric Authentication Identification Market