
 Consumer Biometrics Market | 2026-2036
Consumer Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Biometrics Market Analysis
Edge-based neural processing is narrowing the performance gap between on-device and cloud biometric inference. Apple Inc. leverages its secure enclave architecture to anchor consumer trust in facial authentication across iOS ecosystems. Samsung Electronics Co., Ltd. competes through Knox-integrated fingerprint and iris stacks that extend across Galaxy device tiers. Qualcomm Technologies, Inc. sustains its position by supplying 3D sonic sensor platforms to Android OEMs seeking ultrasonic fingerprint differentiation.
Consumer biometrics encompasses physiological and behavioral identity verification systems that capture, process, and match unique human characteristics against enrolled templates, typically operating with false acceptance rates below 0.001% in certified deployments. These systems serve commercial security, financial authentication, and personal device access control by replacing knowledge-based credentials with inherence factors. Fingerprint recognition dominates unit volumes due to mature CMOS sensor costs and embedded module miniaturization, while facial recognition captures premium value in payment and border-crossing applications where liveness detection requirements elevate software complexity. Voice recognition occupies a narrower niche in call center and smart speaker contexts, constrained by environmental noise variability and replay attack vulnerabilities that limit high-assurance deployment.
The U.S. National Institute of Standards and Technology (NIST) sets accuracy benchmarks through ongoing FRVT and MINEX evaluations that shape vendor procurement criteria for federal and financial clients. The EU AI Act classifies remote biometric identification as high-risk, imposing conformity assessments and human oversight mandates that increase compliance costs for European deployments. Stakeholders must monitor evolving liveness detection standards and cross-border data localization requirements as jurisdictions diverge on biometric storage and algorithmic audit obligations.
Market Dynamics
Edge neural processors are collapsing the latency differential between on-device and cloud-based biometric inference, forcing platform architects to redesign authentication architectures around localized inference rather than centralized processing.
Growth Catalysts
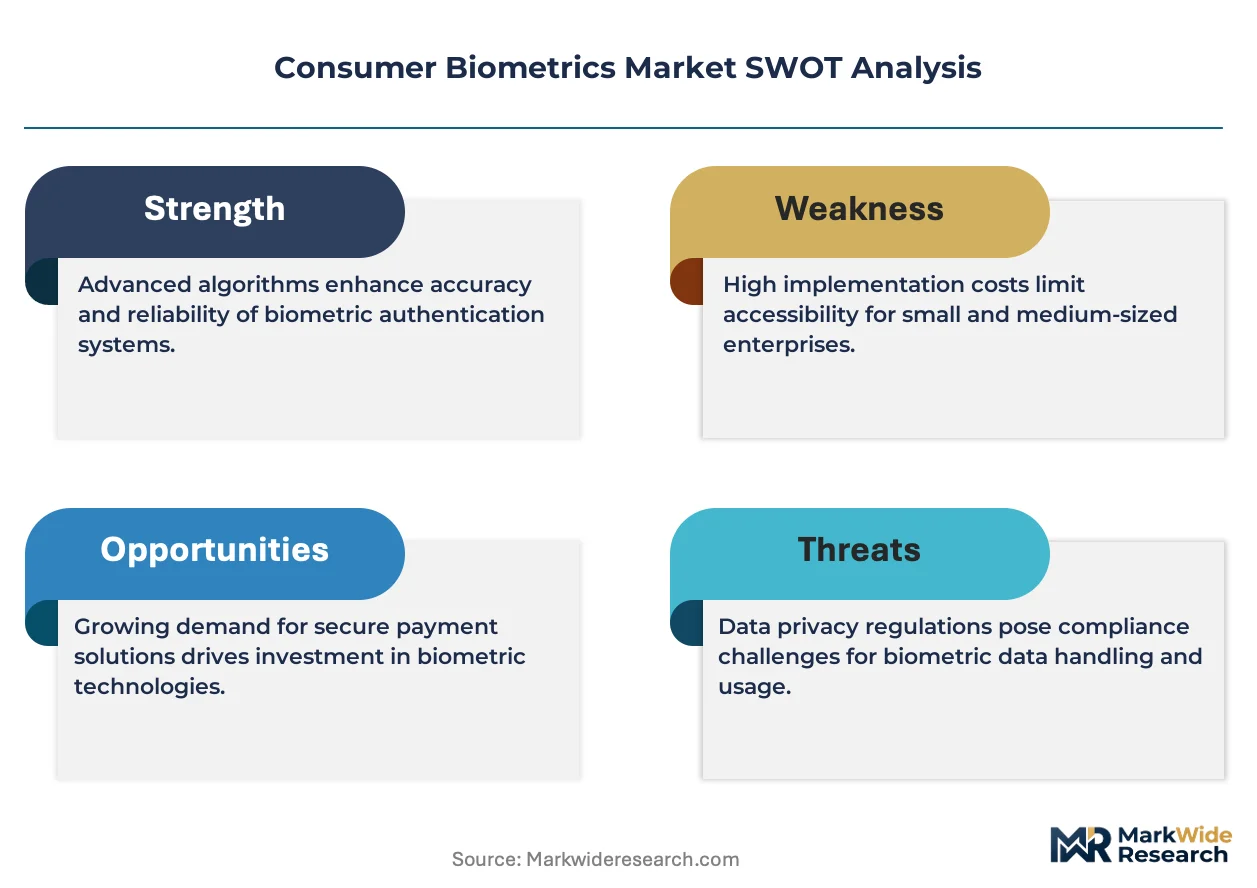
- EU AI Act high-risk classification:Remote biometric identification systems now face mandatory conformity assessments and human oversight protocols, creating procurement urgency among European financial institutions to deploy compliant multimodal platforms before enforcement deadlines.
- Mobile payment authentication:Retail chains across the United States are replacing card-present terminals with biometric-enabled point-of-sale systems that eliminate friction in high-volume transaction environments.
- CMOS sensor miniaturization:Fingerprint module costs have fallen below the threshold for mass-market smartphone integration, expanding addressable device tiers in emerging Asian manufacturing clusters.
Market Restraints
- GDPR algorithmic transparency mandates:Biometric data processors face elevated compliance costs from explainability requirements that force disclosure of template matching logic previously treated as proprietary.
- Silicon supply concentration:Secure enclave fabrication depends on a limited set of foundry providers in Taiwan, creating vulnerability to geopolitical disruption in neural processing unit availability.
- Environmental noise variability:Voice recognition systems remain constrained by acoustic interference that degrades matching accuracy in uncontrolled deployment environments.
Strategic Opportunities
- NIST FRVT benchmark alignment:Vendors achieving top-tier accuracy rankings in facial recognition vendor testing gain preferential access to federal and financial procurement channels in the United States.
- Behavioral biometrics convergence:Keystroke dynamics and gait analysis are integrating with physiological modalities to create continuous authentication layers for high-value transaction monitoring.
- India digital identity stack:The Aadhaar-linked authentication ecosystem creates a regulatory tailwind for biometric service providers targeting financial inclusion and government benefit distribution.
Industry Challenges
- Liveness detection standardization gaps:Inconsistent certification requirements across ISO/IEC 30107-3 presentation attack detection levels force vendors to maintain multiple testing protocols for different jurisdictional approvals.
- Template storage architecture migration:Financial institutions face complex integration cycles when replacing centralized biometric databases with distributed, encrypted edge storage that satisfies emerging data localization requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Biometrics Market |
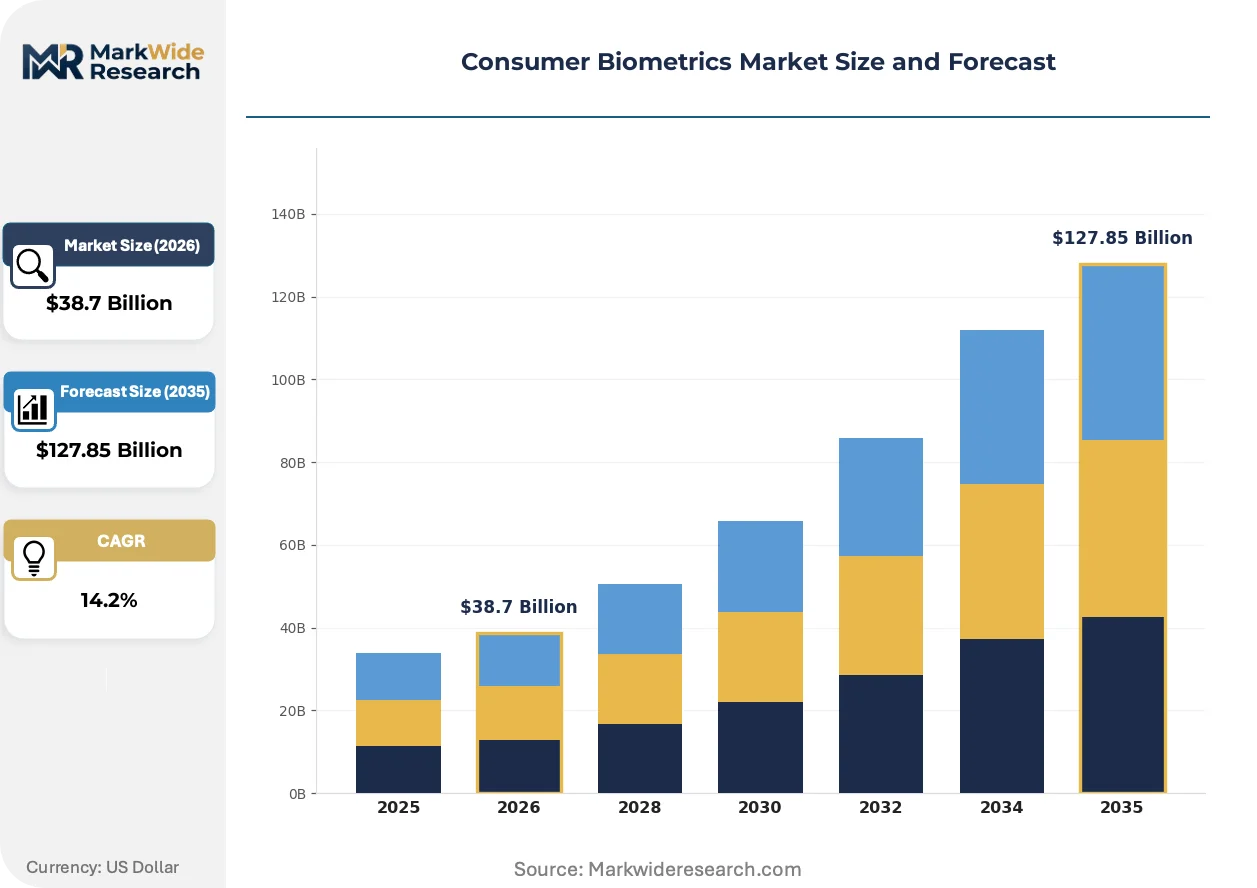
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fingerprint Recognition, Facial Recognition, Iris Recognition, Voice Recognition Application: Mobile Payment, Access Control, Identity Verification, Time & Attendance End User: Retail, Banking, Healthcare, Education Deployment: On-Premises, Cloud-Based, Hybrid, Embedded |
| Companies Covered | Apple Inc., Synaptics Incorporated, Qualcomm Technologies, Inc., IDEMIA, Aware, Inc., Goodix Technology Inc., IDEX Biometrics ASA, Samsung Electronics Co., Ltd., Suprema, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Biometrics Market Emerging Trajectories
Authentication architectures are pivoting from credential-based to inherence-based security models, compressing the acceptable latency window for biometric matching while elevating liveness detection from optional feature to mandatory specification.
Ultrasonic 3D fingerprint sensing is rendering obsolete capacitive touch-based readers in premium device tiers. Automotive OEMs adopting digital key systems now specify sub-100-millisecond matching speeds for driver authentication. The structural consequence is collapsing price premiums for optical fingerprint modules as ultrasonic platforms capture high-assurance deployment slots.
GDPR Article 35 data protection impact assessments now extend explicitly to biometric processing operations across European member states. Controllers must document necessity and proportionality for each template collection point, extending procurement cycles by four to eight months. Financial services verticals are responding by pre-negotiating standard contractual clauses with biometric vendors to accelerate compliance documentation.
Enterprise buyers are unbundling biometric authentication from broader identity-as-a-service contracts, demanding standalone pricing for facial and fingerprint modules that interoperate across cloud platforms. This procurement fragmentation is compressing vendor margins while expanding systems integrator roles in multi-modal deployment architecture. The United States banking sector exhibits the most advanced unbundling behavior, with regional credit unions leading deconsolidation of previously monolithic identity stacks.
Consumer Biometrics Market Segmentation
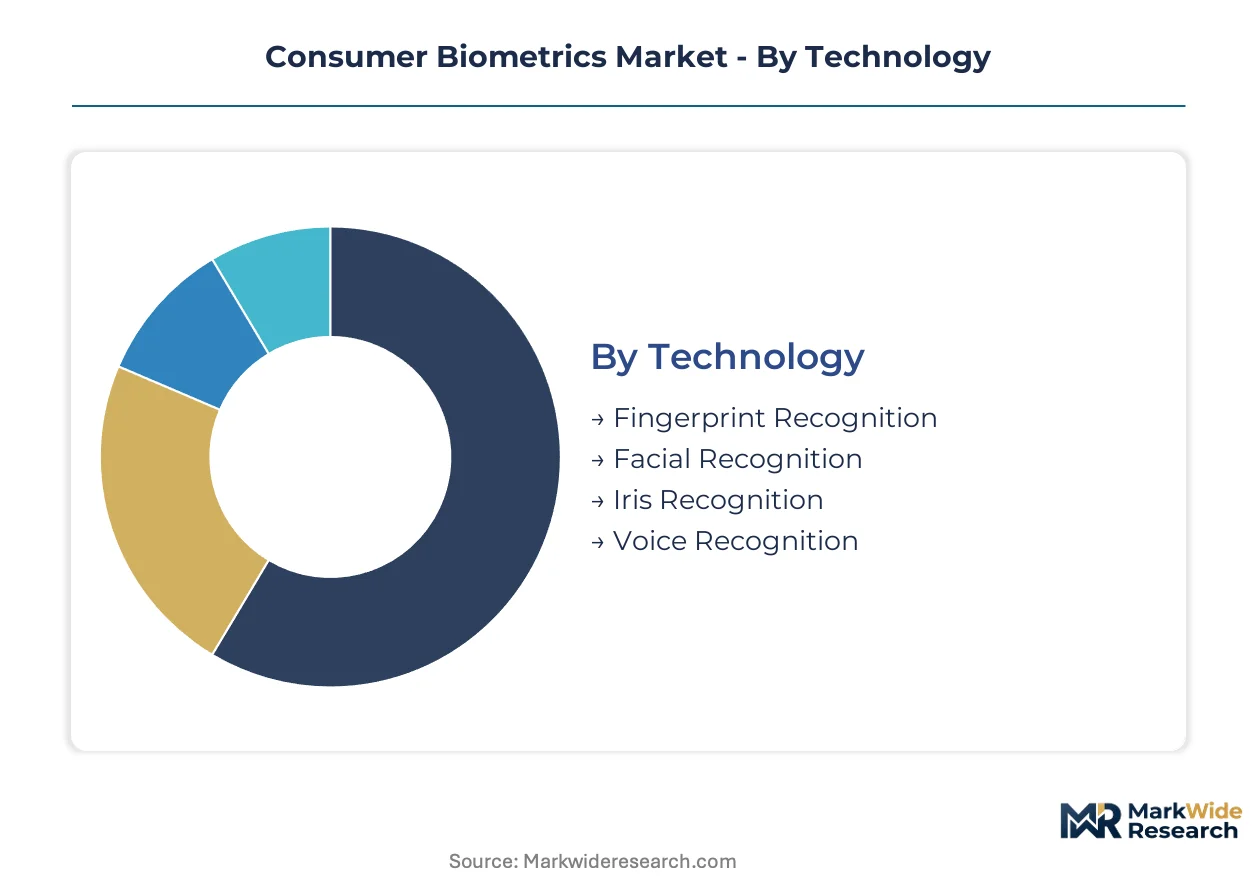
Technology modality determines hardware cost structures and software complexity tiers in consumer biometrics. Application context dictates liveness detection requirements and regulatory exposure. Deployment architecture shapes data sovereignty compliance and latency performance.
Technology:
Cost tier stratification separates mature CMOS-based modalities from premium 3D-sensing platforms requiring dedicated neural processors.
- Fingerprint Recognition:Capacitive and ultrasonic CMOS sensors capture ridge patterns with sub-100-millisecond matching speeds. Retail banking in the United States concentrates demand here for card-present transaction authentication, driven by PCI-DSS compliance deadlines for password elimination.
- Facial Recognition:Structured light and time-of-flight cameras generate depth maps for 3D template extraction with presentation attack detection. Border control agencies and premium smartphone OEMs drive specification intensity, constrained by EU AI Act high-risk classification mandates for remote biometric identification.
- Iris Recognition:Near-infrared imaging of stromal patterns delivers higher entropy templates than fingerprint modalities. Healthcare access control in India deploys this for patient identification within Aadhaar-linked systems.
- Voice Recognition:Spectral analysis of vocal tract characteristics operates in hands-free environments. Smart speaker OEMs and call center operators dominate procurement despite acoustic interference limitations in uncontrolled settings.
Fingerprint recognition commands the established base. The steepest expansion runs through facial recognition.
Application:
Volume concentration tracks payment transaction velocity and physical access point density across commercial facilities.
- Mobile Payment:NFC-integrated biometric authentication replaces card-present verification in retail environments. United States grocery chains and quick-service restaurants are retrofitting POS terminals with fingerprint and facial readers to eliminate checkout friction.
- Access Control:Physical entry systems for corporate campuses and data centers deploy multimodal readers with anti-tailgating integration. Financial services firms in New York and London specify ISO/IEC 30107-3 Level 2 presentation attack detection as baseline procurement criteria.
- Identity Verification:Remote onboarding for digital banking and government services requires document-to-biometric matching with liveness confirmation. India's UIDAI mandates iris or fingerprint capture for Aadhaar authentication in rural financial inclusion programs.
- Time & Attendance:Workforce management systems replace badge-swipe infrastructure with touchless facial or palm recognition. Manufacturing facilities in Germany adopt these under Works Council agreements that prohibit fingerprint storage on employer servers.
Access control commands the established base. Mobile payment exhibits the steepest expansion trajectory.
End User:
Customer type determines security assurance thresholds and integration complexity with legacy identity infrastructure.
- Retail:High-volume transaction environments prioritize sub-second authentication latency. United States big-box retailers deploy fingerprint-enabled self-checkout to reduce shrinkage and labor costs simultaneously.
- Banking:Regulatory capital requirements and fraud liability exposure drive multimodal specification. European institutions under ECB supervision accelerate procurement ahead of EU AI Act enforcement timelines.
- Healthcare:Patient identification and provider authentication demand HIPAA-compliant template storage architectures. United States hospital systems integrate biometric readers with Epic and Cerner EHR platforms.
- Education:Campus access and examination proctoring applications balance cost constraints with civil liberties concerns. Indian universities deploy Aadhaar-linked verification for national entrance examinations.
Banking commands the established base. Healthcare gains share fastest.
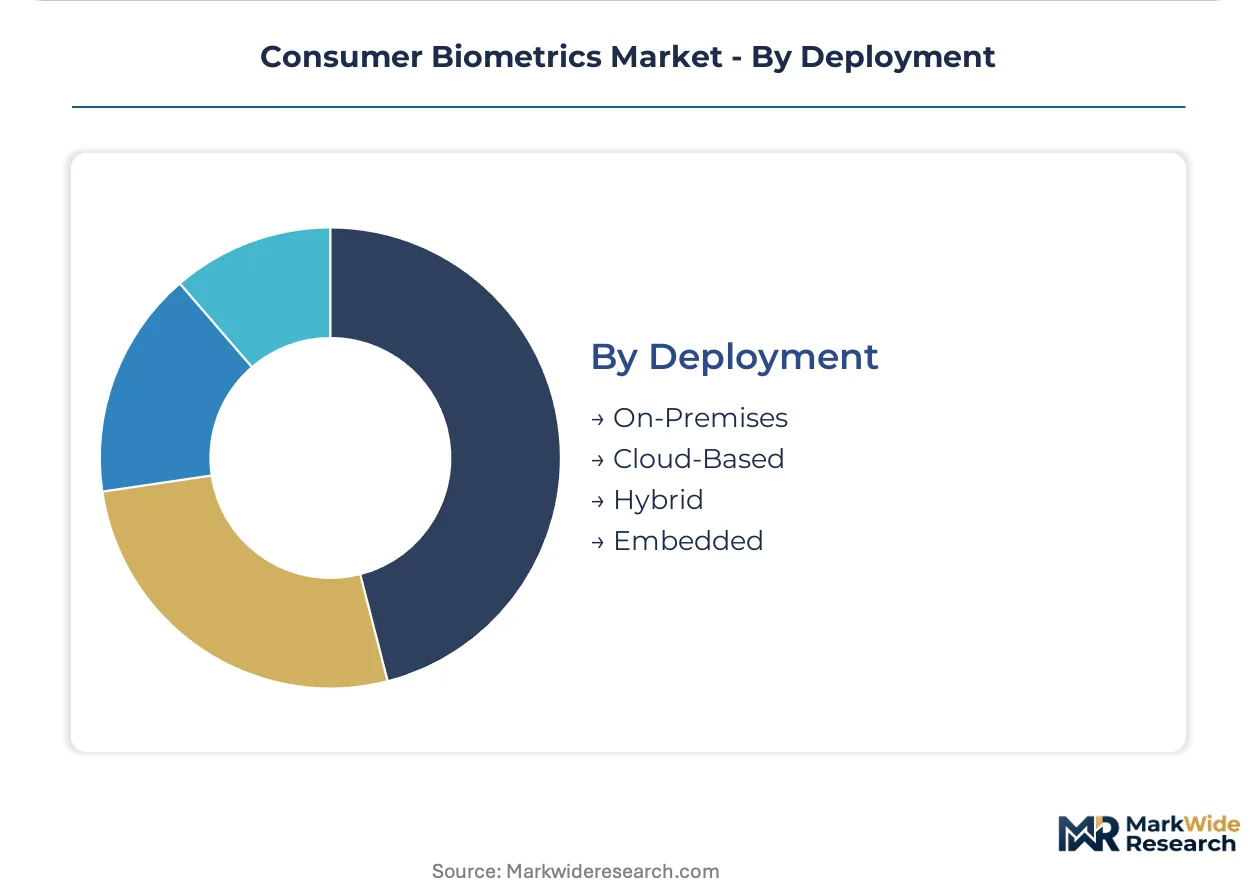
Deployment:
Supply concentration in secure enclave fabrication shapes architecture migration timelines for edge-based inference.
- On-Premises:Dedicated biometric servers within enterprise data centers maintain template databases under direct administrative control. German automotive manufacturers specify this for trade secret protection in R&D facility access.
- Cloud-Based:Centralized matching services enable rapid scaling across distributed branch networks. Australian neobanks leverage AWS and Azure biometric APIs to avoid capital expenditure on dedicated infrastructure.
- Hybrid:Template enrollment occurs on-device with cloud-based backup and cross-device synchronization. Apple's iCloud Keychain and Samsung Pass exemplify this architecture for consumer device ecosystems.
- Embedded:Neural processing units within secure enclaves execute matching without network transmission. Qualcomm's 3D Sonic sensors and Apple's Secure Enclave enable this for premium smartphone tiers.
On-premises commands the established base. Embedded architectures climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea exports secure enclave neural processors to device manufacturers in the United States and Germany. Taiwan supplies CMOS sensor fabrication capacity to fingerprint module integrators across Asian manufacturing clusters.
United States
Financial institutions in New York and Chicago accelerate multimodal biometric procurement ahead of NIST FRVT compliance deadlines. The SEC and FFIEC scrutinize algorithmic transparency in vendor selection processes. Silicon Valley hosts edge-AI chip designers that embed biometric inference directly into smartphone secure enclaves.
Germany
Automotive OEMs in Stuttgart and Munich specify sub-100-millisecond biometric matching for digital key systems. The KBA and BSI enforce ISO/IEC 30107-3 Level 2 presentation attack detection for vehicle access control. Bavarian semiconductor fabs produce near-infrared imaging components for iris recognition modules.
China
MIIT mandates domestic biometric algorithm certification for government procurement contracts. Shenzhen and Dongguan manufacturing clusters drive CMOS sensor cost compression below mass-market smartphone integration thresholds. NMPA regulates biometric data processing in healthcare access control deployments.
India
UIDAI mandates iris or fingerprint capture for Aadhaar-linked rural financial inclusion programs. The RBI directs banks to replace password systems with biometric authentication for benefit distribution. Karnataka and Telangana host software development centers for liveness detection algorithm refinement.
Japan
METI promotes biometric standardization for aging-population healthcare access systems. Osaka-based sensor manufacturers supply ultrasonic fingerprint components to premium automotive Tier 1s. PMDA regulates biometric data handling in pharmaceutical clinical trial participant verification.
Consumer Biometrics Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered technology stacks. The market structure concentrates around secure enclave architects, CMOS sensor fabricators, and algorithm licensing specialists. Three archetypes dominate: vertically integrated device OEMs, component-specialist suppliers, and multimodal platform integrators. M&A activity targets liveness detection startups, while strategic partnerships proliferate between neural processor designers and biometric algorithm vendors.
Among vertically integrated device OEMs, Apple Inc. and Samsung Electronics Co., Ltd. exemplify the secure enclave architecture approach. Component-specialist suppliers include Synaptics Incorporated and Goodix Technology Inc., which occupy positions in fingerprint sensor module supply chains. Qualcomm Technologies, Inc. anchors the neural processor licensing tier, supplying 3D sonic platforms to Android OEMs. IDEMIA represents the multimodal platform integrator archetype, spanning government and commercial identity verification deployments.
| Leading Market Players |
|---|
| Apple Inc. |
| Synaptics Incorporated |
| Qualcomm Technologies, Inc. |
| IDEMIA |
| Aware, Inc. |
| Goodix Technology Inc. |
| IDEX Biometrics ASA |
| Samsung Electronics Co., Ltd. |
| Suprema, Inc. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Taiwanese secure enclave foundries is compressing neural processing unit pricing while forcing CMOS sensor integrators in China and South Korea to absorb margin erosion through volume commitments rather than technology premiums.
Pricing Analysis
Ultrasonic 3D fingerprint sensing commands a three-tier pricing structure across premium, standard, and economy levels that collapses as capacitive optical modules saturate mid-tier smartphone slots. Price differentiation rests on ISO/IEC 30107-3 certification grade and secure enclave integration depth. Cost compression in optical fingerprint tiers is intensifying because Android OEMs are standardizing on reference designs that eliminate customization premiums. Regional credit unions in the United States exhibit the highest price sensitivity, while German automotive OEMs tolerate premium positioning for sub-100-millisecond matching specifications.
Supply Chain Analysis
Contract manufacturing concentration sits with Taiwan Semiconductor Manufacturing Company and Samsung Foundry for secure enclave fabrication, while Foxconn and Luxshare Precision assemble fingerprint modules for device OEMs. Taiwan, South Korea, and China anchor geographic supply concentration for neural processors and CMOS sensors. Raw material dependencies draw from silicon wafers, near-infrared optical components, and rare-earth elements for sensor magnetics. Single-source vulnerability in Taiwanese foundry capacity creates exposure to geopolitical disruption. Distribution runs through direct OEM supply agreements and tiered component distributors serving Asian manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment around GDPR Article 35 and EU AI Act compliance creates sticky vendor relationships that resist displacement.
For Market Incumbents: Entrench position by deepening backward integration into secure enclave design to capture neural processing margins currently flowing to foundry partners. Accelerate ISO/IEC 30107-3 Level 2 certification investment ahead of European enforcement timelines to lock out second-tier competitors lacking testing infrastructure. The threat of behavioral biometrics convergence from keystroke and gait analysis specialists demands preemptive multimodal patent filing.
For New Entrants and Emerging Players: Pursue white-space opportunity in Indian Aadhaar-linked healthcare access control where UIDAI mandates create procurement volume without incumbent saturation. Target European time-and-attendance deployments under Works Council agreements that prohibit employer server storage, favoring edge-embedded architectures. A go-to-market angle through systems integrators managing multi-modal deployment architecture bypasses direct competition with platform OEMs.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among algorithm licensing specialists with NIST FRVT benchmark positioning that feeds multi-year federal and financial procurement cycles. Long-term viability over a decade-long window favors vendors with liveness detection IP that satisfies evolving presentation attack standards. Acquisition targets should display embedded architecture revenue mix above fifty percent. The signal to watch is NIST FRVT accuracy ranking volatility as a predictor of procurement channel access.
| Strategic Initiative | Industry Significance |
|---|---|
| Secure Enclave Architecture Investment | Apple and Samsung leverage proprietary silicon to anchor consumer trust in facial authentication ecosystems. |
| NIST FRVT Benchmark Alignment | Top-tier accuracy rankings unlock preferential access to federal and financial procurement channels in the United States. |
| Liveness Detection Startup Acquisition | Presentation attack detection IP satisfies EU AI Act high-risk classification mandates and ISO/IEC 30107-3 requirements. |
| Behavioral Biometrics Convergence | Keystroke dynamics and gait analysis integration creates continuous authentication layers for high-value transaction monitoring. |
| India Digital Identity Stack Partnership | Aadhaar-linked authentication ecosystem creates regulatory tailwind for biometric service providers targeting financial inclusion. |
Methodological Framework
A spread of perspectives from biometric algorithm engineers, secure enclave architects, financial services procurement officers, and automotive Tier 1 supplier quality managers converged on the working assumptions. Primary interview insights combined with secondary validation from SEC 10-K filings, NIST FRVT evaluation reports, UIDAI technical specifications, and EU AI Act implementation guidance. Bottom-up component demand modeling and top-down market sizing triangulated volume estimates across technology modalities.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include technology modality, application context, deployment architecture, and regional regulatory cluster. CAGRs were derived from unit shipment trajectories and value-per-unit compression curves. Industry-specific forecast inputs incorporated NIST FRVT accuracy progression rates and EU AI Act compliance cost absorption assumptions.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles and cross-border data localization enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about neural processing unit cost curves and liveness detection standardization timelines. Quarterly review of NIST FRVT evaluation releases and EU AI Act implementing act publications is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Biometric ATM Market
Biometrics & Identity Management
Latin America Government & Security Biometrics Market
Biometrics & Identity Management
China Mobile Biometrics Market
Biometrics & Identity Management
Europe Enterprise Biometrics Market
Biometrics & Identity Management
Mobile Biometric Security and Services Market
Biometrics & Identity Management
Identity Theft Protection Services Market
Biometrics & Identity Management
Global Human Identification Market
Biometrics & Identity Management
Palm Vein Biometrics Market
Biometrics & Identity Management
Vein Recognition Biometrics Market
Biometrics & Identity Management
ID Verification Market
Biometrics & Identity Management
Military Biometrics Market
Biometrics & Identity Management
Asia Pacific Biometrics in Government Market
Biometrics & Identity Management
Mobile Biometrics Market
Biometrics & Identity Management
FIDO Authentication Market
Biometrics & Identity Management
Gait Biometrics Market
Biometrics & Identity Management
Europe Biometrics in Government Market