
 Biometrics Software Market | 2026-2036
Biometrics Software Market Size, Share, and Industry Trends Forecast 2026-2036
Biometrics Software Market Analysis
Fragmentation across new buyers in retail and healthcare is recalibrating procurement patterns for biometric platforms. IDEMIA leverages its civil identity specialization to anchor large-scale government contracts across multiple continents. NEC Corporation sustains heavy R&D intensity in facial recognition algorithms, while Thales competes through integrated digital security portfolios spanning both hardware and software layers.
Biometrics software encompasses algorithmic platforms that capture, process, and match physiological or behavioral characteristics against enrolled templates using template sizes typically measured in kilobytes and matching speeds under one second. These systems serve commercial and institutional purposes by replacing password-based authentication with factor-binding identity assurance. Fingerprint recognition occupies the most mature position with established sensor cost curves, whereas facial recognition represents the fastest-expanding category driven by smartphone integration and contactless access protocols. Cloud-based deployment captures expanding margin pools as vendors shift from perpetual licenses toward recurring authentication-as-a-service models.
The EU AI Act classifies remote biometric identification as high-risk, mandating conformity assessments before market entry across member states. India's BIS framework and the United States' NIST testing protocols shape product standards through accuracy benchmarks and interoperability requirements. Stakeholders must monitor evolving algorithmic audit obligations and procurement certification timelines to align product roadmaps with compliance windows.
Market Dynamics
Cloud-native authentication architectures are collapsing deployment timelines from months to weeks, forcing incumbent vendors to restructure pricing models and delivery mechanisms around consumption-based billing.
Growth Catalysts
- Remote Biometric Identification Mandates:The EU AI Act's high-risk classification system is accelerating conformity assessment investments across member states, creating certified vendor pools for public procurement.
- Contactless Access Protocols:Healthcare facilities and transit authorities in India are expanding facial recognition deployments for patient verification and fare collection systems.
- Smartphone Integration:Fingerprint and facial matching APIs embedded in iOS and Android ecosystems are conditioning consumer expectations for frictionless authentication across banking and retail applications.
Market Restraints
- Algorithmic Audit Costs:Third-party bias testing and documentation requirements under the EU AI Act are inflating compliance expenditures for facial recognition vendors serving European public sector clients.
- Sensor Supply Concentration:Fingerprint module fabrication remains concentrated in East Asian contract manufacturers, exposing procurement timelines to regional logistics disruptions.
- Template Interoperability Limitations:Proprietary template formats from legacy vendors lock enterprises into single-source relationships, retarding competitive substitution.
Strategic Opportunities
- Behavioral Biometrics Convergence:Keystroke dynamics and gait analysis algorithms are merging with physiological modalities to create continuous authentication layers for financial services fraud detection.
- Authentication-as-a-Service Channels:Hyperscaler marketplaces are emerging as primary distribution vectors, enabling biometric vendors to bypass direct enterprise sales cycles.
- India's Digital Public Infrastructure:The BIS framework and Aadhaar-linked authentication protocols are creating standardized procurement pathways for domestic and foreign software providers.
Industry Challenges
- Multimodal System Integration:Enterprise IT departments struggle to orchestrate fingerprint, facial, and voice recognition engines within existing identity and access management stacks.
- Biometric Data Protection Certification:ISO/IEC 30107-3 presentation attack detection testing and GDPR-aligned data protection impact assessments are extending product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biometrics Software Market |
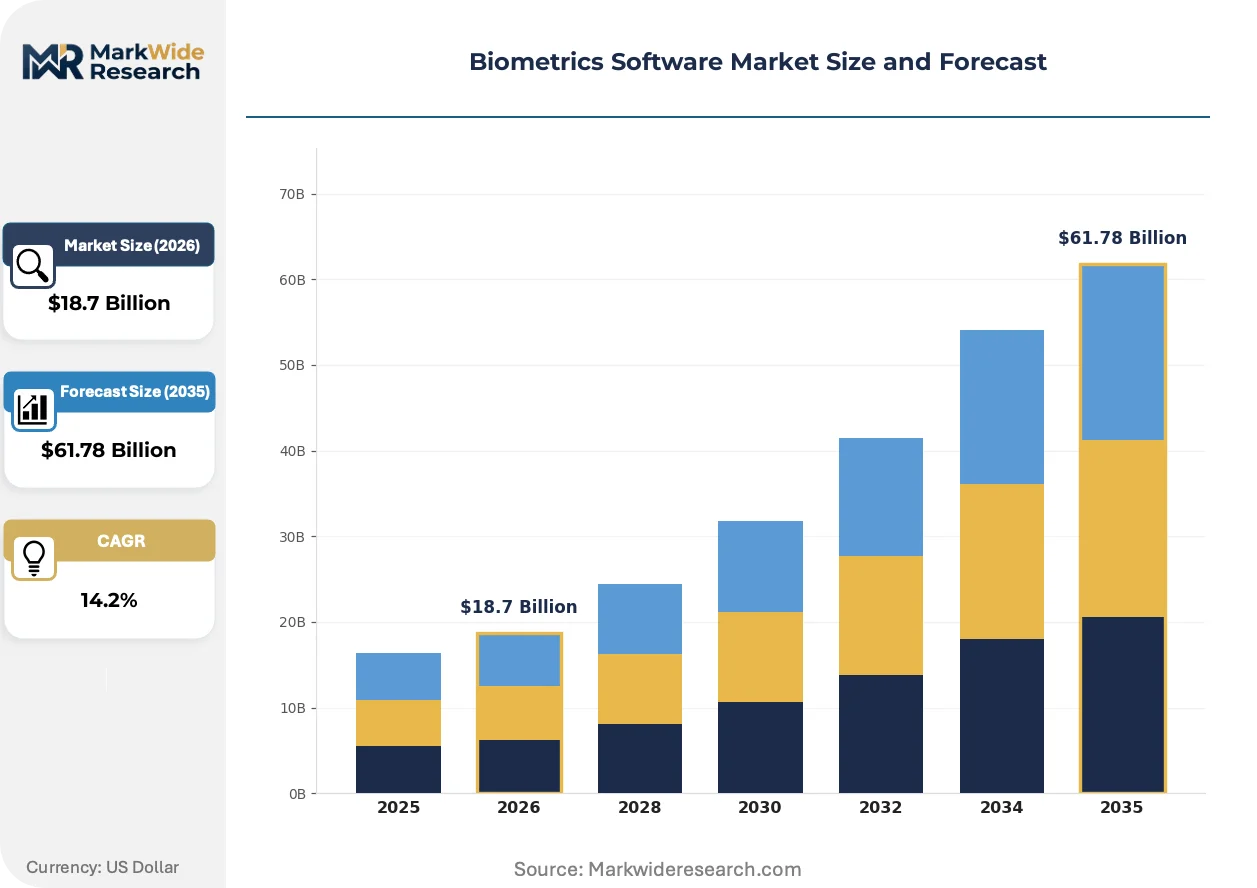
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fingerprint Recognition, Facial Recognition, Iris Recognition, Voice Recognition End User: Healthcare, Government, Banking, Retail Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Application: Access Control, Identity Verification, Time Tracking, Border Control |
| Companies Covered | IDEMIA, NEC Corporation, Thales, Fujitsu, HID Global, Aware Inc., ASSA ABLOY, Fingerprint Cards AB, Goodix Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biometrics Software Market Emerging Trajectories
Edge-computing architectures are redistributing processing loads from centralized data centers to endpoint devices, altering latency benchmarks and data sovereignty calculations across deployment architectures.
On-device neural processing units in smartphones and access control terminals are rewriting performance expectations for biometric matching. Banks and payment networks are prioritizing NPU-enabled devices for card-not-present transaction verification. This compression of matching latency to sub-100 milliseconds is eliminating cloud-roundtrip dependencies for high-frequency authentication scenarios.
The EU AI Act's high-risk system classification is mandating algorithmic transparency documentation and human oversight protocols for remote biometric identification. Vendors serving European law enforcement and border control agencies are restructuring product documentation and audit trail capabilities. Facial recognition platforms with embedded explainability features are capturing preference share in EU public procurement evaluations.
Enterprise buyers are unbundling perpetual software licenses into modular subscription components spanning enrollment, matching, and lifecycle management functions. System integrators and managed security service providers are capturing intermediary value by packaging biometric capabilities into broader identity platforms. This pattern is most pronounced in United States healthcare and financial services verticals, where CISOs prioritize vendor consolidation over point-solution procurement.
Biometrics Software Market Segmentation
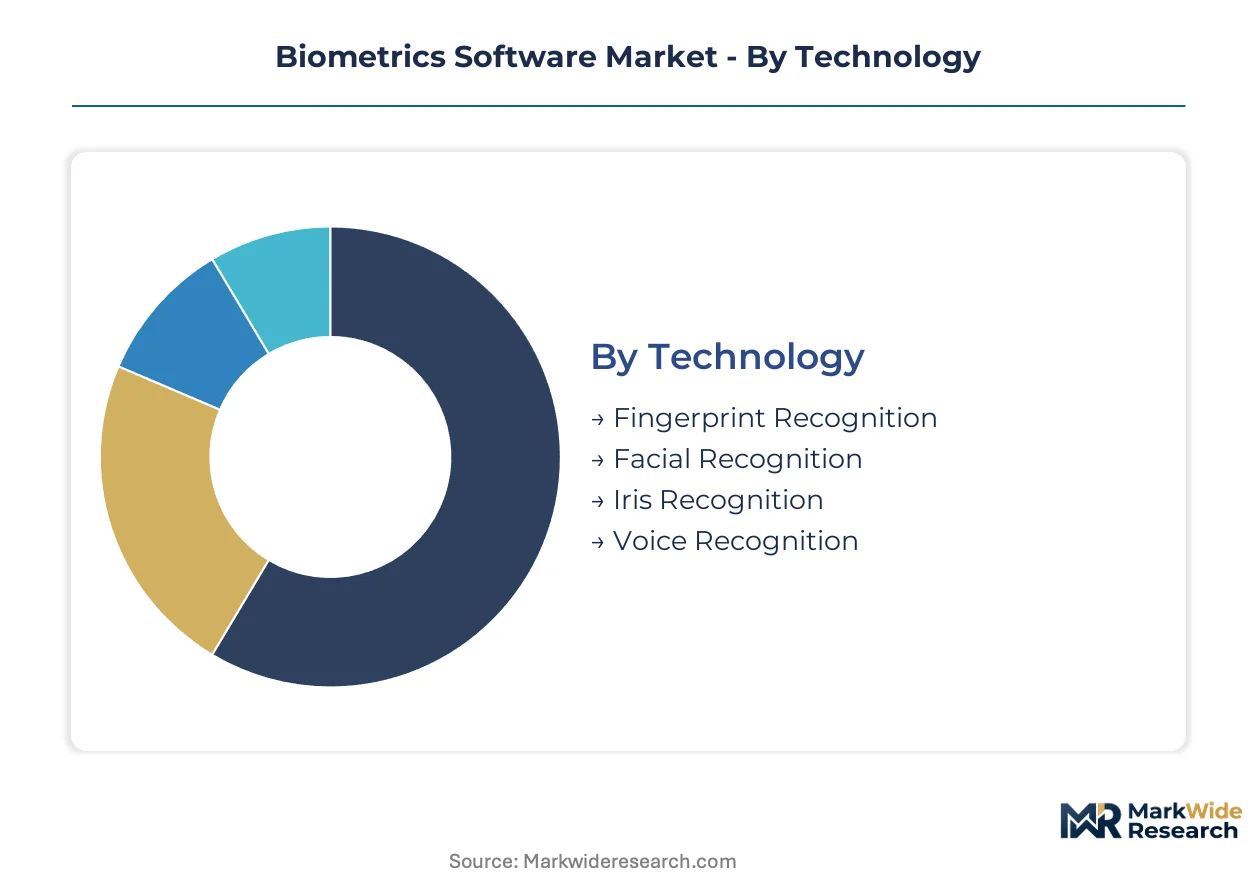
Biometrics software segments diverge sharply in margin structure and procurement complexity. Technology choices lock buyers into specific sensor ecosystems, while deployment models determine whether vendors capture recurring revenue or one-time license fees.
Technology:
Standardization varies from mature ISO templates to proprietary neural architectures that resist interoperability.
- Fingerprint Recognition:Template-matching algorithms process minutiae points from capacitive or optical sensors with sub-500-millisecond verification speeds. Banking networks in India deploy these systems for ATM authentication and branch access control, driven by BIS certification requirements and Aadhaar integration mandates.
- Facial Recognition:Deep convolutional networks extract 512-dimensional feature vectors from 2D or 3D facial geometry, enabling contactless verification at distances up to two meters. Transit authorities in the United States are expanding these deployments for airport passenger processing and fare gate authentication, responding to post-pandemic contactless protocols.
- Iris Recognition:Near-infrared imaging captures unique trabecular patterns with false match rates below one in one million. High-security facilities favor this modality where fingerprint degradation or facial occlusion risks exist.
- Voice Recognition:Spectral analysis of vocal tract acoustics enables remote authentication through telephone channels. Call centers and financial institutions deploy voice biometrics for account recovery and fraud prevention in card-not-present transactions.
Most installed capacity flows through Fingerprint Recognition. Expansion is steepest in Facial Recognition.
End User:
Procurement sophistication escalates from commercial self-service deployments to sovereign identity systems with national security implications.
- Government:Civil identity registries and law enforcement databases demand algorithmic platforms capable of billion-scale deduplication and de-duplication against watchlists. India's Aadhaar program and United States federal agencies drive volume through standardized tender processes.
- Banking:Know-your-customer compliance and transaction authentication requirements are accelerating multimodal deployments combining facial liveness detection with document verification. European institutions face EU AI Act conformity assessments for remote biometric identification.
- Healthcare:Patient identity matching across electronic health record systems reduces duplicate records and insurance fraud. Facilities prioritize palm-vein or facial modalities where hygiene concerns limit fingerprint sensor contact.
- Retail:Loyalty program enrollment and frictionless checkout pilots are absorbing cloud-based facial matching APIs with per-transaction pricing. Loss prevention teams deploy these systems against organized retail crime.
Revenue concentrates in Government contracts. Healthcare is climbing fastest as interoperability mandates harden.
Deployment:
Architecture choices trade data sovereignty against operational agility, with latency requirements often dictating the decision.
- Cloud-Based:API-first platforms deliver elastic matching capacity with consumption-based billing, eliminating capital expenditure for enrollment infrastructure. Financial services firms in the United States favor this model for seasonal authentication spikes.
- On-Premises:Air-gapped installations satisfy data residency requirements for defense and intelligence applications. These deployments carry higher upfront licensing costs but eliminate recurring subscription exposure.
- Hybrid:Edge enrollment with cloud matching splits processing loads, enabling offline continuity during network interruptions. Critical infrastructure operators favor this architecture for operational resilience.
- Mobile:On-device matching through smartphone secure enclaves eliminates server-side biometric storage, addressing GDPR and state-level biometric privacy statutes. Banking applications drive adoption through FIDO2 certification requirements.
Cloud-Based deployments carry the heaviest current investment. Mobile architectures are gaining share fastest as NPU penetration deepens.
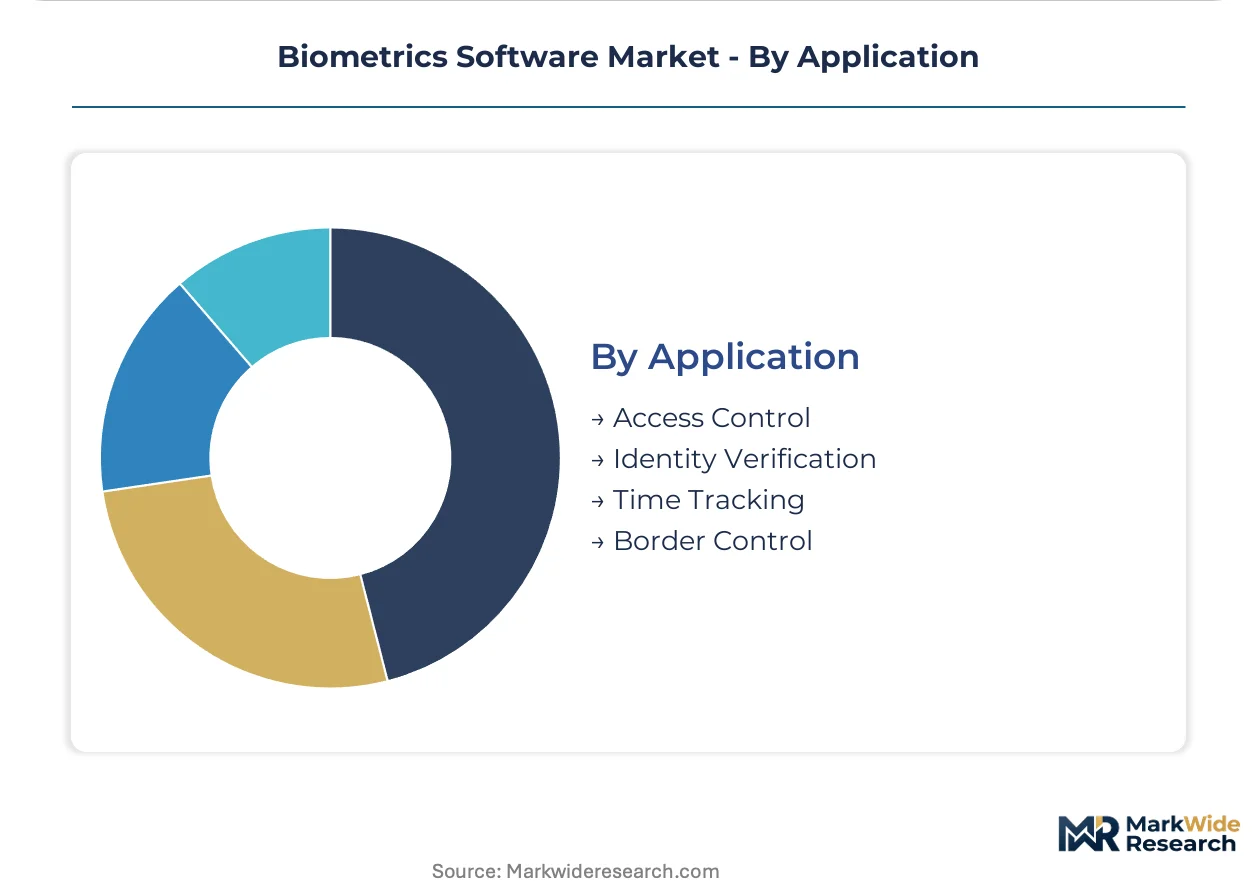
Application:
Use case specificity determines whether vendors compete on accuracy benchmarks or integration flexibility.
- Identity Verification:Document-to-biometric matching for account onboarding requires liveness detection and presentation attack resistance certified to ISO/IEC 30107-3 Level 2. Digital banks and fintech platforms drive demand.
- Access Control:Physical entry systems integrate biometric readers with building management platforms, prioritizing throughput speed for high-traffic environments. Corporate campuses and data centers represent core demand.
- Border Control:Automated border crossing gates match traveler facial images against e-passport chips and central watchlists. EU entry-exit system mandates are expanding procurement volumes.
- Time Tracking:Workforce management systems record employee attendance through fingerprint or facial verification, replacing badge-based systems vulnerable to buddy-punching fraud. Manufacturing and logistics facilities dominate adoption.
Access Control retains the largest installed base. Identity Verification is expanding most quickly as digital onboarding becomes standard.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's biometric infrastructure investments outpace Germany's precision-engineering focus, while the United States balances federal security mandates against state-level privacy fragmentation. Each geography shapes distinct procurement pathways and compliance architectures.
United States
Department of Homeland Security border modernization and TSA credential authentication programs drive federal procurement volumes. NIST testing protocols establish accuracy benchmarks that filter vendor eligibility for government contracts. Washington DC and Northern Virginia host concentrated defense and intelligence contractor ecosystems deploying billion-scale facial recognition systems.
India
Aadhaar-linked authentication protocols and BIS certification requirements standardize procurement across banking and welfare distribution networks. The Unique Identification Authority of India mandates interoperability standards that reshape vendor qualification criteria. Bangalore and Hyderabad anchor domestic software development clusters serving both government and fintech authentication demands.
Germany
Automotive manufacturers and industrial conglomerates demand ISO/IEC 30107-3 certified liveness detection for workforce access control systems. The EU AI Act's high-risk classification triggers conformity assessment investments across Bavaria and Baden-Württemberg. Munich hosts enterprise security software clusters integrating biometric modules into broader identity platforms.
United Kingdom
Financial Conduct Authority guidance on biometric authentication for digital banking accelerates multimodal deployment across retail banking networks. GDPR-aligned data protection impact assessments extend procurement timelines for facial recognition vendors. London's fintech corridor concentrates demand for cloud-based identity verification APIs serving neobank onboarding pipelines.
Japan
METI standards for presentation attack detection shape vendor qualification for financial services and critical infrastructure applications. Aging demographics drive demand for contactless authentication in healthcare facilities and public transit. Tokyo-Osaka corridor hosts integrated circuit design clusters supplying neural processing units for edge-based biometric matching.
Biometrics Software Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across contract tiers, creating a bifurcated structure where scale advantages clash with customization depth. Tier-one vendors anchor government identity programs through civil registry specialization, while mid-scale players capture enterprise authentication niches. Three archetypes dominate: integrated security conglomerates with hardware-software portfolios, algorithm specialists with heavy R&D intensity, and component suppliers feeding OEM integration channels. Competitive dynamics center on certification accumulation for EU AI Act compliance and cloud marketplace distribution partnerships that bypass direct sales cycles.
Within the integrated security tier, IDEMIA and Thales exemplify conglomerate positioning through civil identity system anchoring across multiple continents. NEC Corporation occupies a specialist position representing heavy algorithmic investment in facial recognition architectures. These three names illustrate the competitive spectrum from portfolio breadth to technical depth, with each archetype capturing distinct margin pools in government versus commercial procurement channels.
| Leading Market Players |
|---|
| IDEMIA |
| NEC Corporation |
| Thales |
| Fujitsu |
| HID Global |
| Aware Inc. |
| ASSA ABLOY |
| Fingerprint Cards AB |
| Goodix Technology |
| Others |
Supply Flow & Price Mechanics
Horizontal integration into cloud infrastructure layers anchors pricing power for authentication-as-a-service vendors while compressing margins for perpetual-license incumbents. The EU AI Act's conformity assessment timeline and India's BIS certification windows create divergent cost structures that reshape procurement negotiations across government and enterprise segments.
Pricing Analysis
Capacity additions in India's domestic software development clusters are reshaping price floors for cloud-based biometric platforms serving Aadhaar-linked authentication networks. Subscription-tiered pricing stratifies across ISO/IEC 30107-3 certification levels, with Level 2 liveness detection commanding premium positioning against baseline template-matching offerings. Pricing pressure stems from hyperscaler marketplace distribution models that disintermediate direct enterprise sales cycles and compress channel margins. Government buyers in the United States exhibit lowest price sensitivity given NIST testing protocol requirements and billion-scale deduplication mandates, while retail loyalty program operators drive hardest bargain hunting for per-transaction facial matching APIs.
Supply Chain Analysis
Refurbishment flows for fingerprint sensor modules and edge-computing terminals create secondary supply channels that extend hardware lifecycle value and temper raw material demand spikes. Component fabrication concentrates in Taiwan, South Korea, and China, with near-infrared imaging arrays and neural processing units drawing from specialized semiconductor foundries. The supply chain rests on CMOS sensor wafers, NPU chipsets, and optical lens assemblies as critical inputs. Single-source vulnerability persists in East Asian contract manufacturing for fingerprint modules, exposing procurement timelines to regional logistics disruptions. Distribution runs through hyperscaler marketplaces and system integrator channels that bundle biometric capabilities into broader identity platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between India's standardized BIS certification pathways that accelerate vendor qualification and the EU AI Act's algorithmic audit requirements that inflate compliance expenditures and extend sales cycles.
For Market Incumbents: Cement cloud-native architecture investments to collapse deployment timelines from months to weeks, matching consumption-based billing models that emerging competitors deploy through hyperscaler channels. Fortify position against pure-play algorithm specialists by accumulating EU AI Act conformity assessments ahead of procurement windows, while deepening backward integration into NPU-enabled edge device supply chains to capture hardware-software margin stacking. For New Entrants and Emerging Players: Hyperscaler marketplace partnerships offer the most penetrable channel for bypassing direct enterprise sales cycles and achieving rapid scale. Target India's fintech authentication demand where Aadhaar-linked protocols create standardized procurement pathways without the EU's algorithmic transparency documentation burdens. Prioritize behavioral biometrics convergence—keystroke dynamics and gait analysis—as a white-space entry angle where physiological modality incumbents lack continuous authentication capabilities. For Investors and Strategic Acquirers: Consolidation pressure builds where algorithmic audit costs under the EU AI Act strain mid-scale facial recognition vendors lacking diversified revenue streams across government and commercial channels. Frame long-term viability around authentication-as-a-service recurring revenue models that displace perpetual license dependence. Target acquisition candidates with embedded explainability features capturing preference share in EU public procurement evaluations. Monitor hyperscaler marketplace partnership announcements as inflection indicators for distribution channel power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Assessment | Certification investments unlock public procurement eligibility across member states before competitive windows close. |
| Hyperscaler Marketplace Partnership | AWS and Azure distribution channels bypass direct enterprise sales cycles for authentication-as-a-service deployment. |
| Edge NPU Hardware Integration | On-device matching capabilities address GDPR data sovereignty requirements while eliminating cloud latency dependencies. |
| Behavioral Biometrics Acquisition | Keystroke dynamics and gait analysis algorithms extend continuous authentication layers for financial fraud detection. |
| India BIS Certification Pathway | Standardized vendor qualification criteria under UIDAI mandates accelerate Aadhaar-linked contract capture. |
Methodological Framework
Multiple input streams—primary interviews with biometric software executives, IT procurement officers at financial institutions, and system integration specialists—were reconciled against secondary validation from SEC filings, hyperscaler capex disclosures, and NIST accuracy benchmark publications. Bottom-up triangulation across deployment model adoption curves and top-down reconciliation against government identity program budgets shaped volume and value estimates.
Data-stream reconciliation across technology, end-user, deployment, and application segmentation dimensions anchored the analytical framework throughout the projection horizon. CAGRs were derived from elasticity modeling against authentication transaction growth and cloud infrastructure expansion curves. Modeled inputs included EU AI Act compliance timeline assumptions, India BIS certification throughput rates, and NPU penetration forecasts in smartphone and access control terminal shipments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to algorithmic audit obligation expansions beyond the EU and hyperscaler marketplace commission structure revisions. Forecasts reflect documented assumptions regarding interoperability mandate adoption timelines and presentation attack detection standard evolution. Practitioners should monitor NIST test protocol updates and UIDAI tender announcement patterns for early signals of procurement qualification shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Hand Geometry Biometrics Market
Biometrics & Identity Management
Mobile Biometrics Market
Biometrics & Identity Management
Passive Authentication Market
Biometrics & Identity Management
Global Biometric Identification Market
Biometrics & Identity Management
Face Voice Biometric Market
Biometrics & Identity Management
Global Mobile User Authentication Market
Biometrics & Identity Management
Authentication Solution Market
Biometrics & Identity Management
Latin America Biometrics Market
Biometrics & Identity Management
Global Authentication Services Market
Biometrics & Identity Management
Global Biometric Authentication Identification Market
Biometrics & Identity Management
E-Government Identity Management Market
Biometrics & Identity Management
IRIS Biometrics Market
Biometrics & Identity Management
Biometrics As a Service in Healthcare Market
Biometrics & Identity Management
Airport Biometrics Market
Biometrics & Identity Management
Password Management Market
Biometrics & Identity Management
AI-Enabled Biometrics Market