
 OTN Transport and Switching Equipment Market | 2026-2036
OTN Transport and Switching Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
OTN Transport and Switching Equipment Market Analytics
Carrier procurement channels for OTN transport and switching equipment is narrowing as hyperscale data center operators and national telecom incumbents consolidate vendor lists around proven interoperability. Ciena Corporation sustains technology leadership in programmable coherent optics, while Huawei Technologies Co. Ltd. dominates integrated transport platforms across Asia-Pacific deployment corridors. Nokia Corporation leverages its Bell Labs heritage to anchor high-performance photonic switching portfolios in European and North American carrier networks.
OTN transport and switching equipment encompasses optical line terminals, reconfigurable optical add-drop multiplexers, and packet-optical transport platforms engineered to ITU-T G.709 standards for digital wrapper multiplexing of client signals onto wavelength-division multiplexed fiber infrastructure. These systems enable sub-wavelength grooming, deterministic latency, and carrier-grade resilience for converged packet and optical networks. Wavelength Division Multiplexing technology occupies the largest installed base but Software-Defined Networking integration represents the fastest-expanding configuration as operators automate provisioning across disaggregated optical layers. Cloud Services application demand outpaces legacy telecommunication spending as content delivery networks and AI training clusters strain existing fiber capacity.
The International Telecommunication Union shapes product standards through G.709 and G.798 series recommendations that govern OTN frame structures and equipment functional models, while the FCC in the United States and MIIT in China set spectrum, licensing, and infrastructure deployment rules that directly condition carrier capital expenditure timing. Compliance with these layered regulatory frameworks determines market access eligibility and influences product development roadmaps across vendor engineering organizations. Stakeholders must monitor evolving national broadband subsidy programs and optical spectrum policy revisions to anticipate procurement windows and align R&D investments with certified interoperability requirements.
Market Dynamics
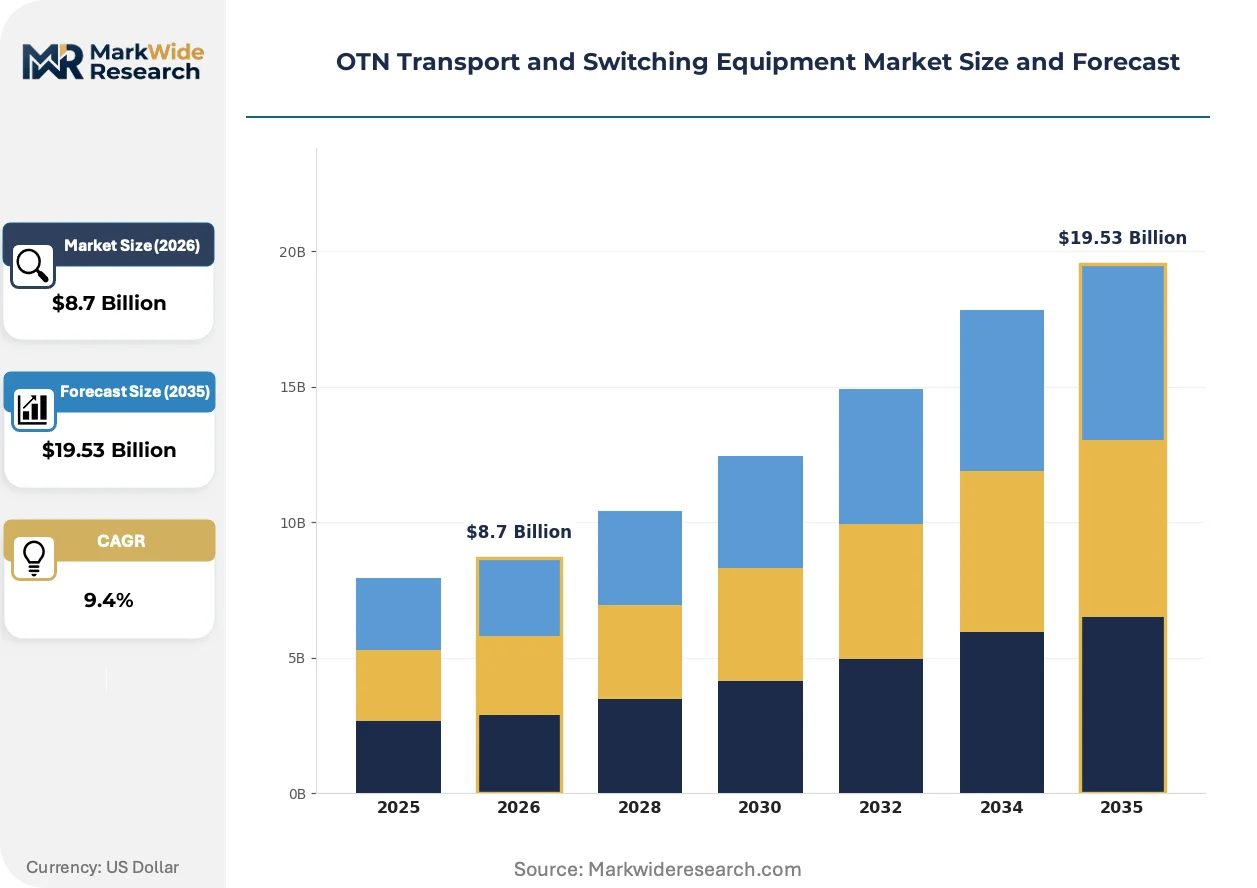
The transition from 100G to 400G coherent optics is compressing equipment refresh cycles as cloud service providers and telecom carriers rebuild backbone infrastructure to support AI training clusters and 5G transport requirements.
Growth Catalysts
- Cloud backbone expansion:Hyperscale data center operators are deploying 400G wavelength-division multiplexing systems to interconnect distributed AI compute facilities, creating sustained equipment demand.
- ITU-T G.709 standards evolution:The latest amendments to the Optical Transport Network frame structure specifications enable more efficient sub-wavelength grooming and lower-latency service delivery.
- National broadband programs:Subsidized fiber rollout initiatives in the United States, Germany, and China are accelerating metro and long-haul transport procurement timelines.
Market Restraints
- Indium phosphide supply concentration:Foundry capacity for coherent optical DSPs and indium phosphide modulators concentrates among a limited set of Asian semiconductor manufacturers.
- Trade control complexity:Export licensing requirements affecting optical component shipments to certain deployment corridors create procurement uncertainty for multinational carriers.
- Copper interconnect substitution:High-volume data center interconnects under 2 kilometers increasingly favor active electrical cables over optical transceivers for cost-sensitive applications.
Strategic Opportunities
- Software-defined optical layer automation:Integration of SDN controllers with disaggregated optical transport platforms enables programmable provisioning that reduces operational expenditure.
- Rural fiber backhaul:Underserved regions in India and Brazil present deployment opportunities for cost-optimized OTN switching platforms with reduced port density.
- EU Green Deal alignment:Energy-efficient coherent optics certification under evolving European sustainability frameworks creates preference for low-power 400G ZR+ solutions.
Industry Challenges
- Photonic integration engineering scarcity:The specialized skill set required for silicon photonics and indium phosphide chip design outpaces university program output.
- Multi-vendor interoperability certification:Carrier requirements for mixed-vendor OTN network operation extend testing timelines and complicate product launch schedules.
- Legacy TDM service migration:Embedded base of SONET/SDH equipment requires careful traffic grooming during transition to packet-optical infrastructure without service disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OTN Transport and Switching Equipment Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Multiplexers, Transmitters Technology: Wavelength Division Multiplexing, Digital Cross Connect, Optical Transport Network, Software-Defined Networking Application: Telecommunication, Data Center, Enterprise Network, Cloud Services End User: Service Providers, Enterprises, Government, Research Institutions |
| Companies Covered | Nokia Corporation, Ciena Corporation, Cisco Systems Inc., Huawei Technologies Co. Ltd., ZTE Corporation, Fujitsu Limited, Infinera Corporation, ADVA Optical Networking, Ribbon Communications Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OTN Transport and Switching Equipment Market Evolving Landscape
Operational models across optical transport are pivoting toward autonomous provisioning and energy-optimized architectures as artificial intelligence workloads reshape capacity planning methodologies.
Coherent optical transmission is migrating from 100G QPSK modulation to 400G 16QAM and higher-order constellations. Cloud service providers are deploying these systems at unprecedented density in AI training clusters. The shift is compressing the economic lifespan of existing 100G line cards and accelerating chassis replacement decisions.
China's MIIT spectrum policy revisions are mandating more efficient optical spectrum utilization in national backbone networks. The regulations push carriers toward flexible grid ROADM architectures and tighter channel spacing. Equipment vendors are responding with programmable transceoders that support multiple modulation formats on common hardware.
Carrier procurement patterns now favor disaggregated optical line systems over vertically integrated transport platforms. Network operators are sourcing white-box transponders separately from optical layer components and control plane software. This unbundling is most pronounced in North American and Western European markets where open optical networking specifications have gained traction.
OTN Transport and Switching Equipment Market Segmentation
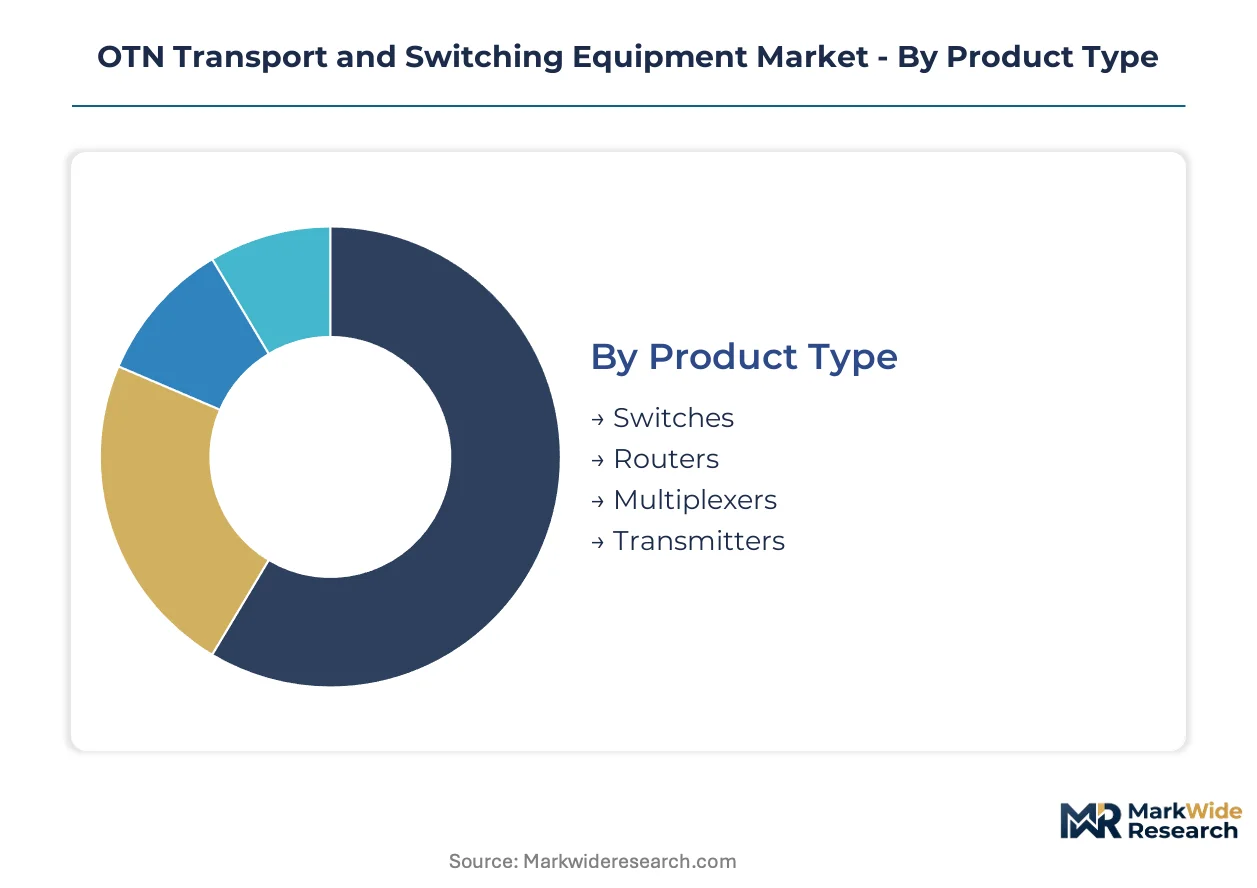
Segmentation in OTN transport equipment reveals distinct procurement rhythms across product categories. Equipment refresh cycles vary dramatically between core infrastructure and edge aggregation layers.
Product Type:
Switches turn over fastest as data centers upgrade port densities, while transmitters maintain the longest deployment cycles given fiber plant longevity.
- Switches:Packet-optical switches integrate OTN switching with Ethernet aggregation at 400G line rates. Cloud service providers in the United States and China are consolidating vendor lists around programmable platforms that support hitless software upgrades.
- Multiplexers:Reconfigurable optical add-drop multiplexers enable wavelength grooming across flexible grid architectures. German carriers are deploying ROADM nodes with CDC (colorless, directionless, contentionless) capabilities to support 5G transport timing requirements.
- Routers:IP-over-DWDM routers collapse layers by integrating coherent optics directly into routing platforms.
- Transmitters:Coherent optical transmitters with silicon photonics modulators anchor long-haul links.
Multiplexers anchor the volume base while switches gain share at the steepest rate.
Technology:
Cost tiers separate legacy TDM infrastructure from programmable packet-optical platforms requiring software subscription models.
- Software-Defined Networking:SDN controllers automate optical layer provisioning through open northbound APIs. North American hyperscale operators are standardizing on disaggregated control planes to reduce operational expenditure across multi-vendor networks.
- Wavelength Division Multiplexing:Dense WDM systems with 400G coherent channels dominate submarine and terrestrial long-haul corridors. Chinese national backbone deployments are compressing channel spacing to 50 GHz to maximize fiber spectrum utilization.
- Optical Transport Network:ITU-T G.709 compliant framing enables sub-wavelength grooming and deterministic latency guarantees.
- Digital Cross Connect:Legacy DXC platforms persist for TDM service aggregation in regulated carrier environments.
Wavelength Division Multiplexing commands the installed base while Software-Defined Networking climbs the fastest.
Application:
Customer type determines margin structure, with cloud operators demanding volume discounts that telecom carriers rarely achieve.
- Cloud Services:Hyperscale data center interconnects require 400G ZR+ coherent pluggables at unprecedented port density. AI training clusters in Northern Virginia and Frankfurt are straining existing fiber capacity and forcing accelerated chassis replacements.
- Data Center:Colocation facilities deploy modular OTN switching platforms with pay-as-you-grow licensing. Chinese cloud providers are expanding metro data center footprints under MIIT infrastructure deployment guidelines.
- Telecommunication:National carriers maintain OTN cores for 5G fronthaul and mobile backhaul aggregation.
- Enterprise Network:Private optical networks for financial services demand deterministic latency guarantees.
Telecommunication anchors the volume base while Cloud Services expands most quickly.
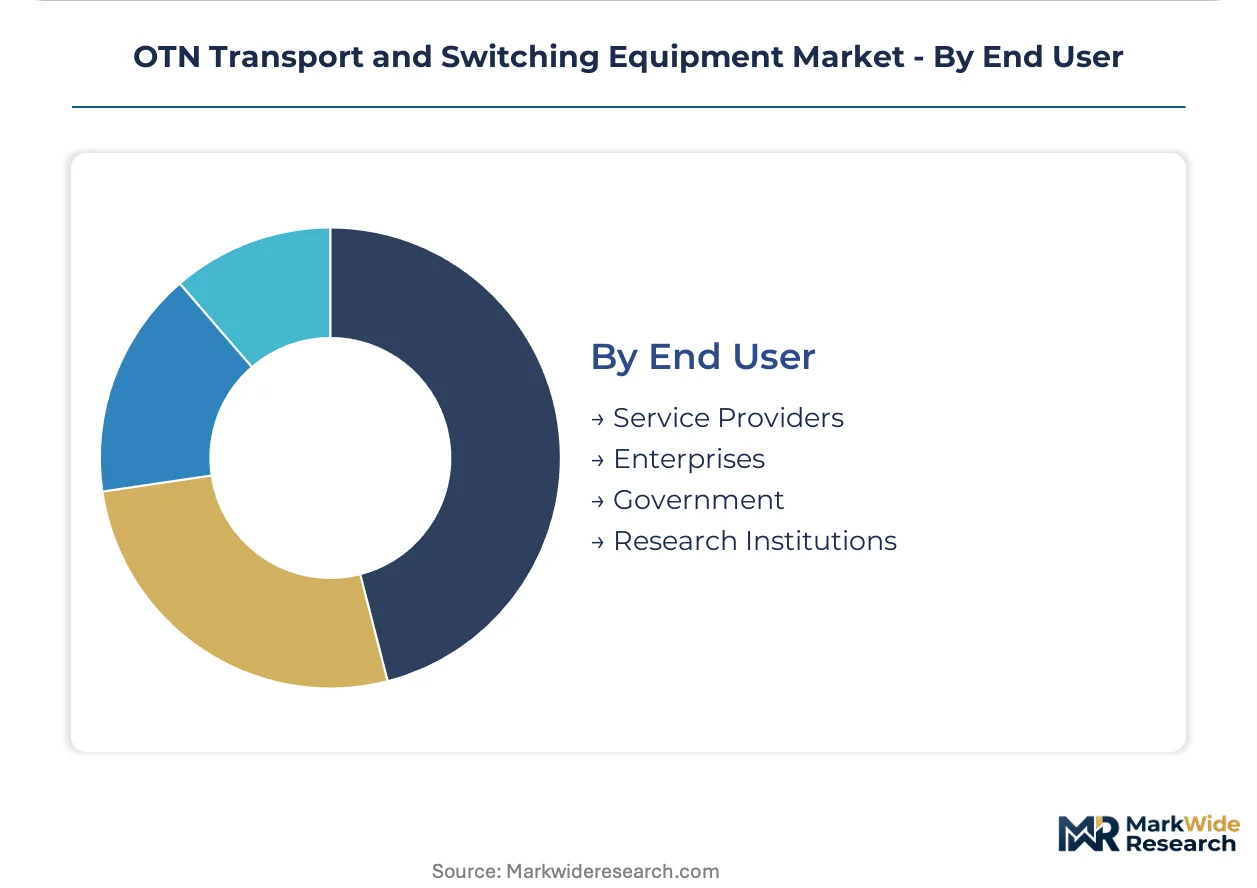
End User:
Supply concentration varies sharply, with service providers consolidating around three-vendor shortlists while research institutions source specialized test equipment.
- Service Providers:Tier-1 carriers in Germany and the United States are mandating open line system interoperability to avoid single-vendor lock-in. Procurement teams now require OIF-compliant transponders that operate across disaggregated optical layers.
- Government:National security networks specify domestically sourced encryption-capable OTN equipment. FCC infrastructure subsidy programs are accelerating rural fiber backhaul deployments with OTN switching at aggregation hubs.
- Enterprises:Large enterprises deploy private wavelength services for campus interconnect and disaster recovery.
- Research Institutions:National laboratories source experimental 800G coherent prototypes for next-generation network research.
Service Providers anchor the volume base while Government procurement climbs the fastest under broadband subsidy expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment pricing power concentrates in the United States and Germany where carrier consolidation strengthens procurement leverage, while Chinese vendors absorb margin compression through integrated supply chains. Regulatory subsidy timing and spectrum policy divergences create asynchronous procurement windows across deployment corridors. National security classifications increasingly condition vendor eligibility in backbone infrastructure tenders.
United States
Hyperscale data center operators in Northern Virginia and Dallas-Fort Worth are driving 400G coherent port demand for AI training cluster interconnects. FCC broadband subsidy programs under the Infrastructure Investment and Jobs Act accelerate rural fiber backhaul deployments with OTN switching at aggregation hubs. The Bay Area and Seattle technology corridors host cloud provider engineering teams that specify disaggregated optical line system architectures.
China
MIIT spectrum policy revisions mandate tighter channel spacing and flexible grid ROADM architectures in national backbone networks. State-directed capital expenditure flows through China Mobile, China Telecom, and China Unicom for 5G transport infrastructure buildouts. The Yangtze River Delta and Pearl River Delta regions concentrate equipment manufacturing and systems integration capabilities.
Germany
Deutsche Telekom and Vodafone Germany are consolidating vendor lists around open optical networking specifications to avoid single-source dependencies. EU Green Deal alignment requirements create procurement preference for energy-efficient 400G ZR+ coherent solutions with certified power consumption metrics. The Munich and Berlin metro areas anchor carrier network operations centers and equipment testing facilities.
Japan
METI industrial policy supports domestic coherent optical component manufacturing through targeted R&D consortia and procurement preference guidelines. NTT and KDDI are deploying OTN switching platforms for 5G mobile backhaul aggregation in Tokyo-Osaka-Nagoya corridor networks. Yokohama and Osaka house photonics research institutes that collaborate with equipment vendors on next-generation modulation format development.
India
TRAI infrastructure sharing mandates and BharatNet rural fiber programs create demand for cost-optimized OTN platforms with reduced port density. Reliance Jio and Bharti Airtel are expanding metro data center interconnect capacity in Mumbai, Delhi-NCR, and Bangalore. The Department of Telecommunications spectrum allocation timelines condition carrier capital expenditure phasing for transport network upgrades.
OTN Transport and Switching Equipment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in modulator and DSP supply. The vendor base stratifies between vertically integrated transport platform providers and disaggregated optical layer component suppliers. Three archetypes dominate: coherent optics technology leaders, integrated transport platform vendors, and open networking specialists pursuing white-box market positions. Competitive moves center on strategic partnerships for interoperability certification and vertical integration into indium phosphide foundry capacity.
Among North American equipment vendors, Ciena Corporation and Cisco Systems Inc. exemplify divergent strategic positioning—Ciena occupying the coherent optics technology leadership archetype while Cisco represents IP-layer convergence into transport infrastructure. Nokia Corporation anchors the European integrated platform tradition through its Bell Labs heritage. These three companies illustrate how geographic origin and corporate history shape competitive archetype selection in carrier procurement markets.
| Leading Market Players |
|---|
| Nokia Corporation |
| Ciena Corporation |
| Cisco Systems Inc. |
| Huawei Technologies Co. Ltd. |
| ZTE Corporation |
| Fujitsu Limited |
| Infinera Corporation |
| ADVA Optical Networking |
| Ribbon Communications Inc. |
| Others |
Value Network & Pricing Analysis
Yokohama's photonics manufacturing cluster anchors coherent optical component supply, with its DSP and modulator foundry capacity directly conditioning pricing power for 400G transponder vendors serving North American hyperscale operators.
Pricing Analysis
Configured-to-order pricing for programmable ROADM nodes commands a 15-25% premium over standard 100G line card configurations. Three-tier pricing structure across premium, standard, and economy levels separates ITU-T G.709-certified platforms from basic wavelength-division multiplexing gear. Cost compression in the economy tier is intensifying because Chinese vendors are absorbing margin erosion through integrated indium phosphide supply chains. Cloud service providers exhibit the highest price sensitivity due to volume procurement leverage, while government national security networks accept premium pricing for domestic encryption capabilities.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for multinational carriers sourcing disaggregated optical line systems. Foundry capacity concentrates in Taiwan, South Korea, and Japan for coherent DSPs and silicon photonics modulators. The OTN equipment supply chain draws from indium phosphide substrates, rare-earth-doped fiber amplifiers, and specialized ASIC packaging. Single-source vulnerability persists for 400G ZR+ coherent pluggables where only two Asian foundries qualify for automotive-grade reliability standards. Distribution runs through carrier procurement consortia and hyperscale direct sourcing teams rather than traditional channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the vendor base creates entry niches as carrier procurement shifts toward disaggregated optical layers and open line system interoperability mandates proliferate.
For Market Incumbents: Entrench through backward integration into indium phosphide foundry capacity to secure coherent optics supply against tariff disruption. Deepen certification investments for OIF-compliant transponders that operate across multi-vendor ROADM architectures. Defend against white-box encroachment by embedding SDN controllers with carrier network operations centers in Northern Virginia and Frankfurt. For New Entrants and Emerging Players: Build out rural fiber backhaul specialization for cost-optimized OTN platforms with reduced port density targeting BharatNet and FCC subsidy corridors. India and Brazil present the most penetrable geographies given incumbent vendor list consolidation fatigue. Pursue a go-to-market angle through systems integration partnerships with regional carriers lacking in-house optical engineering expertise. For Investors and Strategic Acquirers: Carve-out targets emerge from telecom equipment conglomerates divesting non-core optical transport divisions to focus on 5G radio access networks. Long-term viability hinges on coherent optics IP portfolios and established carrier qualification relationships. Watch for MIIT spectrum policy acceleration as the inflection signal indicating Chinese state capital expenditure timing for backbone infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Open Line System Certification | OIF-compliant interoperability unlocks multi-vendor procurement for Deutsche Telekom and Verizon. |
| Indium Phosphide Foundry Acquisition | Captive modulator supply insulates Ciena and Nokia against Asian semiconductor tariff exposure. |
| SDN Controller Platform Launch | Disaggregated control planes reduce operational expenditure across China Mobile's metro networks. |
| Rural Fiber Backhaul Partnership | BharatNet and FCC subsidy alignment positions ADVA for cost-optimized 100G aggregation hub deployments. |
| 400G ZR+ Energy Certification | EU Green Deal power metrics preference differentiates low-coherent solutions in Vodafone Germany tenders. |
Research Methodology
Cross-validation between carrier procurement officer interviews and vendor SEC filings anchors the qualitative findings in this study. Primary fieldwork encompassed optical network architects at hyperscale operators, transport engineering directors at Tier-1 carriers, photonics R&D leads at component suppliers, and regulatory affairs specialists at equipment vendors. Secondary sources included ITU-T G.709 standards documentation, FCC Infrastructure Investment and Jobs Act disbursement records, MIIT spectrum policy bulletins, and EU Green Deal technical specifications. Bottom-up equipment shipment modeling triangulated against top-down carrier capital expenditure disclosures.
Calibration against historical 100G-to-400G transition cycles informed penetration curve assumptions across the projection horizon. Segmentation dimensions spanned product type, technology configuration, application vertical, and end-user archetype. CAGRs derived from slope-intercept analysis of equipment refresh cycle compression and cloud backbone expansion trajectories. Industry-specific inputs incorporated coherent optics port density trends and national broadband subsidy program phasing.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-directed vendors or trade policy escalations would shift outcomes. Model boundaries exclude copper interconnect substitution above 2 kilometers and experimental 800G coherent prototypes not yet qualified for production deployment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Information and Communication Technology
Estonia E-Commerce Market
Information and Communication Technology
Middle East and Africa Digital Signage Software Market
Information and Communication Technology
Automotive Digital Retailing Software Market
Information and Communication Technology
Acoustic Simulation Software Market
Information and Communication Technology
Enterprise Mobility in Energy Sector Market
Information and Communication Technology
Bitcoin Project Incubator Service Market
Information and Communication Technology
Europe Educational Robot Market
Information and Communication Technology
Netherlands Data Center Rack Market
Information and Communication Technology
UK Point of Sale Software Market
Information and Communication Technology
Internet Protocol Version 6 (IPv6) Market
Information and Communication Technology
Global Retail Execution Software Market
Information and Communication Technology
Asia-Pacific Database Management Software Market
Information and Communication Technology
Spain Sports Management Software Market
Information and Communication Technology
Artificial Intelligence Oven Market
Information and Communication Technology
Backup-As-A-Service (Baas) Market
Information and Communication Technology
Middle East Metaverse Market