
 Spain Sports Management Software Market | 2026-2036
Spain Sports Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Sports Management Software Market Insights
Buyer concentration among Spain's amateur sports clubs is decoupling from traditional federation-controlled procurement toward independent SaaS selection. SportEasy leverages cloud-native architecture to anchor its position among regional football leagues. Teamer competes through mobile-first scheduling tools that sustain engagement across multisport associations. PlayyOn differentiates via integrated payment collection features that control revenue workflows for smaller clubs.
Spain sports management software comprises cloud-hosted and on-premise platforms that automate athlete registration, fixture coordination, financial tracking, and stakeholder communication for sports organizations. These systems typically operate through API-connected modules with real-time synchronization across desktop and mobile endpoints, serving federations that must manage membership databases exceeding ten thousand records. Deployment mode insights reveal cloud-based delivery capturing the fastest expansion as amateur clubs abandon legacy server installations, while product type dynamics show team management modules retaining the deepest margin pools due to recurring subscription structures. End user patterns indicate professional teams representing a mature segment with slower switch rates, whereas fitness centers emerge as a structurally underpenetrated category with higher acquisition costs.
Spain's Ley del Deporte and Royal Spanish Football Federation operational statutes shape product requirements by mandating digital member registries and transparent financial reporting from affiliated clubs. The national data protection authority enforces GDPR-aligned athlete data handling protocols that constrain vendor architecture choices. Stakeholders must monitor forthcoming federation API standardization initiatives that will determine platform interoperability and market access tiers.
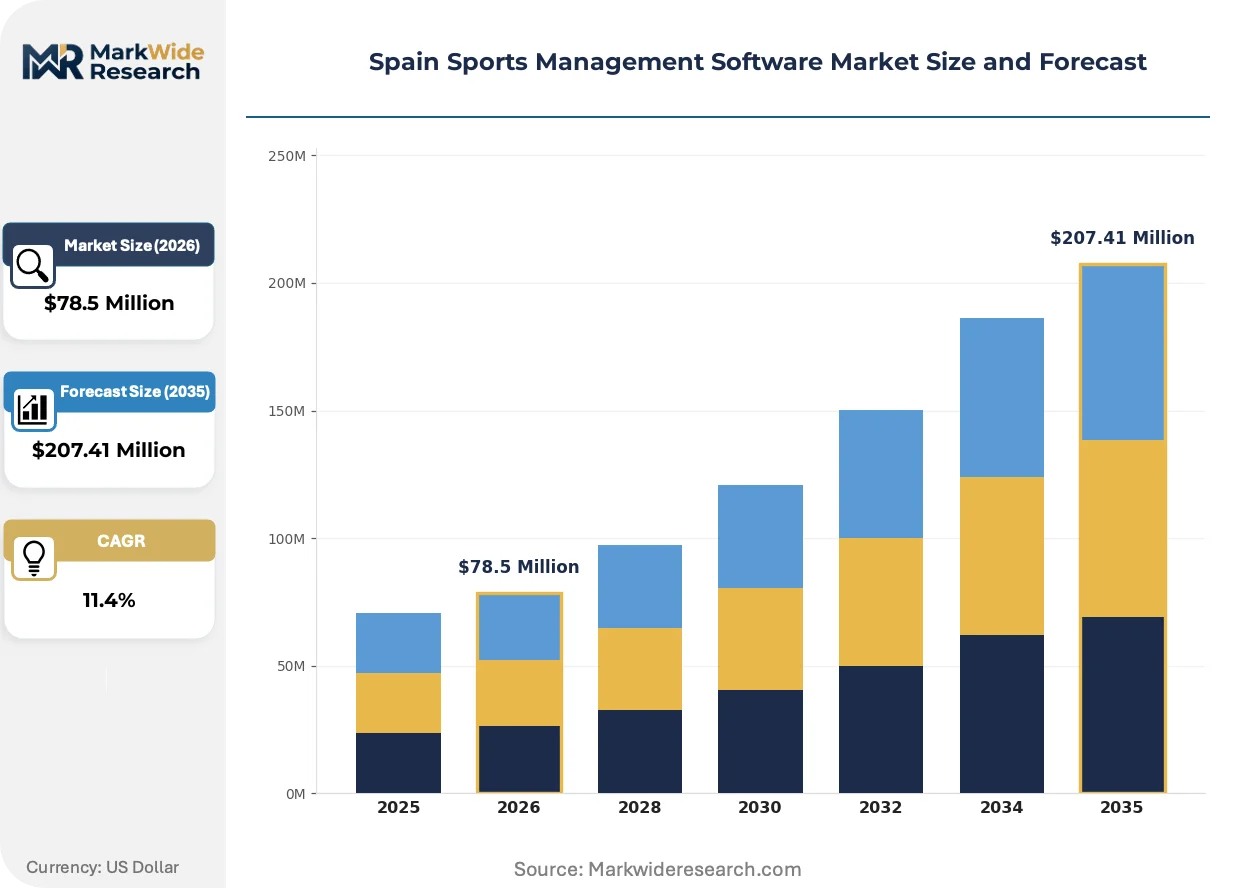
Market Dynamics
Spain's Ley del Deporte is forcing amateur football clubs across Catalonia and Andalusia to abandon paper-based member registries for cloud-hosted governance platforms, compressing procurement cycles and reshaping vendor selection criteria.
Growth Catalysts
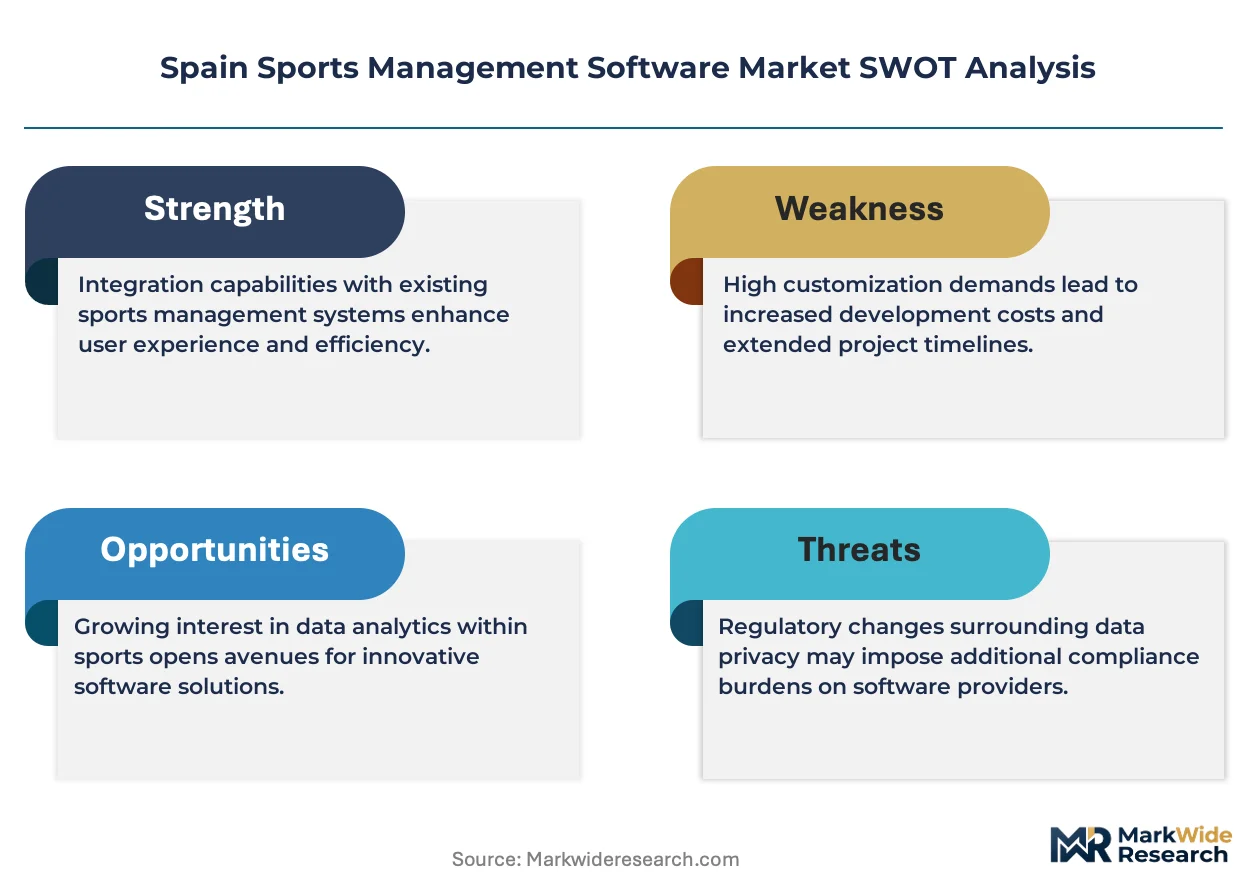
- GDPR-Aligned Data Mandates:The national data protection authority enforces athlete data handling protocols that require federations to maintain transparent digital registries, creating compliance-driven demand for secure cloud architectures.
- Grassroots Football Density:Catalonia's amateur club networks generate concentrated procurement volume as regional leagues seek operational parity with Royal Spanish Football Federation standards.
- Mobile-First Engagement:Multisport associations in Andalusia prioritize scheduling tools accessible via smartphone interfaces, accelerating platform refresh cycles.
Market Restraints
- Legacy Server Sunk Costs:Established clubs in Madrid retain on-premise installations with multi-year depreciation schedules, delaying SaaS migration timelines.
- Federation API Uncertainty:Pending standardization initiatives from the Royal Spanish Football Federation create interoperability risk for vendors investing in proprietary connector development.
- Small-Club Budget Rigidities:Annual subscriptions exceeding €500 strain treasuries of village-level associations in Extremadura and Castilla-La Mancha.
Strategic Opportunities
- Fitness Center White Space:Commercial gyms in Barcelona and Valencia remain structurally underpenetrated, presenting higher-margin vertical expansion paths.
- Payment Integration Convergence:Combining fixture management with embedded revenue collection addresses cash-flow visibility gaps for treasurer-led clubs.
- Basque Country Regional Expansion:Independent sporting culture in autonomous communities with distinct linguistic governance creates localization service premiums.
Industry Challenges
- Technical Staff Scarcity:Rural clubs in Galicia lack personnel capable of configuring API connections between member databases and federation reporting portals.
- Multi-Platform Integration Friction:Disparate legacy accounting tools resist seamless data exchange with modern team management modules, forcing manual reconciliation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Sports Management Software Market |
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $207.41 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Team Management, Event Scheduling, Performance Analytics, Fan Engagement Deployment: Cloud-Based, On-Premise, Hybrid, Mobile End User: Professional Teams, Amateur Clubs, Sports Associations, Fitness Centers Service Type: Training Solutions, Ticketing Services, Marketing Solutions, Consulting |
| Companies Covered | SportEasy, Teamer, PlayyOn, SportMember, Director 11, TeamSnap, Playpass, TeamTracky, Blue Star Sports, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Sports Management Software Market Trends and Innovations
Cloud-native architectures are displacing server-based installations across Spain's amateur sports ecosystem, while regulatory pressure and shifting procurement authority reshape how clubs evaluate and deploy management platforms.
Blockchain-verified credentialing is decentralizing athlete identity management across regional federations. The Royal Spanish Football Federation pilots distributed ledger protocols for tamper-proof member verification. Basque and Catalan leagues adopt these standards fastest, compressing fraud risk while reducing manual validation overhead for tournament eligibility checks.
Spain's Ley del Deporte mandates transparent financial reporting from all affiliated clubs, forcing treasurers to adopt automated audit trails. The national data protection authority enforces GDPR-aligned protocols that constrain vendor data architecture choices. Smaller associations in Andalusia respond by prioritizing platforms with pre-configured compliance modules over custom-built solutions.
Buyer authority is migrating from federation procurement committees to individual club committees with independent SaaS evaluation rights. Regional football leagues in Catalonia now select platforms without central federation approval, fragmenting historical vendor lock-in. This pattern appears strongest among multisport associations seeking scheduling flexibility across disciplines.
Spain Sports Management Software Market Segmentation
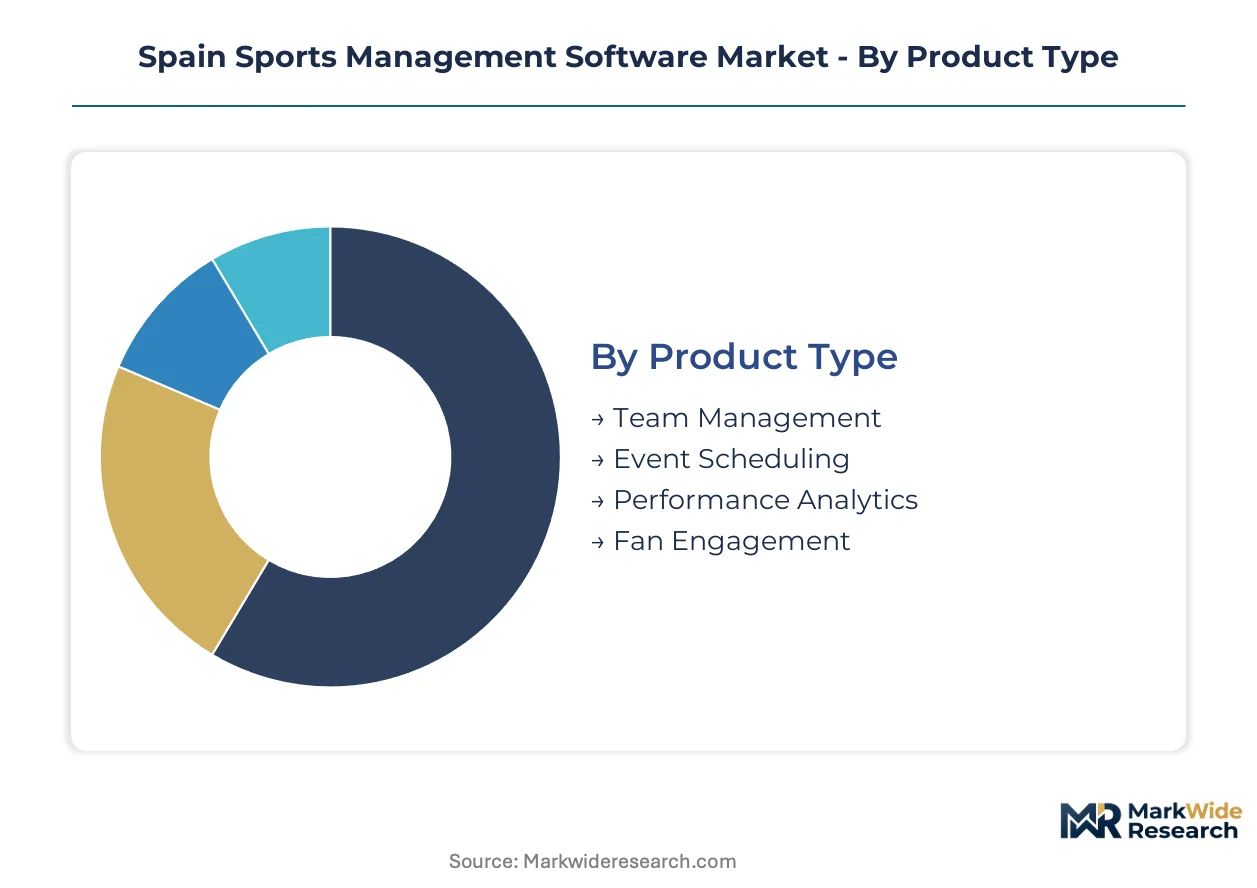
Spain's sports management software market fragments across four critical dimensions that determine procurement authority and compliance burden. Amateur football clubs in Catalonia and Andalusia drive volume concentration, while Ley del Deporte mandates reshape which deployment modes and service types federations will certify.
Product Type:
Certification requirements from Spain's national data protection authority and the Royal Spanish Football Federation vary sharply across product modules, with athlete data handling protocols forcing architecture decisions.
- Team Management:Cloud-native platforms automate member registration, fixture coordination, and financial tracking through API-connected modules. Catalonia's amateur club networks generate concentrated procurement volume as regional leagues seek operational parity with federation standards.
- Event Scheduling:Mobile-first interfaces enable real-time fixture coordination across multisport associations. Andalusian clubs prioritize smartphone accessibility, accelerating platform refresh cycles and displacing legacy calendar tools.
- Performance Analytics:Athlete monitoring dashboards integrate biometric data streams for coaching staff. GDPR-aligned handling protocols constrain vendor architecture choices for federations managing sensitive health records.
- Fan Engagement:Digital membership portals and communication tools sustain stakeholder relationships. Smaller associations in Extremadura delay adoption due to subscription cost rigidities.
Leading the category by volume: Team Management. Expanding most quickly: Event Scheduling.
Deployment:
Cost tier stratification separates enterprise-grade installations from lightweight SaaS subscriptions accessible to village-level treasuries.
- Cloud-Based:Federated data architectures with real-time synchronization across desktop and mobile endpoints. Amateur clubs abandon legacy server installations fastest in Catalonia and Andalusia where Ley del Deporte compliance deadlines compress procurement cycles.
- On-Premise:Server-based installations retained by established Madrid clubs with multi-year depreciation schedules delaying SaaS migration timelines.
- Hybrid:Mixed architectures bridging legacy accounting tools with modern team management modules. Galician rural clubs face technical staff scarcity configuring API connections to federation reporting portals.
- Mobile:Smartphone-native applications prioritizing scheduling flexibility. Multisport associations select these without central federation approval, fragmenting historical vendor lock-in.
Dominant by revenue: Cloud-Based. Gaining share fastest: Mobile.
End User:
Application maturity varies from saturated professional segments to structurally underpenetrated verticals with higher acquisition costs.
- Professional Teams:Mature segment with slower switch rates and established vendor relationships. Royal Spanish Football Federation operational protocols drive standardization requirements.
- Amateur Clubs:Grassroots football density in Catalonia generates procurement volume as Ley del Deporte mandates digital governance standards.
- Sports Associations:Multisport bodies seeking cross-discipline scheduling flexibility. Buyer authority migrates from federation procurement committees to independent club committees.
- Fitness Centers:Commercial gyms in Barcelona and Valencia remain structurally underpenetrated, presenting higher-margin vertical expansion paths with distinct operational workflows.
Highest penetration: Professional Teams. Steepest expansion trajectory: Fitness Centers.
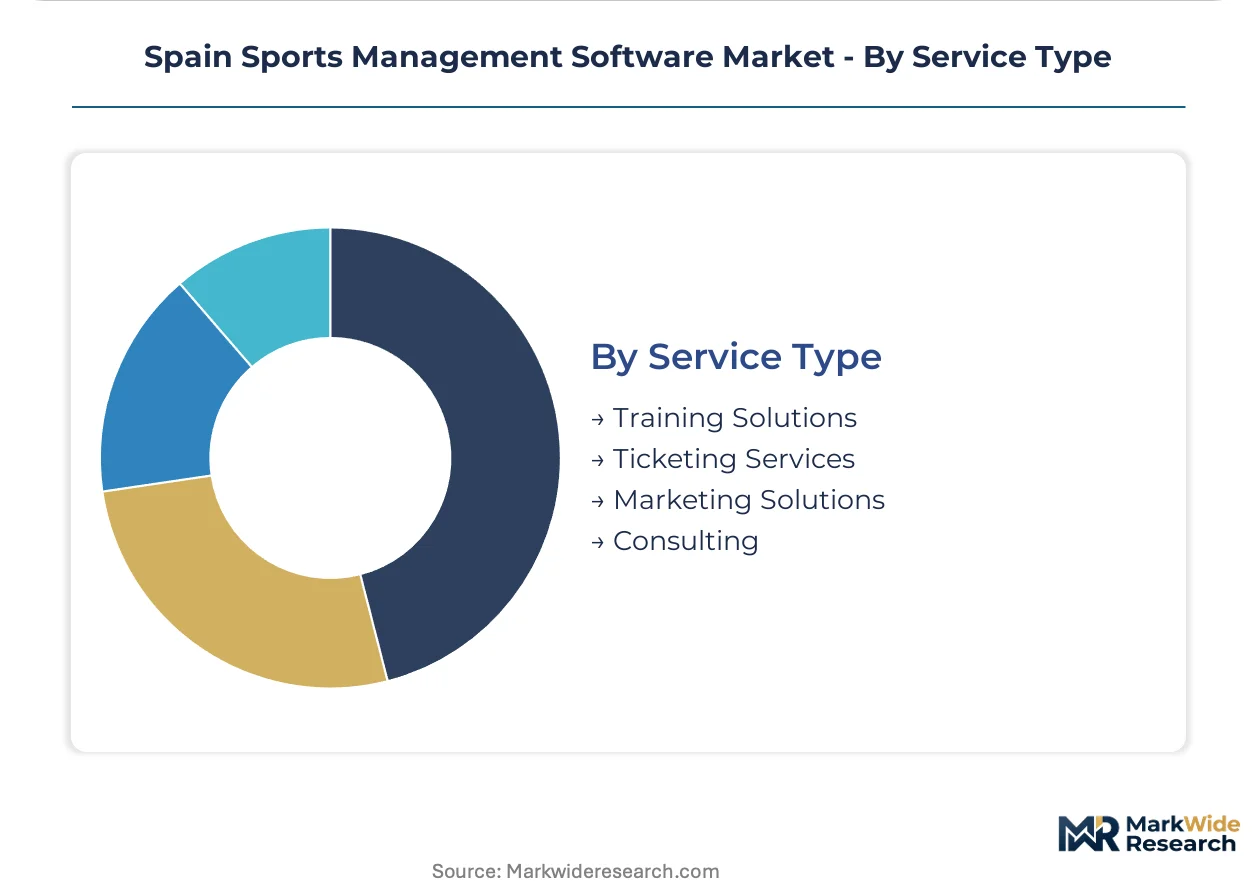
Service Type:
Customer type differentiation separates compliance-driven federations from revenue-optimizing commercial operators.
- Training Solutions:Athlete development modules with embedded credentialing and progression tracking. Basque and Catalan leagues adopt blockchain-verified standards fastest.
- Ticketing Services:Embedded revenue collection addressing cash-flow visibility gaps for treasurer-led clubs. Payment integration convergence creates platform stickiness.
- Marketing Solutions:Sponsor management and digital outreach tools. Smaller associations deprioritize these modules against mandatory compliance spending.
- Consulting:Implementation support for API standardization and federation portal integration. Technical staff scarcity in rural regions sustains service premiums.
Deepest margin pool: Training Solutions. Climbing fastest: Ticketing Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's sports management software demand concentrates in autonomous communities with dense amateur football networks and progressive digital governance mandates. Catalonia and Andalusia generate the highest procurement volumes as regional leagues accelerate cloud platform adoption ahead of Ley del Deporte compliance deadlines.
Catalonia
Grassroots football density across Barcelona and Tarragona provinces drives concentrated platform procurement. The regional government's digital sports initiative subsidizes SaaS adoption for clubs with under 500 members. Girona-based multisport associations are pioneering mobile-first scheduling tools that bypass traditional federation procurement channels.
Andalusia
Seville and Málaga amateur clubs prioritize smartphone-native interfaces for fixture coordination across multiple disciplines. Andalusia's regional sports law pre-dates national mandates, creating earlier compliance pressure than other autonomous communities. Córdoba province treasurers are embedding payment collection modules to address cash-flow visibility gaps.
Madrid
Established clubs in the capital retain on-premise server installations with multi-year depreciation schedules that delay SaaS migration. The Community of Madrid's sports federation maintains stricter API standardization requirements than national baselines. Alcobendas and Las Rozas municipal sports complexes are testing hybrid architectures bridging legacy accounting with modern team management modules.
Basque Country
Independent sporting culture in Bilbao and San Sebastián creates localization service premiums for vendors offering Euskera-language interfaces. The Basque regional government operates distinct athlete credentialing systems that resist seamless integration with Royal Spanish Football Federation protocols. Vitoria-Gasteiz rugby and pelota associations are adopting blockchain-verified membership standards faster than football-centric regions.
Valencia
Commercial fitness centers in Alicante and Castellón provinces represent structurally underpenetrated verticals with higher-margin expansion potential. The Valencian Community's tourism-driven sports economy prioritizes fan engagement modules for event-based revenue. Elche and Benidorm gym operators are testing team management platforms adapted from club sports workflows.
Spain Sports Management Software Market Competitive Landscape
Barcelona-based vendors anchor the cloud-native tier; Madrid specialists hold hybrid deployment expertise. The vendor base splits between federation-aligned incumbents and independent SaaS challengers. Three archetypes dominate: mobile-first scheduling specialists, payment-integrated revenue platforms, and compliance-focused governance suites. Competitive moves concentrate on API standardization partnerships and Basque-Catalan localization services.
Among the independent challengers, SportEasy and Teamer exemplify the mobile-first archetype, while PlayyOn anchors payment-integrated positioning. These three occupy distinct competitive vectors: SportEasy represents cloud-native architecture depth, Teamer exemplifies cross-discipline scheduling flexibility, and PlayyOn sits within embedded revenue workflow specialization. Their collective presence fragments historical federation vendor lock-in across Spain's autonomous communities.
| Leading Market Players |
|---|
| SportEasy |
| Teamer |
| PlayyOn |
| SportMember |
| Director 11 |
| TeamSnap |
| Playpass |
| TeamTracky |
| Blue Star Sports |
| Others |
Pricing and Supply Chain Analysis
Amateur football clubs in Catalonia and Andalusia concentrate procurement authority toward SaaS subscription models that stratify across compliance-grade, feature-rich, and basic tiers. This buyer archetype's budget rigidities compress vendor margins while federation mandates elevate data-security premiums.
Pricing Analysis
Volume concentrates in entry-level subscriptions under €500 annually, while margin pools deepen in compliance-certified tiers with GDPR-aligned audit modules. Pricing stratifies across premium federation-certified, standard cloud-native, and economy mobile-only levels. Cost compression in the entry tier intensifies because village-level associations in Extremadura and Castilla-La Mancha resist recurring fees. Amateur clubs with sub-200 members exhibit highest price sensitivity; professional teams with established vendor relationships show lowest.
Supply Chain Analysis
Technical talent scarcity in Spain's rural autonomous communities constrains implementation velocity for cloud-native platform rollouts. Software development concentrates in Barcelona and Madrid, with customer success operations anchored in Valencia. Infrastructure-as-a-Service draws from Amazon Web Services, Microsoft Azure, and Google Cloud Platform. Single-source vulnerability sits with federation API standardization delays that could fragment platform interoperability. Distribution runs through direct vendor sales teams and regional systems integrators serving multisport associations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's sports management software market functions as a cost-of-compliance arena where Ley del Deporte mandates erect data-architecture barriers that favor vendors with pre-certified governance modules.
For Market Incumbents: Lock in federation API partnerships before Royal Spanish Football Federation standardization finalizes, cementing connector moats against modular challengers. Deepen vertical integration into Basque and Catalan localization services to capture autonomous community premiums. Cloud-native architecture depth represents the priority defensive lever against mobile-first entrants. For New Entrants and Emerging Players: Launch via embedded payment collection workflows targeting treasurer-led clubs in Andalusia and Valencia where cash-flow visibility gaps remain acute. Fitness centers in Barcelona and Alicante present the most penetrable vertical expansion path. White-space concentration in commercial gyms with distinct operational workflows supports a vertical-first go-to-market. For Investors and Strategic Acquirers: The window for entry favors compliance-focused governance suites with pre-built Ley del Deporte certification modules. Long-term viability rests on federation relationship durability and API standardization timing. Watch for Royal Spanish Football Federation interoperability announcements as the inflection signal determining platform tier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Federation API Partnership | Secures interoperability certification ahead of Royal Spanish Football Federation standardization mandates. |
| Localization Service Expansion | Captures premium pricing in Basque Country and Catalonia through Euskera and Catalan language interfaces. |
| Payment Integration Development | Addresses cash-flow visibility gaps for treasurer-led amateur clubs in Andalusia and Extremadura. |
| Fitness Center Vertical Entry | Penetrates structurally underpenetrated commercial gyms in Barcelona and Valencia with adapted workflows. |
| Compliance Module Pre-Certification | Accelerates procurement cycles for clubs facing Ley del Deporte digital governance deadlines. |
Research Methodology
Independent corroboration across federation procurement officers, SaaS vendor executives, and amateur club treasurers underwrites the qualitative findings in this study. Primary fieldwork engaged platform engineers, regional sports association administrators, and national data protection authority compliance leads. Secondary validation drew from Royal Spanish Football Federation operational statutes, Spanish Data Protection Agency regulatory filings, and autonomous community sports law databases. Bottom-up club-level demand estimates and top-down federation membership projections were reconciled through iterative triangulation.
Comparable-period anchoring to pre-mandate adoption baselines established the forecast framework across the projection horizon. Segmentation modeling spanned deployment mode, organization size, product module, and regional compliance deadline clustering. CAGRs were derived from adoption curve analysis calibrated to Ley del Deporte implementation phases. Industry-specific inputs included federation API standardization timelines and GDPR enforcement intensity variations by autonomous community.
The model assumes a particular technology adoption path; alternative pathways for blockchain-verified credentialing would alter the outlook if distributed ledger protocols achieve federation-wide deployment ahead of schedule. Forecasts reflect assumptions about regulatory enforcement consistency and rural technical staffing availability. Material deviation in Royal Spanish Football Federation standardization timing or national data protection authority penalty severity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Conversion Rate Optimization (CRO) Software Market
Software & Services
Online Donation Software Market
Software & Services
Point of Sale (Pos) Software Market
Software & Services
Europe Enterprise Resource Planning (ERP) Software Market
Software & Services
Cloud Testing and ASQ Software Market
Software & Services
Multivariate Testing Software Market
Software & Services
SMS Marketing Software Market
Software & Services
Global License Management Market
Software & Services
Employee Advocacy Software Market
Software & Services
Point Cloud Processing Software Market
Software & Services
Bridge Analysis Software Market
Software & Services
Global Permit Management Software Market
Software & Services
Sales Force Automation Software Market
Software & Services
Commerce As a Service (Caas) Market
Software & Services
Global Programming Software Market
Software & Services
Employee Engagement Solutions Market