
 UK Point of Sale Software Market | 2026-2036
UK Point of Sale Software Market Size, Share, and Industry Trends Forecast 2026-2036
UK Point of Sale Software Market Intelligence
Subscription-based leasing for cloud POS infrastructure is reconfiguring competitive entry barriers for independent software vendors. Lightspeed leverages its multi-vertical product architecture to sustain cross-selling momentum across retail and hospitality. Shopify anchors its UK position through deep integration with domestic payment acquirers and fulfillment networks. Oracle competes at the enterprise tier with database-native transaction processing that reduces latency for high-volume merchants.
Point of sale software comprises transaction processing applications that interface with card readers, barcode scanners, and inventory databases through API-driven middleware layers. The system executes sales authorization, tax calculation, and real-time stock depletion while feeding analytics dashboards for workforce and supply chain planning. Cloud-based deployment leads the product type dimension as merchants abandon server maintenance burdens, while mobile POS registers the fastest structural expansion due to pop-up retail and curbside service models. The hospitality vertical commands concentrated margin pools because table-service workflows require complex modifier handling and kitchen display integration that commands premium licensing tiers.
The UK Payment Systems Regulator and Financial Conduct Authority jointly enforce open banking standards and Strong Customer Authentication protocols that reshape software certification requirements. PCI DSS compliance mandates from the PCI Security Standards Council govern card data handling architectures, pushing vendors toward tokenization and point-to-point encryption. The Information Commissioner's Office GDPR enforcement creates liability exposure around customer purchase histories, forcing explicit consent workflows into loyalty module design. Stakeholders must monitor how real-time payment scheme participation requirements from Pay.UK alter middleware connectivity obligations before committing to platform architectures.
Market Dynamics
Open banking interoperability mandates from the Payment Systems Regulator are forcing incumbent POS vendors to rebuild API architectures, compressing deployment timelines and elevating compliance costs across the UK merchant ecosystem.
Growth Catalysts
- Strong Customer Authentication (SCA):PSD2 enforcement mandates two-factor verification for card-not-present transactions, accelerating merchant migration to certified cloud POS platforms that embed compliant authentication workflows.
- Tablet-based ordering:British quick-service restaurant chains are deploying handheld terminals for tableside payment capture, reducing checkout friction and labor redeployment costs during peak service windows.
- Greater London retail corridor density:High-traffic merchant clusters in the capital generate concentrated demand for low-latency transaction processing and real-time inventory synchronization across multi-location operations.
Market Restraints
- PCI DSS certification costs:Point-to-point encryption and tokenization requirements impose six-figure compliance investments that exclude smaller independent software vendors from enterprise-tier procurement.
- GDPR liability exposure:Information Commissioner's Office enforcement around customer purchase histories forces explicit consent workflows into loyalty module design, extending development cycles.
- Legacy hardware lock-in:Merchants with depreciated on-premise server infrastructure face sunk-cost barriers to cloud migration despite superior total cost of ownership profiles.
Strategic Opportunities
- Manchester hospitality expansion:The city's growing restaurant and hotel clusters present underpenetrated demand for table-service POS with kitchen display system integration.
- Curbside service infrastructure:Mobile POS registers enable pop-up retail and fulfillment-adjacent payment capture, opening deployment models beyond traditional fixed-terminal environments.
- Pay.UK real-time payments:Participation requirements in the national real-time payment scheme create middleware connectivity obligations that favor vendors with pre-certified integration stacks.
Industry Challenges
- API architecture reconfiguration:Open banking interoperability demands are forcing engineering teams to rebuild core middleware layers while maintaining backward compatibility with existing merchant integrations.
- Workforce planning analytics integration:Merchants increasingly demand POS platforms that feed labor optimization dashboards, requiring vendors to develop cross-functional data pipelines beyond transaction processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Point of Sale Software Market |
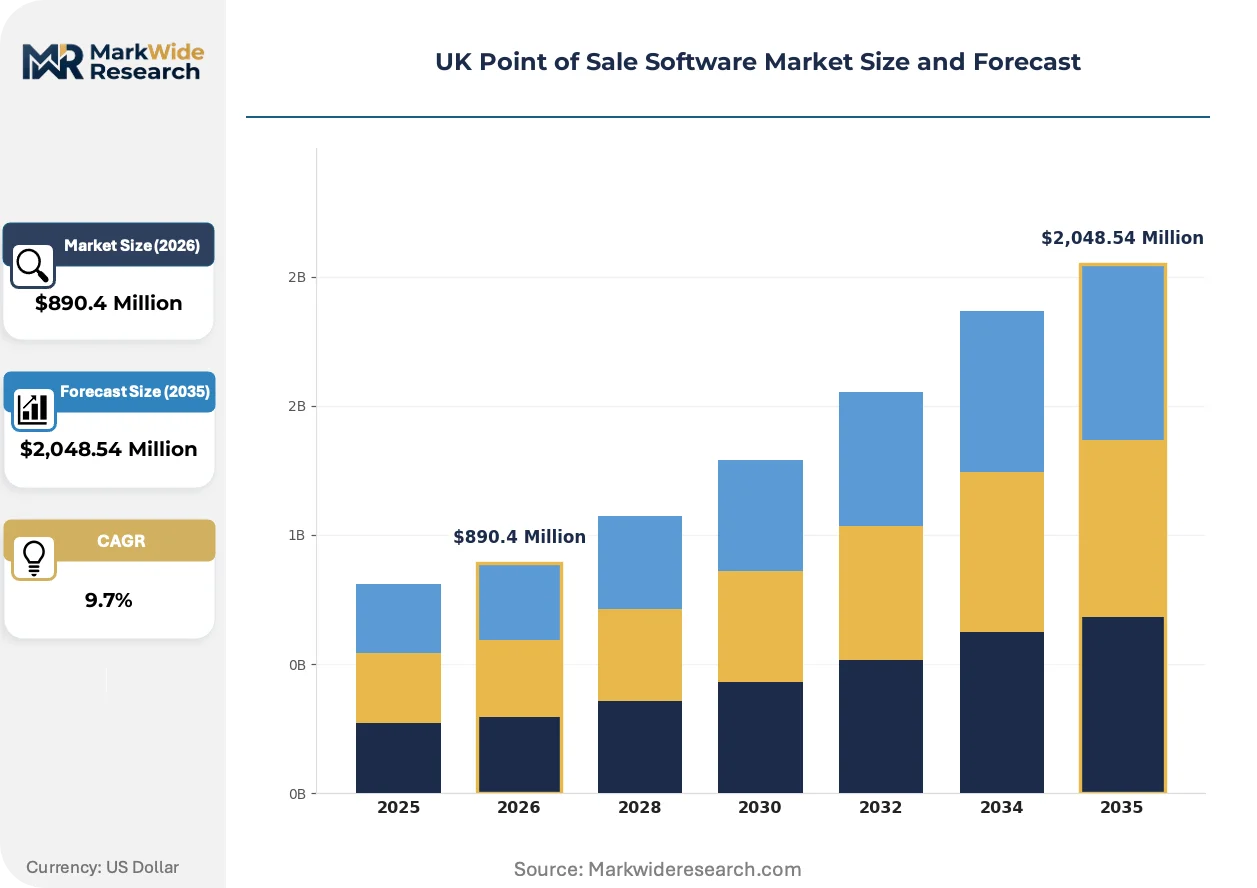
| Market Size in 2026 | $890.4 Million |
| Market Size in 2035 | $2,048.54 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Mobile, Kiosk Industry Vertical: Retail, Hospitality, Healthcare, Entertainment Payment Method: Credit Card, Mobile Payment, Cash, Contactless Deployment Model: Single Site, Multi-Site, Franchise, Enterprise |
| Companies Covered | NCR Corporation, Lightspeed, Oracle, Diebold Nixdorf, Shopify, PayPal, Revel Systems, Clover Network, Flooid, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Point of Sale Software Market Strategic Shifts & Innovations
Cloud-native transaction processing is displacing on-premise server architectures across UK retail and hospitality, compressing deployment timelines and shifting vendor business models toward recurring revenue structures.
Serverless payment processing infrastructure is rendering obsolete dedicated merchant-hosted hardware for transaction authorization. Mid-market hospitality operators are adopting API-first platforms that scale compute resources elastically during seasonal demand spikes. This architecture eliminates capital expenditure on depreciating servers while reducing failover latency for high-volume merchants.
The Payment Systems Regulator's open banking mandate requires real-time account-to-account payment rails within POS workflows. This policy compresses interchange fee dependencies for merchants while forcing acquirers to modernize settlement infrastructure. Enterprise retail chains are responding by piloting variable recurring payment authorization for subscription commerce models.
Curbside fulfillment workflows are reshaping terminal deployment patterns across UK grocery and quick-service verticals. Merchants are unbundling fixed-register investments in favor of smartphone-tethered card readers that roam between parking bays and pickup counters. This behavior is most visible in Greater London's supermarket chains, where labor redeployment flexibility outweighs hardware durability premiums.
UK Point of Sale Software Market Segmentation
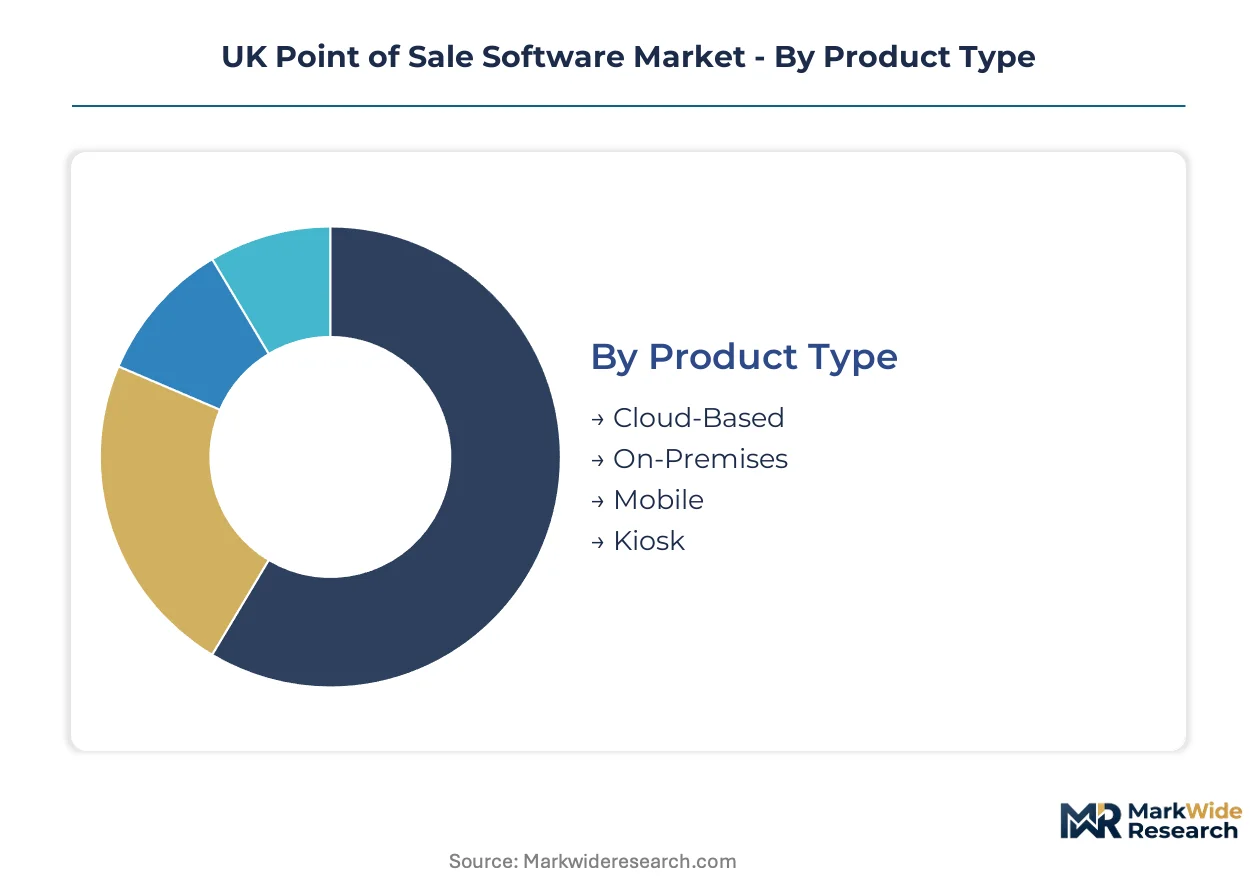
POS software segmentation reveals distinct procurement cycles across deployment modes and verticals. Cloud infrastructure compresses renewal timelines while legacy on-premise systems extend replacement windows, creating tiered vendor engagement strategies.
Product Type:
Cloud-based deployments turn over every 18-24 months as merchants chase feature releases, while on-premise installations persist for 7-10 years due to capital recovery requirements.
- Cloud-Based:Browser-accessible transaction processing eliminates server maintenance burdens. Greater London's high-traffic retail corridors drive concentrated demand for elastic scaling during seasonal peaks.
- Mobile:Smartphone-tethered card readers enable roaming payment capture across curbside and pop-up environments. Manchester's expanding hospitality clusters adopt these for tableside service flexibility.
- On-Premises:Merchant-hosted server architectures retain residual presence among legacy enterprise installations.
- Kiosk:Self-service terminal software supports unmanned checkout lanes in high-volume grocery and quick-service formats.
Cloud-based platforms anchor the volume base while mobile deployments gain share at the steepest rate.
Industry Vertical:
Retail merchants prioritize inventory synchronization capabilities, whereas hospitality operators demand kitchen display integration and modifier handling complexity.
- Hospitality:Table-service workflows require complex modifier routing and real-time kitchen communication. Premium licensing tiers capture concentrated margin pools from full-service restaurant chains.
- Retail:Multi-location inventory synchronization and barcode integration dominate procurement criteria. Greater London's dense retail corridors generate the highest transaction velocity requirements.
- Healthcare:Clinic and pharmacy POS systems integrate with patient management databases for compliance tracking.
- Entertainment:Venue and event-based deployments emphasize rapid transaction throughput during concentrated demand windows.
Retail anchors the volume base while hospitality climbs the fastest on premium feature adoption.
Payment Method:
Contactless infrastructure refreshes on 3-5 year hardware cycles, while cash-handling modules face extended depreciation schedules.
- Contactless:Tap-to-pay authorization dominates UK quick-service and grocery verticals. The Payment Systems Regulator's open banking push accelerates terminal replacement timelines.
- Mobile Payment:Digital wallet integration requires continuous SDK updates for Apple Pay and Google Pay compatibility.
- Credit Card:Chip-and-PIN processing remains the baseline certification requirement for all certified platforms.
- Cash:Drawer management and till reconciliation modules retain relevance in specific hospitality sub-segments.
Credit card processing anchors the volume base while contactless climbs fastest on terminal refresh cycles.
Deployment Model:
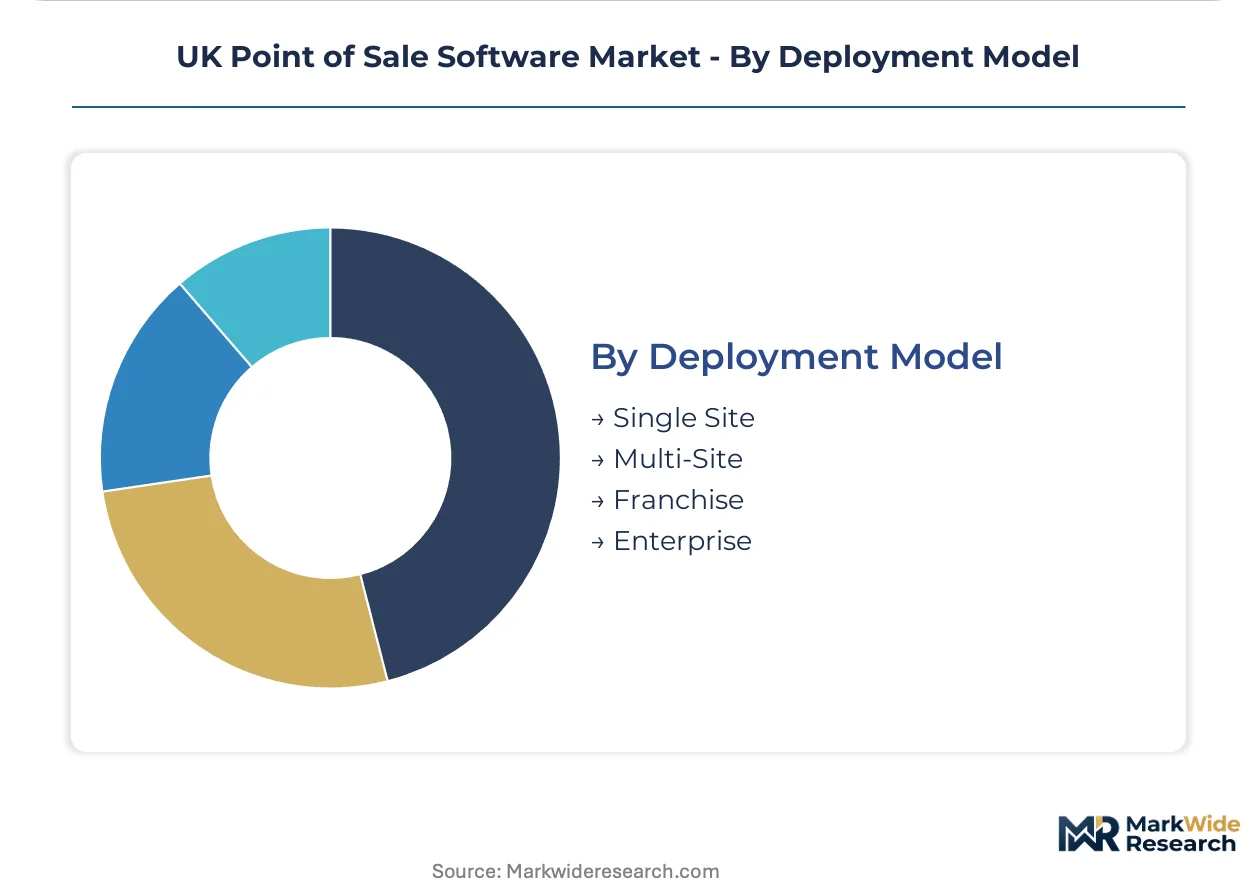
Single-site implementations deploy in weeks, whereas enterprise rollouts extend across 12-18 months due to integration complexity.
- Enterprise:Centralized transaction routing across hundreds of locations demands database-native processing architectures. Oracle and similar vendors compete on latency reduction for high-volume merchants.
- Multi-Site:Regional chain operators require real-time inventory visibility across 10-50 location footprints.
- Franchise:Franchisor-mandated standardization creates consolidated procurement decisions affecting dozens of operator locations.
- Single Site:Independent merchants prioritize rapid deployment and minimal technical overhead.
Single-site deployments anchor the volume base while enterprise contracts expand most quickly on consolidation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK POS software sector operates as a net importer of enterprise-grade platforms, with domestic demand outstripping indigenous development capacity and drawing sustained foreign vendor investment into Greater London and Manchester commercial corridors.
Greater London
High-traffic retail corridors in the capital generate concentrated demand for low-latency transaction processing and real-time inventory synchronization across multi-location operations. The Payment Systems Regulator enforces open banking interoperability mandates that compress deployment timelines for vendors serving merchant clusters in Westminster and the City. Canary Wharf's fintech density accelerates pilot programs for variable recurring payment authorization in subscription commerce models.
Manchester
Expanding hospitality clusters across the city center and Salford Quays present underpenetrated demand for table-service POS with kitchen display system integration. The Financial Conduct Authority's Strong Customer Authentication protocols reshape software certification requirements for operators scaling from single-site to multi-location footprints. Northern Quarter's independent restaurant density drives adoption of tablet-based ordering systems for tableside payment capture.
Birmingham
Midlands retail regeneration projects concentrate procurement activity for cloud-native infrastructure among regional chain operators seeking elastic scaling capabilities. GDPR enforcement from the Information Commissioner's Office creates liability exposure around customer purchase histories, forcing explicit consent workflows into loyalty module design for Bullring and Grand Central merchants. Digbeth's creative district incubates pop-up retail deployments utilizing mobile POS registers.
Scotland
Edinburgh and Glasgow hospitality markets demonstrate accelerating migration from legacy on-premise installations toward subscription-based cloud leasing models. PCI DSS compliance mandates from the PCI Security Standards Council govern card data handling architectures, pushing vendors toward tokenization for merchants in Princes Street and Buchanan Street corridors. Scottish Enterprise innovation funding supports pilot programs for curbside fulfillment workflows in grocery and quick-service verticals.
Wales
Cardiff's retail core and Swansea's emerging hospitality clusters exhibit procurement patterns favoring rapid-deployment single-site solutions over enterprise-tier complexity. Pay.UK real-time payment scheme participation requirements alter middleware connectivity obligations for vendors targeting Welsh merchant bases. The Welsh Government's digital infrastructure investments reduce connectivity barriers for cloud POS adoption in secondary urban centers.
UK Point of Sale Software Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying encryption modules, kitchen display hardware, and payment terminal firmware. The UK market exhibits tiered consolidation with enterprise-grade vendors competing on database-native latency reduction while mid-market specialists pursue vertical-specific feature depth. Three archetypes dominate: full-stack platform providers, hospitality-focused workflow specialists, and retail-centric inventory synchronization vendors. Competitive moves center on API architecture modernization for open banking compliance and subscription model transitions that shift revenue recognition toward recurring structures.
Within the full-stack platform tier, Lightspeed and Shopify represent multi-vertical expansion strategies, while Oracle occupies a position anchored to enterprise-grade transaction processing architectures. Lightspeed leverages cross-selling momentum across retail and hospitality through unified product architectures, and Shopify deepens UK market penetration through domestic payment acquirer integration. Oracle competes at the latency-sensitive tier for high-volume merchants requiring database-native processing capabilities.
| Leading Market Players |
|---|
| NCR Corporation |
| Lightspeed |
| Oracle |
| Diebold Nixdorf |
| Shopify |
| PayPal |
| Revel Systems |
| Clover Network |
| Flooid |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure providers in Ireland and the Netherlands concentrate compute capacity for UK-facing POS deployments, anchoring margin pools in subscription revenue tiers rather than perpetual licensing. Payment terminal manufacturing in China and Taiwan feeds hardware cost structures that compress as merchants shift toward smartphone-tethered card readers.
Pricing Analysis
Enterprise retail chains anchor pricing structures around subscription-based SaaS tiers scaled by transaction volume and location count. Three-tier pricing structure across premium, standard, and economy levels separates Oracle's database-native latency offerings from Lightspeed's mid-market hospitality bundles and Shopify's entry-level retail packages. Pricing pressure stems from open banking API certification costs that vendors must absorb to maintain Payment Systems Regulator compliance. Independent merchants exhibit highest price sensitivity, while high-volume quick-service chains prioritize latency reduction over per-seat licensing fees.
Supply Chain Analysis
Tariff exposure between China and the UK dominates hardware procurement risk for payment terminal and kitchen display system components. Taiwan and South Korea supply chipsets for contactless readers, while China manufactures plastic enclosures and battery assemblies. Raw material dependencies span lithium-ion cells, EMV-certified secure elements, and high-brightness LCD panels. Single-source vulnerability concentrates in EMV kernel certification providers. Distribution runs through authorized reseller networks and direct vendor sales teams serving Greater London and Manchester merchant clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as open banking mandates splinter vendor compliance capabilities, creating niche openings for API-native specialists serving mid-market hospitality operators.
For Market Incumbents: Pre-empt margin erosion from cloud-native entrants by accelerating backward integration into payment acquirer relationships, securing preferential interchange terms for merchant portfolios. Invest in database-native processing architectures that reduce latency below 50 milliseconds for high-volume Greater London retail corridors. Threat substitution from serverless payment infrastructure demands preemptive certification in Pay.UK real-time payment schemes. For New Entrants and Emerging Players: Pursue Manchester's expanding hospitality clusters with kitchen display system integration bundled at price points below enterprise-tier Oracle deployments. White-space concentration sits in tablet-based tableside ordering for Northern Quarter independent restaurants lacking technical integration resources. Go-to-market leverage flows through hospitality-focused value-added resellers with existing relationships in Salford Quays development zones. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native POS deployments as serverless architectures eliminate merchant-hosted hardware requirements. Long-term viability favors vendors with pre-certified open banking API stacks and recurring revenue concentration above 70 percent. Acquisition target archetype: mid-market hospitality specialists with kitchen display integration and Manchester-based customer density. Signal to watch: Payment Systems Regulator enforcement actions accelerating merchant migration away from legacy on-premise installations.| Strategic Initiative | Industry Significance |
|---|---|
| Open Banking API Certification | Payment Systems Regulator mandates compress deployment timelines for compliant vendors. |
| Kitchen Display System Integration | Table-service workflows in Manchester hospitality clusters command premium licensing tiers. |
| Real-Time Payment Scheme Participation | Pay.UK connectivity obligations favor vendors with pre-certified middleware stacks. |
| Subscription Revenue Model Transition | Cloud-native deployments shift recognition toward recurring structures across retail and hospitality. |
| Curbside Fulfillment Infrastructure | Mobile POS registers enable roaming payment capture in Greater London supermarket chains. |
Research Approach
Desk research of Payment Systems Regulator policy filings, PCI Security Standards Council certification databases, and Pay.UK scheme documentation preceded structured interviews with CTOs at quick-service restaurant chains, IT procurement officers at Greater London retail groups, and integration specialists at domestic payment acquirers. Primary fieldwork validated assumptions around open banking API migration timelines and cloud POS adoption thresholds. Secondary triangulation drew from Financial Conduct Authority enforcement records, Information Commissioner's Office GDPR guidance, and vendor SEC disclosures. Bottom-up merchant deployment estimates were cross-checked against top-down software spending projections.
Assumptions around open banking interoperability deadlines and Strong Customer Authentication enforcement intensity were held fixed, while merchant vertical mix and regional adoption pace were varied across sensitivity scenarios. The analytical framework modeled deployment model, organization size, vertical specialization, integration complexity, and regional corridor density across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific inputs included tablet-based ordering penetration rates in British quick-service chains and real-time inventory synchronization requirements in multi-location retail operations.
Sensitivities concentrate around Payment Systems Regulator enforcement intensity, PCI DSS certification timeline compression, and GDPR liability exposure around customer purchase histories. Forecasts reflect these documented assumptions and risk weightings. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Construction Enterprise Resource Planning (ERP) Software Market
Software & Services
Movie Editing Software Market
Software & Services
Parametric Design Software Market
Software & Services
Objectives & Key Results (OKR) Software Market
Software & Services
G Suite Technology Services Market
Software & Services
Global SEO Software Market
Software & Services
Global Call Tracking Software Market
Software & Services
Change Control Management Software Market
Software & Services
Apparel Software Market
Software & Services
API Design Software Market
Software & Services
North America IT Services Market
Software & Services
HACCP Software Market
Software & Services
Global Application Management Services Market
Software & Services
Australia HR Payroll Software Market
Software & Services
Global Product Management Software Market
Software & Services
Application Development and Modernization (ADM) Market