
 Internet Protocol Version 6 (IPv6) Market | 2026-2036
Internet Protocol Version 6 (IPv6) Market Size, Share, and Industry Trends Forecast 2026-2036
Internet Protocol Version 6 (IPv6) Market Foresight
Carrier-grade network infrastructure procurement is reshaping vendor relationships across the IPv6 hardware and services landscape. Cisco Systems dominates router and switch deployments through its extensive certification programs and service provider partnerships. Juniper Networks competes in high-throughput edge routing with specialized silicon optimized for dual-stack translation. China Telecom Global Limited extends its position through submarine cable investments linking Asia-Pacific PoPs to European IXPs.
Internet Protocol Version 6 is a 128-bit addressing protocol defined in RFC 8200, designed to replace the 32-bit IPv4 standard by expanding the address space to 340 undecillion unique identifiers and mandating IPsec for baseline security. Its primary purpose is enabling end-to-end device connectivity for cloud-native applications, industrial IoT sensors, and mobile networks where network address translation creates latency and management overhead. Router and switch hardware commands the largest product type revenue pool, while network management software captures disproportionate margin through recurring subscription models. Cloud computing application segments are expanding fastest as hyperscalers deploy IPv6-native load balancers and container orchestration layers.
The Office of Management and Budget mandates IPv6-only operational targets for US federal agencies, while the European Telecommunications Standards Institute publishes conformance frameworks under EU cybersecurity certification schemes. India's Telecom Regulatory Authority issues numbering resource guidelines that embed IPv6 readiness requirements into ISP licensing conditions. Stakeholders must monitor dual-stack operational costs against native IPv6 transition timelines as regional regulatory deadlines diverge.
Market Dynamics
The exhaustion of IPv4 address pools under Regional Internet Registry allocation policies is forcing carriers and enterprises into accelerated transition timelines, while 5G backhaul requirements and IoT sensor proliferation create simultaneous demand pressure for end-to-end routable connectivity.
Growth Catalysts
- OMB IPv6-Only Mandates:United States federal agencies face operational deadlines that compress procurement cycles for native IPv6 infrastructure and disqualify dual-stack vendors from contract eligibility.
- 5G Network Densification:Telecommunications carriers require expanded address spaces for massive machine-type communications and ultra-reliable low-latency use cases in smart manufacturing and autonomous transport.
- IoT Device Proliferation:Industrial sensor deployments in energy, agriculture, and logistics sectors demand direct addressability without network address translation overhead or session state management complexity.
Market Restraints
- Dual-Stack Operational Burden:Enterprises maintaining parallel IPv4 and IPv6 networks face doubled monitoring, troubleshooting, and security policy enforcement costs during extended transition periods.
- Specialized Engineering Talent Scarcity:The shallow labor pool for BGP routing, subnetting, and security architecture in 128-bit address spaces extends deployment timelines and elevates professional services dependency.
- Legacy Application Dependency:Embedded systems and industrial control platforms built on IPv4-only stacks require hardware replacement or translation layer investments that delay native transition ROI.
Strategic Opportunities
- Cloud-Native Load Balancer Demand:Hyperscale data center operators in the United States and Germany are procuring IPv6-native application delivery controllers to eliminate NAT-induced latency in container orchestration environments.
- EU Cybersecurity Certification Schemes:The European Telecommunications Standards Institute conformance frameworks create preferred vendor status for equipment meeting IPv6-ready baseline requirements in public sector tenders.
- Submarine Cable IPv6 Provisioning:Trans-Pacific and trans-Atlantic cable investments linking Singapore, Japan, and France enable point-of-presence operators to offer native IPv6 transit without tunneling overhead.
Industry Challenges
- Address Planning Complexity:Network architects must design hierarchical subnet allocations across 340 undecillion addresses without the scarcity constraints that disciplined IPv4 conservation practices previously enforced.
- Security Policy Recertification:Firewall rule bases, intrusion detection signatures, and access control lists require comprehensive audit and rewrite to accommodate extension headers and flow label semantics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internet Protocol Version 6 (IPv6) Market |
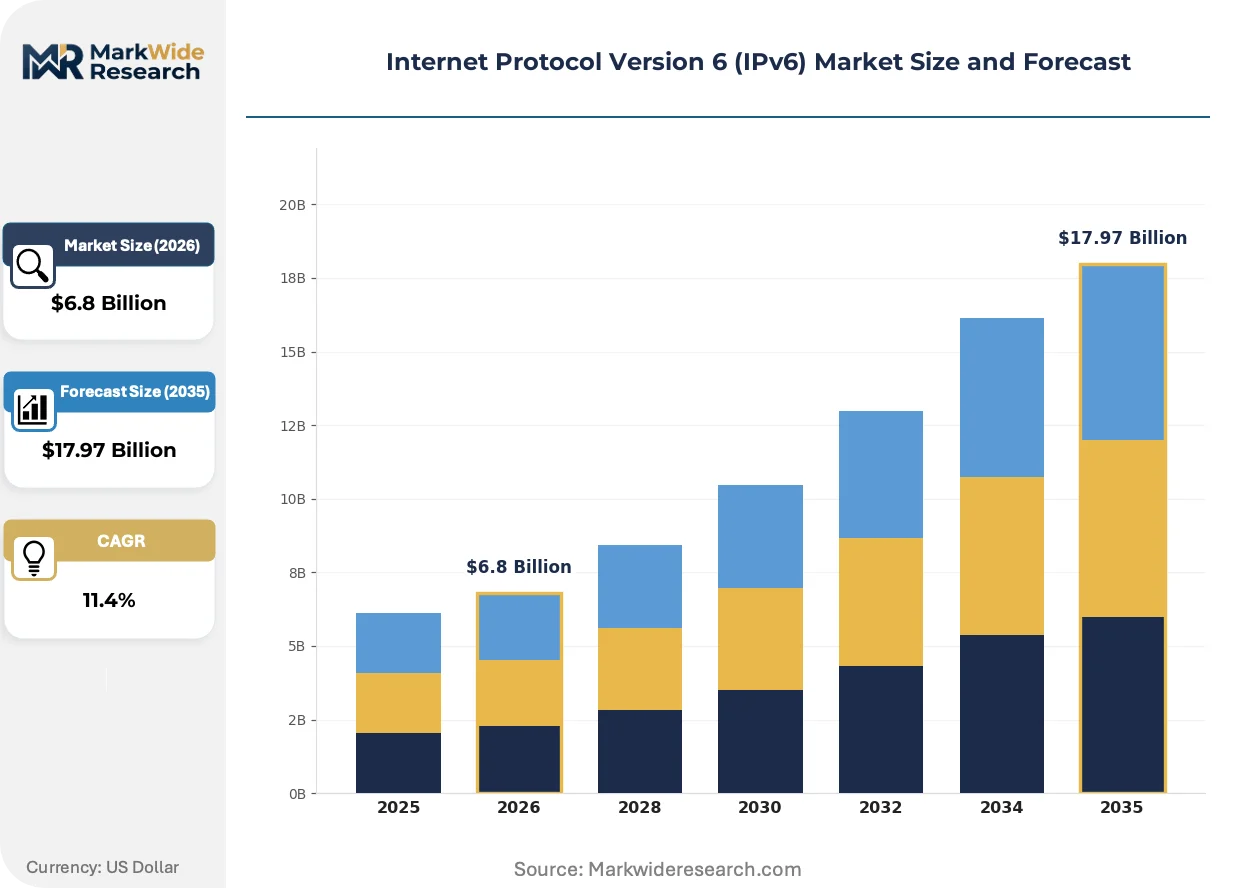
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Router, Switch, Firewall, Network Management Software Application: Data Center, Enterprise Networking, Cloud Computing, IoT End User: Telecommunications, Government, Healthcare, Education Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises |
| Companies Covered | NTT Communications Corporation, Hewlett Packard Enterprise Development LP, Cisco Systems Inc., D-Link Corporation, IBM, Verizon, China Telecom Global Limited, Juniper Networks, AT&T Intellectual Property, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internet Protocol Version 6 (IPv6) Market Shifts & Advancements
Network function virtualization and software-defined perimeter architectures are compressing hardware dependency in routing infrastructure, while regulatory mandates and procurement model evolution reshape vendor selection criteria across carrier and enterprise segments.
Segment Routing over IPv6 (SRv6) is virtualizing traffic engineering functions previously executed in MPLS label switched paths. Tier-1 carriers in Japan and Germany are deploying SRv6 for simplified traffic steering without overlay network complexity. This compression of protocol layers reduces operational expenditure in backbone networks while enabling programmable path selection for latency-sensitive applications.
The Office of Management and Budget memorandum M-21-07 mandates IPv6-only operational targets for federal civilian agencies by 2025, eliminating dual-stack as an acceptable end state. Defense and intelligence community networks are accelerating compliance to maintain contract eligibility. Equipment vendors are recertifying product lines under NIST SP 800-119 guidelines to capture this captive demand segment.
Hyperscaler procurement teams are unbundling hardware acquisition from professional services engagement, shifting toward self-managed IPv6 deployment with vendor-agnostic automation tooling. This disintermediation of systems integrators concentrates in United States cloud computing markets where internal platform engineering teams possess sufficient routing expertise. The pattern compresses margin capture for traditional network equipment providers while elevating open-source routing stack adoption.
Internet Protocol Version 6 (IPv6) Market Segmentation
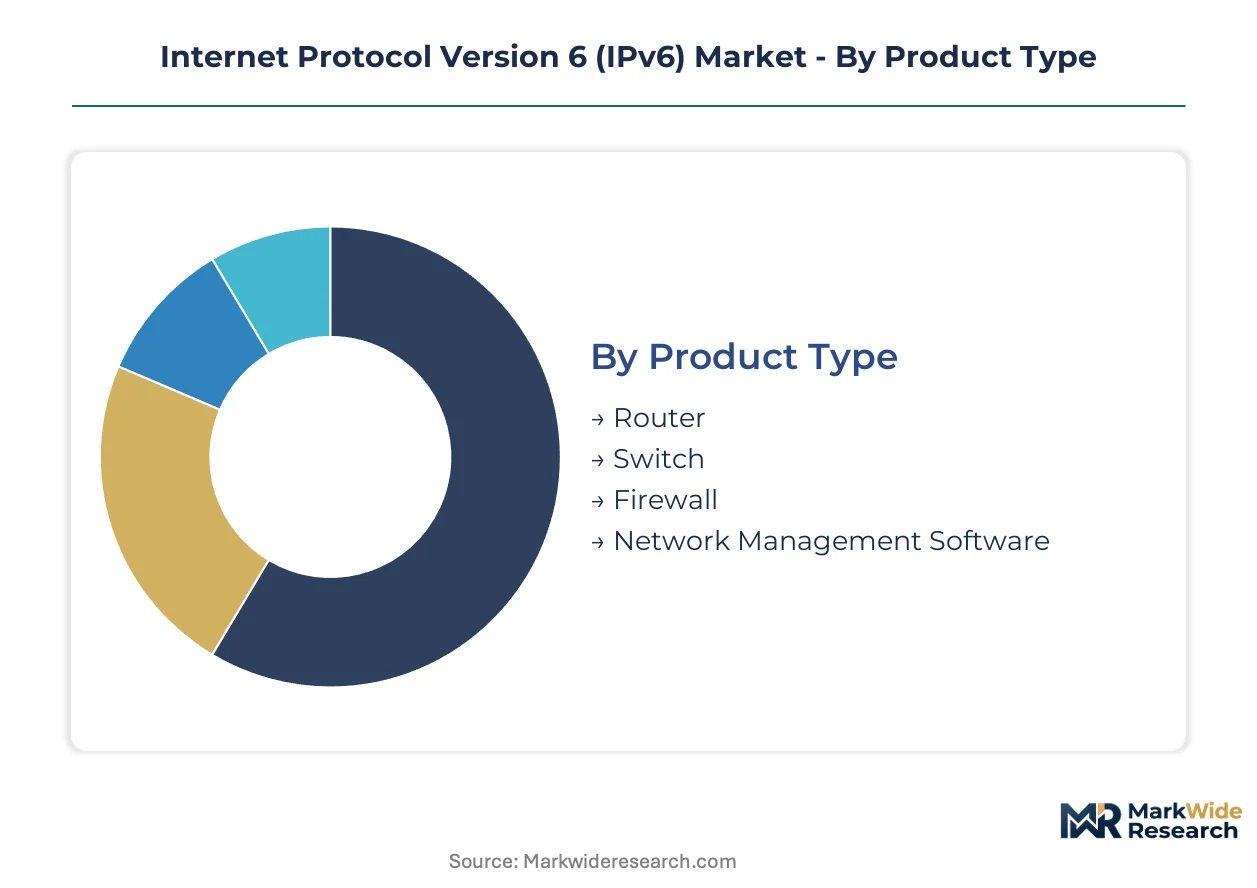
IPv6 market segmentation reveals divergent procurement patterns across hardware infrastructure, software orchestration, and service delivery models. Each dimension captures distinct buyer priorities—from carrier-grade throughput requirements to federal compliance mandates—that reshape vendor positioning and pricing architecture.
Product Type:
Mature hardware categories dominate capital expenditure cycles while emerging software layers capture recurring revenue streams through subscription monetization.
- Router:Carrier-grade routing platforms process dual-stack and native IPv6 forwarding at terabit-scale throughput. Telecommunications carriers in the United States and Japan prioritize these deployments for 5G backhaul densification and core network refreshes.
- Switch:Data center switching fabrics enable leaf-spine architectures with IPv6-native segment routing capabilities. Hyperscale operators in Germany and Singapore drive procurement volume for software-defined data center interconnects.
- Firewall:Next-generation firewalls inspect IPv6 extension headers and enforce security policies across 128-bit address spaces. Enterprise buyers in regulated sectors require these for compliance with federal cybersecurity frameworks.
- Network Management Software:Orchestration platforms automate address allocation, path computation, and policy propagation. Cloud-native deployments favor these tools for container network interface management.
Router hardware handles the majority of throughput; network management software is gaining share fastest through SaaS pricing models.
Application:
Volume concentration tilts toward centralized infrastructure while edge-distributed use cases expand addressable market scope.
- Data Center:Hyperscale facilities deploy IPv6-native load balancers and anycast routing to eliminate NAT overhead in east-west traffic patterns. Operators in Northern Virginia and Frankfurt lead procurement for cloud region expansions.
- Cloud Computing:Container orchestration layers require end-to-end addressability for pod-to-pod communication without translation gateways. Kubernetes-native service meshes drive this segment's expansion trajectory.
- Enterprise Networking:Campus and branch infrastructure transitions from dual-stack pilot programs to production IPv6-only LAN segments. Financial services firms in New York and London accelerate this shift for regulatory audit simplification.
- IoT:Industrial sensor networks demand direct addressability for millions of endpoints without stateful NAT session tables. Smart manufacturing deployments in South Korea and Germany concentrate demand here.
Data center applications anchor current revenue; IoT represents the steepest expansion trajectory as industrial digitization accelerates.
End User:
Procurement authority varies from centralized federal mandates to distributed institutional decision-making across sectors.
- Telecommunications:Tier-1 and Tier-2 carriers modernize backbone, metro, and access layers for IPv6-only subscriber provisioning. 5G standalone core requirements in the United States and Japan compress deployment timelines.
- Government:Federal civilian agencies face OMB-mandated operational deadlines that disqualify dual-stack vendors from contract eligibility. Defense and intelligence networks impose additional NIST certification requirements.
- Healthcare:Hospital systems and payer networks upgrade infrastructure to support connected medical devices and telehealth platforms. HIPAA-compliant address management drives specialized procurement criteria.
- Education:Research universities and K-12 districts modernize campus networks for eduroam federation and student device density. NSF-funded research networks in the United States pioneer native IPv6 scientific computing environments.
Telecommunications captures the largest procurement volume; government compliance mandates are reshaping vendor qualification standards most aggressively.
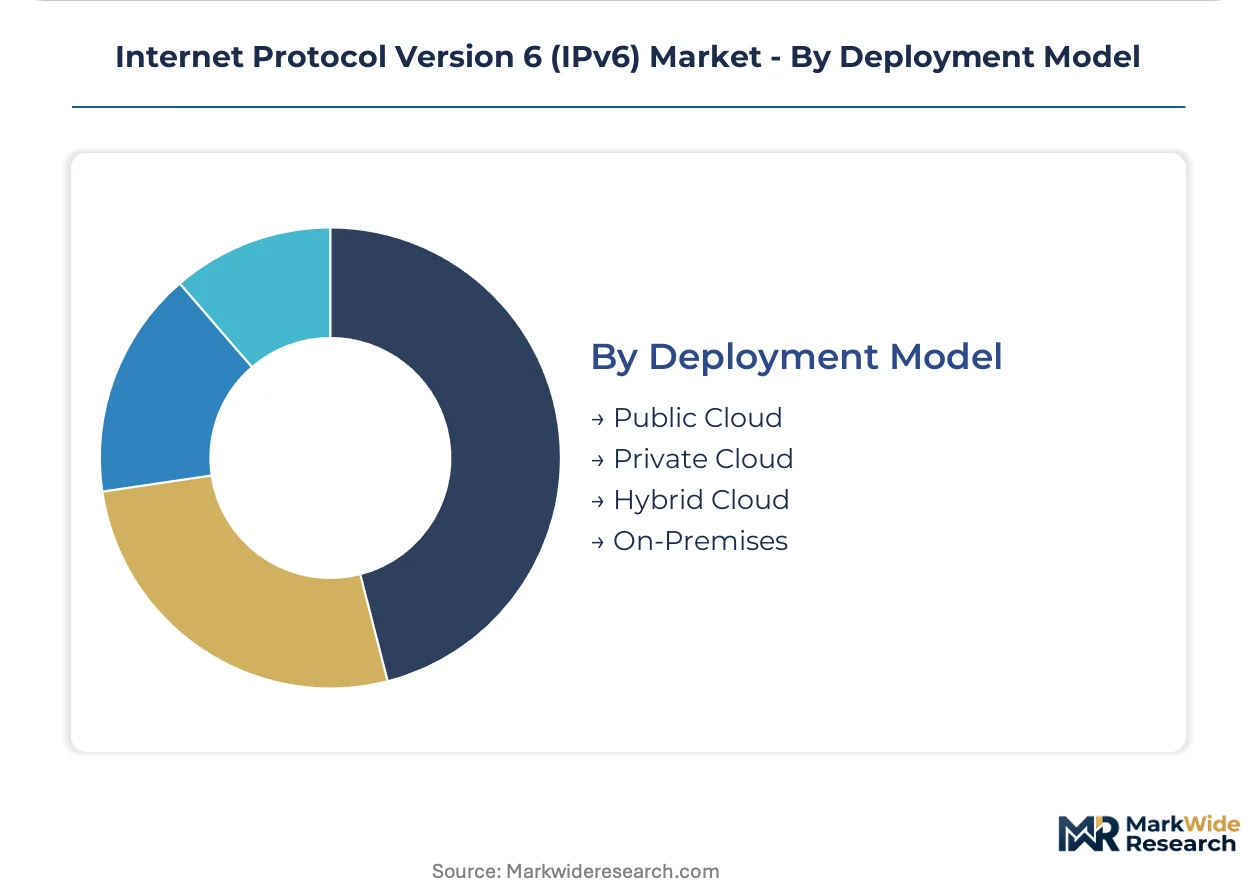
Deployment Model:
Infrastructure control preferences segment buyers across fully managed, self-operated, and hybrid operational paradigms.
- Public Cloud:Hyperscale providers offer IPv6-native virtual networks with automatic address assignment and internet egress. Amazon Web Services, Microsoft Azure, and Google Cloud Platform compete on prefix delegation flexibility.
- Private Cloud:Enterprise-owned infrastructure delivers sovereign data control with OpenStack or VMware NSX orchestration. German and French buyers prioritize this model for GDPR-aligned data residency.
- Hybrid Cloud:Workload portability across on-premises and cloud environments requires consistent IPv6 addressing and policy enforcement. Financial services firms favor this architecture for burst capacity management.
- On-Premises:Legacy data centers and industrial control systems maintain dedicated hardware for air-gapped or latency-sensitive operations. Manufacturing and energy sectors retain this model for operational technology isolation.
Public cloud deployments lead on new contract volume; private cloud is climbing fastest in regulated European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where federal procurement mandates and carrier infrastructure refresh cycles compress vendor margins, while Asian markets command premium hardware valuations through submarine cable investments and 5G standalone core deployments.
United States
OMB memorandum M-21-07 drives federal agency IPv6-only deadlines, disqualifying dual-stack vendors from civilian contract eligibility. NIST SP 800-119 certification requirements reshape vendor qualification standards for defense and intelligence networks. Northern Virginia hyperscale data center clusters anchor procurement volume for cloud-native load balancers and anycast routing infrastructure.
Japan
METI industrial digitization programs accelerate smart manufacturing sensor deployments requiring direct IPv6 addressability. Tier-1 carriers deploy Segment Routing over IPv6 for simplified traffic engineering without MPLS overlay complexity. Tokyo and Osaka metro areas concentrate 5G standalone core infrastructure investment from NTT Communications and regional telecommunications providers.
Germany
ETSI conformance frameworks under EU cybersecurity certification schemes create preferred vendor status for IPv6-ready equipment in public sector tenders. GDPR-aligned data residency requirements sustain private cloud deployment preference over public hyperscaler alternatives. Frankfurt data center clusters lead procurement for software-defined data center interconnects with native IPv6 segment routing capabilities.
China
MIIT numbering resource guidelines embed IPv6 readiness requirements into ISP licensing conditions through national dual carbon goals alignment. China Telecom Global Limited extends submarine cable investments linking Asia-Pacific points-of-presence to European internet exchange points. Yangtze River Delta industrial zones concentrate IoT sensor network deployments for smart manufacturing and logistics automation.
Singapore
Trans-Pacific cable investments enable point-of-presence operators to offer native IPv6 transit without tunneling overhead to regional financial services firms. Maritime logistics hubs demand direct addressability for container tracking and port automation systems. The city-state's internet exchange infrastructure anchors Southeast Asian IPv6 traffic aggregation for submarine cable landing stations.
Internet Protocol Version 6 (IPv6) Market Competitive Landscape
Carrier-grade infrastructure specialists and enterprise networking generalists split the market across procurement cycles with divergent certification requirements. The vendor base concentrates around three strategic archetypes: telecommunications equipment incumbents with service provider certification programs, cloud-native software vendors with container orchestration integration, and regional systems integrators with government security clearances. Competitive positioning depends on NIST certification completion for federal eligibility and ETSI conformance for European public sector access.
Among telecommunications equipment providers, Cisco Systems Inc. and Juniper Networks exemplify the carrier-grade routing archetype with extensive service provider partnership ecosystems. China Telecom Global Limited occupies a position within submarine cable infrastructure investment and Asia-Europe transit provisioning. NTT Communications Corporation anchors the Asia-Pacific carrier segment through 5G standalone core deployments and industrial IoT platform integration.
| Leading Market Players |
|---|
| NTT Communications Corporation |
| Hewlett Packard Enterprise Development LP |
| Cisco Systems Inc. |
| D-Link Corporation |
| IBM |
| Verizon |
| China Telecom Global Limited |
| Juniper Networks |
| AT&T Intellectual Property |
| Others |
Supply & Pricing Matrix
Carrier-grade router undercapacity in Japan and Germany compresses lead times for high-throughput IPv6 platforms while simultaneously elevating configured-to-order premiums. This utilization squeeze forces hyperscale buyers toward multi-year frame agreements that lock pricing before capacity constraints intensify further.
Pricing Analysis
The customization-premium spread between standard catalog routers and carrier-configured platforms reaches widest separation in federal procurement channels where NIST SP 800-119 certification requirements add substantial compliance overhead. Subscription-based network management software captures recurring margin through SaaS-tiered pricing that scales with pod density in container orchestration environments. Price differentiation hinges on certification grade and geographic delivery cost, with United States federal contracts commanding premiums over enterprise segments. Cost compression in standard switching hardware intensifies as Taiwanese ODMs expand production capacity. Telecommunications carriers exhibit lowest price sensitivity due to 5G standalone core deployment deadlines, while education sector buyers face constrained capital budgets.
Supply Chain Analysis
Contract-manufacturing concentration rests with Foxconn, Jabil, and Flex holding dominant capacity for carrier-grade routing hardware across Taiwan, Mexico, and Malaysia. Specialized silicon foundries in Taiwan and South Korea feed merchant silicon for high-throughput forwarding engines. Raw material dependencies center on advanced packaging substrates, high-purity copper for backplane interconnects, and rare earth elements for power amplification modules. Single-source vulnerability concentrates in merchant silicon supply where Broadcom and Marvell dominate programmable forwarding chipsets. Distribution runs through direct OEM salesforces for carrier accounts and value-added resellers for enterprise mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IPv6 infrastructure incumbents face substitution pressure from cloud-native virtualized routing stacks that displace purpose-built hardware in hyperscale environments. Defense requires hardening certification moats while accelerating software-defined perimeter integration.
For Market Incumbents: Harden NIST SP 800-119 and ETSI conformance positions to disqualify uncertified rivals from federal and EU public sector tenders. Pursue backward integration into merchant silicon supply through strategic foundry partnerships that secure forwarding engine capacity. Cloud-native routing software represents the primary substitution threat; counter with hybrid hardware-software bundles that preserve margin in transitional dual-stack deployments. For New Entrants and Emerging Players: Pursue white-space opportunity in IPv6-native network management software where SaaS pricing models enable rapid land-and-expand penetration. Target education sector deployments in research university environments where eduroam federation requirements create procurement urgency with lower certification barriers. Position through open-source routing stack integration that appeals to platform engineering teams with sufficient internal expertise to bypass traditional systems integrators. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-defined networking segments as virtualization compresses hardware dependency in routing infrastructure. Long-term viability favors vendors with recurring revenue exposure through subscription orchestration platforms rather than transactional hardware cycles. Acquisition target archetype: cloud-native network management specialists with Kubernetes-native container network interface capabilities. Monitor hyperscaler procurement team hiring patterns as inflection indicator for self-managed deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| NIST SP 800-119 Certification Completion | Federal contract eligibility under OMB M-21-07 mandates disqualifies non-compliant vendors from civilian agency procurement. |
| Segment Routing over IPv6 Deployment | Tier-1 carriers in Japan and Germany compress operational expenditure through simplified traffic engineering without MPLS overlay complexity. |
| Cloud-Native Load Balancer Integration | Hyperscale operators in Northern Virginia eliminate NAT-induced latency through IPv6-native application delivery controllers. |
| Submarine Cable IPv6 Provisioning | Trans-Pacific investments linking Singapore to European IXPs enable native transit without tunneling overhead for financial services firms. |
| Open-Source Routing Stack Adoption | Self-managed deployment patterns concentrate in United States cloud computing markets with sufficient internal platform engineering expertise. |
Research Methodology
A spread of perspectives from carrier network architects, federal procurement officers, hyperscale platform engineers, and enterprise IT directors converged on the working assumptions. Primary interviews with telecommunications equipment vendors and secondary validation through SEC filings, hyperscaler capex disclosures, and Regional Internet Registry allocation records anchored demand-side calibration. Bottom-up triangulation across router shipment data and top-down reconciliation against carrier infrastructure refresh budgets ensured cross-verification.
Demand-supply-balance framing across the analysis window modeled carrier backbone investment cycles against merchant silicon foundry capacity expansion. Segmentation dimensions included product type, application, end user, and deployment model with regional regulatory cluster differentiation. CAGRs derived from weighted average of historical deployment trajectories and mandated transition deadlines. IPv6 address allocation velocity and 5G standalone core deployment timelines served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native virtualized routing entrants would shift outcomes beyond modeled ranges. Forecasts reflect assumptions regarding OMB compliance adherence and ETSI certification timeline adherence. Quarterly review of hyperscaler procurement team hiring patterns and carrier capex guidance revisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Vietnam Data Center Server Market
Data Center and Networking
Graph Database Market
Data Center and Networking
Middle East Data Center Server Market
Data Center and Networking
Dynamic Data Management System Market
Data Center and Networking
Hong Kong Data Center Networking Market
Data Center and Networking
Saudi Arabia Data Center Server Market
Data Center and Networking
Software Defined Video Networking Market
Data Center and Networking
Virtual Data Optimizer Market
Data Center and Networking
Nigeria Data Center Networking Market
Data Center and Networking
Global Storage Area Network (SAN) Switches Market
Data Center and Networking
Brazil Servers Market
Data Center and Networking
Internet Protocol Television (IPTV) Content Delivery Network (CDN) Market
Data Center and Networking
Spain Data Center Networking Market
Data Center and Networking
Network Connectivity Tester Market
Data Center and Networking
Europe Data Center Interconnect Market
Data Center and Networking
MPLS-Based Core Network Market