
 Bitcoin Project Incubator Service Market | 2026-2036
Bitcoin Project Incubator Service Market Size, Share, and Industry Trends Forecast 2026-2036
Bitcoin Project Incubator Service Market Insights
Market Context
Layer-2 scaling infrastructure is reshaping how Bitcoin-native projects prototype and deploy applications. Y Combinator leverages its established venture pipeline to attract founders exploring ordinals and BRC-20 token standards. Techstars anchors several blockchain-focused accelerators with dedicated Bitcoin tracks in North American metros. Outlier Ventures dominates the European incubator landscape through its Web3 accelerator thesis and specialized base-layer focus.
Technical Definition and Segment Structure
A Bitcoin project incubator service provides structured mentorship, capital access, and technical infrastructure to early-stage ventures building on or adjacent to the Bitcoin blockchain, typically spanning twelve to twenty-four month engagement cycles with milestone-based progression. The service encompasses validator node setup, Lightning Network integration, and security auditing for proof-of-work consensus applications. Funding access and mentorship command the largest margin pools within service offerings, while token allocation models represent the fastest-growing engagement structure as projects experiment with novel incentive alignment. Decentralized finance and wallet solutions anchor application demand, though blockchain gaming incubation is expanding rapidly as developers explore Bitcoin-based asset interoperability.
Regulatory Framework
The SEC, CFTC, and state-level money transmitter regulators in the United States collectively shape incubator operating models through enforcement actions targeting unregistered token offerings and custodial arrangements. The EU's Markets in Crypto-Assets regulation and MiCA framework impose compliance obligations on incubators serving projects with European user bases. Stakeholders must monitor how jurisdictional arbitrage between regulatory regimes influences incubator geographic placement and client selection criteria.
Market Dynamics
Layer-2 scaling infrastructure is compressing prototype-to-deployment cycles for Bitcoin-native ventures, forcing incubators to retool technical support stacks around ordinals, BRC-20 standards, and Lightning Network integrations.
Growth Catalysts
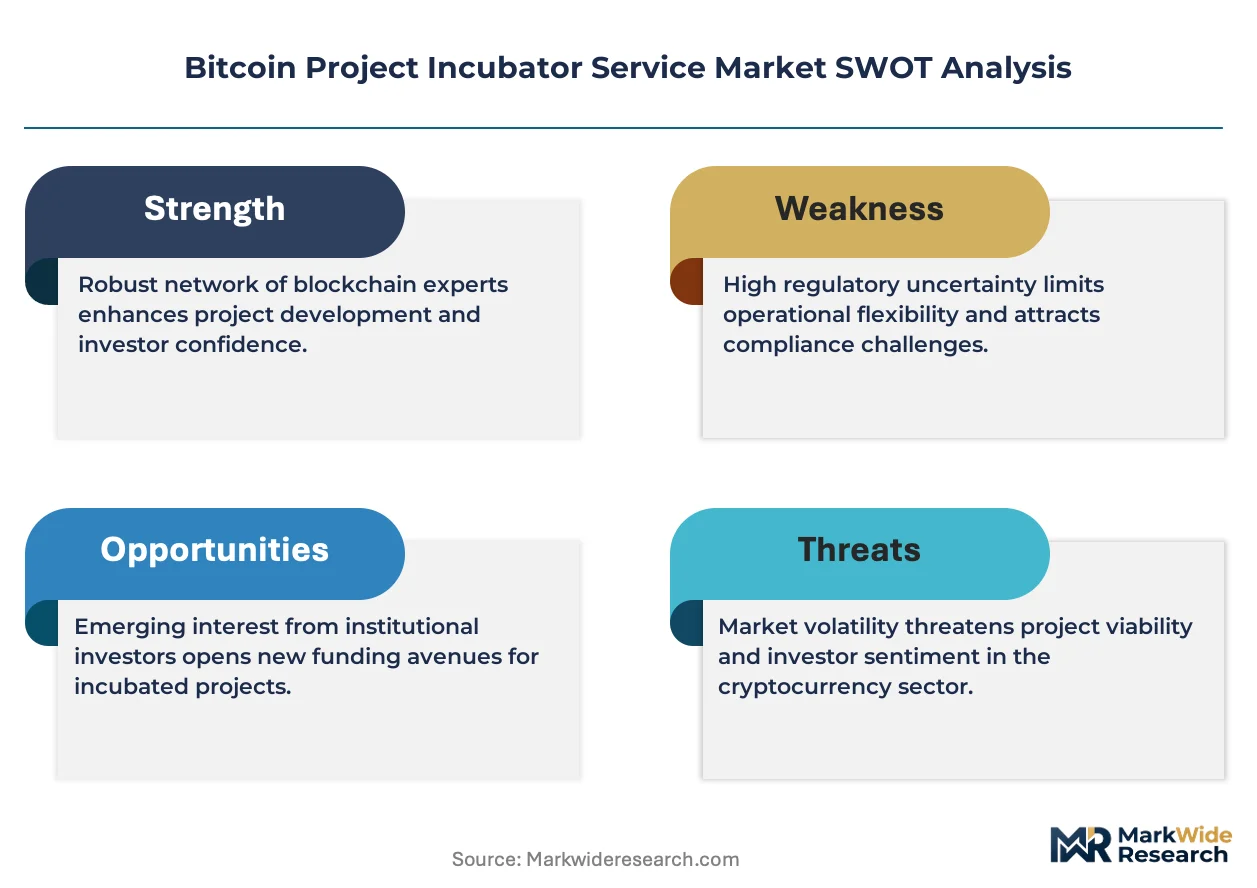
- MiCA Framework:The EU's Markets in Crypto-Assets regulation provides compliance clarity that reduces legal uncertainty for incubators serving European user bases. This accelerates capital deployment into structured programs.
- Blockchain Gaming Studios:Developers exploring Bitcoin-based asset interoperability are driving demand for specialized mentorship in proof-of-work consensus applications and cross-chain tooling.
- Austin and Miami Clusters:Concentrated founder density in these emerging crypto hub cities creates network effects that reduce talent acquisition costs for incubator cohort programs.
Market Restraints
- SEC Enforcement Posture:Evolving digital asset scrutiny creates structural uncertainty around token allocation models, forcing incubators to maintain redundant legal architectures.
- Validator Node Capital Requirements:Proof-of-work infrastructure demands substantial hardware investment that elevates minimum viable cohort sizes and excludes smaller programs.
- Lightning Network Technical Debt:Channel liquidity management complexity limits the pool of qualified technical mentors available to support portfolio companies.
Strategic Opportunities
- Bitcoin-Native DeFi:Decentralized finance applications built directly on base-layer Bitcoin remain underpenetrated relative to Ethereum alternatives, creating white space for specialized vertical programs.
- Ordinals and Inscriptions:The convergence of NFT functionality with Bitcoin's security model opens new application categories that existing incubators have not systematically addressed.
- State-Level Regulatory Arbitrage:Wyoming and Texas have enacted crypto-friendly frameworks that attract incubator placement away from traditional financial centers.
Industry Challenges
- Smart Contract Security Auditing Talent:The specialized skill set required to audit Bitcoin-adjacent protocols remains scarce, elongating due diligence timelines for cohort selection.
- Custodial Arrangement Compliance:Multi-signature wallet infrastructure for portfolio company treasury management triggers money transmitter licensing questions across jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bitcoin Project Incubator Service Market |
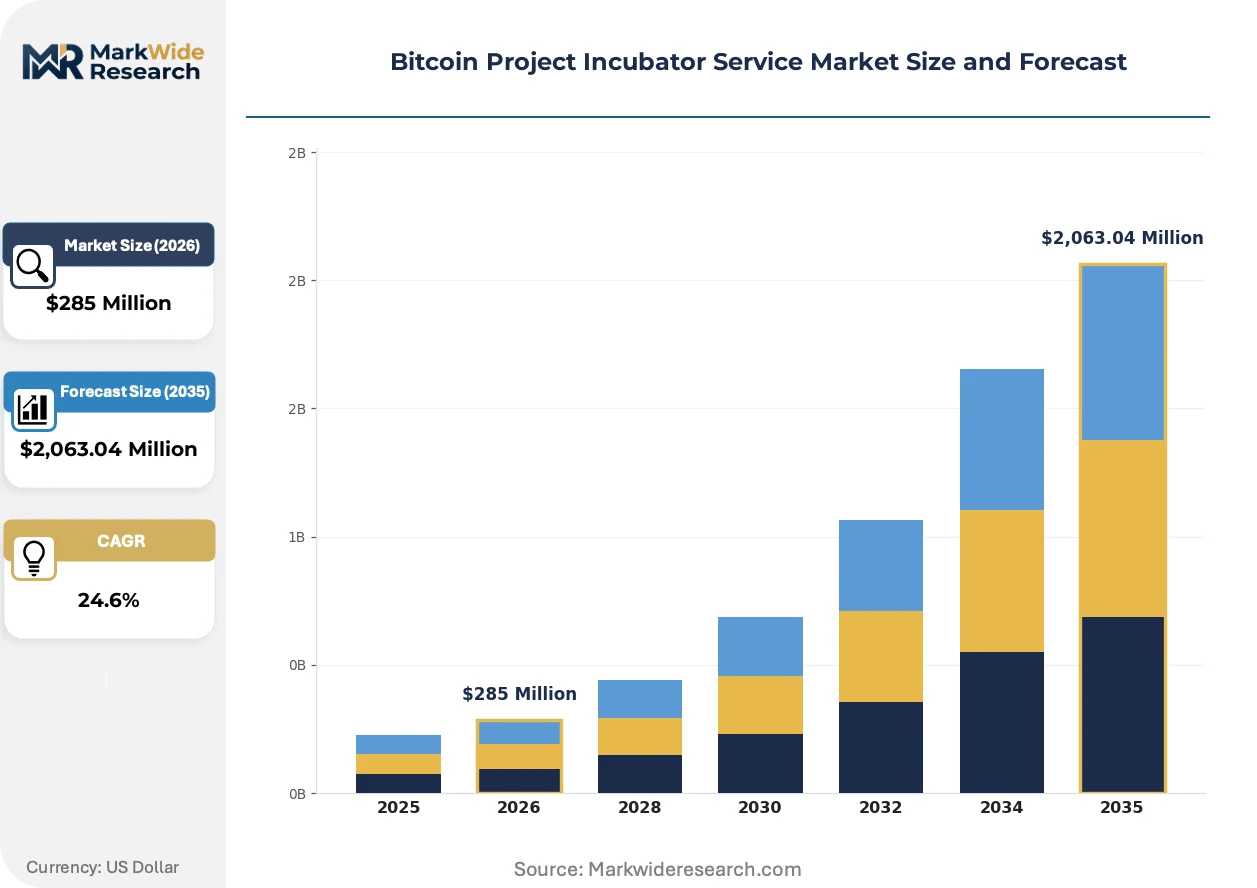
| Market Size in 2026 | $285 Million |
| Market Size in 2035 | $2,063.04 Million |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Offering: Mentorship, Funding Access, Technical Support, Marketing Assistance, Regulatory Guidance Application: Decentralized Finance, Blockchain Gaming, NFT Platforms, Cryptocurrency Exchanges, Wallet Solutions Client Type: Startups, Small Enterprises, Blockchain Developers, Crypto Entrepreneurs, Technology Innovators Engagement Model: Equity-Based, Fee-for-Service, Revenue Sharing, Subscription, Token Allocation |
| Companies Covered | Y Combinator, Techstars, Plug and Play Tech Center, 500 Global, Outlier Ventures, Digital Currency Group, Blockchain Founders Fund, Blockchain Trust Accelerator, Chicago Bitcoin Center, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bitcoin Project Incubator Service Market Trends and Innovations
Automation is restructuring how incubators deliver technical infrastructure and mentorship, compressing service delivery models while expanding addressable founder populations beyond traditional geographic clusters.
Zero-knowledge proof tooling is digitizing how Bitcoin projects demonstrate compliance and transaction validity without revealing sensitive protocol details. Blockchain gaming studios are adopting these verification layers at accelerating velocity. This capability is digitizing the security auditing workflow, reducing third-party validation costs for early-stage ventures.
The SEC's evolving digital asset enforcement posture is forcing incubators to restructure token allocation models around equity-only or SAFE instruments. This regulatory pressure elevates legal compliance costs across all cohort programs. Early-stage DeFi ventures are responding by delaying token launches until post-Series A funding rounds.
Founder expectations around milestone-based capital access are compressing traditional twelve-to-twenty-four month engagement cycles into six-month sprint structures. This behavioral shift disrupts incubator unit economics and forces program redesign. The pattern is most visible in United States-based accelerators where Y Combinator's compressed timeline has reset competitive benchmarks.
Bitcoin Project Incubator Service Market Segmentation
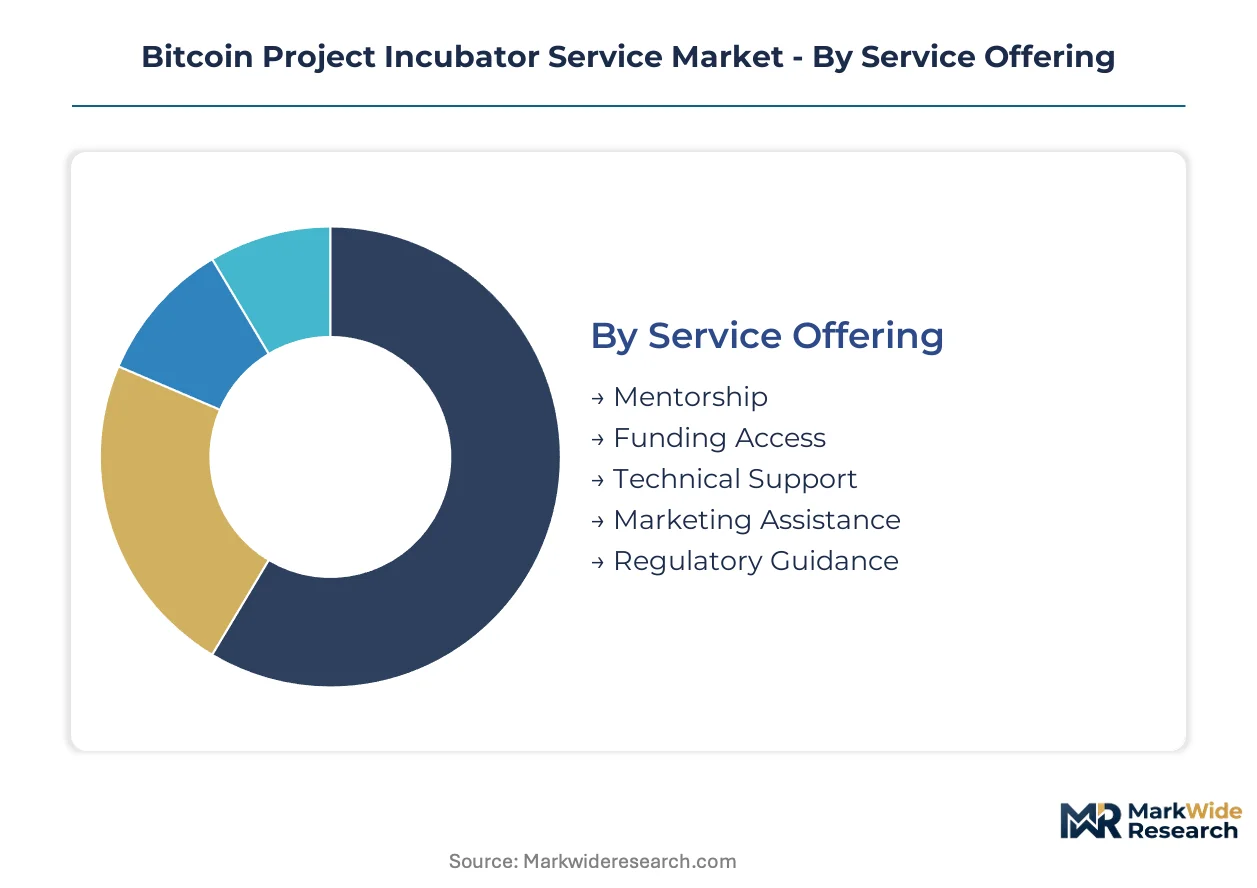
Incubator service segmentation reveals how capital allocation, technical specialization, and regulatory exposure concentrate differently across engagement structures. Understanding these fault lines enables stakeholders to match program design with founder risk profiles and jurisdictional constraints.
Service Offering:
After-sales intensity varies dramatically across service types, with ongoing technical infrastructure demanding sustained engineering support versus one-time regulatory consultations.
- Funding Access:Capital deployment mechanisms include SAFE instruments, equity stakes, and milestone-based tranche releases. Demand concentrates among Austin and Miami founders navigating SEC scrutiny around token allocation models, where legal architecture redundancy elevates compliance costs.
- Technical Support:Validator node setup, Lightning Network integration, and security auditing for proof-of-work applications require specialized engineering talent. European blockchain gaming studios drive demand here as developers explore Bitcoin-based asset interoperability and ordinals implementation.
- Mentorship:Structured guidance spanning twelve-to-twenty-four month cycles with compressed six-month variants emerging in United States accelerators.
- Marketing Assistance:Community building and token launch strategy support targeting DeFi and wallet solution ventures.
- Regulatory Guidance:MiCA compliance structuring for EU user bases and state-level money transmitter navigation in Wyoming and Texas.
Funding Access holds the largest share; momentum sits with Technical Support.
Application:
Cost tier stratification separates base-layer infrastructure ventures from application-layer experiments with divergent capital intensity and regulatory exposure.
- Blockchain Gaming:Studios exploring Bitcoin-based asset interoperability and ordinals functionality represent the fastest-expanding client segment. Proof-of-work consensus mentorship and cross-chain tooling support concentrate demand in European and United States clusters.
- Decentralized Finance:Bitcoin-native lending, derivatives, and yield protocols remain underpenetrated relative to Ethereum alternatives. Founders here delay token launches until post-Series A rounds to evade SEC enforcement attention.
- NFT Platforms:Ordinals and inscription-based digital collectibles leveraging Bitcoin's security model.
- Wallet Solutions:Self-custody infrastructure with multi-signature treasury management triggering licensing questions.
- Cryptocurrency Exchanges:On-ramp and liquidity provision ventures requiring custodial arrangement compliance architecture.
Decentralized Finance commands established revenue pools; Blockchain Gaming climbs the fastest.
Client Type:
Customer maturity profiles dictate incubator customization depth, from first-time solo founders requiring full-stack support to serial entrepreneurs seeking targeted capital access.
- Startups:Pre-seed and seed-stage ventures with twelve-to-twenty-four month engagement cycles and milestone-based progression. Austin and Miami density creates network effects reducing talent acquisition costs for cohort programs.
- Blockchain Developers:Technical founders with protocol expertise seeking go-to-market and regulatory navigation support. This segment expands most quickly as Layer-2 infrastructure compresses prototype-to-deployment cycles.
- Crypto Entrepreneurs:Repeat founders with existing investor relationships and token launch experience.
- Small Enterprises:Established companies pivoting into Bitcoin-adjacent product lines.
- Technology Innovators:Researchers and academic teams commercializing zero-knowledge proof and scaling research.
Startups anchor program enrollment; Blockchain Developers gain share fastest.
Engagement Model:
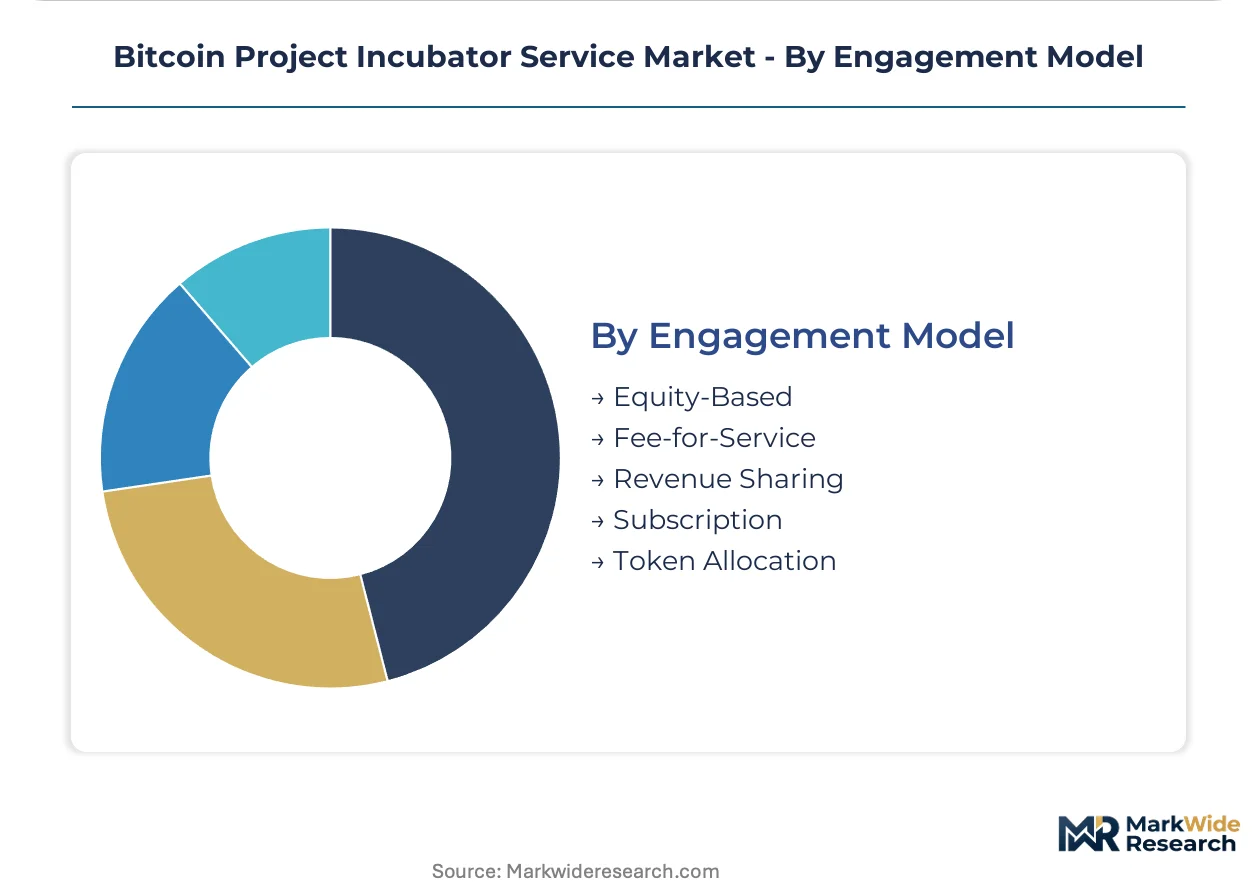
Margin structure and legal complexity diverge sharply across compensation mechanisms, with equity-based arrangements offering upside participation versus fee-for-service limiting regulatory exposure.
- Token Allocation:Novel incentive alignment structures with direct protocol participation rights. SEC enforcement posture forces incubators to maintain redundant legal architectures around these arrangements, elevating compliance costs.
- Equity-Based:Traditional venture-style stakes with standardized SAFE instruments gaining preference as regulatory pressure mounts.
- Fee-for-Service:Fixed consulting and technical implementation contracts with predictable revenue but capped upside.
- Revenue Sharing:Performance-linked compensation tied to portfolio company commercial milestones.
- Subscription:Recurring access to mentorship networks and technical infrastructure on monthly or annual terms.
Equity-Based structures dominate established programs; Token Allocation faces steepest expansion trajectory amid regulatory recalibration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israeli incubators export specialized blockchain security expertise to European gaming studios navigating MiCA compliance. Singapore-based programs attract Southeast Asian founders seeking capital access structures that minimize SEC jurisdictional exposure.
United States
Austin and Miami founder density creates network effects that compress talent acquisition costs for cohort programs. SEC enforcement actions targeting unregistered token offerings force incubators to maintain redundant legal architectures around equity-only instruments. Wyoming and Texas state-level frameworks attract incubator placement away from traditional financial centers.
United Kingdom
London anchors European demand for Bitcoin-native DeFi mentorship as founders delay token launches until post-Series A rounds. The Financial Conduct Authority's evolving stablecoin guidance shapes how programs structure custodial arrangements for portfolio treasuries. Cambridge and Oxford academic clusters feed technical talent into zero-knowledge proof research commercialization.
Germany
Berlin blockchain gaming studios drive demand for ordinals implementation support and cross-chain tooling mentorship. BaFin's crypto custody licensing requirements elevate compliance costs for programs serving German user bases. The Bavarian fintech corridor concentrates technical infrastructure providers specializing in Lightning Network integration.
Switzerland
Zug's crypto valley hosts incubator programs leveraging FINMA's established token classification guidance to reduce legal uncertainty. Banking partnerships in Geneva and Zurich provide fiat on-ramp infrastructure for portfolio companies. The Swiss regulatory clarity attracts founders from jurisdictions with enforcement-heavy postures.
Singapore
Monetary Authority of Singapore's payment services framework enables structured token allocation models that US-based programs cannot replicate. Regional founders from Indonesia and Vietnam cluster here to access capital while minimizing SEC exposure. The city-state's banking infrastructure supports multi-signature treasury management for cohort ventures.
Bitcoin Project Incubator Service Market Competitive Landscape
On the supply side, the industry is fragmented across venture-style accelerators, specialized crypto-native funds, and hybrid corporate venture arms with dedicated blockchain tracks. Three archetypes dominate: generalist tech accelerators running Bitcoin-specific verticals, crypto-native incubators with deep protocol expertise, and investment funds with attached mentorship infrastructure. Competitive moves concentrate on geographic expansion into regulatory-friendly jurisdictions and vertical specialization around ordinals, BRC-20 standards, and Lightning Network tooling.
Within the venture accelerator archetype, Y Combinator and Techstars occupy positions that leverage established founder pipelines to attract Bitcoin-native applicants. Outlier Ventures anchors the European specialized tier with its Web3 accelerator thesis and base-layer technical focus. These three exemplify how scale-driven programs compete against crypto-native specialists through brand recognition and alumni network effects rather than protocol-specific depth.
| Leading Market Players |
|---|
| Y Combinator |
| Techstars |
| Plug and Play Tech Center |
| 500 Global |
| Outlier Ventures |
| Digital Currency Group |
| Blockchain Founders Fund |
| Blockchain Trust Accelerator |
| Chicago Bitcoin Center |
| Others |
Pricing and Supply Chain Analysis
SEC enforcement posture on unregistered token offerings functions as the dominant regulatory chokepoint, compressing pricing tier spreads between equity-only incubator programs and token-allocation alternatives while simultaneously reshaping supply chain geography toward Wyoming and Texas.
Pricing Analysis
The ordinals-to-BRC-20 technology-generation pricing gap separates premium-tier programs commanding full-stack mentorship and Lightning Network infrastructure from standard-tier offerings limited to regulatory guidance and SAFE instrument structuring. Pricing stratifies across premium, standard, and economy tiers based on technical specialization depth and geographic cluster access, with Austin and Miami cohorts carrying location premiums. Cost compression in economy-tier programs is intensifying because validator node capital requirements exclude smaller programs from proof-of-work infrastructure support. Blockchain gaming studios exhibit highest price sensitivity due to elongated runway requirements, while serial crypto entrepreneurs demonstrate lowest sensitivity given established investor relationships.
Supply Chain Analysis
US Commerce Department export controls on advanced cryptography and zero-knowledge proof tooling constrain technical talent flows into incubator mentorship pools, elevating compensation costs for qualified security auditing specialists. Supply concentrates in the United States, Switzerland, and Singapore, with Zug's regulatory clarity and Singapore's banking infrastructure anchoring European and Asia-Pacific program placement. The supply chain draws from academic clusters at Cambridge, MIT, and ETH Zurich for zero-knowledge research commercialization, plus Lightning Network engineering talent from Blockstream and ACINQ alumni networks. Single-source vulnerability sits with MiCA compliance legal architecture providers serving EU-facing programs. Distribution runs through venture capital feeder networks and alumni referral channels rather than traditional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Bitcoin project incubator service market functions as a service-attach opportunity where recurring technical infrastructure support and milestone-based capital access layers expand faster than one-time regulatory consultation engagements.
For Market Incumbents: Harden program moats by deepening Lightning Network technical mentorship capabilities and securing exclusive partnerships with ordinals tooling providers. The threat of Y Combinator's compressed six-month sprint structures resetting competitive benchmarks demands response through differentiation in proof-of-work consensus specialization. Capacity addition in Wyoming and Texas leverages state-level regulatory arbitrage to reduce legal architecture redundancy costs.
For New Entrants and Emerging Players: European blockchain gaming studios navigating MiCA compliance represent the most penetrable white-space target, with Berlin and Barcelona clusters underserved by base-layer Bitcoin specialists. Bitcoin-native DeFi verticals remain underpenetrated relative to Ethereum alternatives, offering second entry angle. A go-to-market anchored in zero-knowledge proof research commercialization from Cambridge and Oxford academic partnerships differentiates against generalist accelerators.
For Investors and Strategic Acquirers: The market sits at a regulatory-recalibration phase that favors specialized crypto-native incubators with deep protocol expertise over generalist tech accelerators running Bitcoin verticals. Long-term viability across the next decade hinges on sustained Layer-2 infrastructure maturation and ordinals ecosystem expansion. Acquisition target archetype: programs with established validator node infrastructure and European MiCA compliance capabilities. The signal to watch is SEC guidance clarity on token allocation models as inflection indicator for equity-only program economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Lightning Network Infrastructure Partnership | Channel liquidity management expertise addresses the technical debt limiting qualified mentor availability for portfolio companies. |
| MiCA Compliance Architecture Development | Structured regulatory guidance for EU user bases accelerates capital deployment into European blockchain gaming studio cohorts. |
| Ordinals Tooling Acquisition | BRC-20 standard implementation capabilities open NFT functionality applications that existing incubators have not systematically addressed. |
| Academic Research Commercialization Alliance | Zero-knowledge proof partnerships with Cambridge and ETH Zurich secure differentiated technical talent pipelines. |
| Geographic Expansion to Wyoming | State-level crypto-friendly frameworks attract incubator placement away from SEC-intensive traditional financial centers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with incubator program directors, blockchain gaming studio founders, Lightning Network engineers, and SEC regulatory counsel; plus secondary validation through MiCA framework documentation, FINMA token classification guidance, state-level Wyoming and Texas legislative records, and venture capital deployment databases. Primary fieldwork captured operational metrics on cohort progression timelines, milestone structures, and legal architecture costs. Bottom-up triangulation across individual program economics reconciled against top-down market sizing from capital deployment velocity and founder pipeline data.
Forecast inputs considered engagement model segmentation across token allocation, equity-based, and fee-for-service structures; application verticals spanning blockchain gaming, Bitcoin-native DeFi, and wallet solutions; and geographic clusters in Austin, Miami, Berlin, and Singapore. CAGRs were derived from cohort expansion rates and capital deployment trajectories across the projection horizon. Industry-specific inputs included Layer-2 infrastructure maturity curves and ordinals protocol adoption velocity.
Macroeconomic conditions sit as an overlay; deviation in venture capital availability and cryptocurrency market sentiment would shift the trajectory. Forecasts reflect documented assumptions around SEC enforcement continuity and MiCA implementation timelines. Material shifts in token allocation model legality or proof-of-work consensus regulatory treatment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Blockchain in Smart Home Market
Blockchain Technology
Pharmaceutical Blockchain Market
Blockchain Technology
Blockchain in Pharmaceutics Market
Blockchain Technology
Global Blockchain in Logistics Market
Blockchain Technology
Web 3.0 Market
Blockchain Technology
Blockchain Gaming Market
Blockchain Technology
Global Blockchain Supply Chain Market
Blockchain Technology
Web 3.0 Blockchain Market
Blockchain Technology
Marine Blockchain Market
Blockchain Technology
Blockchain Messaging Apps Market
Blockchain Technology
Global Blockchain Market
Blockchain Technology
Blockchain Technology in Energy Market
Blockchain Technology
Blockchain in Energy Utilities Market
Blockchain Technology
Blockchain in Manufacturing Market
Blockchain Technology
Global Blockchain Government Market
Blockchain Technology
Global Blockchain IoT Market