
 Estonia E-Commerce Market | 2026-2036
Estonia E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Estonia E-Commerce Market Foresight
Estonian logistics infrastructure is restructuring around automated last-mile hubs and regional fulfillment nodes. Zalando SE leverages its centralized European warehousing network to serve Estonian fashion buyers with compressed delivery windows. Rimi Baltic anchors its position through integrated online-to-offline grocery fulfillment, while Barbora competes via rapid delivery slots in Tallinn and surrounding municipalities.
Estonia e-commerce denotes digitally mediated transactions for goods and services conducted through web-based interfaces and native mobile applications, typically integrating encrypted payment gateways, inventory management APIs, and real-time order tracking protocols. Fashion and electronics categories within product type segmentation occupy the deepest margin pools due to higher unit values and return-driven repeat engagement. Online marketplaces within sales channel segmentation sustain volume leadership, though mobile apps represent the fastest-growing access point as smartphone penetration deepens across retail consumers and business procurement officers.
Estonia operates under EU regulatory frameworks including the Digital Services Act, GDPR, and Consumer Rights Directive, which collectively mandate platform transparency, data protection standards, and 14-day withdrawal rights for digital purchases. The Estonian Consumer Protection and Technical Regulatory Authority enforces national compliance with these supranational obligations. Stakeholders must monitor evolving EU platform liability rules and domestic enforcement intensity to anticipate compliance cost trajectories.
Market Dynamics
The Estonia e-commerce sector is restructuring around automated fulfillment infrastructure as logistics operators deploy robotic sorting systems and micro-fulfillment nodes to compress delivery windows for Tallinn and Tartu consumers.
Growth Catalysts
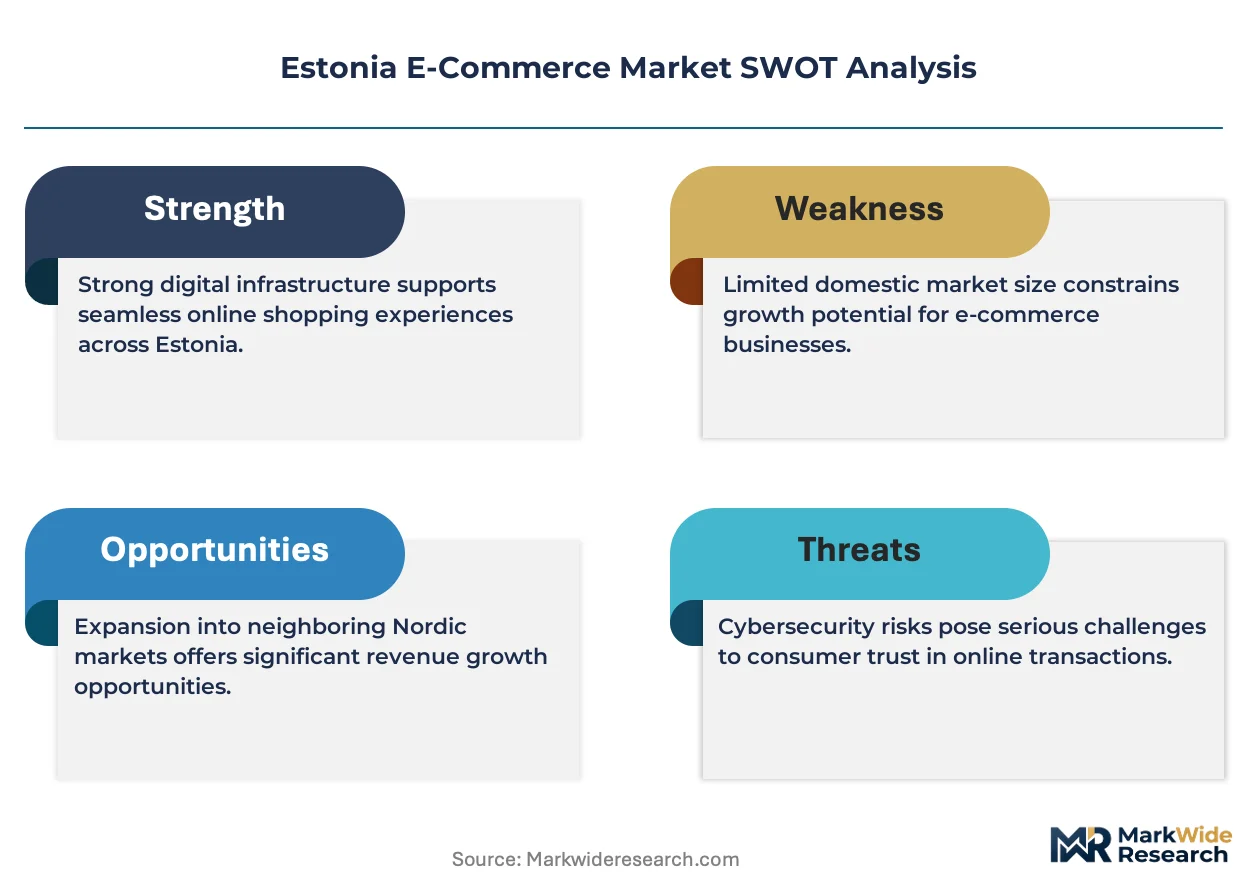
- EU Digital Services Act:Platform transparency mandates are accelerating seller verification standards across Estonian marketplaces, reducing consumer friction in cross-border transactions.
- Smartphone penetration:Mobile-first purchasing behavior among Tallinn urban consumers is expanding addressable reach for grocery and fashion verticals.
- Regional fulfillment nodes:Automated last-mile hubs in Harju and Tartu counties are compressing delivery timelines for perishable goods.
Market Restraints
- Labor cost inflation:Warehouse operator wages in Estonia are rising faster than automation amortization schedules, squeezing margin structures for mid-sized platforms.
- Carrier concentration:Baltic parcel networks depend on a limited set of cross-border logistics providers, creating vulnerability during peak seasonal demand.
- Return logistics complexity:Fashion category return rates impose reverse-flow costs that erode unit economics for apparel-focused retailers.
Strategic Opportunities
- Ida-Viru County:Industrial corridor cities including Narva show underpenetrated e-commerce adoption relative to Tallinn, offering first-mover expansion potential.
- Live commerce integration:Real-time video shopping formats are converging with social platform infrastructure to create new conversion channels for electronics retailers.
- Green delivery mandates:EU Green Deal logistics incentives favor electric vehicle fleet transitions, enabling carbon-neutral positioning for early adopters.
Industry Challenges
- API integration complexity:Legacy inventory management systems at Estonian retailers require costly middleware development to connect with marketplace platforms.
- GDPR compliance timelines:Data localization requirements for cross-border payment processors extend certification cycles for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Estonia E-Commerce Market |
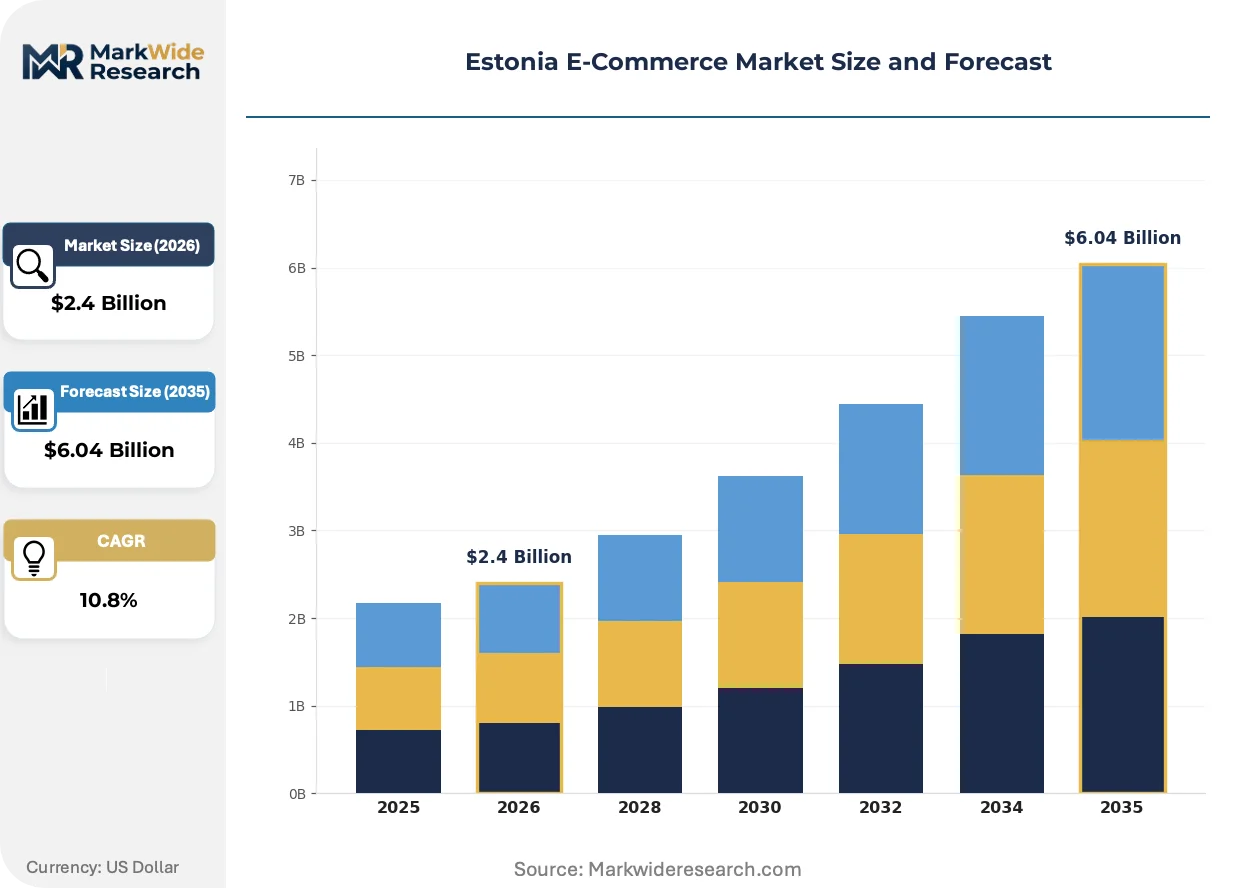
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.04 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronics, Fashion, Home Goods, Groceries Customer Type: Retail Consumers, Businesses, Educational Institutions, Non-profits Sales Channel: Online Marketplaces, Brand Websites, Social Media, Mobile Apps Payment Method: Credit Cards, PayPal, Bank Transfers, Digital Wallets |
| Companies Covered | Zalando SE, Rimi Baltic, Barbora, Coop Maksimarket, Pigu Group, Selver AS, Kaubamaja Grupp, Prisma Peremarket, Euronics Estonia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Estonia E-Commerce Market Shifts & Advancements
Three distinct vectors are reshaping Estonian digital commerce: warehouse robotics compressing fulfillment economics, EU platform accountability rules recalibrating seller relationships, and mobile-native purchasing patterns fragmenting traditional category loyalty.
Warehouse robotics is automating order picking and sortation processes across Tallinn-area distribution centers. Omnichannel retailers are deploying autonomous mobile robots at accelerating pace to handle grocery and fashion SKU proliferation. This automation is compressing labor cost exposure while enabling same-day delivery promises previously reserved for premium tiers.
GDPR enforcement intensity from the Estonian Consumer Protection and Technical Regulatory Authority is tightening data handling protocols for marketplace operators. Cross-border platforms must now maintain localized data processing records and breach notification procedures. Fashion and electronics segments with high cross-border purchase volumes face the steepest compliance adaptation costs.
Subscription-based replenishment models are displacing transactional purchasing for household consumables in Tartu and Tallinn. Traditional supermarket loyalty programs are losing traction to app-native auto-delivery services that lock in recurring revenue. Grocery verticals show the most visible behavioral shift, with urban consumers prioritizing convenience over price comparison.
Estonia E-Commerce Market Segmentation
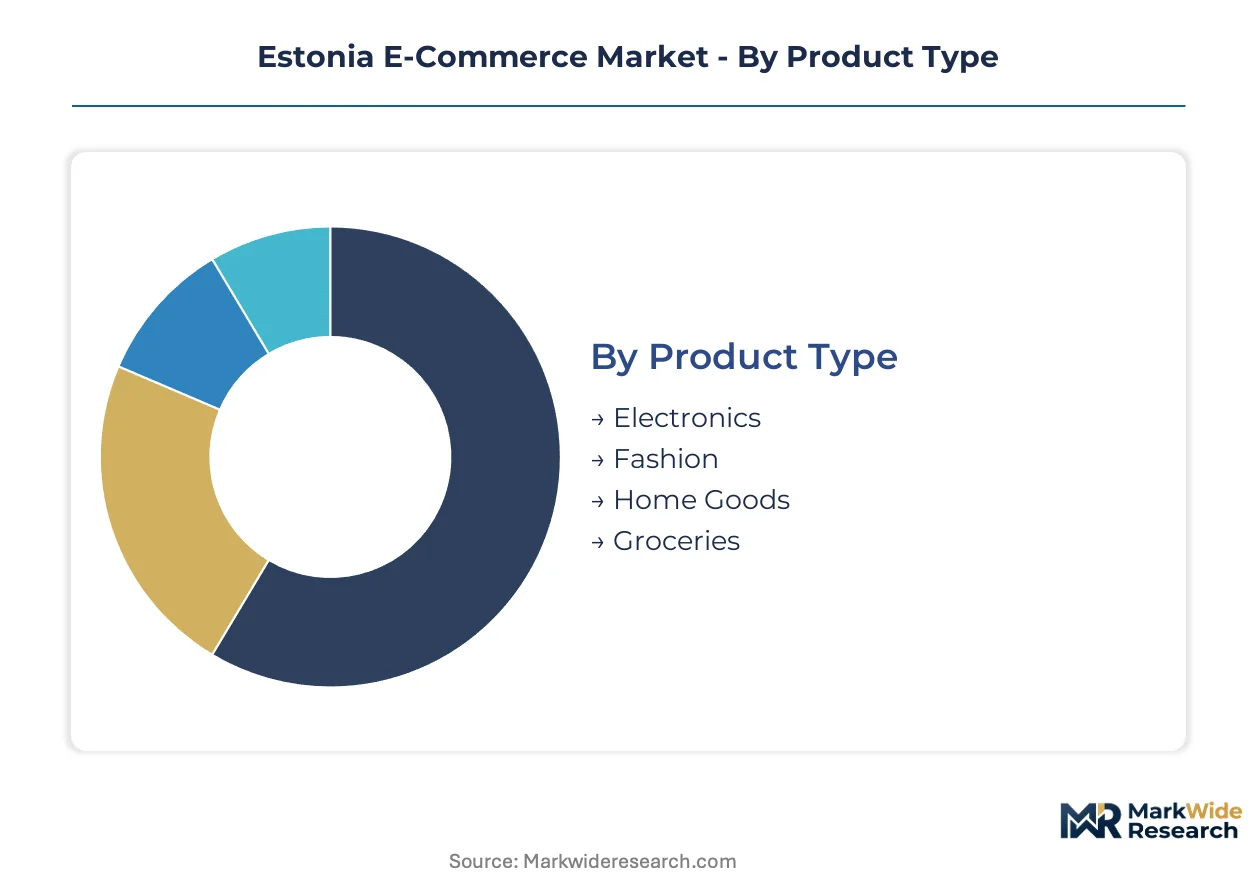
Estonian e-commerce segmentation reveals distinct operational economics across product verticals and channel architectures. Upgrade cycles in electronics and fashion drive repeat purchase frequency, while grocery adoption accelerates through subscription mechanics. Understanding these segment boundaries enables precise resource allocation for platform operators and logistics providers.
Product Type:
Replacement-driven purchasing patterns in electronics and fashion create the highest customer lifetime value pools, with upgrade cycles compressing as smartphone refresh rates and seasonal fashion calendars accelerate.
- Electronics:High-consideration purchases encompassing smartphones, laptops, and consumer appliances with extended warranty attachment rates. Demand clusters in Tallinn's tech-savvy urban corridors where younger demographics prioritize specification transparency and rapid delivery windows over price comparison.
- Fashion:Apparel and accessories with elevated return logistics complexity due to sizing uncertainty and visual-tactile mismatch. Tartu and Tallinn urban consumers drive volume, though return rates erode unit economics and necessitate sophisticated reverse logistics infrastructure.
- Home Goods:Furniture, décor, and household equipment with bulky fulfillment requirements. Narva and other Ida-Viru corridor cities show underpenetrated adoption relative to capital region saturation.
- Groceries:Perishable and packaged food products with compressed delivery windows and temperature-controlled handling mandates. Subscription auto-replenishment models are displacing transactional purchasing in Harju and Tartu counties.
Volume placements concentrate in Electronics; the faster expansion belongs to Groceries.
Customer Type:
Procurement authority and order frequency diverge sharply across organizational boundaries, with business buyers demanding invoice integration and educational institutions requiring competitive tender compliance.
- Retail Consumers:Individual purchasers with fragmented basket sizes and high price elasticity. Mobile-native behavior dominates in Tallinn and Tartu urban cores where app-based purchasing has normalized.
- Businesses:Corporate procurement officers with volume-based negotiation leverage and ERP integration requirements. B2B platforms must support purchase order workflows and VAT-compliant invoicing to capture this segment.
- Educational Institutions:Universities and schools with formal tender processes and extended payment terms. Tartu University corridor generates concentrated demand for electronics and educational materials.
- Non-profits:Charitable organizations with constrained budgets and donor accountability requirements. Smaller transaction volumes but mission-aligned supplier preferences create niche positioning opportunities.
Transaction frequency peaks among Retail Consumers; revenue per order climbs highest for Businesses.
Sales Channel:
Channel economics shift as discovery and fulfillment functions decouple, with social platforms capturing upstream attention and dedicated apps monetizing through convenience premiums.
- Online Marketplaces:Aggregator platforms with multi-seller inventory and comparison shopping infrastructure. Zalando SE and regional operators sustain volume leadership through centralized European warehousing networks serving Estonian buyers.
- Brand Websites:Direct-to-consumer channels with margin retention advantages and first-party data accumulation. Fashion and electronics verticals leverage exclusive drops and loyalty programs to reduce marketplace dependency.
- Social Media:Discovery-driven commerce through Instagram and TikTok with impulse purchase mechanics. Live commerce formats are converging with platform infrastructure to create conversion channels for electronics retailers.
- Mobile Apps:Native applications with push notification re-engagement and streamlined checkout flows. Grocery verticals show the most visible behavioral shift toward app-native auto-delivery services.
Marketplace volume retains dominance; Mobile Apps gain share fastest through convenience-driven urban adoption.
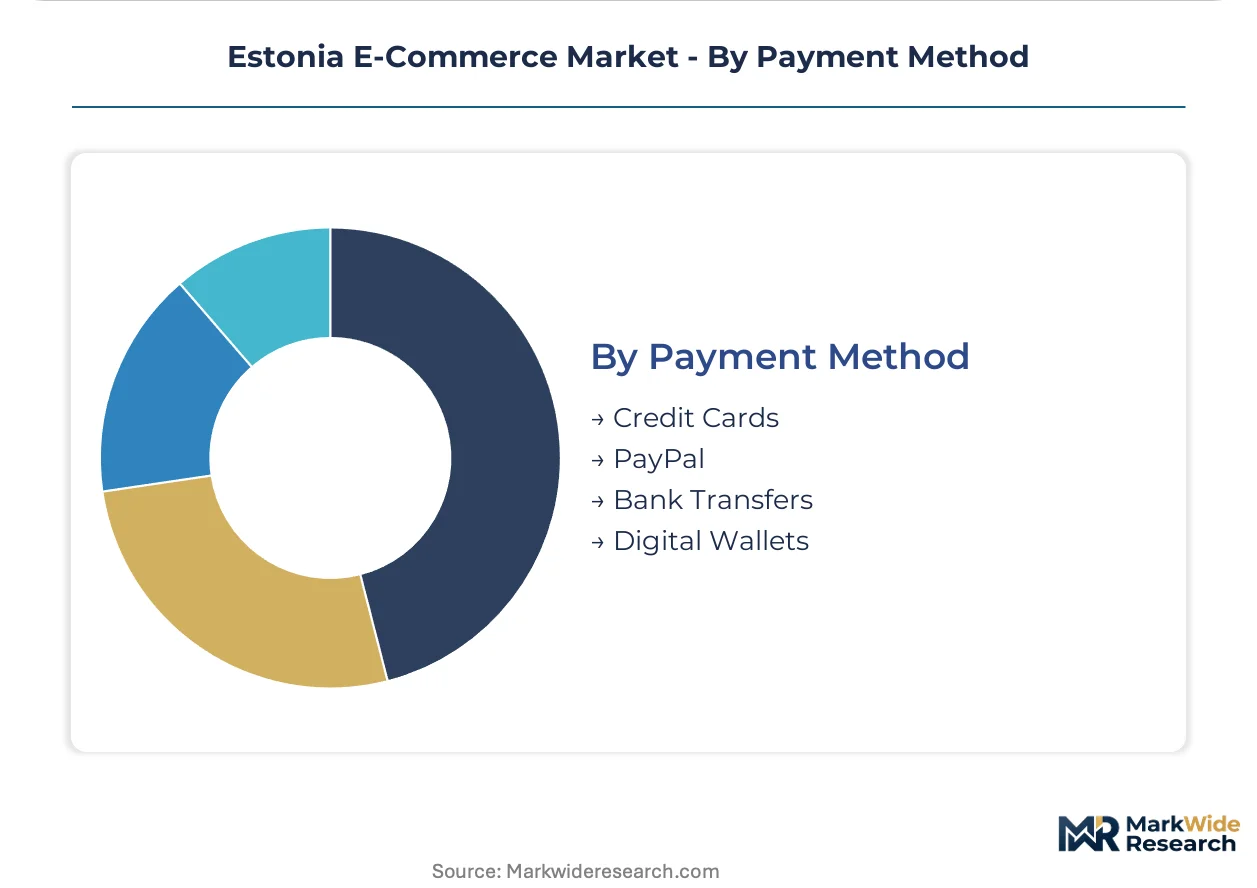
Payment Method:
Settlement infrastructure preferences reflect trust hierarchies and transaction size thresholds, with digital wallets displacing traditional instruments among younger demographics.
- Credit Cards:Revolving credit instruments with chargeback protection and reward program attachment. Dominant for electronics and fashion purchases above threshold values where consumer protection matters.
- PayPal:Stored-credential wallets with cross-border transaction facilitation. Strong penetration in fashion purchases from international marketplaces where buyer protection reduces perceived risk.
- Bank Transfers:Direct debit arrangements with lower merchant fees but extended settlement timelines. Preferred by B2B procurement and cost-conscious retail consumers in price-sensitive categories.
- Digital Wallets:Smartphone-integrated payment tokens with biometric authentication and one-tap checkout. Apple Pay and Google Pay adoption accelerates among Tallinn's mobile-first consumer base.
Credit Cards process the largest transaction values; Digital Wallets expand most quickly through smartphone penetration deepening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Harju County's digital infrastructure density anchors Estonian e-commerce logistics, with fiber-optic penetration and automated fulfillment nodes concentrating buyer activity in the Tallinn metropolitan corridor.
Harju County
Smartphone penetration rates exceeding national averages drive mobile-first grocery and fashion purchasing among Tallinn's urban consumers. The Estonian Consumer Protection and Technical Regulatory Authority enforces GDPR compliance timelines for cross-border payment processors operating in the capital. Last-mile automation hubs in Tallinn compress delivery windows for perishable goods and electronics.
Tartu County
University-driven electronics demand from Tartu University students and faculty sustains high-consideration purchase volumes for laptops and educational devices. EU Digital Services Act platform transparency mandates apply to marketplace operators serving this academic corridor. Tartu urban core shows accelerating subscription-based replenishment adoption for household consumables.
Ida-Viru County
Industrial corridor cities including Narva exhibit underpenetrated e-commerce adoption relative to capital region saturation, creating first-mover expansion potential for grocery and home goods verticals. National enforcement of EU Consumer Rights Directive withdrawal protocols applies equally to this eastern region. Narva's logistics connectivity improvements are attracting regional fulfillment node investment.
Pärnu County
Seasonal tourism fluctuations generate variable demand spikes for fashion and electronics among domestic and international visitors. GDPR data localization requirements extend certification cycles for new market entrants targeting this coastal market. Pärnu's retail infrastructure is integrating online-to-offline fulfillment capabilities to capture visitor purchasing.
Lääne-Viru County
Commuter-linked purchasing patterns connect Rakvere residents to Tallinn's marketplace inventory while sustaining local grocery delivery platform subscriptions. Estonian national compliance with EU Green Deal logistics incentives favors electric vehicle fleet transitions for operators serving this northern corridor. Rakvere distribution points are expanding same-day coverage zones.
Estonia E-Commerce Market Competitive Landscape
Global majors compete with regional champions across fulfillment infrastructure and delivery velocity dimensions. The Estonian e-commerce sector shows moderate concentration, with pan-European fashion aggregators and Baltic grocery specialists coexisting alongside domestic retail incumbents. Two strategic archetypes dominate: centralized European warehousing networks serving cross-border fashion demand, and integrated online-to-offline grocery operators with captive store footprints. Competitive moves center on last-mile automation deployment and subscription-based customer lock-in mechanics.
Among Germany-based fashion aggregators, Zalando SE exemplifies the centralized warehousing archetype serving Estonian buyers through compressed European delivery windows. Baltic grocery specialists Rimi Baltic and Barbora occupy distinct positioning within the rapid fulfillment tier, with the former leveraging integrated store networks and the latter competing via dedicated delivery slot density in Tallinn and surrounding municipalities.
| Leading Market Players |
|---|
| Zalando SE |
| Rimi Baltic |
| Barbora |
| Coop Maksimarket |
| Pigu Group |
| Selver AS |
| Kaubamaja Grupp |
| Prisma Peremarket |
| Euronics Estonia |
| Others |
Supply & Pricing Matrix
EU Green Deal logistics incentives gate qualified supply access and premium-tier pricing power for Estonian e-commerce operators, favoring electric fleet transitions and carbon-neutral fulfillment infrastructure as baseline requirements for competing in Tallinn and Tartu urban corridors.
Pricing Analysis
Warranty and return-service bundling separates premium electronics retailers from unbundled marketplace sellers in Estonia, with extended protection plans and hassle-free reverse logistics commanding price premiums in smartphone and laptop categories. Three-tier pricing structure across premium, standard, and economy levels tracks delivery velocity and after-sales service depth, with same-day fulfillment and instant replacement guarantees anchoring top-tier positioning. Cost compression in mid-market fashion verticals is intensifying because return logistics complexity erodes unit economics, squeezing platforms unable to amortize reverse-flow infrastructure. Business procurement officers show lowest price sensitivity due to ERP integration requirements and invoice workflow value, while individual retail consumers in Narva and Ida-Viru corridor cities exhibit highest elasticity.
Supply Chain Analysis
Domestic-content mandates under EU Digital Services Act seller verification protocols are reshaping sourcing requirements for Estonian marketplaces, forcing platform operators to validate local business registrations and tax compliance documentation before listing access. Geographic supply concentration draws from Germany, Poland, and the Netherlands for fashion and electronics inventory, with Baltic grocery specialists sourcing perishables from regional agricultural cooperatives in Latvia and Lithuania. Raw material dependencies rest on semiconductor components for electronics, synthetic textiles for fast fashion, and temperature-controlled packaging for grocery verticals. Single-source vulnerability runs through Baltic parcel networks dependent on limited cross-border logistics providers. Distribution feeds from centralized European warehousing networks through last-mile automation hubs in Harju and Tartu counties.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Estonian e-commerce is consolidating around automated fulfillment scale and subscription-based customer lock-in, with labor cost inflation and carrier concentration squeezing mid-sized platforms unable to amortize infrastructure investments.
For Market Incumbents: Acquire automated last-mile hub capacity in Tartu County and Ida-Viru corridor cities to compress delivery windows for grocery and electronics verticals. Backward integration into temperature-controlled fleet assets reduces carrier concentration exposure during peak seasonal demand. Invest in GDPR-compliant data localization infrastructure to preempt certification cycle extensions for cross-border payment processing. For New Entrants and Emerging Players: Capture underpenetrated home goods demand in Narva and Rakvere where commuter-linked purchasing patterns create first-mover expansion potential. Target live commerce integration for electronics retail, leveraging real-time video shopping formats to bypass established marketplace discovery economics. Deploy app-native auto-replenishment services with push notification re-engagement to lock in recurring grocery revenue before incumbent subscription migration completes. For Investors and Strategic Acquirers: Accelerating warehouse robotics deployment across Tallinn-area distribution centers is the leading indicator that fulfillment automation scale is becoming the primary competitive moat. Platforms with integrated online-to-offline grocery networks and captive store footprints represent the most defensible acquisition archetype over the medium-term horizon. Monitor EU Digital Services Act enforcement intensity from the Estonian Consumer Protection and Technical Regulatory Authority as the signal for compliance cost trajectories affecting new entrant viability.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Fulfillment Hub Deployment | Robotic sorting systems in Harju County compress delivery windows for perishable goods. |
| Subscription-Based Customer Lock-In | Auto-replenishment models displace transactional purchasing in Tartu and Tallinn grocery verticals. |
| Electric Fleet Transition | EU Green Deal incentives enable carbon-neutral positioning for early logistics adopters. |
| GDPR Data Localization Investment | Localized processing records preempt certification delays for cross-border payment processors. |
| Live Commerce Platform Integration | Real-time video shopping creates conversion channels for electronics retailers beyond traditional discovery. |
Research Methodology
Independent corroboration across platform operations executives, logistics network managers, and regulatory compliance officers underwrites the qualitative findings, combined with validation from Estonian Consumer Protection and Technical Regulatory Authority guidance documents, EU Digital Services Act implementation notices, and customs trade flow records. Bottom-up demand modeling triangulates against top-down macroeconomic indicators across the analysis window.
Rate-of-change decomposition separates volume growth from mix-shift effects across product type segmentation, customer type procurement authority tiers, and sales channel migration patterns. Modeled dimensions span electronics replacement cycles, fashion return-rate economics, grocery subscription mechanics, and mobile app penetration trajectories. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporate smartphone refresh rate acceleration and automated warehouse robotics deployment schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU platform liability rule evolution, labor cost inflation trajectories, and carrier network consolidation dynamics. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Slovak Republic E-Commerce Market
E-Commerce Solutions
Latin America E-Commerce Logistics Market
E-Commerce Solutions
Southeast Asia Cross-Border E-Commerce Market
E-Commerce Solutions
Finland E-Commerce Market
E-Commerce Solutions
Dropshipping Market
E-Commerce Solutions
Second-Hand E-Commerce Market
E-Commerce Solutions
Italy E-Commerce Market
E-Commerce Solutions
Shopping Application Market
E-Commerce Solutions
Qatar E-Commerce Market
E-Commerce Solutions
E-Commerce Buy Now Pay Later Market
E-Commerce Solutions
E-Commerce Household Appliances Market
E-Commerce Solutions
Business to Business E Commerce Market
E-Commerce Solutions
Digital Gift Cards (Egift Cards) Market
E-Commerce Solutions
Cross-Border B2C E-Commerce Market
E-Commerce Solutions
Spain E-Commerce Market
E-Commerce Solutions
Middle East and Africa E-Commerce Apparel Market