
 Asia-Pacific Database Management Software Market | 2026-2036
Asia-Pacific Database Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Database Management Software Market Analytics
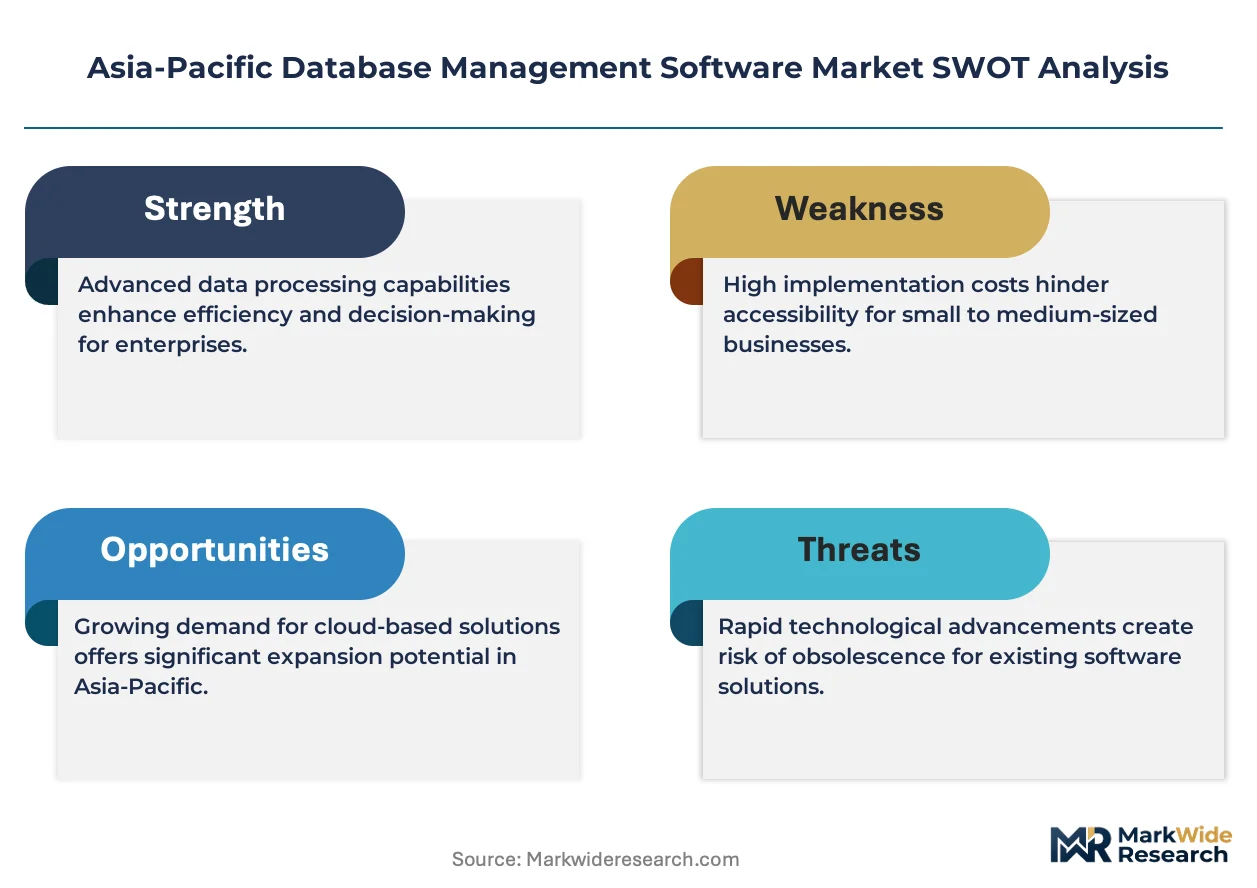
Singapore's data center expansion is tilting regional capacity toward ASEAN cloud infrastructure. Oracle Corporation anchors enterprise relational database deployments across Southeast Asian banking networks. Amazon Web Services competes through distributed database services tailored to multi-zone resilience requirements. Microsoft Corp extends its hybrid cloud database footprint through localized Azure regions in Australia and Japan.
Database management software encompasses systems that organize, store, retrieve, and manipulate structured and unstructured data through query languages, indexing algorithms, and transaction management protocols with ACID compliance or BASE flexibility. These platforms serve commercial and industrial users by enabling real-time analytics, operational record-keeping, and regulatory reporting across transactional and analytical workloads. Relational database systems sustain dominant revenue share in BFSI and legacy enterprise environments where SQL standardization and mature tooling preserve switching costs. NoSQL database architectures capture accelerating demand from retail and IT services sectors managing variable schema requirements and horizontal scaling imperatives. Cloud database deployment models concentrate margin pools in managed services where infrastructure abstraction reduces customer total cost of ownership.
India's Digital Personal Data Protection Act imposes data fiduciary obligations that reshape vendor architectural choices for on-premises and hybrid deployments. China's Cybersecurity Law and data localization requirements, enforced by the Cyberspace Administration of China, restrict cross-border data flows and compel in-country infrastructure investment. Australia's Privacy Act and Notifiable Data Breaches scheme, administered by the Office of the Australian Information Commissioner, elevate encryption and access control standards for healthcare and government database implementations. Stakeholders must weigh sovereign data requirements against cloud agility when selecting deployment architectures and geographic redundancy strategies.
Market Dynamics
Cloud-native database architectures are forcing a wholesale reconfiguration of vendor competitive positioning across Asia-Pacific financial services, as sovereign data mandates and latency requirements fracture previously centralized deployment models.
Growth Catalysts
- India's Digital Personal Data Protection Act:Data fiduciary obligations are compelling domestic enterprises to upgrade on-premises and hybrid database infrastructure, creating immediate replacement demand.
- Distributed SQL adoption:BFSI institutions across Southeast Asia are deploying horizontally scalable relational engines to support real-time payment clearing systems.
- China's fintech hub concentration:Shenzhen and Hangzhou payment processors are driving specialized graph database deployments for fraud detection networks.
Market Restraints
- Data localization hardware costs:China's Cybersecurity Law mandates in-country server deployment, inflating capital requirements for foreign vendors.
- Legacy Oracle skill scarcity:Southeast Asian system integrators face acute shortages of certified DBAs for mission-critical banking migrations.
- Open-source substitution pressure:PostgreSQL and MongoDB Community Edition are capturing mid-market workloads previously served by commercial licenses.
Strategic Opportunities
- ASEAN cloud infrastructure gap:Vietnam and Philippines enterprise segments remain underpenetrated by managed database services.
- Australia's Privacy Act encryption mandates:Healthcare providers must upgrade database security layers, creating compliance-driven refresh cycles.
- Edge-database convergence:5G manufacturing networks in South Korea and Japan require localized transaction processing at plant level.
Industry Challenges
- Multi-cloud orchestration complexity:Japanese automotive suppliers struggle to maintain transactional consistency across AWS, Azure, and domestic cloud zones.
- Cross-border data governance fragmentation:India's data protection authority and China's cyberspace administration impose conflicting residency requirements on regional headquarters operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Database Management Software Market |
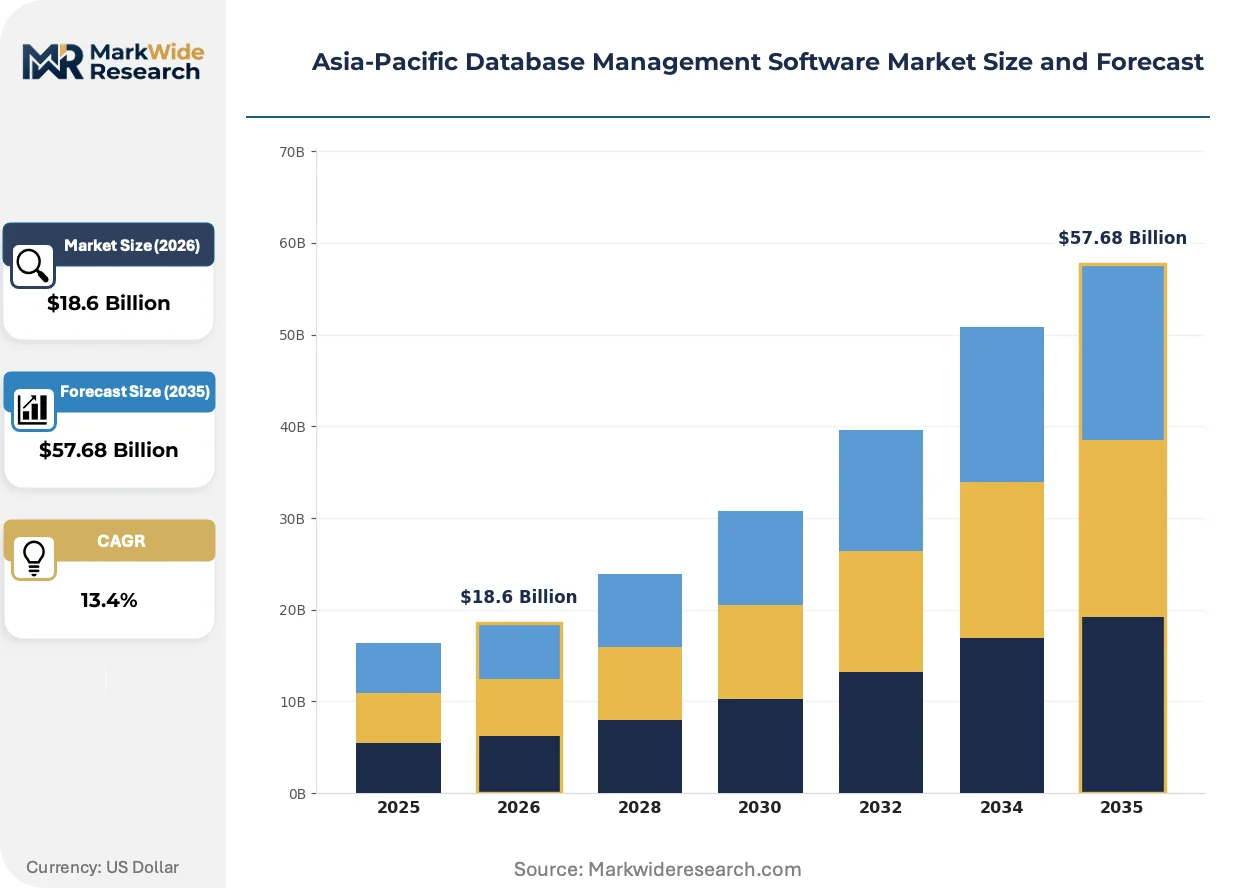
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $57.68 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Relational Database, NoSQL Database, In-Memory Database, Cloud Database Deployment Model: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud End User: IT Services, BFSI, Retail, Healthcare Technology: Machine Learning, Data Warehousing, Big Data Analytics, Distributed Database |
| Companies Covered | SAP SE, Google Cloud, Oracle Corporation, MongoDB Inc, Teradata Corp, International Business Machines Corp, Amazon Web Services, Snowflake Inc, Microsoft Corp, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Database Management Software Market Evolving Landscape
Serverless database provisioning is compressing procurement cycles and collapsing traditional capacity planning disciplines across Asia-Pacific enterprise IT.
Vector database extensions are rendering obsolete conventional full-text indexing for AI-powered recommendation engines. E-commerce platforms in Singapore and Australia are adopting pgvector and specialized vector stores within six-month procurement windows. This shift is rendering obsolete the Lucene-based search architectures that dominated product discovery stacks for two decades.
China's data localization enforcement by the Cyberspace Administration of China is mandating in-country encryption key custody and audit logging. Foreign cloud vendors must establish joint ventures or license technology to domestic operators. BFSI deployments in Shanghai and Beijing are responding by bifurcating architectures between domestic and international instances.
Consumption-based pricing is displacing perpetual licensing in Australian and Japanese enterprise procurement. Database vendors now meter by query volume and storage tier rather than socket or core. This pattern is most visible in Sydney and Tokyo financial services, where operational expenditure treatment outweighs capital efficiency considerations.
Asia-Pacific Database Management Software Market Segmentation
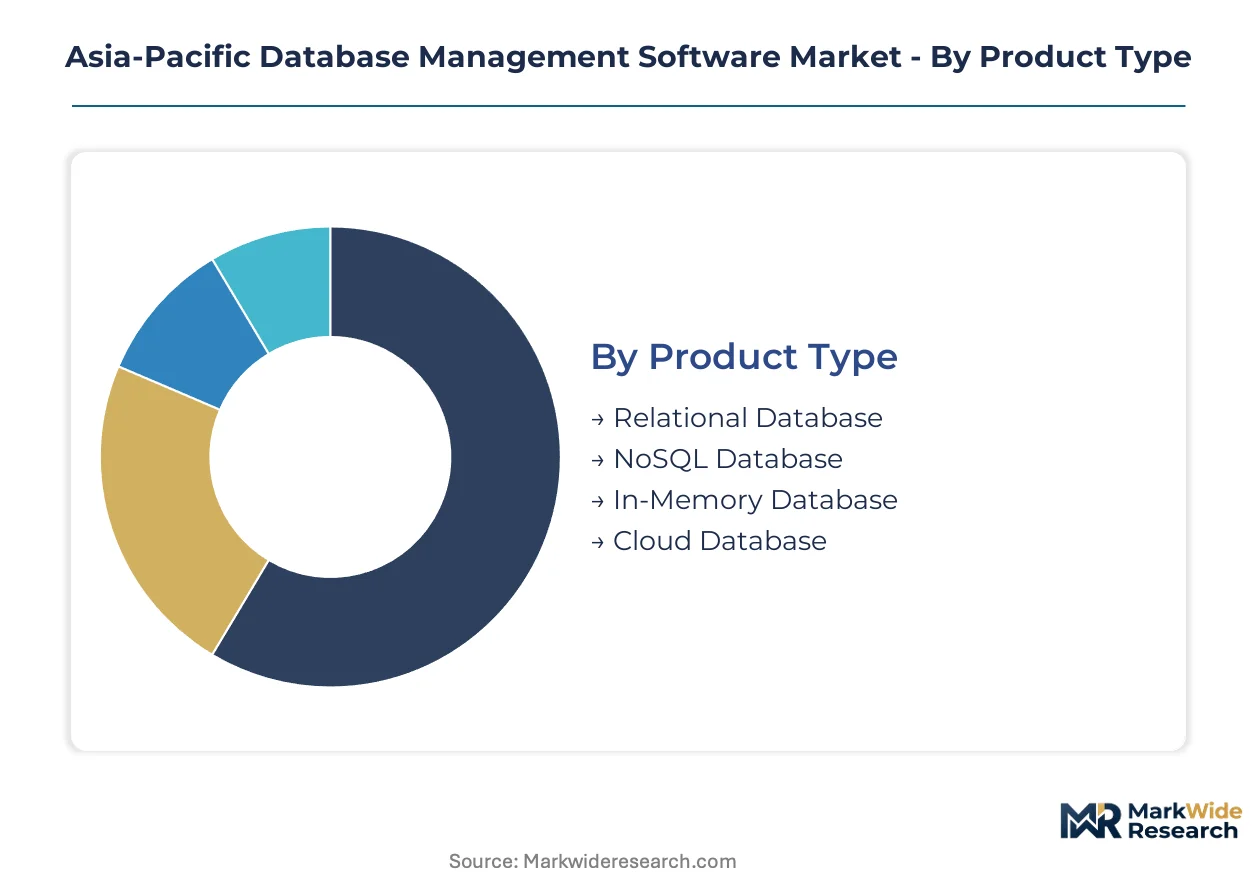
Database management software segmentation in Asia-Pacific reflects divergent workload requirements across sovereign data jurisdictions and cloud maturity levels. Vendor positioning depends on matching architectural flexibility to India's data fiduciary obligations, China's localization mandates, and Australia's encryption standards.
Product Type:
Use-case spectrum spans legacy transaction processing through real-time AI inference, with schema flexibility and latency tolerance determining architectural selection.
- Relational Database:ACID-compliant engines with SQL standardization dominate BFSI core banking systems across Southeast Asian trade finance networks. Japanese megabanks and Singaporean sovereign wealth funds sustain demand for mature tooling and certified DBA ecosystems despite cloud migration pressure.
- NoSQL Database:Document, key-value, and wide-column stores handle variable schema requirements in Indian e-commerce platforms and Chinese social commerce backends. Horizontal scaling imperatives drive MongoDB and Cassandra deployments where transactional consistency relaxes toward eventual consistency models.
- In-Memory Database:SAP HANA and Redis Enterprise power sub-millisecond fraud detection in South Korean payment networks.
- Cloud Database:Managed PostgreSQL and Aurora instances concentrate margin pools in Sydney and Tokyo financial services procurement.
The dominant share belongs to Relational Database, while NoSQL Database is gaining share fastest among retail and IT services workloads.
Deployment Model:
Cost tier stratification separates capital-intensive sovereign infrastructure from operational expenditure flexibility in regulated industries.
- On-Premises:Dedicated hardware deployments persist in Chinese state-owned enterprises and Indian public sector banks where data localization laws prohibit cross-border cloud residency. Capital expenditure treatment and air-gapped security architectures sustain procurement despite higher total cost of ownership.
- Public Cloud:AWS, Azure, and Alibaba Cloud managed database services capture Australian healthcare and Japanese manufacturing workloads seeking consumption-based pricing and elastic capacity. Operational expenditure classification and automated patching reduce internal infrastructure management burden.
- Private Cloud:VMware and OpenStack-based database platforms serve ASEAN defense contractors and Australian government agencies with hybrid control requirements.
- Hybrid Cloud:Split architectures bifurcate sensitive transaction processing on-premises while analytics workloads burst to public cloud in Indian IT services corridors.
Public Cloud holds the dominant share, though Hybrid Cloud shows the steepest expansion trajectory as sovereignty requirements fracture previously centralized models.
End User:
Customer type concentration maps to digital transformation maturity and regulatory compliance burden across national boundaries.
- IT Services:Indian system integrators and Philippine business process outsourcing firms deploy multi-tenant database platforms for global enterprise clients. Data residency requirements and cross-border project delivery create demand for geographically distributed database replication.
- BFSI:Banks, insurers, and payment processors across Indonesia, Thailand, and Vietnam drive distributed SQL adoption for real-time clearing systems. Regulatory capital requirements and disaster recovery mandates sustain premium pricing for high-availability configurations.
- Retail:Australian supermarket chains and Southeast Asian marketplace operators adopt vector databases for recommendation personalization.
- Healthcare:Japanese hospital networks and Australian aged care providers upgrade encryption layers under privacy act mandates.
BFSI commands the dominant share, while Healthcare is expanding most quickly under compliance-driven refresh cycles.
Technology:
Maturity gradient separates production-hardened analytics stacks from emerging AI-integrated architectures.
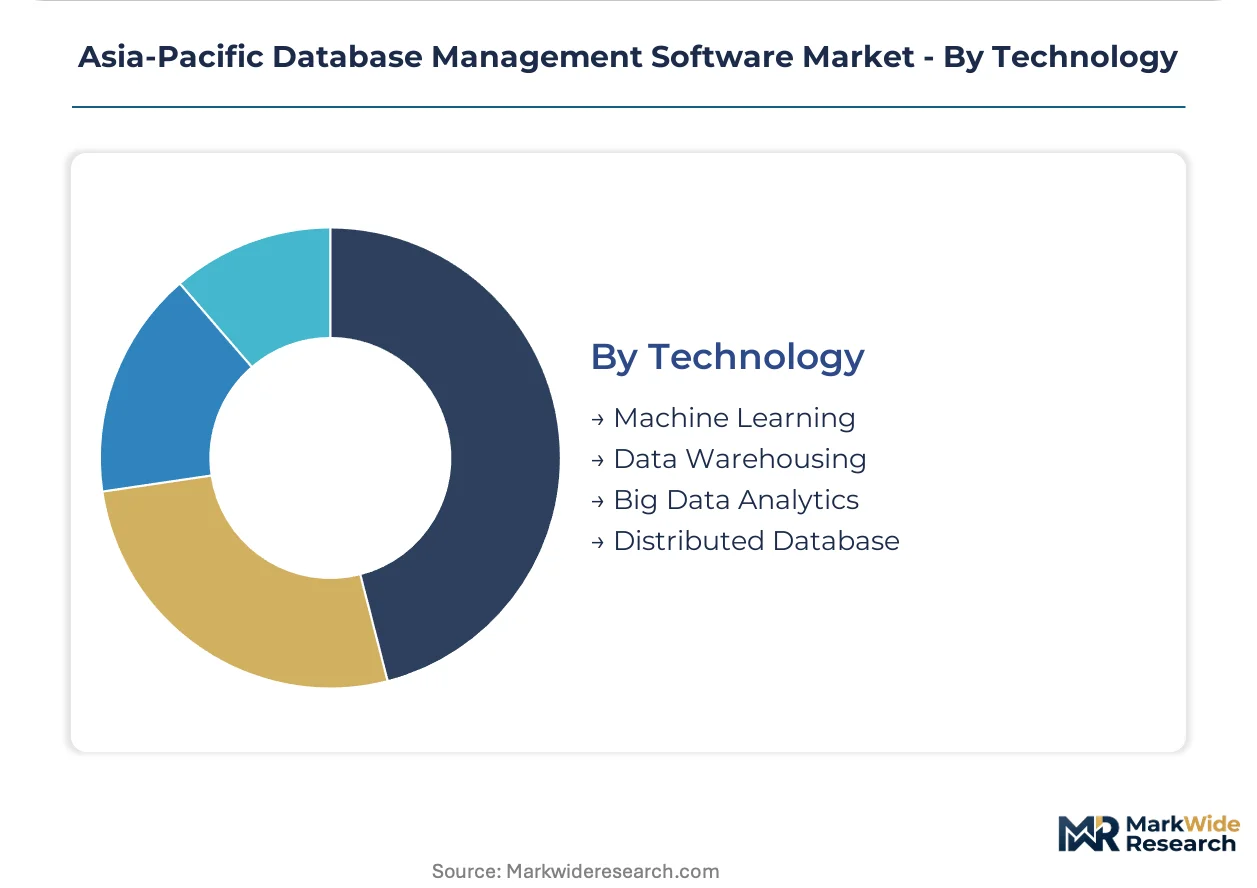
- Machine Learning:Embedded ML operators in cloud databases automate query optimization and anomaly detection for Chinese fintech risk engines. TensorFlow and PyTorch integration with feature stores accelerates model deployment pipelines in Singaporean algorithmic trading firms.
- Data Warehousing:Snowflake and BigQuery deployments consolidate fragmented ERP systems in Australian mining conglomerates and Japanese automotive suppliers. Separation of compute and storage architectures reduces idle capacity costs for intermittent analytical workloads.
- Big Data Analytics:Spark and Hadoop ecosystems process telemetry streams in South Korean smart factory networks.
- Distributed Database:CockroachDB and YugabyteDB engines span multi-zone deployments for ASEAN payment infrastructure resilience.
Data Warehousing maintains the dominant share, while Machine Learning is climbing the fastest as vector extensions reshape database procurement priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the Asia-Pacific database management software market, with Chinese enterprises prioritizing sovereign data infrastructure while Australian and Japanese buyers favor consumption-based cloud procurement models.
China
State-owned enterprises and fintech payment processors in Shenzhen and Hangzhou drive specialized graph database deployments for fraud detection networks. The Cyberspace Administration of China enforces data localization through mandatory in-country encryption key custody and audit logging requirements. Foreign cloud vendors must establish joint ventures or license technology to domestic operators, bifurcating architectures between domestic and international instances.
India
IT services corridors in Bengaluru and Hyderabad deploy multi-tenant database platforms for global enterprise clients facing cross-border data residency requirements. The Digital Personal Data Protection Act imposes data fiduciary obligations that compel domestic enterprises to upgrade on-premises and hybrid infrastructure. System integrators face acute shortages of certified database administrators for mission-critical banking migrations.
Japan
Automotive suppliers in Nagoya and Tokyo struggle to maintain transactional consistency across multi-cloud zones spanning AWS, Azure, and domestic cloud providers. METI guidelines encourage operational expenditure classification for database procurement, accelerating consumption-based pricing adoption. Healthcare providers in Osaka must upgrade encryption layers under privacy act mandates.
Australia
Sydney and Melbourne financial services firms concentrate margin pools in managed PostgreSQL and Aurora instances seeking elastic capacity. The Privacy Act and Notifiable Data Breaches scheme administered by the Office of the Australian Information Commissioner elevates encryption standards. Mining conglomerates consolidate fragmented ERP systems through Snowflake and BigQuery deployments.
Singapore
Sovereign wealth funds and Southeast Asian banking networks sustain demand for mature relational tooling despite cloud migration pressure. Data center expansion tilts regional capacity toward ASEAN cloud infrastructure, attracting Oracle Corporation enterprise deployments. E-commerce platforms adopt pgvector extensions for AI-powered recommendation engines within compressed procurement cycles.
Asia-Pacific Database Management Software Market Competitive Landscape
Capability concentration sits with established relational database vendors possessing mature certified administrator ecosystems; scale advantage sits with hyperscale cloud providers offering distributed infrastructure abstraction. The market structures around three tiers: legacy enterprise incumbents with switching cost protection, cloud-native challengers capturing horizontal scaling workloads, and open-source distributors eroding mid-market commercial license positions. Dominant competitive moves include strategic partnerships with regional system integrators and geographic expansion through localized cloud region establishment.
Within the legacy enterprise tier, Oracle Corporation and SAP SE exemplify vendors sustaining dominant revenue share in BFSI core banking systems through SQL standardization and mature tooling. Microsoft Corp occupies a position bridging on-premises and hybrid cloud deployments through localized Azure regions in Australia and Japan. Amazon Web Services represents the hyperscale archetype competing through distributed database services tailored to multi-zone resilience requirements.
| Leading Market Players |
|---|
| SAP SE |
| Google Cloud |
| Oracle Corporation |
| MongoDB Inc |
| Teradata Corp |
| International Business Machines Corp |
| Amazon Web Services |
| Snowflake Inc |
| Microsoft Corp |
| Others |
Value Network & Pricing Analysis
The Shanghai-Singapore data center freight corridor channels hardware procurement costs directly into downstream pricing stratification across cloud-native and on-premises deployment tiers. Transit delays through this corridor amplify capital expenditure premiums for Chinese localization-compliant infrastructure while compressing margins on ASEAN-managed service offerings.
Pricing Analysis
Geographic price spreads between Sydney-Tokyo financial services procurement and Vietnam-Philippines enterprise segments exceed three-to-one for equivalent managed PostgreSQL configurations. Consumption-based metering by query volume and storage tier dominates Australian and Japanese operational expenditure classifications, while Indian and Chinese buyers face perpetual licensing premiums for sovereign-compliant deployments. Cost compression in mid-market commercial licenses intensifies as PostgreSQL and MongoDB Community Edition capture workloads previously served by enterprise agreements. IT services corridors in Bengaluru and Hyderabad exhibit the highest price sensitivity due to multi-tenant margin pressure, whereas Singaporean sovereign wealth funds sustain premium pricing for certified Oracle DBA ecosystems.
Supply Chain Analysis
Upstream semiconductor feedstock for database server hardware concentrates in Taiwan, South Korea, and Japan, with advanced node dependencies for in-memory processing engines. Memory modules, flash storage arrays, and specialized AI accelerators anchor bill-of-materials volatility for high-performance deployments. Single-source vulnerability in advanced packaging capacity threatens delivery timelines for SAP HANA and Redis Enterprise configurations in South Korean payment networks. Distribution runs through hyperscale cloud provider direct procurement channels for public cloud workloads, while on-premises deployments channel through regional system integrators with certified administrator ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open-source substitution pressure from PostgreSQL and MongoDB Community Edition demands active defense from commercial license incumbents across Asia-Pacific mid-market procurement. Incumbents must navigate this threat through architectural lock-in and certified ecosystem deepening.
For Market Incumbents: Pre-empt defection to open-source alternatives by embedding vector database extensions and ML operators that exceed community edition capabilities. Deepen vertical integration into certified administrator training pipelines across Southeast Asian system integrators to preserve switching cost protection. Oracle and SAP SE must accelerate localized cloud region establishment in Vietnam and Philippines before hyperscale providers capture emerging ASEAN demand.
For New Entrants and Emerging Players: Pursue underpenetrated managed database service opportunities in Vietnamese and Philippine enterprise segments where sovereign data requirements have delayed hyperscale adoption. Target hybrid cloud orchestration tooling for Japanese automotive suppliers struggling with multi-cloud transactional consistency. Lead with consumption-based pricing models that align with METI operational expenditure guidelines in Tokyo and Nagoya procurement cycles.
For Investors and Strategic Acquirers: Carve-out targets emerge from legacy system integrators possessing certified Oracle DBA ecosystems but lacking cloud-native transformation capabilities. Long-term viability centers on acquisition multiples that reflect sustainable switching cost protection rather than license revenue erosion. Watch distributed SQL adoption rates in ASEAN payment infrastructure as the inflection signal for relational database displacement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Geographic Expansion | Localized Azure regions in Australia and Japan capture hybrid cloud procurement preference. |
| Strategic Partnership | Joint ventures with domestic Chinese operators satisfy Cyberspace Administration localization mandates. |
| Platform Integration | Vector database extensions embed AI inference capabilities that community editions cannot replicate. |
| Acquisition of Specialist Firm | CockroachDB and YugabyteDB distributed engines fill multi-zone resilience capability gaps. |
| Product Launch | Serverless provisioning compresses procurement cycles for Singaporean e-commerce platform adoption. |
Research Methodology
Operator-level perspectives from CTOs, IT procurement officers, platform engineers, and channel partners anchored the qualitative base for this study. Primary interviews across Indian system integrators, Australian healthcare providers, and Japanese automotive suppliers combined with secondary validation from SEC filings, hyperscaler capex disclosures, and regulatory authority enforcement notices. Bottom-up deployment model sizing and top-down vertical expenditure analysis provided triangulation across the Asia-Pacific database management software landscape.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs derived from historical license revenue trajectories, cloud migration velocity indices, and sovereign data mandate enforcement timelines. Machine learning integration intensity and vector database procurement velocity served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in regional cloud infrastructure investment cycles or data localization enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding open-source substitution velocity and hyperscale provider pricing discipline. Cross-checking against vendor-specific earnings disclosures and regional system integrator utilization rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Instant Messaging Software Market
Software & Services
Association Management Software Market
Software & Services
Global Continuous Integration Tools Market
Software & Services
Semiconductor Fabrication Software Market
Software & Services
United Kingdom IT Services Market
Software & Services
Network Bandwidth Management Software Market
Software & Services
Open Stack Service Market
Software & Services
Global Cloud Testing Market
Software & Services
Movie Editing Software Market
Software & Services
Global Fixed Asset Management Software Market
Software & Services
Global Restaurant Management Software Market
Software & Services
Hackathon Management Software Market
Software & Services
Global Call Tracking Software Market
Software & Services
Global Pre-Employment Testing Software Market
Software & Services
Combat Management Systems Software Market
Software & Services
Global Server Management Software Market