
 Global Optical Transport Network (OTN) Equipment Market | 2026-2036
Global Optical Transport Network (OTN) Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Optical Transport Network (OTN) Equipment Market Foresight
The EU Green Deal's digital infrastructure sustainability targets are repositioning procurement criteria for optical transport hardware across European telecom operators. Ciena Corporation leverages coherent optical technology leadership to sustain premium positioning in submarine and terrestrial long-haul segments. Nokia Corporation anchors its competitive stance through in-house silicon photonics development, while Fujitsu dominates Japan's domestic NTT network upgrades with specialized ultra-long-reach platforms.
Optical Transport Network equipment comprises wavelength-division multiplexing terminals, reconfigurable optical add-drop multiplexers, and digital cross-connect systems engineered to ITU-T G.709 protocols for signal mapping, multiplexing, and forward error correction across fiber-optic infrastructures. DWDM technology leads installed capacity due to its 96-channel C-band density, though coherent 800G pluggables in Ethernet applications represent the fastest-expanding margin pool as cloud operators bypass traditional transponder architectures. Enterprise networks remain a mature segment with replacement-driven demand, whereas data backhaul for 5G fronthaul consolidation concentrates growth in mobile infrastructure budgets.
The U.S. FCC's broadband equity programs, China's MIIT gigabit optical network mandates, and the EU's CSRD disclosure requirements collectively shape equipment certification, energy efficiency benchmarks, and supply chain documentation burdens. ITU-T standards harmonization with OIF implementation agreements determines interoperability thresholds for multi-vendor deployments. Stakeholders must monitor coherent DSP generation transitions and national fiber subsidy allocation timelines to calibrate capacity investments against technology obsolescence risk.
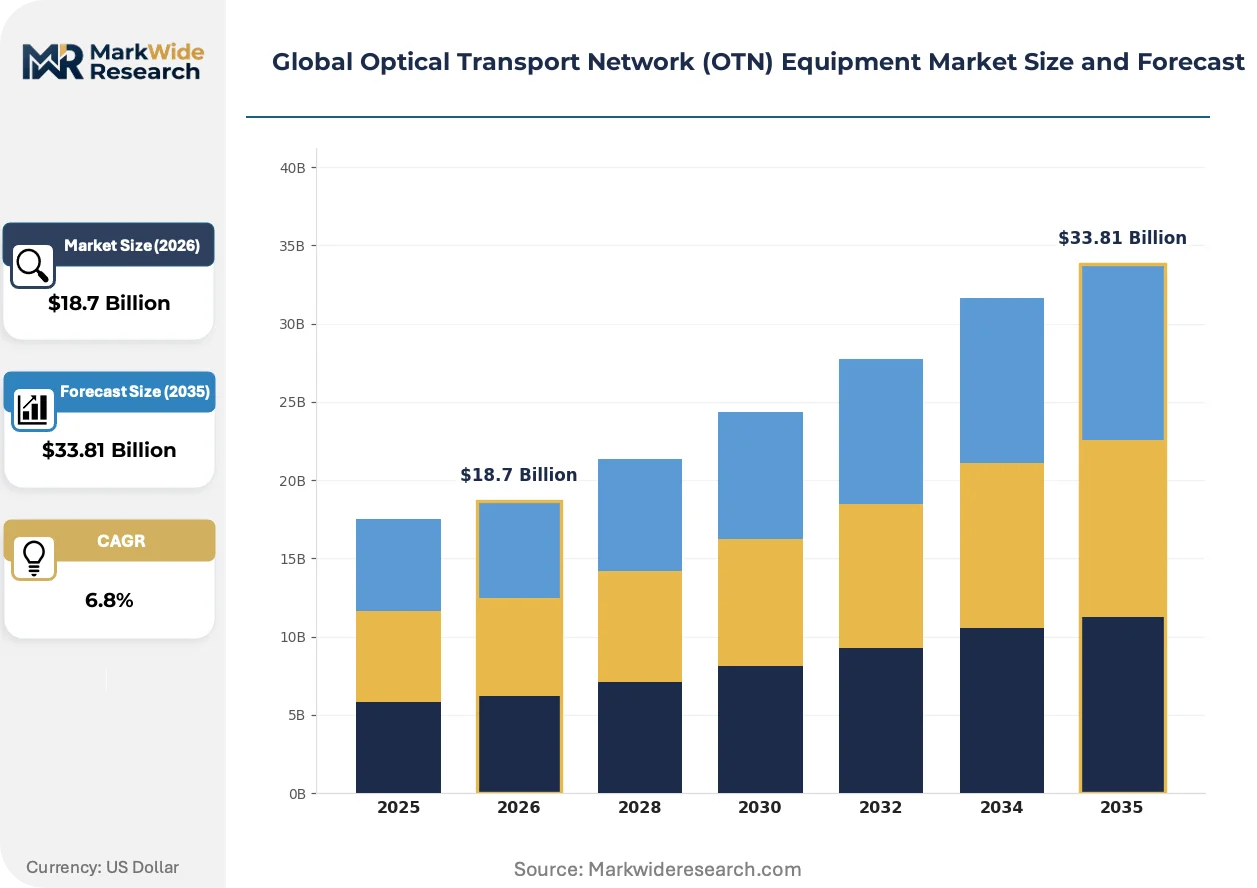
Market Dynamics
ITU-T G.709 standard evolution toward OTUCn interfaces is compressing equipment refresh cycles, forcing operators to reconcile stranded asset risk against capacity scaling imperatives.
Growth Catalysts
- China MIIT gigabit mandates:National backbone fiber programs in Beijing and Shanghai are accelerating wavelength-division multiplexing terminal deployments.
- Cloud data center interconnection:Hyperscale operators are scaling coherent 800G pluggable adoption to manage surging inter-facility traffic volumes.
- EU Green Deal sustainability targets:Energy efficiency benchmarks are repositioning procurement criteria for optical transport hardware across European telecom operators.
Market Restraints
- Indium phosphide supply concentration:Coherent DSP foundry capacity concentrates in East Asian contract manufacturers, creating input cost volatility.
- Submarine cable system complexity:Ultra-long-reach platform development requires specialized marine qualification timelines that extend deployment schedules.
- Legacy SDH infrastructure lock-in:Enterprise networks face technical limitation in protocol translation between synchronous digital hierarchy and packet-optical architectures.
Strategic Opportunities
- German national fiber subsidies:Bundesförderung für Gigabitnetze program creates underpenetrated demand for reconfigurable optical add-drop multiplexers in rural backhaul.
- Silicon photonics convergence:Integration of CMOS fabrication with optical component manufacturing is reducing transponder cost structures.
- India TRAI infrastructure sharing:Regulatory tailwind from tower fiberization mandates is opening dark fiber leasing channels for mobile infrastructure budgets.
Industry Challenges
- Coherent optical engineering talent scarcity:DSP algorithm development and forward error correction optimization require specialized skill sets concentrated in academic and vendor research labs.
- Multi-vendor interoperability certification:ITU-T harmonization with OIF implementation agreements creates compliance timeline friction for equipment qualification.
- Legacy SONET/SDH integration complexity:Digital cross-connect system replacement projects face operational friction from embedded management system dependencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Optical Transport Network (OTN) Equipment Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Multiplexer, Optical Switch, Repeater, Transponder, Regenerator, Optical Amplifier Technology: DWDM, CWDM, TDM, Ethernet, SONET, SDH Application: Cloud Data Centers, Telecommunication Service, Content Delivery, Enterprise Networks, Data Backhaul, Scientific Research End User Industry: Telecom Service Providers, Internet Exchange Points, Data Center Operators, Government Agencies, Research Institutes, Financial Institutions |
| Companies Covered | Huawei Technologies, Ciena Corporation, Nokia Corporation, ZTE Corporation, Infinera Corporation, Cisco Systems, Fujitsu, Ericsson, NEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Optical Transport Network (OTN) Equipment Market Shifts & Advancements
Coherent optical technology advancement is collapsing the distinction between submarine and terrestrial platforms, while regulatory sustainability mandates are rewriting equipment specification standards.
Coherent 800G pluggables are expanding into cloud data center interconnection applications. Hyperscale operators in the United States and China are bypassing traditional transponder architectures to reduce power consumption and rack space requirements. This technology is expanding into metro aggregation networks, compressing the addressable market for standalone wavelength-division multiplexing terminals.
EU CSRD disclosure requirements are mandating granular supply chain carbon footprint documentation for optical transport hardware. Equipment vendors must now certify energy efficiency benchmarks across manufacturing, transport, and operational phases. Submarine cable system suppliers face the steepest compliance burden due to marine survey and installation emissions accounting.
Service unbundling is fragmenting traditional equipment-plus-maintenance contracts. Mobile network operators in Germany and Japan are separating hardware procurement from software-defined network management subscriptions. This pattern is most visible in 5G fronthaul consolidation projects, where operators favor disaggregated white-box optical line terminals over integrated vendor stacks.
Global Optical Transport Network (OTN) Equipment Market Segmentation
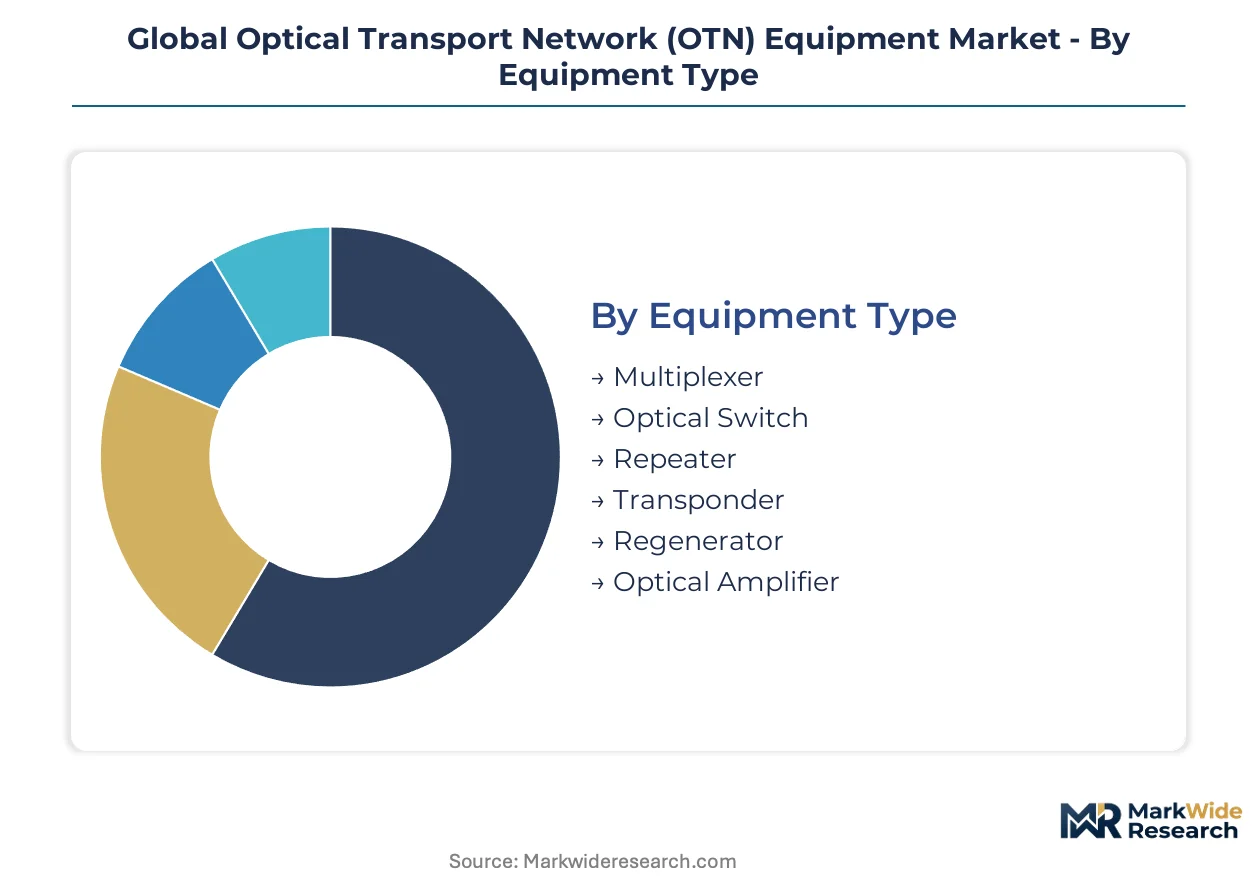
OTN equipment segmentation reveals how procurement priorities diverge across infrastructure layers. Buyers in submarine cable systems prioritize reach and reliability over cost, while cloud operators optimize for density and power efficiency.
Equipment Type:
Network architects select hardware based on functional role in the optical path, not interchangeable commodity logic.
- Multiplexer:Combines multiple optical signals onto a single fiber using wavelength-division multiplexing protocols. Cloud data center operators in the United States and China are scaling deployments to manage surging inter-facility traffic volumes. DWDM multiplexers lead volumes today; coherent pluggable variants are gaining share fastest.
- Transponder:Converts client-side electrical signals to optical line-side wavelengths with forward error correction. Telecom service providers in Germany under the Bundesförderung für Gigabitnetze program drive demand for reconfigurable variants in rural backhaul.
- Optical Switch:Routes wavelengths without optical-to-electrical conversion, preserving signal integrity.
- Repeater:Amplifies attenuated optical signals across ultra-long-haul submarine and terrestrial spans.
- Regenerator:Reshapes, retimes, and retransmits degraded signals for legacy protocol compatibility.
- Optical Amplifier:Boosts signal power across C-band and L-band using erbium-doped fiber amplification.
Transponder architectures are fragmenting as coherent pluggables displace standalone chassis.
Technology:
Technology selection locks operators into specific spectral efficiency and interoperability regimes for decade-long depreciation cycles.
- DWDM:Dense wavelength-division multiplexing packs 96 channels into C-band spectrum at 50GHz or 75GHz spacing. China MIIT gigabit mandates accelerate wavelength-division multiplexing terminal deployments in Beijing and Shanghai backbone networks.
- Ethernet:Packet-based transport natively interfaces with cloud switching fabrics without protocol translation. Hyperscale operators bypass traditional transponder architectures to reduce power consumption and rack space requirements.
- CWDM:Coarse spacing reduces cost for metro access networks with lower channel count requirements.
- TDM:Time-division multiplexing persists in legacy enterprise networks facing replacement-driven demand.
- SONET:Synchronous optical networking equipment faces stranded asset risk as operators migrate to packet-optical.
- SDH:Synchronous digital hierarchy infrastructure in Europe and Asia creates protocol translation friction for modernization projects.
DWDM dominates installed capacity; Ethernet represents the steepest expansion trajectory.
Application:
Application segmentation tracks where traffic growth translates into equipment procurement urgency versus maintenance-driven replacement.
- Cloud Data Centers:Inter-facility connectivity demands coherent 800G pluggables with minimal latency and power draw. United States and China hyperscale operators compress refresh cycles to match traffic doubling timelines.
- Data Backhaul:5G fronthaul consolidation concentrates growth in mobile infrastructure budgets across Germany and Japan. Tower fiberization mandates from India TRAI open dark fiber leasing channels.
- Telecommunication Service:National backbone fiber programs in the United States, China, and Germany sustain wavelength-division multiplexing terminal demand.
- Content Delivery:Edge caching architectures require metro aggregation density with rapid service provisioning.
- Enterprise Networks:Mature segment with replacement-driven demand and legacy SDH integration complexity.
- Scientific Research:Specialized ultra-long-reach platforms for astronomy and particle physics data pipelines.
Data backhaul commands the largest share of current procurement; cloud data center interconnection is climbing the fastest.
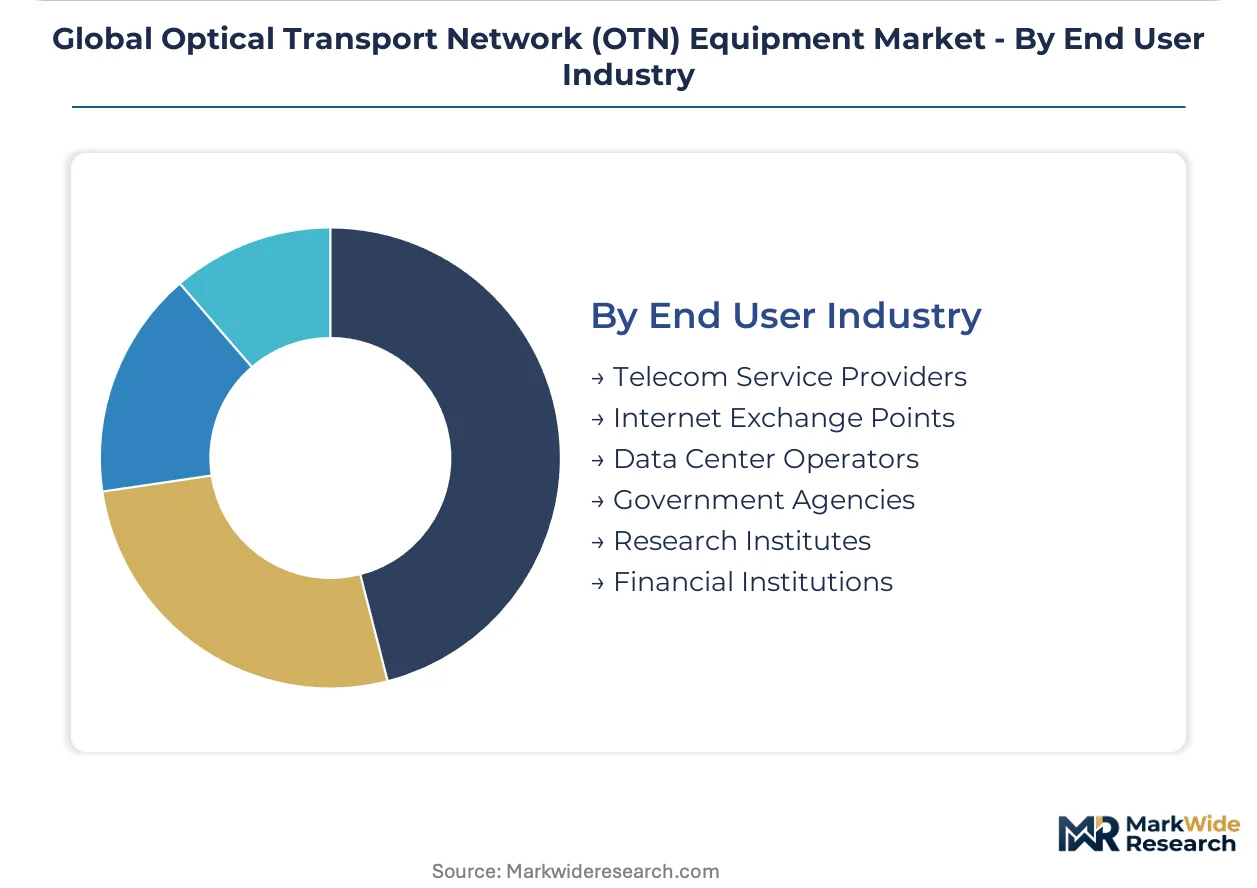
End User Industry:
End user categories reflect diverging technical specifications, contract structures, and vendor relationship models.
- Telecom Service Providers:Incumbent operators specify ITU-T G.709 compliance and multi-vendor interoperability for submarine and terrestrial long-haul. EU Green Deal sustainability targets reposition procurement criteria across European networks.
- Data Center Operators:Hyperscale buyers disaggregate hardware from software-defined network management, favoring white-box optical line terminals.
- Internet Exchange Points:Traffic aggregation hubs in Frankfurt, London, and Amsterdam demand low-latency switching fabrics.
- Government Agencies:National security networks require certified supply chains and domestic manufacturing content.
- Research Institutes:CERN and astronomy collaborations drive specialized ultra-long-reach platform development.
- Financial Institutions:Low-latency trading infrastructure prioritizes deterministic performance over cost optimization.
Telecom service providers absorb the majority of capital expenditure; data center operators are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The optical transport equipment industry traces its commercial scaling to NTT's deployment of dense wavelength-division multiplexing systems across Japan's metropolitan corridors during the 1990s, establishing the technical foundation that spread to North American and European backbone networks.
United States
Hyperscale data center operators in Ashburn, Virginia and Hillsboro, Oregon are compressing refresh cycles to match traffic doubling timelines. The FCC's broadband equity programs shape equipment certification timelines and subsidy allocation for rural fiber builds. Cloud interconnection demand concentrates in Northern Virginia's Data Center Alley, where coherent 800G pluggable adoption bypasses traditional transponder architectures.
China
National backbone fiber programs in Beijing and Shanghai accelerate wavelength-division multiplexing terminal deployments to support gigabit optical network mandates. MIIT regulations establish energy efficiency benchmarks and domestic content requirements for carrier procurement. The Yangtze River Delta cluster around Shanghai anchors manufacturing and R&D concentration for coherent DSP development.
Germany
Telecom operators under the Bundesförderung für Gigabitnetze program create underpenetrated demand for reconfigurable optical add-drop multiplexers in rural backhaul segments. EU CSRD disclosure requirements mandate granular supply chain carbon footprint documentation for optical transport hardware. The Rhine-Ruhr metropolitan region concentrates 5G fronthaul consolidation projects with disaggregated white-box procurement preferences.
Japan
NTT network upgrades drive specialized ultra-long-reach platform demand for domestic submarine and terrestrial long-haul segments. METI standards harmonization with ITU-T G.709 protocols determines interoperability thresholds for multi-vendor deployments. The Kanto region around Tokyo maintains R&D concentration in coherent optical engineering and forward error correction optimization.
India
Tower fiberization mandates from TRAI open dark fiber leasing channels for mobile infrastructure budgets in data backhaul applications. Regulatory infrastructure sharing requirements reduce capital intensity for 5G fronthaul deployment. The Delhi-NCR corridor concentrates procurement activity as carriers consolidate optical transport layers ahead of spectrum auctions.
Global Optical Transport Network (OTN) Equipment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and vertical integration depth. The vendor base organizes into three tiers: coherent DSP specialists commanding premium positioning, integrated systems houses with captive silicon photonics capabilities, and white-box assemblers competing on cost. Consolidation pressure concentrates at the mid-tier as cloud disaggregation erodes traditional equipment-plus-software bundling. Dominant competitive moves include strategic partnerships for coherent component supply and geographic expansion into national fiber subsidy programs.
Within the integrated systems tier, Huawei Technologies and ZTE Corporation represent scale-driven Asian challengers with end-to-end portfolio breadth, while Ciena Corporation exemplifies coherent optical technology leadership through premium positioning in submarine and terrestrial long-haul segments. Nokia Corporation anchors European competitive presence through in-house silicon photonics development, occupying a position between specialized DSP vendors and diversified telecom equipment houses.
| Leading Market Players |
|---|
| Huawei Technologies |
| Ciena Corporation |
| Nokia Corporation |
| ZTE Corporation |
| Infinera Corporation |
| Cisco Systems |
| Fujitsu |
| Ericsson |
| NEC Corporation |
| Others |
Supply & Pricing Matrix
Coherent DSP algorithm specialists concentrated in Japan's Kanto region and California's Bay Area create labor-cost differentials that widen pricing-tier spreads between premium integrated systems and commodity white-box alternatives. This geographic concentration of optical engineering talent forces equipment vendors to absorb R&D premiums or offshore development to lower-cost design centers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates submarine-qualified platforms from metro-optimized systems and disaggregated white-box alternatives. Price differentiation hinges on ITU-T G.709 compliance certification and coherent DSP generation—latest-generation 800G-capable modules command substantial premiums over 400G legacy stock. Cost compression in the standard tier is intensifying because cloud operators are bypassing traditional transponder architectures for pluggable alternatives. Data center operators exhibit the highest price sensitivity, prioritizing power-per-bit metrics over brand premiums, while submarine cable consortiums remain least sensitive due to decade-long depreciation cycles and reliability imperatives.
Supply Chain Analysis
Refurbishment flows for legacy wavelength-division multiplexing terminals create secondary market channels that undercut new equipment pricing in enterprise replacement cycles. Manufacturing concentration rests on Taiwan and South Korea for coherent DSP foundry capacity, with Japan and the United States anchoring specialized optical component fabrication. Indium phosphide substrate supply and erbium-doped fiber amplification modules constitute critical input dependencies. Single-source vulnerability in East Asian contract manufacturing creates exposure to geopolitical friction and export control expansion. Distribution runs through direct vendor relationships with tier-1 telecom operators, supplemented by systems integrators serving mid-market enterprise and government segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through silicon photonics convergence, which collapses transponder cost structures while preserving premium positioning for submarine and ultra-long-reach platforms.
For Market Incumbents: Cement coherent optical technology leadership through captive DSP development and ITU-T standards participation. Threats from disaggregated white-box alternatives in cloud data center interconnection demand defensive moves into software-defined network management subscriptions. Prioritize backward integration into indium phosphide foundry partnerships to secure input cost stability against East Asian supply concentration.
For New Entrants and Emerging Players: Tower companies and rural broadband cooperatives represent the most accessible channel partners for bypassing incumbent vendor relationships. White-space targets concentrate in Germany's Bundesförderung für Gigabitnetze rural backhaul deployments and India's TRAI-mandated tower fiberization programs. Position around open optical line terminal architectures with subscription-based network management to match mobile operator procurement preferences.
For Investors and Strategic Acquirers: Hyperscale cloud operators are the most active acquirer in this space, seeking vertical control over inter-facility connectivity hardware. Long-term viability favors coherent DSP specialists with patent portfolios in forward error correction and silicon photonics integration. Watch for inflection signals in national fiber subsidy allocation timelines and ITU-T G.709 evolution milestones toward OTUCn interface standardization.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Integration | CMOS fabrication convergence reduces transponder costs while preserving submarine platform premiums. |
| Coherent DSP Verticalization | In-house algorithm development secures margin control against East Asian foundry concentration. |
| Open Line Terminal Disaggregation | Hardware-software separation matches cloud operator procurement preferences in metro aggregation. |
| Submarine System Qualification | Marine-grade reliability certification creates decade-long replacement cycle lock-in with cable consortiums. |
| Sustainability Certification Program | EU CSRD compliance documentation becomes mandatory procurement filter across European telecom operators. |
Research Methodology
Direct dialogue with optical network architects at tier-1 telecom operators, procurement leads at hyperscale data center operators, coherent DSP engineering directors, and submarine cable system project managers grounded qualitative findings in operational reality. Secondary validation drew from ITU-T standards documentation, OIF implementation agreements, FCC broadband equity program filings, MIIT gigabit network mandates, and EU CSRD regulatory texts. Bottom-up equipment deployment tracking across national fiber programs was triangulated against top-down vendor revenue segmentation.
Segment-level projections across equipment type, technology protocol, application layer, and end-user industry were generated through the modeling period. The analytical framework incorporated coherent DSP generation transitions, national subsidy allocation trajectories, and cloud operator capex cycle phasing as industry-specific forecast inputs. CAGRs were derived from equipment refresh cycle compression rates and traffic growth elasticity assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ITU-T standards evolution timing and indium phosphide supply chain reconfiguration. Practitioners should monitor coherent 800G pluggable adoption rates in cloud interconnection and national fiber subsidy disbursement schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
5G Network Infrastructure Market
Telecommunications Infrastructure
Europe 5G Infrastructure Market
Telecommunications Infrastructure
Global Telecom System Integration Market
Telecommunications Infrastructure
UAE Telecom Towers Market
Telecommunications Infrastructure
Spain Telecom Towers Market
Telecommunications Infrastructure
Nepal Telecom Market
Telecommunications Infrastructure
Asia Pacific Voice Over LTE Market
Telecommunications Infrastructure
Wireless Infrastructure Market
Telecommunications Infrastructure
Peru Telecom Tower Market
Telecommunications Infrastructure
Fixed Telephony Service Market
Telecommunications Infrastructure
Global Telecom Towers Market
Telecommunications Infrastructure
Germany Telecom Towers Market
Telecommunications Infrastructure
Fixed-Line Communications Market
Telecommunications Infrastructure
5G Infrastructure Market
Telecommunications Infrastructure
OTN Equipment Market
Telecommunications Infrastructure
Vietnam Telecom Towers Market