
 Automotive Digital Retailing Software Market | 2026-2036
Automotive Digital Retailing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Digital Retailing Software Market Insights
The capital-intensity divergence between legacy dealer system providers and lean cloud-native entrants is unwinding competitive assumptions about scale requirements. CDK Global leverages decades of dealer management system integration to sustain entrenched relationships with large dealership groups. Cox Automotive competes through vertical control over listing, financing, and logistics workflows. AutoFi differentiates by specializing in embedded lending APIs that bridge digital retailing with captive finance arms.
Automotive digital retailing software encompasses cloud-based and on-premise platforms that enable vehicle discovery, pricing, financing, and contract execution through unified digital interfaces, typically integrating with DMS, CRM, and lender systems via REST APIs or proprietary middleware. E-commerce platform deployments now lead product-type adoption as dealers seek end-to-end transaction capability rather than lead-generation tools. Cloud-based technology architectures are expanding fastest among deployment models, though on-premise solutions retain strongholds at enterprise dealer groups with legacy IT governance. Dealerships remain the dominant end-user category, while OEM-direct digital retailing programs are reshaping integration-level requirements toward API-first custom solutions.
The US FTC's revised advertising substantiation standards and state-level DMV digital transaction rules are elevating compliance costs for platform providers. NHTSA data privacy guidelines for connected vehicle sales intersect with digital retailing workflows, forcing tighter consent management architectures. OEMs and dealer groups must monitor how regulatory fragmentation across California, Texas, and Florida affects cross-state digital transaction validity and data residency obligations.
Market Dynamics
Consolidation of dealer technology stacks across multi-state operations is forcing platform providers to prioritize API-first architectures that bridge legacy DMS infrastructure with cloud-native transaction workflows.
Growth Catalysts
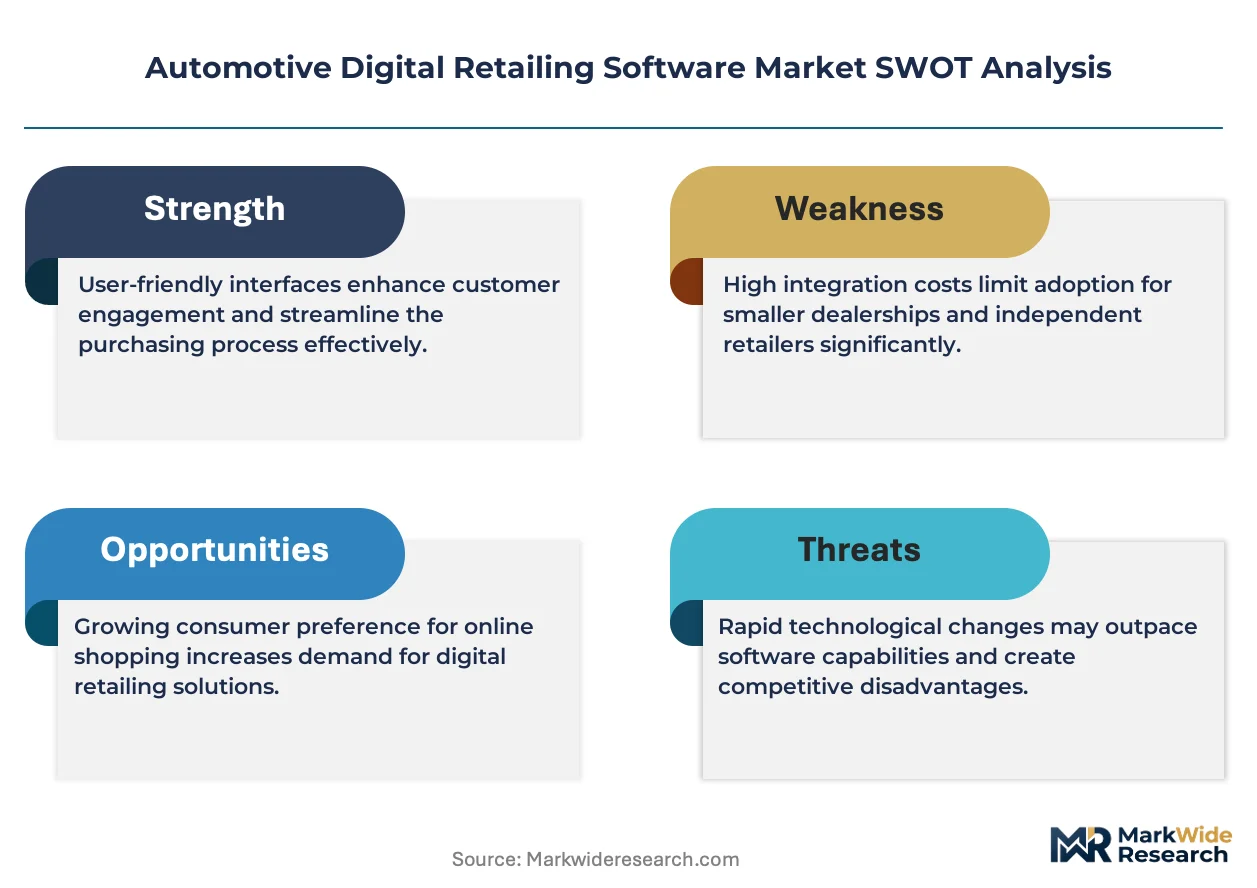
- FTC Advertising Substantiation Standards:The US FTC's revised rules mandate transparent pricing disclosures in digital auto advertising, compelling dealers to adopt compliant software platforms that automate disclosure workflows and audit trails.
- E-commerce Platform Deployments:Franchise dealerships are replacing lead-generation tools with end-to-end transaction platforms that execute full vehicle purchases online, including digital contract execution and remote notarization.
- Captive Finance Integration:OEM captive finance arms are demanding embedded lending APIs that pre-qualify buyers and structure real-time loan terms within digital retailing interfaces.
Market Restraints
- Legacy IT Governance:Enterprise dealer groups with entrenched on-premise DMS infrastructure face multi-year migration timelines and sunk-cost resistance that slows cloud adoption.
- State Regulatory Fragmentation:Divergent digital transaction validity rules across California, Texas, and Florida create compliance complexity for platform providers serving multi-state dealer groups.
- Data Residency Obligations:NHTSA data privacy guidelines for connected vehicle sales impose consent management architectures that increase platform development costs.
Strategic Opportunities
- OEM-Direct Digital Retailing:Manufacturer-owned digital sales channels are creating demand for custom API-first solutions that bypass traditional dealer management systems entirely.
- Remote Online Notarization:State-level DMV digital transaction rule expansions are enabling fully remote vehicle purchases without physical document exchange.
- Embedded Insurance Workflows:Convergence of digital retailing platforms with real-time insurance quoting APIs creates new revenue streams at the point of vehicle configuration.
Industry Challenges
- Middleware Integration Complexity:Bridging REST APIs with proprietary legacy DMS protocols requires specialized engineering talent that commands premium compensation in tight labor markets.
- Cross-State Compliance Certification:Platform providers must maintain separate audit documentation for each state's evolving digital motor vehicle sales regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Digital Retailing Software Market |
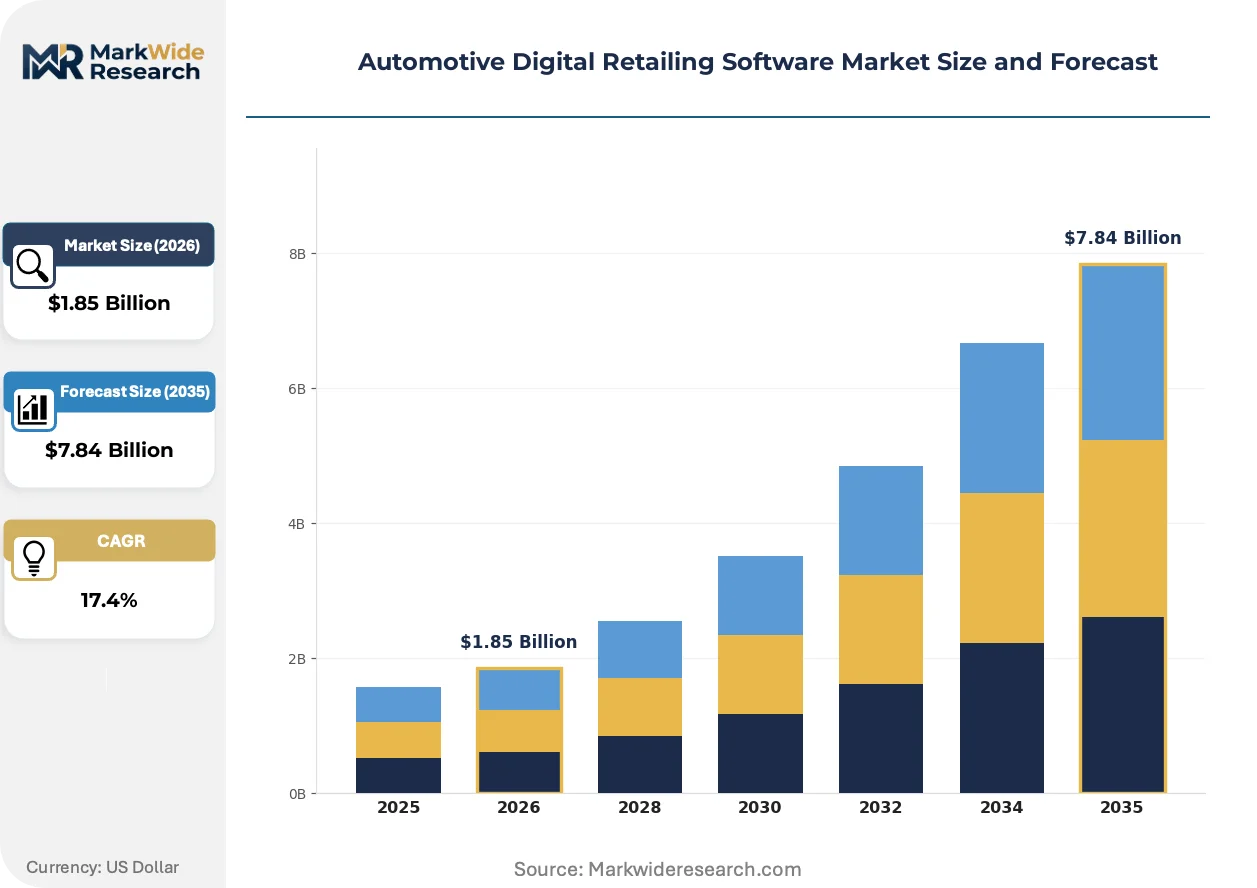
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CRM Software, Inventory Management, E-commerce Platform, Dealership Management End User: Dealerships, OEMs, Financing Institutions, Aftermarket Providers Technology: Cloud-Based, On-Premise, Mobile Applications, AI-Powered Solutions Integration Level: Third-Party Integration, API-Based, Custom Solutions, Out-of-the-Box |
| Companies Covered | Cox Automotive, CDK Global, Dabadu, Upstart, Gubagoo, AutoFi, CarNow, Dealer Inspire, OTIONE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Digital Retailing Software Market Trends and Innovations
Platform architecture is fragmenting as modular API ecosystems replace monolithic dealer systems, enabling specialized vendors to capture value at discrete workflow stages.
Headless commerce engines are decomposing the traditional digital retailing stack into discrete microservices for inventory, pricing, credit, and contracting. Mid-size dealer groups are adopting these modular architectures fastest, stitching together best-of-breed components rather than accepting bundled suites. This decomposition is compressing switching costs and eroding vendor lock-in that previously protected entrenched platform providers.
The US NHTSA and FTC are tightening intersecting mandates on consumer data protection and advertising transparency for connected vehicle sales. Platform providers must now embed granular consent management and automated disclosure verification into transaction workflows. Dealer groups operating across multiple states face escalating compliance engineering costs as regulatory fragmentation deepens.
Buyer expectations for seamless omnichannel experiences are collapsing the distinction between online research and in-store purchase. Franchise dealerships are unbundling their sales processes, allowing customers to initiate transactions digitally and complete them at physical locations without re-entering data. This hybrid model is most advanced in metropolitan markets where dealer groups have invested in unified customer data platforms.
Automotive Digital Retailing Software Market Segmentation
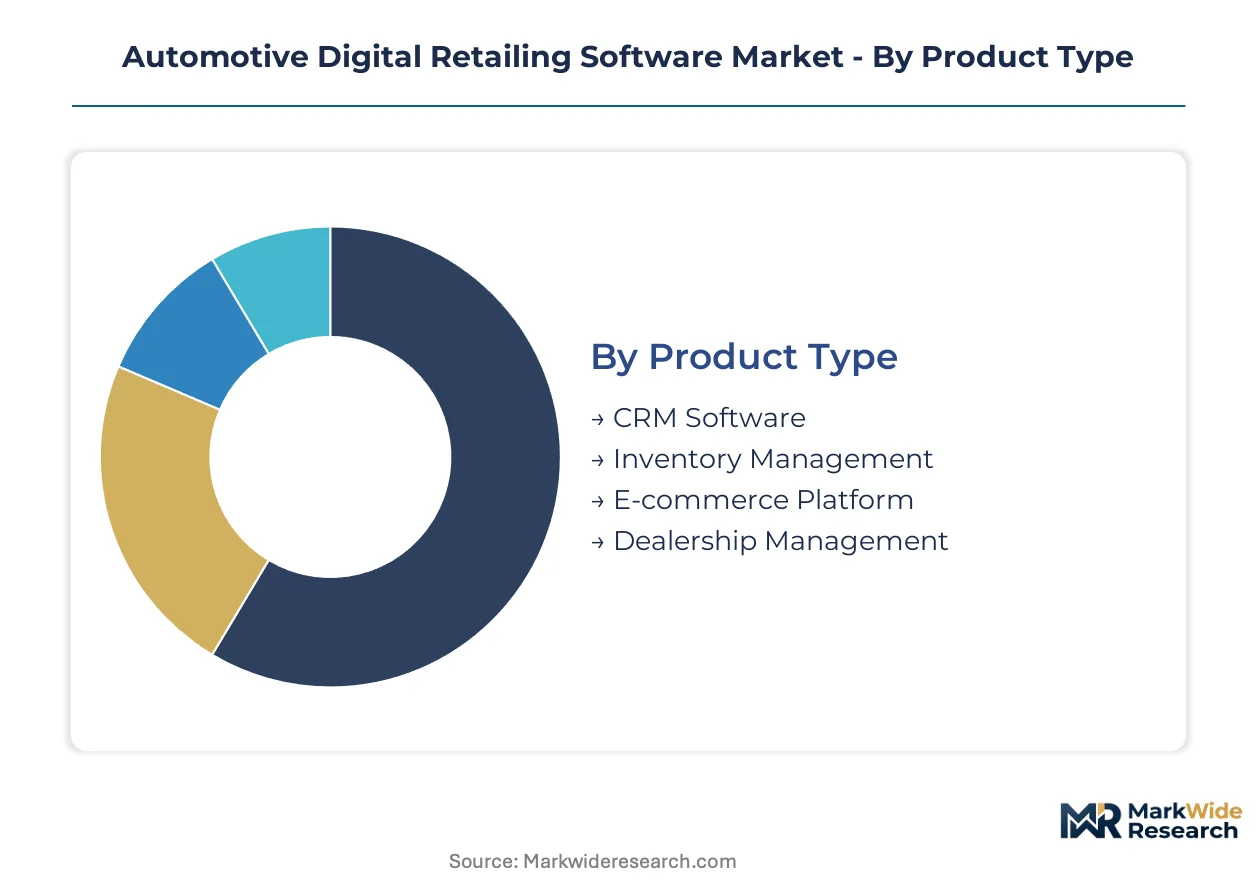
Channel configuration in automotive digital retailing software determines how value flows between platform providers and end-users. Each segment category reflects distinct technical requirements, deployment constraints, and buyer sophistication levels that shape vendor go-to-market strategies.
Product Type:
CRM Software and E-commerce Platform deployments flow primarily through dealer group technology committees, while Inventory Management and Dealership Management systems route through legacy DMS upgrade cycles.
- E-commerce Platform:End-to-end transaction engines enable vehicle discovery, pricing, financing, and digital contract execution through unified interfaces. Demand concentrates among franchise dealership groups in the United States seeking to replace lead-generation tools with full purchase completion capability, driven by FTC advertising substantiation mandates requiring transparent pricing disclosures.
- CRM Software:Customer relationship management systems track prospect interactions, automate follow-up workflows, and integrate with DMS for sales pipeline visibility. Adoption clusters at mid-size dealer groups consolidating multi-state operations, constrained by middleware complexity when bridging REST APIs with proprietary legacy protocols.
- Inventory Management:Real-time vehicle availability, pricing optimization, and lot management tools.
- Dealership Management:Comprehensive operational platforms spanning sales, service, parts, and accounting modules.
Dealership Management dominates installed base. E-commerce Platform is where expansion concentrates.
End User:
Dealerships and OEMs operate on contrasting procurement timelines, with financing institutions and aftermarket providers occupying intermediary positions in the value chain.
- Dealerships:Franchise and independent vehicle retailers implementing digital retailing workflows across showrooms and online channels. United States dealer groups drive volume, motivated by captive finance integration demands from OEM lending arms requiring embedded pre-qualification APIs.
- OEMs:Manufacturer-direct digital sales programs bypassing traditional dealer networks for vehicle configuration and purchase. Expansion centers on API-first custom solutions in California and Texas markets, shaped by state-level DMV digital transaction rule variations.
- Financing Institutions:Banks, credit unions, and captive lenders embedding loan origination into retail interfaces.
- Aftermarket Providers:Extended warranty, insurance, and service contract vendors integrating with retail platforms.
Dealerships anchor current revenue. OEMs represent the steepest expansion trajectory.
Technology:
Cloud-Based architectures and On-Premise systems serve different governance profiles, while Mobile Applications and AI-Powered Solutions target specific workflow enhancement opportunities.
- Cloud-Based:Scalable, subscription-delivered platforms with continuous feature updates and reduced IT overhead. Growth concentrates among mid-size dealer groups in Florida and Texas, accelerated by remote online notarization enablement for fully digital vehicle purchases.
- On-Premise:Locally hosted systems with direct data control and customized security configurations. Retention is strongest at enterprise dealer groups with legacy IT governance and multi-year sunk-cost investments in existing infrastructure.
- Mobile Applications:Native and progressive web apps for sales staff and customer self-service.
- AI-Powered Solutions:Machine learning models for credit decisioning, pricing optimization, and conversational interfaces.
On-Premise retains enterprise strongholds. Cloud-Based is gaining share fastest.
Integration Level:
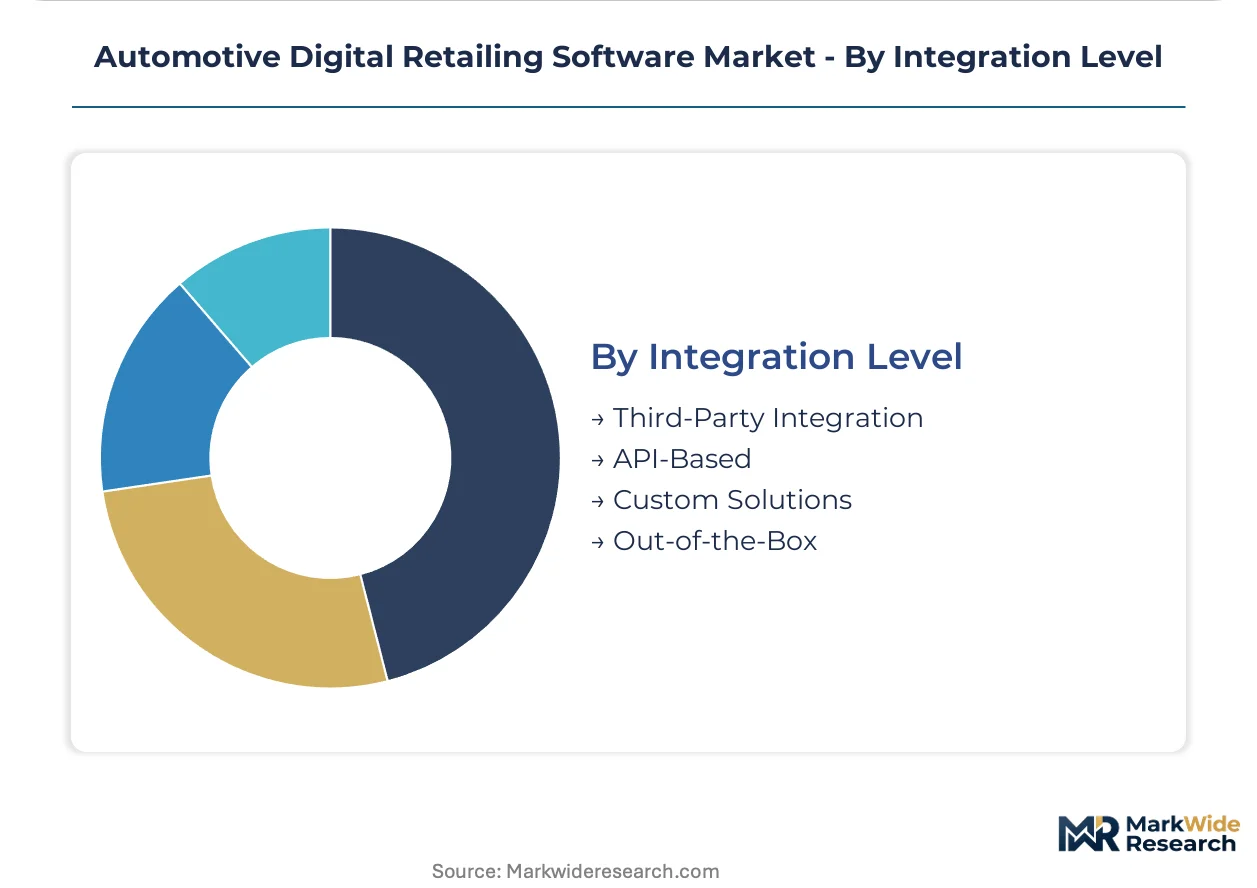
Third-Party Integration and API-Based approaches reflect architectural philosophy divides, while Custom Solutions and Out-of-the-Box deployments serve different organizational capabilities.
- API-Based:RESTful and proprietary interface architectures enabling modular, best-of-breed system composition. Demand clusters at mid-size dealer groups adopting headless commerce engines, driven by decomposition of monolithic stacks into discrete microservices for inventory, pricing, and contracting.
- Custom Solutions:Bespoke development for OEM-direct programs and large dealer group specific requirements. Concentration is highest among manufacturer-owned digital retailing initiatives requiring bypass of traditional DMS infrastructure entirely.
- Third-Party Integration:Pre-built connectors to established DMS, CRM, and lender platforms.
- Out-of-the-Box:Standardized configurations with minimal customization for rapid deployment.
Third-Party Integration dominates current deployments. API-Based is where vendor R&D investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes automotive digital retailing software through end-to-end transaction platforms, while Germany and Japan emphasize DMS-integrated compliance modules, and China pursues OEM-direct API architectures that bypass traditional dealer infrastructure entirely.
United States
Franchise dealer groups in Texas and Florida are consolidating multi-state technology stacks around cloud-native platforms with remote online notarization. The FTC's revised advertising substantiation standards mandate automated pricing disclosure workflows. Metropolitan clusters in California, particularly Los Angeles and San Francisco, are advancing hybrid omnichannel models that unify digital initiation with physical completion.
Germany
Automotive groups in Bavaria and Baden-Württemberg are retrofitting legacy DMS infrastructure with API middleware for captive finance integration. The EU AI Act intersects with digital retailing through credit decisioning transparency requirements. Stuttgart and Munich anchor development concentration for embedded lending architectures serving premium OEM programs.
China
Domestic EV manufacturers in Shanghai and Shenzhen are deploying manufacturer-direct sales platforms that circumvent traditional dealer networks. MIIT data localization rules impose consent management architectures for connected vehicle transactions. The Yangtze River Delta region, centered on Shanghai, concentrates R&D investment for headless commerce microservices.
Japan
Dealer associations in Tokyo and Osaka are resisting full digital transaction adoption in favor of showroom-integrated consultation tools. METI guidelines on consumer finance disclosure shape platform compliance engineering. The Nagoya industrial corridor, hosting Toyota's captive operations, pilots embedded insurance workflow integration at point of vehicle configuration.
United Kingdom
Independent dealer groups in London and the Southeast are adopting modular API-first architectures faster than franchise networks. FCA consumer duty rules elevate audit trail requirements for digital finance origination. The Midlands manufacturing belt, including Birmingham, is testing OEM-direct pilot programs that challenge traditional dealer franchise laws.
Automotive Digital Retailing Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrated among legacy platform providers possessing entrenched DMS relationships. The middle tier fragments across embedded lending specialists, headless commerce engine developers, and regional SaaS vendors. Two strategic archetypes dominate: vertically integrated workflow controllers and modular API-first disrupters. Competitive moves center on middleware acquisition to bridge legacy protocols and strategic partnerships with captive finance arms for pre-qualification integration.
Within the legacy integration tier, CDK Global and Cox Automotive occupy positions sustained by decades of dealer management system entrenchment. AutoFi exemplifies the embedded lending specialist archetype, occupying a position between digital retailing interfaces and captive finance API requirements. These three companies represent the competitive spectrum from bundled suite providers to discrete workflow specialists.
| Leading Market Players |
|---|
| Cox Automotive |
| CDK Global |
| Dabadu |
| Upstart |
| Gubagoo |
| AutoFi |
| CarNow |
| Dealer Inspire |
| OTIONE |
| Others |
Pricing and Supply Chain Analysis
Embedded lending API substitution for traditional point-of-sale finance workflows is redrawing supplier geography toward fintech development clusters while compressing implementation pricing for mid-size dealer groups. This displacement simultaneously elevates cloud-native platform valuations and erodes on-premise licensing premiums across the United States, Germany, and China.
Pricing Analysis
After-sales service contract bundling drives lifetime value capture for platform providers, with subscription-SaaS tiered pricing dominating deployment economics. Price differentiation rests on integration depth with captive finance arms and NHTSA consent management certification tiers. Cost compression in standard-tier implementations is intensifying because mid-size dealer groups are stitching together headless commerce microservices rather than accepting bundled suites. Independent dealer groups in the United Kingdom exhibit highest price sensitivity, while enterprise dealer groups with legacy DMS entrenchment demonstrate lowest sensitivity due to switching cost barriers.
Supply Chain Analysis
Middleware engineering talent chokepoints in Austin, Berlin, and Bangalore constrain platform development velocity for API-first architectures. Software development draws from cloud infrastructure providers, specialized fintech engineering pools, and legacy DMS protocol specialists. Single-source vulnerability concentrates in REST API gateway providers serving multi-state dealer compliance requirements. Distribution runs through direct enterprise sales teams for large dealer groups and value-added resellers for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive digital retailing software fragmentation creates entry niches as OEM-direct digital sales programs bypass traditional dealer management systems entirely. Dealer technology stack decomposition enables specialist capture at discrete workflow stages.
For Market Incumbents: Secure captive finance API exclusivity through embedded pre-qualification partnerships with OEM lending arms. Deepen backward integration into remote online notarization infrastructure to defend against modular disrupters. CDK Global and Cox Automotive must accelerate middleware acquisition to bridge proprietary legacy DMS protocols with cloud-native transaction workflows before headless commerce engines erode switching costs.
For New Entrants and Emerging Players: Differentiate on AI-powered credit decisioning transparency compliant with EU AI Act requirements for European market entry. Target OEM-direct digital retailing programs in Shanghai and Shenzhen requiring API-first custom solutions that circumvent traditional dealer infrastructure. Lead with insurance workflow integration at point of vehicle configuration, exploiting convergence gaps that bundled suite providers have not addressed.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed embedded lending specialists possessing captive finance relationships but lacking omnichannel scale. Five-to-ten year viability favors platforms with demonstrated cross-state compliance certification maintenance across California, Texas, and Florida regulatory variations. Monitor FTC advertising substantiation enforcement intensity as inflection indicator for compliance-engineering spend acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Middleware bridges REST APIs with CDK Global and Cox Automotive legacy DMS protocols. |
| Strategic Partnership | Embedded lending APIs connect AutoFi architectures with Toyota Financial Services workflows. |
| Acquisition of Specialist Firm | Remote online notarization capabilities enable fully digital vehicle purchases without physical exchange. |
| Geographic Expansion | California DMV digital transaction rules require separate compliance engineering from Texas implementations. |
| Product Launch | Headless commerce microservices decompose monolithic stacks into discrete inventory and contracting modules. |
Research Methodology
A standing panel of dealership operations directors, captive finance technology leads, DMS integration specialists, and FTC compliance officers provided ongoing calibration against market developments. Primary interviews with platform engineering executives and secondary validation through SEC 10-K filings, NHTSA regulatory dockets, and state DMV rulemaking records anchored demand-side assessment. Bottom-up dealer technology spend analysis and top-down software market sizing triangulated value estimates.
Consistency checks validated volume and value outputs against IHS Markit vehicle registration data and hyperscaler automotive vertical revenue disclosures across the analysis window. Segmentation modeling incorporated product type, deployment architecture, integration complexity, and regional regulatory cluster dimensions. CAGRs derived from logistic adoption curve fitting against dealer group technology refresh cycles and OEM-direct program rollout timelines.
Material uncertainties — FTC enforcement intensity variations, state-level DMV rule fragmentation, and captive finance API standardization delays — sit outside the modeled envelope. Forecasts reflect assumptions about middleware engineering labor availability and cloud infrastructure cost trajectories. Practitioners should keep alternative scenarios live as NHTSA connected vehicle privacy guidance and EU AI Act credit transparency requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Payroll and HR Software Market
Software & Services
Europe Business Software Market
Software & Services
Global Headless CMS Software Market
Software & Services
Global Backup Restore Software Market
Software & Services
Global Customer Service Software Market
Software & Services
Programmable Automation Controller Software Market
Software & Services
Application Platform As a Service Market
Software & Services
Performance Management Software Market
Software & Services
Global Referral Software Market
Software & Services
Cloud Business Process Management (BPM) Software Market
Software & Services
Design Collaboration Software Market
Software & Services
App Development Software Market
Software & Services
Software License Management (SLM) Market
Software & Services
Model Based Testing Tools Market
Software & Services
HVAC Solution Software Market
Software & Services
Content Creation Software Market