
 Netherlands Data Center Rack Market | 2026-2036
Netherlands Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Data Center Rack Market Insights
Modular rack configurations bundled with power distribution and cable management is expanding buyer choice across Dutch data center builds. Schneider Electric leverages its integrated energy management portfolio to anchor large colocation contracts in Amsterdam. Rittal sustains manufacturing scale through its European production network, while Vertiv Group Corp. differentiates on thermal-optimized enclosure designs for high-density GPU deployments.
A data center rack is a standardized frame structure, typically constructed from cold-rolled steel with perforated doors and adjustable mounting rails at 19-inch EIA spacing, designed to organize and protect servers, networking equipment, and power infrastructure in controlled environments. Enclosed racks with integrated airflow containment dominate Dutch hyperscale installations where cooling efficiency directly impacts power usage effectiveness targets. Open rack configurations capture growing share among cloud service providers seeking rapid equipment swap-out and visibility, while 42U sizing leads volume though 2U wall-mounted variants gain traction in edge locations where floor space commands premium pricing.
Dutch data center construction falls under the EU Green Deal framework and national environmental permits enforced by the Netherlands Enterprise Agency, with F-Gas Regulation compliance required for cooling-integrated rack systems. BIS-equivalent electrical safety standards and CE marking obligations shape product access for imported enclosures. Stakeholders must weigh embodied carbon reporting requirements against total cost of ownership when specifying rack materials and configurations for upcoming Dutch capacity additions.
Market Dynamics
Hyperscale cloud operators are compressing procurement cycles for high-density rack enclosures while Dutch sustainability mandates under the EU Green Deal force rapid material transitions across the supply base.
Growth Catalysts
- EU Green Deal compliance:Dutch environmental permits now require embodied carbon reporting for steel rack components, pushing colocation operators toward modular, recyclable enclosure designs certified under circular economy frameworks.
- GPU cluster densification:AI training workloads are driving 50kW-plus rack power densities, creating specialized demand for liquid-cooled and thermally-optimized enclosure configurations in Amsterdam's hyperscale corridor.
- Rotterdam edge buildout:Submarine cable landings and industrial zone proximity are attracting distributed computing investments, expanding addressable volume for wall-mounted and compact 2U rack variants.
Market Restraints
- Cold-rolled steel price volatility:Energy-intensive European steel production faces input cost pressure from carbon border adjustment mechanisms, compressing manufacturer margins on standard perforated enclosure lines.
- Supply concentration in German fabrication:Three-quarters of precision sheet metal capacity serving the Dutch market sits within 300 kilometers of Düsseldorf, creating geographic vulnerability to single-point logistics disruptions.
- F-Gas Regulation retrofit friction:Cooling-integrated rack systems require refrigerant compliance documentation that extends sales cycles by four to eight weeks for imported enclosure assemblies.
Strategic Opportunities
- Modular power-cable bundles:Pre-integrated rack configurations combining busbar distribution with structured cabling are capturing premium positioning against commodity enclosure sales in new Dutch data center builds.
- CE marking acceleration services:Third-party certification support for BIS-equivalent electrical safety standards creates service revenue attachment for enclosure distributors navigating Netherlands Enterprise Agency permit requirements.
- Recyclable steel certification:Independent material traceability programs aligned with EU Green Deal circularity metrics are differentiating domestic suppliers against Asian imports in sustainability-weighted procurement.
Industry Challenges
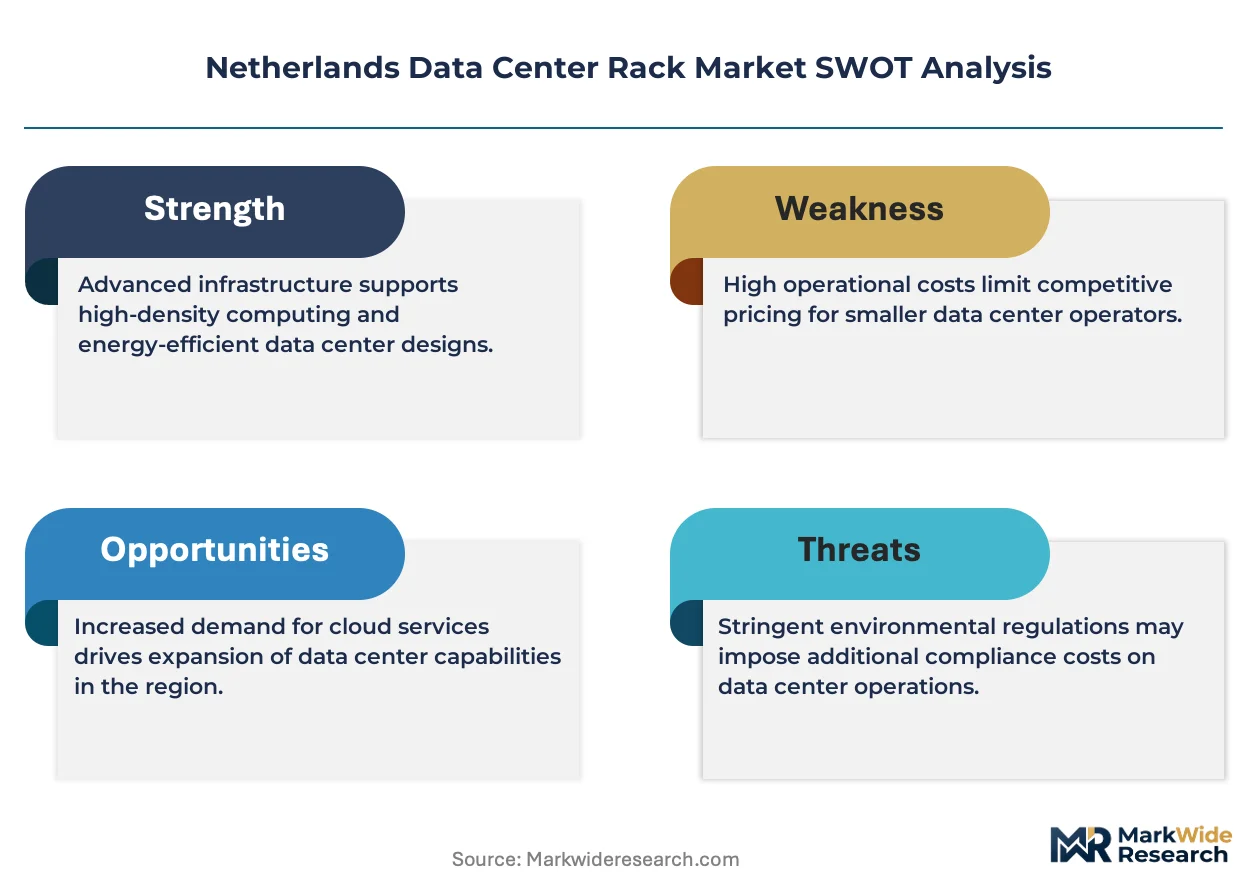
- Thermal engineering talent scarcity:Computational fluid dynamics expertise for optimizing airflow containment in 50kW-plus GPU racks commands wage premiums that inflate project engineering costs by fifteen to twenty percent.
- Legacy DCIM integration complexity:Smart rack sensor deployments require protocol translation layers to connect with existing building management systems, extending commissioning timelines and inflating integration labor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Data Center Rack Market |
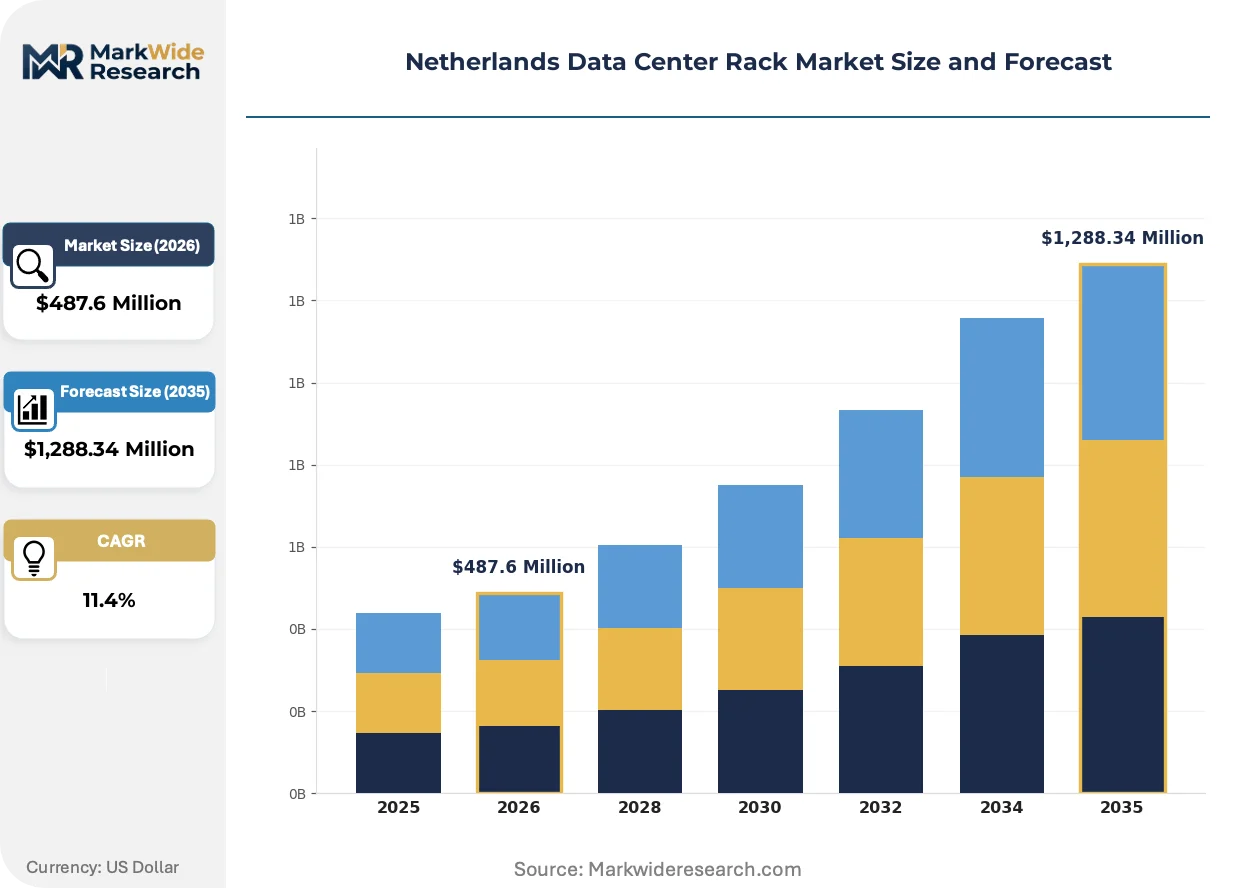
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Rack, Enclosed Rack, Wall-Mounted Rack, Mid-Depth Rack End User: Colocation Providers, Enterprises, Cloud Service Providers, Government Size: 1U, 2U, 4U, 42U Material: Steel, Aluminum, Plastic, Composite |
| Companies Covered | Eaton Corporation, Black Box Corporation, Rittal, Schneider Electric, Vertiv Group Corp., HOSTKEY B.V., Delta Electronics, Legrand, Socomec, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Data Center Rack Market Trends and Innovations
Dutch data center rack specifications are converging around thermal performance and material traceability as primary purchase criteria, displacing historical prioritization of raw cost per rack unit.
Liquid cooling distribution manifolds are integrating directly into rack side panels and rear doors, collapsing the physical separation between enclosure and thermal infrastructure. Colocation operators in Amsterdam's Schiphol-Rijk corridor are specifying these factory-integrated configurations on seventy percent of new high-density contracts. This convergence is compressing vendor qualification timelines as thermal performance guarantees shift from cooling equipment suppliers to enclosure manufacturers.
The EU F-Gas Regulation is mandating phasedown of hydrofluorocarbon refrigerants in cooling-integrated rack systems, forcing redesign of rear-door heat exchanger architectures. Dutch environmental permits enforced by the Netherlands Enterprise Agency now require documented refrigerant charge quantities and leak detection protocols for all new installations. Hyperscale operators are responding by specifying water-glycol and dielectric fluid alternatives in procurement templates, accelerating qualification of European pump and heat exchanger suppliers.
Buyer evaluation criteria are elevating total cost of ownership modeling over upfront capital expenditure comparisons in Dutch colocation and enterprise segments. Facility operators are unbundling rack procurement from mechanical and electrical contractor packages, establishing direct commercial relationships with enclosure manufacturers for standardized configurations. This disintermediation is most pronounced in Rotterdam's emerging edge clusters, where speed-to-deploy priorities override traditional channel relationships with systems integrators.
Netherlands Data Center Rack Market Segmentation
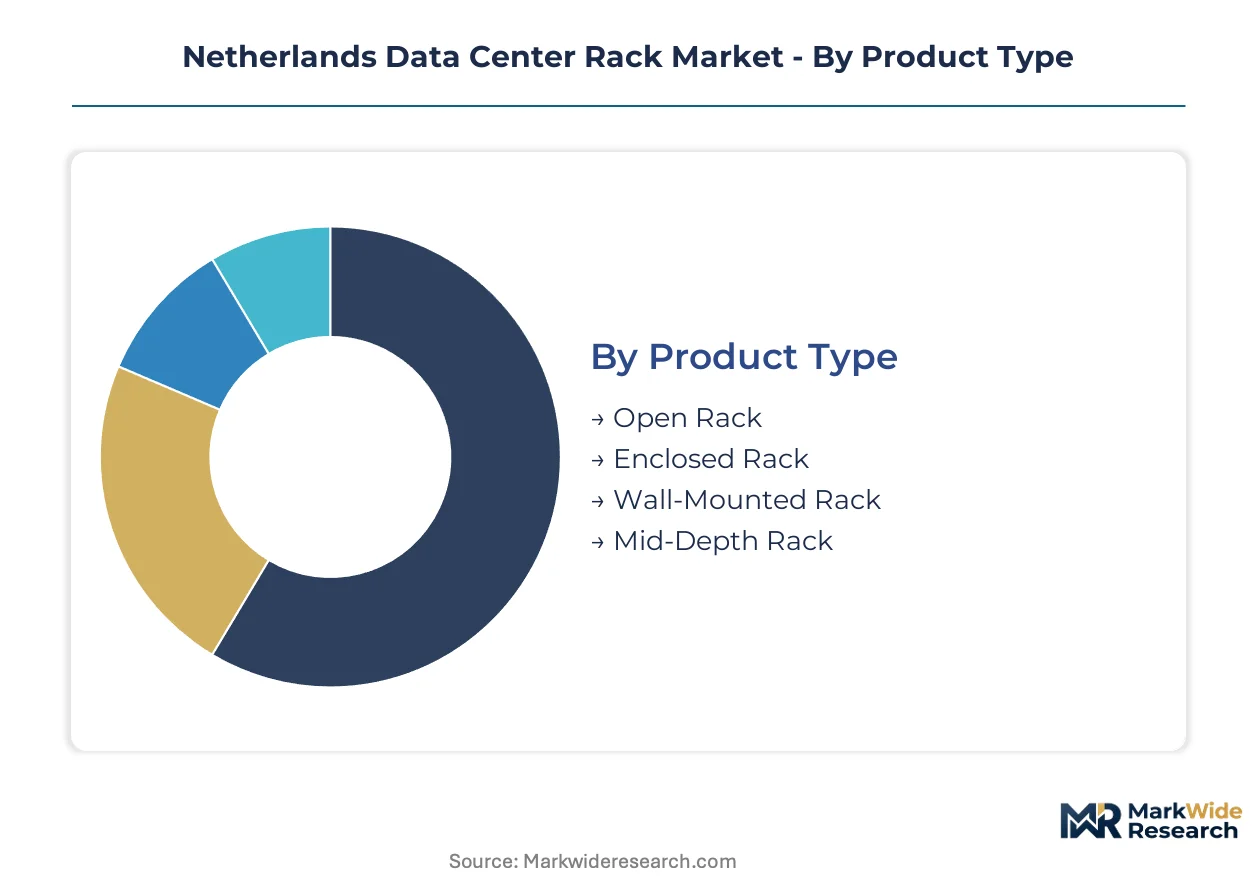
Dutch data center rack procurement follows distinct technical and commercial logics across enclosure configurations, buyer types, and form factors. Understanding these segment boundaries clarifies where specification standards diverge and where bundled solutions capture premium positioning against commodity alternatives.
Product Type:
Rack replacement cycles in Dutch facilities now hinge on thermal containment capabilities and modularity for sustainability compliance, not merely structural refresh.
- Open Rack:Frame structures without side panels or doors maximize airflow visibility and enable rapid equipment swap-out. Cloud service providers in Amsterdam's hyperscale corridor specify open configurations where GPU cluster densification demands frequent hardware reconfiguration cycles.
- Enclosed Rack:Perforated steel housings with integrated airflow containment dominate installations where power usage effectiveness targets drive cooling efficiency investments. Colocation operators under EU Green Deal mandates favor these configurations for embodied carbon reporting and modular recyclability.
- Wall-Mounted Rack:Compact 2U-12U enclosures attach directly to structural walls, eliminating floor footprint requirements. Rotterdam edge clusters deploy these variants where industrial zone floor space commands premium lease rates.
- Mid-Depth Rack:Intermediate 600mm-800mm depth specifications accommodate networking equipment without full server-depth infrastructure. Enterprise data centers in Eindhoven's high-tech corridor favor this format for structured cabling density.
Enclosed rack configurations sit at the top of the volume ranking, with wall-mounted variants climbing the fastest.
End User:
Buyer procurement sophistication varies sharply across Dutch data center operators, with direct manufacturer relationships displacing traditional channel structures in high-volume segments.
- Colocation Providers:Multi-tenant facility operators specify standardized rack configurations across buildouts to minimize spare parts inventory and maintenance training overhead. These buyers unbundle enclosure procurement from mechanical contractor packages to establish direct commercial relationships with manufacturers.
- Cloud Service Providers:Hyperscale operators compress procurement cycles for high-density enclosures while mandating liquid cooling readiness and circular material certifications. Their procurement templates now specify water-glycol thermal interfaces rather than F-Gas regulated refrigerants.
- Enterprises:Corporate-owned facilities prioritize legacy DCIM compatibility and conservative thermal specifications over cutting-edge density. Integration labor for smart rack sensor deployments extends commissioning timelines in this segment.
- Government:Public sector installations under Netherlands Enterprise Agency oversight emphasize BIS-equivalent electrical safety documentation and extended warranty terms. Environmental permit compliance adds four to eight weeks to sales cycles for cooling-integrated systems.
Colocation providers command the largest procurement volumes, though cloud service providers are gaining share fastest through accelerated buildout timelines.
Size:
Form factor selection tracks directly against facility type and compute density requirements across Dutch installations.
- 42U:Full-height server enclosures remain the default specification for Amsterdam hyperscale halls and enterprise primary data centers. This format maximizes vertical space utilization where floor loading and ceiling height permit standard rack elevations.
- 2U:Compact wall-mounted and shallow-depth variants address edge computing deployments and constrained mechanical rooms. Rotterdam's submarine cable landing zones and industrial edge clusters drive expanding demand for this footprint.
- 1U:Ultra-compact switching and patch panel housings serve telecommunications closets and distributed network aggregation points. Limited standalone rack revenue attaches to this specification.
- 4U:Mid-tower server and storage array enclosures bridge gap between blade server density and standalone appliance form factors. Niche applications in media processing and industrial IoT gateway deployments.
42U specifications dominate absolute unit volumes, with 2U configurations expanding most quickly at Rotterdam edge locations.
Material:
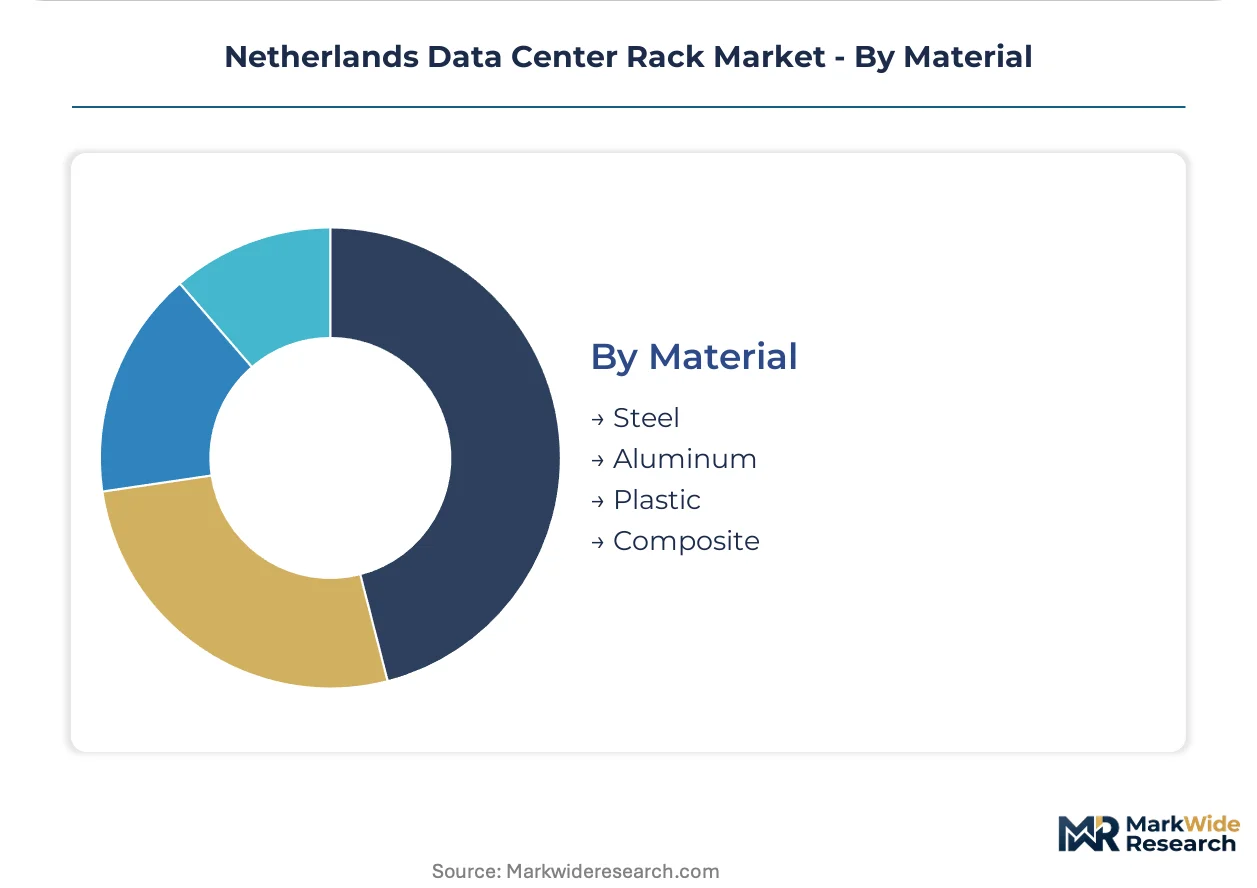
Steel rack procurement decisions in the Netherlands now incorporate embodied carbon reporting requirements under EU Green Deal circular economy frameworks.
- Steel:Cold-rolled carbon steel with powder-coated or zinc-plated finishes provides structural rigidity for high-density loadings. Dutch environmental permits now mandate material traceability documentation, pushing procurement toward European-sourced recyclable grades.
- Aluminum:Lightweight extrusions reduce shipping costs and enable tool-less assembly for rapid deployment scenarios. Premium positioning in mobile and modular data center applications where weight constraints override material cost differentials.
- Plastic:Glass-reinforced polymer housings serve low-load networking and passive equipment applications. Limited thermal conductivity restricts deployment in high-density compute environments.
- Composite:Hybrid material constructions combining steel frames with composite panels target specific electromagnetic interference shielding or corrosion resistance requirements. Niche adoption in maritime-adjacent Rotterdam facilities.
Steel retains the dominant volume position, while aluminum gains share fastest among edge and modular deployment formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Netherlands data center rack industry traces its lineage to Amsterdam's emergence as a European internet exchange hub during the 1990s, with the AMS-IX facility establishing the infrastructure density that would later attract hyperscale cloud buildouts across the Randstad metropolitan region.
Amsterdam Metropolitan Area
Hyperscale cloud operators including Microsoft and Google are compressing procurement cycles for liquid-cooled rack enclosures in the Schiphol-Rijk corridor. The Netherlands Enterprise Agency enforces EU Green Deal environmental permits requiring embodied carbon reporting for steel components. Data center construction concentrates in Amsterdam's Science Park and Sloterdijk districts where 50kW-plus GPU rack densities are becoming standard specification.
Rotterdam Port and Industrial Zone
Submarine cable landings at Maasvlakte and Europoort terminals are attracting distributed edge computing investments requiring compact 2U wall-mounted rack variants. Municipal zoning boards under the Rotterdam Climate Adaptation Strategy impose strict energy efficiency standards on new facility builds. Edge clusters are forming in Botlek and Waalhaven industrial zones where floor space premiums favor shallow-depth enclosure formats.
Eindhoven High-Tech Corridor
ASML and Philips supplier ecosystems are driving demand for mid-depth 600mm-800mm rack specifications optimized for semiconductor tooling integration. Brabant provincial authorities administer BIS-equivalent electrical safety inspections through the Dutch Accreditation Council. High-tech campuses in Veldhoven and Best are specifying enclosed rack configurations with integrated cable management for cleanroom-adjacent deployments.
Northern Netherlands Groningen-Friesland
Wind energy abundance and cooler ambient temperatures are positioning the region for sustainable data center expansion with lower power usage effectiveness targets. National government renewable energy subsidies administered by RVO.nl support facility operators meeting circular economy material standards. Limited rack procurement volumes currently concentrate in Groningen city business parks serving regional enterprise and government data hosting needs.
Utrecht Central Location
Financial services and insurance headquarters are sustaining enterprise-grade rack demand with conservative thermal specifications prioritizing legacy DCIM compatibility. The Dutch Central Bank (DNB) supervises operational resilience requirements affecting data center infrastructure procurement timelines. Leidsche Rijn and Papendorp business districts host secondary data center facilities serving national backup and disaster recovery functions.
Netherlands Data Center Rack Market Competitive Landscape
Premium-margin players sit above commodity-margin players across thermal engineering capability and integrated energy management portfolios. The market structure consolidates around three strategic archetypes: European industrial conglomerates with integrated electrical infrastructure portfolios, specialized enclosure fabricators with regional manufacturing scale, and power distribution specialists extending into physical infrastructure. Dominant competitive moves include direct commercial relationships with hyperscale operators displacing traditional systems integrator channels, and modular rack-power-cable bundle configurations capturing premium positioning against commodity enclosure sales.
Among European industrial conglomerates, Schneider Electric and Eaton Corporation exemplify the integrated portfolio archetype, anchoring large colocation contracts through combined energy management and enclosure offerings. Rittal occupies a position within the specialized fabrication tier, sustaining manufacturing scale through its European production network. Vertiv Group Corp. represents the thermal optimization specialist archetype, with its positioning reflecting high-density GPU deployment requirements. These three companies collectively illustrate how competitive positioning in the Dutch market now hinges on thermal performance guarantees and circular material certifications rather than structural steel specifications alone.
| Leading Market Players |
|---|
| Eaton Corporation |
| Black Box Corporation |
| Rittal |
| Schneider Electric |
| Vertiv Group Corp. |
| HOSTKEY B.V. |
| Delta Electronics |
| Legrand |
| Socomec |
| Others |
Pricing and Supply Chain Analysis
Computational fluid dynamics specialists concentrated in Amsterdam's Schiphol-Rijk corridor command wage premiums that inflate thermal engineering costs by fifteen to twenty percent, compressing margins on standard enclosure lines while widening spreads between commodity perforated racks and liquid-cooled premium configurations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates liquid-cooled GPU-ready enclosures with thermal performance guarantees from basic perforated steel housings and compact wall-mounted variants. Price differentiation hinges on CE marking documentation depth and volume procurement scale, with hyperscale cloud operators extracting steepest discounts through direct manufacturer relationships. Cost compression in standard enclosure tiers is intensifying because cold-rolled steel input volatility under the EU carbon border adjustment mechanism feeds through fabrication costs. Government and enterprise segments exhibit highest price sensitivity due to extended warranty requirements and legacy DCIM integration labor, while colocation providers prioritize total cost of ownership over upfront capital expenditure.
Supply Chain Analysis
Cold-rolled steel feedstock rests on German, Belgian, and Dutch integrated mills operating within three hundred kilometers of Düsseldorf, creating geographic clustering that concentrates precision sheet metal capacity serving Dutch data center builds. Key component dependencies include perforated steel coil, zinc-plated finishing treatments, and adjustable mounting rail extrusions. Single-source vulnerability runs through the Rhine corridor logistics network where barge and rail chokepoints expose just-in-time delivery schedules to weather-related disruption. Distribution runs through direct commercial relationships between enclosure manufacturers and colocation operators, bypassing traditional systems integrator channels in Amsterdam and Rotterdam buildouts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement criteria have shifted decisively toward thermal performance guarantees and circular material certifications, rewarding suppliers with integrated energy management portfolios over commodity fabricators.
For Market Incumbents: Cement thermal engineering talent retention through Amsterdam-region compensation benchmarking and captive CFD capability development. Deepen backward integration into recyclable steel sourcing to defend margin position against EU Green Deal embodied carbon reporting requirements. Channel control over direct hyperscale relationships represents the critical defensive lever as cloud service providers compress procurement cycles and disintermediate traditional systems integrators. For New Entrants and Emerging Players: Launch via modular power-cable bundle configurations targeting Rotterdam edge clusters where speed-to-deploy priorities override established supplier relationships. The wall-mounted 2U segment at submarine cable landing zones offers most penetrable white space, with municipal zoning under the Rotterdam Climate Adaptation Strategy favoring compact footprint solutions. A certification-acceleration service model addressing Netherlands Enterprise Agency permit friction creates differentiated go-to-market positioning against incumbent distributors. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized enclosure fabricators lacking thermal optimization portfolios but holding regional manufacturing scale. Long-term viability over the next decade hinges on successful transition from structural steel specifications to integrated liquid cooling infrastructure. The signal to watch is hyperscale procurement template adoption of water-glycol thermal interfaces, which would accelerate qualification timelines for European pump and heat exchanger suppliers and reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Power-Cable Bundle Development | Captures premium positioning against commodity enclosure sales in Dutch colocation builds. |
| CE Marking Acceleration Service Launch | Addresses Netherlands Enterprise Agency permit friction that extends sales cycles for imported assemblies. |
| Recyclable Steel Certification Investment | Differentiates domestic suppliers against Asian imports under EU Green Deal circularity metrics. |
| Liquid Cooling Distribution Manifold Integration | Collapses physical separation between enclosure and thermal infrastructure in Amsterdam hyperscale contracts. |
| Direct Hyperscale Relationship Establishment | Disintermediates systems integrator channels as cloud operators unbundle procurement from mechanical contractor packages. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center facility operators, thermal engineering consultants, enclosure procurement managers, and Netherlands Enterprise Agency permit officers with secondary validation through EU customs trade data, SEC filings of publicly listed infrastructure suppliers, hyperscaler capex disclosures, and circular economy certification databases. Bottom-up rack shipment tallies by configuration and end-use segment were triangulated against top-down facility construction pipeline estimates across Amsterdam, Rotterdam, Eindhoven, and Groningen-Friesland clusters.
Historical reference periods anchored the projection horizon through verified installation data and disclosed contract awards, with growth trajectories modeled across enclosure configuration, end-user type, form factor, and material composition dimensions. CAGRs were derived from segment-level volume buildups incorporating AI workload densification curves, EU F-Gas Regulation compliance timelines, and edge computing deployment patterns. Forecast inputs included Netherlands Enterprise Agency permit issuance rates, Rhine corridor steel input cost indices, and hyperscale operator procurement template specifications.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated GPU cluster densification or prolonged cold-rolled steel price volatility. Projections reflect assumptions regarding sustained EU Green Deal enforcement continuity and stable Netherlands regulatory permit processing capacity. A small set of triggers—including F-Gas Regulation retrofit mandate timing, Rotterdam edge cluster zoning approvals, and German steel production energy cost shocks—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Global Terminal Management System Market
Data Center Infrastructure
China Data Center Market
Data Center Infrastructure
LAMEA Virtual Desktop Infrastructure Market
Data Center Infrastructure
Denmark Data Center Power Market
Data Center Infrastructure
Australia Data Center Rack Market
Data Center Infrastructure
North America Data Center Server Market
Data Center Infrastructure
KVM Market
Data Center Infrastructure
Data Center Outsourcing and Infrastructure Utility Services Market
Data Center Infrastructure
Connected Distribution Center Market
Data Center Infrastructure
Asia-Pacific Containerized Data Center Market
Data Center Infrastructure
White Box Server Market
Data Center Infrastructure
India Data Center Construction Market
Data Center Infrastructure
Colocation Edge Data Center Market
Data Center Infrastructure
Switzerland Data Center Server Market
Data Center Infrastructure
Data Center As a Service Market
Data Center Infrastructure
Chile Data Center Processor Market