
 Enterprise Mobility in Energy Sector Market | 2026-2036
Enterprise Mobility in Energy Sector Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Mobility in Energy Sector Market Foresight
Asset-light leasing models for ruggedized mobile fleets is reconfiguring competitive entry barriers across the energy sector. Microsoft leverages its Azure cloud backbone to anchor utility-specific field service platforms. BlackBerry competes through hardened endpoint security architectures purpose-built for critical infrastructure operators. Cisco Systems extends its networking dominance into private LTE deployments that underpin real-time mobility for offshore and remote generation sites.
Enterprise mobility in the energy sector denotes the integrated ecosystem of mobile devices, applications, and management platforms that enable field personnel to execute asset inspection, work order management, and safety compliance across geographically dispersed generation, transmission, and distribution infrastructure. These systems typically incorporate AES-256 encryption, offline synchronization protocols, and geofencing capabilities to maintain operational continuity in connectivity-constrained environments. Cloud solutions within the deployment dimension are capturing disproportionate growth as utilities retire legacy client-server architectures. Device management capabilities represent the most mature margin pool, though security solutions are emerging as the fastest-expanding category driven by escalating threat surface exposure across OT-IT converged networks.
The Federal Energy Regulatory Commission enforces reliability standards that mandate auditable access controls for critical cyber assets, directly elevating procurement priority for mobile security solutions in North American utilities. The EPA's methane emissions monitoring rules are driving oil and gas operators to deploy mobile inspection platforms with integrated sensor telemetry and automated reporting workflows. Stakeholders must evaluate whether their current mobility architectures can absorb impending NERC CIP version 7 requirements without wholesale platform replacement.
Market Dynamics
NERC CIP cybersecurity mandates are compressing procurement cycles for hardened endpoint solutions across North American utilities, forcing operators to retire consumer-grade mobility stacks in favor of purpose-built critical infrastructure architectures.
Growth Catalysts
- NERC CIP Version 7 Compliance Deadlines:North American utilities face mandatory upgrades to mobile access controls for critical cyber assets, accelerating replacement of legacy field service platforms.
- Methane Emissions Monitoring Rules:EPA regulations compel oil and gas operators to deploy mobile inspection platforms with integrated sensor telemetry for automated leak detection and reporting workflows.
- Offshore Wind Expansion:European and Asia-Pacific offshore generation buildouts create demand for private LTE-enabled mobility solutions in connectivity-constrained marine environments.
Market Restraints
- Semiconductor Supply Concentration:Ruggedized device production depends on specialized chip fabrication concentrated in Taiwan and South Korea, exposing procurement to geopolitical disruption risks.
- Legacy System Integration Friction:Utilities operate decades-old SCADA and work management systems with proprietary protocols that resist API-based mobile connectivity without expensive middleware.
- Specialized Talent Scarcity:OT-IT convergence requires field engineers with dual expertise in industrial control systems and mobile platform administration, a skill combination with limited supply pipeline.
Strategic Opportunities
- EU CSRD Sustainability Reporting:Corporate Sustainability Reporting Directive mandates granular asset-level data collection, creating demand for mobile platforms with embedded carbon accounting and ESG workflow automation.
- India Grid Modernization:The country's central electricity regulator is driving smart meter and distributed energy resource deployments that require field mobility infrastructure at scale.
- AR-Enabled Remote Assistance:Convergence of augmented reality headsets with 5G private networks enables expert-guided maintenance without physical site visits, opening subscription revenue models.
Industry Challenges
- Multi-Jurisdictional Certification Burden:Mobility solutions must simultaneously satisfy NERC CIP in the United States, IEC 62351 internationally, and country-specific critical infrastructure standards, extending sales cycles.
- Field Workforce Digital Literacy Gaps:Veteran utility technicians require structured reskilling programs to operate tablet-based inspection applications and interpret real-time sensor dashboards effectively.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Mobility in Energy Sector Market |
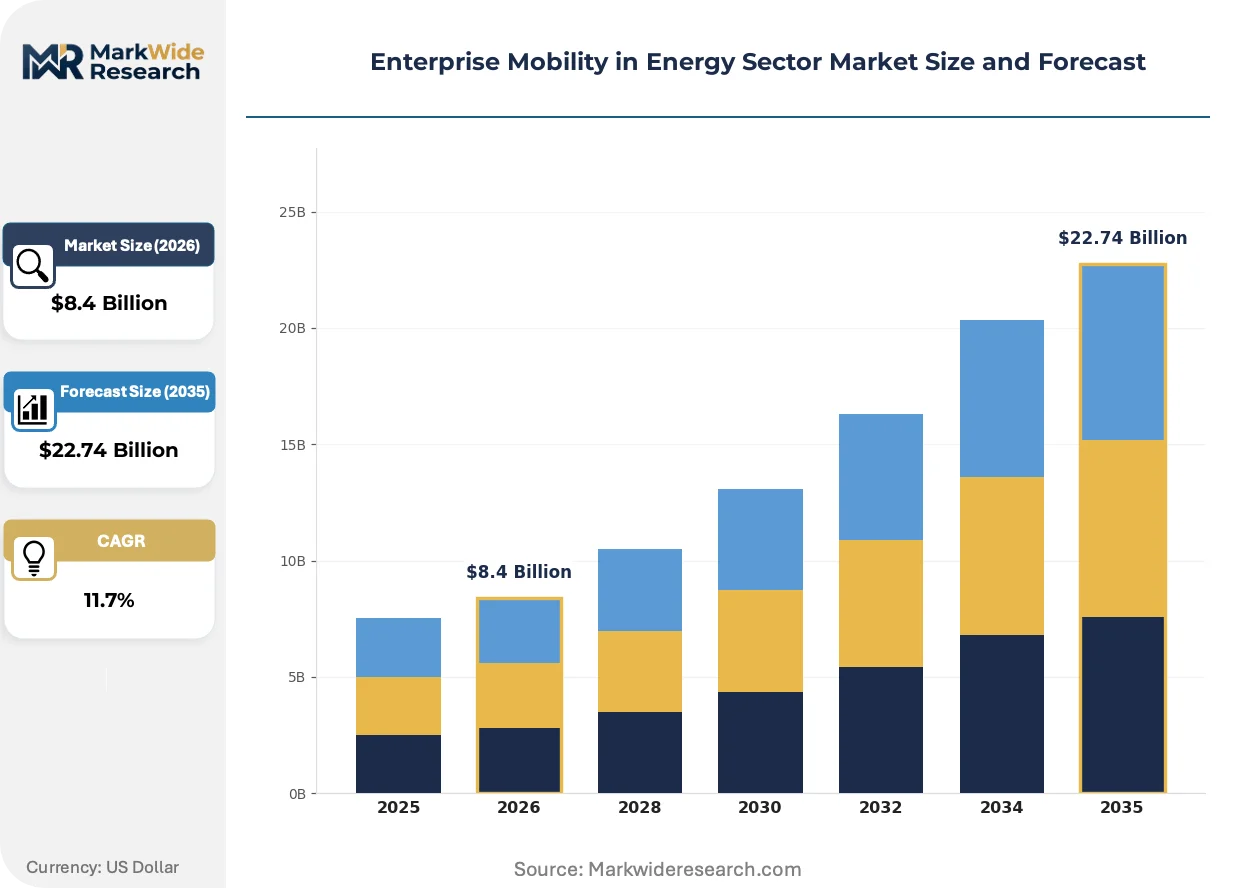
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $22.74 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Applications, Cloud Solutions, Device Management, Security Solutions End User: Utilities, Oil & Gas Companies, Renewable Energy Firms, Equipment Manufacturers Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Service Type: Consulting Services, Support Services, Custom Development, Training Services |
| Companies Covered | Apteligent, Workrise, BlackBerry, Microsoft, IBM, Cisco Systems, McAfee, Oracle, Cloud Software Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Mobility in Energy Sector Market Shifts & Advancements
Edge-native mobile architectures are displacing cloud-dependent field service platforms, enabling real-time decision-making in connectivity-starved generation and transmission environments without synchronization delays.
Zero-trust security frameworks are collapsing perimeter-based network access models for field devices. Utilities in Texas and California are mandating continuous device attestation and micro-segmentation for all mobile endpoints touching critical cyber assets. This architecture compresses vendor qualification timelines by eliminating legacy VPN-dependent solutions from procurement shortlists.
EPA methane emissions regulations are forcing oil and gas operators to retrofit mobile inspection fleets with optical gas imaging integration and automated regulatory reporting. Midstream operators in the Permian Basin are consolidating point solutions into unified platforms to satisfy simultaneous state and federal disclosure requirements without duplicate field visits.
Performance-based service contracts are displacing perpetual software licenses across European utilities. E.ON and Enel are piloting outcome-linked pricing where mobility platform fees scale with measurable improvements in field workforce utilization and safety incident reduction, compressing upfront capital requirements while shifting vendor risk profiles.
Enterprise Mobility in Energy Sector Market Segmentation
Segmentation in enterprise mobility reveals how energy operators prioritize investments across infrastructure layers. Product architecture choices determine compliance posture. Deployment models reflect connectivity constraints in remote generation environments. Service procurement patterns expose organizational readiness for OT-IT convergence.
Product Type:
Cost tier stratification across product categories shapes procurement volume and margin capture for vendors serving critical infrastructure operators.
- Security Solutions:These platforms incorporate AES-256 encryption, continuous device attestation, and micro-segmentation architectures purpose-built for NERC CIP compliance. Demand concentrates among North American utilities facing mandatory endpoint hardening deadlines for critical cyber assets under FERC-enforced reliability standards.
- Cloud Solutions:Scalable infrastructure replaces legacy client-server architectures with API-native field service platforms. European utilities are retiring on-premises systems fastest under EU CSRD sustainability reporting mandates requiring centralized data aggregation.
- Mobile Applications:Work order management and inspection tools with offline synchronization protocols.
- Device Management:Ruggedized fleet provisioning and lifecycle management platforms.
Security Solutions command the established base. The steepest expansion runs through Cloud Solutions.
End User:
Application intensity varies sharply across energy subsectors based on regulatory exposure and asset dispersion patterns.
- Utilities:Transmission and distribution operators deploy integrated mobility stacks for grid asset inspection, outage response, and vegetation management. United States investor-owned utilities are consolidating point solutions into unified platforms to satisfy simultaneous state PUC and federal reliability requirements.
- Oil & Gas Companies:Midstream and upstream operators require methane leak detection workflows with optical gas imaging integration. Permian Basin operators are retrofitting inspection fleets under EPA emissions monitoring rules mandating automated reporting telemetry.
- Renewable Energy Firms:Offshore wind developers leverage private LTE-enabled mobility for marine environment connectivity.
- Equipment Manufacturers:OEMs embed mobility platforms into service contracts for distributed generation asset fleets.
Utilities command the established base. The steepest expansion runs through Oil & Gas Companies.
Deployment:
Volume distribution across deployment models reflects connectivity infrastructure maturity and data sovereignty requirements in regulated markets.
- Cloud-Based:Fully managed SaaS platforms eliminate capital expenditure for field service infrastructure. India grid modernization programs are accelerating adoption as state electricity boards seek scalable solutions without dedicated IT operations.
- Edge Computing:Localized processing enables real-time decision-making in connectivity-starved transmission corridors and offshore generation sites. Texas utilities are mandating edge-native architectures for critical cyber assets to eliminate synchronization delays during network segmentation events.
- On-Premises:Air-gapped installations for highest-security critical infrastructure environments.
- Hybrid:Mixed architectures balancing cloud scalability with local control for sensitive OT systems.
On-Premises commands the established base. The steepest expansion runs through Edge Computing.
Service Type:
Customer type segmentation reveals how energy organizations structure vendor relationships based on internal technical capacity and platform complexity.
- Consulting Services:Architecture design and compliance roadmap development for NERC CIP, IEC 62351, and multi-jurisdictional certification requirements. European utilities are engaging consultants most intensively under EU CSRD implementation timelines requiring ESG workflow automation design.
- Custom Development:Bespoke application builds integrating proprietary SCADA protocols and legacy work management systems. Japanese utilities are commissioning custom middleware to bridge decades-old industrial control systems with modern mobile APIs.
- Support Services:24/7 operational assistance and break-fix coverage for field-deployed device fleets.
- Training Services:Structured reskilling programs for veteran technicians transitioning to tablet-based inspection platforms.
Support Services command the established base. The steepest expansion runs through Consulting Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC reliability standards and NERC CIP mandates are compressing procurement cycles for hardened endpoint solutions across North American utilities. European utilities face EU CSRD sustainability reporting deadlines requiring granular asset-level data collection infrastructure. Asia-Pacific grid modernization programs are accelerating field mobility investments as state electricity boards retire legacy client-server architectures.
United States
Investor-owned utilities in Texas and California are consolidating point solutions into unified platforms to satisfy simultaneous state PUC and federal reliability requirements. The EPA's methane emissions monitoring rules compel Permian Basin operators to deploy mobile inspection platforms with integrated sensor telemetry. Houston anchors midstream operator retrofit programs for optical gas imaging integration and automated regulatory reporting workflows.
Germany
E.ON and Enel are piloting outcome-linked pricing models where mobility platform fees scale with measurable improvements in field workforce utilization. The EU CSRD mandates granular asset-level data collection, creating demand for mobile platforms with embedded carbon accounting. Bavaria hosts the most intensive consulting engagements for ESG workflow automation design under tight implementation timelines.
India
State electricity boards are driving smart meter and distributed energy resource deployments that require field mobility infrastructure at scale. The Central Electricity Authority is accelerating grid modernization programs as regulators push scalable solutions without dedicated IT operations. Maharashtra and Gujarat concentrate the largest procurement volumes for cloud-based SaaS platforms eliminating capital expenditure requirements.
Japan
Utilities are commissioning custom middleware to bridge decades-old industrial control systems with modern mobile APIs. METI industrial digitization incentives support OT-IT convergence investments for transmission and distribution operators. The Kansai region around Osaka hosts the most intensive integration projects for proprietary SCADA protocol adaptation.
United Kingdom
Offshore wind developers in the North Sea are leveraging private LTE-enabled mobility solutions for marine environment connectivity. The country's national electricity regulator is enforcing reliability standards that elevate procurement priority for security-hardened endpoint architectures. Scotland concentrates the largest deployments for real-time decision-making in connectivity-constrained generation environments.
Enterprise Mobility in Energy Sector Market Competitive Landscape
On the supply side, the industry is consolidating around technology conglomerates with cloud infrastructure assets and specialized cybersecurity vendors with critical infrastructure certifications. Strategic archetypes include hyperscale platform providers anchoring utility-specific field service stacks, endpoint security specialists with NERC CIP-compliant architectures, and networking equipment vendors extending into private LTE deployments. Dominant competitive moves encompass strategic partnerships between cloud providers and industrial software vendors, plus portfolio diversification into edge-native architectures eliminating synchronization delays.
Among North American technology conglomerates, Microsoft and Cisco Systems exemplify the hyperscale platform archetype leveraging existing cloud and networking dominance into utility verticals. BlackBerry occupies a specialist position representing the hardened endpoint security tier purpose-built for critical infrastructure operators. These three companies anchor the competitive structure without exhaustive market coverage claims.
| Leading Market Players |
|---|
| Apteligent |
| Workrise |
| BlackBerry |
| Microsoft |
| IBM |
| Cisco Systems |
| McAfee |
| Oracle |
| Cloud Software Group |
| Others |
Supply & Pricing Matrix
Trans-Pacific shipping corridors from Taiwan and South Korea feed specialized semiconductor fabrication for ruggedized mobility devices, concentrating supply-side leverage among a handful of foundries while forcing downstream vendors into tiered pricing stratification based on security certification tiers and fleet scale commitments.
Pricing Analysis
Certification level creates the primary spread across enterprise mobility offerings, with NERC CIP-compliant security architectures commanding substantial premiums over standard commercial-grade alternatives. Subscription-based SaaS models dominate utility procurement, though project-based licensing persists for custom SCADA integrations. Price differentiation hinges on AES-256 encryption depth and geofencing granularity alongside deployment volume. Cost compression in mid-tier cloud solutions is intensifying because hyperscale providers are bundling field service platforms with existing infrastructure contracts. Municipal utilities exhibit the highest price sensitivity due to rate-case scrutiny, while major investor-owned operators prioritize compliance posture over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard practice among Taiwanese and South Korean semiconductor foundries serving ruggedized device manufacturers. Component sourcing draws from specialized fabs in Taiwan for application processors, South Korea for memory modules, and Japan for industrial-grade sensors. Raw material dependencies include rare earth elements for magnetometers, high-grade aluminum alloys for chassis durability, and sapphire glass for display protection. Single-source vulnerability concentrates in advanced node chip fabrication, where geopolitical friction threatens procurement continuity. Distribution runs through authorized industrial distributors with field engineering support rather than consumer electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise mobility in energy traces a cyclical recovery pattern anchored to utility capital expenditure refresh cycles, with NERC CIP version 7 compliance deadlines compressing replacement timelines across North American infrastructure operators.
For Market Incumbents: Entrench platform stickiness through deep integration with utility work management systems and SCADA protocols that resist displacement. Prioritize backward integration into edge-native hardware architectures to eliminate third-party synchronization dependencies. Defensive consolidation around private LTE networking capabilities counters emerging hyperscale bundling threats from cloud infrastructure providers.
For New Entrants and Emerging Players: Establish a beachhead in methane emissions monitoring workflows for Permian Basin oil and gas operators facing EPA retrofit mandates. White-space concentration appears in AR-enabled remote assistance subscriptions for offshore wind maintenance, where incumbent platforms lack immersive technology integration. A vertical-specific go-to-market angle through optical gas imaging partnerships accelerates credibility without competing head-on against entrenched field service suites.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cybersecurity specialists with critical infrastructure certifications over generalist mobility platforms facing commoditization pressure. Long-term viability hinges on OT-IT convergence expertise that deepens switching costs across decade-long utility procurement cycles. Acquisition targets should demonstrate proven NERC CIP audit track records and existing relationships with FERC-jurisdictional reliability coordinators. The signal to watch is acceleration in performance-based contracting pilots among European utilities, which would validate outcome-linked pricing as a durable margin expansion mechanism.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native Architecture Development | Texas utilities mandate localized processing to eliminate cloud synchronization delays during network segmentation events. |
| Private LTE Network Deployment | North Sea offshore wind developers require marine-grade connectivity for real-time asset monitoring in coverage gaps. |
| NERC CIP Certification Investment | FERC-enforced reliability standards elevate procurement priority for audited endpoint security architectures. |
| AR-Enabled Remote Assistance Platform | Expert-guided maintenance subscriptions reduce physical site visits for geographically dispersed generation assets. |
| EU CSRD Compliance Integration | Embedded carbon accounting workflows capture sustainability reporting mandates across European utility procurement. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility planning officers, field service operations managers, cybersecurity compliance leads, and private LTE network engineers. Secondary validation drew from FERC reliability filings, EIA grid modernization databases, EPA emissions enforcement records, and IEA distributed energy resource deployment trackers. Bottom-up triangulation across field mobility procurement volumes and top-down reconciliation against utility capital expenditure disclosures anchored market sizing.
Calibration against historical deployment cycles and regulatory deadline clustering shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, end-user subsector, security certification tier, and regional regulatory framework. CAGRs were derived from slope analysis of replacement cycle acceleration and compliance-driven procurement compression. Industry-specific forecast inputs encompassed NERC CIP version 7 implementation timelines and EU CSRD reporting phase-in schedules.
Stress conditions across semiconductor supply disruption, geopolitical trade restriction, and utility rate-case delay were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology substitution rates. Macroeconomic contraction, regulatory forbearance, or breakthrough edge-computing architectures would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
IT Operations Management Market
Digital Solutions
Consent Management Market
Digital Solutions
Business Transcription Market
Digital Solutions
Change and Configuration Management Market
Digital Solutions
Express Digitizer Market
Digital Solutions
France ICT Market
Digital Solutions
Cloud Logistics Software Market
Digital Solutions
Contactless Ticketing Solutions Market
Digital Solutions
Global User Experience (UX) Market
Digital Solutions
Anticipatory Commerce Infrastructure Market
Digital Solutions
Latin America IT Market
Digital Solutions
Online Recruitment Market
Digital Solutions
India ICT Market
Digital Solutions
Data Monetization Platform Market
Digital Solutions
Application Performance Management Market
Digital Solutions
Digital User Experience Solutions Market