
 Middle East Metaverse Market | 2026-2036
Middle East Metaverse Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Metaverse Market Insights
Subscription-based access to persistent virtual environments is pivoting how platform economics function across the Middle East. Meta leverages its social-graph infrastructure to anchor developer ecosystems in the Gulf. Arabia VR competes through localized Arabic-language content pipelines and regional event hosting. VR Arabia differentiates by controlling exclusive partnerships with Saudi entertainment venues and museum digitization projects.
The Middle East Metaverse comprises persistent, shared digital spaces rendered through real-time 3D engines, accessed via head-mounted displays or spatial computing endpoints, with latency requirements typically below 20 milliseconds for synchronous multiplayer presence. Its primary commercial purpose spans virtual property showcasing, remote industrial collaboration, and gamified consumer engagement. Virtual Reality occupies the dominant hardware revenue pool, while Blockchain-enabled asset ownership is recording the fastest enterprise uptake across property tokenization and digital identity verification. Cloud-Based deployment leads in scalability for real estate visualization workloads, though Edge Computing is gaining ground for low-latency gaming and defense training simulations.
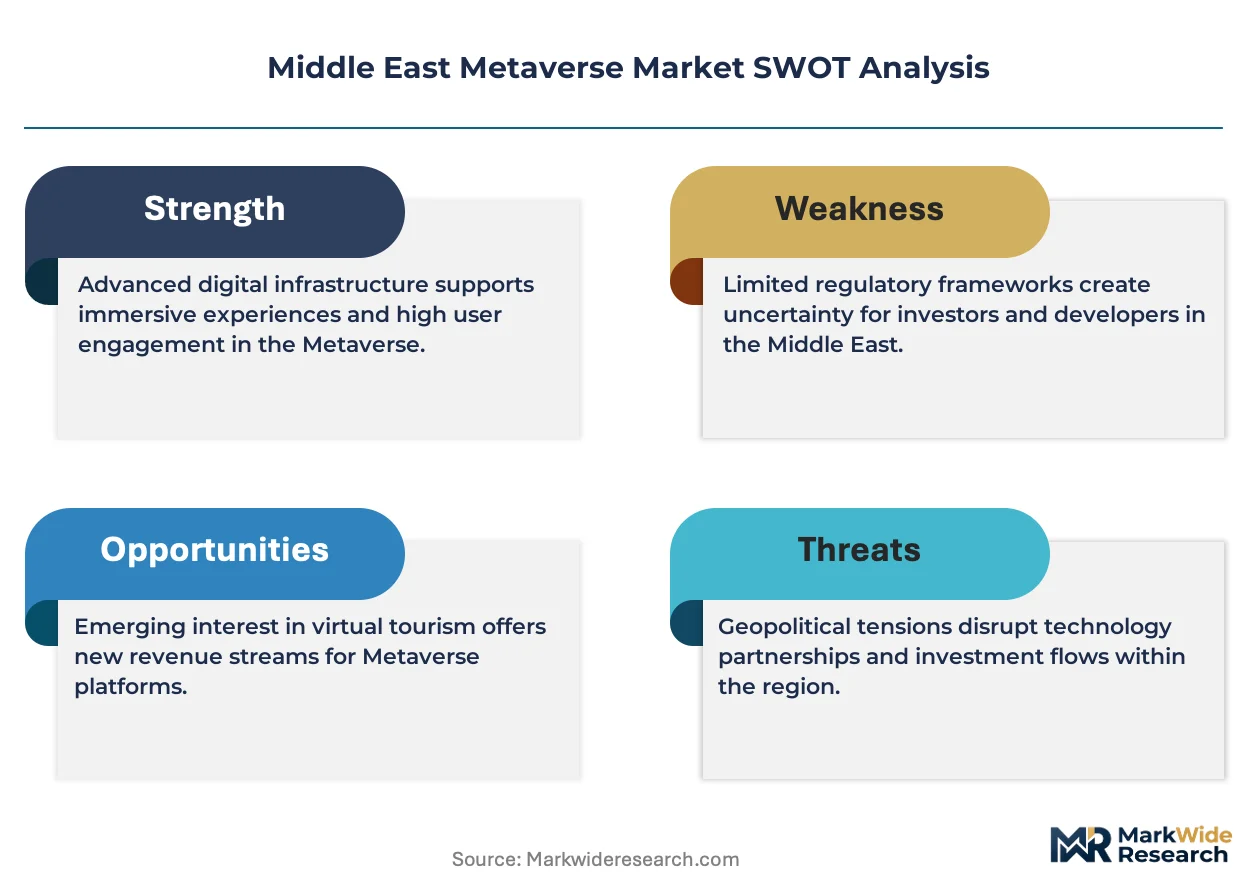
Saudi Arabia's Communications and Information Technology Commission and the UAE's Telecommunications and Digital Government Regulatory Authority shape spectrum allocation and data residency requirements for immersive platforms. Dubai's Virtual Assets Regulatory Authority and Bahrain's Central Bank framework govern blockchain-based metaverse transactions and digital asset custody. Stakeholders must monitor how evolving personal data localization mandates intersect with cross-border avatar identity standards and sovereign cloud certification requirements.
Market Dynamics
Sovereign capital deployment through Saudi Arabia's giga-projects and Dubai's Virtual Assets Regulatory Authority licensing regime are compressing platform development timelines while fragmenting technical standards across national boundaries.
Growth Catalysts
- Immersive training mandates:Saudi Arabia's healthcare regulators now require simulation-based certification for surgical residencies, creating institutional demand for persistent virtual environments.
- Virtual asset frameworks:VARA's licensing structure for digital property custody is legitimizing blockchain-based ownership models across real estate tokenization use cases.
- Edge infrastructure buildout:UAE telecom operators are deploying sub-10ms latency nodes specifically for defense and gaming applications, enabling synchronous multiplayer presence at scale.
Market Restraints
- Hardware import dependencies:Head-mounted display supply concentrates through East Asian manufacturing clusters, exposing Gulf deployers to shipping volatility and customs clearance friction.
- Spectrum allocation bottlenecks:Saudi Arabia's CITC and UAE's TDRA maintain divergent mmWave licensing procedures, complicating cross-border avatar identity synchronization.
- Data residency compulsion:Personal data localization mandates force redundant cloud infrastructure investments, inflating operational overhead for platform operators serving multiple Gulf jurisdictions.
Strategic Opportunities
- Bahrain's regulatory arbitrage:The Central Bank's crypto-asset framework permits faster licensing than VARA or CITC regimes, attracting middleware developers seeking operational beachheads.
- Museum digitization pipelines:Saudi entertainment venues and cultural institutions lack in-house 3D capture capabilities, opening service contracts for specialized spatial computing vendors.
- Spatial computing convergence:Real-time 3D engines are merging with AI-driven NPC generation, enabling persistent virtual environments that adapt without manual content updates.
Industry Challenges
- Arabic NLP talent scarcity:Natural language processing specialists capable of localizing voice interfaces for Gulf dialects command premium compensation, constraining platform localization velocity.
- Interoperability standard gaps:Avatar identity formats and virtual asset metadata schemas lack cross-platform consensus, forcing developers into redundant integration work for each national deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Metaverse Market |
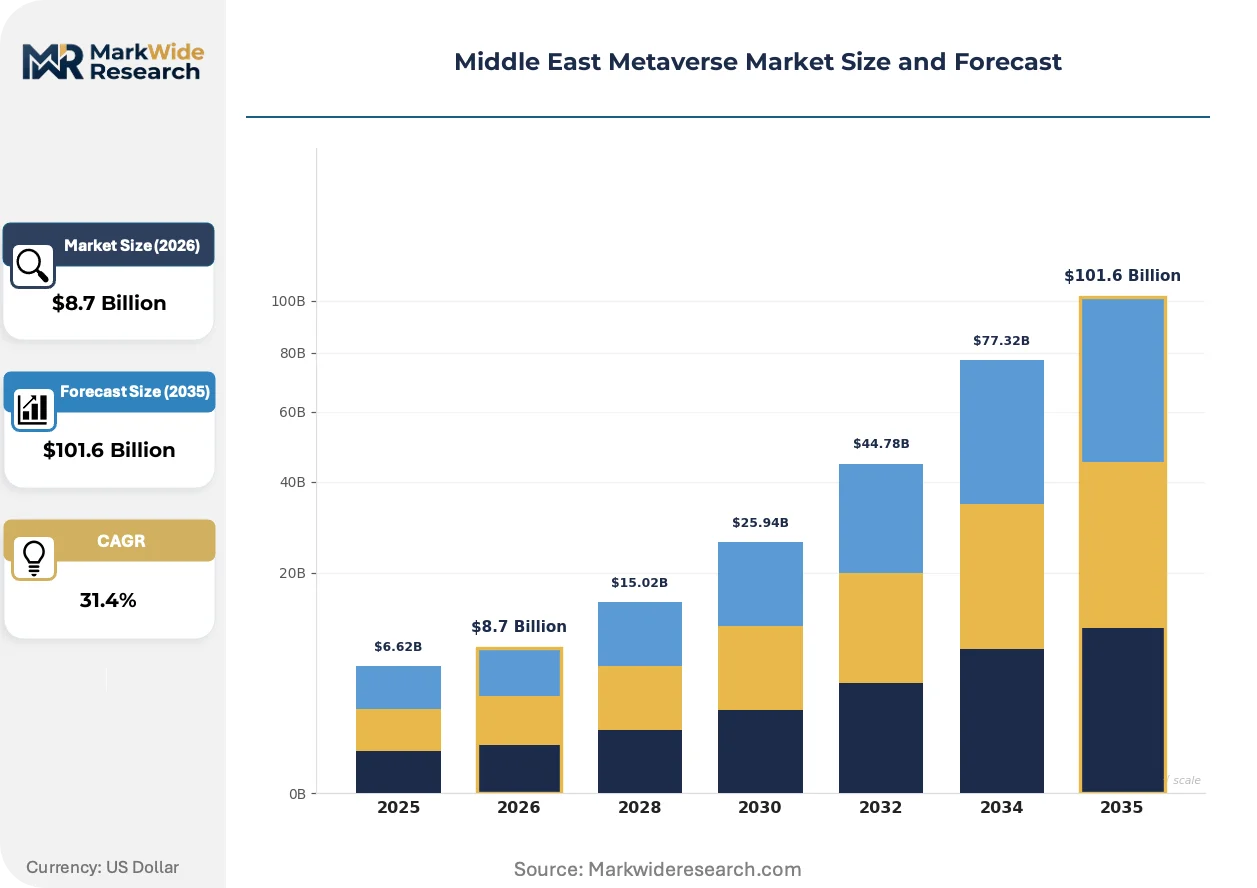
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $101.6 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virtual Reality, Augmented Reality, Mixed Reality, Wearable Devices End User: Gaming Industry, Retailers, Real Estate, Enterprises Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Technology: Blockchain, Artificial Intelligence, 3D Modeling, Networking |
| Companies Covered | Meta, Roblox, Epic Games, Decentraland, Unity Technologies, ByteDance, Arabia VR, VR Arabia, Unimersiv, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Metaverse Market Trends and Innovations
Real-time 3D engines are absorbing artificial intelligence capabilities that previously required separate middleware stacks, compressing the vendor landscape while expanding functional scope for end-users.
Cloud rendering architectures are absorbing GPU-intensive workloads that previously demanded local hardware, enabling Saudi healthcare institutions to deploy surgical simulations through thin-client terminals. The shift is absorbing capital expenditure from end-user facilities into centralized data center investments controlled by telecom operators and sovereign wealth vehicles.
VARA's virtual asset custody rules are mandating segregated wallet infrastructure and audit trails for metaverse property transactions, forcing platform operators to rearchitect payment flows. The regulation most acutely affects real estate visualization platforms targeting Dubai's luxury property marketing segment, which must now integrate licensed custodians into their purchase pathways.
Enterprise procurement of immersive training is fragmenting from centralized IT budgets into line-of-business ownership, with Saudi hospital networks now authorizing department-level simulation subscriptions. This shift is compressing sales cycles for specialized healthcare VR vendors while displacing generalist platform providers that lack clinical workflow integration. The pattern is most visible in Riyadh's tertiary care institutions, where surgical department heads control independent technology budgets.
Middle East Metaverse Market Segmentation
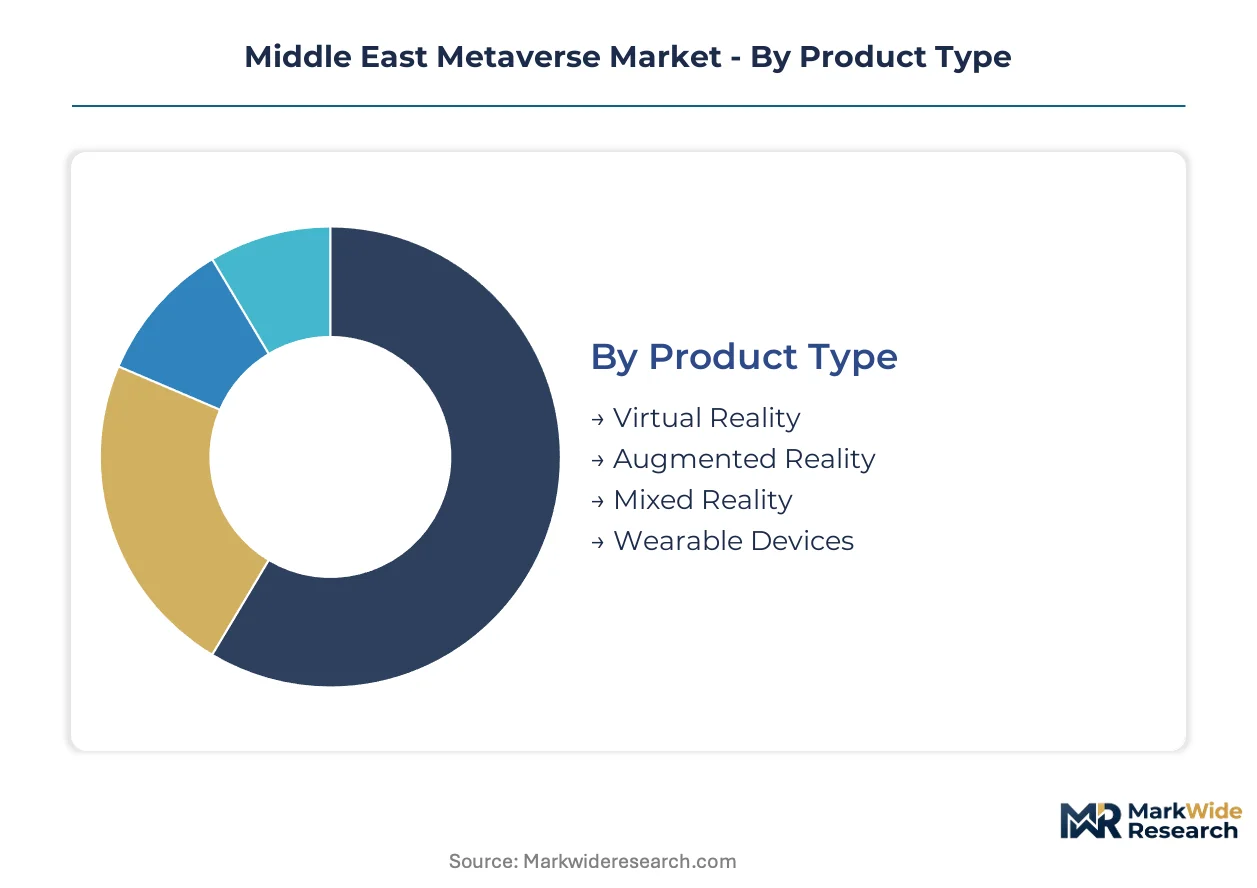
Segmentation across the Middle East Metaverse Market reveals how sovereign capital deployment and regulatory fragmentation concentrate demand in distinct technical configurations. Product type and deployment mode choices directly reflect latency requirements, data residency mandates, and institutional procurement authority in Saudi Arabia and the UAE.
Product Type:
Supply concentration in head-mounted display manufacturing clusters shapes hardware availability and import friction across Gulf deployment scenarios.
- Virtual Reality:Fully immersive headsets with 90Hz+ refresh rates and 6DoF tracking dominate surgical simulation and defense training workloads. Saudi Arabia's healthcare regulators now mandate VR-based certification for surgical residencies, institutionalizing procurement through hospital IT budgets rather than discretionary spending.
- Augmented Reality:Optical see-through displays overlay digital assets onto physical environments for industrial maintenance and real estate visualization. UAE property developers deploy AR for off-plan sales in Dubai's luxury segment, where VARA custody rules require integrated wallet infrastructure for tokenized asset previews.
- Mixed Reality:Passthrough-enabled headsets blend physical and digital presence for collaborative design reviews.
- Wearable Devices:Haptic gloves and spatial computing wristbands extend presence fidelity for enterprise training scenarios.
Today's leader: Virtual Reality. Tomorrow's challenger: Mixed Reality.
End User:
Procurement authority is fragmenting from centralized IT departments into line-of-business ownership, altering vendor selection criteria across buyer categories.
- Gaming Industry:Multiplayer synchronous environments demand sub-10ms latency infrastructure that UAE telecom operators are deploying through edge nodes. Riyadh and Dubai esports venues drive hardware refresh cycles for competitive titles.
- Retailers:Virtual storefronts and digital twin showrooms enable immersive product exploration without physical inventory exposure.
- Real Estate:Persistent virtual environments for property showcasing absorb the largest cloud rendering workloads, with VARA licensing requirements forcing custodian integration into purchase pathways. Dubai's luxury segment leads tokenization pilots.
- Enterprises:Industrial collaboration platforms and remote expert assistance systems concentrate in Saudi giga-project developments.
Real Estate commands current infrastructure investment. Gaming Industry shows the steepest expansion trajectory as sovereign wealth vehicles target esports ecosystem development.
Deployment:
Latency thresholds and data localization mandates create divergent infrastructure economics across deployment architectures.
- Cloud-Based:Centralized GPU rendering enables thin-client access from Saudi healthcare facilities without local hardware expenditure. Telecom operators and sovereign wealth vehicles control capital deployment into data center capacity.
- Edge Computing:Sub-10ms nodes deployed by UAE operators specifically target defense and gaming applications requiring synchronous multiplayer presence.
- On-Premises:Air-gapped installations serve classified government and military simulation requirements.
- Hybrid:Split workloads between local rendering and cloud offload balance latency against capital efficiency.
Cloud-Based absorbs majority capital flows. Edge Computing is gaining share fastest as latency-sensitive use cases proliferate.
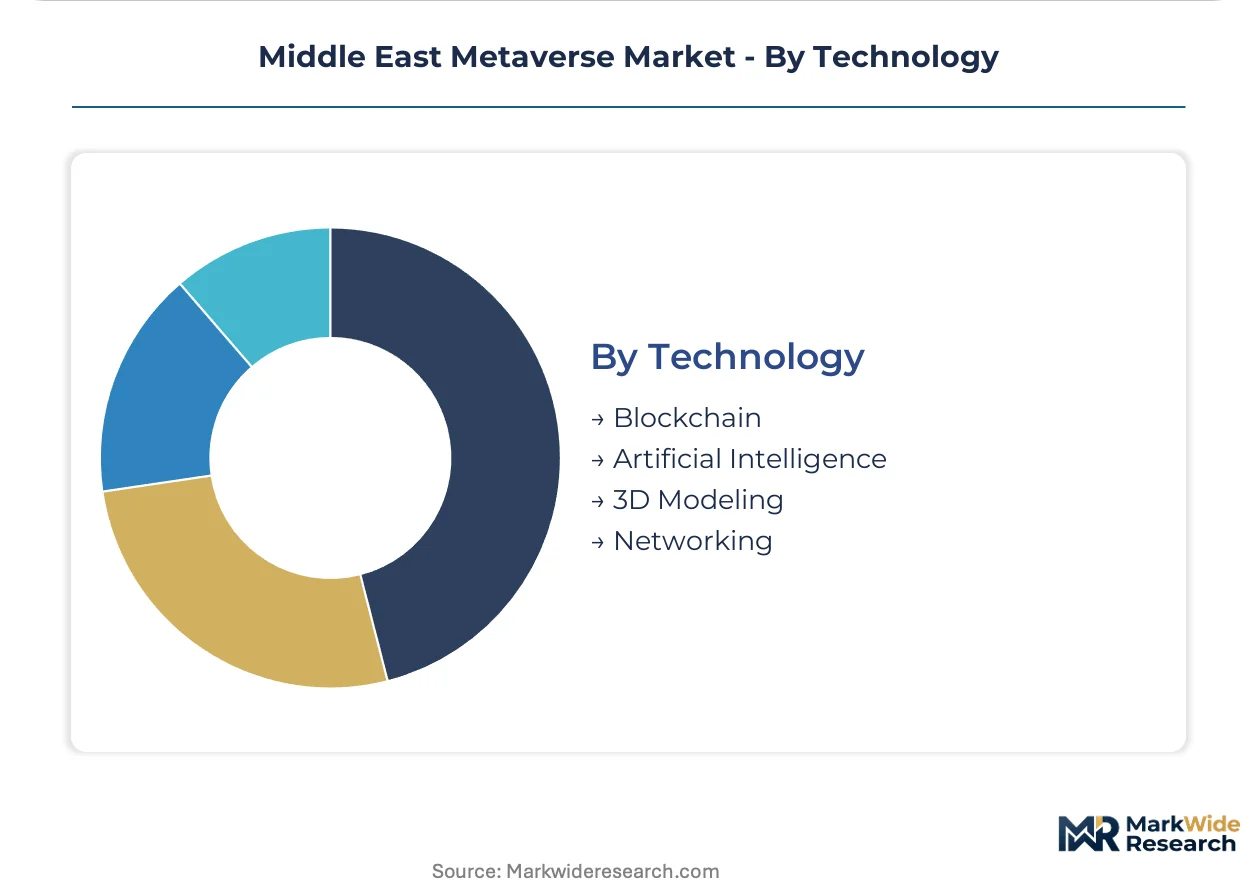
Technology:
Functional integration between previously separate middleware stacks is compressing vendor landscapes while expanding platform capabilities.
- Blockchain:Distributed ledger infrastructure enables property tokenization and avatar identity verification. VARA's custody rules mandate segregated wallets and audit trails, forcing rearchitecture of real estate visualization payment flows.
- Artificial Intelligence:Generative NPC systems and procedural environment adaptation reduce manual content update burdens for persistent virtual spaces.
- 3D Modeling:Photogrammetry and NeRF-based capture pipelines serve museum digitization contracts across Saudi entertainment venues lacking in-house spatial computing capabilities.
- Networking:Real-time synchronization protocols maintain avatar state consistency across distributed clients.
Blockchain anchors regulatory legitimacy. Artificial Intelligence is expanding most quickly as real-time 3D engines absorb generative capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's giga-project pipeline absorbs more sovereign metaverse capital than any other Gulf state, while the UAE's regulatory frameworks attract middleware developers seeking faster licensing pathways.
Saudi Arabia
NEOM's linear city development and Red Sea Project drive demand for persistent virtual environments in property visualization and remote collaboration. The Communications and Information Technology Commission mandates data residency for immersive platforms, forcing cloud infrastructure localization. Riyadh's tertiary hospital networks now control independent VR simulation budgets, bypassing centralized IT procurement.
United Arab Emirates
Dubai's luxury real estate segment requires tokenized asset previews with integrated custody infrastructure under VARA rules. The Telecommunications and Digital Government Regulatory Authority allocates mmWave spectrum for low-latency gaming nodes. Abu Dhabi's sovereign wealth vehicles direct capital into edge data centers serving defense training applications.
Bahrain
The Central Bank's crypto-asset framework permits faster licensing than neighboring regimes, attracting blockchain middleware developers. Regulatory arbitrage opportunities concentrate in Manama's fintech hub, where virtual asset custody startups establish operational beachheads. The country's compact geography enables rapid edge node deployment for sub-10ms latency workloads.
Qatar
Preparations for multi-sport event hosting accelerate investment in virtual venue replicas and spectator engagement platforms. The national telecom operator builds localized cloud rendering capacity to avoid cross-border data transfer restrictions. Doha's museum digitization initiatives lack in-house spatial computing capabilities, opening service contracts for specialized vendors.
Middle East Metaverse Market Competitive Landscape
Top-tier vendors anchor platform infrastructure, while regional specialists capture localized content and event hosting contracts. The market structure splits between global engine providers with social-graph advantages and Gulf-based operators with Arabic-language pipelines. Strategic archetypes include sovereign-integrated platform developers, regulatory-arbitrage middleware vendors, and venue-exclusive content studios. Dominant competitive moves center on exclusive partnerships with Saudi entertainment venues and VARA-compliant custody integration.
Within the regional specialist tier, Arabia VR and VR Arabia exemplify divergent localization strategies. Arabia VR occupies a position tied to Arabic-language content pipelines and regional event hosting, while VR Arabia anchors its presence through exclusive venue partnerships and museum digitization contracts. Meta represents the global platform archetype, leveraging social-graph infrastructure to anchor developer ecosystems across Gulf markets.
| Leading Market Players |
|---|
| Meta |
| Roblox |
| Epic Games |
| Decentraland |
| Unity Technologies |
| ByteDance |
| Arabia VR |
| VR Arabia |
| Unimersiv |
| Others |
Pricing and Supply Chain Analysis
Certification-tier divergence between VARA-licensed custody platforms and unlicensed visualization tools manifests in both subscription pricing and cloud infrastructure sourcing. Premium tiers command integrated wallet architecture and segregated audit trails, while economy offerings rely on generic rendering nodes without compliance overlay.
Pricing Analysis
Capacity additions in UAE edge data centers are reshaping price floors for low-latency workloads. Three-tier pricing structure across premium, standard, and economy levels separates VARA-compliant custody bundles from basic visualization subscriptions from thin-client access tiers. Price differentiation rests on latency guarantees and data residency certification. Cost compression in standard-tier cloud rendering is intensifying because telecom operators are consolidating GPU procurement. Gaming venues show highest price sensitivity; healthcare institutions least.
Supply Chain Analysis
Freight costs for head-mounted displays from East Asian manufacturing clusters absorb 8-12% of landed hardware value across Gulf ports. Supply concentrates in China, South Korea, and Taiwan for display panels, optical waveguides, and haptic sensors. Component dependencies span gallium nitride semiconductors, rare-earth magnets, and precision injection-molded housings. Single-source vulnerability concentrates in advanced OLED microdisplay fabrication. Distribution runs through Dubai's Jebel Ali free zone for regional fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering, with Dubai's VARA licensing regime creating mandatory infrastructure upgrades that lock in recurring platform revenue.
For Market Incumbents: Deploy VARA custody certification as a competitive moat. Integrate segregated wallet infrastructure before smaller competitors complete licensing. Edge node partnerships with UAE telecom operators defend against latency arbitrage from Bahrain-based entrants. For New Entrants and Emerging Players: Channel partners in Saudi hospital procurement committees offer fastest path to surgical simulation contracts. White-space targets include museum digitization pipelines lacking in-house spatial computing and Arabic NLP localization for voice interfaces. Go-to-market through department-level budget authority bypasses centralized IT gatekeepers. For Investors and Strategic Acquirers: Consolidation pressure builds where middleware developers lack VARA licensing but possess deployable edge infrastructure. Long-term viability favors platforms with sovereign wealth backing and regulatory beachheads in multiple Gulf jurisdictions. Acquisition target archetype: Bahrain-licensed custody startups with UAE expansion capability. Signal to watch: CITC data residency mandates tightening cross-border avatar synchronization.| Strategic Initiative | Industry Significance |
|---|---|
| VARA Licensing Acquisition | Unlocks Dubai luxury real estate tokenization workflows under mandatory custody rules. |
| Edge Node Partnership | Secures sub-10ms latency guarantees for defense and gaming synchronous presence. |
| Arabic NLP Development | Addresses talent scarcity constraining voice interface localization velocity. |
| Museum Digitization Contract | Captures service revenue from Saudi entertainment venues lacking in-house 3D capture. |
| Hospital Department Integration | Aligns with Riyadh tertiary care budget fragmentation toward line-of-business ownership. |
Research Methodology
Multiple input streams — platform engineering leads at telecom operators, surgical department heads in Riyadh hospital networks, VARA licensing officers, spatial computing vendors, and real estate tokenization developers — were reconciled against hyperscaler capex disclosures, CITC spectrum allocation filings, customs import records for HMD hardware, and sovereign wealth vehicle investment databases. Bottom-up deployment counts and top-down infrastructure spend estimates were triangulated.
Data-stream reconciliation across product type, deployment architecture, end-user vertical, and national regulatory cluster generated volume and value outputs throughout the forecast period. CAGRs were derived from infrastructure deployment timelines and procurement authorization patterns. Industry-specific inputs included edge node latency specifications, VARA custody rule compliance costs, and giga-project visualization contract values.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CITC data residency mandate expansion and mmWave spectrum allocation bottlenecks. Forecasts reflect documented assumptions about sovereign capital continuity and hardware import clearance efficiency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality for Consumer Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
India Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Training Market
Virtual Reality (VR) and Augmented Reality (AR)
Neuro-Gaming Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
Industrial Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Global VR for Medical Market
Virtual Reality (VR) and Augmented Reality (AR)
Japan Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Dressing Room Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR Solutions Market
Virtual Reality (VR) and Augmented Reality (AR)
Location-Based VR Entertainment Market
Virtual Reality (VR) and Augmented Reality (AR)
Para-Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
Telepresence Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Florida Augmented and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Augmented and Mixed Reality (VR/AR) Market