
 Gene Editing Market | 2026-2036
Gene Editing Market Size, Share, and Industry Trends Forecast 2026-2036
Gene Editing Market Analysis
Project finance tied to milestone-based clinical partnerships is narrowing the field of well-capitalized gene editing competitors. CRISPR Therapeutics leverages its vertically integrated manufacturing footprint to control cost of goods for autologous cell therapies. Editas Medicine anchors its competitive position through sustained R&D intensity in in vivo editing modalities. Thermo Fisher Scientific extends its reach across reagent supply chains, competing on scale rather than therapeutic ownership.
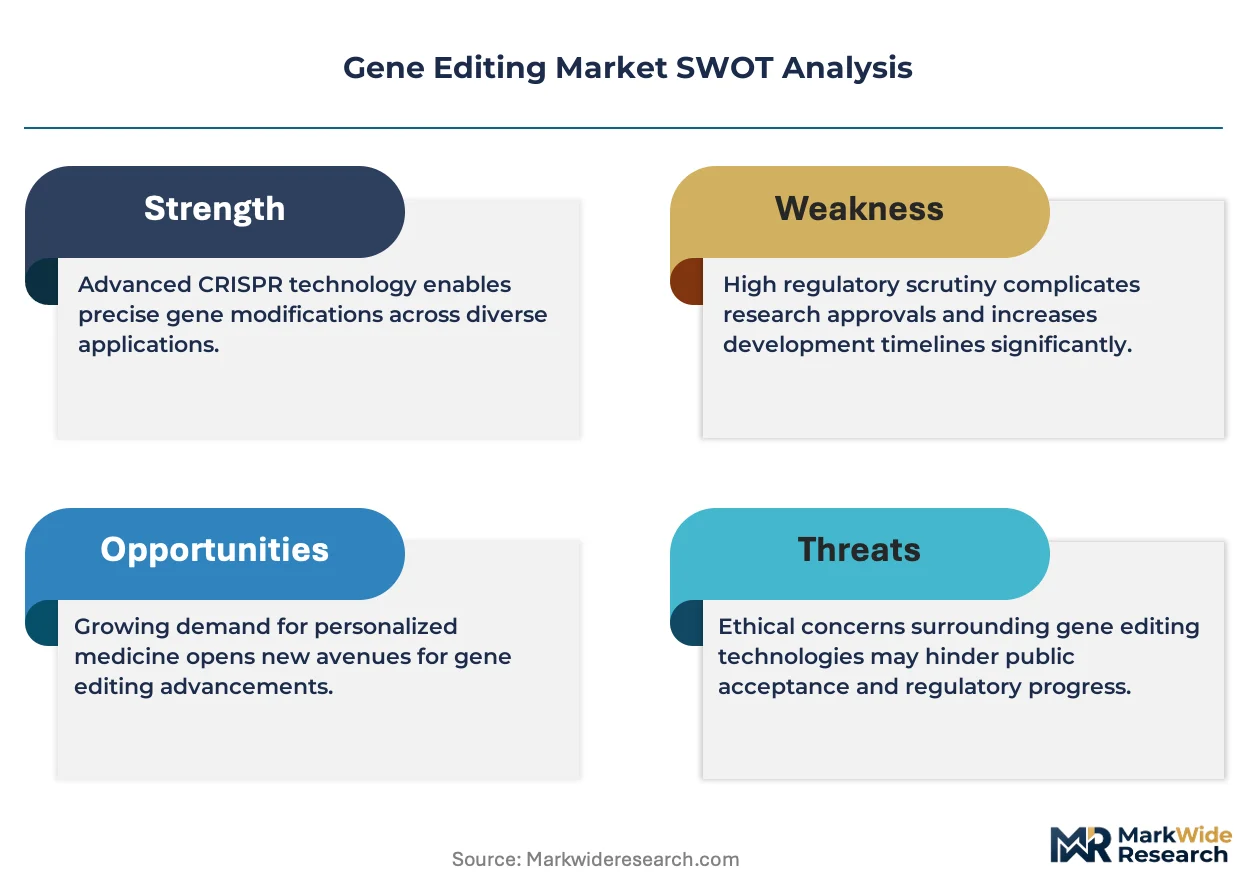
Gene editing encompasses programmable nuclease systems, base editors, and prime editors that introduce site-specific DNA modifications through guided molecular machinery operating at defined chromosomal loci. These technologies serve therapeutic correction of monogenic diseases, crop trait enhancement, and industrial strain optimization through precise genomic alteration. CRISPR product lines dominate current revenue pools owing to licensing breadth and tool-kit standardization across academic and commercial labs. Cell therapy applications within the technology segment attract the fastest expansion of manufacturing capacity and regulatory filing activity. Agricultural end users represent a maturing demand channel where trait-stacking workflows and regulatory clearance timelines now determine margin capture more than technical feasibility alone.
The FDA maintains active guidance on gene therapy CMC requirements while the EMA applies its ATMP framework to assess edited-cell product quality and long-term follow-up obligations. China's NMPA has issued technical review standards for gene-editing therapies that shape trial design for sponsors seeking simultaneous East-West development paths. Stakeholders must monitor how reimbursement authorities in Germany, Japan, and the United States calibrate value thresholds for one-time curative interventions against chronic management alternatives.
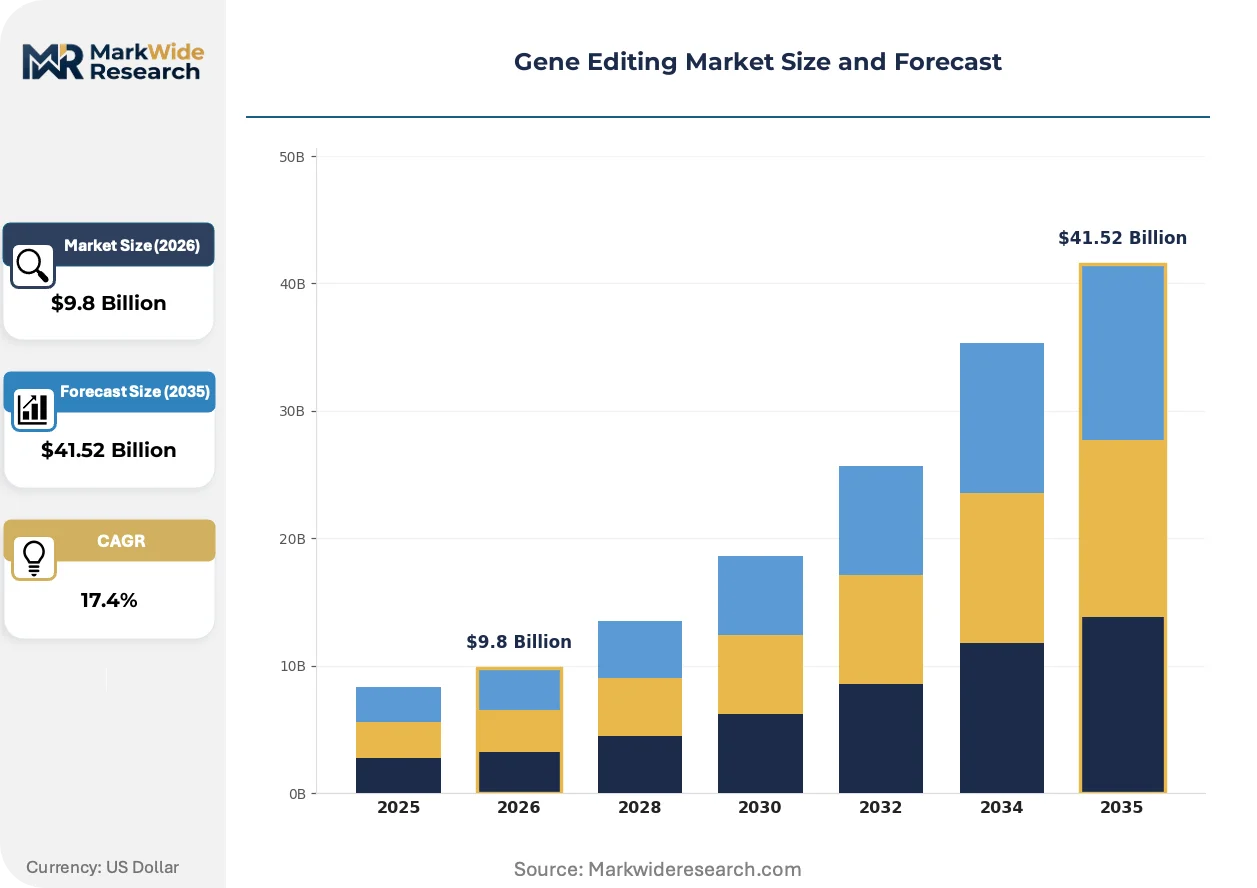
Market Dynamics
Milestone-based clinical partnerships are concentrating capital among gene editing sponsors capable of funding multi-year CMC development, compressing the competitive field before pivotal trial readouts.
Growth Catalysts
- ATMP Framework Expansion:The EMA's adaptive pathway designations for advanced therapy medicinal products shorten regulatory timelines for autologous cell therapies, accelerating sponsor investment in manufacturing scale-up.
- Base Editing Maturation:Cytosine and adenine base editors now enable single-nucleotide corrections without double-strand breaks, expanding addressable disease targets beyond those tractable with first-generation CRISPR nucleases.
- United States Trial Density:Clustered academic medical centers in Boston, San Francisco, and Research Triangle Park generate patient access advantages that concentrate Phase I/II activity on American soil.
Market Restraints
- Plasmid DNA Supply Concentration:GMP-grade plasmid manufacturing capacity concentrates among three contract manufacturers in the United States and Europe, creating single-source vulnerability for viral vector production.
- Long-Term Follow-Up Burden:FDA guidance mandates 15-year post-treatment monitoring for germline-editing exposure risks, imposing persistent cost structures on sponsors of curative interventions.
- Allogeneic Cell Immunogenicity:Host-versus-graft rejection mechanisms limit durability of donor-derived edited-cell products, constraining the market expansion that universal cell therapies promised.
Strategic Opportunities
- In Vivo Liver Editing:Lipid nanoparticle delivery systems now enable direct hepatic gene correction without ex vivo cell manipulation, opening therapeutic categories previously reserved for rare diseases with extractable cell types.
- Japan's Sakigake Designation:PMDA's priority review framework for regenerative medicines offers truncated approval timelines that reward first-mover sponsors with accelerated market access in the world's third-largest pharmaceutical market.
- Agricultural Trait Stacking:Multiplexed editing workflows allow seed developers to combine drought tolerance, disease resistance, and nutritional enhancement in single transformation events, differentiating premium germplasm offerings.
Industry Challenges
- GMP Manufacturing Workforce Scarcity:Cell therapy facilities in the United States and Europe compete for personnel with experience in closed-system bioreactor operation and automated cell processing platforms.
- IP Thicket Navigation:Overlapping patent estates covering CRISPR-Cas9, Cas12, and delivery modalities force sponsors into complex licensing negotiations before clinical candidate selection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gene Editing Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $41.52 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CRISPR, ZFN, TALEN, Antisense Oligonucleotide Application: Therapeutics, Agriculture, Industrial Biotechnology, Genomics End User: Pharmaceuticals, Academic Research, Biotechnology Firms, Agriculture Companies Technology: Gene Therapy, Genome Engineering, Cell Therapy, Synthetic Biology |
| Companies Covered | CRISPR Therapeutics, Intellia Therapeutics, Editas Medicine, Beam Therapeutics, Sangamo Therapeutics, Thermo Fisher Scientific, Merck KGaA, Lonza, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gene Editing Market Emerging Trajectories
Prime editing and epigenome editing platforms are collapsing the technical boundary between research tool and therapeutic modality, forcing rapid capability investment across the supplier base.
Prime editing deploys engineered reverse transcriptase fused to Cas9 nickase to install precise edits without donor DNA templates or double-strand breaks. Biopharmaceutical sponsors in the United States and Europe are advancing prime-edited candidates into IND-enabling studies at a pace that outstrips manufacturing protocol standardization. This capability is collapsing the historical distinction between small-molecule precision and gene therapy permanence, pressuring platform companies to defend technical differentiation through editing-fidelity metrics rather than intellectual property alone.
The FDA's 2024 update to gene therapy CMC guidance clarifies expectations for potency assay validation and comparability protocols following manufacturing changes. Sponsors must now demonstrate analytical correlation between pre- and post-change product attributes using orthogonal methods, increasing regulatory submission preparation timelines. Cell therapy developers with autologous pipelines face the steepest compliance burden, as patient-specific starting material complicates standardization of release criteria across manufacturing sites.
Academic medical centers are consolidating procurement authority for gene editing reagents through centralized core facilities, displacing individual laboratory purchasing decisions. Thermo Fisher Scientific and specialized distributors now compete for multi-year supply agreements with university procurement offices rather than principal investigator relationships. This concentration is most visible in the United States, where National Institutes of Health funding flows increasingly require documented cost efficiency in shared resource utilization.
Gene Editing Market Segmentation
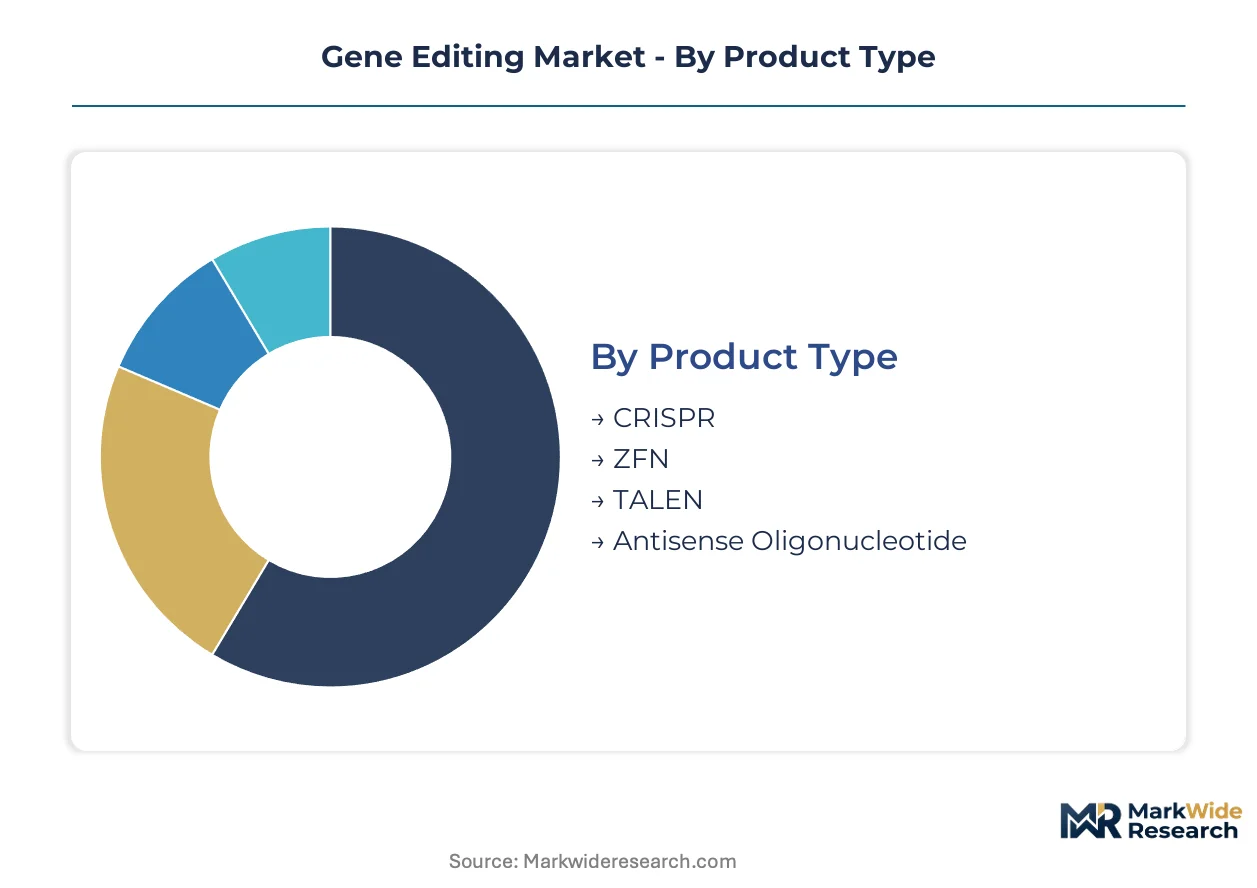
Gene editing market segmentation reveals how technical capabilities, therapeutic applications, and end-user requirements create distinct commercial pathways. Each dimension carries unique regulatory burdens, manufacturing constraints, and pricing dynamics that shape vendor strategy.
Product Type:
Mature nuclease platforms coexist with emerging precision editors, creating a technology stack where clinical validation and IP accessibility determine commercial traction.
- CRISPR:RNA-guided programmable nucleases dominate current therapeutic pipelines and research tool adoption due to licensing breadth and standardized protocols. Demand concentrates in United States biopharmaceutical development, where clustered academic medical centers accelerate IND filings for autologous cell therapies. The platform's modular architecture enables rapid retargeting across disease indications.
- Antisense Oligonucleotide:Synthetic nucleic acid strands modulate gene expression through mRNA targeting without permanent genomic alteration, serving chronic disease management where reversible intervention is preferred. European regulatory familiarity via EMA's ATMP framework sustains sponsor investment in liver-targeted delivery systems for metabolic disorders.
- ZFN:Zinc finger nucleases pioneered programmable genome editing but now serve niche applications where smaller protein size enables viral vector packaging constraints.
- TALEN:Transcription activator-like effector nucleases retain utility in agricultural trait engineering where off-target specificity requirements differ from human therapeutic standards.
CRISPR retains volume leadership; Antisense Oligonucleotide holds the steepest expansion curve.
Application:
Cost tier stratification separates curative interventions requiring manufacturing scale from research tools with lower regulatory barriers.
- Therapeutics:In vivo and ex vivo gene correction for monogenic diseases commands premium pricing tied to manufacturing complexity and clinical outcome durability. United States reimbursement authorities calibrate value thresholds against chronic management alternatives, while Japan's PMDA Sakigake designation accelerates market access for regenerative medicine sponsors.
- Agriculture:Trait-stacking workflows combine drought tolerance, disease resistance, and nutritional enhancement in single transformation events, differentiating premium germplasm offerings. Regulatory clearance timelines in major grain-exporting nations now determine margin capture more than technical feasibility alone.
- Industrial Biotechnology:Microbial strain optimization for enzyme production and biofuel pathways leverages precise genomic alteration to improve yield and reduce fermentation costs.
- Genomics:Research applications in functional genomics and disease model generation absorb standardized reagent kits with volume pricing sensitive to academic funding cycles.
Therapeutics commands the highest value per procedure; Agriculture is expanding most quickly as regulatory frameworks mature.
End User:
Customer type determines procurement authority concentration and technical support requirements across the value chain.
- Pharmaceuticals:Sponsors of gene-edited therapies require GMP-grade reagents, viral vector manufacturing partnerships, and regulatory consulting services bundled into milestone-based clinical contracts. United States and European sponsors dominate therapeutic development investment.
- Academic Research:Principal investigators at clustered academic medical centers in Boston, San Francisco, and Research Triangle Park generate demand for research-use-only kits and shared core facility access.
- Biotechnology Firms:Platform companies developing proprietary editing technologies or delivery modalities require custom synthesis services and IP navigation support.
- Agriculture Companies:Seed developers and crop protection firms prioritize trait-stacking capabilities and regulatory dossier preparation for multi-jurisdiction approval.
Pharmaceuticals retains volume leadership; Biotechnology Firms holds the steepest expansion curve.
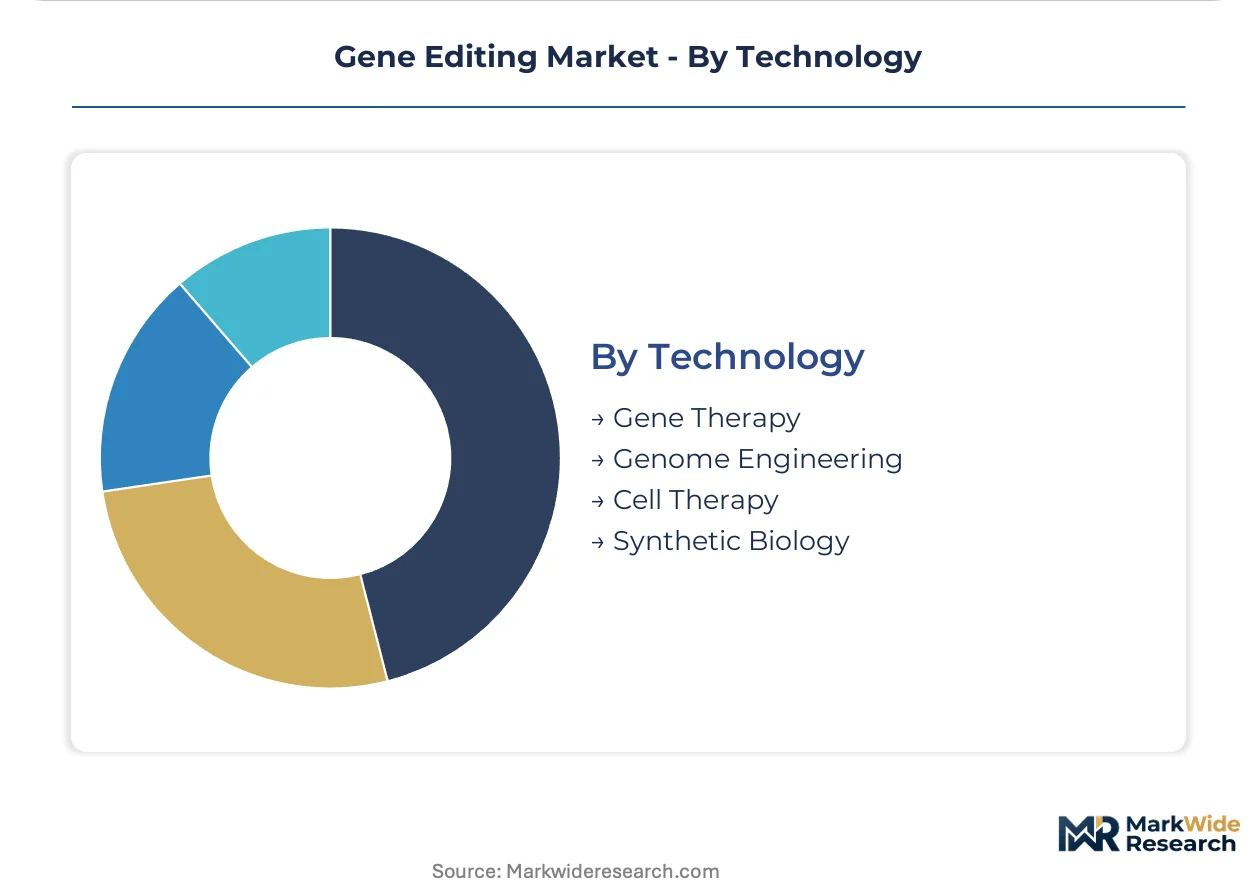
Technology:
Supply concentration distinguishes modalities requiring patient-specific manufacturing from those enabling universal product approaches.
- Gene Therapy:Viral and non-viral delivery of therapeutic genetic material addresses inherited monogenic disorders, with FDA guidance on CMC requirements shaping sponsor investment in potency assay validation. Long-term follow-up obligations for germline-editing exposure risks impose persistent cost structures.
- Cell Therapy:Autologous and allogeneic edited-cell products face manufacturing scale constraints and host-versus-graft rejection mechanisms that limit durability of donor-derived approaches. GMP manufacturing workforce scarcity in United States and European facilities intensifies competition for closed-system bioreactor expertise.
- Genome Engineering:Research and agricultural applications of programmable nucleases operate with lower regulatory barriers and faster iteration cycles than human therapeutic deployment.
- Synthetic Biology:Design-build-test cycles for engineered biological systems integrate gene editing with metabolic pathway optimization for industrial and therapeutic endpoints.
Gene Therapy retains volume leadership; Cell Therapy holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gene editing reagents and therapeutic candidates flow predominantly from United States and European manufacturing hubs toward clinical trial sites in East Asia and emerging markets. Import dependence for GMP-grade plasmid DNA concentrates risk in trans-Atlantic supply chains while China's NMPA accelerates domestic trial approvals.
United States
FDA's 2024 gene therapy CMC guidance shapes sponsor investment in potency assay validation and comparability protocols. The agency's 15-year post-treatment monitoring mandate for germline-editing exposure risks imposes persistent cost structures on curative interventions. Boston, San Francisco, and Research Triangle Park host the densest concentration of Phase I/II clinical activity, with academic medical centers generating patient access advantages that concentrate early-stage development on American soil.
Germany
EMA's ATMP framework applies adaptive pathway designations that shorten regulatory timelines for autologous cell therapies, accelerating manufacturing scale-up investments. The country's national pharmaceutical regulator emphasizes long-term follow-up obligations for edited-cell product quality assessment. Heidelberg and Munich anchor industrial clusters where contract manufacturers compete for closed-system bioreactor expertise amid GMP workforce scarcity.
China
NMPA technical review standards for gene-editing therapies shape trial design for sponsors seeking simultaneous East-West development paths. The regulator's alignment with international ICH guidelines facilitates multi-regional clinical trial participation. Shanghai and Suzhou biotech parks concentrate domestic platform companies developing proprietary delivery modalities and base-editing technologies.
Japan
PMDA's Sakigake designation for regenerative medicines offers truncated approval timelines that reward first-mover sponsors with accelerated market access. METI coordinates national investment in cell therapy manufacturing infrastructure to reduce import dependence. The Kanto region around Tokyo hosts the principal concentration of clinical research organizations managing edited-cell trial execution.
Switzerland
Swissmedic applies streamlined procedures for ATMP assessment that attract sponsor headquarters relocation from broader European markets. The regulator's scientific advice meetings enable early alignment on CMC requirements for prime-editing candidates. Basel's pharmaceutical cluster integrates gene editing into existing biologics manufacturing infrastructure, leveraging captive viral vector production capabilities.
Gene Editing Market Vendor Landscape
On the supply side, the industry is bifurcated between therapeutic developers owning end-to-end pipelines and reagent suppliers competing on manufacturing scale. Platform biotechnology companies concentrate around CRISPR and base-editing modalities, while diversified life sciences conglomerates dominate consumables and analytical instrumentation. Three strategic archetypes prevail: vertically integrated therapeutic sponsors, contract manufacturing organizations with captive GMP facilities, and research-tool vendors competing through distribution breadth. Competitive intensity manifests in milestone-based clinical partnerships and multi-year supply agreements with academic core facilities.
Among therapeutic developers, CRISPR Therapeutics, Editas Medicine, and Intellia Therapeutics occupy positions as archetypal platform sponsors, each representing distinct strategic bets on ex vivo versus in vivo editing modalities. Thermo Fisher Scientific anchors the reagent supply tier through scale-driven competition for centralized university procurement contracts. Beam Therapeutics exemplifies the base-editing specialization archetype, while Merck KGaA and Lonza represent European contract manufacturing and service provision. These named entities illustrate how technical differentiation and manufacturing footprint, rather than therapeutic ownership alone, determine competitive positioning across the value chain.
| Leading Market Players |
|---|
| CRISPR Therapeutics |
| Intellia Therapeutics |
| Editas Medicine |
| Beam Therapeutics |
| Sangamo Therapeutics |
| Thermo Fisher Scientific |
| Merck KGaA |
| Lonza |
| Agilent Technologies |
| Others |
Supply Flow & Price Mechanics
GMP-grade plasmid DNA undercapacity across United States and European contract manufacturing facilities drives supplier pricing power while forcing therapeutic sponsors into long-term offtake commitments. This utilization squeeze propagates through viral vector production costs and shapes how cell therapy developers negotiate milestone-based clinical partnerships.
Pricing Analysis
Pharmaceutical sponsors anchor value-based pricing for autologous cell therapies against chronic management alternatives. Three-tier pricing structure across premium GMP-grade reagents, validated research-use kits, and bulk industrial enzymes reflects certification grade and manufacturing scale. Cost compression in research-use reagents is intensifying because academic core facility procurement consolidation demands volume discounts. Biotechnology firms exhibit highest price sensitivity due to constrained venture funding cycles, while large pharmaceutical sponsors absorb premium pricing for regulatory-ready materials.
Supply Chain Analysis
Export control regimes governing dual-use gene editing technologies restrict CRISPR-Cas9 plasmid flows between United States and Chinese biotechnology clusters. GMP manufacturing capacity concentrates in the United States, Germany, and Switzerland, drawing from specialized fermentation media, single-use bioreactor components, and synthetic guide RNA chemistries. Single-source vulnerability for plasmid DNA creates supply chain risk as three contract manufacturers dominate trans-Atlantic production. Distribution runs through milestone-based clinical supply agreements rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gene editing market is entering a cyclical recovery phase as FDA and EMA accelerated pathway designations restore sponsor confidence following regulatory guidance clarity. Base editing and prime editing platform maturation is compressing development timelines and attracting renewed capital deployment.
For Market Incumbents: Harden manufacturing footprint control through captive GMP facility investments in Boston and Research Triangle Park clusters. Lock in multi-year plasmid DNA supply agreements before contract manufacturer capacity saturates. Defend against emerging base-editing specialists by accelerating in vivo liver editing programs through lipid nanoparticle delivery partnerships.
For New Entrants and Emerging Players: Agricultural trait stacking in drought-resistant grain varieties represents the most penetrable entry point given maturing regulatory frameworks in major exporting nations. Japan's PMDA Sakigake designation pathway for regenerative medicines offers truncated approval timelines for first-mover sponsors. Pursue direct licensing to seed developers rather than building captive germplasm pipelines.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across autologous cell therapy manufacturing as closed-system bioreactor automation demands scale investments. Five-to-ten year viability favors platform companies with differentiated delivery modalities and established CMC regulatory correspondence. Monitor FDA potency assay validation guidance updates as the signal indicating which sponsors will face delayed IND timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive GMP facilities in United States academic medical center clusters reduce plasmid DNA supply risk. |
| Regulatory Approval Pathway | EMA ATMP adaptive designations compress autologous cell therapy development timelines for European market access. |
| Platform Integration | Base editing and prime editing convergence collapses boundaries between research tools and therapeutic modalities. |
| Long-term Supply Agreement | Multi-year reagent contracts with academic core facilities displace individual laboratory purchasing decisions. |
| Geographic Expansion | Japan Sakigake designation pursuit accelerates regenerative medicine market entry in the third-largest pharmaceutical market. |
Methodological Framework
Desk research of FDA gene therapy CMC guidance documents, EMA ATMP framework publications, and ClinicalTrials.gov registry entries preceded structured interviews with cell therapy manufacturing executives, regulatory affairs leads at gene editing sponsors, academic core facility directors, and GMP contract manufacturer operations managers. Secondary validation drew from SEC biopharmaceutical filings, NIH funding databases, and patent estate landscaping. Bottom-up therapeutic pipeline enumeration and top-down market sizing triangulated volume estimates.
Assumptions held fixed across the projection horizon include current FDA 15-year post-treatment monitoring mandates and existing EMA ATMP pathway structures. Segmentation dimensions modeled encompass editing modality, therapeutic application, delivery mechanism, and regional regulatory cluster. CAGRs were derived from sponsor-reported clinical trial advancement rates and manufacturing capacity expansion announcements. Forecast inputs incorporated base editing platform maturation curves and lipid nanoparticle delivery system adoption trajectories.
Stress conditions across plasmid DNA manufacturing capacity utilization, germline editing regulatory restrictions, and allogeneic cell immunogenicity resolution timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding reimbursement authority value threshold calibration. Material shifts in FDA gene therapy CMC guidance or EMA long-term follow-up obligation requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
CRISPR Gene Detection and Diagnostic Market
Gene Editing & CRISPR
North America Gene Synthesis Market
Gene Editing & CRISPR
UK Gene Editing Market
Gene Editing & CRISPR
Japan Gene Editing Market
Gene Editing & CRISPR
US Gene Editing Market
Gene Editing & CRISPR
Cas9 Nuclease Market
Gene Editing & CRISPR
South Korea Gene Editing Market
Gene Editing & CRISPR
Global CRISPR and Cas Genes Market
Gene Editing & CRISPR
Knock Out Mouse Model Market
Gene Editing & CRISPR
Zinc Finger Nuclease Technology Market
Gene Editing & CRISPR
Immunodeficient Mouse Models Market
Gene Editing & CRISPR
Genome Engineering Market
Gene Editing & CRISPR
Global CRISPR and CRISPR-Associated (Cas) Genes Market
Gene Editing & CRISPR
China Gene Editing Market
Gene Editing & CRISPR
Global Recombinant DNA (Rdna) Technology Market
Gene Editing & CRISPR
Genetically Modified Animal Model Market