
 HDPE Large Blow Molded Products Market | 2026-2036
HDPE Large Blow Molded Products Market Size, Share, and Industry Trends Forecast 2026-2036
HDPE Large Blow Molded Products Market Outlook
Co-extrusion and multi-layer barrier technology is tilting manufacturing economics toward higher-performance HDPE tanks and containers. Greif leverages captive resin sourcing and backward integration into industrial packaging formats across North American chemical corridors. Mauser Group anchors its position through reusable intermediate bulk container systems that compete on total cost of ownership rather than unit price. Plastipak Packaging dominates food-grade blow molding with in-house preform and bottle production lines that sustain margin control.
HDPE large blow molded products are fabricated through extrusion blow molding of high-density polyethylene resin with melt indices typically between 0.2 and 0.5 g/10min, producing hollow structures ranging from 20-liter containers to 1,000-liter intermediate bulk tanks for liquid and powder containment. Containers and tanks command the largest volume share as chemical and agricultural buyers standardize on polymer alternatives to steel drums for corrosion resistance and weight reduction. The chemicals application segment generates premium pricing due to UN-certified designs and multi-layer barrier requirements, while food and beverage applications face stricter migration limits that differentiate compliant suppliers. Custom capacity configurations are expanding fastest as original equipment manufacturers specify dimensional tolerances for automated filling and handling lines.
The EPA regulates industrial container emissions and recycling mandates under RCRA hazardous waste provisions, while REACH and the EU F-Gas Regulation restrict certain additive chemistries and mandate recyclability disclosures for packaging placed on European markets. India's BIS certification requirements for plastic containers used in food contact and chemical transport create compliance thresholds that filter smaller molders from institutional supply chains. Stakeholders must monitor how extended producer responsibility frameworks and recycled content mandates in multiple jurisdictions reshape resin specifications and tooling investments.
Market Dynamics
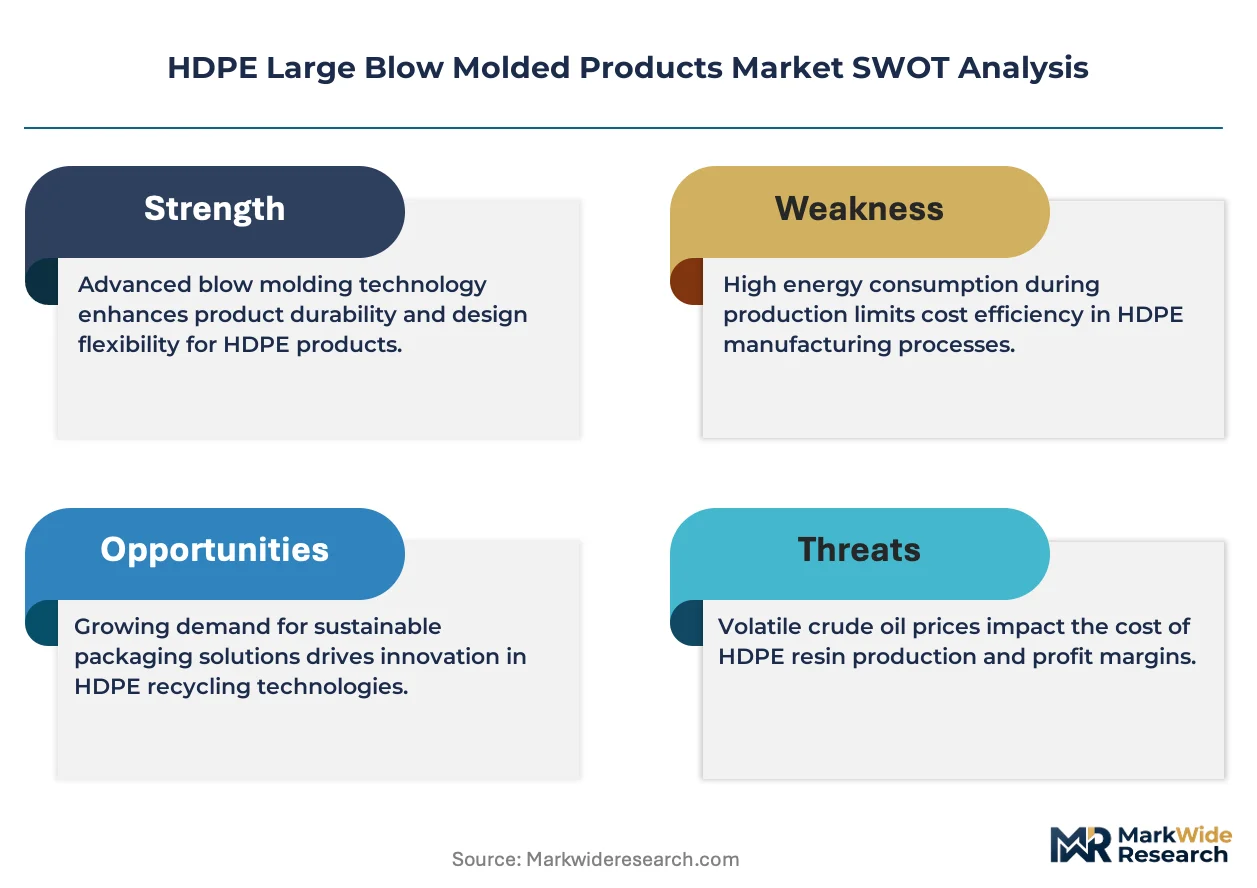
Co-extrusion barrier technology is compressing margins for single-layer molders while rewarding multi-layer specialists with UN-certified chemical container contracts. The shift from steel to polymer bulk packaging is accelerating tooling replacement cycles across chemical corridors in Germany, India, and the United States.
Growth Catalysts
- REACH and EU F-Gas Regulation:These frameworks mandate recyclability disclosures and restrict certain additive chemistries, filtering non-compliant suppliers from European institutional supply chains and expanding addressable market share for certified molders.
- Agricultural tank replacement cycles:Farmers in the United States and India are standardizing on HDPE alternatives to metal tanks for corrosion resistance and weight reduction, driving volume in 500-liter to 1,000-liter capacity segments.
- Co-extrusion blow molding:Multi-layer barrier technology enables oxygen and moisture protection previously requiring metal or glass, opening food-grade and agrochemical applications with stricter permeation specifications.
Market Restraints
- Resin price volatility:Ethylene feedstock costs fluctuate with crude oil benchmarks, squeezing margin predictability for molders without captive resin sourcing or long-term supply agreements.
- Tooling capital intensity:Multi-layer co-extrusion dies and precision mold fabrication require seven-figure investments that exclude smaller regional molders from premium chemical container segments.
- Metal drum residual preference:Certain hazardous chemical shippers in India and Germany retain steel drum specifications for extreme temperature or pressure applications, limiting polymer penetration in niche UN-certified categories.
Strategic Opportunities
- India BIS certification expansion:The Bureau of Indian Standards is tightening food contact and chemical transport container requirements, creating compliance thresholds that reward early-investing molders with institutional supply chain lock-in.
- Recycled content mandates:Extended producer responsibility frameworks in Germany and California are forcing brand owners to source post-consumer HDPE, creating premium pricing tiers for molders with integrated recycling and flake processing capabilities.
- Automated filling line integration:Original equipment manufacturers in the United States are specifying dimensional tolerances for robotic handling systems, opening custom engineering contracts for molders with precision metrology and rapid prototyping services.
Industry Challenges
- Multi-layer process engineering talent:Co-extrusion die design and barrier layer adhesion control require specialized polymer science expertise that concentrates in German and United States technical centers, creating recruitment bottlenecks for expanding facilities.
- UN certification timeline compression:Chemical container approvals now require accelerated drop-test and permeation validation cycles, straining testing laboratory capacity and delaying revenue recognition for new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HDPE Large Blow Molded Products Market |
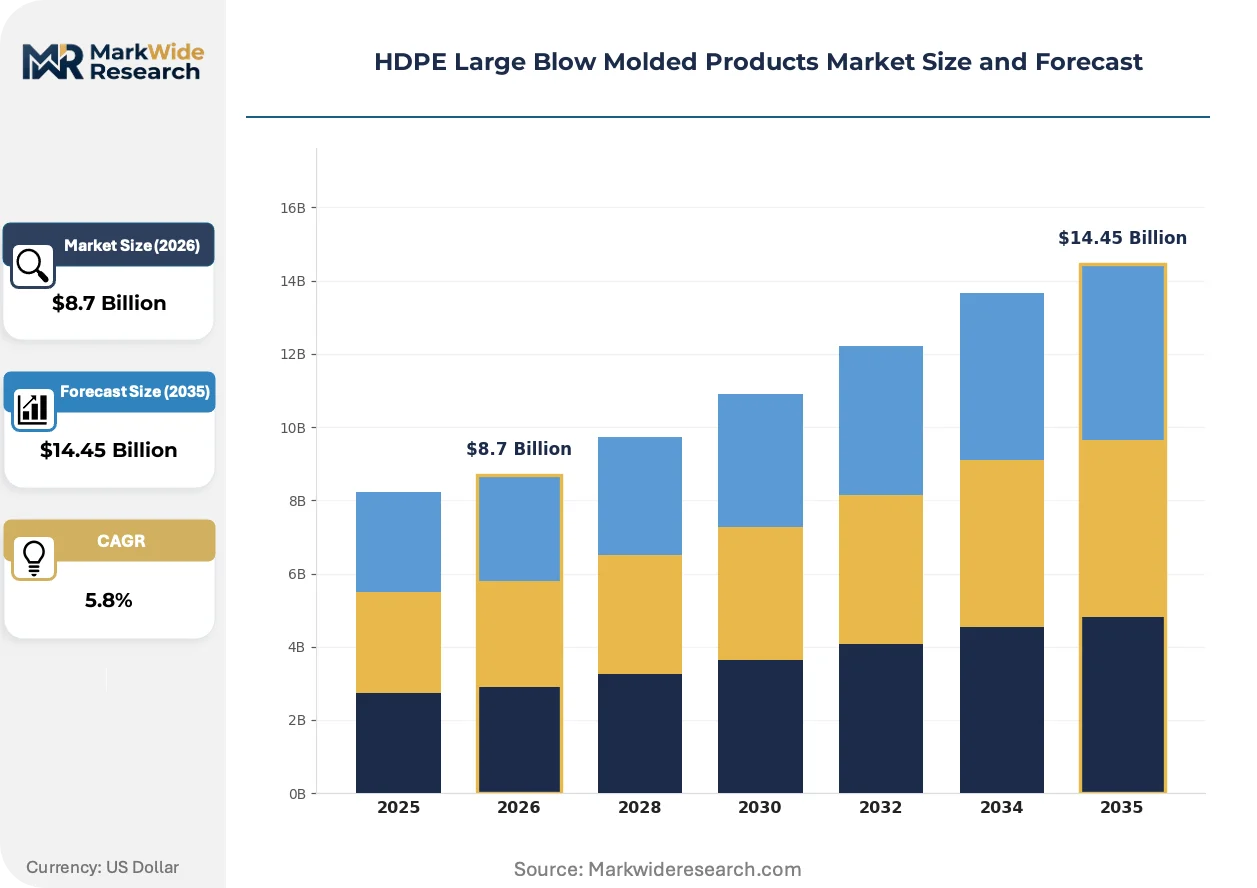
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containers, Tanks, Pallets, Bottles Application: Agriculture, Industrial, Food & Beverage, Chemicals End User: Manufacturers, Distributors, Retailers, Exporters Capacity: Small, Medium, Large, Custom |
| Companies Covered | Time Technoplast, ALPLA Group, Greif, Mold Tek Packaging, Plastipak Packaging, Mauser Group, Berry Global, Takween Advanced Industries, SchuTz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HDPE Large Blow Molded Products Market Strategic Shifts
Material science advances and regulatory stringency are converging to reshape competitive positioning in large blow molded packaging. Three forces are actively restructuring how value is captured across the value chain.
Multi-layer co-extrusion with ethylene vinyl alcohol barrier layers is rendering obsolete single-layer HDPE tanks in oxygen-sensitive chemical and food applications. Agricultural cooperatives and specialty chemical distributors are specifying these structures for multiyear storage reliability. The technology is compressing addressable market share for commodity molders while expanding margin pools for barrier-certified specialists.
REACH substance restrictions and the EU F-Gas Regulation are prohibiting certain phthalate plasticizers and fluorinated additives in packaging placed on European markets. Molders serving German chemical corridors are reformulating resin compounds and requalifying supply chains to maintain market access. Food-grade applications face the steepest compliance burden, with migration limit documentation now required for each production batch.
Buyers are consolidating vendor relationships around total cost of ownership metrics rather than unit price comparisons. Chemical processors in the United States are awarding multi-year container supply contracts to molders offering integrated logistics, cleaning, and tracking services. This bundling is displacing transactional spot purchasing in intermediate bulk container categories and concentrating volume with vertically integrated suppliers.
HDPE Large Blow Molded Products Market Segmentation
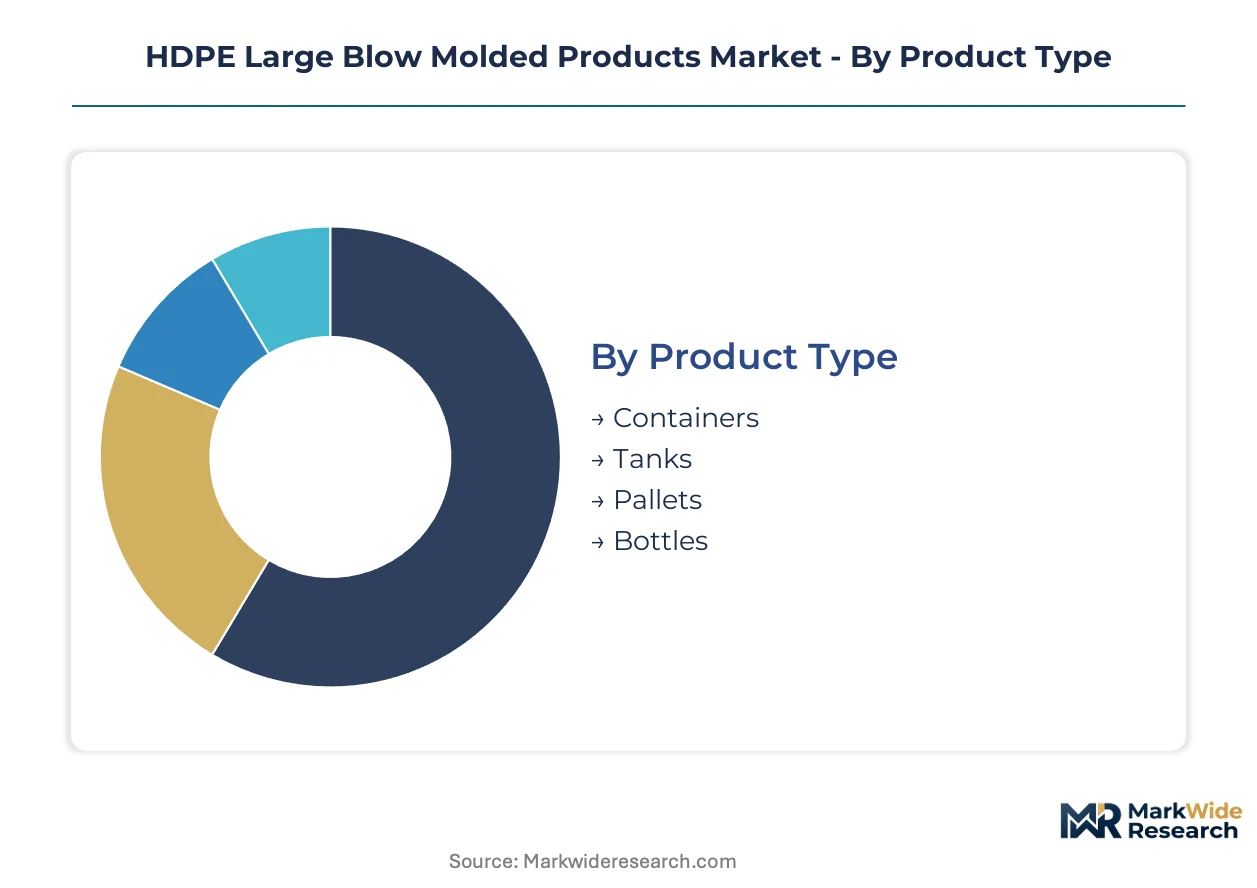
HDPE large blow molded products fragment across four distinct dimensions. Product geometry determines tooling investment and barrier specifications. Application verticals impose divergent regulatory compliance burdens that reshape supplier economics.
Product Type:
Cost tier separates commodity hollowware from engineered containment systems with multi-layer specifications.
- Containers:Intermediate bulk containers and drum formats dominate chemical logistics with UN-certified designs. German and United States chemical corridors concentrate demand as shippers replace steel with polymer alternatives for corrosion resistance and weight reduction.
- Tanks:Agricultural and industrial storage vessels range from 500-liter to 1,000-liter capacities with co-extrusion barrier layers for multiyear chemical storage. Farmers in India and the United States are standardizing on these formats, driving volume in replacement cycles for metal tank infrastructure.
- Pallets:Structural load-bearing platforms integrate with container systems for automated handling lines.
- Bottles:Food-grade and industrial packaging formats with preform-based production economics.
Containers hold installed capacity. Tanks are rotating up the share rankings.
Application:
Regulatory stringency creates margin stratification across end-use verticals.
- Chemicals:UN-certified intermediate bulk containers and drums require multi-layer barrier technology and accelerated drop-test validation. REACH and EPA RCRA provisions mandate recyclability disclosures and restrict additive chemistries, filtering non-compliant suppliers from institutional supply chains.
- Agriculture:Spray tanks, nutrient storage vessels, and transport containers specify corrosion-resistant HDPE alternatives to metal. Agricultural cooperatives in the United States and India are consolidating vendor relationships around total cost of ownership metrics rather than unit price comparisons.
- Industrial:General-purpose containment and material handling applications with standardized specifications.
- Food & Beverage:Migration limit documentation and batch-level compliance create the steepest regulatory burden among all application verticals.
Chemicals commands premium positioning. Agriculture is climbing the fastest.
End User:
Procurement scale and technical specification authority vary sharply across buyer categories.
- Manufacturers:Original equipment manufacturers and chemical processors specify dimensional tolerances for automated filling and handling lines. These buyers award multi-year contracts to molders offering integrated logistics, cleaning, and tracking services.
- Distributors:Agricultural supply and chemical logistics intermediaries consolidate volume around reusable container programs.
- Retailers:End-market packaging buyers with standardized volume requirements.
- Exporters:Shippers navigating UN certification and cross-border regulatory compliance.
Manufacturers anchor contract value. Distributors are gaining procurement influence.
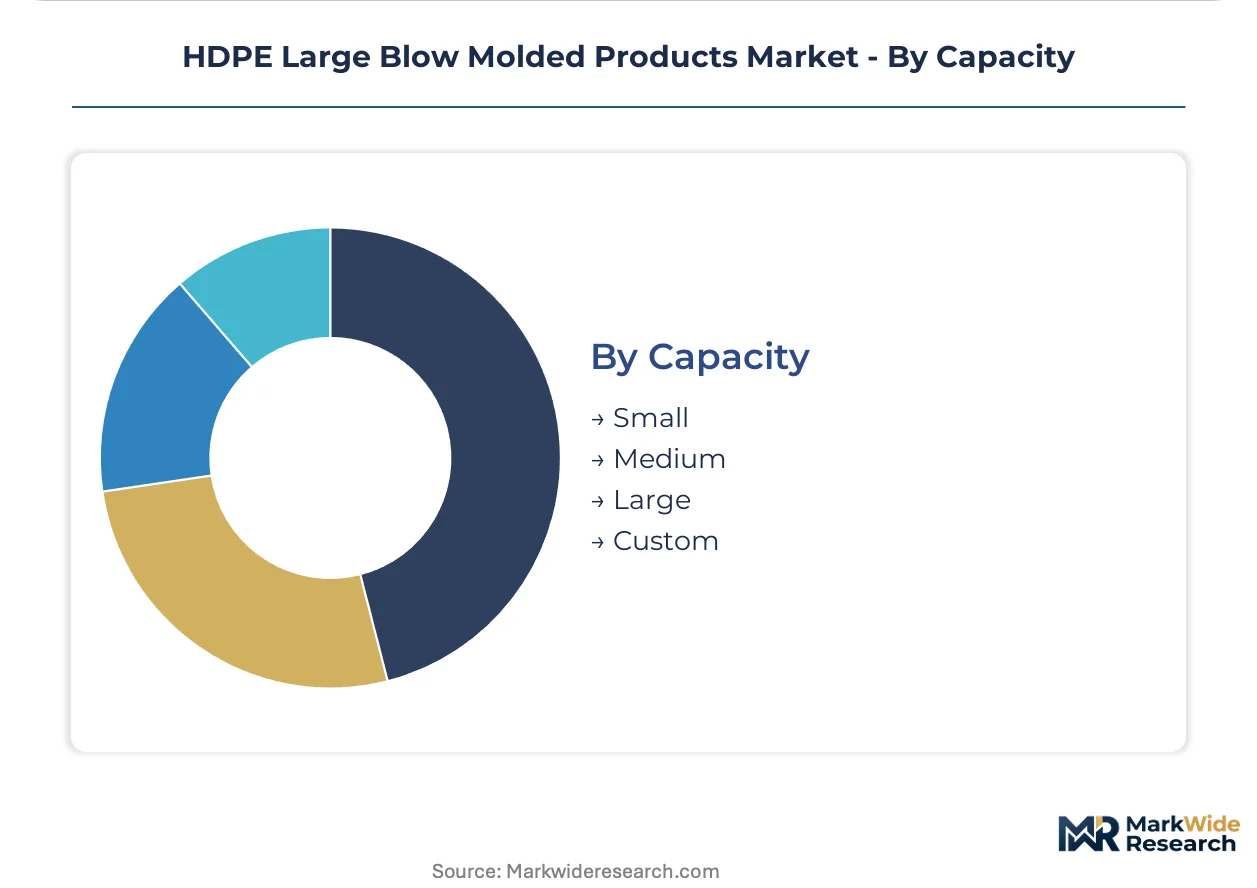
Capacity:
Volume segmentation aligns with automation economics and custom engineering capabilities.
- Custom:Original equipment manufacturers specify dimensional tolerances for robotic handling systems, opening engineering contracts for molders with precision metrology and rapid prototyping services. This segment concentrates in United States manufacturing clusters serving automated production lines.
- Large:500-liter to 1,000-liter tanks for agricultural and chemical storage with standardized barrier specifications.
- Medium:Intermediate drum and container formats with balanced tooling efficiency and application flexibility.
- Small:Bottles and compact containers with high-volume preform production economics.
Custom configurations command engineering premiums. Large capacity is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical corridors export UN-certified intermediate bulk containers to processors across the Netherlands and Belgium, while Indian molders supply agricultural tanks to Southeast Asian farming cooperatives. This trade-flow architecture concentrates manufacturing capacity in three national clusters where regulatory stringency and raw material access intersect.
Germany
Chemical processors along the Rhine-Main corridor drive demand for multi-layer barrier containers as they replace steel drums with polymer alternatives. The EU F-Gas Regulation and REACH compliance standards restrict additive chemistries and mandate recyclability disclosures for all packaging placed on European markets. Production concentrates in North Rhine-Westphalia, where molders serve BASF and Bayer supply chains with UN-certified designs.
United States
Agricultural cooperatives in Iowa and Illinois are standardizing on HDPE spray tanks and nutrient storage vessels, displacing corroded metal infrastructure from the 1990s. EPA RCRA hazardous waste provisions regulate industrial container emissions and mandate recycling infrastructure for chemical packaging. Manufacturing clusters in Texas and Louisiana leverage proximate ethylene feedstock from Gulf Coast petrochemical complexes.
India
Farmers in Maharashtra and Gujarat are consolidating vendor relationships around 500-liter to 1,000-liter HDPE tanks for corrosion resistance and weight reduction in transport applications. BIS certification requirements for plastic containers used in food contact and chemical transport filter smaller molders from institutional supply chains. Mold Tek Packaging and Time Technoplast anchor production in Pune and Hyderabad, serving domestic agrochemical distributors.
China
Industrial packaging demand from Yangtze River Delta chemical processors is accelerating as state-owned enterprises modernize bulk logistics infrastructure. GB standards for plastic containers used in hazardous material transport impose testing protocols that parallel UN certification requirements. Manufacturing concentrates in Jiangsu and Zhejiang provinces, where molders supply Sinopec and private chemical conglomerates.
Brazil
Agricultural exporters in São Paulo state require corrosion-resistant storage tanks for fertilizer and agrochemical handling ahead of soybean planting cycles. ANVISA regulates food-contact plastic containers while the national environmental agency oversees chemical packaging disposal frameworks. Production clusters in São Paulo and Rio Grande do Sul serve Mercosur trade corridors with standardized drum and intermediate bulk container formats.
HDPE Large Blow Molded Products Market Competitive Environment
On the supply side, the industry is consolidating around three distinct capability tiers: integrated resin-to-container operators, specialized multi-layer barrier molders, and regional commodity fabricators. German and United States-based players dominate UN-certified chemical packaging through captive resin sourcing and backward integration into industrial formats. Indian specialists capture agricultural tank volume through cost-optimized single-layer production. The dominant competitive moves are vertical integration into resin compounding and geographic expansion through distributor partnerships in emerging chemical corridors.
Within the integrated industrial packaging tier, Greif exemplifies the North American model of captive resin sourcing and logistics bundling, while Mauser Group anchors European reusable intermediate bulk container systems that compete on total cost of ownership metrics. Plastipak Packaging occupies a position in food-grade blow molding with in-house preform production lines that sustain margin control against commodity competitors. These three players represent how scale and vertical integration separate premium-tier suppliers from regional fabricators.
| Leading Market Players |
|---|
| Time Technoplast |
| ALPLA Group |
| Greif |
| Mold Tek Packaging |
| Plastipak Packaging |
| Mauser Group |
| Berry Global |
| Takween Advanced Industries |
| SchuTz |
| Others |
Value Chain & Pricing Dynamics
Gulf Coast ethylene cracker concentration in the United States funnels pricing power to resin-integrated molders while squeezing margin pools for converters buying spot polyethylene. This upstream clustering concentrates cost leverage among three North American operators who supply German and Indian chemical corridors through long-term offtake structures.
Pricing Analysis
Single-layer commodity molding, multi-layer barrier systems, and next-generation recycled-content tanks occupy distinct pricing tiers with widening spreads. Three-tier pricing structure across premium, standard, and economy levels reflects UN certification grade and captive resin access as primary differentiation drivers. Cost compression in commodity drum segments is intensifying because Indian and Chinese spot buyers arbitrage regional ethylene spreads. Agricultural cooperatives exhibit highest price sensitivity while chemical processors purchasing UN-certified intermediate bulk containers prioritize total cost of ownership metrics over unit pricing.
Supply Chain Analysis
Ethylene feedstock draws from United States Gulf Coast, Saudi Arabian crackers, and Northwest European naphtha complexes as the three dominant upstream nodes. HDPE resin, co-extrusion barrier additives, and precision-machined mold tooling represent critical input dependencies. Single-source vulnerability concentrates in German multi-layer die engineering talent pools where three specialized fabricators control barrier technology licensing. Distribution runs through chemical corridor logistics hubs in North Rhine-Westphalia, Texas, and Maharashtra with integrated container cleaning and tracking services displacing transactional spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive positioning through regulatory entrenchment. REACH certification timelines and UN drop-test validation create switching costs that lock institutional buyers into qualified supplier relationships.
For Market Incumbents: Entrench barrier technology leadership by acquiring German co-extrusion die engineering capabilities before recruitment bottlenecks tighten further. Expand captive resin compounding in Texas and Louisiana to offset ethylene price volatility threatening margin predictability. Chemical processors consolidating vendor relationships around integrated logistics services represent the most defensible revenue base against emerging Indian cost competitors. For New Entrants and Emerging Players: Agricultural tank replacement cycles in Maharashtra and Gujarat represent the most penetrable entry point given BIS certification thresholds still filtering smaller molders from institutional supply chains. Mid-cap Indian distributors seeking second-source security for 500-liter to 1,000-liter nutrient storage vessels offer partnership pathways without direct confrontation with integrated incumbents. Target precision metrology services for United States original equipment manufacturers specifying robotic handling tolerances as a engineering-led beachhead. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier molders with BIS certification lock-in and established distributor relationships in Indian agricultural corridors. Five-to-ten year viability hinges on recycled content mandate compliance capabilities as extended producer responsibility frameworks reshape resin specifications across German and California markets. Watch for inflection signals in UN certification laboratory capacity constraints accelerating revenue recognition delays for new product launches.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive ethylene sourcing insulates margin pools from Gulf Coast feedstock volatility affecting spot buyers. |
| Multi-Layer Barrier Technology Licensing | German die engineering partnerships unlock UN-certified chemical container contracts with premium pricing tiers. |
| BIS Certification Pre-Positioning | Early compliance investment locks institutional supply chain access as Indian standards tighten filtration thresholds. |
| Integrated Logistics Service Bundling | Container cleaning and tracking services displace transactional purchasing among United States chemical processors. |
| Recycled Content Processing Capacity | Post-consumer HDPE flake capabilities capture premium pricing under California and German extended producer responsibility mandates. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured interviews with plant managers at chemical processors, procurement leads at agricultural cooperatives, distribution channel partners in German and Indian corridors, and technical R&D directors specializing in barrier layer adhesion. Secondary validation incorporated customs and trade data from ACC and Cefic, SEC 10-K filings from integrated packaging operators, and BIS certification registries. Bottom-up volume modeling triangulated against top-down ethylene consumption benchmarks.
Calibration anchored volume and value outputs across the analysis window to actual production capacity announcements and resin supply agreements. Segmentation dimensions modeled include product geometry tier, application vertical regulatory burden, end-user procurement scale, and regional production hub clustering. CAGRs were derived from slope-intercept analysis of disclosed capacity expansions and replacement cycle timing. Co-extrusion technology adoption curves and UN certification backlog durations served as industry-specific forecast inputs.
Practitioners should monitor ethylene cracker turnaround schedules and UN laboratory capacity expansion announcements for early signals of forecast revision triggers. Cross-checking against ACC resin shipment data and Cefic chemical packaging trade flows is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Europe Polyamide Market
Polymers & Resins
Italy Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Liquid Saturated Polyester Resin Market
Polymers & Resins
Geopolymer Market
Polymers & Resins
Petroleum Resins Market
Polymers & Resins
Polyphenylene Sulfide Market
Polymers & Resins
Polyester Polyol Market
Polymers & Resins
North America Geopolymer Market
Polymers & Resins
Copolyesters Market
Polymers & Resins
North America Linear Low-Density Polyethylene Market
Polymers & Resins
Chlorinated Polyvinyl Chloride (CPVC) Market
Polymers & Resins
Europe Thermoplastics Market
Polymers & Resins
South America Polyvinyl Chloride (PVC) Market
Polymers & Resins
Conditioning Polymers Market
Polymers & Resins
Global Polycarbonate Market
Polymers & Resins
Tie Layer Resin Market