
 Organoids and Spheroids Market | 2026-2036
Organoids and Spheroids Market Size, Share, and Industry Trends Forecast 2026-2036
Organoids and Spheroids Market Intelligence
The organoid and spheroid supply landscape is rebalancing between premium patient-derived models and commodity immortalized-cell spheroids used in high-throughput screening. Thermo Fisher Scientific leverages its end-to-end cell culture portfolio to anchor the premium tier with validated reagent-to-analytics workflows. STEMCELL Technologies Inc. specializes in organoid-specific media formulations that sustain differentiation protocols across gastrointestinal and neural lineages. Merck KGaA competes through its BioReliance testing services, which extend spheroid-based toxicology assays into regulatory submission packages for pharmaceutical clients.
Organoids and spheroids constitute self-organizing three-dimensional cellular aggregates derived from stem cells or primary tissues, typically ranging from 100 to 500 micrometers in diameter and cultivated within extracellular matrix scaffolds or suspension bioreactors to replicate organ-level physiology for disease modeling and compound screening. The drug discovery application segment leads current revenue contribution, as pharmaceutical companies replace two-dimensional cytotoxicity assays with liver and cardiac spheroid models that better predict human metabolism outcomes. Microfluidics-enabled organoid platforms represent the fastest-expanding technology category, integrating perfusion and real-time imaging to compress experimental timelines for biotech firms running lean R&D operations.
FDA's Center for Drug Evaluation and Research continues evaluating organoid data for investigational new drug applications, while EMA's Committee for Medicinal Products for Human Use refines qualification opinions on organoid-based biomarkers under the EU MDR framework. ISO technical committees are developing benchmark standards for spheroid reproducibility that will determine which contract research organizations gain preferred vendor status with multinational pharmaceutical sponsors. Stakeholders must monitor which regulatory jurisdiction first accepts organoid efficacy data as primary evidence, since that determination will redirect biopharma procurement toward compliant suppliers.
Market Dynamics
The transition from animal testing to human-relevant organoid models is compressing preclinical timelines and forcing pharmaceutical sponsors to requalify their contract research vendor panels.
Growth Catalysts
- FDA animal testing alternatives pathway:The Center for Drug Evaluation and Research's expanded acceptance of organoid efficacy data for investigational new drug applications accelerates sponsor investment in validated 3D culture platforms.
- Microfluidics integration:Perfusion-enabled organoid bioreactors reduce compound screening timelines from weeks to days, enabling lean biotech firms to compete with well-capitalized pharmaceutical R&D operations.
- German academic procurement:Helmholtz Association and Max Planck Institute clusters drive concentrated demand for neural and gastrointestinal organoid media formulations, anchoring European supplier expansion.
Market Restraints
- Matrigel supply concentration:Mouse sarcoma-derived basement membrane extracts dominate extracellular matrix scaffolds, creating single-source vulnerability for organoid culture standardization.
- ISO standardization lag:Pending benchmark standards for spheroid reproducibility delay preferred vendor designations by multinational pharmaceutical sponsors, freezing procurement decisions.
- Immortalized cell substitution:Commodity HepG2 and HEK293 spheroids satisfy high-throughput toxicology screening at one-tenth the cost of patient-derived organoids, capping premium model penetration.
Strategic Opportunities
- Japan's PMDA organoid guidance:Pending qualification opinions on organoid-based biomarkers under revised pharmaceutical regulations create first-mover advantage for compliant suppliers.
- Organoid-on-chip convergence:Integration of microfluidic perfusion with patient-derived models enables real-time metabolic monitoring, opening subscription revenue streams from diagnostic applications.
- Direct-to-biotech distribution:Bypassing traditional CRO intermediaries through cloud-based organoid ordering platforms captures margin from lean R&D operations in Boston and San Diego clusters.
Industry Challenges
- Organoid specialist talent scarcity:Cross-trained cell biologists capable of sustaining differentiation protocols across neural, hepatic, and cardiac lineages command premium compensation, constraining scale-up velocity.
- EMA MDR compliance timelines:Extended qualification opinion processes for organoid-based biomarkers delay European revenue recognition and strain working capital for emerging suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organoids and Spheroids Market |
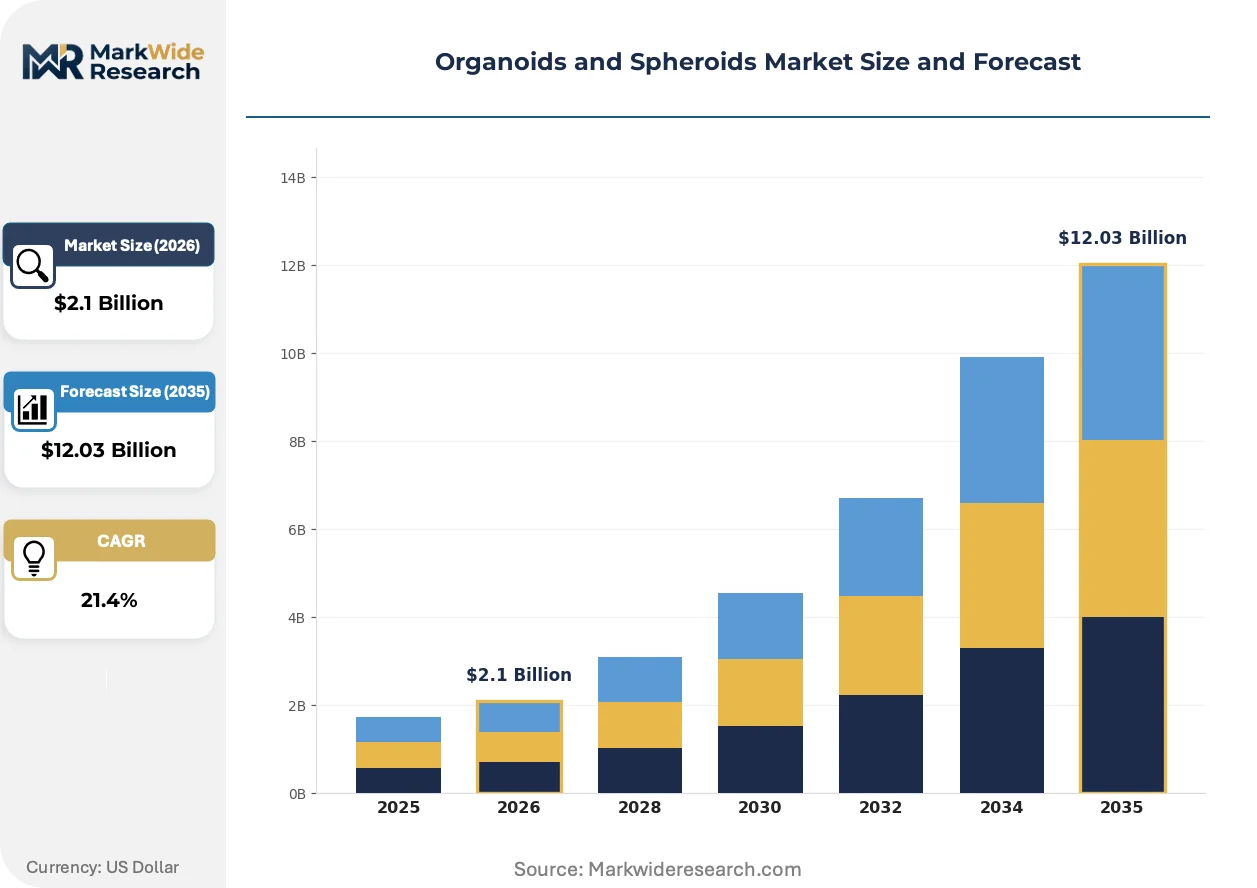
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $12.03 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organoids, Spheroids, 3D Cell Culture, Tissue Models Application: Drug Discovery, Cancer Research, Toxicology Testing, Regenerative Medicine End User: Pharmaceutical Companies, Academic Research Institutions, Biotech Firms, Contract Research Organizations Technology: 3D Printing, Microfluidics, Biofabrication, Automated Cell Culture |
| Companies Covered | Thermo Fisher Scientific, Inc., STEMCELL Technologies Inc., Merck KGaA, Corning Incorporated, Lonza, InSphero, Hubrecht Organoid Technology (HUB), Prellis Biologics, Molecular Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organoids and Spheroids Market Strategic Shifts & Innovations
Microfluidic perfusion systems and AI-guided image analysis are compressing experimental timelines while regulatory qualification pathways mature across multiple jurisdictions.
Multi-organoid connected systems replicate organ-organ crosstalk through microfluidic channels, enabling pharmacokinetic modeling that single-tissue models cannot achieve. Mid-sized pharmaceutical sponsors in the Netherlands and Switzerland are adopting these platforms for lead optimization. This technology is decentralizing toxicology screening from centralized CRO facilities toward in-house biopharma laboratories, compressing decision cycles.
EMA's Committee for Medicinal Products for Human Use is refining qualification opinions on organoid-based efficacy endpoints under the EU MDR framework. This regulatory development forces sponsors to pre-validate organoid data packages before submission, increasing upfront protocol investment. Cardiac safety assessment applications face the steepest compliance burden, driving consolidation toward suppliers with established EMA rapporteur relationships.
Pharmaceutical procurement departments are unbundling organoid supply from full-service CRO contracts, establishing direct relationships with specialized media and matrix suppliers. This disintermediation fragments incumbent CRO revenue streams while creating volume commitments for organoid technology vendors. The shift is most visible in United States East Coast biotech clusters, where lean R&D operations prioritize cost transparency over integrated service convenience.
Organoids and Spheroids Market Segmentation
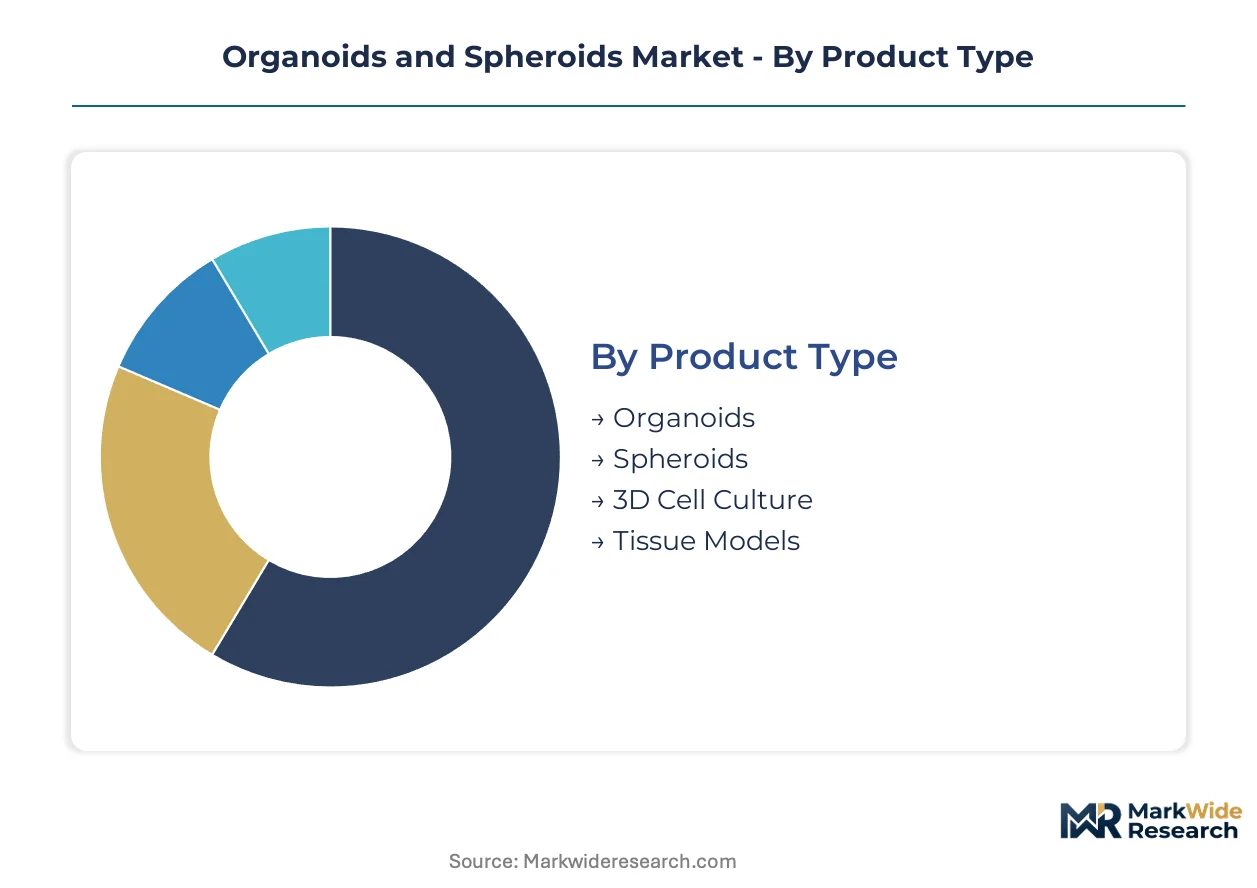
Segmentation in organoids and spheroids reveals divergent compliance burdens across product tiers. Patient-derived organoids face EMA qualification pathways under EU MDR, while commodity spheroids operate under ISO pending standards with lighter documentation requirements.
Product Type:
FDA's expanded acceptance of organoid efficacy data for investigational new drug applications creates tiered certification requirements across this category.
- Organoids:Self-organizing 3D structures derived from stem cells or primary tissues, typically 100-500 micrometers, cultivated in extracellular matrix scaffolds. Demand concentrates among pharmaceutical sponsors seeking regulatory-submission-grade disease models for liver and cardiac safety assessments, constrained by Matrigel supply concentration and EMA MDR compliance timelines.
- Spheroids:Compact cellular aggregates formed from immortalized or primary cells without matrix dependency, suited for high-throughput screening. Procurement from academic clusters in Germany and Japan drives volume, with Helmholtz Association and Max Planck Institute specifications anchoring European supplier expansion.
- 3D Cell Culture:Broad category encompassing scaffold-based and suspension systems for organ-level physiology replication.
- Tissue Models:Engineered constructs combining multiple cell types to simulate organ architecture for compound screening.
Leading the category by volume: Spheroids. Growing fastest: Organoids.
Application:
Cost stratification separates premium patient-derived applications from commodity screening workflows.
- Drug Discovery:Pharmaceutical companies replace 2D cytotoxicity assays with liver and cardiac spheroid models that better predict human metabolism outcomes. Microfluidics-enabled platforms compress timelines from weeks to days, enabling lean biotech firms in Boston and San Diego to compete with well-capitalized R&D operations.
- Cancer Research:Patient-derived tumor organoids enable personalized therapy selection and resistance mechanism studies. Demand clusters at academic medical centers with established biobank infrastructure, particularly in Japan where PMDA guidance on organoid-based biomarkers creates first-mover positioning.
- Toxicology Testing:HepG2 and HEK293 spheroids satisfy regulatory screening at reduced cost versus patient-derived alternatives.
- Regenerative Medicine:Organoid applications in tissue repair face extended EMA qualification opinion processes under EU MDR.
Drug Discovery commands the largest revenue share. Cancer Research exhibits the steepest expansion trajectory.
End User:
Customer type determines procurement channel preferences and service bundling requirements.
- Pharmaceutical Companies:Multinational sponsors unbundle organoid supply from full-service CRO contracts, establishing direct relationships with specialized media and matrix suppliers. This disintermediation fragments incumbent CRO revenue while creating volume commitments for technology vendors, most visible in United States East Coast biotech clusters.
- Academic Research Institutions:German Helmholtz Association and Max Planck Institute networks drive concentrated demand for neural and gastrointestinal organoid media formulations. Procurement prioritizes cost transparency over integrated service convenience.
- Biotech Firms:Lean R&D operations favor cloud-based organoid ordering platforms bypassing traditional CRO intermediaries.
- Contract Research Organizations:ISO benchmark standards for spheroid reproducibility will determine preferred vendor status with multinational pharmaceutical sponsors.
Pharmaceutical Companies anchor procurement volume. Biotech Firms are gaining share fastest through direct supplier relationships.
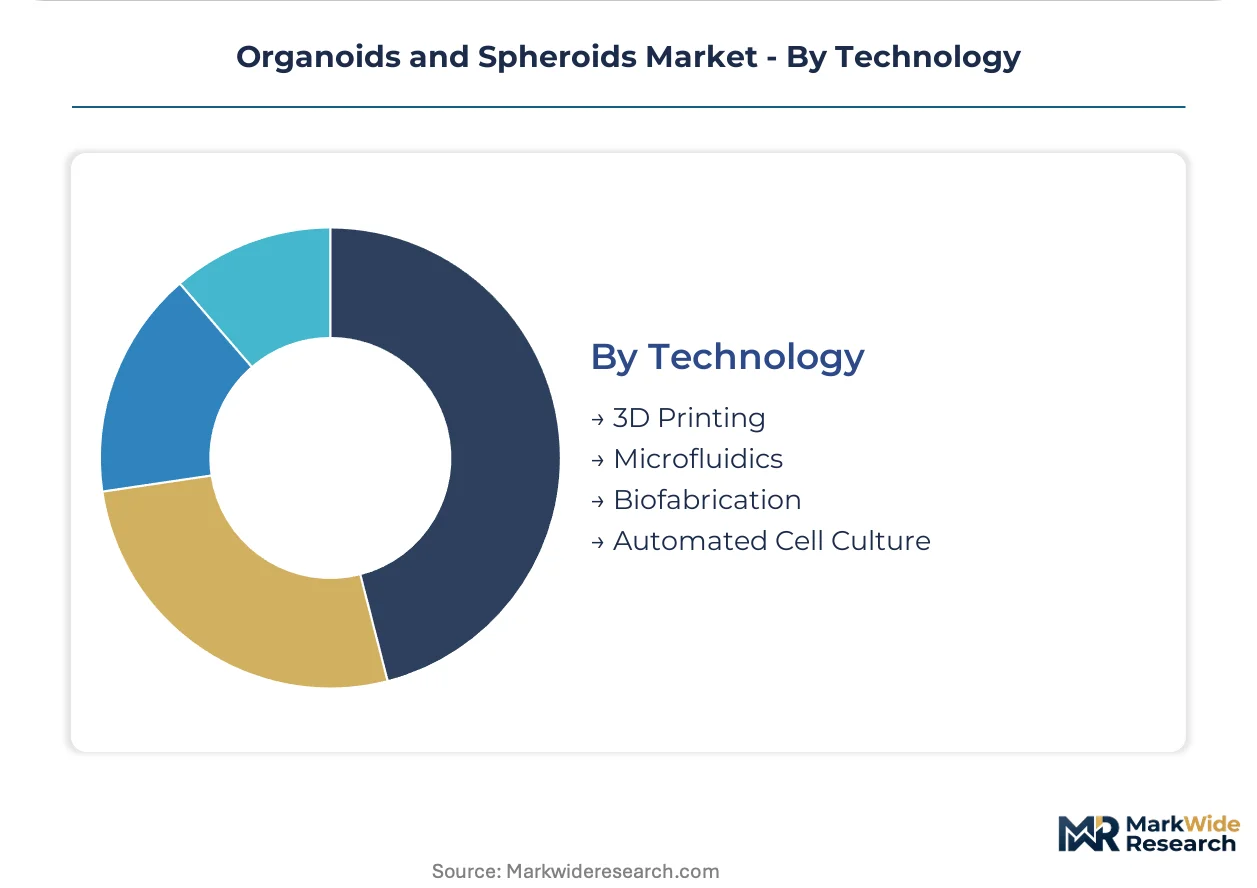
Technology:
Supply concentration in microfluidic components shapes vendor differentiation.
- Microfluidics:Perfusion-enabled organoid bioreactors integrate real-time imaging and metabolic monitoring, opening subscription revenue streams from diagnostic applications. Mid-sized pharmaceutical sponsors in the Netherlands and Switzerland adopt multi-organoid connected systems for pharmacokinetic modeling that single-tissue platforms cannot achieve.
- 3D Printing:Bioink deposition systems for scaffold fabrication serve specialized tissue engineering applications with limited standardization.
- Biofabrication:Automated assembly of cellular constructs spans academic and industrial research settings.
- Automated Cell Culture:Robotic platforms reduce technician burden in high-throughput screening operations.
Microfluidics leads technology investment. 3D Biofabrication shows emerging traction in multi-organoid system integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Kendall Square biotech corridor anchors procurement volume for patient-derived organoid models, while San Diego's Torrey Pines cluster drives cloud-based ordering platform adoption among lean R&D operations.
United States
FDA's Center for Drug Evaluation and Research evaluates organoid efficacy data for investigational new drug applications, accelerating sponsor investment in validated 3D culture platforms. The agency's expanded acceptance of animal testing alternatives compresses preclinical timelines for pharmaceutical sponsors. East Coast biotech clusters in Massachusetts and North Carolina unbundle organoid supply from full-service CRO contracts, establishing direct relationships with specialized media suppliers.
Germany
Helmholtz Association and Max Planck Institute networks drive concentrated demand for neural and gastrointestinal organoid media formulations. EMA's Committee for Medicinal Products for Human Use refines qualification opinions on organoid-based biomarkers under the EU MDR framework, forcing sponsors to pre-validate data packages before submission. Academic procurement in Baden-Württemberg and Bavaria anchors European supplier expansion with specifications for reproducible differentiation protocols.
Japan
PMDA's pending guidance on organoid-based biomarkers creates first-mover advantage for compliant suppliers in personalized therapy selection applications. METI supports domestic biomanufacturing capabilities through targeted research funding at academic medical centers with established biobank infrastructure. Tokyo and Osaka clusters concentrate demand for patient-derived tumor organoids in cancer resistance mechanism studies.
Switzerland
Swissmedic's evolving stance on organoid-based efficacy data attracts mid-sized pharmaceutical sponsors adopting multi-organoid connected systems for pharmacokinetic modeling. The country's precision medicine initiatives align with microfluidics-enabled platforms that integrate perfusion and real-time metabolic monitoring. Basel's pharmaceutical corridor leads European adoption of organoid-on-chip convergence technologies for lead optimization.
Netherlands
Leiden and Utrecht biotech hubs adopt microfluidic perfusion systems that compress compound screening timelines from weeks to days. Dutch academic institutions prioritize cost transparency in procurement, favoring direct supplier relationships over integrated CRO service bundles. EMA rapporteur relationships with local testing facilities position the country as a compliance gateway for European market access.
Organoids and Spheroids Market Key Industry Players
Premium-margin players sit above commodity-margin players across reagent validation tiers, with certified organoid media formulations commanding pricing multiples over unvalidated alternatives. The supply landscape rebalances between patient-derived model specialists and high-throughput spheroid commoditizers. Three archetypes dominate: end-to-end workflow integrators, lineage-specific media formulators, and regulatory testing service bundlers. Consolidation pressures favor acquisition of differentiation-protocol expertise, while geographic expansion targets compliant supplier status in pending Japanese and European regulatory pathways.
Within the workflow integration tier, Thermo Fisher Scientific Inc. anchors premium positioning through validated reagent-to-analytics portfolios. STEMCELL Technologies Inc. exemplifies lineage-specific specialization with sustained differentiation protocols across gastrointestinal and neural applications. Merck KGaA occupies a regulatory service position, extending spheroid-based toxicology assays into submission packages for pharmaceutical clients. These three represent distinct competitive vectors—breadth, depth, and compliance bundling—that structure procurement decisions across multinational sponsor panels.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| STEMCELL Technologies Inc. |
| Merck KGaA |
| Corning Incorporated |
| Lonza |
| InSphero |
| Hubrecht Organoid Technology (HUB) |
| Prellis Biologics |
| Molecular Devices |
| Others |
Cost & Logistics Intelligence
Venture-backed organoid media specialists and university spinouts dominate the premium tier, concentrating pricing power among entities with validated differentiation protocols and EMA rapporteur relationships. This ownership pattern reinforces supply discipline, as compliant suppliers withhold volume discounts until pharmaceutical sponsors commit to multi-year media formulations and matrix supply agreements.
Pricing Analysis
Outcome-linked pricing anchors the premium tier, with patient-derived organoid models commanding multiples based on regulatory submission viability under FDA and EMA pathways. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified organoid media from research-grade formulations and commodity HepG2 spheroids. Cost compression in the economy tier intensifies as Chinese suppliers expand immortalized-cell spheroid capacity, eroding margins for undifferentiated players. Academic research institutions in Germany and Japan exhibit highest price sensitivity, while pharmaceutical sponsors running IND-enabling studies show lowest sensitivity to per-assay costs.
Supply Chain Analysis
Regional distribution centers in Massachusetts, Baden-Württemberg, and Tokyo prefecture anchor hub-and-spoke patterns for temperature-sensitive organoid media and Matrigel extracts. Manufacturing concentrates in the United States, Germany, and Japan, with Singapore emerging as a secondary hub for Asia-Pacific fulfillment. Production draws from murine sarcoma-derived basement membrane extracts, recombinant extracellular matrix proteins, and synthetic hydrogel scaffolds. Single-source vulnerability in Matrigel supply creates structural risk for standardization-dependent protocols. Distribution runs through specialized life science distributors and direct cloud-based platforms serving lean biotech operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The organoids and spheroids market functions as a cost-of-compliance story, with EMA's EU MDR qualification opinions for organoid-based biomarkers erecting barrier-to-entry moats that favor incumbent suppliers with established rapporteur relationships.
For Market Incumbents: Anticipate procurement disintermediation by pharmaceutical sponsors unbundling organoid supply from full-service CRO contracts, and respond by deepening direct relationships with media and matrix suppliers in Boston and San Diego clusters. Certification investment in ISO benchmark standards for spheroid reproducibility represents the critical lever for preferred vendor designation with multinational sponsors. Threat substitution from microfluidics-enabled organoid-on-chip platforms demands preemptive platform integration to retain pricing power. For New Entrants and Emerging Players: Begin with cloud-based organoid ordering platforms targeting lean biotech firms in United States East Coast corridors, bypassing traditional CRO intermediaries to capture margin from transparency-prioritized procurement. The most penetrable segment lies in neural and gastrointestinal organoid media formulations for German Helmholtz Association and Max Planck Institute networks, where academic specifications remain underserved by incumbent portfolios. Go-to-market execution should emphasize cost transparency and rapid customization turnaround versus integrated service bundling. For Investors and Strategic Acquirers: Distressed-cycle entries favor differentiation-protocol specialists with established EMA pre-submission histories in Switzerland and the Netherlands, where mid-sized pharmaceutical sponsors concentrate adoption of multi-organoid connected systems. Long-term viability over the next decade hinges on regulatory acceptance of organoid efficacy data as primary evidence, redirecting biopharma procurement toward compliant suppliers. The signal to watch is which jurisdiction—FDA, EMA, or PMDA—first accepts organoid-based biomarkers for full regulatory submissions, compressing competitive windows for non-compliant players.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Qualification Opinion Pursuit | Secures preferred vendor status with multinational pharmaceutical sponsors under EU MDR framework. |
| Matrigel Alternative Development | Reduces single-source vulnerability for extracellular matrix scaffolds in organoid standardization. |
| Microfluidics Platform Integration | Enables real-time metabolic monitoring for diagnostic subscription revenue streams. |
| Direct-to-Biotech Distribution Launch | Captures margin from lean R&D operations in Boston and San Diego biotech clusters. |
| Multi-Organoid Connected System Deployment | Replicates organ-organ crosstalk for pharmacokinetic modeling in Swiss and Dutch sponsors. |
Research Approach
Document review covered FDA investigational new drug application filings, EMA qualification opinion records, ISO technical committee draft standards, and clinical protocol registries, complemented by interviews with drug development executives, regulatory affairs leads at pharmaceutical sponsors, organoid media formulation scientists, and contract research organization procurement managers. Secondary validation drew from SEC 10-K disclosures of listed life science suppliers, patent filings in 3D cell culture methods, and trade data on extracellular matrix extract imports. Bottom-up segment sizing triangulated against top-down pharmaceutical R&D expenditure allocation models.
Segment-level projections across product type, application, end user, and technology dimensions were generated through structured growth accounting over the projection horizon. CAGRs were derived from regression-adjusted adoption curves incorporating regulatory milestone timelines and pharmaceutical sponsor pipeline data. Industry-specific forecast inputs included PMDA guidance development schedules, academic procurement budget cycles at Helmholtz Association institutes, and microfluidics component cost trajectories.
Underlying measurement precision varies by segment; drug discovery applications with established pharmaceutical sponsor adoption carry tighter precision than emerging regenerative medicine applications facing extended EMA qualification timelines. Forecasts reflect documented assumptions regarding regulatory acceptance timelines and raw material supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Research
Precision Medicine Market
Medical Research
Metabolomics Market
Medical Research
Forensic Medicine Market
Medical Research
PDX Models Market
Medical Research
Mice Model Technologies Market
Medical Research
Epigenomics Market
Medical Research
Methicillin-Resistant Staphylococcus Aureus (MRSA) Drugs Market
Medical Research
India Computer-Aided Drug Discovery Market
Medical Research
Global Humanized Mouse Model Market
Medical Research
Lab Automation in Drug Discovery Market
Medical Research
Global Patient Derived Xenograft Models Market
Medical Research
North America Biobanks Market
Medical Research
Health Economics and Outcomes Research (HEOR) Services Market
Medical Research
Global Human Liver Models Market
Medical Research
Europe Induced Pluripotent Stem Cells (Ipscs) Market
Medical Research
AAV Contract Development and Manufacturing Organizations Market