
 US Wearable Medical Devices Market | 2026-2036
US Wearable Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
US Wearable Medical Devices Market Insights
Texas is tilting toward medical device manufacturing expansion with new cleanroom capacity in the Dallas-Fort Worth metroplex. Apple Inc. leverages its silicon design pipeline to sustain tight integration between sensors and processing cores. Medtronic Plc anchors its wearable portfolio through deep expertise in implantable cardiac rhythm management. Dexcom, Inc. specializes in continuous glucose monitoring substrates that dominate pharmacy benefit formularies.
US wearable medical devices comprise body-worn electronic instruments that capture, transmit, and analyze physiological parameters through biosensors, accelerometers, and photoplethysmography modules operating at sampling frequencies between 100-512 Hz for clinical-grade diagnostics. Their primary commercial purpose centers on shifting care delivery from episodic clinic visits to continuous ambulatory surveillance, reducing acute events through real-time anomaly detection. Smartwatches now command the largest revenue pool among product types as FDA 510(k) clearances stack for atrial fibrillation detection algorithms. Diabetes management devices represent the fastest-expanding category as automated insulin delivery systems pair with smartphone ecosystems. Chronic disease management applications sit at the deepest margin tier due to recurring consumable revenue and payer reimbursement durability.
FDA 510(k) premarket notification requirements shape hardware validation timelines and software-as-medical-device classification thresholds, while HIPAA security rules govern cloud transmission architectures for protected health information. CMS national coverage determinations directly expand or contract addressable populations for remote therapeutic monitoring codes. Stakeholders must weigh FDA breakthrough device designation pathways against the compliance burden of quality system regulation audits as software update cadences accelerate beyond traditional hardware refresh cycles.
Market Dynamics
CMS reimbursement expansion for remote therapeutic monitoring codes is pulling capital toward continuous ambulatory surveillance platforms, compressing traditional episodic care delivery timelines and forcing hospital systems to reconfigure their patient touchpoint architectures.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearances for software-as-medical-device algorithms reduce validation timelines from 18 months to under 12 months for predicate-backed submissions.
- Photoplethysmography miniaturization:Optical sensor modules now integrate into wrist-worn form factors at clinical-grade precision, unlocking atrial fibrillation detection for consumer-accessible price points.
- Texas cleanroom infrastructure:Dallas-Fort Worth metroplex additions expand domestic manufacturing capacity for Class II device assembly, reducing offshore dependency for final-stage production.
Market Restraints
- Lithium-polymer cell volatility:Battery chemistry supply concentrates in East Asian contract manufacturers, exposing margins to raw material tariff fluctuations and logistics bottlenecks.
- HIPAA cloud architecture compliance:Protected health information transmission requirements impose encryption and audit-log infrastructure costs that inflate platform operational overhead by 15-25 percent.
- Silicon photonics foundry access:Advanced biosensor wafer fabrication capacity remains captive to semiconductor majors, constraining startup hardware scaling.
Strategic Opportunities
- Behavioral health integration:Anxiety and depression biomarker detection through galvanic skin response and heart rate variability opens reimbursement pathways outside traditional chronic disease categories.
- Medicaid remote monitoring expansion:State-level waivers for continuous glucose monitoring in Type 2 populations address underpenetrated lower-income demographics previously excluded from commercial coverage.
- Federated learning architectures:Edge-computing model training on device-resident data eliminates centralized cloud storage liabilities while preserving algorithm improvement velocity.
Industry Challenges
- FDA quality system regulation audit cadence:Software update frequencies exceeding quarterly cycles strain traditional hardware-centric inspection protocols, creating compliance documentation backlogs.
- Interoperability with legacy EHR systems:HL7 FHIR implementation gaps force manual data bridge construction for hospital system procurement, extending sales cycles and integration costs.
- Biosensor calibration drift:Photoplethysmography accuracy degradation over device lifespan requires algorithmic compensation or hardware redundancy, complicating long-term reliability claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Wearable Medical Devices Market |
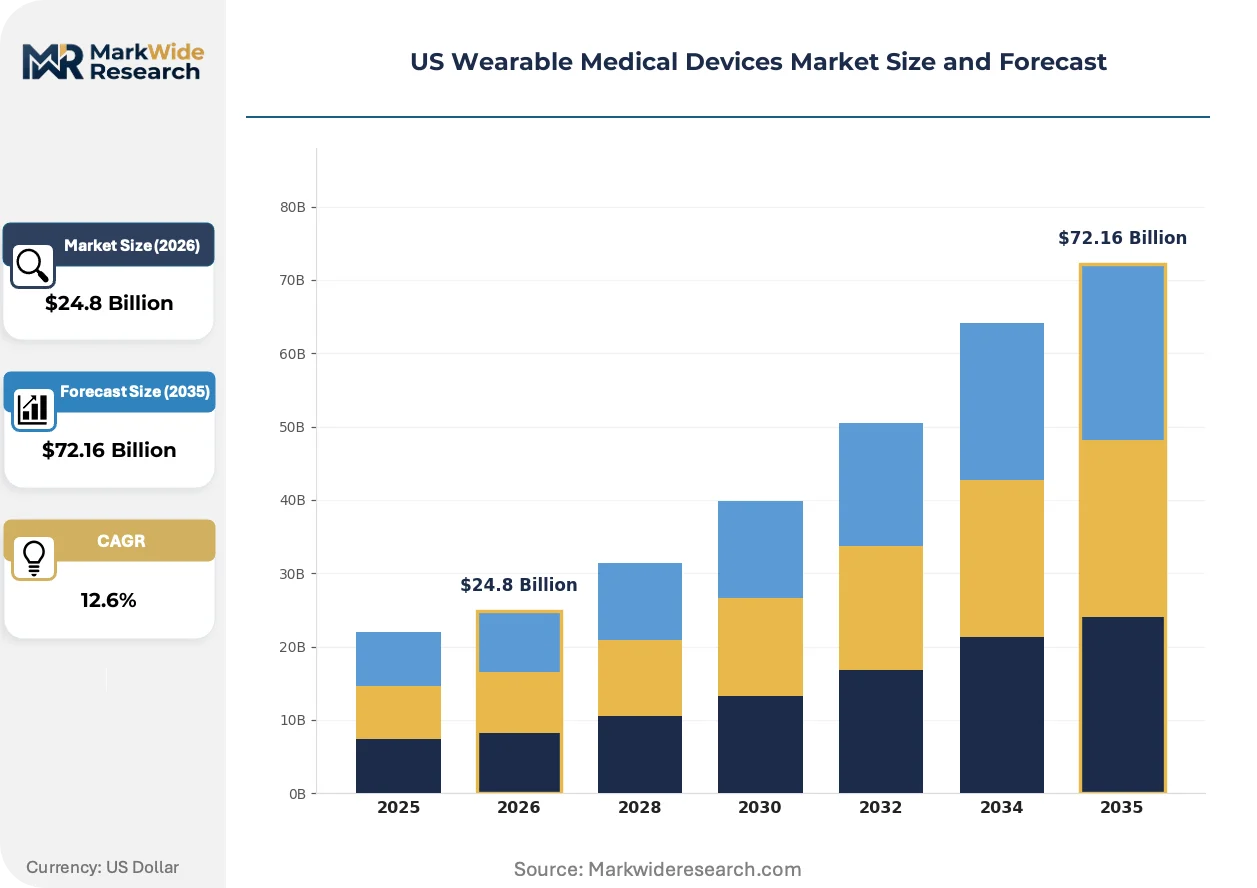
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $72.16 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, ECG Monitors, Diabetes Management Devices End User: Patients, Healthcare Providers, Fitness Enthusiasts, Research Institutions Technology: Bluetooth, NFC, Wi-Fi, RFID Application: Chronic Disease Management, Fitness Monitoring, Preventive Care, Telehealth |
| Companies Covered | Apple Inc., Fitbit, Garmin Ltd., Medtronic Plc, Abbott Laboratories, Koninklijke Philips N.V., Dexcom, Inc., OMRON Corporation, iRhythm Technologies, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Wearable Medical Devices Market Trends and Innovations
Silicon design pipelines and cloud-native health platforms are compressing the iteration cycle between sensor hardware, signal processing algorithms, and clinical validation, collapsing traditional multi-year product development timelines into 18-month windows.
Photoplethysmography modules operating at 512 Hz sampling frequencies are rendering obsolete lower-fidelity accelerometer-only cardiac monitoring devices in ambulatory settings. Cardiology departments at integrated delivery networks are adopting these optical systems for post-discharge arrhythmia surveillance, replacing Holter monitors that require return clinic visits for data retrieval. The structural consequence is a compression in diagnostic device rental revenue pools as ownership models shift to disposable patch economics.
CMS national coverage determinations for remote therapeutic monitoring codes are expanding addressable populations for continuous physiologic surveillance beyond traditional cardiac and diabetic indications. Pulmonology and nephrology subspecialties now qualify for reimbursement under expanded category definitions, pulling venture funding toward respiratory rate and fluid status sensor development. Hospital systems in California and Massachusetts are restructuring their population health contracts to capture these new revenue streams.
Direct-to-consumer channel bypass of traditional durable medical equipment distributors is fragmenting procurement authority across employer wellness programs, pharmacy benefit managers, and payer-owned virtual care platforms. Large self-insured employers in the technology and financial services verticals are negotiating enterprise contracts for biometric monitoring subscriptions, displacing individual prescription-driven acquisition. This pattern concentrates most visibly in the San Francisco Bay Area and New York metropolitan corridors where employer-sponsored digital health benefits penetration exceeds national averages by 40 percentage points.
US Wearable Medical Devices Market Segmentation
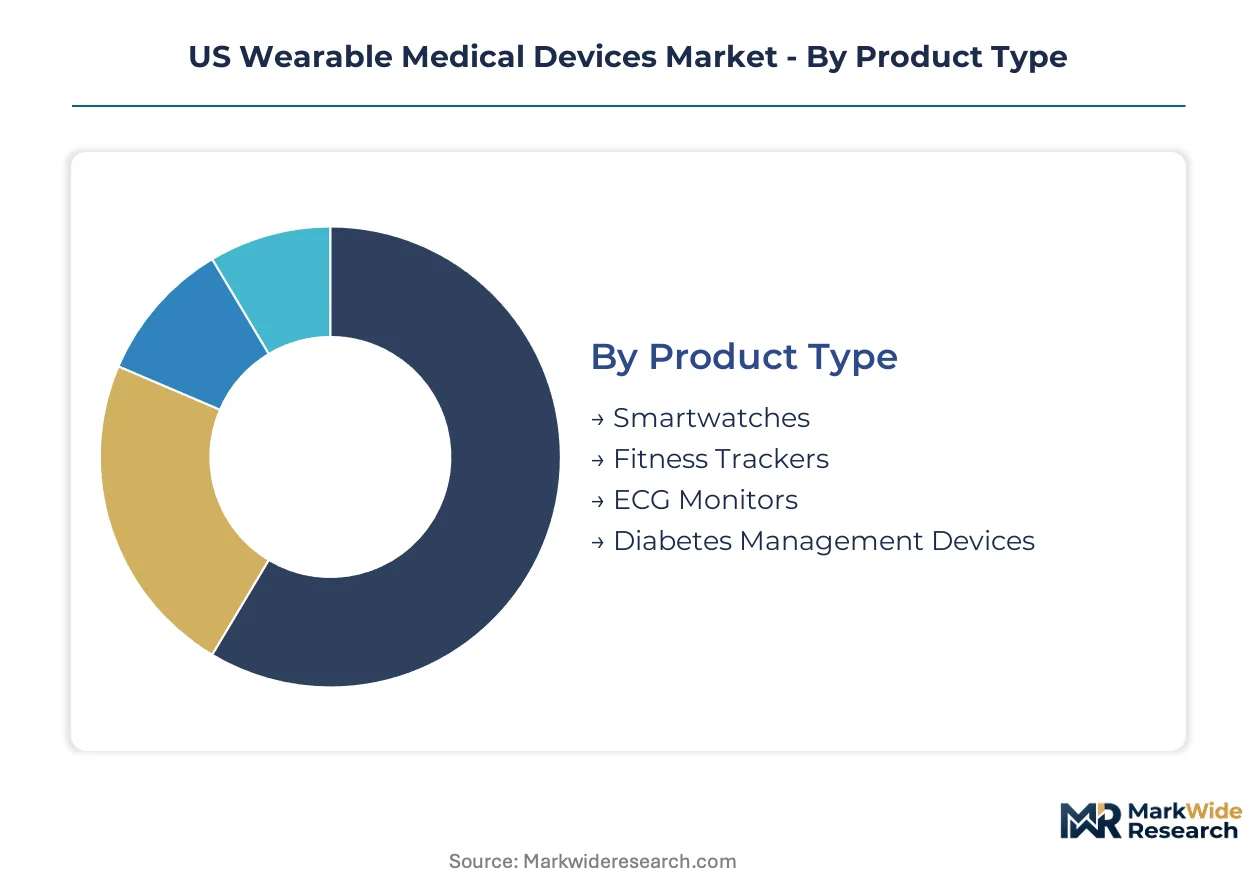
Segmentation of US wearable medical devices reveals how reimbursement pathways, sensor miniaturization, and care delivery models intersect to create distinct commercial territories. Each dimension carries implications for FDA clearance requirements, CMS billing code eligibility, and go-to-market channel strategy.
Product Type:
Clinical use-case spectrum spans consumer-grade wellness tracking through prescription-grade diagnostic monitoring, with FDA 510(k) clearance thresholds determining reimbursement eligibility and channel placement.
- Smartwatches:Photoplethysmography-enabled wrist-worn devices now sample at 512 Hz for atrial fibrillation detection algorithms cleared under FDA 510(k) pathways. Demand concentrates among integrated delivery networks in California's digital health corridor seeking post-discharge arrhythmia surveillance alternatives to Holter monitors.
- Diabetes Management Devices:Continuous glucose monitoring substrates pair with automated insulin delivery systems through smartphone ecosystems, dominating pharmacy benefit formularies as CMS broadens coverage criteria. Massachusetts medical device cluster anchors manufacturing and algorithm development for this category.
- Fitness Trackers:Lower-sampling-frequency accelerometer-based devices serve employer wellness program contracts without diagnostic claims.
- ECG Monitors:Single-lead and multi-lead patch configurations target cardiology department procurement for event monitoring.
Established volume favors smartwatches; emerging adoption favors diabetes management devices.
End User:
Procurement authority fragments across prescription-driven clinical acquisition, direct-to-consumer retail, and enterprise wellness contracting, each with distinct price sensitivity and regulatory exposure.
- Healthcare Providers:Hospital systems expanding remote patient monitoring programs drive Class II device procurement through value-based care contracts. Texas cleanroom capacity additions in Dallas-Fort Worth support domestic assembly for this institutional channel.
- Patients:Direct-to-consumer bypass of durable medical equipment distributors accelerates as self-insured employers negotiate biometric monitoring subscriptions. San Francisco Bay Area technology sector penetration exceeds national averages by substantial margins.
- Fitness Enthusiasts:Wellness-oriented consumers purchase through retail channels without prescription requirements or insurance involvement.
- Research Institutions:Academic medical centers deploy investigational devices for clinical trial endpoints and algorithm validation studies.
Institutional procurement sustains premium pricing; employer-sponsored channels are expanding most quickly.
Technology:
Connectivity protocols determine data transmission security architecture, battery consumption profiles, and interoperability with legacy electronic health record systems.
- Bluetooth:Low-energy protocols dominate wrist-worn form factors, enabling continuous pairing with smartphone ecosystems while preserving lithium-polymer cell longevity. HIPAA encryption requirements for protected health information transmission add 15-25 percent operational overhead to platform architectures.
- Wi-Fi:Higher-bandwidth connectivity supports real-time streaming for inpatient telemetry applications and cloud-native analytics platforms.
- NFC:Near-field communication enables tap-to-pair glucose meter synchronization and pharmacy point-of-sale integration.
- RFID:Passive and active radio-frequency identification supports asset tracking and patient identification in acute care settings.
Bluetooth anchors consumer-facing volume; Wi-Fi commands institutional premium tiers.
Application:
Reimbursement durability and consumable revenue recurrence vary sharply across episodic diagnostic use versus continuous chronic disease surveillance.
- Chronic Disease Management:Recurring sensor replacement revenue and durable CMS reimbursement codes generate the deepest margin tier. Pulmonology and nephrology subspecialties now qualify under expanded remote therapeutic monitoring category definitions.
- Telehealth:Virtual care platforms integrate biometric streams for asynchronous provider review, with state-level Medicaid waivers expanding continuous glucose monitoring access for Type 2 populations.
- Fitness Monitoring:Non-diagnostic wellness tracking operates outside FDA regulatory pathways and insurance reimbursement.
- Preventive Care:Risk stratification applications target employer wellness program budgets rather than clinical billing codes.
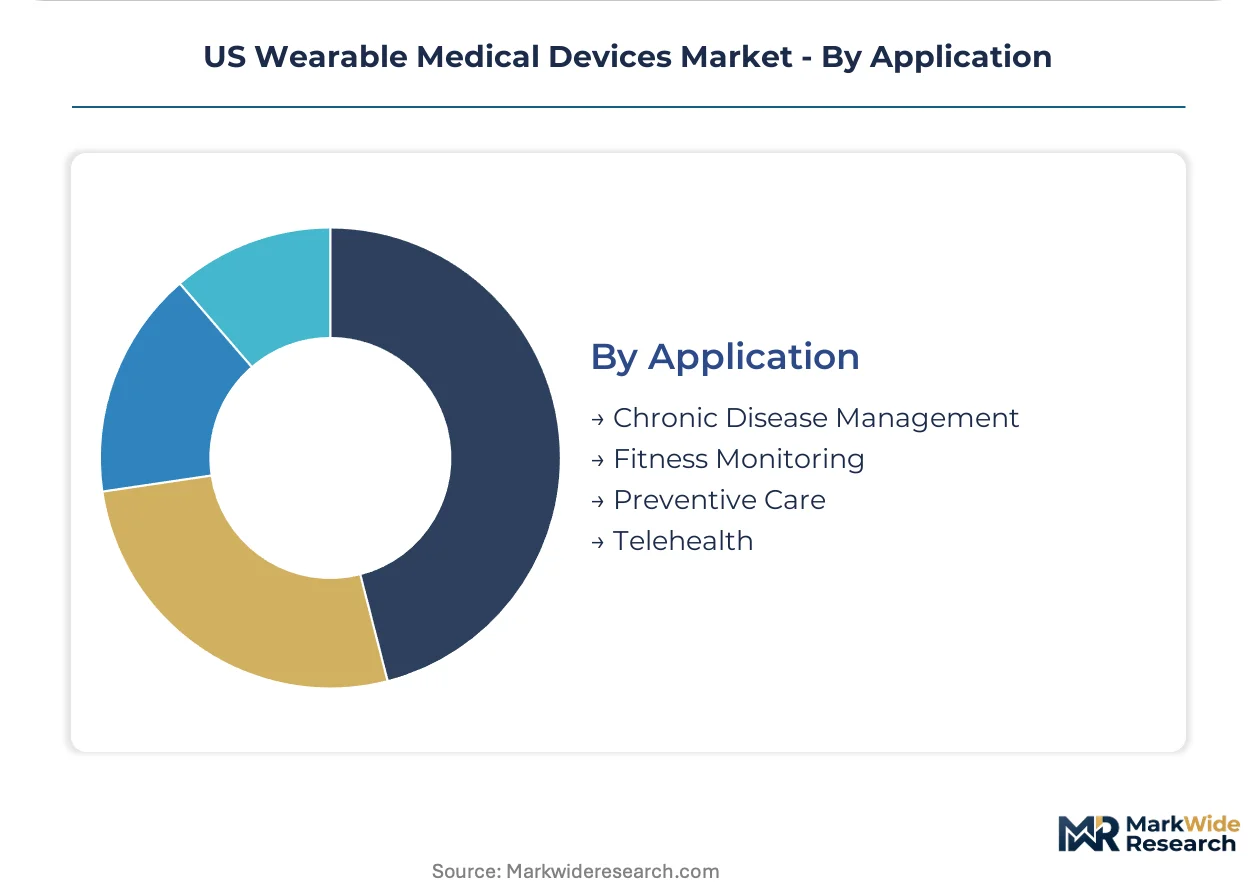
Chronic disease management holds margin concentration; telehealth integration offers the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California and Massachusetts deploy wearable medical devices for integrated delivery network contracts, while Texas concentrates manufacturing capacity expansion. FDA 510(k) clearance density varies sharply across state medical device clusters.
California
Hospital systems in the San Francisco Bay Area negotiate enterprise biometric monitoring subscriptions with self-insured technology employers. FDA breakthrough device designations concentrate in Stanford-adjacent incubators. Silicon Valley sensor startups partner with Apple Inc. for photoplethysmography module integration.
Massachusetts
Academic medical centers in Greater Boston validate continuous glucose monitoring algorithms for automated insulin delivery systems. CMS national coverage determinations drive reimbursement consulting activity through local health policy firms. The Route 128 corridor anchors Dexcom, Inc. manufacturing and algorithm development operations.
Texas
Dallas-Fort Worth metroplex cleanroom additions expand Class II device assembly capacity for hospital procurement channels. Texas Medical Center institutions pilot remote therapeutic monitoring programs under expanded CMS codes. Houston-based contract manufacturers reduce offshore dependency for final-stage production.
Minnesota
Medtronic Plc anchors implantable cardiac rhythm management expertise that extends into wearable patch surveillance. The Twin Cities medical device cluster sustains FDA quality system regulation audit infrastructure. Mayo Clinic Rochester validates atrial fibrillation detection algorithms for post-discharge monitoring.
New York
Self-insured financial services employers in Manhattan negotiate direct-to-consumer biometric subscription contracts bypassing durable medical equipment distributors. Weill Cornell Medicine participates in federated learning architecture trials for edge-computing model training. Buffalo manufacturing facilities assemble ECG monitor patches for cardiology department procurement.
US Wearable Medical Devices Market Competitive Landscape
Capability concentration sits with silicon design and biosensor substrate specialists; scale advantage sits with consumer electronics platforms and diversified medical device conglomerates. The market structures around three tiers: vertically integrated technology platforms, implantable-to-wearable transition specialists, and continuous monitoring substrate pure-plays. Dominant competitive moves include FDA 510(k) pathway acceleration through predicate-backed submissions and strategic partnerships between sensor module fabricators and cloud-native health platforms.
Within the diversified medical device tier, Medtronic Plc and Abbott Laboratories occupy positions anchored by implantable expertise that extends into ambulatory surveillance. Among continuous monitoring specialists, Dexcom, Inc. exemplifies the substrate-focused archetype dominating pharmacy benefit formularies. Apple Inc. represents the consumer platform vector leveraging silicon design pipelines for sensor-processor integration.
| Leading Market Players |
|---|
| Apple Inc. |
| Fitbit |
| Garmin Ltd. |
| Medtronic Plc |
| Abbott Laboratories |
| Koninklijke Philips N.V. |
| Dexcom, Inc. |
| OMRON Corporation |
| iRhythm Technologies, Inc. |
| Others |
Pricing and Supply Chain Analysis
Lithium-polymer cell production concentrates in South Korean and Chinese contract manufacturers, tethering margin pools in downstream wearable assembly to East Asian battery chemistry supply chains and exposing pricing power to raw material tariff volatility. This upstream concentration forces US-based device makers to absorb logistics cost fluctuations or reconfigure sourcing toward domestic alternatives.
Pricing Analysis
Long-term offtake agreements dominate procurement between hospital systems and continuous glucose monitoring suppliers, locking in sensor replacement revenue streams across multi-year population health contracts. Pricing stratifies across FDA 510(k) cleared diagnostic tiers, unregulated wellness trackers, and prescription-grade cardiac monitoring patches. Cost compression in the wellness tracker segment is intensifying because employer wellness programs demand volume discounts for enterprise biometric subscriptions. Self-insured employers in the technology sector exhibit the highest price sensitivity, while integrated delivery networks purchasing Class II devices for remote patient monitoring programs prioritize reimbursement durability over unit cost.
Supply Chain Analysis
Photoplethysmography sensor wafers feed from Taiwanese and South Korean foundry capacity, with advanced silicon photonics fabrication remaining captive to semiconductor majors. Raw material dependencies span lithium-polymer cells, biosensor substrates, and medical-grade elastomers for skin-contact interfaces. Single-source vulnerability concentrates in East Asian battery chemistry supply, where logistics bottlenecks and tariff exposure threaten production continuity. Distribution runs through durable medical equipment distributors for prescription devices, direct-to-consumer channels for wellness trackers, and enterprise procurement portals for employer-sponsored biometric monitoring programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US wearable medical devices market sits in a cyclical recovery phase as CMS reimbursement expansion for remote therapeutic monitoring codes pulls capital back toward continuous ambulatory surveillance platforms following pandemic-era care delivery disruptions.
For Market Incumbents: Entrench market position through backward integration into photoplethysmography sensor module fabrication and captive lithium-polymer cell supply partnerships that reduce East Asian dependency. Expand cleanroom capacity in the Dallas-Fort Worth metroplex to secure domestic Class II device assembly for hospital procurement channels threatened by offshore logistics volatility. For New Entrants and Emerging Players: Medicaid remote monitoring waivers for Type 2 diabetes populations in underserved states represent the most penetrable entry point outside commercial coverage formularies. Behavioral health biomarker detection through galvanic skin response opens reimbursement pathways distinct from saturated cardiac and diabetic categories. Pursue federated learning architecture partnerships with academic medical centers to bypass centralized cloud storage compliance burdens. For Investors and Strategic Acquirers: Capital is best deployed toward continuous monitoring substrate specialists with durable pharmacy benefit formulary positioning and automated insulin delivery system integration. Long-term viability across the projection horizon hinges on FDA 510(k) clearance velocity and CMS national coverage determination timing. Watch state-level Medicaid waiver expansion rates as the inflection indicator for addressable population growth in lower-income demographics.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Predicate-backed clearances compress validation timelines from 18 months toward 12 months for algorithm-as-device pathways. |
| Hospital System Partnership | Value-based care contracts with Texas Medical Center institutions anchor procurement volume for remote therapeutic monitoring programs. |
| Software Companion Development | Smartphone ecosystem integration enables automated insulin delivery pairing that dominates pharmacy benefit formularies. |
| Reimbursement Strategy | CMS national coverage determination consulting secures billing code eligibility for pulmonology and nephrology subspecialty expansion. |
| CE Marking Pathway | European market access diversification reduces reliance on FDA clearance cadence volatility for revenue recognition timing. |
Research Methodology
Cross-validation between primary interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and pharmacy benefit directors and secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and SEC medical device segment disclosures anchors the qualitative findings. Bottom-up demand modeling across patient population segments and top-down market sizing through payer coverage expansion analysis provide triangulation checks.
Calibration against historical CMS national coverage determination implementation timelines and FDA breakthrough device designation precedent cases shapes the analytical framework across the projection horizon. Segmentation dimensions span product type, end user procurement authority, connectivity protocol, and application reimbursement durability. CAGRs derive from fitted growth curves adjusted for regulatory clearance velocity and coverage expansion trajectories. Forecast inputs incorporate photoplethysmography sampling frequency adoption curves and remote therapeutic monitoring code utilization rates.
Macroeconomic conditions sit as an overlay; deviation in lithium-polymer raw material pricing, East Asian logistics capacity, or CMS reimbursement policy would shift the trajectory. Forecasts reflect documented assumptions regarding FDA clearance timelines and state-level Medicaid waiver expansion. Cross-checking against hospital capital expenditure surveys and GPO contract award databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
India Enteral Feeding Devices Market
Medical Devices
Mobile Healthcare Devices Market
Medical Devices
Pocket Ventilation Systems Market
Medical Devices
Nasal Atomizer Devices Market
Medical Devices
Digital Magnifiers Market
Medical Devices
Critical Care Devices Market
Medical Devices
Subperiosteal Implants Market
Medical Devices
North America Intraocular Lens Market
Medical Devices
Depression Devices Market
Medical Devices
Neurovascular Devices Market
Medical Devices
China Ophthalmic Devices Market
Medical Devices
Global Foley Catheters Market
Medical Devices
Neurovascular Stent Market
Medical Devices
Endoscope Reprocessing Device Market
Medical Devices
IV Poles Market
Medical Devices
Mexico Electrocardiograph (ECG) Market