
 Global 28-Homobrassinolide Market | 2026-2036
Global 28-Homobrassinolide Market Size, Share, and Industry Trends Forecast 2026-2036
Global 28-Homobrassinolide Market Foresight
The divergence between premium and commodity tiers in 28-homobrassinolide is hardening around purity certification and formulation stability. BASF SE leverages its integrated agrochemical platform to sustain supply consistency for European and Latin American seed producers. Syngenta AG anchors its position through proprietary formulation technology that extends shelf life in tropical storage conditions. Zhengzhou Zhengshi Chemical competes on cost-optimized powder production, occupying the mid-tier channel for domestic Chinese farming enterprises.
28-homobrassinolide is a C28 brassinosteroid plant hormone analog, typically synthesized via steroidal side-chain modification from campesterol or brassicasterol precursors, functioning primarily as a cell elongation and stress tolerance promoter in commercial agriculture. Liquid concentrate formulations dominate export channels due to ease of tank-mix compatibility with fungicide and insecticide programs. Vegetable farming applications represent the fastest-expanding segment as greenhouse operators in protected-culture systems adopt precision dosing protocols for tomato and pepper fruit set enhancement. Oilseed crops remain a mature, price-sensitive category where bulk granular form generates thinner margins but secures multi-season supply contracts.
The US EPA regulates 28-homobrassinolide under FIFRA pesticide tolerance frameworks, while China's NMPA and MEE enforce GB standard residue limits that shape import eligibility for foreign suppliers. REACH registration requirements in Europe filter out uncertified producers from specialty horticultural channels. Stakeholders must monitor evolving maximum residue limits across multiple jurisdictions and calibrate purity investments against the regulatory cost of market exclusion.
Market Dynamics
China's NMPA and India's CDSCO residue tightening is bifurcating formulation demand toward certified high-purity grades, forcing manufacturers to recalibrate purity investments against exclusion risk from import eligibility.
Growth Catalysts
- East Asian rice intensification:Agricultural cooperatives in China's Shandong and Henan provinces are expanding procurement of brassinosteroid formulations for wheat and rice yield programs, concentrating demand near domestic manufacturing clusters.
- Greenhouse precision dosing:Protected-culture tomato and pepper operators in vegetable farming are adopting liquid concentrate tank-mix protocols, accelerating consumption of stable-shelf-life formulations.
- REACH registration filtering:Specialty horticultural channels in Europe are excluding uncertified producers, creating protected premium segments for compliant suppliers with validated residue documentation.
Market Restraints
- Campesterol feedstock volatility:Steroidal precursor supply fluctuates with vegetable oil processing volumes, compressing margin predictability for powder-grade manufacturers.
- Shandong-Henan production concentration:Domestic Chinese manufacturers cluster in two provinces, creating geographic supply vulnerability to regional logistics disruptions or environmental enforcement actions.
- Granular oilseed commoditization:Bulk multi-season contracts for mature oilseed applications generate thinner margins that disincentivize R&D reinvestment.
Strategic Opportunities
- Latin American seed producer channels:European and Asian suppliers can expand into Brazilian and Argentine seed treatment markets where brassinosteroid penetration in soybean and maize remains underdeveloped.
- Tropical storage formulation technology:Proprietary shelf-life extension chemistry unlocks distribution into Southeast Asian and Sub-Saharan African markets lacking cold-chain infrastructure.
- US EPA FIFRA tolerance alignment:Early movers achieving pesticide tolerance certification gain first-mover advantage in specialty crop segments before residue limits tighten further.
Industry Challenges
- Multi-jurisdiction MRC calibration:Formulators must maintain parallel residue documentation systems for China's GB standards, US EPA tolerances, and REACH registrations, stretching compliance teams.
- Stability validation capex:Tropical-condition shelf-life testing requires accelerated aging infrastructure investment before market entry into high-humidity geographies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 28-Homobrassinolide Market |
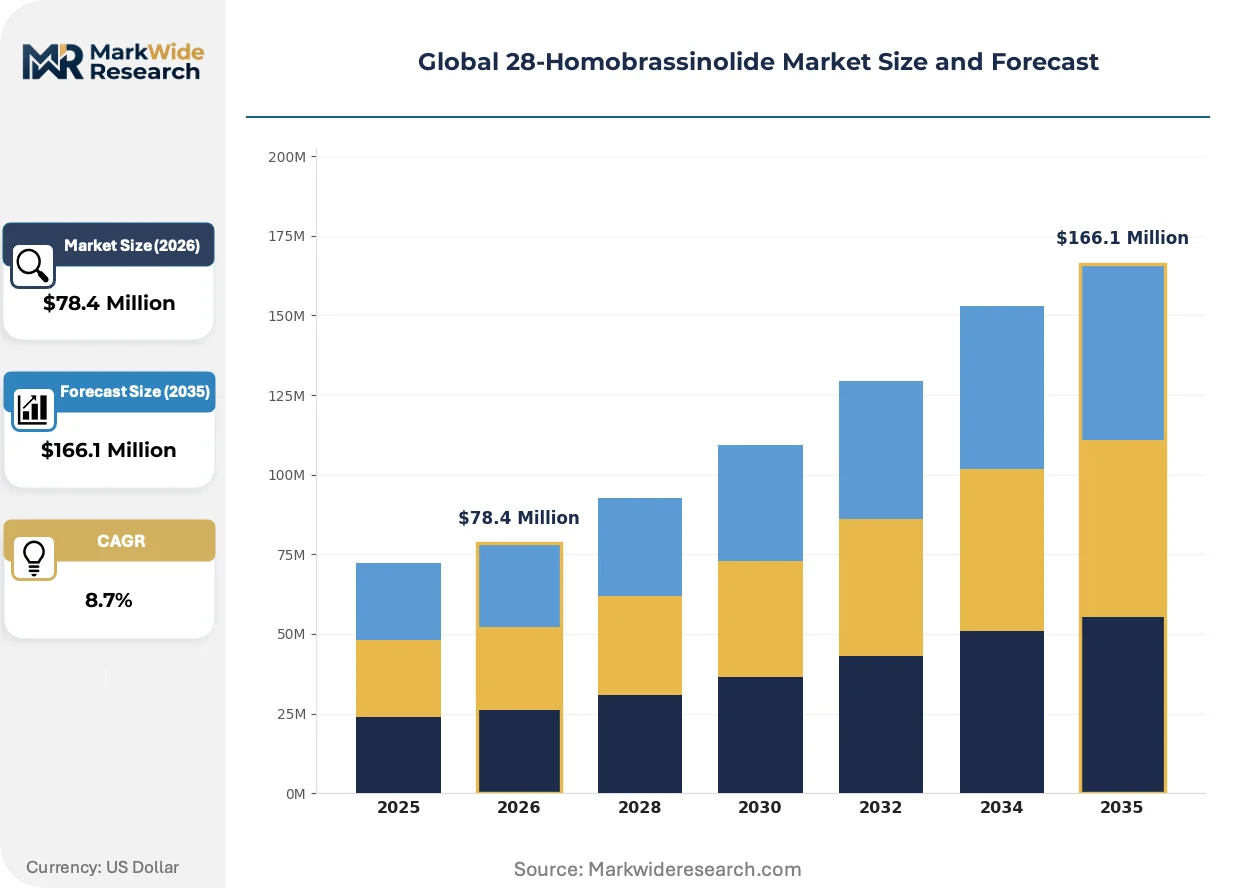
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $166.1 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Concentrate, Powder Form, Granular Form, Emulsifiable Concentrate Application: Cereal Crops, Horticultural Plants, Oilseed Crops, Vegetable Farming End Use Industry: Agricultural Cooperatives, Seed Producers, Farming Enterprises, Plant Research Institutes Packaging Type: Plastic Bottles, Aluminum Cans, Sachets, Bulk Containers |
| Companies Covered | BASF SE, Syngenta AG, Bayer AG, FMC Corporation, UPL, Zhengzhou Zhengshi Chemical, Shandong Ench Chemical, Zhengzhou Nongda Biochemical, TRC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 28-Homobrassinolide Market Shifts & Advancements
Formulation chemistry and regulatory compliance systems are the twin axes of competitive differentiation, with technology convergence and jurisdiction-specific certification requirements reshaping supplier capabilities.
Microencapsulation delivery systems for brassinosteroid active ingredients are converging with precision agriculture sensor networks, enabling variable-rate application in greenhouse environments. Dutch and Spanish protected-culture operators are piloting these integrated systems for tomato fruit set timing. The technology is converging with existing fungicide and insecticide tank-mix programs, compressing the separate-input supply chain into unified crop protection bundles.
China's MEE enforcement of GB standard residue limits is accelerating purity-grade stratification across import channels. Foreign suppliers without certified high-purity documentation face progressive exclusion from specialty horticultural segments. Vegetable farming applications in East Asian markets are most affected, with procurement teams demanding batch-specific chromatographic validation.
Certification-driven preference formation is displacing price-first procurement in European specialty crop channels. Buyers in protected-culture systems now require REACH-registered formulations with documented tropical stability data. This pattern is most visible in Benelux and northern Italian greenhouse clusters, where multi-input suppliers without regulatory documentation are losing tank-mix positioning to certified competitors.
Global 28-Homobrassinolide Market Segmentation
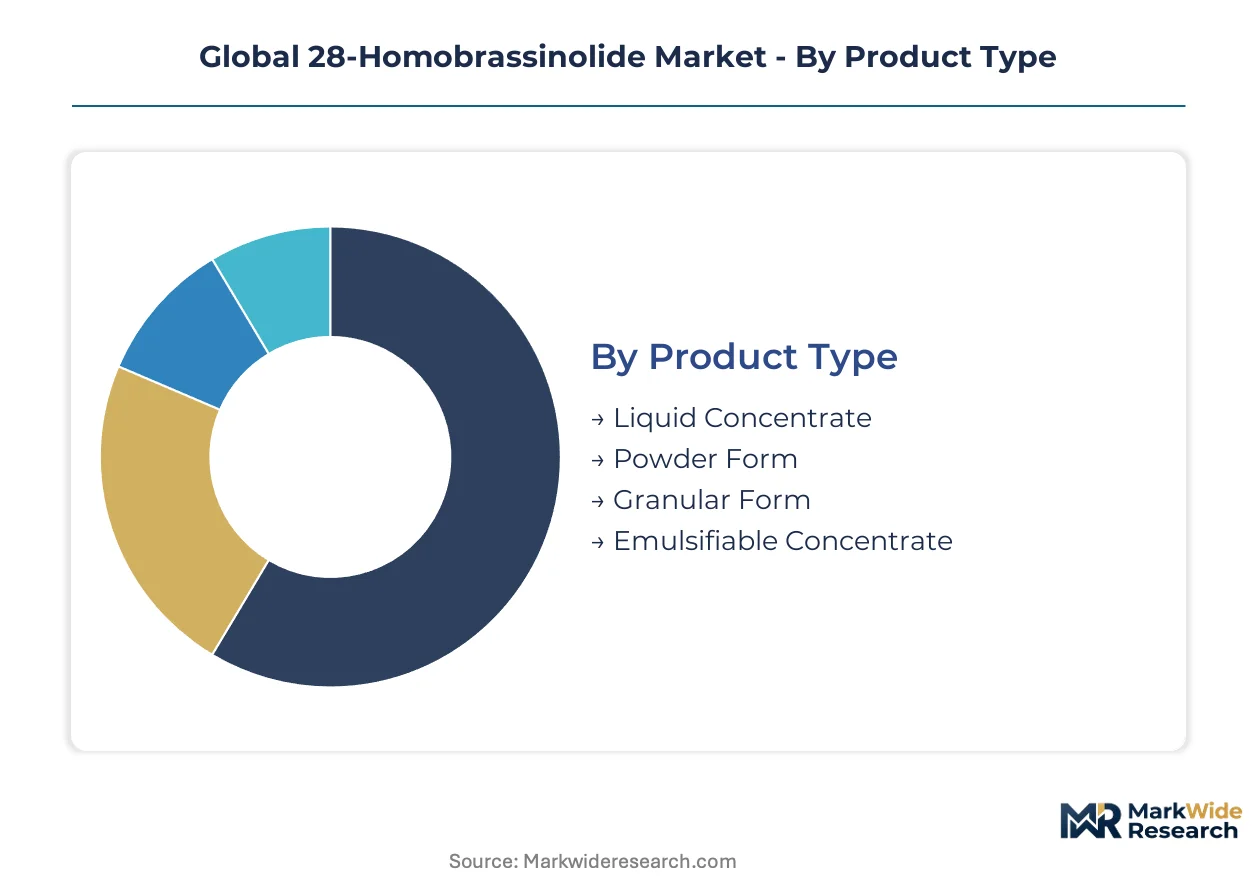
Segmentation in 28-homobrassinolide markets reflects divergent technical requirements across formulation chemistry, crop physiology, and distribution infrastructure. Procurement patterns vary sharply between research-grade purity demands and bulk agricultural applications.
Product Type:
Customization versus standardization tension runs deepest here, with liquid concentrates demanding precision formulation engineering while powder grades compete on feedstock cost optimization.
- Liquid Concentrate:Homogeneous solutions with defined active ingredient solubility enable seamless tank-mix compatibility with fungicide and insecticide programs. Demand concentrates in Benelux and Spanish greenhouse clusters where protected-culture operators require stable shelf-life under variable storage conditions.
- Powder Form:Crystalline active ingredient with defined particle size distribution offers cost-optimized production for domestic Chinese farming enterprises in Shandong and Henan provinces. Zhengzhou Zhengshi Chemical anchors mid-tier supply through campesterol-derived synthesis with streamlined purification.
- Granular Form:Slow-release matrix formulations suit mechanized broadcasting equipment in broadacre oilseed operations across the Canadian prairies.
- Emulsifiable Concentrate:Self-emulsifying oil-in-water systems address tropical humidity challenges in Southeast Asian rice intensification programs.
Leading the category by volume: Powder Form. Expanding most quickly: Liquid Concentrate.
Application:
Margin stratification follows crop value intensity, with high-value protected vegetables commanding formulation premiums versus commoditized broadacre cereals.
- Vegetable Farming:Precision dosing protocols for tomato and pepper fruit set enhancement drive adoption of sensor-integrated application systems. Dutch and Spanish greenhouse operators pilot microencapsulation delivery converging with variable-rate technology, compressing input supply chains into unified crop protection bundles.
- Cereal Crops:Rice and wheat intensification programs in East Asian agricultural cooperatives generate volume demand for certified high-purity grades. China's NMPA residue tightening redirects procurement toward chromatographically validated batches with documented GB standard compliance.
- Horticultural Plants:Ornamental and nursery applications in northern Italy require REACH-registered formulations with tropical stability documentation for export-oriented producers.
- Oilseed Crops:Mature soybean and canola segments in Brazil and Argentina generate thinner margins through bulk multi-season contracts, disincentivizing R&D reinvestment.
Dominant by revenue: Vegetable Farming. Gaining share fastest: Cereal Crops.
End Use Industry:
Procurement sophistication tiers separate institutional research buyers from price-sensitive farming collectives, with seed producers occupying the technical middle ground.
- Seed Producers:Brazilian and Argentine soybean and maize seed treatment operations represent underpenetrated channels where brassinosteroid penetration remains nascent. Early movers achieving US EPA FIFRA tolerance certification capture positioning before residue limits tighten further.
- Agricultural Cooperatives:East Asian rice and wheat intensification programs in China's Shandong and Henan provinces concentrate demand near domestic manufacturing clusters with streamlined logistics.
- Farming Enterprises:Individual operators in Sub-Saharan African markets lacking cold-chain infrastructure drive demand for tropical storage formulation technology.
- Plant Research Institutes:Academic and government laboratories in Japan and South Korea require analytical-grade purity with batch-specific chromatographic certificates for phytohormone mechanism studies.
Highest volume purchaser: Agricultural Cooperatives. Steepest expansion trajectory: Seed Producers.
Packaging Type:
Distribution economics and application scale determine container selection, with small-format precision dosing contrasting bulk logistics efficiency.
- Plastic Bottles:Standard HDPE containers with child-resistant closures dominate retail channels for farming enterprises in Latin American markets.
- Aluminum Cans:Light-blocking metal containers protect photosensitive formulations in high-temperature storage environments across Middle Eastern distribution networks.
- Sachets:Single-use foil laminates enable precise small-batch dosing for greenhouse precision agriculture trials in Dutch protected-culture systems.
- Bulk Containers:Intermediate bulk totes and drum formats serve agricultural cooperative procurement with dedicated tank-mix infrastructure.
Most widely deployed: Plastic Bottles. Fastest-growing format: Sachets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong and Henan provinces concentrate China's 28-homobrassinolide manufacturing capacity, anchoring feedstock-to-formulation supply chains for rice and wheat intensification programs across East Asia.
China
Agricultural cooperatives in Shandong and Henan provinces drive procurement volume for brassinosteroid formulations targeting rice yield enhancement. NMPA residue tightening under GB standards redirects demand toward chromatographically validated high-purity grades. Domestic manufacturers cluster near campesterol feedstock sources in these provinces, streamlining powder-grade production logistics.
United States
Specialty crop seed producers in California's Central Valley and Florida's vegetable belts adopt liquid concentrate tank-mix protocols for precision greenhouse operations. EPA FIFRA pesticide tolerance frameworks regulate residue limits, shaping import eligibility for foreign suppliers. Early movers achieving tolerance certification capture positioning in tomato and pepper fruit set segments before regulatory thresholds tighten.
Netherlands
Protected-culture greenhouse operators in Westland and North Brabant pilot microencapsulation delivery systems converging with sensor networks for variable-rate brassinosteroid application. REACH registration requirements filter uncertified producers from specialty horticultural channels. Benelux procurement teams now demand batch-specific stability documentation for tropical storage conditions.
Brazil
Soybean and maize seed treatment operations in Mato Grosso and Paraná represent underpenetrated channels where brassinosteroid penetration remains nascent. ANVISA phytosanitary regulations govern plant growth regulator import protocols, creating compliance barriers for uncertified Asian suppliers. Argentine cooperatives mirror this pattern, with bulk granular form dominating price-sensitive oilseed contracts.
India
Rice intensification programs in Punjab and Haryana agricultural cooperatives generate volume demand for certified brassinosteroid formulations. CDSCO tightening of plant growth regulator residue limits parallels China's NMPA trajectory, bifurcating procurement toward documented high-purity grades. Domestic formulation demand concentrates near processing clusters in Gujarat and Maharashtra.
Global 28-Homobrassinolide Market Competitive Landscape
Capital-heavy producers compete with asset-light formulation specialists across tiered purity-grade segments. Integrated agrochemical platforms sustain supply consistency through captive steroidal precursor sourcing, while mid-tier powder manufacturers optimize campesterol feedstock costs. Three archetypes dominate: multinational integrated platforms with regulatory documentation depth, regional synthesis specialists serving domestic agricultural cooperatives, and research-grade purity suppliers for institutional laboratories. Competitive moves center on REACH registration completion for European specialty channels and tropical stability validation for Southeast Asian expansion.
Among German-integrated agrochemical platforms, BASF SE anchors premium-tier positioning through formulation stability expertise. Swiss-registered Syngenta AG occupies proprietary shelf-life extension technology for tropical storage conditions. Chinese synthesis specialists including Zhengzhou Zhengshi Chemical represent cost-optimized powder production archetypes, serving mid-tier domestic farming enterprises in Shandong and Henan provinces with streamlined campesterol-derived manufacturing.
| Leading Market Players |
|---|
| BASF SE |
| Syngenta AG |
| Bayer AG |
| FMC Corporation |
| UPL |
| Zhengzhou Zhengshi Chemical |
| Shandong Ench Chemical |
| Zhengzhou Nongda Biochemical |
| TRC |
| Others |
Supply & Pricing Matrix
China's NMPA residue tightening under GB standards is redirecting procurement teams toward chromatographically validated high-purity grades, forcing manufacturers to absorb purity investment costs or surrender import eligibility. Supply response concentrates in Shandong and Henan provinces where domestic producers cluster near campesterol feedstock sources, compressing mid-tier powder margins while premium liquid concentrate pricing holds firm.
Pricing Analysis
Yield-per-hectare outcomes anchor value-based pricing for brassinosteroid formulations, with greenhouse operators in Benelux and Spain paying premiums for documented fruit set enhancement. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered liquid concentrates from mid-tier powder grades and bulk granular oilseed formulations. Pricing pressure stems from campesterol feedstock volatility tied to vegetable oil processing volumes, squeezing powder-grade manufacturers most acutely. Agricultural cooperatives in East Asia exhibit highest price sensitivity, while seed producers in Brazil and Argentina prioritize regulatory documentation over unit cost.
Supply Chain Analysis
Campesterol feedstock supply rests on vegetable oil processing clusters in China, India, and Indonesia, with steroidal precursor availability fluctuating with crushing season volumes. Brassinosteroid active ingredient synthesis draws from brassicasterol and campesterol inputs, while formulation stability depends on proprietary shelf-life chemistry and tropical-condition testing infrastructure. Single-source vulnerability concentrates in Shandong-Henan manufacturing clusters, exposing supply continuity to regional environmental enforcement or logistics disruption. Distribution runs through agricultural cooperative procurement networks in East Asia, specialty horticultural channels in Europe, and seed treatment distributors in Latin America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over campesterol feedstock and in-house tropical stability validation infrastructure separates viable competitors from margin-compressed assemblers.
For Market Incumbents: Lock in supply consistency through backward integration into steroidal precursor sourcing or long-term offtake agreements with vegetable oil processors. Defend premium positioning by completing REACH registration for European specialty channels and accelerating tropical stability certification before Southeast Asian residue limits tighten. Channel control through exclusive distribution partnerships with Brazilian and Argentine seed treatment networks limits entrant access to the fastest-expanding demand segment. For New Entrants and Emerging Players: Sub-Saharan African farming enterprises lacking cold-chain infrastructure represent an underserved buyer archetype accessible through proprietary shelf-life extension formulations. White-space targets include mechanized oilseed operations in the Canadian prairies seeking slow-release granular alternatives, and protected-culture greenhouse pilots in Mexico requiring sensor-integrated microencapsulation systems. A go-to-market angle emphasizing tropical stability documentation without incumbent certification backlogs unlocks distributor relationships in humidity-challenged geographies. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier synthesis specialists possessing campesterol feedstock relationships and latent capacity for purity-grade upgrading given NMPA and CDSCO trajectory convergence. Long-term viability over the coming decade hinges on regulatory documentation depth rather than scale economics alone. Acquisition target archetypes include Chinese powder manufacturers in Shandong and Henan with streamlined logistics and upgradeable purification infrastructure. The signal to watch is batch-specific chromatographic validation becoming mandatory for import eligibility across multiple Asian jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steroidal Precursor Supply | Captive campesterol sourcing insulates margin volatility from vegetable oil processing fluctuations. |
| REACH Registration Completion | Validated documentation unlocks Benelux and northern Italian greenhouse procurement channels. |
| Tropical Stability Certification Program | Accelerated aging infrastructure enables distribution into Southeast Asian and Sub-Saharan markets. |
| Long-term Supply Agreement with Seed Producers | Multi-season contracts with Brazilian soybean operations secure volume before residue limits tighten. |
| Joint Venture for Microencapsulation Technology | Precision delivery convergence with sensor networks captures Dutch and Spanish greenhouse pilots. |
Research Methodology
Multi-period observation of NMPA enforcement patterns, CDSCO registration timelines, and REACH completion rates anchored the trend analysis, supplemented by interviews with plant growth regulator formulators, agricultural cooperative procurement managers, and steroidal precursor suppliers. Primary fieldwork with greenhouse operators in the Netherlands and Spain, seed treatment distributors in Brazil, and powder manufacturers in Shandong province combined with secondary validation from customs trade data, NMPA GB standard filings, and EPA FIFRA tolerance databases. Bottom-up volume triangulation across formulation types, crop applications, and end-use industries converged with top-down market sizing.
Segment-weighting across product type, application, and end-use industry dimensions shaped the analytical framework over the projection horizon. Modeled dimensions included liquid concentrate versus powder versus granular form, vegetable farming versus cereal crops versus oilseed applications, and seed producers versus agricultural cooperatives versus farming enterprises. CAGRs derived from regression analysis of historical procurement volumes against regulatory milestone timing and crop intensification program announcements. Industry-specific forecast inputs incorporated campesterol feedstock price volatility indices and tropical stability testing capacity expansion timelines.
Revisions become necessary when NMPA or CDSCO accelerate residue limit implementation, when campesterol supply disruptions exceed seasonal variation, or when REACH registration requirements expand to additional horticultural segments. Forecasts reflect documented assumptions about regulatory trajectory continuity and feedstock supply elasticity. A small set of named triggers warrants ongoing watch: MEE enforcement intensity in Shandong and Henan, ANVISA phytosanitary protocol alignment with Asian standards, and EPA FIFRA tolerance threshold adjustments for specialty crops.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Dipentene (Limonene) Market
Specialty Chemicals
Asia Pacific Methyl Glucose Market
Specialty Chemicals
Organic Sulfur Market
Specialty Chemicals
Salt Hydrate Market
Specialty Chemicals
Organometallics Market
Specialty Chemicals
Allantoin Market
Specialty Chemicals
Enzyme Inhibitors Market
Specialty Chemicals
Microcrystalline Wax Market
Specialty Chemicals
Asia-Pacific Niacinamide Market
Specialty Chemicals
Halogen-Free Flame Retardants Market
Specialty Chemicals
PPG-20 Methyl Glucose Ether Market
Specialty Chemicals
Specialty Methacrylate Market
Specialty Chemicals
Stearates Market
Specialty Chemicals
Phenylbenzimidazole Sulfonic Acid Market
Specialty Chemicals
Phenyl Trimethicone Market
Specialty Chemicals
Europe Aerosol Cans Market