
 Asia Pacific Bentonite Market | 2026-2036
Asia Pacific Bentonite Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Bentonite Market Outlook
Aftermarket service revenue for drilling fluid reconditioning is narrowing as operators shift toward fresh bentonite procurement to meet stricter downhole performance standards. Imerys leverages its integrated mining and processing footprint across multiple Asia Pacific jurisdictions to secure raw material consistency. Ashapura Group anchors its position through specialized calcium bentonite grades tailored to Indian foundry customers. Minerals Technologies Inc. competes by extending its sodium bentonite supply relationships with oilfield service companies operating in Australia's offshore basins.
Bentonite is a colloidal aluminum phyllosilicate clay composed primarily of montmorillonite, exhibiting high swelling capacity in water and thixotropic viscosity behavior critical to drilling fluid suspension and sealant impermeability. The material functions as a viscosifier, fluid-loss controller, and binder across industrial processes requiring rheological stability or hydraulic containment. Sodium bentonite commands the dominant share of drilling fluid demand due to superior swelling index performance in freshwater systems, while calcium bentonite retains cost advantages in foundry sand binding where lower thermal expansion tolerances apply. Powder form leads volume shipments for construction sealant blending, though pelletized grades are gaining traction in cat litter applications across Japanese and South Korean retail channels.
China's MIIT enforces GB standards governing bentonite purity and heavy metal limits for oilfield chemicals, while India's BIS mandates ISI certification for construction-grade material used in landfill liners and tunnel waterproofing. Australia's TGA oversight of pharmaceutical-grade bentonite for internal use creates a separate compliance tier that filters out smaller processors lacking GMP-aligned facilities. Stakeholders must monitor evolving environmental discharge rules in Indonesia and Vietnam that could restrict dry-stack tailings from bentonite beneficiation, reshaping site selection for new grinding capacity.
Market Dynamics
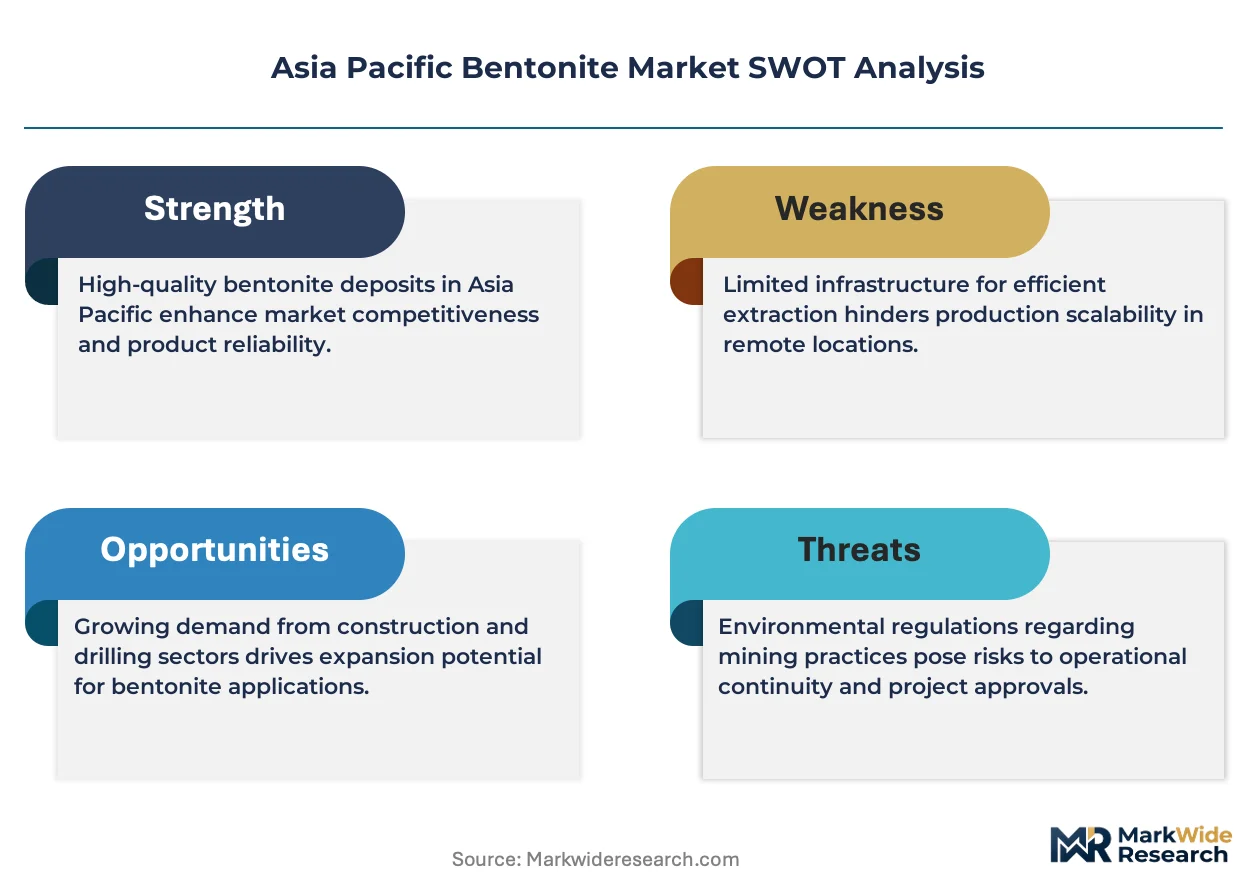
China's MIIT enforcement of GB standards for drilling fluid purity and heavy metal limits is compressing the supplier base, forcing processors to upgrade beneficiation infrastructure or exit the market entirely.
Growth Catalysts
- GB Standard Tightening:China's MIIT mandates stricter bentonite purity thresholds for oilfield chemicals, eliminating subscale processors and concentrating volume among certified suppliers.
- Foundry Sand Binding:Steel casting output expansion in India and China absorbs larger bentonite volumes as foundries seek thermal expansion control in mold applications.
- Shandong-Jiangsu Cluster Density:Petrochemical and metalworking concentration in eastern China's industrial corridor sustains localized demand pull for drilling and sealing grades.
Market Restraints
- Input Cost Volatility:Diesel and electricity price swings directly impact open-pit mining and thermal drying economics for calcium bentonite processors.
- Supply Concentration Risk:Premium sodium bentonite deposits concentrate in select Wyoming-type geological formations outside the Asia Pacific region, creating import dependency.
- Substitution Threat:Polymer-based drilling fluid additives from oilfield chemical suppliers encroach on bentonite's viscosifier role in high-temperature wells.
Strategic Opportunities
- Vietnam Infrastructure Buildout:Tunnel waterproofing and landfill liner mandates under Vietnam's environmental ministry create construction-grade demand in an underpenetrated market.
- Pharmaceutical-Grade Certification:Australia's TGA oversight of ingestible bentonite for detoxification applications rewards GMP-aligned processors with pricing premiums.
- Pelletized Cat Litter Channel:Japanese and South Korean retail chains are expanding shelf space for bentonite-based clumping litter, displacing silica gel alternatives.
Industry Challenges
- Beneficiation Skill Shortage:Dry-stack tailings management and wet-process quality control require specialized mineral processing engineers scarce in Indonesia and Vietnam.
- BIS Certification Timelines:India's ISI mark approval for construction-grade bentonite involves 12-18 month testing cycles that delay market entry for new suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Bentonite Market |
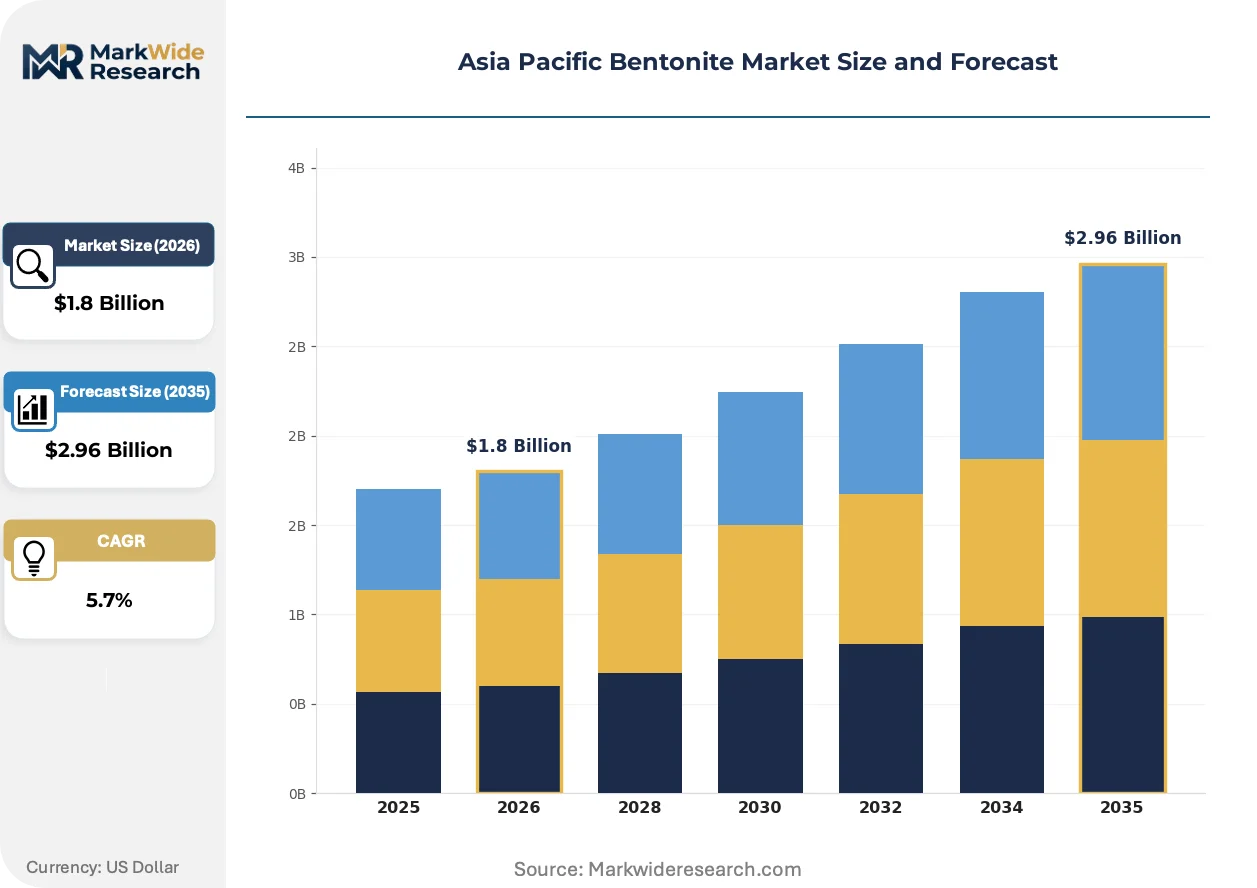
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Bentonite, Calcium Bentonite, Potassium Bentonite, Aluminum Bentonite End Use Industry: Construction, Oil & Gas, Agriculture, Pharmaceuticals Form: Powder, Granules, Pellets, Liquid Application: Drilling Fluids, Cat Litter, Foundry Sand, Sealants |
| Companies Covered | Imerys, Minerals Technologies Inc., Ashapura Group, Pacific Bentonite Ltd., Black Hills Bentonite, LLC, Kunimine Industries Co. Ltd, Clariant AG, Bentonite Performance Minerals LLC., Wyo-Ben Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Bentonite Market Strategic Shifts
Processing technology and regulatory compliance frameworks are restructuring competitive advantage, with digital quality control and environmental accountability separating viable suppliers from marginal operators.
High-shear mixing with inline rheology monitoring is migrating from batch processing to continuous-flow systems. Indian foundry sand blenders adopt this to reduce thermal shock defects in steel castings. The technology is migrating from premium automotive casting lines to standard industrial foundries, compressing tolerance for uncontrolled viscosity variation.
China's MIIT is tightening GB 5005.1 standards for drilling fluid bentonite, mandating lower quartz content and stricter heavy metal ceilings. Beneficiation plants must install magnetic separation and acid-wash circuits to comply. Offshore drilling contractors in Australia's Bass Strait now specify certified-grade sodium bentonite exclusively, rejecting blended or reclaimed material.
Direct procurement from mine-mouth processors is displacing layered distributor networks in Japan's construction chemicals sector. Large waterproofing contractors now contract Shandong-based grinding facilities for containerized bentonite shipments, bypassing Tokyo trading houses. The shift is most visible in tunnel segment projects where just-in-time delivery and lot-traceability dominate supplier selection.
Asia Pacific Bentonite Market Segmentation
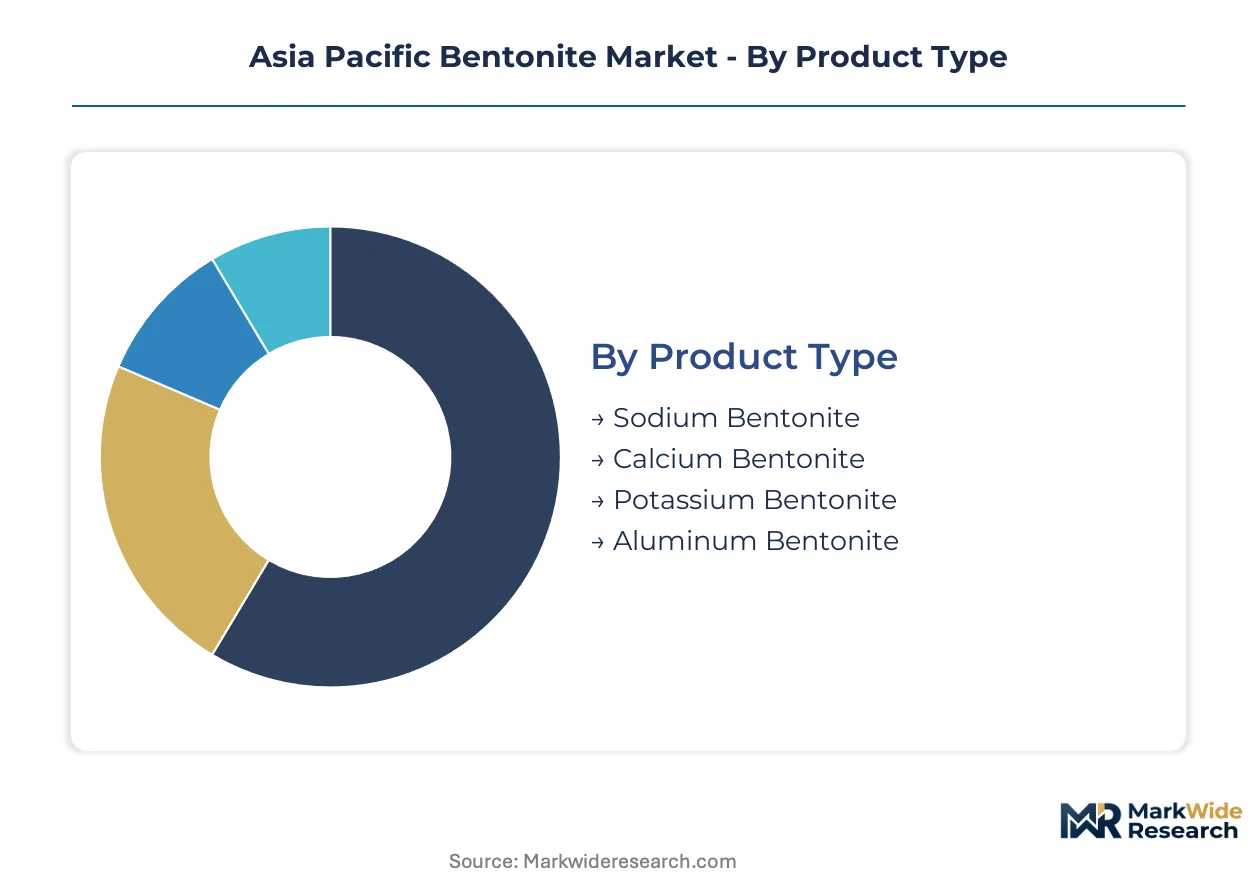
Bentonite's functional diversity across swelling capacity, rheology control, and binding strength creates distinct value pools by chemistry, form, and end-use specification. Segmentation reveals where technical differentiation commands pricing power versus where commoditization compresses margins.
Product Type:
Sodium bentonite turns inventory fastest in drilling fluid supply chains, while aluminum grades sit longest in specialty chemical distribution.
- Sodium Bentonite:Montmorillonite-rich clay with superior swelling index in freshwater systems, essential for viscosity and fluid-loss control in oilfield applications. Demand concentrates in Australia's offshore basins where drilling contractors specify certified grades exclusively, rejecting reclaimed material under tightening performance standards.
- Calcium Bentonite:Lower swelling capacity than sodium grades but cost-advantaged for thermal expansion control in foundry sand binding. Indian steel casting clusters in Gujarat and Maharashtra absorb volume as mold-makers seek consistent green strength under BIS-monitored quality regimes.
- Potassium Bentonite:Modified ionic composition for specific shale inhibition requirements in drilling fluids, serving niche high-temperature well segments.
- Aluminum Bentonite:Specialty grade for catalyst support and adsorbent applications, moving through pharmaceutical and chemical processing channels with extended qualification cycles.
Sodium bentonite dominates installed base. Calcium bentonite is where expansion concentrates.
End Use Industry:
Cost tier separation runs deepest between specification-critical oilfield buyers and price-sensitive agricultural blenders.
- Construction:Sealant and waterproofing applications in tunneling and landfill liner systems, governed by India's BIS ISI certification and China's GB standards for impermeability performance. Shandong-Jiangsu corridor contractors drive volume through direct mine-mouth procurement.
- Oil & Gas:Drilling fluid viscosifiers and lost-circulation materials for onshore and offshore operations. Australia's Bass Strait contractors now mandate fresh bentonite over reconditioned material, compressing aftermarket service revenue.
- Agriculture:Soil amendment and animal feed binder applications, competing with alternative clay minerals on cost per ton rather than technical specification.
- Pharmaceuticals:Ingestible detoxification and topical preparations under Australia's TGA oversight, rewarding GMP-aligned processors with substantial pricing premiums over industrial grades.
Oil & gas commands highest per-ton value. Construction delivers volume scale.
Form:
Volume throughput varies tenfold between bulk powder shipments and packaged liquid dispersions.
- Powder:Standard grind for construction sealant blending and foundry sand preparation, shipped in bulk containers to grinding facilities across eastern China.
- Granules:Intermediate sizing for controlled-release agricultural applications and certain drilling fluid blends.
- Pellets:Engineered clumping substrates for cat litter, gaining shelf space in Japanese and South Korean retail chains as silica gel alternatives face displacement.
- Liquid:Pre-hydrated suspensions for automated drilling fluid systems, reducing on-site mixing labor but adding freight cost.
Powder moves the greatest tonnage. Pellets are climbing the fastest.
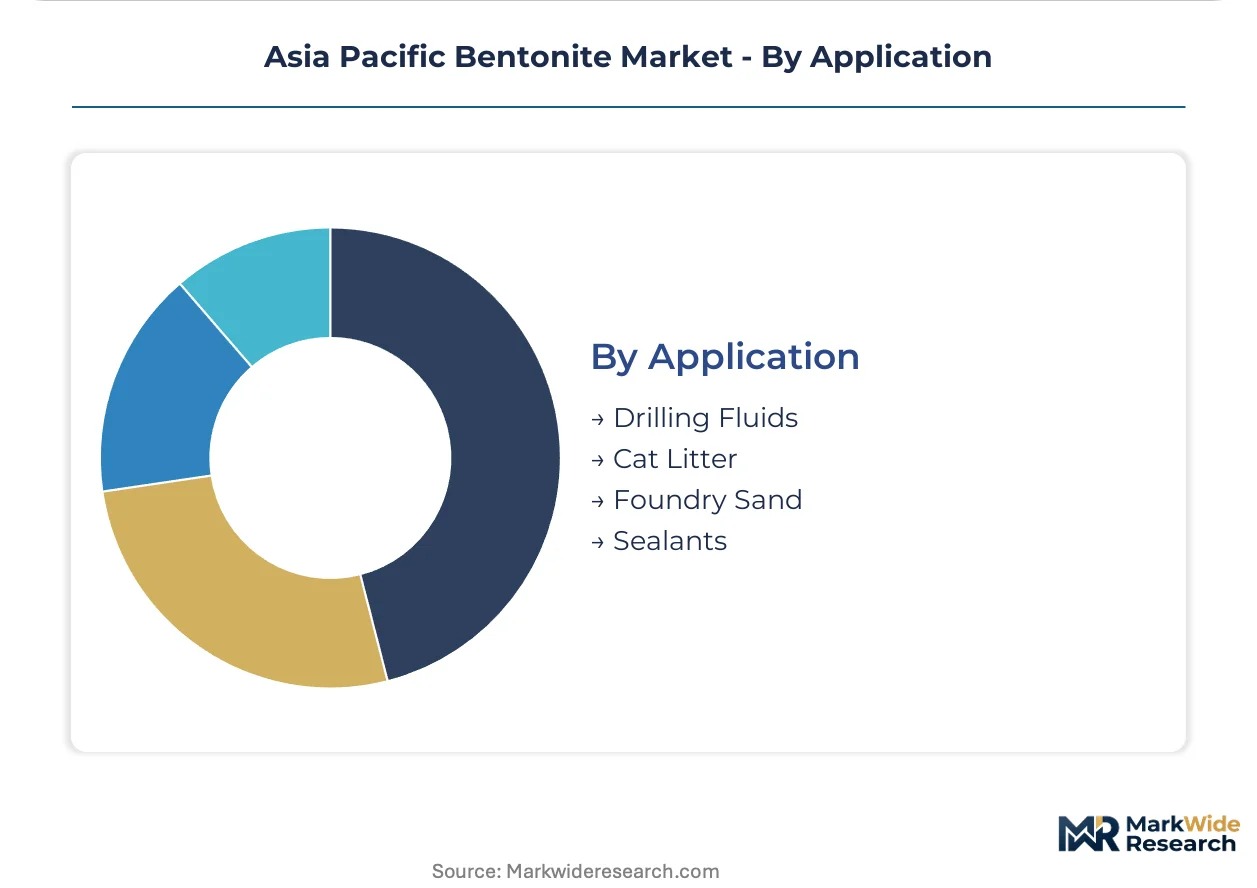
Application:
Customer concentration separates fragmented cat litter retail from consolidated oilfield procurement.
- Drilling Fluids:Rheology stabilization and borehole sealing for oil and gas extraction, with China's MIIT tightening GB 5005.1 purity thresholds that eliminate subscale processors.
- Cat Litter:Clumping pet care products, with Japanese retail chains expanding bentonite-based offerings and South Korean distributors following.
- Foundry Sand:Mold binding for steel casting in India and China, where high-shear mixing with inline rheology monitoring is migrating from premium automotive lines to standard industrial foundries.
- Sealants:Waterproofing membranes and tunnel segment gaskets, with Vietnam's infrastructure buildout creating new demand under environmental ministry mandates.
Drilling fluids anchor revenue stability. Foundry sand is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the region: China and India prioritize foundry-grade calcium bentonite for steel casting, while Australia and offshore Southeast Asian markets specify premium sodium bentonite for drilling fluids under tightening performance standards.
China
Steel casting expansion in Shandong and Jiangsu provinces absorbs substantial calcium bentonite volumes for mold binding applications. MIIT enforcement of GB 5005.1 standards for drilling fluid purity eliminates subscale processors, concentrating supply among certified beneficiation plants. Petrochemical clusters along the Yangtze River Delta sustain localized demand for sealant-grade material in tunnel waterproofing projects.
India
Foundry sand binding dominates consumption as Gujarat and Maharashtra steel casting clusters seek consistent green strength under thermal stress. BIS mandates 12-18 month ISI certification timelines for construction-grade bentonite used in landfill liners, filtering out smaller importers. Direct procurement relationships are displacing layered distributor networks for large infrastructure contractors.
Australia
Offshore drilling contractors in the Bass Strait specify certified-grade sodium bentonite exclusively, rejecting reclaimed or blended material. TGA oversight of pharmaceutical-grade bentonite for ingestible detoxification applications rewards GMP-aligned processors with substantial pricing premiums. Western Australian mining operations generate ancillary demand for drilling fluid additives in exploration campaigns.
Japan
Retail chains are expanding shelf space for pelletized bentonite cat litter, displacing silica gel alternatives in pet care channels. METI industrial standards govern construction sealant specifications for tunnel segment waterproofing in Tokyo-Osaka corridor infrastructure projects. Kansai region distributors maintain specialized inventory for foundry customers serving automotive component manufacturers.
Vietnam
Environmental ministry mandates for tunnel waterproofing and landfill liner systems are creating construction-grade demand in an underpenetrated market. Beneficiation skill shortages in dry-stack tailings management constrain local processing capacity expansion. Northern province infrastructure buildout around Hanoi and Hai Phong is absorbing imported powder shipments for sealant blending operations.
Asia Pacific Bentonite Market Competitive Environment
Capability concentration sits with integrated mining-to-processing operators; scale advantage sits with diversified industrial mineral conglomerates. The supplier base compresses around three strategic archetypes: Wyoming-linked sodium bentonite importers serving oilfield specifications, Indian calcium bentonite specialists aligned with foundry clusters, and Asia-Pacific integrated processors controlling mine-mouth grinding capacity. Dominant competitive moves include backward integration into captive bentonite mining and geographic expansion through containerized shipment contracts bypassing traditional trading houses.
Among Asia-Pacific integrated processors, Ashapura Group occupies a position exemplifying the foundry-specialist archetype through its calcium bentonite focus on Indian steel casting customers. Minerals Technologies Inc. and Imerys represent the diversified industrial mineral tier, with the former anchoring sodium bentonite supply relationships in Australian offshore basins and the latter leveraging multi-jurisdictional processing footprints for raw material consistency. These three entities illustrate the capability-scale tension reshaping supplier positioning.
| Leading Market Players |
|---|
| Imerys |
| Minerals Technologies Inc. |
| Ashapura Group |
| Pacific Bentonite Ltd. |
| Black Hills Bentonite, LLC |
| Kunimine Industries Co. Ltd |
| Clariant AG |
| Bentonite Performance Minerals LLC. |
| Wyo-Ben Inc |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Shandong grinding facilities is compressing spot-market premiums while tightening GB 5005.1 certification timelines concentrate pricing power among MIIT-compliant suppliers. Diesel and electricity cost volatility feeds directly into calcium bentonite processing economics, forcing operators to choose between margin sacrifice and volume reduction.
Pricing Analysis
Long-term offtake contracts dominate sodium bentonite procurement for Australian offshore drilling contractors, insulating certified suppliers from spot-price erosion. Three-tier pricing structure across pharmaceutical-grade, construction-certified, and industrial-standard levels reflects BIS ISI and TGA compliance investments. Pricing pressure stems from polymer-based drilling fluid additives encroaching on viscosifier applications. Agricultural blenders exhibit highest price sensitivity, while oilfield service companies prioritize performance consistency over per-ton savings.
Supply Chain Analysis
Tariff exposure between Wyoming deposit operators and Asia Pacific processors dominates supply chain risk assessment for premium sodium bentonite grades. Geographic supply concentrates in China's Shandong-Jiangsu corridor, India's Gujarat-Maharashtra foundry belt, and Australia's Bass Strait logistics hubs. Raw material dependencies rest on diesel fuel for open-pit extraction, thermal drying energy, and containerized ocean freight capacity. Single-source vulnerability from Wyoming-type geological formations outside the region creates import dependency for high-swelling-index material. Distribution runs through direct mine-mouth contracts displacing Tokyo trading house intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat environment where BIS ISI and MIIT GB certification timelines create regulatory entrenchment, locking in incumbent advantages through 12-18 month approval cycles that new entrants cannot shortcut.
For Market Incumbents: Entrench position through backward integration into captive bentonite mining in Rajasthan and Xinjiang, eliminating raw material arbitrage risk. Accelerate high-shear mixing technology deployment to capture foundry sand binding upgrades as Indian automotive casting lines migrate from batch to continuous-flow processing. Polymer substitution threats in high-temperature drilling applications demand R&D investment in hybrid bentonite-polymer formulations. For New Entrants and Emerging Players: Build out Vietnam infrastructure buildout exposure through sealant-grade powder supply relationships with Hanoi-Hai Phong waterproofing contractors, bypassing established Shandong supply chains. The underpenetrated Vietnamese tunnel and landfill liner market offers lowest certification friction relative to BIS or MIIT jurisdictions. Go-to-market angle: containerized just-in-time delivery with lot-traceability documentation matching Japanese contractor specifications. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across beneficiation infrastructure as magnetic separation and acid-wash circuit investments become mandatory for GB 5005.1 compliance. Five-to-ten year viability favors processors with GMP-aligned facilities capable of pharmaceutical-grade certification under TGA oversight. Acquisition target archetype: integrated mine-mouth operators in India or China with existing foundry relationships and unutilized grinding capacity. Signal to watch: MIIT enforcement actions eliminating subscale processors, compressing certified supplier counts and expanding margin pools for survivors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Mining | Rajasthan and Xinjiang deposit control secures raw material consistency against Wyoming import dependency. |
| GB 5005.1 Certification Investment | MIIT compliance eliminates subscale competitors and concentrates volume among certified beneficiation plants. |
| High-Shear Mixing Technology Deployment | Inline rheology monitoring captures Indian foundry migration from automotive to industrial casting lines. |
| Direct Mine-Mouth Procurement Contracts | Containerized shipments to Japanese waterproofing contractors displace Tokyo trading house intermediaries. |
| GMP-Aligned Facility Construction | TGA pharmaceutical-grade certification unlocks substantial pricing premiums in Australian detoxification applications. |
Study Parameters
Desk research of customs trade records, BIS certification databases, and MIIT regulatory filings preceded structured interviews with beneficiation plant managers, foundry procurement leads at Gujarat steel casting clusters, oilfield service company technical directors, and construction chemical distributors across the Shandong-Jiangsu corridor. Primary intelligence combined with secondary validation from SEC filings of diversified industrial mineral conglomerates and Australian TGA registration data. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down production capacity assessments across China, India, and Australia.
Assumptions held fixed include current GB 5005.1 and BIS ISI certification standards, existing Wyoming deposit export volumes to Asia Pacific, and baseline diesel-electricity cost ratios for open-pit mining economics. Variables stress-tested encompass polymer substitution rates in drilling fluids, Vietnam infrastructure spending trajectories, and TGA pharmaceutical-grade demand elasticity. Segmentation modeling spanned product chemistry tiers, end-use industry specifications, physical form factors, and regional production hub capacity utilization. CAGRs were derived from fitted growth curves calibrated to historical foundry sand and drilling fluid consumption patterns.
Stress conditions across diesel price volatility, BIS certification timeline extensions, and MIIT enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these assumptions and risk factors including Indonesia-Vietnam environmental discharge rule changes affecting dry-stack tailings operations. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Nepheline Syenite Market
Industrial Minerals
Mineral Salt Ingredients Market
Industrial Minerals
India Feed Minerals Market
Industrial Minerals
Fluorspar Market
Industrial Minerals
Olivine Sand Market
Industrial Minerals
Diatomite Mining Market
Industrial Minerals
Chelated Minerals Market
Industrial Minerals
Europe Frac Sand Market
Industrial Minerals
Europe Diatomite Market
Industrial Minerals
Potash Ores Market
Industrial Minerals
Middle East Feed Minerals Market
Industrial Minerals
Potassium Schoenite Market
Industrial Minerals
North America Limestone Market
Industrial Minerals
Boron Minerals and Chemicals Market
Industrial Minerals
Seaweed Derived Minerals Market
Industrial Minerals
Gluconate Mineral Market