
 North America Perms and Relaxants Market | 2026-2036
North America Perms and Relaxants Market Size, Share, and Industry Trends Forecast 2026-2036
North America Perms and Relaxants Market Analytics
Professional salon distribution is tilting toward consolidated beauty supply networks that serve independent stylists and franchise chains. L'Oréal S.A. anchors this channel through specialized professional divisions that control educator-led training programs. Henkel AG & Co. KGaA competes via Schwarzkopf Professional's salon-exclusive lines that leverage color-perm combination protocols. Procter & Gamble Co. navigates the mass-premium boundary with relaxed-texture products distributed through dual salon-retail pathways.
Perms and relaxants comprise chemical reconditioning systems that alter hair keratin structure through reduction-oxidation cycles, typically employing ammonium thioglycolate or sodium hydroxide at controlled pH levels to achieve permanent wave or straightening outcomes. These formulations serve both aesthetic transformation and textured-hair manageability needs across consumer and professional settings. Relaxing creams lead product-type revenue due to sustained demand in African-American and Latino consumer bases, while natural extract ingredient types represent the fastest-expanding margin pool as clean-label preferences intensify. Salon application channels dominate volume, though home-use kits are gaining structural presence through subscription beauty services.
The U.S. FDA oversees cosmetic safety through voluntary adverse-event reporting and ingredient disclosure requirements under the Modernization of Cosmetics Regulation Act, while Health Canada mandates stricter ingredient prohibitions through its Hotlist that directly limits relaxant formulation options. State-level legislation in California under Proposition 65 creates additional compliance layers for formaldehyde-releasing preservatives commonly found in neutralizer systems. Stakeholders must monitor evolving federal preemption debates and patchwork state standards that could fragment formulation requirements across the U.S.-Canada trade corridor.
Market Dynamics
Clean-beauty mandates at state level are forcing wholesale reformulation of neutralizer systems, compressing development cycles and elevating R&D spend as the dominant cost driver across the competitive set.
Growth Catalysts
- California Proposition 65:Formaldehyde disclosure requirements are accelerating migration to thio-free and cysteamine-based alternatives among professional formulators seeking liability protection.
- Multicultural salon density:Metropolitan clusters in Houston and Los Angeles concentrate demand for textured-hair services, creating predictable volume anchors for supply chain planning.
- Subscription beauty services:Direct-to-consumer kit models are expanding addressable market reach beyond traditional salon-dependent consumers into time-constrained professional segments.
Market Restraints
- Raw material concentration:Sodium hydroxide and ammonium thioglycolate supply concentrates among specialty chemical producers in the US Gulf Coast, exposing formulators to hurricane-season disruption risk.
- Health Canada Hotlist:Stricter ingredient prohibitions than FDA standards fragment formulation portfolios, forcing dual-SKU strategies that inflate inventory carrying costs.
- Natural hair movement:Chemical-free styling preferences among younger African-American consumers are compressing relaxant frequency and lifetime customer value in core demographic segments.
Strategic Opportunities
- Texas metro expansion:Underserved salon networks in Dallas-Fort Worth and San Antonio offer first-mover positioning for educator-led professional distribution models.
- Botanical keratin alternatives:Convergence of plant-derived bond-building technologies with traditional reduction chemistry opens premium positioning at 40-60% gross margin tiers.
- State-level clean-beauty mandates:New York and Illinois are drafting disclosure requirements that will favor early reformulators with compliant portfolios already validated for California.
Industry Challenges
- Cosmetology licensure gaps:Chemical texture service certification varies across state boards, creating liability exposure for manufacturers whose educator programs train on non-standardized protocols.
- Legacy neutralizer inventory:Formaldehyde-releasing systems still dominate wholesale beauty supply channels, complicating trade-in programs for next-generation formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Perms and Relaxants Market |
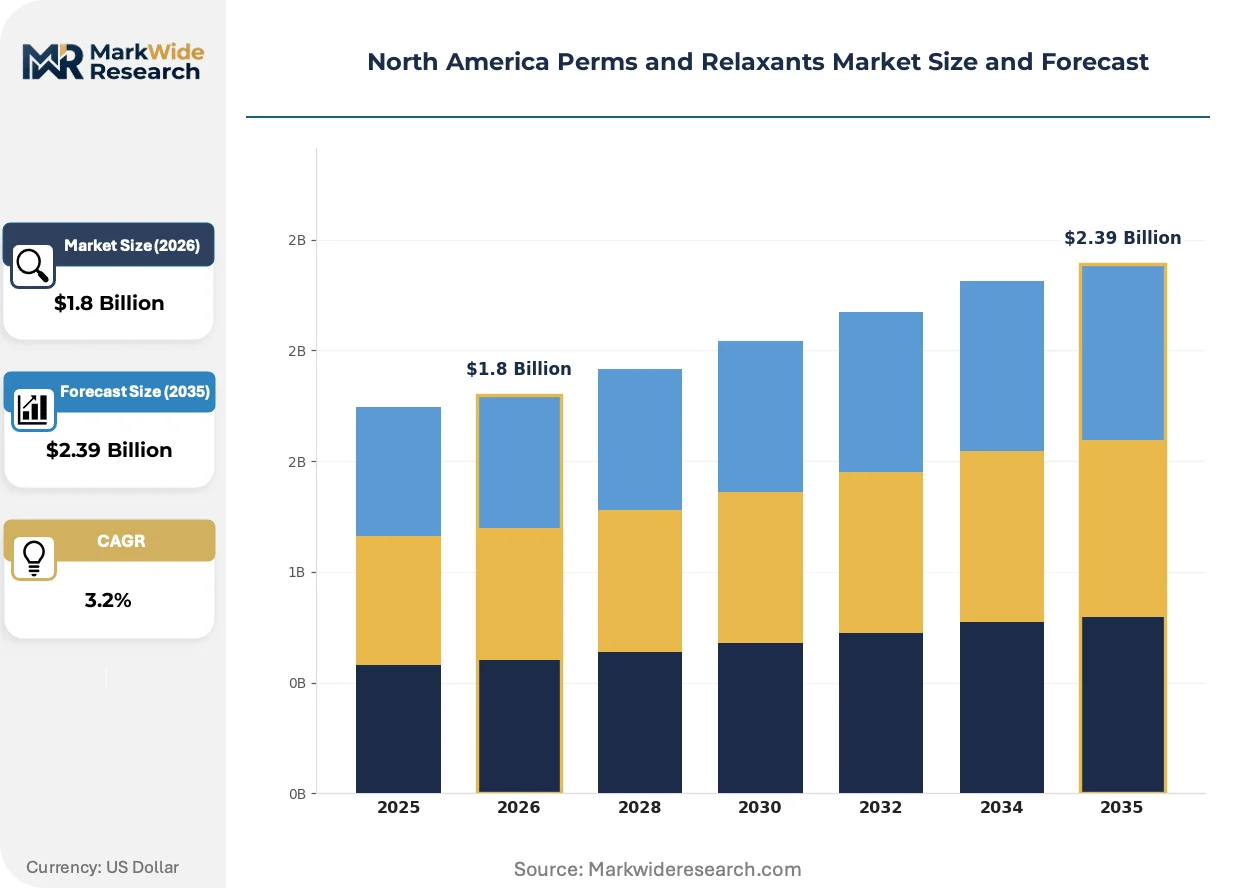
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.39 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Perming Solutions, Relaxing Creams, Neutralizers, Color-Gel Systems Application: Salons, Home Use, Professional Use, Spa Treatment Ingredient Type: Sulfates, Ammonium Thioglycolate, Hydroxides, Natural Extracts Customer Demographics: Women, Men, Teenagers, Seniors |
| Companies Covered | L'Oréal S.A., Henkel AG & Co. KGaA, Procter & Gamble Co., Coty Inc., Unilever PLC, Jotoco Corp., Makarizo International, Kadus Professionals, Revlon, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Perms and Relaxants Market Evolving Landscape
Formulation chemistry is bifurcating between high-performance alkaloid systems and clean-label botanical alternatives, with professional education networks serving as the primary transmission mechanism for technical adoption.
Hybrid cysteamine-thioglycolate systems is hybridizing traditional perm architecture by combining reduced odor profiles with accelerated processing times. Independent stylists in California and New York are adopting these platforms at twice the rate of franchise chains. The technology is compressing service duration from 90 to 45 minutes, enabling higher chair-turn economics in premium urban salons.
The Modernization of Cosmetics Regulation Act is imposing mandatory adverse-event reporting and facility registration requirements that previously operated on voluntary compliance. Manufacturers must now maintain batch-level traceability systems that add 12-18 months to product development timelines. Professional-only brands with existing quality-management infrastructure are absorbing compliance costs more efficiently than mass-market entrants.
Salon-exclusive distribution is fragmenting as independent stylists bypass consolidated beauty supply networks through direct manufacturer purchasing portals. Franchise chains are responding with captive private-label programs that lock in stylist loyalty through exclusive formulation access. Texas and Florida display the most pronounced channel disintermediation, where lower state-level regulatory friction accelerates direct procurement experimentation.
North America Perms and Relaxants Market Segmentation
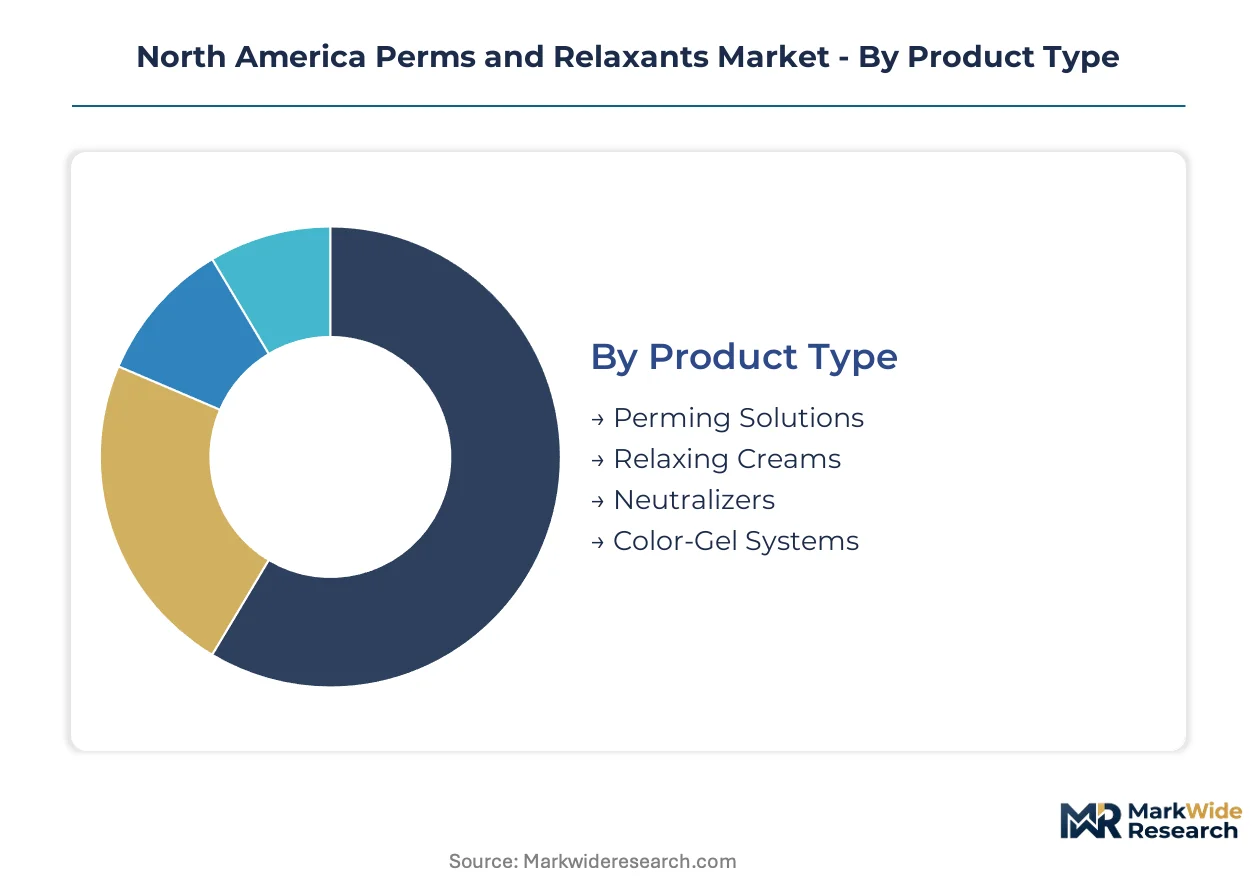
Segmentation in perms and relaxants determines formulation complexity, regulatory exposure, and service protocol requirements. Each category maps distinct supply chain configurations and margin structures that shape competitive positioning across professional and consumer channels.
Product Type:
After-sales service intensity varies sharply by product type, with professional-only systems demanding educator-led technical support and home-use kits requiring digital troubleshooting infrastructure.
- Relaxing Creams:Sodium hydroxide or calcium hydroxide-based alkaline formulations permanently straighten tightly coiled hair through cysteine bond cleavage. Demand concentrates in Houston and Los Angeles salon clusters serving African-American and Latino clientele, where stylist certification programs drive brand loyalty through repeated service cycles.
- Perming Solutions:Ammonium thioglycolate or glyceryl thioglycolate systems create permanent waves via reduction-oxidation cycling at controlled pH. California metropolitan networks favor low-odor cysteamine hybrids that compress processing time while reducing respiratory exposure liability for independent stylists.
- Neutralizers:Hydrogen peroxide or sodium bromate-based oxidizing agents reform disulfide bonds in waved or relaxed hair. These formulations face Proposition 65 disclosure pressure in California.
- Color-Gel Systems:Hybrid perm-color combination products streamline salon service protocols. Texas franchise chains show early adoption of these time-compressing platforms.
Relaxing creams hold the largest share; momentum sits with color-gel systems.
Application:
Volume distribution across application channels reflects labor cost differentials and regulatory friction in state-level cosmetology governance.
- Salons:Licensed cosmetologists perform chemical texture services under state board protocols with mandatory ventilation and patch testing requirements. California and Texas account for concentrated demand due to multicultural demographics and dense metropolitan stylist networks.
- Professional Use:Mobile stylists and booth renters operating outside franchise structures purchase through direct manufacturer portals. Florida shows pronounced channel disintermediation as independent practitioners bypass consolidated beauty supply distributors.
- Home Use:Consumer-directed kits with simplified application instructions and pre-measured components. Subscription beauty services are expanding reach into time-constrained professional segments across New York and Illinois.
- Spa Treatment:Premium hospitality venues offering chemical texture services alongside wellness positioning. Limited penetration outside luxury urban markets.
Salon channels dominate volume; home-use applications are climbing the fastest.
Ingredient Type:
Margin structures diverge between commodity alkaloid feedstocks and botanical positioning premiums that command shelf-space allocation in clean-beauty retail.
- Natural Extracts:Plant-derived bond-building technologies using cysteine from fermented sources or hydrolyzed vegetable proteins. California Proposition 65 compliance and New York draft disclosure requirements favor early reformulators with validated clean-label portfolios.
- Ammonium Thioglycolate:Traditional reducing agent for permanent waving with established efficacy and odor profiles. Supply concentrates among US Gulf Coast specialty chemical producers.
- Hydroxides:Sodium, calcium, and lithium hydroxide systems for hair straightening at high pH. Health Canada Hotlist restrictions fragment formulation portfolios versus FDA standards.
- Sulfates:Surfactant components for cleansing and product penetration enhancement. Facing clean-beauty substitution pressure in premium positioning tiers.
Hydroxides retain the largest installed base; natural extracts show the steepest expansion trajectory.
Customer Demographics:
Service frequency and lifetime value calculations vary by demographic cohort due to hair growth cycles, style transition patterns, and chemical treatment tolerance.
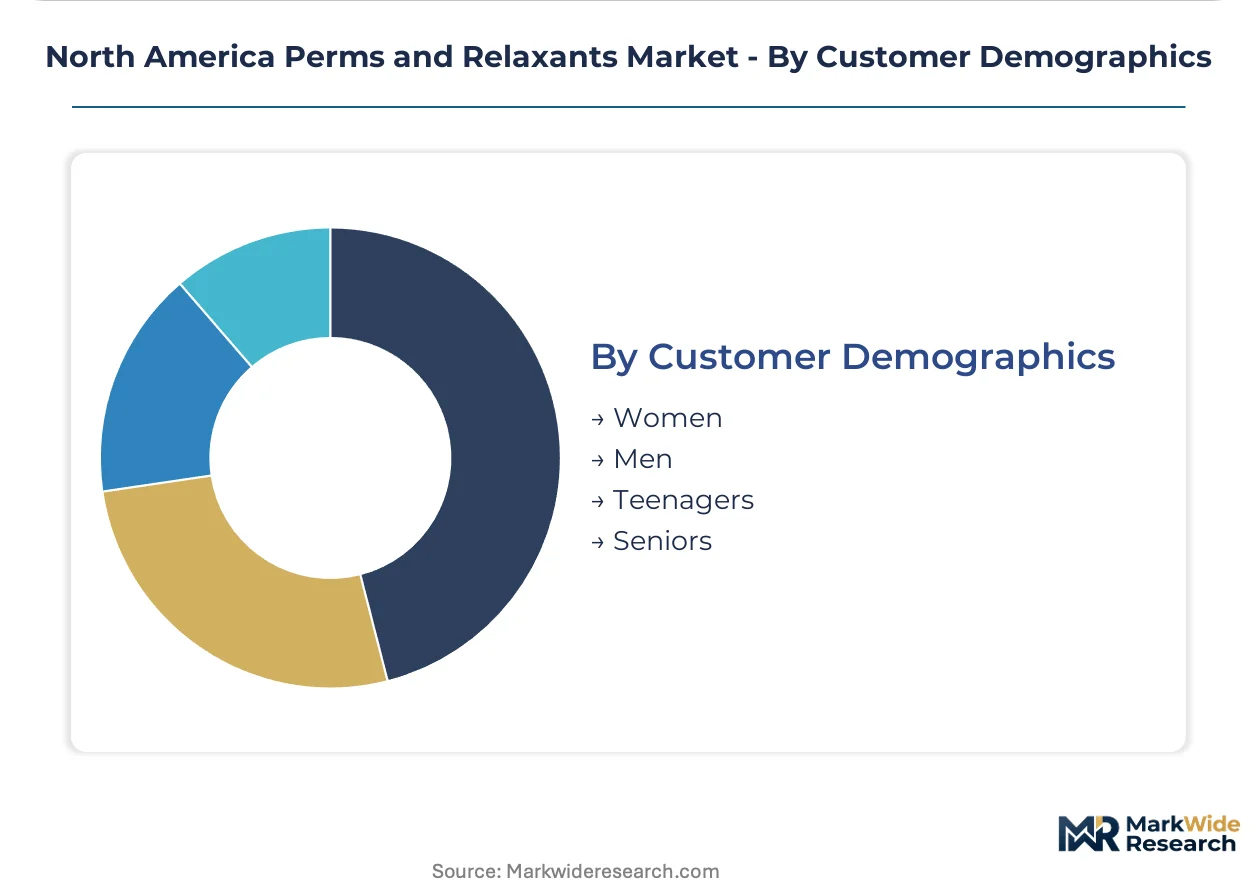
- Women:Core revenue base across all product categories with highest service frequency in textured-hair segments. California and Texas multicultural populations drive concentrated consumption.
- Teenagers:First chemical treatment decisions influenced by social media styling trends and peer recommendation networks. Subscription kit models target this cohort's price sensitivity and digital-native purchasing behavior.
- Men:Growing acceptance of permanent waving and straightening services in metropolitan markets. Barbershop channel expansion in Texas and Florida creates alternative distribution pathways.
- Seniors:Gray hair texture management needs with specific formulation requirements for reduced elasticity and porosity. Underrepresented in current product development pipelines.
Women command the largest share; teenagers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Houston's petrochemical corridor underwrites Texas's dominance in perms and relaxants manufacturing, while the I-35 freight spine connects formulation plants to salon distribution networks across the central United States.
United States
California and Texas concentrate consumption through multicultural demographics and dense metropolitan salon networks. The FDA's Modernization of Cosmetics Regulation Act imposes mandatory adverse-event reporting and facility registration requirements that extend product development timelines. Houston and Los Angeles anchor professional distribution channels where independent stylists drive adoption of low-odor cysteamine formulations.
Canada
Toronto and Montreal salon clusters generate concentrated demand for textured-hair services among African-Canadian and Caribbean-Canadian populations. Health Canada's Hotlist enforces stricter ingredient prohibitions than FDA standards, fragmenting formulation portfolios for cross-border suppliers. Ontario's beauty supply distributors absorb compliance costs through dual-SKU inventory strategies serving provincial professional channels.
Mexico
Mexico City and Guadalajara metropolitan areas concentrate professional salon services with expanding demand for premium chemical texture treatments. COFEPRIS cosmetic registration requirements create regulatory friction for imported formulations containing sodium hydroxide at elevated concentrations. Northern border states display pronounced channel disintermediation as stylists source directly from Texas-based manufacturer portals.
North America Perms and Relaxants Market Competitive Landscape
On the supply side, the industry is consolidating around multinational chemical conglomerates with captive professional education networks and regional specialty formulators serving fragmented salon channels. Three archetypes dominate: Paris-based beauty conglomerates with professional divisions controlling educator-led training programs, German chemical specialists leveraging salon-exclusive distribution protocols, and American mass-market players navigating dual salon-retail pathways. Competitive moves concentrate on portfolio diversification into botanical keratin alternatives and geographic expansion through direct-to-stylist purchasing portals.
Within the professional-education archetype, L'Oréal S.A. and Henkel AG & Co. KGaA exemplify the integrated model where specialized divisions anchor stylist loyalty through certification programs. Procter & Gamble Co. occupies a hybrid position bridging mass-market scale with professional channel access. These three entities represent the dominant competitive anchors shaping formulation standards and distribution architecture across North American salon networks.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Henkel AG & Co. KGaA |
| Procter & Gamble Co. |
| Coty Inc. |
| Unilever PLC |
| Jotoco Corp. |
| Makarizo International |
| Kadus Professionals |
| Revlon, Inc. |
| Others |
Value Network & Pricing Analysis
Undercapacity in Texas Gulf Coast thioglycolate production is compressing supplier margins while elevating pricing leverage for specialty chemical producers serving professional salon formulators. This utilization squeeze propagates through contract renegotiation cycles, pushing raw material pass-through clauses deeper into manufacturer-processor agreements.
Pricing Analysis
Volume-discount tiering separates salon-exclusive professional lines from mass-market retail kits from subscription direct-to-consumer offerings. Certification-grade differentiation separates FDA-registered facility production from contract-manufactured alternatives, with California Proposition 65 compliance adding a third pricing stratum. Pricing pressure stems from clean-beauty reformulation costs that manufacturers struggle to fully recover in wholesale beauty supply channels. Franchise chains show lowest price sensitivity due to captive volume commitments; independent stylists operating through direct portals exhibit highest elasticity.
Supply Chain Analysis
Hurricane-season disruption risk along the Texas-Louisiana petrochemical corridor dominates supply chain vulnerability assessments for North American formulators. Sodium hydroxide and ammonium thioglycolate feedstock production concentrates in US Gulf Coast facilities, with secondary sourcing from German and Japanese specialty chemical exporters. Single-source vulnerability intensifies for cysteamine-based alternatives where fermentation-derived inputs rest on limited biomanufacturing capacity. Distribution runs through consolidated beauty supply networks serving franchise chains, while independent stylists accelerate disintermediation through direct manufacturer portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America perms and relaxants market sits in early-cycle expansion as subscription beauty services penetrate time-constrained professional segments previously locked out of salon-dependent consumption. This channel innovation extends addressable market reach without requiring proportional salon infrastructure investment.
For Market Incumbents: Insulate professional channel margins by accelerating captive supply integration into botanical keratin alternative feedstocks. Deepen educator-led certification programs in Texas metro expansion zones before competitive training networks establish presence. Counter direct-to-stylist disintermediation through exclusive formulation access locked to loyalty volume commitments.
For New Entrants and Emerging Players: Build out subscription kit infrastructure targeting teenage and young professional demographics with simplified application protocols and digital troubleshooting support. Penetrate Dallas-Fort Worth and San Antonio salon networks where educator-led distribution remains undersupplied relative to multicultural service demand. Anchor go-to-market execution through social-native styling influencer partnerships rather than traditional beauty supply distributor relationships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across clean-label reformulation pipelines as batch-level traceability systems extend development timelines. Long-term viability favors targets with existing FDA facility registration and California Proposition 65 validated portfolios that absorb compliance costs more efficiently than mass-market entrants. Monitor Health Canada Hotlist expansion signals as early indicators of cross-border formulation standardization pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Botanical Keratin Alternative Development | Plant-derived bond-building technologies open premium positioning tiers compliant with California Proposition 65 disclosure mandates. |
| Educator-Led Professional Distribution Expansion | Certification programs in Texas metro clusters lock stylist loyalty before competitive training networks establish presence. |
| Direct-to-Stylist Portal Investment | Bypassing consolidated beauty supply networks captures margin compression from channel disintermediation in Florida and Texas. |
| Dual-SKU Portfolio Construction | Parallel formulation tracks satisfy Health Canada Hotlist restrictions without sacrificing FDA-compliant US market access. |
| Subscription Kit Infrastructure Buildout | Pre-measured home-use components extend reach into time-constrained professional segments across New York and Illinois. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA adverse-event reporting databases, Health Canada cosmetic ingredient Hotlist amendments, and state-level clean-beauty legislative tracking. Interviews with professional salon owners, beauty supply distributors, formulation chemists at specialty chemical producers, and cosmetology state board officials combined with trade data from US Gulf Coast petrochemical customs records and salon industry association membership files. Bottom-up volume estimates from metropolitan cluster sampling triangulate against top-down market sizing from manufacturer shipment disclosures.
Forecast inputs incorporate product type segmentation across relaxing creams, perming solutions, neutralizers, and color-gel systems; application channel splits between salon, professional direct-use, home-use kits, and spa treatment; and ingredient type trajectories from hydroxide alkaloids through natural extract alternatives. Modeled CAGRs derive from historical growth pattern regression adjusted for regulatory inflection points and channel shift elasticity parameters. Cross-border formulation divergence between FDA and Health Canada standards represents a key scenario variable.
The forecast holds incumbent behavior within observed patterns; aggressive moves by direct-to-consumer subscription entrants or accelerated state-level clean-beauty mandate adoption would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Cellulose Ether Market
Specialty Chemicals
Silver Iodide Market
Specialty Chemicals
Salicylate Market
Specialty Chemicals
Toner Spray Market
Specialty Chemicals
Diisobutyl Adipate Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
Bio-Wax Market
Specialty Chemicals
Methyltrimethoxysilane Market
Specialty Chemicals
Copovidone Market
Specialty Chemicals
Global Foam Blowing Agents Market
Specialty Chemicals
Cellulose Derivatives Market
Specialty Chemicals
Global Lactobionic Acid Market
Specialty Chemicals
Sodium Hyaluronate Market
Specialty Chemicals
Tetrabromobisphenol a (TBBPA) Market
Specialty Chemicals
Keratin Products Market
Specialty Chemicals
Metominostrobin Market