
 Mexoryl SX (Ecamsule) Market | 2026-2036
Mexoryl SX (Ecamsule) Market Size, Share, and Industry Trends Forecast 2026-2036
Mexoryl SX (Ecamsule) Market Foresight
Asset-light contract manufacturing and toll-processing arrangements are reshaping competitive entry in Mexoryl SX production. L'Oréal S.A. leverages captive synthesis capacity and patent estates to dominate pharmaceutical-grade supply. Biosynth Carbosynth anchors the research chemical segment with catalog distribution across institutional buyers. MFCI Co., Ltd. competes on intermediate manufacturing scale for downstream formulators.
Mexoryl SX, or terephthalylidene dicamphor sulfonic acid, is a water-soluble organic UV-A filter synthesized through sulfonation of camphor-derived precursors, with peak absorption near 345 nanometers; it serves primarily as a photostable broad-spectrum protector in topical dermatological formulations. The sunscreen category leads volume consumption due to regulatory mandates for UV-A labeling in the European Union and Japan, though dermatological applications capture premium pricing through clinic-dispensed protocols. Online retail channels are expanding fastest among distribution pathways, while pharmacies sustain margin pools through pharmacist-counseled SPF recommendations.
Europe's ECHA evaluates UV filters under REACH authorization protocols, while the FDA regulates ecamsule through the over-the-counter sunscreen monograph process in the United States, creating divergent compliance pathways that fragment formulation strategies across jurisdictions. France's ANSM enforces cosmetic safety reporting that reinforces domestic manufacturing concentration. Stakeholders must monitor pending FDA monograph updates and EU Green Deal chemical restriction timelines to align R&D pipelines with evolving barrier-to-market requirements.
Market Dynamics
Patent-protected manufacturing infrastructure in France is creating supply-side concentration that shapes competitive entry and pricing power across the Mexoryl SX value chain, forcing downstream formulators into toll-processing arrangements or captive sourcing deals.
Growth Catalysts
- REACH authorization protocols:ECHA's escalating scrutiny of conventional UV filters under EU chemical safety frameworks is accelerating formulator migration toward photostable benzylidene camphor derivatives with superior toxicological profiles.
- Dermatology clinic protocols:Professional channel expansion through spa and clinic dispensing is capturing premium pricing tiers for pharmaceutical-grade ecamsule formulations with documented photostability data.
- UV-A labeling mandates:Regulatory requirements in Japan and the European Union for broad-spectrum sunscreen claims are embedding Mexoryl SX as a baseline ingredient in SPF product development pipelines.
Market Restraints
- Camphor derivative input volatility:Sulfonation precursor costs fluctuate with turpentine feedstock availability from Southeast Asian plantation harvest cycles.
- Single-country production concentration:L'Oréal's captive synthesis infrastructure in France creates supply vulnerability for non-integrated formulators lacking toll-processing contracts.
- FDA monograph divergence:The United States over-the-counter sunscreen regulatory pathway treats ecamsule as a non-monographed active, requiring New Drug Application investment that fragments formulation strategies.
Strategic Opportunities
- Online retail channel expansion:Direct-to-consumer SPF brands are bypassing pharmacy intermediaries, creating demand for bulk intermediate supply to digital-native cosmetic formulators.
- Research chemical institutional procurement:Academic dermatology and photobiology laboratories are scaling catalog purchases for mechanism-of-UV-protection studies.
- EU Green Deal chemical restriction timelines:Anticipated phase-outs of reef-toxic UV filters are positioning water-soluble organic alternatives for beach-market formulation switches.
Industry Challenges
- Sulfonation process engineering expertise:Specialized organic synthesis talent capable of stereoselective camphor functionalization remains concentrated among legacy French chemical engineering programs.
- Photostability certification timelines:Third-party validation of UV-A protection persistence under solar simulator exposure protocols extends product development cycles for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexoryl SX (Ecamsule) Market |
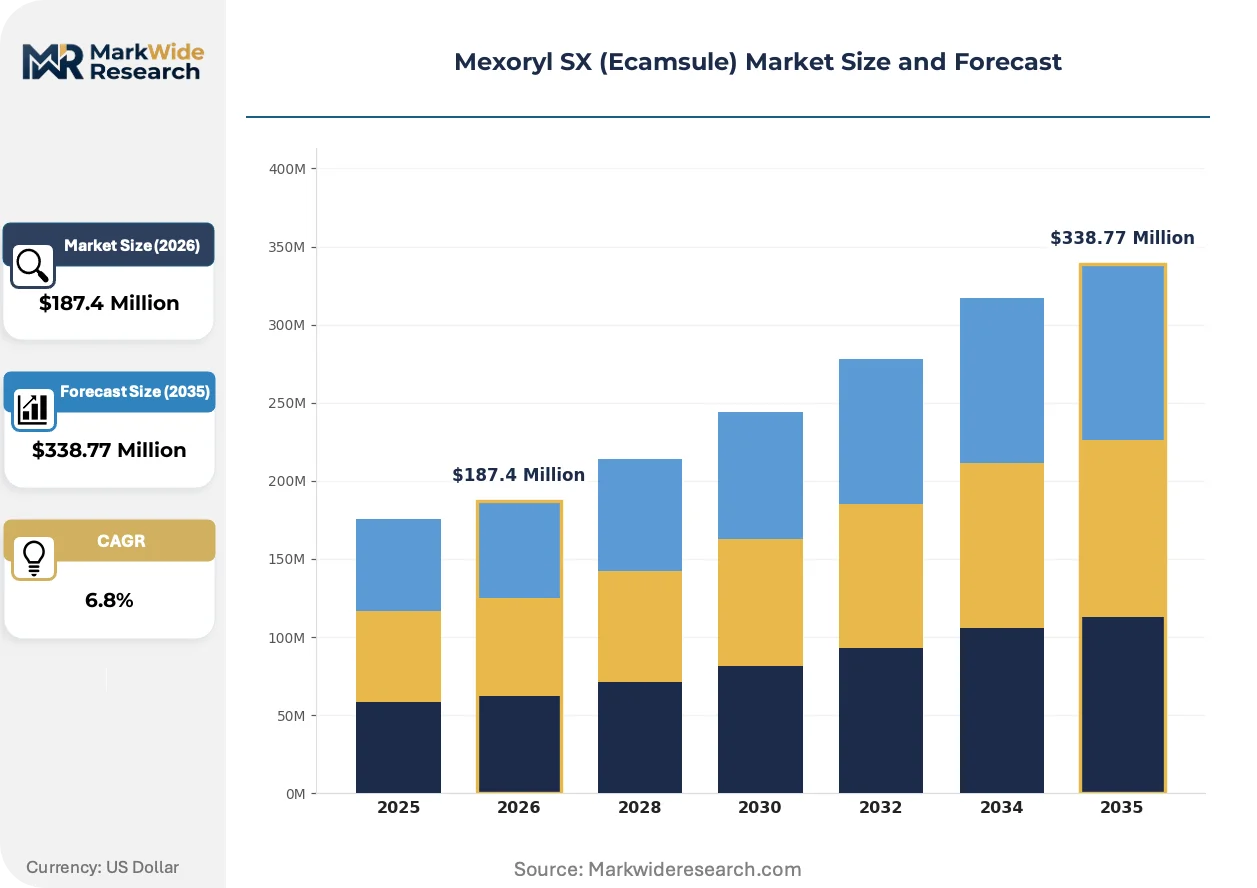
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sunscreen, Moisturizer, Lotion, Cream Application: Commercial, Personal Care, Dermatological, Cosmetic Distribution Channel: Online Retail, Pharmacies, Supermarkets, Specialty Stores End User: Adults, Children, Spa Professionals, Dermatologists |
| Companies Covered | L'Oréal S.A., Biosynth Carbosynth, ChemScene LLC, National Analytical Corporation, Norna Technology Co., Skylead Pharmaceuticals & Chemicals, MFCI Co., Ltd., Parchem Fine and Specialty Chemicals, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexoryl SX (Ecamsule) Market Shifts & Advancements
Reformulation pressures from chemical safety regulators are compressing development cycles and forcing ingredient substitution decisions across sunscreen and dermatological product portfolios.
Encapsulation technologies using silica-based matrices are extending photostability duration for water-soluble UV filters in aqueous formulations. Premium cosmetic brands in Japan and South Korea are integrating these delivery systems into next-generation SPF launches. Conventional unencapsulated ecamsule is rendering obsolete in high-end product lines where degradation kinetics determine competitive positioning.
France's ANSM is tightening cosmetic safety reporting requirements for UV filter concentration thresholds in leave-on products. This regulatory friction is pushing formulators toward lower-concentration, higher-efficacy formulation architectures. The professional dermatology channel is responding with clinic-compounded protocols that bypass mass-market concentration limits.
Pharmacy-counseled SPF recommendations are losing share to algorithm-driven online skin assessment tools that personalize UV protection regimens. Direct-to-consumer brands are capturing this behavioral shift through subscription replenishment models. This pattern is most pronounced in urban French and German markets where digital health integration accelerates purchasing decision compression.
Mexoryl SX (Ecamsule) Market Segmentation
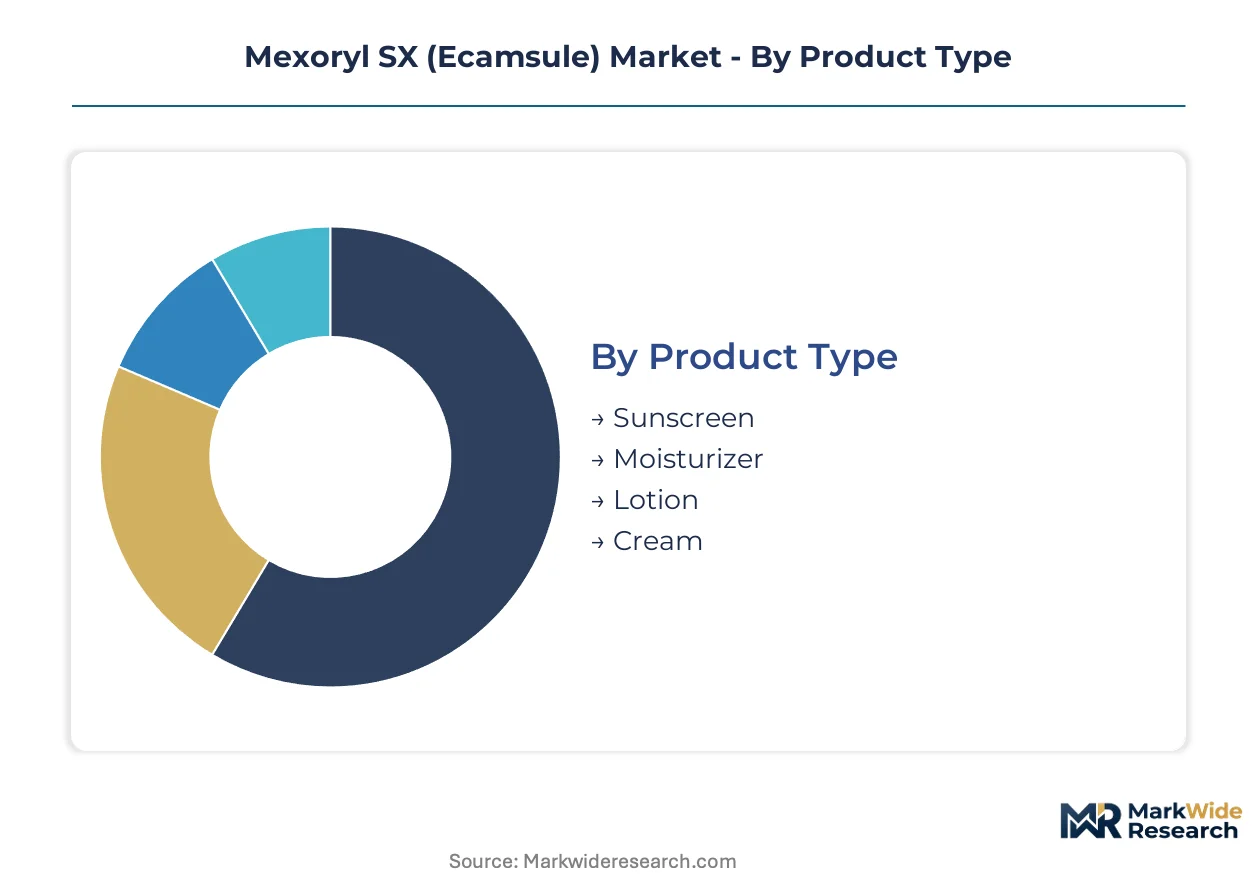
Mexoryl SX formulation requirements diverge sharply across delivery formats and professional contexts, with photostability specifications and concentration thresholds varying by end-use environment. Understanding these segment boundaries clarifies procurement patterns and margin architecture for ingredient suppliers.
Product Type:
The use-case spectrum spans mass-market daily wear to clinic-dispensed therapeutic protocols, with each format imposing distinct solubility and sensory requirements on ecamsule incorporation.
- Sunscreen:SPF formulations demand water-soluble UV-A protection at concentrations meeting EU and Japanese broad-spectrum labeling mandates. Beach and sport variants prioritize photostability under prolonged solar exposure, driving demand for encapsulated ecamsule grades in premium product lines.
- Moisturizer:Daily facial hydrators incorporate lower ecamsule loads for incidental UV exposure, with texture and cosmetic elegance determining competitive positioning. Korean and French dermocosmetic brands dominate formulation innovation in this hybrid protection-plus-hydration category.
- Lotion:Body-care applications favor cost-optimized ecamsule intermediates for high-volume production, with spreadability and dry-down time as critical sensory parameters.
- Cream:Richer emulsion bases accommodate higher active concentrations for photodermatosis patients, with pharmacy-dispensed therapeutic creams capturing premium pricing tiers.
The dominant share belongs to Sunscreen, while Moisturizer is closing the gap fastest.
Application:
Cost tier stratification separates commodity personal care from reimbursed dermatological protocols, with regulatory pathway complexity determining margin capture.
- Commercial:Salon and spa bulk procurement focuses on professional-grade ecamsule with documented batch photostability certification. Treatment protocols in French and Japanese aesthetic clinics specify pharmaceutical-grade supply chains with full traceability documentation.
- Personal Care:Mass-market daily use products prioritize cost-efficient intermediate sourcing, with online direct-to-consumer brands compressing traditional pharmacy distribution margins through subscription replenishment models.
- Dermatological:Clinic-compounded formulations for photosensitivity disorders require ANSM-registered active pharmaceutical ingredient status, creating supply exclusivity for L'Oréal's captive manufacturing infrastructure.
- Cosmetic:Color cosmetics with integrated UV protection represent a formulation growth vector, with South Korean cushion compact and BB cream innovations driving novel delivery system development.
Dermatological applications command the highest unit economics, though Personal Care generates the largest absolute volume throughput.
Distribution Channel:
Customer type concentration shapes procurement scale and technical service requirements, with institutional buyers demanding specification documentation that diverges from consumer-facing channels.
- Online Retail:Digital-native SPF brands bypass pharmacy intermediaries, sourcing bulk ecamsule intermediates for in-house formulation. Algorithm-driven skin assessment tools in urban French and German markets accelerate purchasing decision compression for personalized UV protection regimens.
- Pharmacies:Pharmacist-counseled SPF recommendations sustain margin pools through trust-based authority, though share erosion to direct-to-consumer channels is pronounced in digitally integrated metropolitan markets.
- Supermarkets:Mass-market volume placement depends on price-optimized formulation architectures, with private-label expansion in European grocery chains pressuring branded supplier margins.
- Specialty Stores:Sephora and equivalent beauty retailers curate premium dermocosmetic assortments, with ecamsule-containing products from L'Oréal's La Roche-Posay and Vichy portfolios anchoring UV protection category sets.
Pharmacies retain the largest revenue share, yet Online Retail demonstrates the steepest expansion trajectory among channel pathways.
End User:
Volume concentration among adult daily users contrasts with professional channel premium capture, where specification documentation and training support create supplier stickiness.
- Adults:Daily facial SPF application drives baseline demand, with anti-aging positioning in premium segments justifying higher ecamsule concentrations and advanced delivery systems.
- Children:Pediatric formulations face stringent safety testing requirements, with mineral-filter hybrid architectures preferred for sensitive skin claims despite ecamsule's favorable photostability profile.
- Spa Professionals:Aesthetic clinic dispensing protocols capture premium pricing through treatment bundling, with professional liability considerations driving preference for documented photostability data.
- Dermatologists:Prescription-compounded photoprotection for lupus and porphyria patients requires pharmaceutical-grade ecamsule with full analytical certification, creating the most stringent supply qualification barriers.
Adults constitute the foundational demand base, while Dermatologists represent the highest-value access point per treated patient.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's ANSM cosmetic safety mandates and L'Oréal's patent-protected manufacturing cluster have concentrated pharmaceutical-grade ecamsule supply in Western Europe. Japan's PMDA broad-spectrum labeling requirements and South Korea's MFDS dermocosmetic regulations are accelerating UV-A filter adoption across East Asian formulation hubs.
France
Paris-based dermatology clinics drive premium demand for clinic-dispensed photoprotection protocols. ANSM enforces tightening cosmetic safety reporting for UV filter concentration thresholds in leave-on products. The Île-de-France region hosts L'Oréal's captive synthesis infrastructure, anchoring regional supply for pharmaceutical-grade ecamsule.
United States
FDA over-the-counter sunscreen monograph divergence treats ecamsule as non-monographed, forcing New Drug Application investment for commercialization. Digital-native SPF brands in California and New York Metro bypass traditional pharmacy channels through direct-to-consumer subscription models. Algorithm-driven skin assessment tools accelerate purchasing decision compression in urban coastal markets.
Japan
MFDS-mandated UV-A labeling requirements embed Mexoryl SX as a baseline ingredient in broad-spectrum sunscreen development. METI oversight of cosmetic ingredient safety reinforces preference for photostable organic filters with documented toxicological profiles. Tokyo-Osaka corridor dermocosmetic brands pioneer silica-matrix encapsulation technologies for premium SPF launches.
Germany
ECHA REACH authorization protocols scrutinize conventional UV filters, accelerating formulator migration toward benzylidene camphor derivatives. Berlin and Munich-based aesthetic clinics specify professional-grade ecamsule with full photostability certification. Pharmacy-counseled SPF recommendations sustain margin pools despite erosion to digital channels in metropolitan areas.
South Korea
MFDS cosmetic safety frameworks align with K-beauty export requirements, positioning water-soluble UV filters for cushion compact and BB cream innovations. Seoul Capital Area formulators integrate encapsulated ecamsule into next-generation color cosmetics with integrated photoprotection. Domestic brands leverage subscription replenishment models to capture algorithm-driven skin assessment adoption.
Mexoryl SX (Ecamsule) Market Competitive Landscape
On the supply side, the industry is bifurcated between captive pharmaceutical-grade synthesis and catalog research chemical distribution. Patent-protected manufacturing infrastructure in France creates asymmetric access for downstream formulators lacking toll-processing arrangements. Two strategic archetypes dominate: integrated beauty conglomerates with in-house active ingredient production, and specialized intermediate suppliers serving institutional research buyers. Competitive moves center on capacity reservation contracts and geographic licensing arrangements for regulated markets.
Within the integrated conglomerate tier, L'Oréal S.A. anchors pharmaceutical-grade supply through captive French manufacturing infrastructure. Biosynth Carbosynth exemplifies the research chemical archetype with catalog distribution across academic dermatology and photobiology laboratories. MFCI Co., Ltd. occupies a position among intermediate manufacturers supplying downstream formulators with cost-optimized ecamsule grades for high-volume personal care applications.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Biosynth Carbosynth |
| ChemScene LLC |
| National Analytical Corporation |
| Norna Technology Co. |
| Skylead Pharmaceuticals & Chemicals |
| MFCI Co., Ltd. |
| Parchem Fine and Specialty Chemicals |
| Merck KGaA |
| Others |
Supply & Pricing Matrix
L'Oréal's captive synthesis infrastructure in France captures upstream margin pools, forcing downstream formulators into toll-processing arrangements or premium-priced intermediate sourcing. This concentration funnels pricing power toward pharmaceutical-grade certification holders while squeezing commodity-tier suppliers.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade ecamsule and research-chemical catalog grades. Three-tier pricing structure across premium, standard, and economy levels reflects ANSM registration status, photostability documentation depth, and batch traceability protocols. Cost compression in high-volume personal care tiers is intensifying because Korean and Chinese intermediate suppliers are expanding sulfonation capacity. Mass-market personal care brands exhibit highest price sensitivity, while dermatology clinic protocols show lowest sensitivity due to reimbursed therapeutic positioning.
Supply Chain Analysis
Tariff exposure between France and post-Brexit UK markets dominates supply chain risk planning for ecamsule distributors. Manufacturing concentrates in France, China, and South Korea, with French facilities holding pharmaceutical-grade exclusivity. Sulfonation precursors draw from turpentine feedstock anchored in Southeast Asian plantation harvests. Single-source vulnerability persists for non-integrated formulators lacking toll-processing contracts with L'Oréal's captive infrastructure. Distribution runs through specialty chemical distributors for institutional buyers and direct bulk contracts for integrated beauty conglomerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation between FDA monograph divergence and EU REACH authorization protocols is fragmenting demand into jurisdiction-specific formulation niches, creating entry points for specialized suppliers.
For Market Incumbents: Pre-empt Korean intermediate manufacturers by securing long-term turpentine offtake agreements from Indonesian and Malaysian plantation operators. Deepen backward integration into camphor derivative precursors before sulfonation cost advantages shift to East Asian competitors. Lock in capacity reservation contracts with French toll-processors to defend pharmaceutical-grade supply exclusivity against emerging Chinese entrants seeking ANSM registration.
For New Entrants and Emerging Players: Mid-tier personal care brands in Germany and Japan represent the most penetrable entry point for non-integrated ecamsule suppliers lacking L'Oréal's patent position. Online direct-to-consumer SPF formulators in California and New York Metro bypass FDA monograph barriers through cosmetic-grade positioning, creating demand for research-chemical catalog grades. Target institutional dermatology laboratories with photostability certification services as a service-layer wedge before upstream manufacturing investment.
For Investors and Strategic Acquirers: Capital is best deployed toward toll-processing specialists with existing ANSM relationships and sulfonation engineering talent pipelines from French chemical engineering programs. Long-term viability hinges on regulatory arbitrage capabilities across FDA, ECHA, and MFDS jurisdictions. Watch for FDA monograph updates covering ecamsule as the critical inflection signal determining whether New Drug Application investment becomes mandatory for US market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Camphor Precursors | Secures turpentine feedstock access against Southeast Asian harvest volatility. |
| ANSM Pharmaceutical-Grade Registration | Unlocks clinic-compounded dermatology protocols with premium pricing tiers. |
| Silica-Matrix Encapsulation Partnership | Extends photostability duration for Japanese and South Korean premium SPF launches. |
| Direct-to-Consumer Channel Expansion | Bypasses pharmacy intermediaries in German and French metropolitan markets. |
| Long-Term Toll-Processing Agreement | Guarantees ecamsule supply continuity amid L'Oréal's captive capacity constraints. |
Research Methodology
A spread of perspectives from dermatology clinic procurement managers, cosmetic formulator R&D directors, sulfonation process engineers, and specialty chemical distributors converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation from ANSM cosmetic safety filings, ECHA REACH authorization databases, FDA OTC monograph dockets, and Japanese PMDA broad-spectrum labeling guidelines. Bottom-up segmentation modeling and top-down market sizing triangulated volume and value estimates.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework. Segmentation dimensions modeled include product type, application, distribution channel, and end user, with regulatory jurisdiction clusters as an industry-specific overlay. CAGRs derived from historical volume trajectories, patent expiration timelines, and substitution elasticity for benzylidene camphor derivatives. Forecast inputs incorporated ECHA chemical restriction timelines and FDA monograph update probabilities.
Practitioners should monitor ECHA Green Deal UV filter phase-out announcements and FDA ecamsule monograph inclusion decisions for early signals of demand inflection. Forecasts reflect documented assumptions about regulatory pathway stability and sulfonation capacity expansion rates. Material shifts in REACH authorization scope or turpentine feedstock trade flows would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Natural Insect Repellent Market
Specialty Chemicals
Polyacrylamide Gel Electrophoresis (PAGE) Market
Specialty Chemicals
Freeze-Thaw Stabilizers Market
Specialty Chemicals
Fixing Agent Market
Specialty Chemicals
Rosin Press Market
Specialty Chemicals
Palm Methyl Ester Derivatives Market
Specialty Chemicals
Lanolin Market
Specialty Chemicals
Bio-Ketones Market
Specialty Chemicals
Diindolylmethane Market
Specialty Chemicals
Photo Emulsion Market
Specialty Chemicals
Global Tetrahexyldecyl Ascorbate Market
Specialty Chemicals
Global Curing Agents Market
Specialty Chemicals
Perms and Relaxants Market
Specialty Chemicals
Polyglycerol Sebacate (PGS) Market
Specialty Chemicals
Calcium D-Pantothenate Market
Specialty Chemicals
Propyl Isovalerate Market