
 Organo-Modified Siloxanes Market | 2026-2036
Organo-Modified Siloxanes Market Size, Share, and Industry Trends Forecast 2026-2036
Organo-Modified Siloxanes Market Analytics
German chemical producers is shifting capacity toward higher-margin organo-functional siloxane derivatives. Wacker Chemie AG leverages its integrated silicon metal-to-silicone value chain to sustain cost advantages in silicone fluids. Dow Inc. anchors North American supply through controlled hydrolysis and condensation processes. Evonik Industries differentiates via specialty silicone resins for high-performance coatings.
Organo-modified siloxanes comprise polydimethylsiloxane backbones grafted with organic functional groups such as polyether, amino, or epoxy substituents, yielding surface-active compounds with tunable hydrophilic-lipophilic balance. These materials function primarily as surfactants, defoamers, and conditioning agents across industrial and consumer formulations. Silicone fluids dominate volume flows due to their established use in personal care and textile processing, while silicone resins command margin concentration in protective coatings for electronics and automotive applications. Chemical synthesis technology leads investment intensity as producers pursue atom-efficient routes to reduce chlorosilane waste streams.
REACH registration requirements in Europe govern siloxane environmental fate testing and restrict cyclic siloxane content in rinse-off cosmetics. EPA oversight in the United States monitors volatile methylsiloxanes under TSCA Section 5 premanufacture notification rules. China's MEE enforces GB standards for silicone emissions from chemical synthesis facilities. Stakeholders must track regulatory divergence between jurisdictions to anticipate reformulation costs and regional product registration timelines.
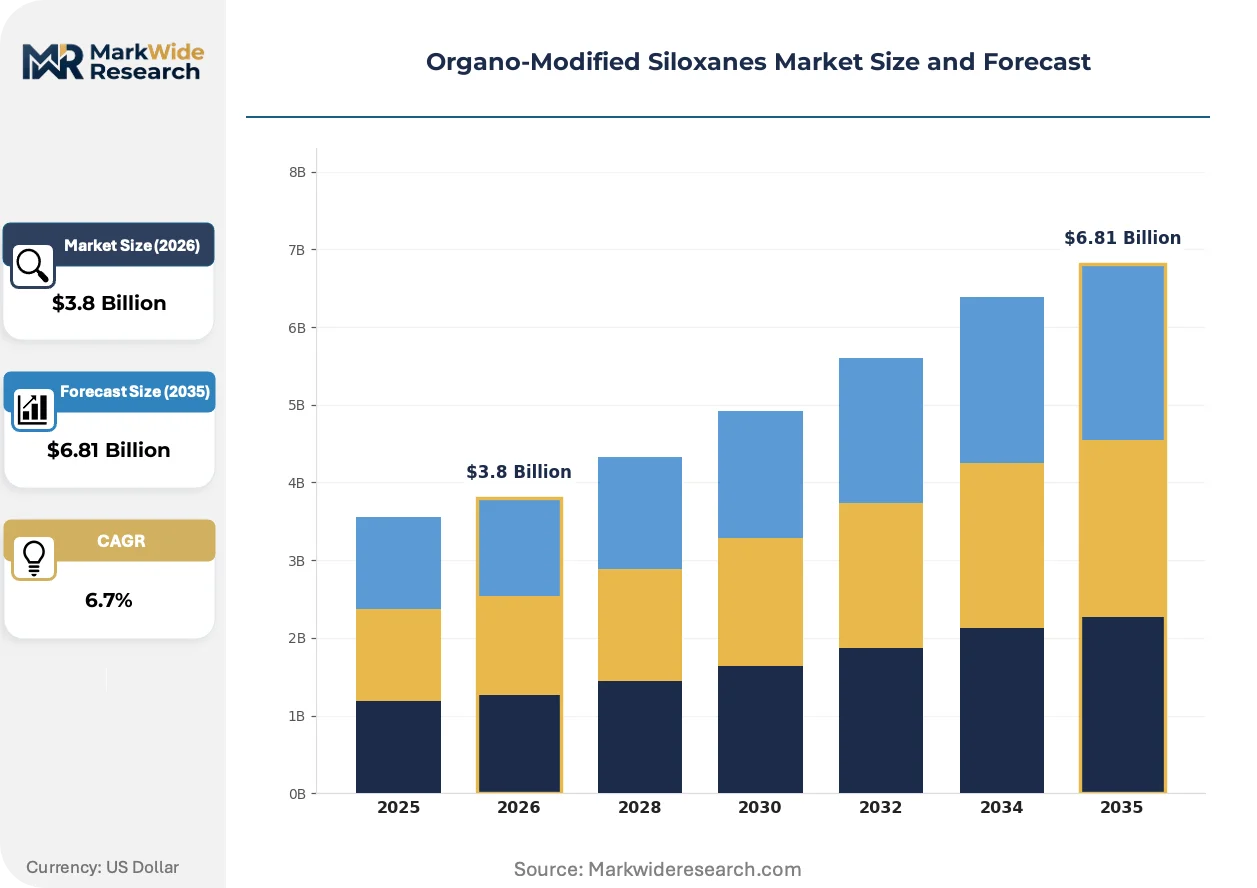
Market Dynamics
REACH registration requirements in Europe are forcing reformulation of cosmetic and industrial silicone products, compressing permissible cyclic siloxane thresholds while manufacturers scramble to certify alternative organo-functional derivatives. This regulatory pressure intersects with atom-efficient synthesis technology investments as producers seek to maintain margin structures amid compliance cost inflation.
Growth Catalysts
- REACH D4-D6 Restrictions:European rinse-off cosmetic limits on cyclotetrasiloxane and cyclopentasililoxane are accelerating demand for compliant linear organo-modified alternatives in shampoo and skincare formulations.
- Automotive Silicone Sealant Procurement:Chinese EV battery pack manufacturers are expanding high-temperature sealant orders to meet thermal management specifications in electric powertrain assemblies.
- Atom-Efficient Chlorosilane Routes:Direct synthesis processes reducing waste streams in methylchlorosilane production are lowering unit economics for silicone fluid intermediates.
Market Restraints
- Silicon Metal Price Volatility:Ferrosilicon and metallurgical-grade silicon feedstock costs fluctuate with Chinese smelter output curbs and electricity pricing reforms, compressing margin predictability for siloxane producers.
- Technical Substitution Limits:Hydrocarbon surfactants and bio-based emulsifiers cannot replicate the thermal stability and surface tension reduction of silicone fluids in high-temperature textile finishing applications.
- ECHA Authorization Bottlenecks:Extended environmental fate testing timelines for novel organo-functional siloxanes delay product registration by 18-36 months, freezing commercialization pipelines.
Strategic Opportunities
- Indian Electronics Manufacturing:Production-linked incentive schemes for semiconductor and mobile device assembly are creating virgin demand for conformal coating resins in Bengaluru and Chennai industrial corridors.
- UV-Curable Silicone Resin Convergence:Combination of photochemistry with epoxy-functional siloxanes enables instant-cure protective coatings for automotive headlamp assemblies, displacing thermal cure systems.
- Saudi Specialty Chemicals Localization:SABIC and downstream partners are soliciting technology transfer partnerships for domestic silicone fluid production under Vision 2030 import substitution mandates.
Industry Challenges
- Organosilicon Chemist Talent Scarcity:Universities in Germany, Japan, and the United States produce insufficient PhD-level specialists in siloxane synthesis and surface chemistry to staff R&D expansion.
- Legacy Chlorosilane Asset Stranding:Producers face write-down risk on hydrolysis plant investments as regulators tighten emissions standards for hydrogen chloride byproduct handling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organo-Modified Siloxanes Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Emulsions, Silicone Resins, Silicone Gels, Silicone Fluids Application: Coatings, Adhesives, Sealants, Personal Care Products End User: Automotive Industry, Construction Sector, Electronics Sector, Textile Industry Technology: Chemical Synthesis, Mechanical Processing, Formulation, Surface Modification |
| Companies Covered | Evonik Industries, Wacker Chemie AG, BASF, Momentive Performance Materials, CHT Group, Dow Inc., Shin-Etsu Chemical Co., Ltd., Supreme Silicones, DeWolf Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organo-Modified Siloxanes Market Evolving Landscape
Process intensification and regulatory chemistry are converging to reshape competitive positioning in organo-modified siloxanes. Manufacturers are retooling synthesis pathways and application testing protocols simultaneously.
Continuous-flow microreactor technology is integrating methoxy-functional silane production with in-line purification, eliminating batch-to-batch variability in polyether-modified siloxane surfactants. Personal care compounders in France and South Korea are adopting these systems to accelerate formulation iteration cycles. The technology is compressing pilot-to-scale timelines from 24 months to under 12 months for new cosmetic-grade silicone emulsifiers.
ECHA's 2024 update to REACH Annex XVII restrictions on cyclic siloxanes in leave-on cosmetics is forcing reformulation of hair care and antiperspirant products containing D4, D5, and D6 compounds. German and Dutch formulators are accelerating substitution with volatile linear dimethicones and phenyl-modified alternatives. The personal care segment is responding with accelerated biodegradability certification investments to preempt further regulatory tightening.
Direct-to-manufacturer procurement platforms are disintermediating traditional silicone fluid distributors in China's Yangtze River Delta electronics cluster. Automotive sealant buyers in Suzhou and Wuxi are negotiating annual volume contracts through B2B marketplaces, compressing spot-market premiums. This channel shift is most visible in high-volume silicone rubber orders for EV battery thermal interface materials, where price transparency pressures legacy distributor margins.
Organo-Modified Siloxanes Market Segmentation
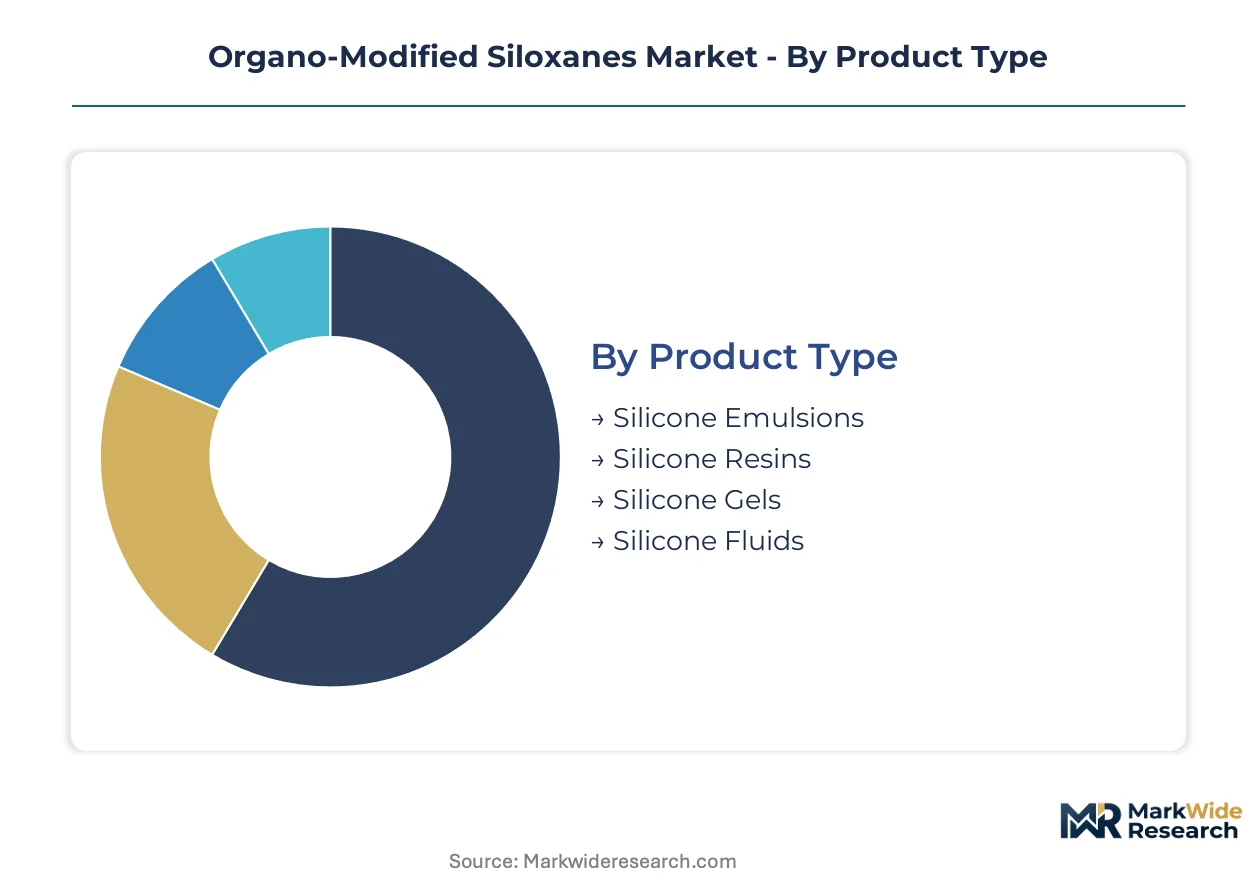
Organo-modified siloxanes exhibit divergent margin profiles and regulatory exposure across product architectures, with silicone fluids commanding volume leadership while specialty resins capture premium positioning in protective coatings. Understanding segment-level supply concentration and application-specific compliance requirements enables procurement optimization and capacity planning across the value chain.
Product Type:
Production assets for silicone fluids concentrate in integrated chlorosilane-to-fluid complexes operated by German and Chinese chemical producers, while silicone resin capacity fragments across specialty coating chemical manufacturers in Japan and the United States.
- Silicone Fluids:Linear polydimethylsiloxane oils with viscosity grades from 0.65 to 1,000,000 centistokes serve as conditioning agents and defoamers. Personal care formulators in France and South Korea absorb the majority of cosmetic-grade fluid volumes, though REACH D4-D6 restrictions are accelerating substitution toward volatile linear dimethicones.
- Silicone Resins:Three-dimensional crosslinked siloxane networks with phenyl or methyl substitution deliver thermal stability and weather resistance. Electronics manufacturers in China's Yangtze River Delta dominate conformal coating procurement for semiconductor protection, with EV battery pack producers expanding high-temperature sealant orders.
- Silicone Emulsions:Oil-in-water dispersions stabilized by surfactant systems enable water-based textile finishing applications.
- Silicone Gels:Soft, tack-free elastomeric materials formulated for medical device cushioning and electronics potting.
Silicone fluids absorb the bulk of installed capacity; silicone resins are expanding most quickly.
Application:
Cost tier differentiation separates commodity sealant formulations from certified cosmetic-grade materials, with regulatory compliance investments driving margin stratification across application categories.
- Personal Care Products:Hair conditioners, skin creams, and antiperspirants utilize amino-functional and polyether-modified siloxanes for sensory modification. German and Dutch formulators are reformulating rinse-off and leave-on products to meet ECHA's tightened cyclic siloxane thresholds, triggering accelerated biodegradability certification investments.
- Coatings:Protective films for automotive, aerospace, and electronics substrates leverage phenyl-modified resins for UV resistance. Japanese automotive headlamp manufacturers are displacing thermal cure systems with UV-curable epoxy-functional siloxanes for instant-cure processing.
- Adhesives:Pressure-sensitive and structural bonding formulations exploit siloxane flexibility and thermal stability.
- Sealants:High-performance joint fillers for construction and transportation applications demand movement accommodation and weathering resistance.
Personal care applications command premium pricing for certified cosmetic grades; coatings are climbing the fastest on electronics and EV battery thermal management demand.
End User:
Volume concentration in automotive procurement reflects the sector's multi-point silicone consumption across powertrain sealing, electronics potting, and interior conditioning applications.
- Automotive Industry:EV battery thermal interface materials, headlamp coatings, and HVAC sealants constitute the dominant demand cluster. Chinese EV producers in Suzhou and Wuxi are negotiating annual volume contracts through B2B procurement platforms, compressing distributor margins.
- Electronics Sector:Conformal coatings for printed circuit boards and semiconductor packaging require ultra-pure silicone resins. India's production-linked incentive schemes for semiconductor assembly in Bengaluru and Chennai are creating virgin demand for specialty coating materials.
- Construction Sector:Structural glazing and weatherproofing applications consume neutral-cure sealant formulations.
- Textile Industry:Softening and water-repellent finishing of fabrics employs amino-functional silicone emulsions.
Automotive procurement absorbs the dominant share of high-performance formulations; electronics is gaining share fastest on semiconductor localization initiatives.
Technology:
Geographic concentration of synthesis expertise in Germany, Japan, and the United States creates capability scarcity for atom-efficient chlorosilane route development.
- Chemical Synthesis:Hydrolysis and condensation of chlorosilanes or alkoxysilanes constitutes the foundational production pathway. Continuous-flow microreactor technology in French and South Korean personal care compounders is compressing pilot-to-scale timelines from 24 months to under 12 months for new cosmetic-grade emulsifiers.
- Surface Modification:Grafting organic functional groups onto polydimethylsiloxane backbones tunes hydrophilic-lipophilic balance for targeted applications.
- Mechanical Processing:High-shear dispersion and milling operations achieve particle size control in gel and emulsion products.
- Formulation:Compounding with additives, fillers, and crosslinkers tailors performance for end-use specifications.
Chemical synthesis commands the majority of capital deployment; surface modification is advancing most rapidly on regulatory-driven reformulation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German metallurgical-grade silicon smelters anchor European feedstock supply for chlorosilane production, while Chinese ferrosilicon output curbs ripple through global siloxane cost structures.
United States
EPA TSCA Section 5 oversight governs premanufacture notification for volatile methylsiloxanes entering cosmetic and industrial formulations. Automotive sealant procurement concentrates in Michigan and Ohio assembly corridors, where EV battery pack manufacturers negotiate thermal interface material contracts through direct sourcing platforms.
Germany
ECHA REACH Annex XVII restrictions on cyclic siloxanes in rinse-off cosmetics force reformulation timelines for hair care and skincare products. Wacker Chemie AG leverages integrated silicon metal-to-silicone value chains in Burghausen to sustain cost advantages in specialty fluid production.
China
MEE GB standards enforce silicone emission limits from chemical synthesis facilities in the Yangtze River Delta. Suzhou and Wuxi electronics manufacturers disintermediate traditional distributors through B2B procurement platforms for high-volume silicone rubber orders serving EV battery thermal management.
Japan
METI industrial standards govern silicone resin specifications for electronics conformal coatings and automotive headlamp assemblies. Osaka and Nagoya industrial clusters specialize in phenyl-modified resin production for semiconductor packaging applications.
India
PLI scheme production-linked incentives for semiconductor and mobile device assembly generate virgin demand for conformal coating resins. Bengaluru and Chennai industrial corridors attract specialty silicone procurement from domestic electronics manufacturers scaling assembly operations.
Organo-Modified Siloxanes Market Competitive Landscape
Global majors compete with regional champions across integrated chlorosilane production and specialty formulation capabilities. Market structure tilts toward consolidation at the feedstock level, with fragmentation increasing downstream in application-specific compounding. Three archetypes dominate: integrated silicon metal-to-silicone producers, specialty resin formulators, and regional emulsion compounders. Competitive moves concentrate on atom-efficient synthesis technology licensing and backward integration into metallurgical-grade silicon sourcing.
Within the integrated producer tier, Wacker Chemie AG and Dow Inc. exemplify scale-driven positions spanning chlorosilane hydrolysis through downstream fluid and resin production. Evonik Industries occupies a specialty-focused position emphasizing high-performance coating materials. Shin-Etsu Chemical Co., Ltd. anchors Asia-Pacific supply concentration through captive silicon metal operations and controlled condensation process expertise.
| Leading Market Players |
|---|
| Evonik Industries |
| Wacker Chemie AG |
| BASF |
| Momentive Performance Materials |
| CHT Group |
| Dow Inc. |
| Shin-Etsu Chemical Co., Ltd. |
| Supreme Silicones |
| DeWolf Chemical |
| Others |
Value Network & Pricing Analysis
Captive silicon metal-to-chlorosilane integration anchors both cost position and pricing power for German and Chinese producers, with Wacker Chemie AG's Burghausen complex exemplifying how upstream control over metallurgical-grade silicon insulates margin structures against ferrosilicon volatility while enabling premium positioning in REACH-compliant cosmetic-grade fluids.
Pricing Analysis
Technical service bundling separates premium silicone fluid quotations from stripped commodity spot transactions, with cosmetic-grade certifications and formulation support commanding substantial premia over standard industrial grades. Three-tier pricing structure across cosmetic-certified, technical, and commodity industrial levels reflects divergence in purity standards and regulatory documentation burdens. Cost compression in standard fluid tiers intensifies as Chinese producers expand direct-to-manufacturer B2B platform sales, eroding distributor markups. Automotive sealant buyers exhibit lowest price sensitivity due to thermal performance specifications, while textile finishers gravitate toward economy emulsion grades.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Chinese EV battery manufacturers in Suzhou and Wuxi, displacing traditional distributor relationships for thermal interface material procurement. Production gravity centers on Germany, China, and Japan, with chlorosilane hydrolysis capacity concentrating in integrated chemical complexes. Feedstock supply draws from metallurgical-grade silicon smelters in Germany and ferrosilicon operations in China, exposing margins to electricity pricing reforms and environmental curbs. Single-source vulnerability in high-purity phenyl-modified resin supply from Japanese producers presents concentration risk for automotive headlamp coating specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race: control over silicon metal feedstock and chlorosilane synthesis assets determines who captures margin in REACH-compliant formulations versus who bleeds share to integrated German and Chinese incumbents.
For Market Incumbents: Anchor cost position through captive silicon metal supply or long-term offtake agreements with German smelters, while accelerating biodegradability certification investments to preempt further ECHA cyclic siloxane restrictions. Defend against specialty resin challengers by locking automotive headlamp manufacturers into multi-year thermal management material contracts before UV-curable epoxy-functional alternatives mature. For New Entrants and Emerging Players: REACH Annex XVII restrictions in Europe open a window for compliant linear organo-modified alternatives, particularly in hair care and antiperspirant reformulation. India's PLI scheme for semiconductor assembly creates virgin demand for conformal coating resins in Bengaluru and Chennai corridors with limited incumbent presence. Target technology transfer partnerships with Saudi downstream partners under Vision 2030 import substitution mandates as a capital-light market entry mechanism. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty resin formulators with automotive and electronics coating certifications, where atom-efficient synthesis IP commands acquisition premia. Five-to-ten year viability hinges on regulatory chemistry capabilities and chlorosilane route environmental compliance rather than commodity scale. Watch ECHA authorization timelines for novel organo-functional siloxanes as the inflection signal for portfolio rotation toward compliant derivative producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Metal | Wacker Chemie AG's captive metallurgical-grade silicon supply insulates chlorosilane production from Chinese ferrosilicon volatility. |
| Continuous-Flow Microreactor Deployment | French and South Korean compounders compress cosmetic-grade emulsifier development cycles from 24 months to under 12 months. |
| REACH-Compliant Product Registration | ECHA authorization bottlenecks of 18-36 months freeze commercialization pipelines for non-compliant cyclic siloxane alternatives. |
| Direct-to-Manufacturer B2B Platform | Yangtze River Delta electronics buyers disintermediate distributors, compressing spot-market premiums on high-volume silicone rubber orders. |
| UV-Curable Epoxy-Functional Resin Development | Japanese automotive headlamp manufacturers displace thermal cure systems with instant-cure photochemistry for processing efficiency. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews spanning silicone plant managers at integrated chlorosilane complexes, procurement leads at Chinese EV battery manufacturers, personal care formulators in France and South Korea, and technical R&D directors at specialty resin producers. ECHA REACH registration databases, EPA TSCA premanufacture notifications, Chinese MEE emission disclosures, and SEC 10-K filings from disclosed chemical producers provided validation layers. Bottom-up capacity modeling triangulated against top-down end-use demand aggregation.
Segment-level granularity modeled product type splits across silicone fluids, resins, emulsions, and gels; application differentiation between personal care, coatings, adhesives, and sealants; end-user concentration in automotive, electronics, construction, and textile verticals; and technology divergence across chemical synthesis, surface modification, mechanical processing, and formulation compounding. CAGRs derived from regression analysis of historical price-volume relationships and forward projection of regulatory-driven substitution elasticities. Forecast inputs incorporated REACH D4-D6 restriction implementation schedules and Indian PLI scheme capacity buildout timelines.
The model assumes a particular technology adoption path; alternative pathways for atom-efficient direct synthesis of methylchlorosilanes would alter the outlook for incumbent hydrolysis asset valuations. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and feedstock cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Divinylbenzene (DVB) Market
Specialty Chemicals
Bismuth Oxychloride Market
Specialty Chemicals
Flame-Retardant Synergist Systems with Low Smoke Toxicity Market
Specialty Chemicals
Photo Emulsion Market
Specialty Chemicals
Global Benzoyl Peroxide Market
Specialty Chemicals
India Prussian Blue Market
Specialty Chemicals
Global Non-Phthalate Plasticizers Market
Specialty Chemicals
Halogen-Free Flame Retardants Market
Specialty Chemicals
Global Specialty Fuel Additives Market
Specialty Chemicals
Global Lactobionic Acid Market
Specialty Chemicals
Special Boiling Point Solvents Market
Specialty Chemicals
Palm Methyl Ester Derivatives Market
Specialty Chemicals
Arginine Market
Specialty Chemicals
Avobenzone Market
Specialty Chemicals
Encapsulated Lactic Acid Market
Specialty Chemicals
Middle East and Africa Polyvinylpyrrolidone (PVP) Market