
 Explosives and Pyrotechnics Market | 2026-2036
Explosives and Pyrotechnics Market Size, Share, and Industry Trends Forecast 2026-2036
Explosives and Pyrotechnics Market Analysis
Ammonium nitrate is pivoting toward emulsion-based formulations as mining operators seek safer, water-resistant blasting agents. Orica Mining Services leverages its integrated manufacturing network across Australia and North America to sustain bulk delivery contracts with major pit operators. MAXAM Corp anchors its position through deep vertical integration into raw nitrates and detonator production. Chemring Group differentiates via specialized propellant chemistry for defense applications.
Explosives and pyrotechnics encompass energetic materials engineered for controlled energy release, typically formulated with oxidizers, fuels, and sensitizers in particle sizes calibrated for specific detonation velocities or burn rates. These materials serve primary functions in rock fragmentation, propulsion, theatrical effects, and ordnance initiation where precise energy output determines operational success. Blasting agents dominate volume throughput in mining applications, while propellants command premium margins through defense procurement cycles. Fireworks remain structurally fragmented across seasonal retail channels, whereas emulsion formulations are displacing packaged explosives in large-scale surface operations due to transport and handling efficiencies.
The US Bureau of Alcohol, Tobacco, Firearms and Explosives enforces strict licensing for explosive precursor commerce, limiting market access to certified distributors and end-users. Australia's Work Health and Safety regulations mandate blast pattern documentation and vibration monitoring, embedding compliance costs into contractor pricing. China's Ministry of Emergency Management controls production quotas for civilian explosive manufacturers, directly constraining supply expansion. Stakeholders must monitor evolving precursor chemical controls across multiple jurisdictions, as regulatory divergence between the US, EU, and Chinese frameworks will determine which formulation technologies achieve scalable deployment.
Market Dynamics
Emulsion-based blasting agents are displacing packaged explosives across deep open-pit operations, compressing transport costs and reducing handling hazards for mining contractors.
Growth Catalysts
- Bulk emulsion adoption:Australian and Chilean mining operators are expanding bulk delivery systems as pit depths exceed 500 meters, favoring water-resistant formulations.
- REACH reformulation mandates:The EU's tightening nitrate compound protocols force manufacturers to invest in safer precursor handling, accelerating premium product differentiation.
- State infrastructure programs:China's western provinces concentrate demand through state-owned conglomerates driving railway tunnels and hydropower excavation.
Market Restraints
- Ammonium nitrate price volatility:Feedstock costs fluctuate with natural gas and fertilizer market cycles, squeezing margin predictability for formulators.
- Production quota controls:China's Ministry of Emergency Management caps civilian explosive manufacturing licenses, constraining supply elasticity.
- Electronic initiation substitution:Non-explosive percussive drilling and mechanical rock breaking advance in noise-sensitive urban construction zones.
Strategic Opportunities
- Defense propellant specialization:NATO ammunition replenishment programs create procurement windows for energetic materials with specific burn-rate tolerances.
- Digital blast optimization:Integration of drone-based fragmentation analysis with emulsion loading systems enables precision drilling contracts.
- Greenfield African mining:Copper-cobalt belt expansions in the Democratic Republic of Congo and Zambia require bulk explosive infrastructure buildout.
Industry Challenges
- Blast engineering talent scarcity:Specialized vibration modeling and pattern design expertise concentrates among retiring cohorts in established mining jurisdictions.
- ATF licensing timelines:US Bureau of Alcohol, Tobacco, Firearms and Explosives precursor commerce permits extend 18-24 months, delaying market entry for new distributors.
- Legacy detonator integration:Mines with existing non-electric initiation stockpiles face capital drag when transitioning to electronic delay systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Explosives and Pyrotechnics Market |
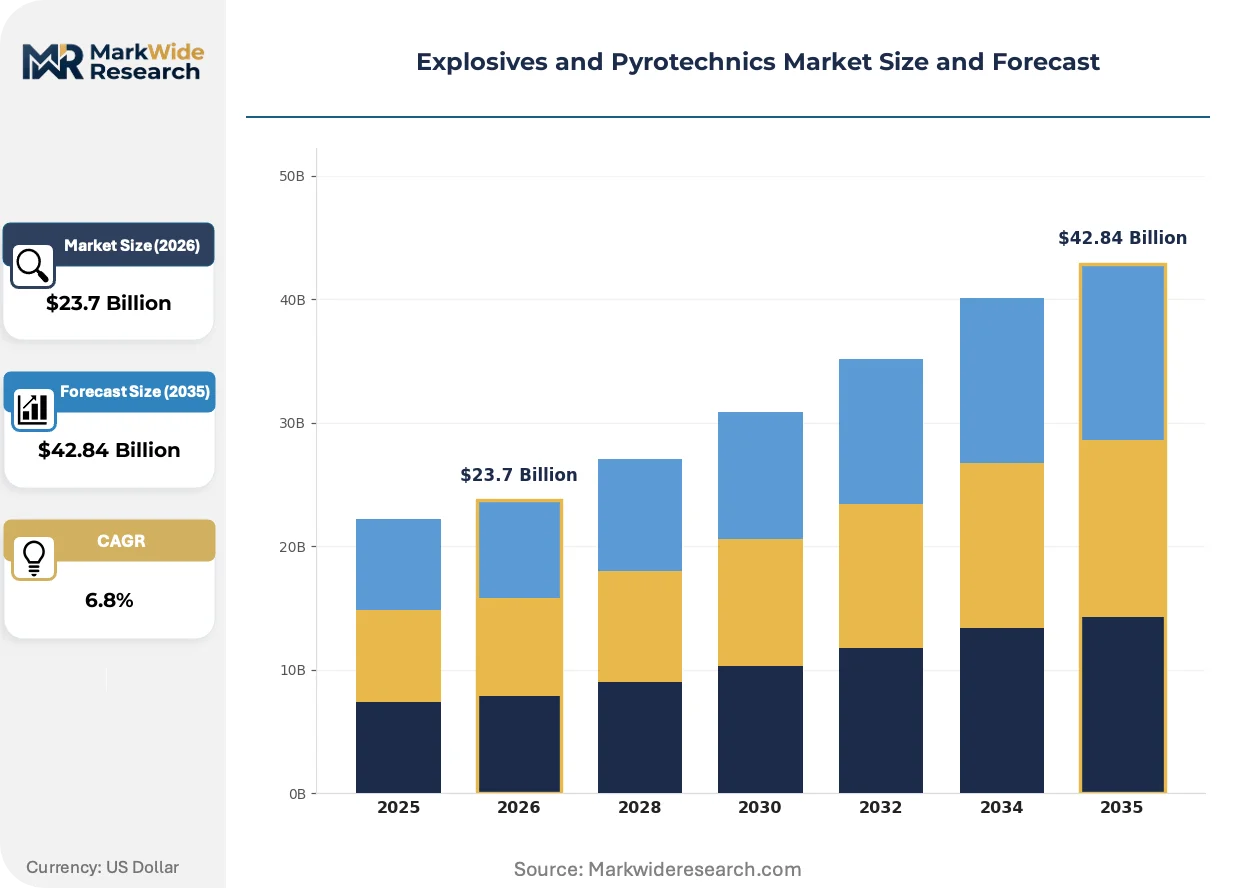
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
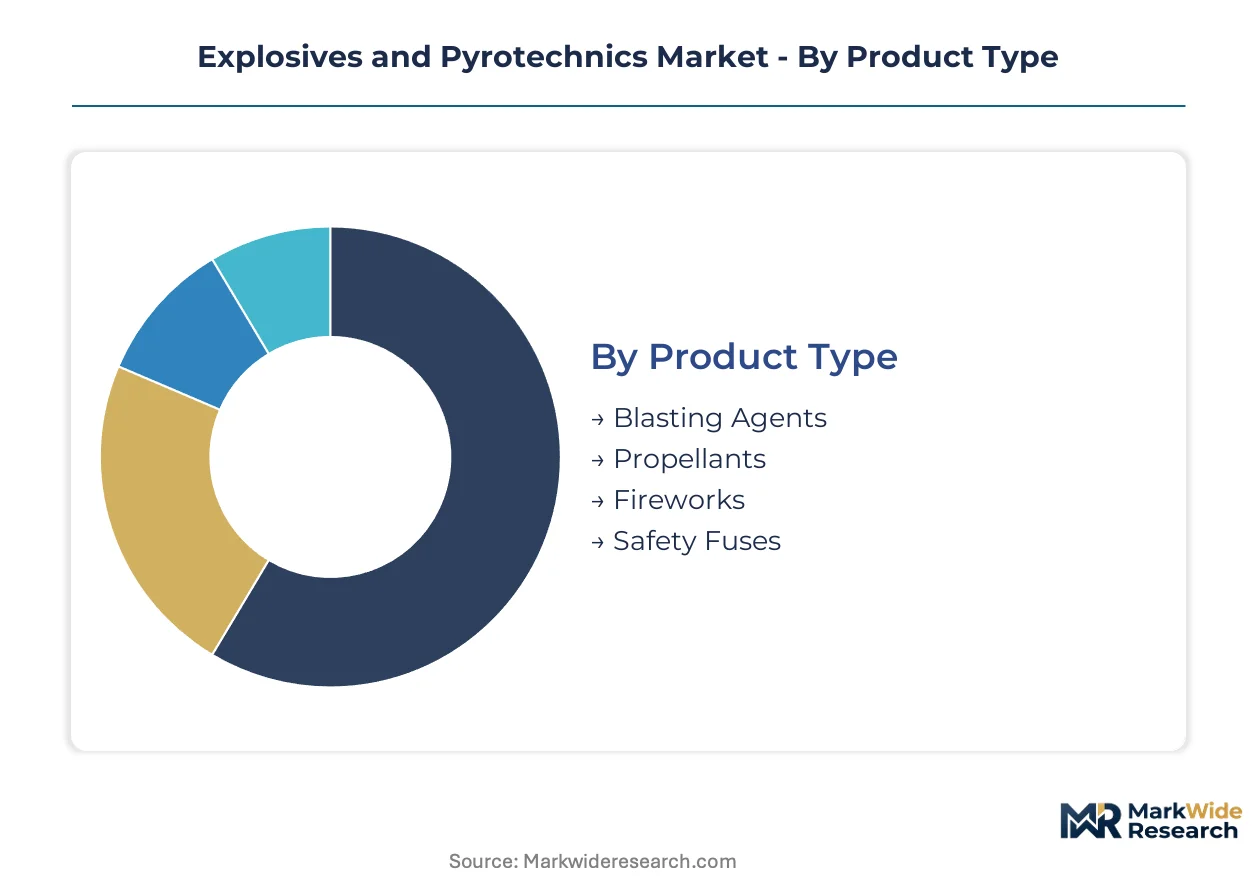
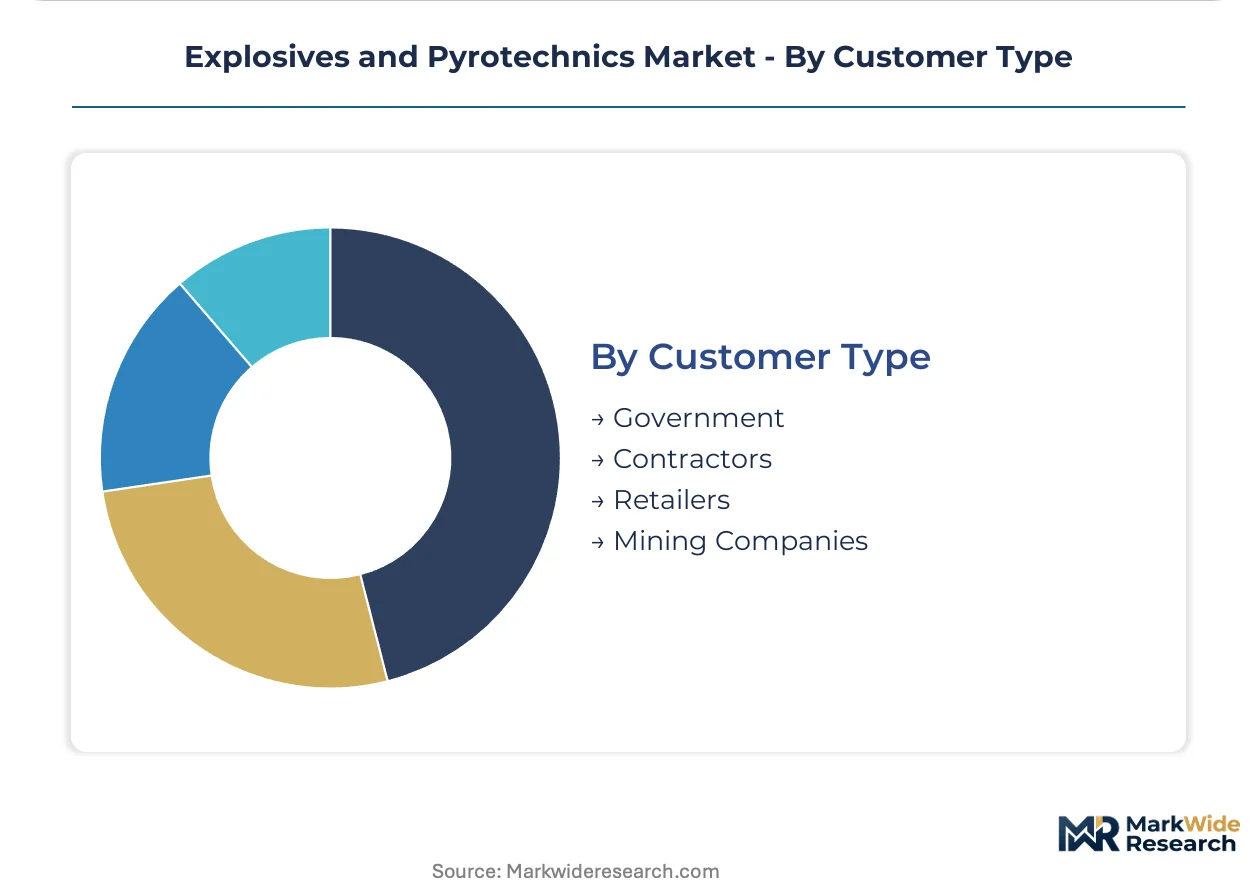
| Segmentation | Product Type: Blasting Agents, Propellants, Fireworks, Safety Fuses Application: Mining, Construction, Military, Entertainment Form: Solid, Liquid, Gas, Emulsions Customer Type: Government, Contractors, Retailers, Mining Companies |
| Companies Covered | Incitec Pivot Limited, AECI Group, Orica Mining Services, Chemring Group, MAXAM Corp, ENAEX, Austin Powder Company, Hanwha Corporation, Sasol Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Explosives and Pyrotechnics Market Emerging Trajectories
Formulation chemistry and initiation electronics are converging to reduce blast variability while regulatory pressure on precursor tracking intensifies across major producing jurisdictions.
Emulsion matrix technology is modularizing blast pattern design by separating oxidizer and fuel phases until site-mixing. Large-scale surface miners in Western Australia and Nevada adopt these systems to eliminate packaged explosive transport hazards. Modular architecture enables real-time viscosity adjustment for varying rock hardness, compressing powder factor optimization cycles from weeks to days.
REACH authorization requirements for nitrate compound handling are mandating closed-loop manufacturing audits across EU production facilities. German and Polish formulators invest in automated precursor weighing and containment systems to satisfy ECHA documentation protocols. Defense procurement chains face the steepest compliance cost escalation due to dual-use chemical scrutiny.
Site-mixed emulsion service contracts are displacing traditional packaged explosive spot purchases in tier-one mining operations. Major pit operators in Chile's Atacama and Western Australia's Pilbara now specify throughput-based pricing tied to fragmentation metrics rather than explosive tonnage. This shift concentrates procurement authority with integrated service providers possessing on-site manufacturing capabilities.
Explosives and Pyrotechnics Market Segmentation
Explosives and pyrotechnics serve radically different operational contexts—from controlled rock fragmentation in kilometer-deep pits to precision propulsion in defense ordnance. Segment boundaries determine formulation chemistry, regulatory pathway, and service model economics for manufacturers.
Product Type:
Standalone blasting agents dominate mining procurement through direct site-mixing infrastructure, while propellants embed within complex weapon system supply chains requiring burn-rate certification.
- Blasting Agents:Formulated from oxidizer-fuel suspensions with detonation velocities calibrated to rock hardness. Australian and Chilean open-pit operators specify bulk emulsion delivery for pits exceeding 500 meters depth, prioritizing water resistance over packaged alternatives. Volume placements concentrate in blasting agents; the faster expansion belongs to emulsion-based formulations displacing packaged explosives.
- Propellants:Engineered energetic materials with controlled burn rates for propulsion and gas generation. NATO ammunition replenishment programs drive specification windows for double-base and composite formulations with tight tolerance bands. Defense procurement cycles command premium margins through multi-year sole-source contracts.
- Fireworks:Pyrotechnic compositions for theatrical and celebratory effects, structurally fragmented across seasonal retail distribution with concentrated demand spikes around national holidays.
- Safety Fuses:Delay initiation devices providing timed flame transmission for non-electric blasting circuits, retaining niche utility in legacy mining operations and remote construction sites lacking electronic infrastructure.
Blasting agents absorb the heaviest capital deployment for on-site manufacturing infrastructure; propellants extract the steepest regulatory compliance costs from dual-use chemical scrutiny.
Application:
Mining and military applications anchor revenue concentration through long-term service contracts, while construction and entertainment segments operate on spot purchasing with higher margin volatility.
- Mining:Surface and underground rock fragmentation requiring tailored powder factors for ore body geometry. China's western provinces concentrate state-owned demand through railway tunnel and hydropower excavation programs.
- Construction:Controlled demolition and excavation in urban environments, facing substitution pressure from mechanical breaking in noise-sensitive zones.
- Military:Ordnance initiation, propulsion, and special effects with specification chains governed by defense procurement authorities. REACH authorization requirements for nitrate handling escalate compliance documentation burdens for EU-based suppliers.
- Entertainment:Theatrical pyrotechnics and display fireworks, structurally constrained by seasonal demand clustering and retail channel fragmentation.
Procurement authority concentrates with mining companies specifying throughput-based pricing; military programs retain the longest qualification timelines for formulation changes.
Form:
Physical state determines transport economics, handling safety protocols, and compatibility with automated loading systems across pit operations.
- Emulsions:Two-phase oxidizer-fuel matrices mixed on-site to eliminate packaged explosive transport hazards. Western Australian and Nevada surface miners adopt modular systems enabling real-time viscosity adjustment for varying rock hardness.
- Solid:Cast, pressed, or extruded formulations including boosters, cast PBX, and black powder derivatives, retaining dominance in legacy initiation systems and specialized defense applications.
- Liquid:Monopropellants and liquid oxidizer solutions for specific propulsion and industrial gas generation applications with limited explosives market penetration.
- Gas:Compressed or liquefied energetic gases for specialized industrial processes, representing minimal share of total explosives volume.
Emulsions capture the steepest adoption trajectory in tier-one mining; solid formulations defend position in defense and legacy mining infrastructure.
Customer Type:
Contractor and mining company procurement patterns diverge sharply on inventory risk allocation and technical service bundling requirements.
- Mining Companies:Tier-one pit operators in Chile's Atacama and Western Australia's Pilbara specifying outcome-based contracts tied to fragmentation metrics rather than explosive tonnage, concentrating authority with integrated service providers.
- Government:Defense ministries and civilian explosive regulatory bodies controlling production quotas, licensing, and strategic stockpile requirements. China's Ministry of Emergency Management caps civilian manufacturing licenses directly.
- Contractors:Blasting service providers absorbing inventory and regulatory compliance burdens for construction and mid-tier mining clients.
- Retailers:Seasonal distribution channels for consumer fireworks, structurally fragmented with minimal technical service component.
Contractor relationships scale fastest with emulsion service model adoption; government procurement retains the most rigid specification and qualification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western Australia's Pilbara region anchors explosives demand through iron ore expansion, while Chile's Atacama copper belt and China's western infrastructure corridors concentrate procurement. State-level mining incentives and production quotas reshape supply elasticity across these extraction zones.
Australia
Bulk emulsion adoption accelerates in Western Australia's deep open-pit iron ore operations exceeding 500 meters depth. Work Health and Safety regulations mandate blast pattern documentation and vibration monitoring, embedding compliance costs into contractor pricing. Queensland's Bowen Basin coal seams sustain packaged explosive demand for gassy underground conditions.
Chile
Copper extraction in the Atacama Desert drives water-resistant emulsion specifications for altitude operations above 3,000 meters. The national mining regulator enforces strict precursor transport permits across the Antofagasta region. State-owned Codelco concentrates procurement authority through centralized explosive service contracts in the Calama mining district.
China
Railway tunneling and hydropower excavation in Sichuan and Yunnan provinces concentrate state-owned demand. The Ministry of Emergency Management caps civilian explosive manufacturing licenses, directly constraining supply expansion. Xinjiang's coal basin development requires specialized cold-weather formulations for sub-zero blasting operations.
United States
Nevada's Carlin gold trend and Appalachian coal seams sustain divergent formulation requirements. The Bureau of Alcohol, Tobacco, Firearms and Explosives enforces 18-24 month licensing timelines for precursor commerce permits. Permian Basin oilfield services drive shaped charge demand for perforating gun applications.
South Africa
Platinum group metal extraction in the Bushveld Complex sustains bulk explosive consumption despite power grid instability. The Department of Mineral Resources and Energy regulates blast proximity to informal settlements near Rustenburg and Limpopo operations. Sasolburg's chemical corridor provides captive nitrate feedstock for regional formulators.
Explosives and Pyrotechnics Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated service providers commanding tier-one mining contracts while regional packagers serve spot construction markets. The vendor base concentrates among five multinational groups controlling bulk emulsion infrastructure, mid-tier regional specialists retaining packaged explosive niches, and state-affiliated producers serving captive domestic demand. Consolidation pressure intensifies as throughput-based pricing models favor capital-heavy integrated operators over product-only suppliers. Strategic moves center on backward integration into raw nitrates and geographic expansion of site-mixing capabilities.
Within the multinational integrated tier, Orica Mining Services, MAXAM Corp, and AECI Group exemplify the capital-intensive service model. Orica anchors the Australian and North American bulk delivery infrastructure. MAXAM occupies a position spanning raw nitrate sourcing through detonator production. AECI represents the African-centric vertical integration archetype with manufacturing clusters across southern extraction zones.
| Leading Market Players |
|---|
| Incitec Pivot Limited |
| AECI Group |
| Orica Mining Services |
| Chemring Group |
| MAXAM Corp |
| ENAEX |
| Austin Powder Company |
| Hanwha Corporation |
| Sasol Limited |
| Others |
Supply Flow & Price Mechanics
Emulsion matrix technology is compressing both production economics and supplier concentration as tier-one mining operators shift from packaged explosives to on-site mixing systems. This transition simultaneously eliminates packaged product premiums and concentrates procurement authority with integrated service providers possessing captive nitrate supply and site-manufacturing capabilities across Australia, Chile, and Nevada.
Pricing Analysis
Volume placements in blasting agents extract thin margins through commodity-scale tonnage contracts, while propellants command premium pricing through defense procurement cycles with sole-source qualification barriers. Three-tier pricing structure across premium, standard, and economy levels separates NATO-specification propellants from commercial blasting agents and seasonal fireworks retail. Cost compression in bulk emulsion services is intensifying because mining companies now specify throughput-based pricing tied to fragmentation metrics rather than explosive tonnage. Mid-tier mining contractors exhibit the highest price sensitivity due to inventory risk absorption, whereas defense ministries demonstrate minimal elasticity given multi-year sole-source dependencies.
Supply Chain Analysis
Ammonium nitrate feedstock rests on natural gas pricing cycles and fertilizer market dynamics, with production gravity centering on Russia, China, and the Middle East. Detonator electronics draw from Taiwanese semiconductor packaging and German precision engineering, while emulsion surfactants rely on specialty chemical producers in Germany and the United States. Single-source vulnerability concentrates in electronic initiation systems where qualified suppliers face 18-24 month ATF licensing timelines. Distribution runs through integrated service providers with on-site manufacturing infrastructure, displacing traditional packaged explosive distributors in tier-one mining jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The explosives and pyrotechnics sector is navigating a technology-transition phase as electronic initiation systems and modular emulsion platforms displace legacy non-electric detonators and packaged explosives across major mining jurisdictions.
For Market Incumbents: Anticipate margin compression in packaged explosives as site-mixed emulsion contracts capture procurement authority from tier-one mining operators. Defend position by deepening backward integration into raw nitrates and expanding on-site manufacturing footprints in Chile's Atacama and Western Australia's Pilbara. Prioritize detonator electronics certification investments to capture electronic initiation substitution demand from legacy non-electric stockpiles. For New Entrants and Emerging Players: Launch via specialized cold-weather formulation services targeting Xinjiang's coal basin development and other sub-zero blasting environments underserved by incumbent infrastructure. Target African copper-cobalt belt expansions in the Democratic Republic of Congo and Zambia where bulk explosive infrastructure buildout lags extraction growth. Pursue site-mixed emulsion service contracts with mid-tier contractors lacking capital for captive manufacturing capabilities. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational integrated service providers seeking geographic fill-in or technology augmentation. Long-term viability favors operators with captive nitrate supply and electronic initiation portfolios over packaged explosive pure-plays. The signal to watch is REACH authorization enforcement intensity across EU defense procurement chains, which will determine compliance cost burdens and competitive positioning for energetic materials suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Nitrates | Captive ammonium nitrate supply insulates margin volatility from natural gas price cycles. |
| Site-Mixed Emulsion Infrastructure Expansion | On-site manufacturing in Chile's Calama district captures Codelco's centralized procurement authority. |
| Electronic Initiation System Certification | ATF licensing compliance opens US defense and tier-one mining contractor channels. |
| Cold-Weather Formulation Development | Specialized products for Xinjiang's sub-zero operations access state-owned Chinese demand. |
| Drone-Based Fragmentation Analytics Integration | Digital blast optimization enables outcome-based pricing tied to rock breakage metrics. |
Methodological Framework
Trade databases, mining production statistics, and defense procurement disclosures formed the secondary backbone, supplemented by customs records for ammonium nitrate and emulsion component flows. Primary interviews with blast engineering directors, mining procurement managers, explosive formulator R&D leads, and regulatory compliance officers at manufacturers across Australia, Chile, and the United States validated demand assumptions and pricing dynamics. Bottom-up tonnage estimates by application and region were cross-checked against top-down market value reconstructions.
Historical trendline analysis established baseline growth patterns across blasting agents, propellants, and pyrotechnics segments, with projection models incorporating product form transitions from packaged explosives to emulsions and electronic initiation penetration rates. Segmentation dimensions included product type, application, physical form, and customer archetype, with regional regulatory clusters modeled separately for REACH, ATF, and Chinese Ministry of Emergency Management compliance pathways. CAGRs were derived from weighted average growth across these segments, with emulsion adoption curves and defense replenishment cycles as primary forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for electronic initiation systems would alter the outlook if non-explosive mechanical breaking advances faster in noise-sensitive urban construction zones. Forecasts reflect assumptions regarding REACH enforcement intensity, Chinese production quota stability, and ammonium nitrate feedstock pricing. A small set of named triggers—regulatory divergence across jurisdictions, electronic initiation substitution rates, and African mining infrastructure buildout pace—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Aerosol Market
Specialty Chemicals
Dimethyl Silicone Market
Specialty Chemicals
Ferrous Gluconate Market
Specialty Chemicals
VCI Aerosol Market
Specialty Chemicals
Crystal Hard Wax Market
Specialty Chemicals
Hydroxypropionic Acid Market
Specialty Chemicals
Polyacrylamide Gel Electrophoresis (PAGE) Market
Specialty Chemicals
Fluorotelomers Market
Specialty Chemicals
Phytosphingosine Market
Specialty Chemicals
Silanes and Silicones Market
Specialty Chemicals
Global Specialty Resins Market
Specialty Chemicals
Preparative and Process Chromatography Market
Specialty Chemicals
Hyaluronic Acid Products Market
Specialty Chemicals
Fatty Acid Methyl Ester Market
Specialty Chemicals
Specialty Methacrylate Market
Specialty Chemicals
Phenylbenzimidazole Sulfonic Acid Market