
 2-(2,2,2-Trifluoroethoxy)-1,3,2-Dioxaphospholane-2-Oxide Market | 2026-2036
2-(2,2,2-Trifluoroethoxy)-1,3,2-Dioxaphospholane-2-Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
2-(2,2,2-Trifluoroethoxy)-1,3,2-Dioxaphospholane-2-Oxide Market Analytics
Battery-grade purity specifications above 99.5% is redrawing supplier hierarchies in fluorinated organophosphorus chemistry. Sigma-Aldrich leverages its analytical standards portfolio to anchor premium positioning for reference-grade material. TCI Chemicals sustains volume leadership through captive synthesis routes in Japanese manufacturing corridors. Shijiazhuang Jianxin Biotechnology competes on cost-adjusted specifications for regional battery chemical integrators.
2-(2,2,2-Trifluoroethoxy)-1,3,2-dioxaphospholane-2-oxide functions as a fluorinated cyclic phosphate ester synthesized via phosphorus pentoxide condensation with trifluoroethanol, serving primarily as a flame-retardant electrolyte additive and reactive intermediate in lithium-ion battery formulations. The compound's phosphorus-fluorine bond confers thermal stability above 200°C and electrochemical compatibility with carbonate-based electrolyte systems. Liquid formulations dominate current procurement volumes due to handling efficiency in automated battery assembly lines, while pharmaceutical-grade powder segments command superior margin pools owing to stringent residual solvent limits. Coatings applications for flame-retardant polymer systems represent the fastest-growing demand vector as electric vehicle OEMs tighten thermal runaway specifications.
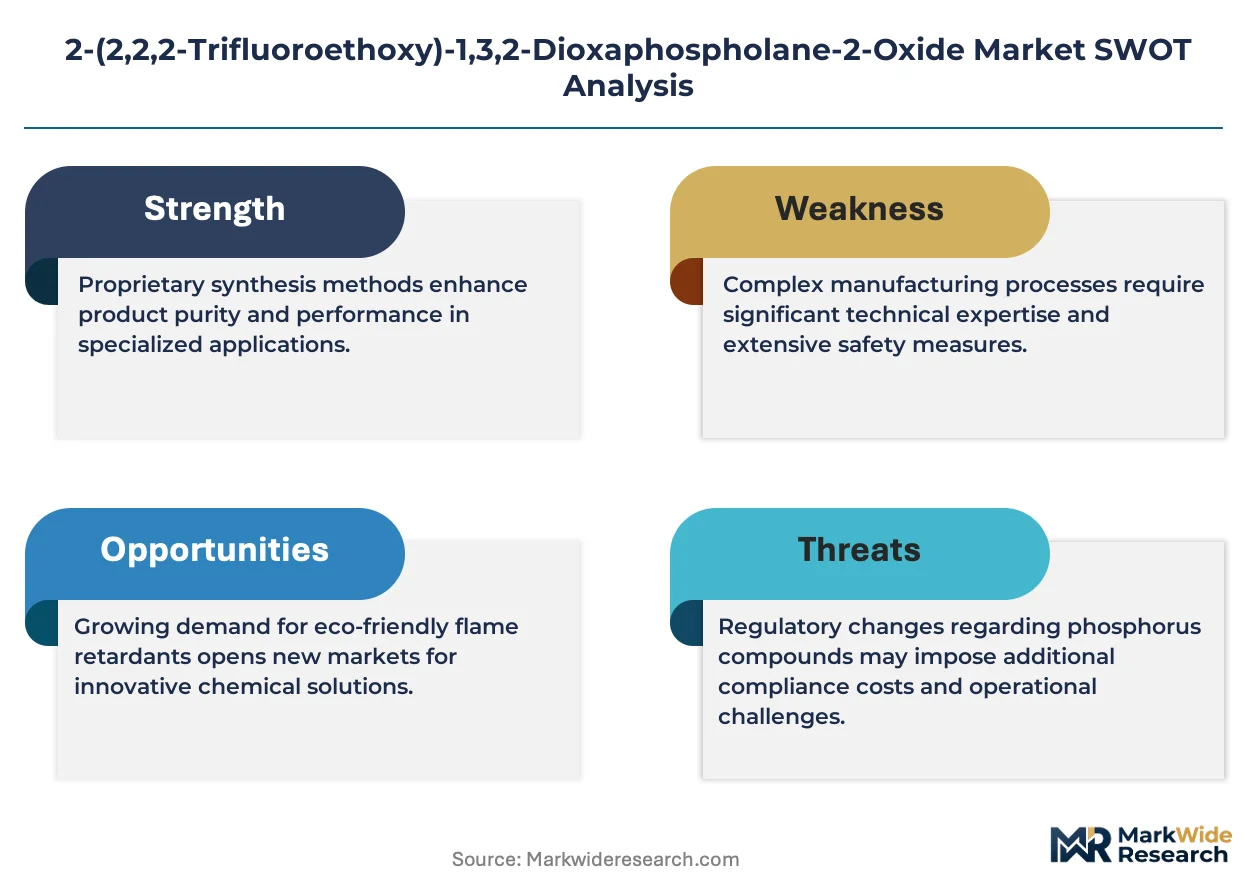
China's MIIT enforces GB/T standards for lithium-ion battery material purity that directly gate domestic supplier qualification, while REACH registration in Europe mandates full toxicological dossiers for fluorinated phosphate imports above one tonne annually. The EPA's TSCA Section 5 premanufacture notification framework governs new U.S. introductions of this substance class, creating staggered market access timelines across jurisdictions. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions in major economies, as structural similarity assessments could trigger precursor substance reclassification with cascading supply chain disclosure obligations.
Market Dynamics
Fluorinated phosphate chemistry is undergoing qualification turbulence as battery-grade purity thresholds above 99.5% separate qualified suppliers from commodity producers, forcing capital redeployment toward analytical infrastructure and captive trifluoroethanol supply.
Growth Catalysts
- GB/T Standard Enforcement:China's MIIT mandates battery material purity certifications that gate domestic supplier qualification, redirecting procurement toward certified fluorinated phosphate producers.
- Thermal Runaway Specifications:Electric vehicle OEMs in South Korea are tightening flame-retardant polymer requirements for battery pack housings, expanding coatings applications for cyclic phosphate esters.
- Seoul-Shenzhen Production Corridors:East Asian electrolyte manufacturing clusters concentrate demand within automated battery assembly lines optimized for liquid additive handling.
Market Restraints
- Phosphorus Pentoxide Volatility:Feedstock cost swings for P2O5 condensation chemistry compress margin predictability for non-integrated producers.
- REACH Dossier Burden:ECHA registration mandates full toxicological profiles for fluorinated phosphate imports exceeding one tonne annually, creating staggered European market access timelines.
- Alternative Flame Retardants:Melamine polyphosphate and expandable graphite formulations compete in polymer coating applications where electrochemical compatibility is non-critical.
Strategic Opportunities
- Solid-State Battery Transition:Sulfide and oxide electrolyte architectures require modified additive chemistries, opening formulation partnerships with solid-state cell developers.
- India PLI Scheme:Production-linked incentives for advanced chemistry cell manufacturing are attracting electrolyte additive qualification programs for domestic battery supply chains.
- Per-Fluoroalkyl Substance Monitoring:Early engagement with OECD structural similarity assessments positions suppliers ahead of potential precursor reclassification cascades.
Industry Challenges
- Analytical Chemist Scarcity:Battery-grade fluorinated organophosphorus synthesis requires 31P-NMR and 19F-NMR expertise that commands premium compensation in semiconductor and pharmaceutical labor markets.
- Multi-Jurisdiction Certification Overlap:Simultaneous EPA TSCA Section 5 premanufacture notification, REACH registration, and MIIT GB/T compliance creates parallel documentation burdens with non-harmonized timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2-(2,2,2-Trifluoroethoxy)-1,3,2-Dioxaphospholane-2-Oxide Market |
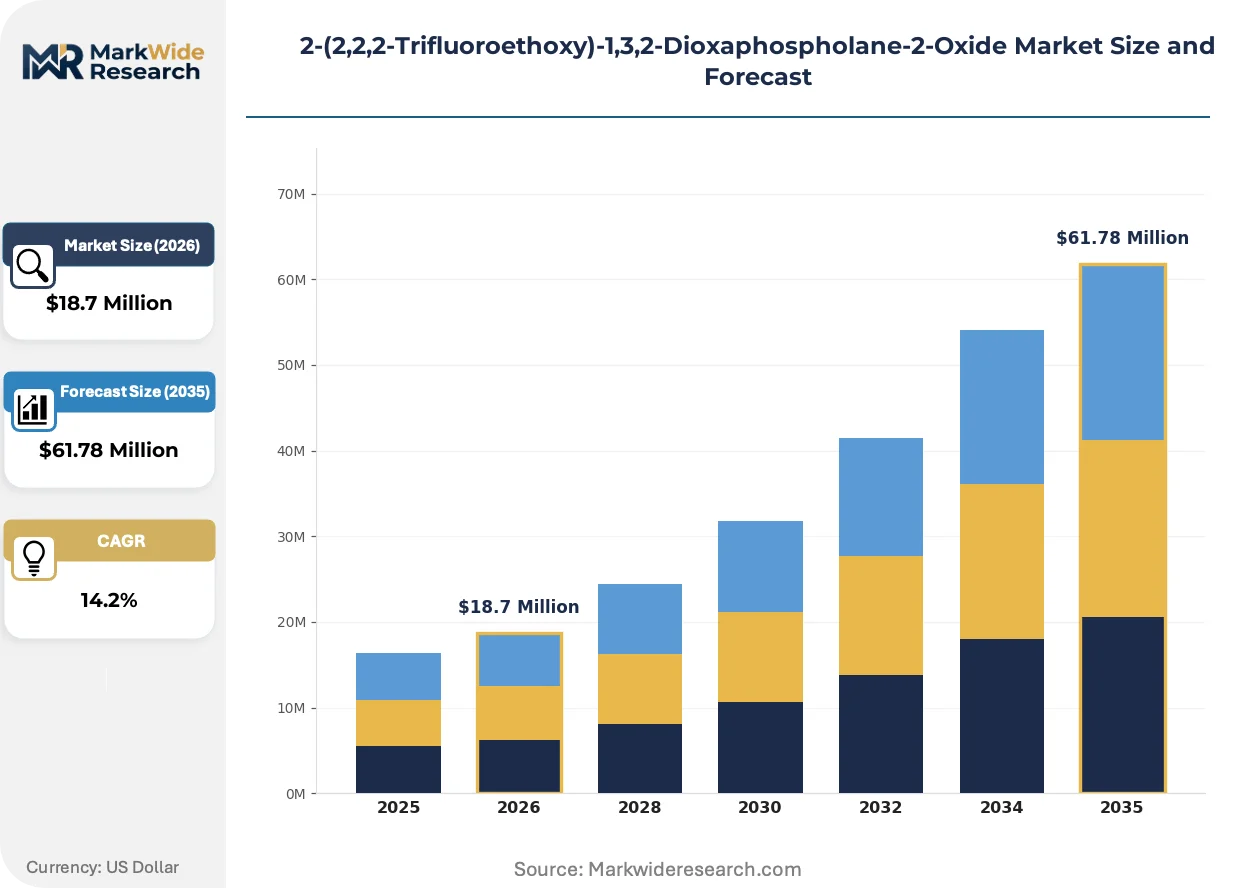
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $61.78 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Gel, Granulate Application: Agriculture, Pharmaceuticals, Coatings, Plastics End User: Manufacturers, Researchers, Distributors, Laboratories Packaging Type: Drums, Bottles, Bags, Containers |
| Companies Covered | GlpBio, Gentaur, BLD Pharm, TCI Chemicals, Sigma-Aldrich, Shijiazhuang Jianxin Biotechnology, SynQuest Labs, Alfa Aesar, ChemScene, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2-(2,2,2-Trifluoroethoxy)-1,3,2-Dioxaphospholane-2-Oxide Market Evolving Landscape
Continuous flow reactor architectures are supplanting batch phosphorus pentoxide condensation, enabling real-time process analytical technology integration that tightens impurity profiles for battery-grade specifications.
Membrane-based purification is supplanting crystallization for residual solvent removal in pharmaceutical-grade powder production. Korean electrolyte manufacturers are adopting this technology to meet residual trifluoroethanol limits below 100 ppm. The shift is compressing qualification cycles for reference-grade material from 18 months toward 12 months.
REACH authorization procedures for fluorinated substances are tightening substance volume tracking requirements across European battery supply chains. Importers must now demonstrate full downstream use disclosure for cyclic phosphate esters above 100 kg annually. German and French electrolyte blenders are consolidating supplier bases to reduce compliance documentation fragmentation.
Long-term offtake contracting is displacing spot procurement for high-purity fluorinated additives. Major South Korean battery chemical integrators are securing 36-month supply agreements with fixed price-volume corridors. This pattern concentrates procurement leverage among Seoul-based electrolyte manufacturers with direct cathode active material partnerships.
2-(2,2,2-Trifluoroethoxy)-1,3,2-Dioxaphospholane-2-Oxide Market Segmentation
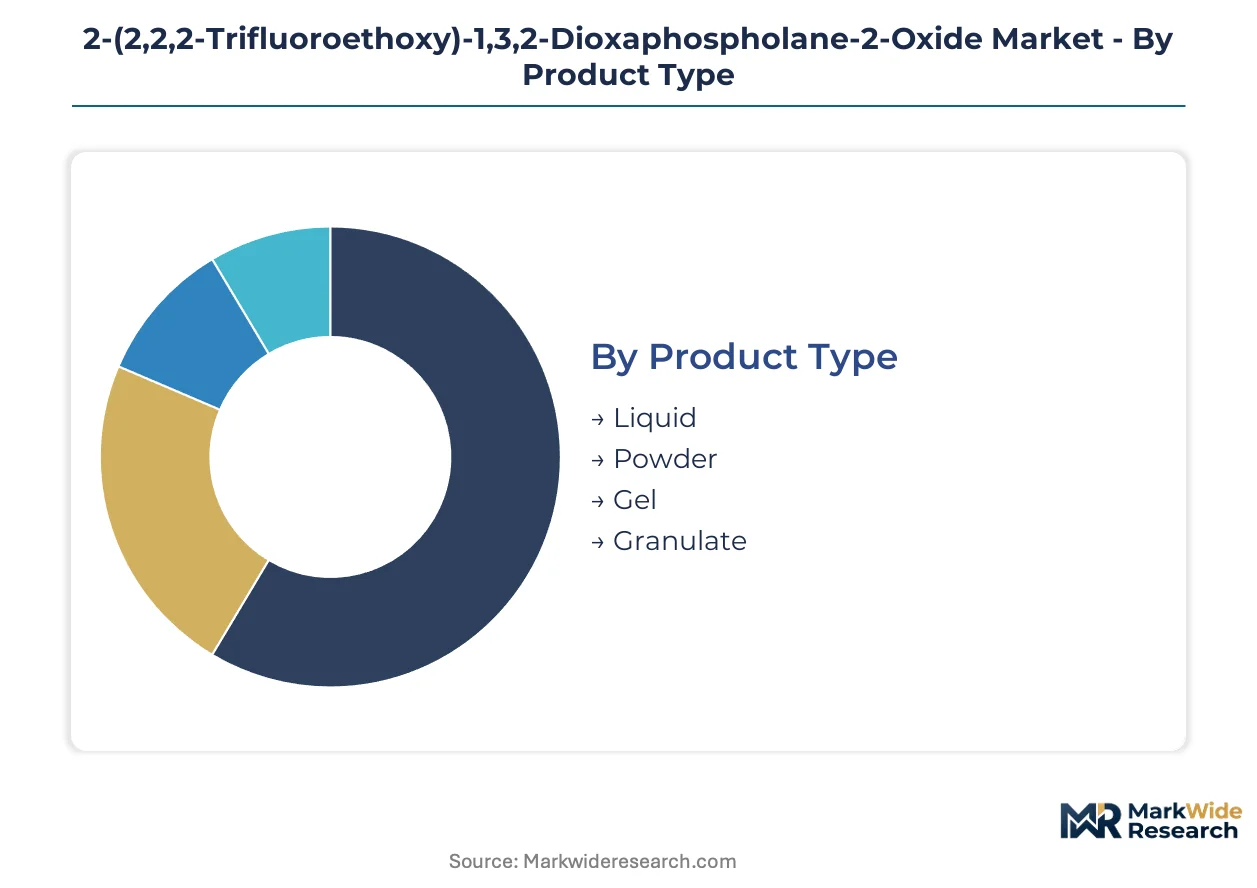
Segmentation in fluorinated organophosphorus chemistry separates procurement channels by purity tier, handling requirements, and regulatory documentation burden. Battery-grade specifications above 99.5% purity command premium positioning distinct from industrial-grade material serving polymer flame-retardant applications.
Product Type:
Liquid formulations concentrate margin pools through automated battery assembly line compatibility, while powder segments extract premiums from pharmaceutical residual solvent thresholds.
- Liquid:Dominates procurement volumes through automated dosing systems in Korean and Chinese electrolyte manufacturing corridors. Seoul-based battery chemical integrators specify liquid handling for carbonate-based electrolyte blending operations requiring thermal stability above 200°C.
- Powder:Commands superior margin pools through stringent residual trifluoroethanol limits below 100 ppm mandated by pharmaceutical-grade certifications. Membrane-based purification technologies are compressing qualification cycles from 18 months toward 12 months for reference-grade material.
- Gel:Specialized viscosity profiles serve niche coating applications where controlled release of flame-retardant functionality is required.
- Granulate:Bulk handling efficiency supports industrial polymer compounding operations with lower purity tolerances.
Liquid holds installed capacity. Powder is rotating up the share rankings.
Application:
Coatings applications are climbing the fastest as electric vehicle OEMs tighten thermal runaway specifications for battery pack housings.
- Coatings:Fastest-expanding demand vector driven by South Korean electric vehicle OEM thermal runaway specifications tightening flame-retardant polymer requirements for battery pack housings.
- Plastics:Competes with melamine polyphosphate and expandable graphite formulations where electrochemical compatibility is non-critical, compressing pricing power for commodity-grade material.
- Pharmaceuticals:Reference-grade specifications anchor premium positioning through Sigma-Aldrich analytical standards portfolio.
- Agriculture:Limited penetration due to fluorinated phosphate cost structure relative to conventional organophosphorus agrochemical intermediates.
Coatings leads capacity additions. Plastics maintains volume foundation.
End User:
Manufacturer procurement concentrates leverage through long-term offtake contracting displacing spot markets.
- Manufacturers:Korean electrolyte blenders are securing 36-month supply agreements with fixed price-volume corridors, consolidating procurement leverage among Seoul-based integrators with direct cathode active material partnerships.
- Researchers:Analytical standards demand from battery material characterization laboratories supports reference-grade premium tiers.
- Distributors:Fragmented documentation burdens from REACH volume tracking requirements above 100 kg annually are forcing consolidation in German and French supply chains.
- Laboratories:31P-NMR and 19F-NMR analytical chemist scarcity commands premium compensation, constraining qualification throughput for new supplier entry.
Manufacturers anchor contract structures. Researchers expand specification influence.
Packaging Type:
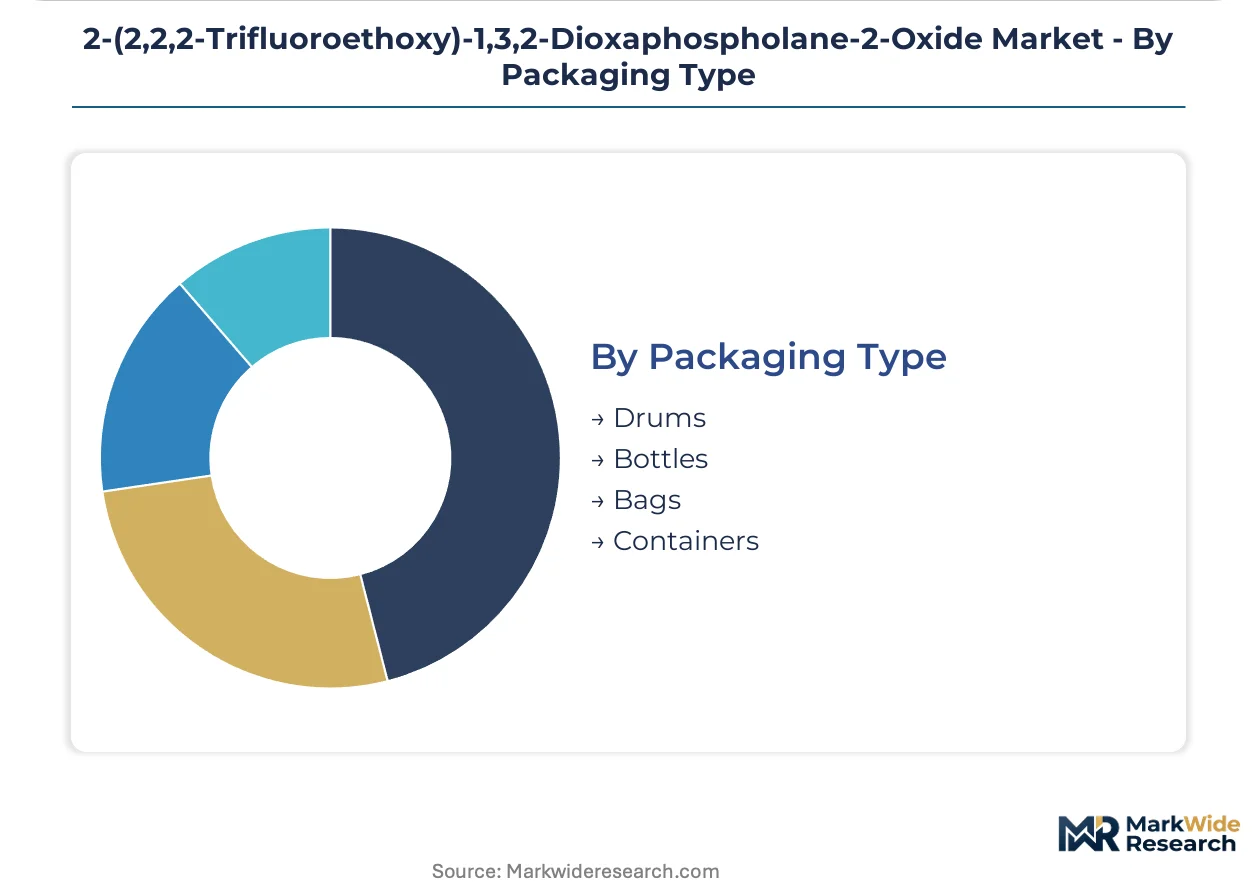
Drums dominate industrial-scale procurement while bottles serve analytical-grade distribution channels.
- Drums:Standard bulk handling for liquid formulations in automated battery assembly corridors around Shenzhen and Seoul production clusters.
- Bottles:Pharmaceutical-grade powder distribution requires inert atmosphere sealing to maintain residual solvent compliance below 100 ppm thresholds.
- Bags:Granulate and powder industrial applications favor cost-efficient bulk logistics for polymer compounding operations.
- Containers:Intermediate volumes support regional distributor inventory positioning for just-in-time electrolyte blending operations.
Drums maintain throughput leadership. Bottles capture specification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing corridors in East Asia concentrate procurement volumes for fluorinated phosphate additives, while regulatory divergence across major economies fragments qualification timelines for new market entrants.
China
MIIT enforces GB/T standards for lithium-ion battery material purity that gate domestic supplier qualification, redirecting procurement toward certified producers. Shenzhen electrolyte manufacturing clusters drive automated assembly line demand for liquid formulations. The Pearl River Delta hosts the densest concentration of battery chemical integrators qualifying fluorinated phosphate supply chains.
South Korea
MFDS regulates pharmaceutical-grade specifications while electric vehicle OEMs tighten thermal runaway requirements for battery pack housings. Seoul-based electrolyte blenders secure 36-month supply agreements with fixed price-volume corridors. The Seoul Capital Area concentrates procurement leverage among cathode active material partnerships.
United States
EPA TSCA Section 5 premanufacture notification frameworks govern new introductions of fluorinated phosphate substances, creating staggered market access timelines. The Pacific Northwest hosts emerging solid-state battery development programs exploring modified additive chemistries. Research institutions in Greater Boston anchor analytical standards demand for reference-grade material.
Germany
ECHA REACH registration mandates full toxicological dossiers for fluorinated phosphate imports exceeding one tonne annually, compressing European supplier bases. Bavaria-based chemical distributors consolidate documentation to reduce compliance fragmentation. The Eindhoven Region across the Dutch border supplies membrane purification technology for residual solvent removal.
Japan
METI oversees industrial chemical standards while TCI Chemicals sustains volume leadership through captive synthesis routes. The Kansai region around Osaka maintains legacy organophosphorus manufacturing infrastructure. Japanese analytical chemist scarcity commands premium compensation in 31P-NMR and 19F-NMR expertise markets.
2-(2,2,2-Trifluoroethoxy)-1,3,2-Dioxaphospholane-2-Oxide Market Competitive Landscape
Concentration sits with integrated chemical specialists possessing captive trifluoroethanol supply and analytical infrastructure for battery-grade purity thresholds. The supplier base stratifies across three archetypes: multinational reference-grade distributors, regional volume manufacturers with backward integration into phosphorus chemistry, and contract synthesis houses serving qualification programs. Competitive moves center on long-term offtake contracting displacing spot procurement, and membrane-based purification technology licensing for residual solvent compliance.
Among multinational reference-grade distributors, Sigma-Aldrich anchors premium positioning through analytical standards portfolio depth. TCI Chemicals exemplifies the regional volume manufacturer archetype with Japanese manufacturing corridor presence. Shijiazhuang Jianxin Biotechnology occupies a position within contract synthesis and regional supply chains for cost-adjusted specifications. These three represent the dominant competitive anchors across pricing and qualification tiers.
| Leading Market Players |
|---|
| GlpBio |
| Gentaur |
| BLD Pharm |
| TCI Chemicals |
| Sigma-Aldrich |
| Shijiazhuang Jianxin Biotechnology |
| SynQuest Labs |
| Alfa Aesar |
| ChemScene |
| Others |
Value Network & Pricing Analysis
Membrane-based purification technology substitution for crystallization is redrawing procurement geography toward Korean electrolyte manufacturers while compressing qualification cycle premiums for reference-grade material. This equipment shift simultaneously concentrates supply chain leverage among Seoul-based integrators and erodes pricing power for non-integrated producers lacking captive analytical infrastructure.
Pricing Analysis
REACH registration dictates the pricing tier structure across European battery supply chains, separating dossier-complete suppliers from commodity importers. Three-tier pricing structure across premium reference-grade, certified battery-grade, and industrial-grade material reflects purity thresholds above 99.5% and residual solvent compliance below 100 ppm. Cost compression in standard-grade liquid formulations is intensifying because phosphorus pentoxide feedstock volatility compresses margin predictability for non-integrated producers. Research laboratories exhibit lowest price sensitivity due to analytical chemist scarcity, while polymer compounding operations in industrial applications drive hardest volume negotiations.
Supply Chain Analysis
Port congestion on Busan-Shanghai trade lanes elevates inbound logistics costs for European and North American electrolyte blenders sourcing from East Asian manufacturing corridors. Supply concentrates in China, South Korea, and Japan, with the Pearl River Delta, Seoul Capital Area, and Kansai region hosting densest production clusters. The supply chain draws from captive trifluoroethanol synthesis, phosphorus pentoxide condensation chemistry, and membrane purification equipment imports from the Eindhoven Region. Single-source vulnerability in 31P-NMR and 19F-NMR analytical chemist expertise constrains new supplier qualification throughput. Distribution runs through long-term offtake contracting with 36-month fixed price-volume corridors displacing spot procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state battery chemistry transitions fragment demand into sulfide and oxide electrolyte formulation niches, creating specialist additive qualification opportunities beyond incumbent carbonate-system suppliers.
For Market Incumbents: Secure 36-month supply agreements with fixed price-volume corridors before alternative flame retardants gain traction in polymer coating applications. Deepen backward integration into captive trifluoroethanol supply to defend margin position against phosphorus pentoxide feedstock volatility. Invest in continuous flow reactor architectures with real-time process analytical technology to tighten impurity profiles for battery-grade specifications above 99.5%. For New Entrants and Emerging Players: Lead with solid-state battery formulation partnerships targeting sulfide and oxide electrolyte architectures where incumbent carbonate-system suppliers lack qualified additive chemistries. Target India's PLI scheme for advanced chemistry cell manufacturing as the most penetrable geography with domestic electrolyte additive qualification programs. Pursue membrane-based purification technology licensing from Dutch equipment providers as the go-to-market angle for pharmaceutical-grade residual solvent compliance. For Investors and Strategic Acquirers: REACH authorization procedures for fluorinated substances reshape the acquisition landscape toward dossier-complete suppliers with full downstream use disclosure infrastructure. Prioritize vertically integrated specialists with captive phosphorus chemistry and analytical infrastructure over contract synthesis houses facing qualification turbulence. Watch OECD structural similarity assessments for per- and polyfluoroalkyl substance precursor reclassification as the signal indicating regulatory-driven consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Trifluoroethanol | Captive feedstock supply insulates margin predictability from phosphorus pentoxide volatility. |
| Membrane Purification Technology Licensing | Dutch equipment partnerships compress qualification cycles from 18 months toward 12 months. |
| Long-term Supply Agreement Structuring | Seoul-based electrolyte manufacturers consolidate procurement leverage through 36-month contracts. |
| Solid-State Battery Formulation Partnership | Sulfide and oxide electrolyte architectures open additive chemistry white space beyond incumbents. |
| Continuous Flow Reactor Deployment | Real-time process analytical technology integration tightens impurity profiles for battery-grade thresholds. |
Research Methodology
Cross-validation between electrolyte manufacturer procurement leads and specialty chemical distributor documentation anchors the qualitative findings in operational reality. Primary interviews with Korean battery chemical integrators, Japanese organophosphorus plant managers, German REACH compliance officers, and Chinese MIIT certification specialists combined with secondary validation from customs trade data, ECHA registration databases, SEC filings of listed chemical producers, and GB/T standard enforcement records. Bottom-up segmentation modeling and top-down market sizing triangulate volume estimates across purity tiers and application segments.
Sensitivity analysis on phosphorus pentoxide feedstock cost assumptions and qualification cycle duration parameters tests forecast robustness across the projection horizon. The analytical framework models grade tier, end-use application, packaging format, and regional production hub segmentation dimensions. CAGRs derive from electrolyte additive demand elasticity against lithium-ion battery production forecasts and solid-state battery technology transition timelines. Industry-specific inputs include 31P-NMR and 19F-NMR analytical chemist compensation trends and membrane purification equipment adoption rates.
The analysis sits within stated boundaries; outcomes outside sustained GB/T standard enforcement, REACH registration maintenance, and thermal runaway specification tightening would require recalibration. Forecasts reflect documented assumptions regarding solid-state battery chemistry transition pace and per-fluoroalkyl substance regulatory trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Stearyl Alcohol Market
Specialty Chemicals
Phosphonate Market
Specialty Chemicals
Mexoryl SX (Ecamsule) Market
Specialty Chemicals
Sodium Adipate Market
Specialty Chemicals
Prils Market
Specialty Chemicals
Europe Malic Acid Market
Specialty Chemicals
Marula Oil Market
Specialty Chemicals
Cellulose Ether Market
Specialty Chemicals
Ferrous Gluconate Market
Specialty Chemicals
Asia Pacific Aerosol Cans Market
Specialty Chemicals
Ethyl Polysilicate Market
Specialty Chemicals
Global Anti-Static Agents Market
Specialty Chemicals
Diindolylmethane Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
Zinc Methionine Chelates Market
Specialty Chemicals
Erucic Acid Market