
 North America Plant-Based Egg Market | 2026-2036
North America Plant-Based Egg Market Size, Share, and Industry Trends Forecast 2026-2036
North America Plant-Based Egg Market Analytics
Foodservice distribution channels is reconfiguring around plant-based egg procurement as institutional buyers rewrite sourcing specifications. Eat Just leverages its mung bean protein isolate technology to anchor supply relationships with national restaurant chains. Follow Your Heart competes through its established refrigerated distribution network spanning conventional grocery and natural retail. The EVERY Company differentiates via precision fermentation-derived proteins that occupy a premium tier in food manufacturing applications.
North America plant-based eggs comprise formulated emulsions of legume proteins, vegetable gums, and lecithins designed to replicate the functional properties—coagulation, foaming, and emulsification—of conventional chicken eggs in cooking and baking applications. Liquid egg formulations dominate current volume due to their direct substitutability in foodservice operations, while powdered egg variants sustain margin pools through extended shelf stability and reduced cold-chain dependency. Pea protein sourcing leads ingredient formulations for clean-label positioning, though soy protein retains cost advantages in bakery end uses where flavor masking proves less critical.
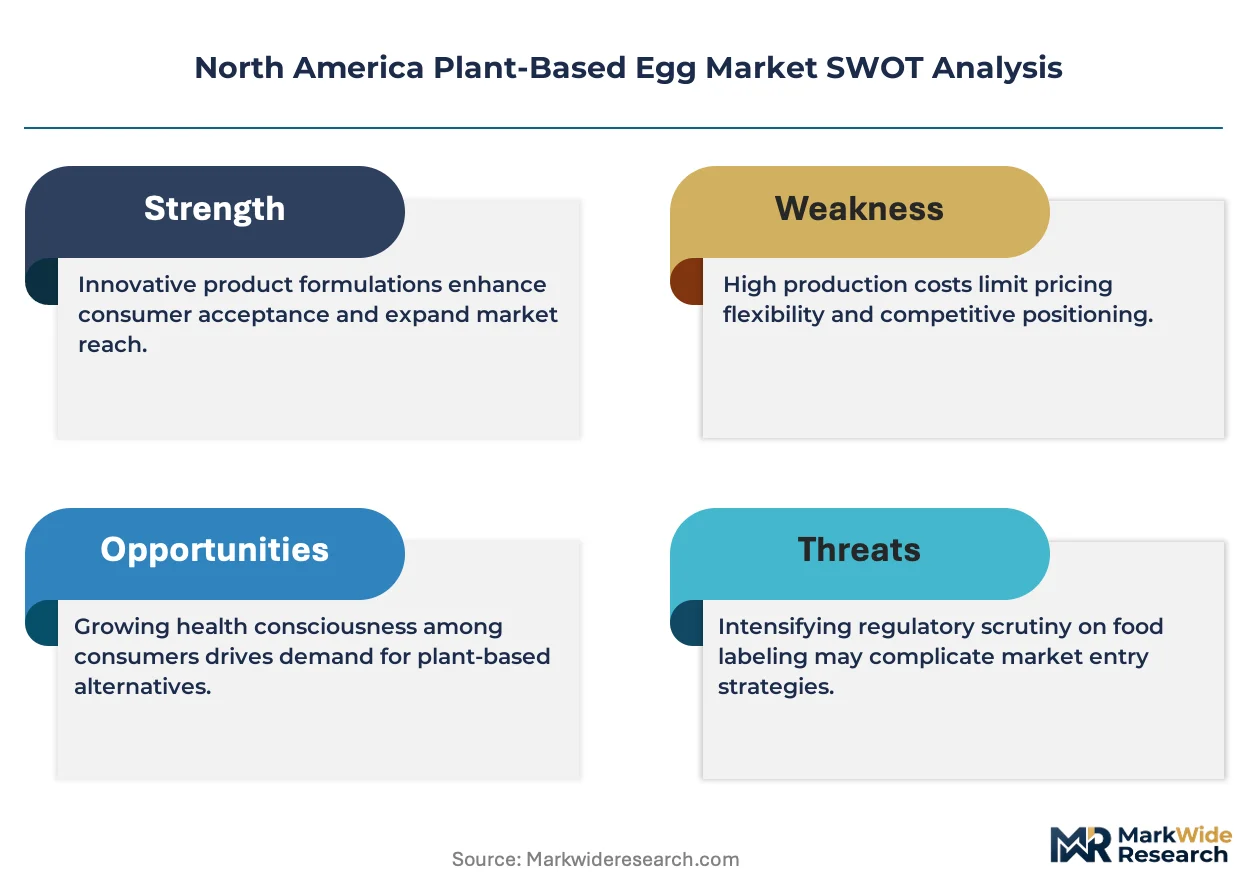
The U.S. FDA and USDA share jurisdiction over plant-based egg labeling and safety standards, with ongoing rulemaking on standards of identity creating compliance uncertainty for formulation claims. Health Canada regulates parallel products through its Food Directorate under the Food and Drugs Act, requiring substantiated protein quality claims that shape how manufacturers communicate nutritional equivalence. Stakeholders must monitor whether state-level cage-free mandates in California, Massachusetts, and Colorado accelerate foodservice substitution timelines faster than federal labeling clarity emerges.
Market Dynamics
Foodservice operators across the United States and Canada are rewriting procurement specifications to mandate cage-free and plant-based alternatives, creating immediate volume commitments that reshape supplier capacity planning and ingredient sourcing strategies.
Growth Catalysts
- California Proposition 12:This animal welfare mandate forces institutional buyers throughout the state to eliminate conventional cage-sourced eggs from supply chains, accelerating substitution timelines for plant-based alternatives in university and corporate cafeteria contracts.
- Mung bean protein isolation:Advances in extraction and functionalization technology now deliver egg-replacement performance in scrambles and omelets without the beany off-notes that previously limited foodservice acceptance.
- Quick-service breakfast menus:National chains expanding all-day breakfast offerings require scalable, pathogen-resistant egg alternatives that reduce kitchen complexity and cross-contamination protocols.
Market Restraints
- Yellow pea protein price volatility:Concentrated sourcing from Canadian prairie processors exposes manufacturers to crop yield fluctuations and rail transport bottlenecks that compress margin pools.
- Functional gap in meringue applications:Current plant-based formulations fail to achieve the foam stability and gloss required for commercial bakery macaron and angel food cake production.
- FDA standards of identity uncertainty:Ongoing rulemaking on egg labeling creates compliance risk for manufacturers making direct nutritional equivalence claims on retail packaging.
Strategic Opportunities
- Colorado and Massachusetts cage-free mandates:These state-level regulatory tailwinds replicate California's procurement pressure, creating contiguous demand expansion for suppliers with established West Coast distribution infrastructure.
- Precision fermentation protein blends:Combining legume bases with fermentation-derived albumins addresses functional gaps in whipping and coagulation for premium bakery ingredient channels.
- Direct-to-foodservice bulk dispensing:Bag-in-box liquid formats with extended ambient stability reduce cold-chain costs for institutional operators in Texas and Florida where refrigeration infrastructure remains limited.
Industry Challenges
- Food technologist recruitment:Shortage of formulation chemists with dual expertise in plant protein functionality and traditional egg rheology slows R&D cycle times for regional manufacturers.
- Co-manufacturer qualification:Dedicated allergen-free production lines require capital investment that exceeds capacity commitment thresholds for mid-scale brands attempting retail distribution expansion.
- Health Canada protein quality substantiation:PDCAAS scoring requirements for nutritional equivalence claims demand extended clinical validation timelines that delay product launches in Canadian retail channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Plant-Based Egg Market |
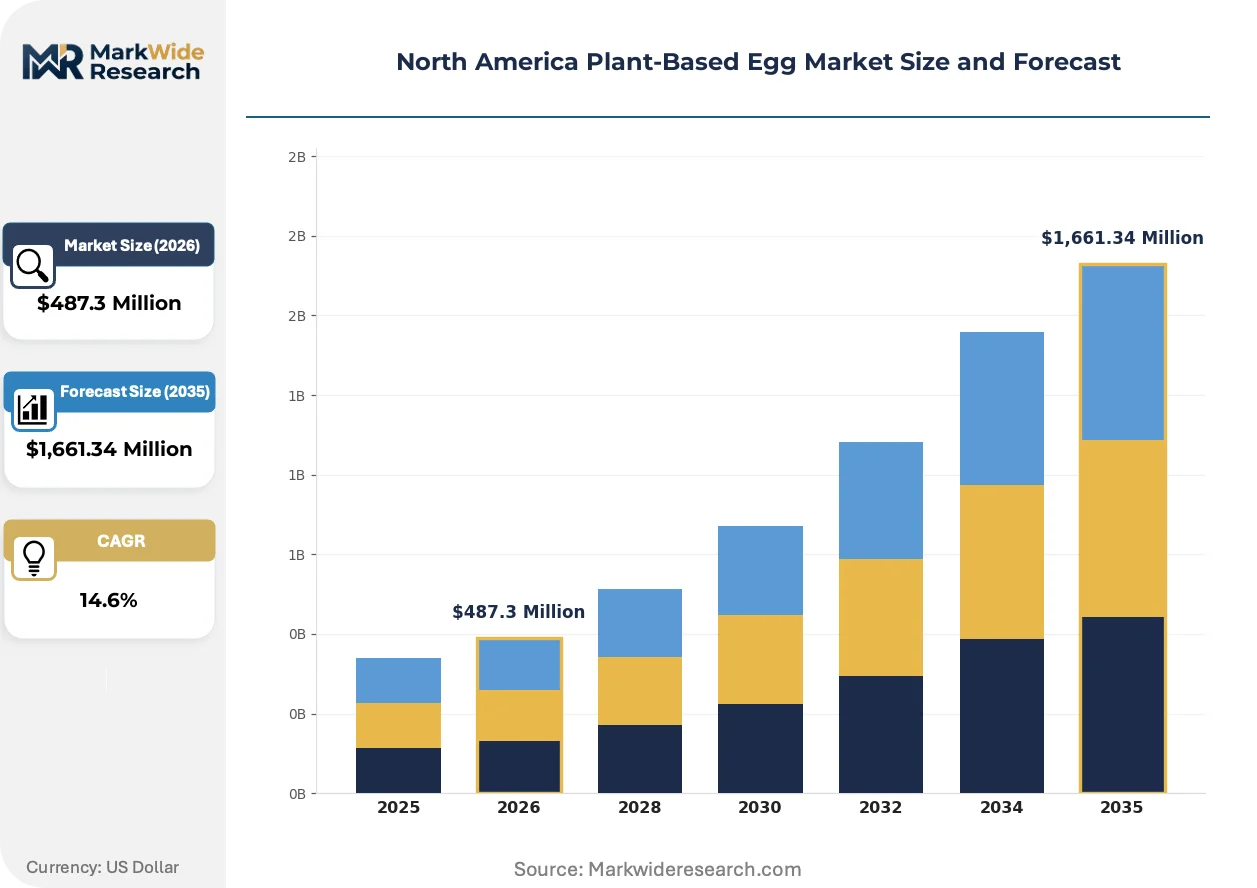
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Egg, Powdered Egg, Scrambled Egg, Egg Substitute End User: Household, Food Service, Retail, Bakery Packaging Type: Bottles, Pouches, Tetra Packs, Cartons Ingredient Source: Pea Protein, Soy Protein, Almond Protein, Others |
| Companies Covered | Follow Your Heart, Eat Just, The EVERY Company, Vegg, Zero Egg, Hatched, Simply Eggless, OGGS, Earth Island, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Plant-Based Egg Market Evolving Landscape
Formulation science and procurement specifications are converging to redefine performance benchmarks for egg alternatives, with functional parity now superseding ingredient simplicity as the primary purchase criterion across commercial food manufacturing.
Mung bean protein isolate is migrating from niche natural retail positioning into mainstream foodservice supply chains. National restaurant operators now specify this ingredient for scrambled egg alternatives in breakfast burritos and sandwich applications. The shift compresses demand for soy-based formulations that dominated early plant-based egg iterations.
The FDA's evolving standards of identity for egg products create compliance uncertainty for manufacturers positioning alternatives in retail dairy cases. This regulatory friction forces reformulation of label claims and redirects marketing investment toward foodservice channels where standards enforcement remains less stringent. California and Massachusetts retail operators face the tightest compliance scrutiny.
University and corporate dining contracts now specify plant-based protein quotas that include egg alternatives alongside meat and dairy substitutes. Foodservice management companies respond by consolidating procurement through specialized distributors with dedicated plant-based SKU portfolios. This concentration is most visible in California's UC system and Pacific Northwest tech campus dining operations.
North America Plant-Based Egg Market Segmentation
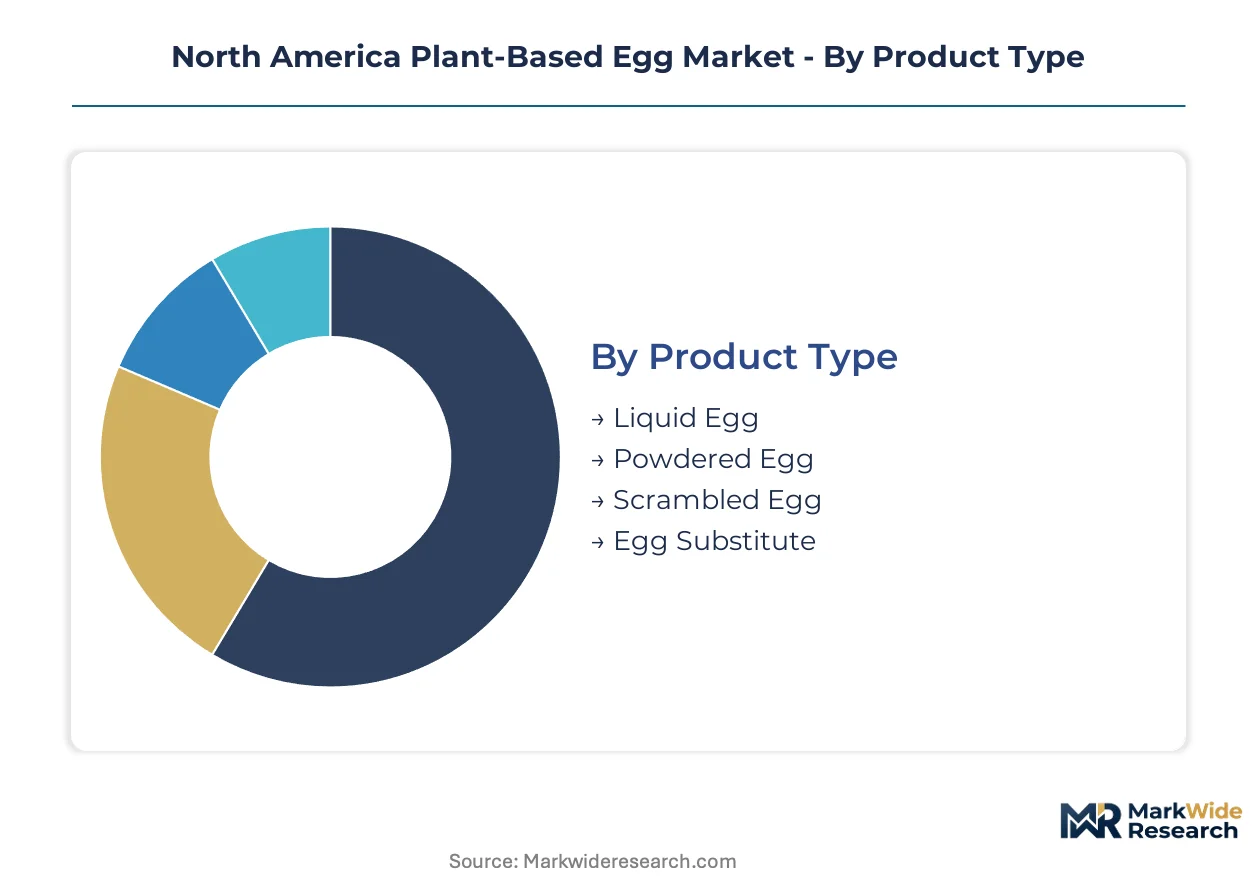
Segmentation in North America's plant-based egg market reveals how formulation chemistry, distribution infrastructure, and procurement specifications intersect. Manufacturers must align product architecture with the distinct performance requirements of foodservice operators, retail channels, and industrial bakeries.
Product Type:
Mature formats dominate foodservice procurement, while emerging variants capture niche applications and extended-shelf-life positioning.
- Liquid Egg:Formulated emulsions of legume proteins, vegetable gums, and lecithins deliver direct substitutability in scrambled applications and baking. Quick-service chains in California and Texas specify liquid formats for breakfast burrito programs, driven by kitchen workflow efficiency and reduced cross-contamination protocols.
- Powdered Egg:Spray-dried protein concentrates with extended ambient stability reduce cold-chain dependency for institutional buyers. University dining contracts across Massachusetts and Colorado favor powdered variants for back-of-house inventory flexibility, though reconstitution ratios require staff retraining.
- Scrambled Egg:Pre-cooked frozen formats target convenience-oriented retail and limited-service foodservice.
- Egg Substitute:Specialty formulations for vegan baking and binding applications in premium natural retail channels.
Liquid egg handles the majority of throughput; powdered egg is expanding most quickly in institutional procurement.
End User:
Volume concentration varies sharply across customer types, with procurement scale and specification stringency creating divergent margin profiles.
- Food Service:National restaurant chains and institutional cafeterias mandate cage-free and plant-based alternatives in rewritten sourcing specifications. The UC system and Pacific Northwest tech campuses consolidate procurement through specialized distributors with dedicated plant-based SKU portfolios.
- Household:Retail consumers in California and Colorado purchase liquid formats for home cooking applications, with Proposition 12 awareness accelerating trial rates.
- Retail:Conventional grocery and natural retail channels face FDA standards of identity uncertainty, redirecting manufacturer investment toward foodservice.
- Bakery:Commercial producers encounter functional gaps in meringue applications, limiting adoption to binding and emulsification uses where flavor masking proves less critical.
Food service commands the largest volume commitment; household penetration is climbing the fastest on a percentage basis.
Packaging Type:
Cost tier and supply chain configuration dictate format selection, with ambient stability and dispensing efficiency as primary technical criteria.
- Bottles:Standard rigid packaging for refrigerated liquid egg in retail dairy cases and conventional grocery distribution.
- Pouches:Flexible formats with reduced material cost and shipping cube efficiency for natural retail channels.
- Tetra Packs:Aseptic cartons deliver extended shelf stability for ambient distribution in Texas and Florida where refrigeration infrastructure remains limited.
- Cartons:Traditional egg-alternative packaging mimicking conventional shell egg presentation for consumer familiarity.
Tetra packs address the most constrained supply chain conditions; pouches show the steepest adoption curve in cost-sensitive channels.
Ingredient Source:
Clean-label positioning and cost engineering drive protein selection, with sourcing geography exposing manufacturers to commodity volatility.
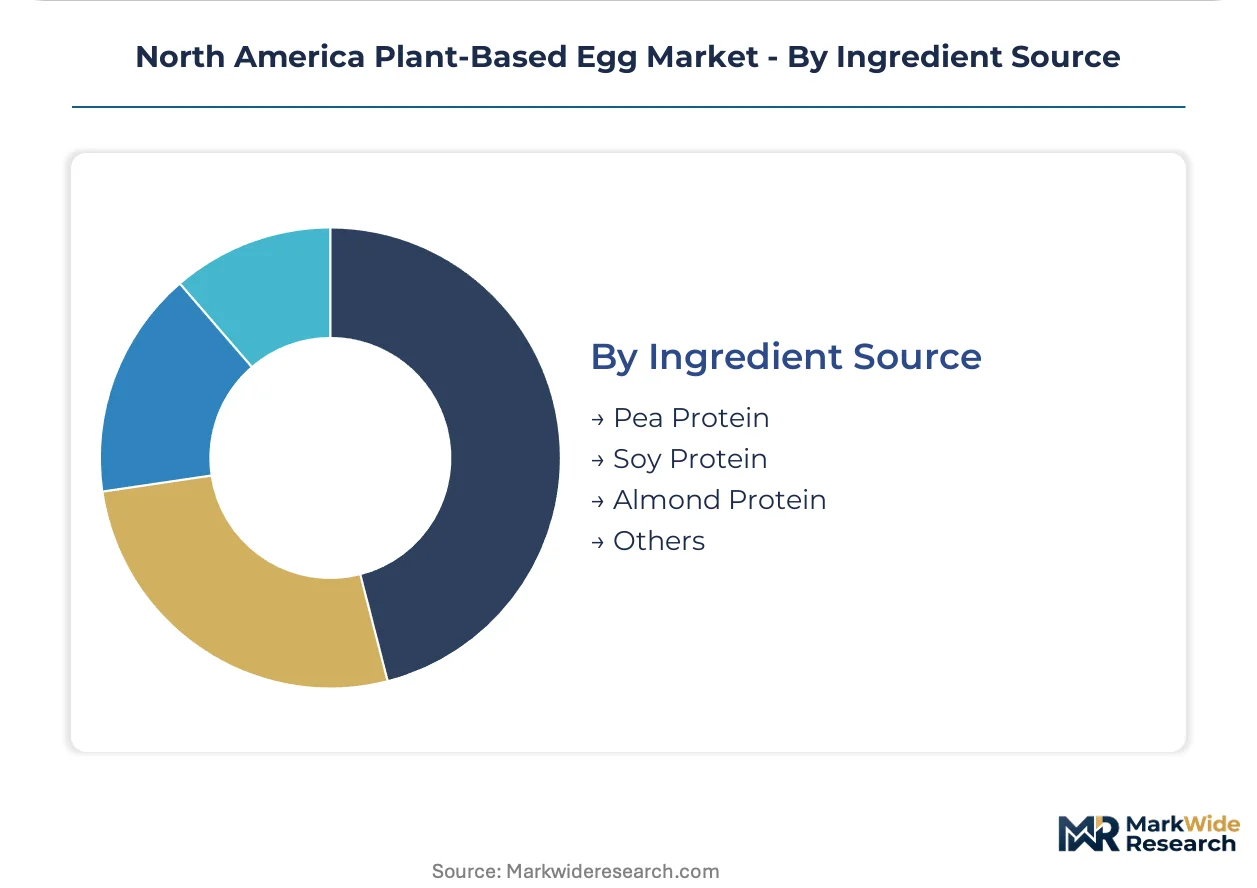
- Pea Protein:Yellow pea isolates from Canadian prairie processors anchor clean-label formulations for retail positioning. Rail transport bottlenecks and crop yield fluctuations compress margin pools, forcing manufacturers toward multi-source contracting strategies.
- Soy Protein:Cost-advantaged isolates retain dominance in bakery end uses where beany off-notes prove less critical than functional performance.
- Almond Protein:Premium positioning for allergen-conscious and paleo-oriented consumer segments in California natural retail.
- Others:Mung bean protein isolate migrating from niche positioning into mainstream foodservice supply chains for scrambled egg alternatives.
Pea protein leads on label appeal; mung bean is gaining share fastest in foodservice specification wins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles-Long Beach complex anchors North American distribution capacity for plant-based egg ingredients, with refrigerated container throughput enabling just-in-time delivery to West Coast foodservice operators. Interstate rail corridors linking California's Central Valley processing facilities to Midwest distribution hubs compress transit times for temperature-sensitive liquid formulations. Cross-border trucking lanes through Detroit-Windsor and Laredo-Nuevo Laredo facilitate ingredient sourcing between U.S. and Canadian manufacturing plants.
United States
California's Proposition 12 enforcement drives institutional procurement shifts across university and corporate cafeteria networks. The FDA's evolving standards of identity for egg products create compliance complexity for retail labeling claims. Los Angeles and San Francisco Bay Area foodservice operators consolidate purchasing through specialized distributors with dedicated plant-based SKU portfolios.
Canada
Health Canada's Food Directorate mandates PDCAAS protein quality substantiation that extends product launch timelines in retail channels. Yellow pea protein processors in Saskatchewan and Manitoba face rail transport bottlenecks that expose manufacturers to margin compression. Toronto and Vancouver foodservice markets specify cage-free and plant-based alternatives in rewritten institutional sourcing contracts.
Mexico
Expanding quick-service breakfast programs in Mexico City and Monterrey create demand for pathogen-resistant egg alternatives that reduce kitchen complexity. The country's national food safety regulator maintains parallel standards to FDA guidelines that facilitate cross-border formulation consistency. Baja California processing facilities leverage proximity to California distribution networks for liquid egg export.
Colorado
State-level cage-free mandates replicate California's procurement pressure for institutional buyers throughout the Front Range corridor. Denver and Boulder corporate campus dining operations specify plant-based protein quotas that include egg alternatives alongside meat substitutes. Mountain West distribution infrastructure supports ambient-stable powdered formats for remote institutional locations with limited refrigeration.
Massachusetts
Commonwealth cage-free regulations accelerate substitution timelines for university dining contracts across the Boston metropolitan area. Harvard and MIT campus foodservice operations consolidate procurement through distributors with dedicated plant-based portfolios. Northeast Corridor cold-chain density supports liquid egg distribution with minimal spoilage risk.
North America Plant-Based Egg Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The North America plant-based egg market structures around three tiers: mung bean protein technology platforms, precision fermentation protein developers, and established refrigerated distribution networks. Strategic archetypes include ingredient technology licensors, foodservice supply contract holders, and clean-label retail brand operators. Capacity expansion and strategic partnerships dominate competitive moves as manufacturers secure pea and mung bean protein offtake agreements.
Within the technology platform tier, Eat Just and The EVERY Company exemplify divergent protein sourcing strategies that anchor competitive positioning. Follow Your Heart occupies a position within established refrigerated distribution networks spanning conventional grocery and natural retail channels. These three companies represent the primary archetypes: mung bean isolate technology, precision fermentation-derived proteins, and legacy plant-based brand infrastructure.
| Leading Market Players |
|---|
| Follow Your Heart |
| Eat Just |
| The EVERY Company |
| Vegg |
| Zero Egg |
| Hatched |
| Simply Eggless |
| OGGS |
| Earth Island |
| Others |
Value Network & Pricing Analysis
Canadian prairie yellow pea processors anchor ingredient cost structures for clean-label formulations, concentrating margin pools with foodservice operators who command volume-commitment leverage in contract negotiations. This upstream concentration forces manufacturers toward multi-source contracting strategies that reshape downstream pricing power across liquid and powdered egg formats.
Pricing Analysis
Volume-discount tiering structures dominate procurement relationships between national restaurant chains and plant-based egg suppliers. Pricing stratifies across premium precision-fermentation formulations, standard legume-protein blends, and economy-grade soy-based alternatives used in bakery applications. Cost compression in mid-tier pea protein formulations is intensifying because rail transport bottlenecks and crop yield fluctuations expose margin pools. Quick-service chains exhibit the highest price sensitivity due to breakfast menu margin constraints, while premium natural retail channels absorb price premiums for mung bean isolate positioning.
Supply Chain Analysis
Contract-manufacturing concentration rests with dedicated allergen-free production facilities in California's Central Valley and Midwest food processing corridors. Raw material sourcing draws from Canadian prairie pea protein processors, mung bean suppliers in Asia, and domestic lecithin and vegetable gum distributors. Single-source vulnerability in yellow pea protein isolates from Saskatchewan and Manitoba exposes manufacturers to rail transport disruptions and crop yield volatility. Distribution runs through refrigerated container networks from Los Angeles-Long Beach to institutional foodservice operators, with ambient-stable powdered formats penetrating remote Mountain West locations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
California Proposition 12 enforcement signals a regulatory inflection that transforms procurement specifications across institutional foodservice, creating high-growth disruption as cage-free mandates cascade through contiguous state markets.
For Market Incumbents: Entrench supply relationships with national restaurant chains through exclusive mung bean protein isolate technology licensing that locks out precision-fermentation competitors. Secure captive supply of Canadian yellow pea protein through backward integration into prairie processing facilities, defending against emerging entrants exploiting rail transport bottlenecks to undercut contract pricing. For New Entrants and Emerging Players: Pursue white-space opportunities in Colorado and Massachusetts institutional dining contracts where cage-free mandates replicate California's procurement pressure without established supplier saturation. Target university and corporate cafeteria segments in the Front Range corridor and Boston metropolitan area with bag-in-box liquid formats that reduce cold-chain costs for operators with limited refrigeration infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward precision-fermentation protein developers with functional performance advantages in bakery meringue applications where current plant-based formulations fail. Long-term viability hinges on FDA standards of identity clarity that validates nutritional equivalence claims for retail channel expansion. Watch for Health Canada PDCAAS scoring determinations as the signal indicating Canadian retail market readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Mung Bean Protein Isolate Scale-Up | Eat Just's extraction technology locks in national chain supply relationships against fermentation competitors. |
| Precision Fermentation Protein Development | The EVERY Company's albumin production addresses functional gaps in commercial bakery meringue applications. |
| Direct-to-Foodservice Bulk Dispensing | Bag-in-box ambient-stable formats reduce cold-chain dependency for Texas and Florida institutional operators. |
| Multi-Source Pea Protein Contracting | Canadian prairie processor diversification mitigates rail transport bottlenecks compressing margin pools. |
| California Distribution Infrastructure Expansion | Los Angeles-Long Beach refrigerated container capacity secures just-in-time delivery to West Coast foodservice. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with foodservice procurement directors, plant-based protein R&D scientists, institutional dining contract managers, and refrigerated distribution logistics specialists; and secondary validation through FDA standards of identity dockets, Health Canada Food Directorate guidance documents, California Proposition 12 enforcement records, and USDA cage-free mandate tracking databases. Bottom-up volume modeling triangulated against top-down market sizing across ingredient source and end-user segmentation.
Forecast inputs considered procurement specification timelines at major university systems, quick-service chain menu expansion patterns, and precision-fermentation protein commercialization trajectories across the analysis window. Segmentation dimensions modeled include product type, end user, packaging format, and ingredient source with regional regulatory cluster overlays. CAGRs derived from volume commitment curves at national restaurant chains and institutional foodservice operators, cross-referenced with pea and mung bean protein capacity expansion announcements.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, rail freight rates, or cold-chain energy costs would shift the trajectory. Forecasts reflect assumptions about FDA rulemaking timelines and state-level cage-free mandate enforcement consistency. Quarterly review of Proposition 12 compliance data, Health Canada protein quality substantiation determinations, and quick-service chain earnings call commentary is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
USA Plant-Based Creamers Market
Plant Based Food
Organic Rice Protein Market
Plant Based Food
Oat Protein Market
Plant Based Food
Plant-Based Waters Market
Plant Based Food
Vegan Protein Concentrate Market
Plant Based Food
Global Plant Protein Market
Plant Based Food
Plant-Based Natural Flavor Market
Plant Based Food
Plant Based Breads Market
Plant Based Food
Plant-Based Yogurt Market
Plant Based Food
Indoor Leafy Green Precision Nutrition Program Market
Plant Based Food
Textured Pea Protein Market
Plant Based Food
Mexico Plant-Based Food and Beverages Market
Plant Based Food
India Plant Based Meat Alternatives Market
Plant Based Food
Vegan Steak Market
Plant Based Food
Plant-Based Hot Dogs Market
Plant Based Food
Lentil Protein Market