
 North America High-Intensity Sweeteners Market | 2026-2036
North America High-Intensity Sweeteners Market Size, Share, and Industry Trends Forecast 2026-2036
North America High-Intensity Sweeteners Market Analytics
The U.S. FDA updated nutrition labeling requirements for added sugars is rebalancing procurement priorities across North American beverage and bakery supply chains. Cargill leverages its integrated fermentation and extraction infrastructure to supply steviol glycosides at scale across the Midwest. Tate & Lyle anchors its position through specialized reformulation services that help food manufacturers replace caloric sweeteners without altering sensory profiles. Ajinomoto Co., Inc. differentiates via amino acid-based sweetener chemistry that serves pharmaceutical and nutraceutical applications.
High-intensity sweeteners are non-caloric or low-caloric compounds, typically 200 to 600 times sweeter than sucrose, produced through chemical synthesis, fermentation, or extraction from plant sources such as Stevia rebaudiana; they function primarily as sugar substitutes in processed foods, beverages, and pharmaceutical formulations where caloric reduction or glycemic control is required. Steviol glycosides now lead product type demand as clean-label preferences push brands away from synthetic chemistry. Sucralose maintains volume dominance in beverage applications where thermal stability during pasteurization remains critical. Among end users, food manufacturers represent the deepest margin pool because bulk procurement contracts and long-term supply agreements lock in multi-year partnerships with sweetener suppliers.
The FDA, Health Canada, and the U.S. EPA collectively govern ingredient safety assessments, residue limits, and environmental discharge standards for high-intensity sweetener manufacturing facilities across North America. These frameworks determine which novel molecules gain market access and how existing products must document purity profiles. Stakeholders must monitor pending GRAS determinations and provincial-level environmental permits that could reshape production economics.
Market Dynamics
Reformulation mandates from FDA and Health Canada are compressing procurement timelines across North American beverage and bakery supply chains, forcing manufacturers to revalidate entire product portfolios under accelerated compliance windows.
Growth Catalysts
- Front-of-Package Labeling:Health Canada's mandatory nutrition symbol regulations are pushing Canadian food processors to accelerate sugar reduction programs ahead of enforcement deadlines.
- Fermentation Scale-Up:Bioprocess engineering advances are lowering unit costs for steviol glycoside production, expanding accessible supply for mid-tier beverage formulators.
- Great Lakes Manufacturing Cluster:Concentrated food and beverage processing infrastructure across Michigan, Ohio, and Illinois generates dense procurement demand and logistics efficiencies for sweetener distributors.
Market Restraints
- Stevia Leaf Supply Concentration:Raw stevia cultivation concentrates in specific growing regions, exposing North American extractors to climate volatility and agricultural input cost swings.
- Thermal Stability Limitations:Natural high-intensity sweeteners degrade under pasteurization temperatures, restricting their deployment in hot-fill beverage applications where sucralose retains functional dominance.
- GRAS Determination Timelines:Novel molecule approvals through FDA's GRAS notification program face extended review cycles, delaying commercialization of next-generation sweetener chemistry.
Strategic Opportunities
- Pharmaceutical Formulations:Amino acid-based sweetener platforms are penetrating pediatric and geriatric drug delivery systems where glycemic control and palatability converge.
- Clean-Label Bakery:Underpenetrated opportunities exist in reduced-sugar baked goods where thermal processing requirements have historically excluded natural high-intensity alternatives.
- Provincial Environmental Permits:Ontario and Quebec regulatory frameworks for fermentation facility emissions create first-mover advantages for suppliers investing in closed-loop bioprocessing infrastructure.
Industry Challenges
- Sensory Matching Expertise:Food manufacturers face acute shortages of formulation scientists capable of replicating sucrose's temporal sweetness profile using high-intensity alternatives.
- Multi-Jurisdictional Compliance:Divergent purity specifications between FDA and Health Canada force suppliers to maintain parallel analytical protocols and documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America High-Intensity Sweeteners Market |
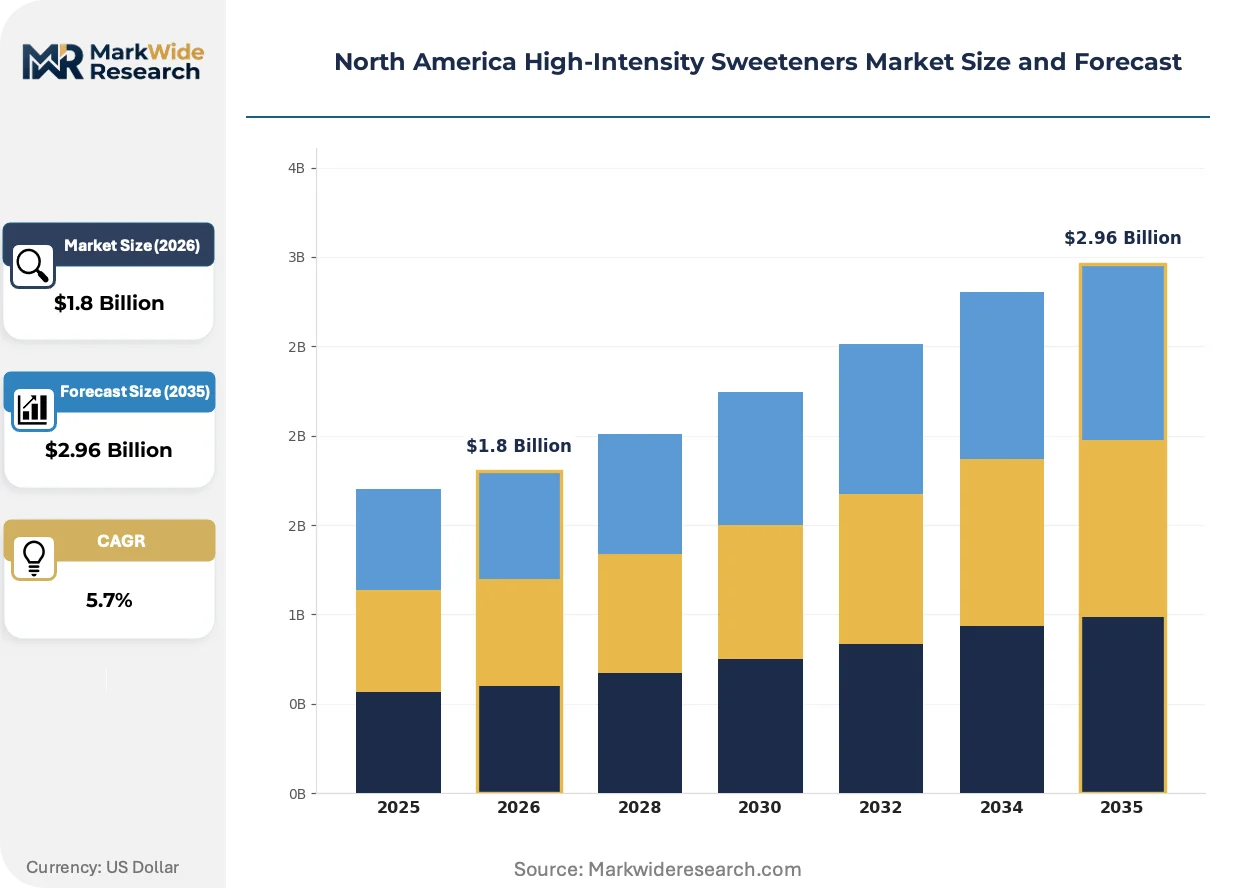
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steviol Glycosides, Sucralose, Aspartame, Acesulfame Potassium Application: Beverages, Dairy Products, Bakery Products, Pharmaceuticals End User: Food Manufacturers, Beverage Companies, Retailers, Restaurants Form: Liquid, Powder, Granulated, Tablet |
| Companies Covered | Archer Daniels Midland Company, Cargill, Ingredion Incorporated, Tate & Lyle, International Flavors & Fragrances Inc., Ajinomoto Co., Inc., Roquette, Sweegen, Heartland, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America High-Intensity Sweeteners Market Evolving Landscape
Bioprocess automation and regulatory labeling convergence are restructuring how North American sweetener suppliers configure production assets and technical service capabilities.
Precision fermentation systems are automating steviol glycoside production at commercial scale, enabling contract manufacturers to achieve batch-to-batch consistency previously unattainable through agricultural extraction. Mid-sized beverage brands are adopting these supply contracts to bypass capital-intensive in-house bioprocessing investments. The technology is automating quality control workflows and compressing time-to-market for reformulated product lines.
Health Canada's front-of-package nutrition symbol regulations are mandating explicit sugar disclosure on prepackaged foods, compelling reformulation across categories previously resistant to recipe modification. Canadian grocery retailers are tightening compositional standards for private-label products ahead of enforcement dates. Bakery and confectionery segments are responding fastest, accelerating pilot programs with multiple sweetener platforms to hedge against sensory rejection risks.
Direct sourcing partnerships between sweetener suppliers and food manufacturers are displacing traditional distributor intermediaries in the U.S. Great Lakes corridor. Large beverage processors are negotiating multi-year offtake agreements that bundle technical reformulation support with volume commitments. This pattern is most visible among Midwestern carbonated soft drink and ready-to-drink tea manufacturers seeking supply security amid raw material volatility.
North America High-Intensity Sweeteners Market Segmentation
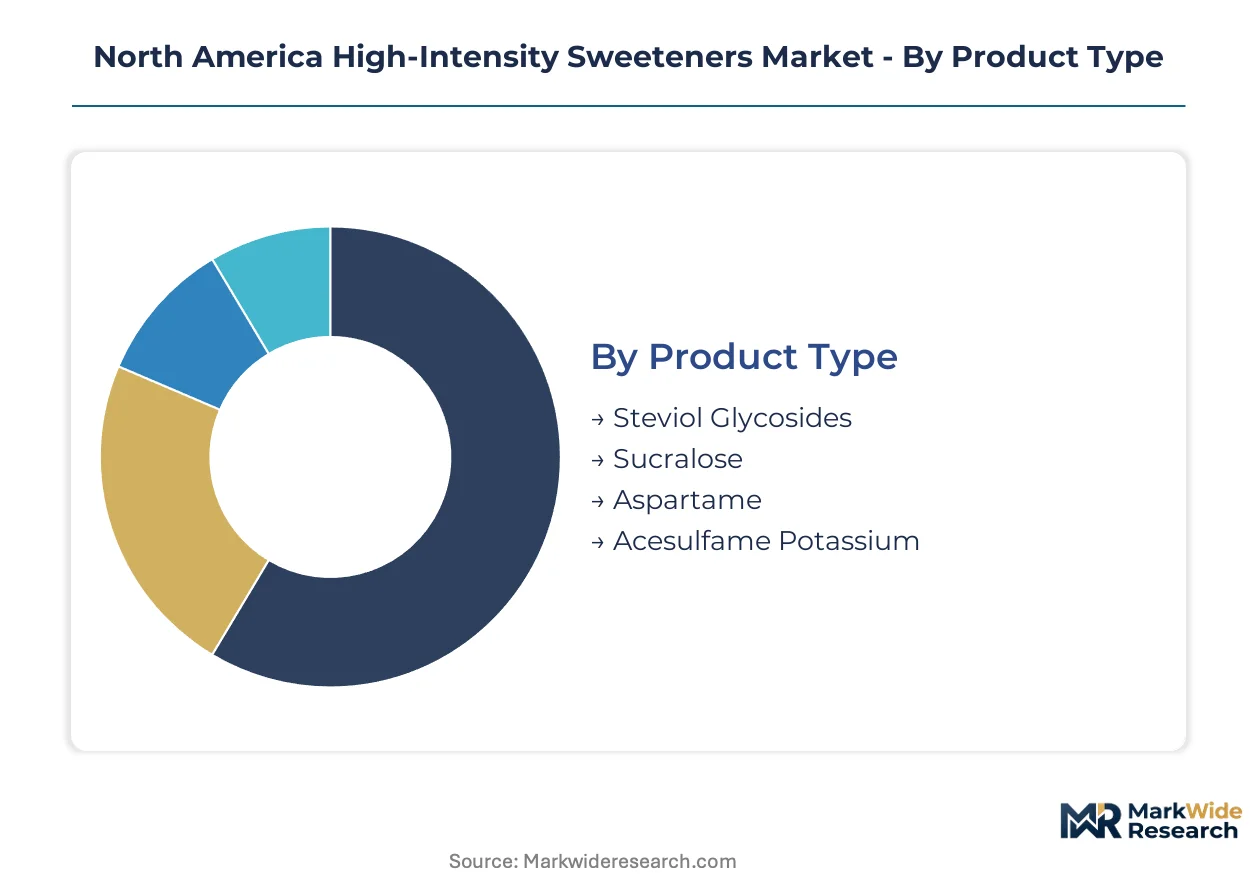
Segmentation reveals how procurement priorities diverge across the North American high-intensity sweeteners supply base. Reformulation timelines, thermal processing requirements, and clean-label positioning reshape demand patterns differently across each dimension.
Product Type:
Product substitution cycles accelerate as beverage and food manufacturers rebalance portfolios between natural extraction and synthetic chemistry platforms.
- Steviol Glycosides:Extracted from Stevia rebaudiana leaves through aqueous extraction or fermentation-derived Reb M and Reb D molecules. Demand concentrates in U.S. Midwest beverage bottlers responding to clean-label mandates from retail chains. Supply constraints from stevia leaf cultivation concentration in Paraguay and China expose processors to agricultural volatility.
- Sucralose:Chemically modified sucrose delivering 600x sweetness with exceptional thermal stability during UHT pasteurization. Procurement clusters in Ohio and Illinois carbonated soft drink facilities where hot-fill processing excludes natural alternatives. FDA GRAS status and decades of safety documentation sustain its position in reformulation-resistant applications.
- Aspartame:Methyl ester of the dipeptide of aspartic acid and phenylalanine, unstable at elevated temperatures requiring cold-process applications. Diet carbonated beverages and tabletop sweeteners in U.S. Northeast distribution corridors.
- Acesulfame Potassium:Calorie-free sulfonamide compound often blended with aspartame or sucralose to mask bitter aftertastes. Chewing gum and confectionery processors in Ontario and Quebec manufacturing zones.
Sucralose sits at the top of the volume ranking, with steviol glycosides climbing the fastest.
Application:
Application-driven procurement separates commodity-scale beverage contracts from specialized pharmaceutical and bakery formulations requiring technical service bundling.
- Beverages:Carbonated soft drinks, ready-to-drink teas, and flavored waters constitute the deepest procurement pool. Great Lakes manufacturing corridors generate dense demand from Michigan and Ohio bottling facilities. Health Canada front-of-package labeling accelerates Canadian reformulation programs.
- Bakery Products:Reduced-sugar cookies, cakes, and pastries face thermal stability barriers that historically excluded natural high-intensity alternatives. Maillard reaction interference and volume loss create formulation complexity.
- Dairy Products:Flavored yogurts and ice creams in U.S. upper Midwest dairy processing clusters. Cold-process applications favor aspartame and sucralose blends.
- Pharmaceuticals:Pediatric and geriatric drug delivery systems where palatability convergence with glycemic control drives amino acid-based sweetener adoption. FDA drug master file requirements extend procurement timelines.
Beverages command the largest procurement volumes, though pharmaceuticals are expanding most quickly.
End User:
End-user scale determines contract structure, with large manufacturers extracting multi-year supply security while smaller buyers face spot-market exposure.
- Food Manufacturers:Multi-billion-dollar bakery and confectionery processors negotiating bulk procurement contracts with embedded technical reformulation support. Long-term offtake agreements lock in pricing across agricultural commodity cycles.
- Beverage Companies:Carbonated soft drink and ready-to-drink tea formulators concentrated in Midwest manufacturing clusters. Direct sourcing partnerships displace distributor intermediaries.
- Retailers:Private-label grocery chains tightening compositional standards ahead of Canadian enforcement deadlines. Quality assurance teams vetting sweetener supplier documentation.
- Restaurants:Foodservice distributors supplying tabletop packets and fountain beverage systems. Lower volume procurement with higher logistics fragmentation.
Food manufacturers anchor procurement volumes, with retailers gaining share fastest on private-label expansion.
Form:
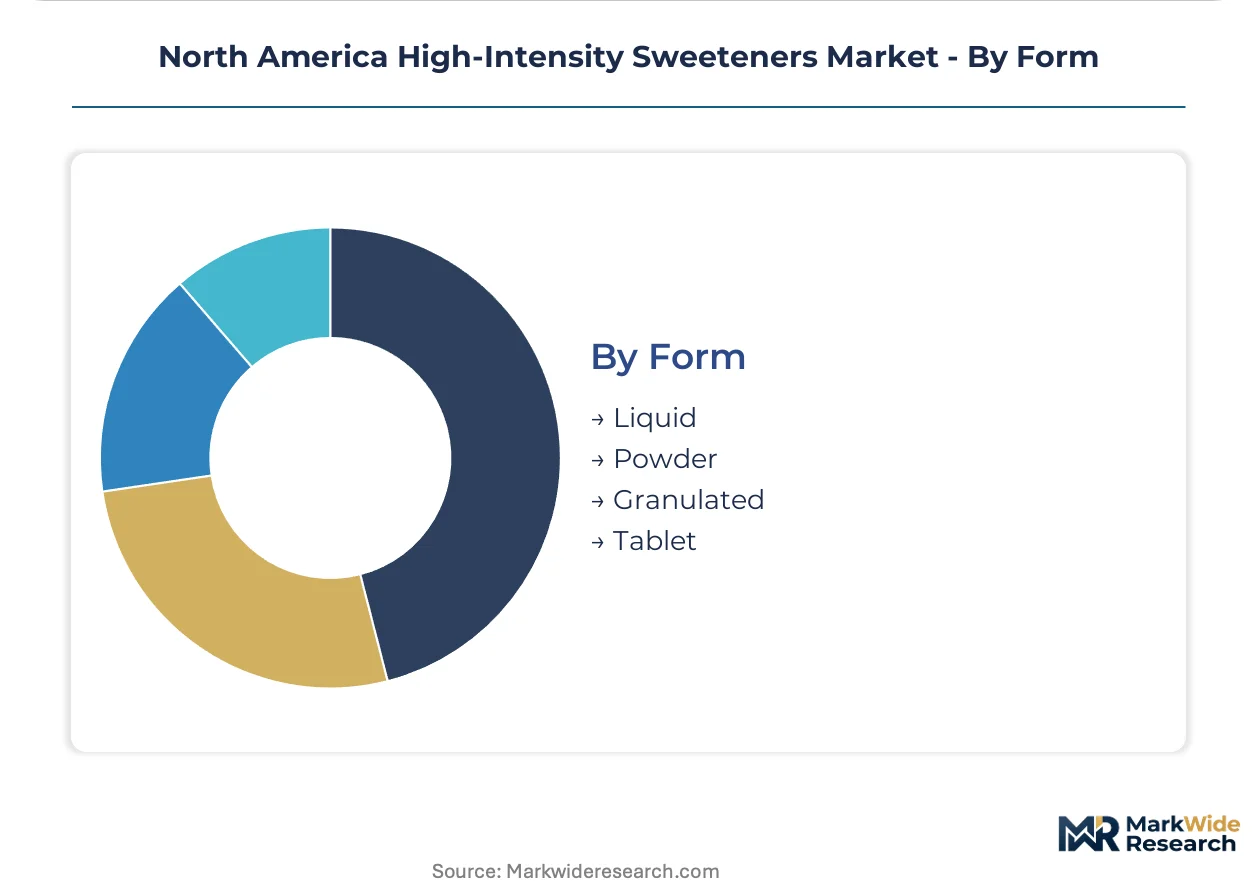
Form selection links to manufacturing process integration, with liquid and powder formats dominating industrial-scale procurement against tablet and granulated retail channels.
- Liquid:Concentrated solutions enabling precise dosing in automated beverage batching systems. Preferred by high-volume carbonated soft drink bottlers in automated production environments.
- Powder:Spray-dried formulations supporting dry-blend bakery and confectionery processing. Dominates Great Lakes food manufacturing procurement.
- Granulated:Free-flowing crystals mimicking sucrose handling characteristics for tabletop and small-scale foodservice applications.
- Tablet:Compressed single-serve units for foodservice tabletop dispensers and pharmaceutical unit-dose packaging.
Powder maintains volume leadership, with liquid formats climbing fastest on beverage automation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food and beverage formulation scientists cluster in the U.S. Great Lakes corridor and southern Ontario, anchoring North American sweetener demand. These technical workforces support reformulation programs across carbonated soft drink, bakery, and dairy processing facilities. Cross-border supply chains integrate procurement between Michigan, Ohio, Illinois, and Ontario manufacturing zones.
United States
Midwestern beverage bottlers in Michigan and Ohio drive concentrated procurement of thermal-stable sweeteners for hot-fill processing lines. FDA updated nutrition labeling requirements for added sugars compress reformulation timelines across bakery and carbonated soft drink portfolios. Chicago and St. Louis serve as distribution hubs where sweetener suppliers co-locate technical service teams with food manufacturer R&D facilities.
Canada
Health Canada's mandatory front-of-package nutrition symbol regulations accelerate sugar reduction programs in Toronto and Montreal food processing corridors. Provincial environmental frameworks in Ontario and Quebec govern fermentation facility emissions permits for steviol glycoside production. Quebec's specialized confectionery manufacturers in Granby and Saint-Hyacinthe expand clean-label reformulation pilots ahead of enforcement deadlines.
Mexico
Beverage concentrate formulators in Mexico City and Guadalajara supply North American export markets with reduced-sugar flavor systems. Mexican health authorities align processed food labeling standards with evolving U.S. and Canadian regulatory precedents. Monterrey's industrial chemical sector hosts toll manufacturing arrangements for high-intensity sweetener blending and packaging operations.
North America High-Intensity Sweeteners Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the North American high-intensity sweeteners supply base. Integrated agricultural processors with captive extraction infrastructure command volume positions in steviol glycoside supply. Specialty chemical houses and fermentation technology providers occupy differentiated niches. Dominant competitive moves include direct sourcing partnerships that displace distributor intermediaries, and bundled technical reformulation services that lock in multi-year supply agreements.
Among integrated agricultural processors, Cargill and Archer Daniels Midland Company exemplify the capital-intensive archetype with Midwest-based supply infrastructure. Tate & Lyle occupies a position within the specialty formulation services tier, while Ajinomoto Co., Inc. represents the amino acid-based chemistry specialization segment serving pharmaceutical applications.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill |
| Ingredion Incorporated |
| Tate & Lyle |
| International Flavors & Fragrances Inc. |
| Ajinomoto Co., Inc. |
| Roquette |
| Sweegen |
| Heartland |
| Others |
Value Network & Pricing Analysis
Stevia leaf agricultural inputs cascade through extraction and fermentation processing tiers before reaching beverage manufacturer procurement desks, with Paraguayan and Chinese cultivation concentration transmitting cost volatility into North American contract pricing structures.
Pricing Analysis
Bundled technical reformulation services command premiums over unbundled commodity sweetener supply across North American procurement contracts. Three-tier pricing structure across premium fermentation-derived glycosides, standard extraction-based stevia, and economy synthetic alternatives separates quality grades. Cost compression in mid-tier steviol glycoside supply is intensifying because bioprocess automation expands accessible production capacity. Private-label grocery retailers exhibit highest price sensitivity due to thin margin structures, while pharmaceutical formulators show lowest sensitivity given regulatory compliance premiums.
Supply Chain Analysis
Regional distribution centers in Chicago and St. Louis anchor hub-and-spoke patterns serving Great Lakes manufacturing corridors. Stevia leaf supply concentrates in Paraguay, China, and select Indian growing regions, while synthetic sweetener production clusters in the United States and China. Raw material dependencies span stevia leaf biomass, corn-derived fermentation feedstocks, and chlorinated sucrose precursors. Single-source vulnerability in stevia leaf supply exposes North American processors to climate-driven crop failures. Distribution runs through direct sourcing partnerships that displace traditional distributor intermediaries among large beverage processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
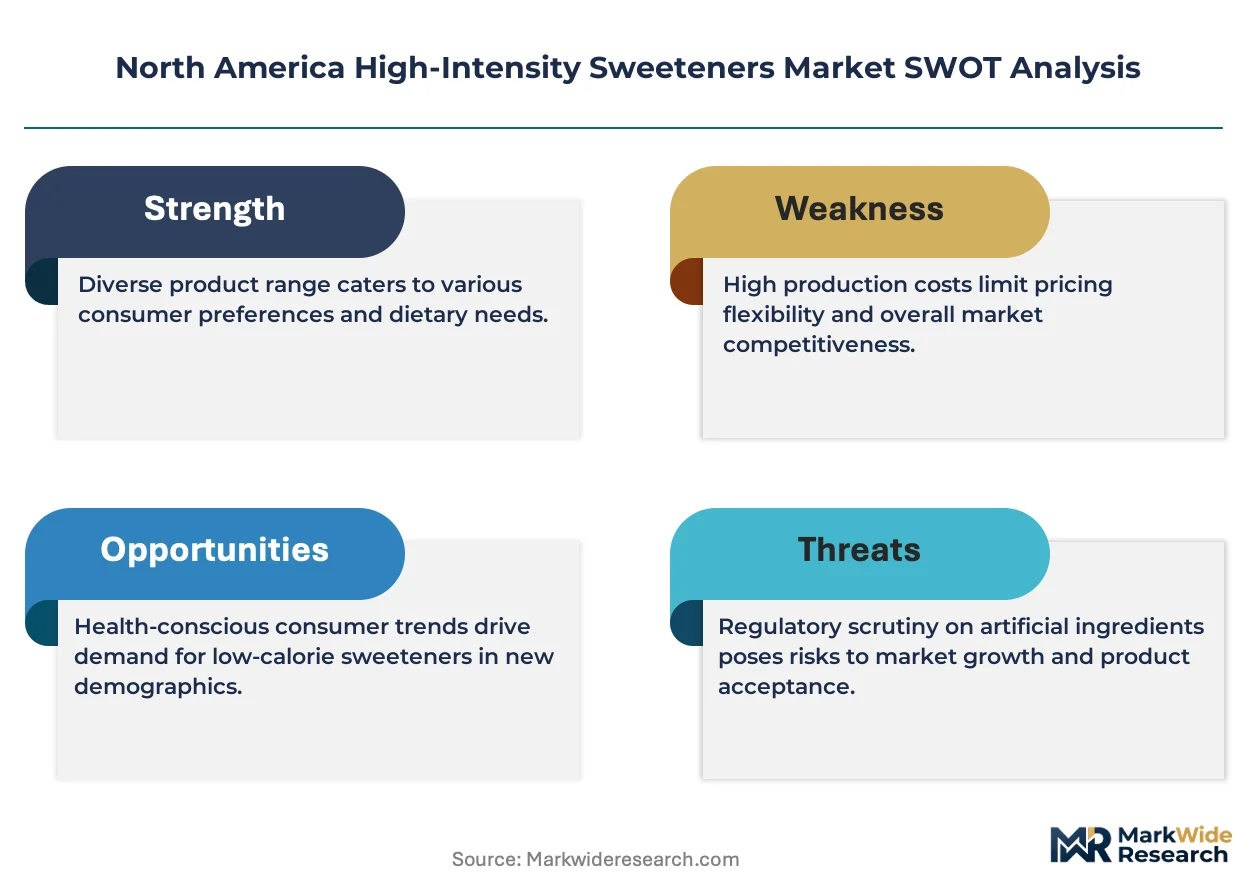
This market functions as a regulatory compounder where Health Canada's front-of-package nutrition symbol enforcement accelerates reformulation demand across Canadian food processing corridors.
For Market Incumbents: Lock in multi-year offtake agreements with Great Lakes beverage bottlers before fermentation capacity expansion floods mid-tier supply. Secure backward integration into stevia leaf cultivation through direct agricultural partnerships in Paraguay to neutralize raw material volatility. Defend margin position by embedding proprietary sensory-matching expertise into technical service bundles that raise switching costs for food manufacturers.
For New Entrants and Emerging Players: E-commerce-enabled direct sourcing platforms offer the lowest-friction entry path into mid-sized bakery and confectionery processor segments. Target clean-label reformulation pilots in Quebec's specialized confectionery manufacturing zones where incumbent technical service coverage remains thin. Pursue toll manufacturing arrangements with Monterrey-based industrial chemical facilities to bypass capital-intensive production asset requirements.
For Investors and Strategic Acquirers: Consolidation pressure builds where fermentation technology providers lack downstream formulation capabilities to capture full value from steviol glycoside production. Acquisition targets with integrated bioprocessing and sensory science teams present strongest long-term viability given reformulation complexity barriers. Watch FDA GRAS determination timelines for novel amino acid-based sweeteners as inflection indicators for next-generation chemistry platform viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Automated bioprocessing infrastructure in Midwest corridors reduces unit costs for steviol glycoside supply. |
| Direct Sourcing Partnership Expansion | Multi-year offtake agreements with beverage manufacturers displace distributor intermediaries and lock volume. |
| Sensory Science Capability Buildout | Reformulation expertise bundling raises switching costs and differentiates commodity sweetener supply. |
| Provincial Environmental Permit Positioning | First-mover fermentation facility approvals in Ontario and Quebec create regulatory moats for bioprocessing assets. |
| Pharmaceutical Sweetener Platform Development | Amino acid-based chemistry specialization penetrates pediatric and geriatric drug delivery applications. |
Research Methodology
Direct dialogue with beverage formulation scientists, food manufacturer procurement directors, fermentation facility operations managers, and Health Canada regulatory affairs specialists grounded qualitative findings. Primary insights combined with secondary validation from FDA GRAS notification databases, Health Canada food labeling guidance documents, U.S. customs trade data on stevia extract imports, and SEC filings from integrated agricultural processors. Bottom-up procurement volume modeling and top-down market sizing triangulated demand estimates across the analysis window.
Segmentation outputs span product type chemistry platforms, application thermal processing requirements, end-user scale tiers, and geographic manufacturing cluster density. CAGRs derived from trend extrapolation of reformulation program adoption curves, regulatory enforcement timeline impacts, and bioprocess cost reduction trajectories. Forecast inputs incorporated Health Canada front-of-package labeling compliance deadlines and FDA nutrition labeling update implementation phases.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation-derived glycosides would alter the outlook if batch consistency or cost targets fail to materialize. Forecasts reflect documented assumptions about regulatory enforcement timing and agricultural input cost stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Natural Sweetener Blends Market
Sweeteners
North America Starch Sweetener Market
Sweeteners
Beetroot Molasses Market
Sweeteners
India Food Sweetener Market
Sweeteners
Asia-Pacific Stevia Market
Sweeteners
Sorbitol Market
Sweeteners
D Psicose Market
Sweeteners
Saudi Arabia Allulose Market
Sweeteners
Stevia Mints Market
Sweeteners
Maltodextrin Market
Sweeteners
Isomaltooligosaccharide Market
Sweeteners
Asia Pacific Food Sweetener Market
Sweeteners
High-Intensity Sweeteners Market
Sweeteners
Europe Food Sweetener Market
Sweeteners
Trehalose Market
Sweeteners
Tagatose Market