
 South America Stevia Market | 2026-2036
South America Stevia Market Size, Share, and Industry Trends Forecast 2026-2036
South America Stevia Market Analytics
Agronomic expertise in steviol glycoside cultivation is collapsing across Paraguay and Colombia, constraining raw material expansion for downstream processors. Cargill Incorporated leverages its existing South American commodity infrastructure to secure leaf supply contracts ahead of competitors. Ingredion Incorporated anchors its position through specialized extraction partnerships with regional cooperatives. GLG Life Tech Corp competes on Reb-A purity grades, differentiating its output for premium beverage contracts.
Stevia denotes a genus of perennial shrubs native to South America whose leaves contain steviol glycosides—primarily rebaudioside A and stevioside—extracted through aqueous processing and purified to sweetness intensities 200-350 times that of sucrose. Powder formulations dominate current volume flows, reflecting their stability in dry-blend manufacturing and extended shelf life in tropical distribution conditions. Liquid extract segments are gaining traction among beverage producers seeking simplified batch integration, while leaf and granulated sugar variants occupy niche positions in health food retail channels.
ANVISA governs stevia's food additive status in Brazil, while Argentina's national food regulator and Peru's health authority maintain aligned but distinct purity thresholds that shape cross-border formulation requirements. These frameworks determine which glycoside concentrations qualify for clean-label claims, directly influencing manufacturer procurement specifications and product positioning strategies. Stakeholders must monitor evolving Mercosur harmonization discussions, as regulatory convergence would reshape competitive access across the trade bloc's integrated production networks.
Market Dynamics
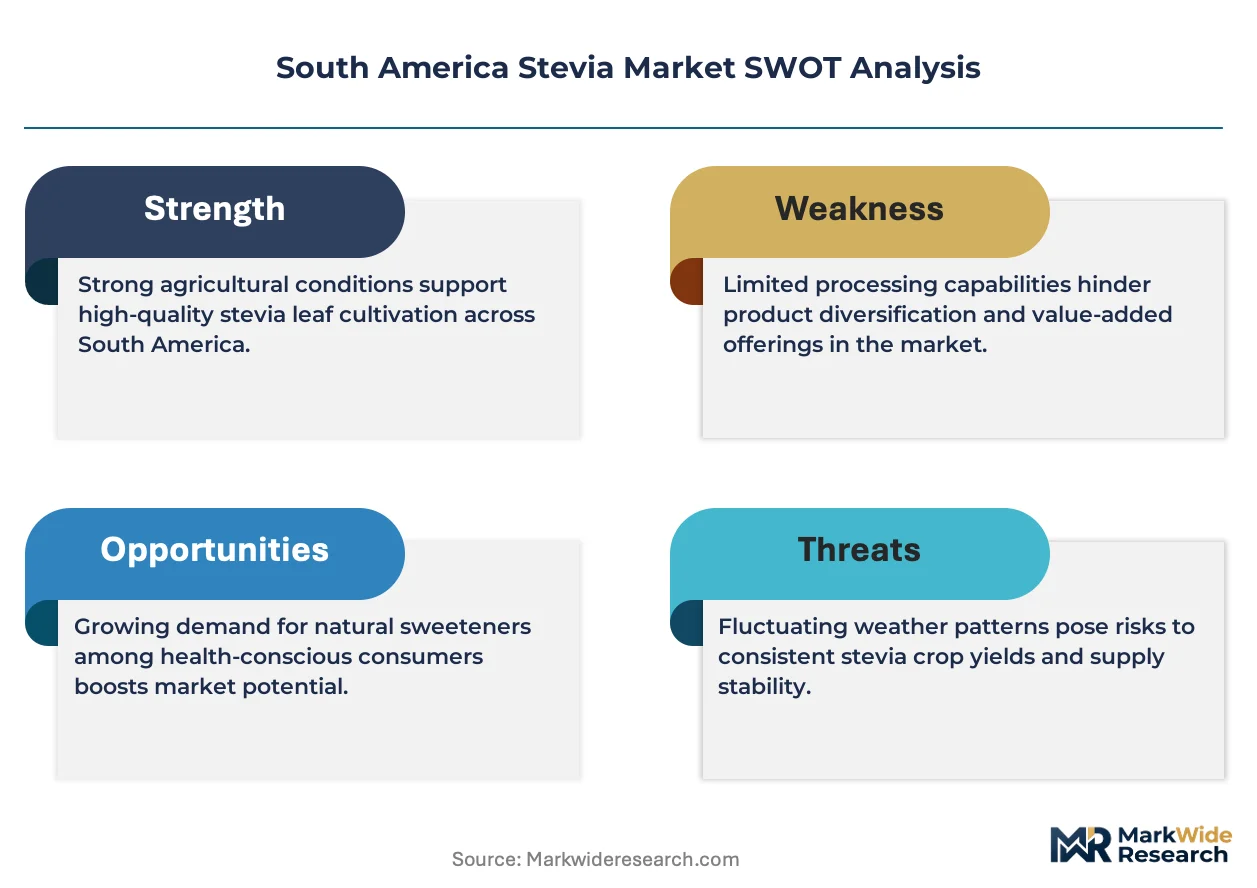
ANVISA's streamlined approval pathways for natural sweeteners are compressing time-to-market for reformulated products, while agronomic expertise collapse in Paraguay and Colombia constrains leaf supply expansion for Brazilian and Argentine processors.
Growth Catalysts
- ANVISA Additive Guidelines:Brazil's updated food additive framework accelerates clean-label certification timelines, enabling faster product launches for beverage manufacturers in São Paulo's manufacturing corridor.
- Beverage Reformulation Mandates:Sugar reduction targets across Mercosur trade bloc markets pull stevia into carbonated soft drinks, ready-to-drink teas, and functional waters at industrial scale.
- Reb-A Purification Advances:Aqueous extraction improvements yield higher-purity glycoside outputs, satisfying premium contract specifications from multinational bottlers operating in southeastern Brazil.
Market Restraints
- Leaf Supply Concentration:Raw material sourcing clusters disproportionately in Paraguay's eastern growing regions, exposing processors to climate volatility and single-origin disruption risk.
- Input Cost Volatility:Steviol glycoside extraction requires substantial water and energy inputs, with electricity pricing fluctuations in Argentina's industrial zones compressing processor margins.
- Technical Bitterness Thresholds:Stevia's lingering aftertaste in certain glycoside ratios limits substitution depth in confectionery applications, capping addressable share against aspartame and sucralose.
Strategic Opportunities
- Peru Health Authority Alignment:Regulatory convergence discussions between Peru's health authority and ANVISA create pathway for unified Mercosur labeling standards, reducing cross-border formulation complexity.
- Liquid Extract Channels:Beverage producers seeking simplified batch integration are shifting procurement toward liquid stevia formats, opening specialized distribution partnerships with Argentine bottling cooperatives.
- Colombian Cultivation Recovery:Agronomic training programs in Colombia's Andean growing regions could restore leaf supply diversity, enabling processor expansion beyond current Paraguay-Brazil supply axis.
Industry Challenges
- Glycoside Grading Expertise Gap:Regional laboratories lack standardized rebaudioside A testing capacity, forcing Brazilian processors to outsource quality verification to third-party facilities in São Paulo.
- Extraction Facility Capex Burden:Aqueous purification infrastructure demands substantial capital deployment, limiting mid-scale processor entry and consolidating advantage among established commodity traders with existing South American infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Stevia Market |
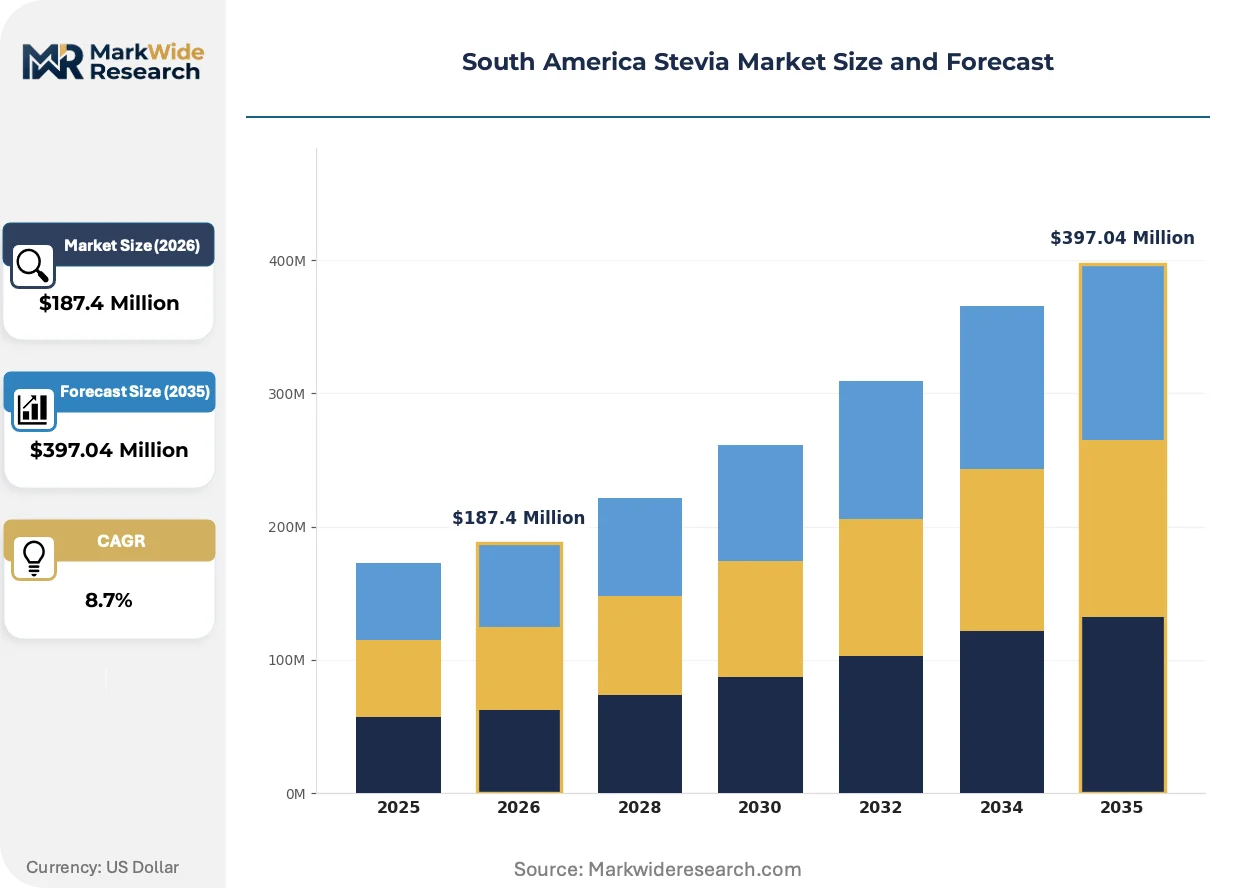
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extract, Powder, Granulated Sugar, Leaf Application: Beverages, Bakery Products, Dairy, Confectionery End User: Food Manufacturers, Beverage Producers, Health Food Stores, Restaurants Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Cargill Incorporated, Tate & Lyle PLC, Archer Daniels Midland Company, GLG Life Tech Corp, Ingredion Incorporated, Tereos Pure Circle Solutions, HYET Sweet, Evolva Holding SA, Stevia First Corporation, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Stevia Market Evolving Landscape
Enzymatic bioconversion methods are transforming steviol glycoside production economics, while regulatory harmonization efforts and procurement centralization reshape competitive access across the continent's integrated production networks.
Enzymatic bioconversion technology is displacing traditional solvent-based extraction in high-capacity processing facilities. Brazilian beverage conglomerates operating in Minas Gerais and Rio de Janeiro states are adopting bioconverted Reb-M and Reb-D variants at accelerating pace. This molecular modification pathway is displacing conventional stevioside-dominant formulations in premium reduced-sugar product lines, compressing demand for lower-purity leaf inputs.
ANVISA's alignment with Mercosur technical standards on natural sweetener purity thresholds is reshaping cross-border formulation requirements. The regulatory convergence reduces compliance duplication for multinational producers operating simultaneous production lines in Brazil and Argentina. Clean-label claim eligibility now hinges on unified glycoside concentration benchmarks, forcing reformulation adjustments in Paraguayan toll processing facilities serving both markets.
Direct contracting between beverage manufacturers and regional agricultural cooperatives is consolidating procurement relationships previously mediated by commodity traders. Argentine wine and soft drink producers in Mendoza's industrial cluster now source leaf supply through specialized extraction partnerships rather than spot market purchases. This channel compression is most visible in Brazil's southeastern manufacturing corridor, where food and beverage clusters dominate procurement specifications and lock in multi-year supply agreements.
South America Stevia Market Segmentation
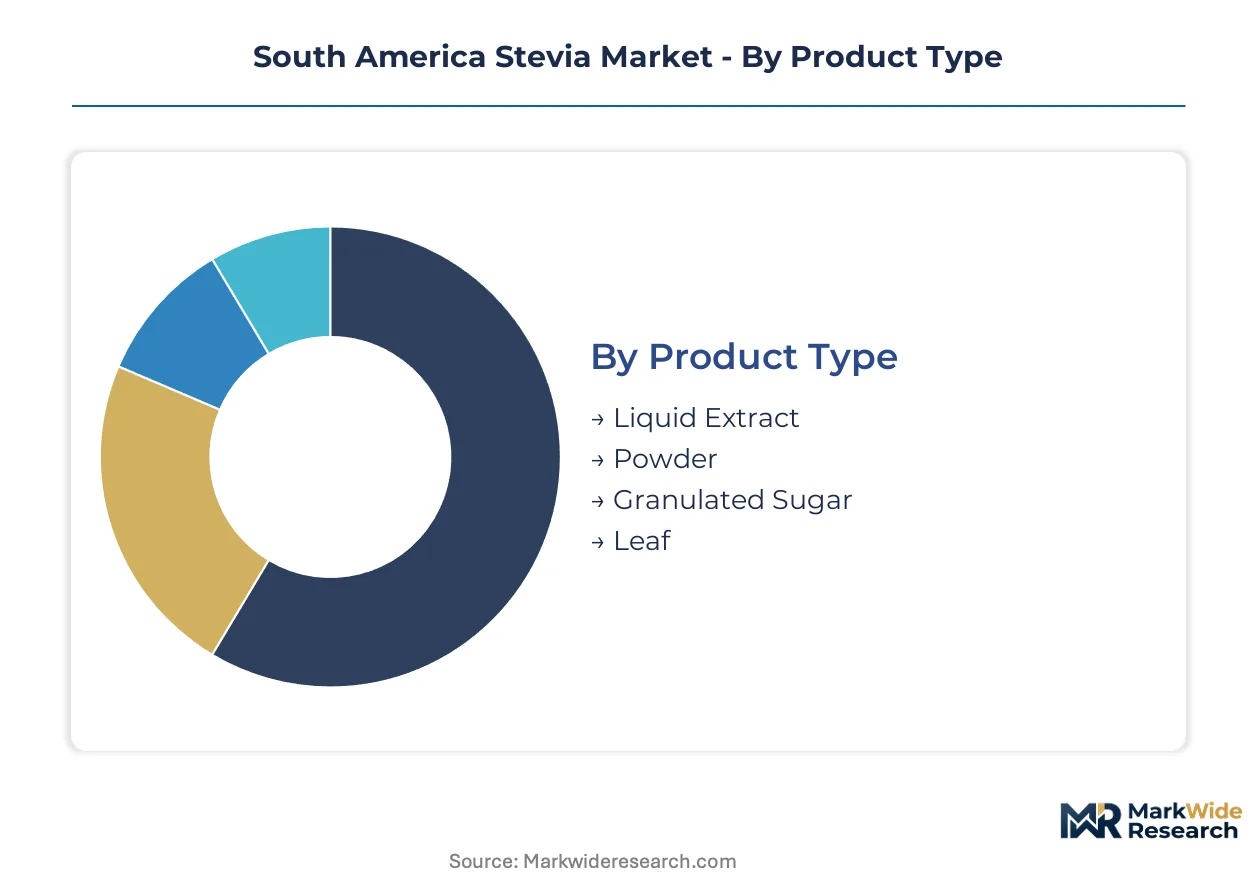
Stevia procurement patterns across South America diverge sharply between domestic formulation needs and export-oriented processing. Segment boundaries reflect raw material sourcing constraints, regulatory purity thresholds, and the concentration of beverage manufacturing in Brazil's southeastern corridor.
Product Type:
Powder formulations dominate domestic procurement across Brazil and Argentina, while liquid extract volumes concentrate in export channels serving multinational bottlers.
- Powder:Dry-blend stability and extended shelf life under tropical distribution conditions make this the default specification for São Paulo's food and beverage clusters. Brazilian manufacturers prioritize powder for its compatibility with existing dry-mix infrastructure and reduced handling complexity in high-humidity environments.
- Liquid Extract:Aqueous solutions enable simplified batch integration for beverage producers seeking streamlined production workflows. Argentine bottling cooperatives in Mendoza's industrial cluster are shifting procurement toward liquid formats to reduce reformulation time and minimize glycoside degradation during processing.
- Granulated Sugar:Crystal formulations occupy niche positions in health food retail channels across urban Brazil.
- Leaf:Unprocessed dried leaf serves traditional consumption patterns and small-scale regional markets in Paraguay.
Powder holds the largest share; momentum sits with liquid extract.
Application:
Cost tier differentiation separates premium glycoside grades for beverages from standard specifications in baked goods and confectionery.
- Beverages:Carbonated soft drinks, ready-to-drink teas, and functional waters absorb the highest-purity Reb-A and Reb-M outputs. ANVISA's clean-label certification timelines accelerate adoption as Brazilian conglomerates reformulate sugar-reduced product lines for Mercosur markets.
- Bakery Products:Heat-stable glycoside blends address thermal degradation challenges in oven-processed applications. Argentine processors serving Buenos Aires manufacturing corridors specify modified stevia formulations that maintain sweetness intensity through Maillard reaction temperatures.
- Dairy:Fermented product applications require glycoside ratios that mask bitterness in acidic pH environments.
- Confectionery:Technical aftertaste thresholds limit substitution depth against aspartame and sucralose in premium chocolate segments.
Beverages command premium pricing tiers; dairy and confectionery face formulation barriers.
End User:
Volume concentration tracks procurement centralization among large-scale manufacturers versus fragmented health food retail demand.
- Food Manufacturers:Industrial-scale buyers in Brazil's southeastern manufacturing corridor lock in multi-year supply agreements with regional cooperatives. Direct contracting displaces spot market purchases as Cargill and Ingredion leverage existing commodity infrastructure to secure leaf supply ahead of competitors.
- Beverage Producers:Multinational bottlers operating simultaneous production lines in Brazil and Argentina drive unified glycoside concentration benchmarks. ANVISA-Mercosur regulatory convergence reduces compliance duplication for cross-border formulation requirements.
- Health Food Stores:Specialty retail channels in São Paulo and Rio de Janeiro absorb smaller granulated and leaf formats.
- Restaurants:Foodservice procurement remains fragmented across independent operators with limited specification consistency.
Food manufacturers anchor volume; beverage producers are expanding most quickly.
Distribution Channel:
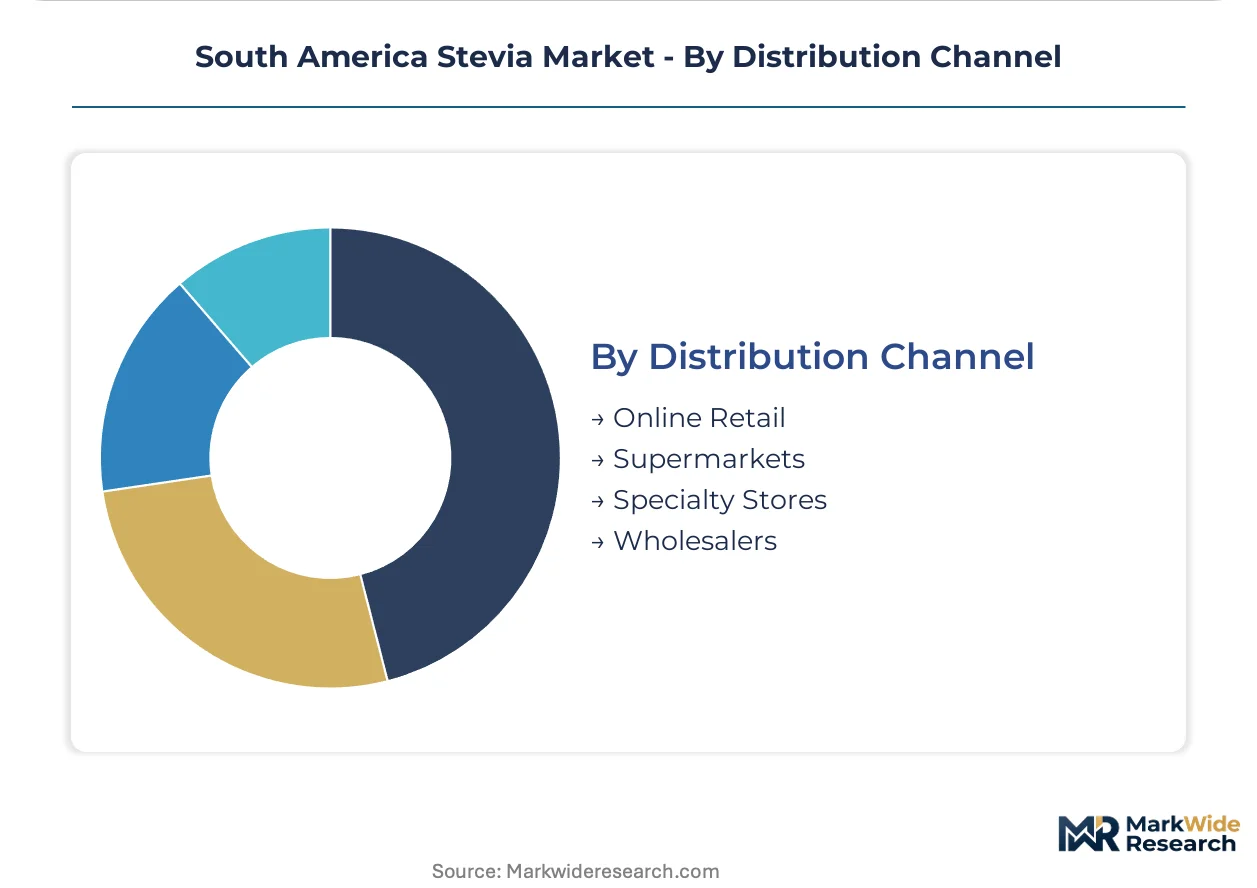
Supply chain configuration separates bulk industrial procurement through wholesalers from branded retail flows via supermarkets and online platforms.
- Wholesalers:Industrial processors and beverage manufacturers source through specialized extraction partnerships and commodity traders with established South American infrastructure. Cargill's existing regional networks consolidate advantage in bulk leaf and intermediate glycoside distribution.
- Supermarkets:Packaged consumer formats reach retail shelves through Brazil's dominant grocery chains in southeastern urban centers.
- Specialty Stores:Health food retailers in Argentina's Mendoza cluster and Peru's Lima metropolitan area serve premium organic and clean-label segments.
- Online Retail:Direct-to-consumer channels remain underdeveloped for stevia-specific procurement, with general e-commerce platforms absorbing limited specialized demand.
Wholesalers capture industrial volume; specialty stores show steepest expansion trajectory in premium segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA steers regulatory direction for natural sweeteners across Brazil's southeastern manufacturing corridor, where beverage reformulation drives procurement concentration. Argentina and Paraguay anchor raw material flows, while Peru and Colombia present expansion vectors for diversified leaf supply.
Brazil
São Paulo's food and beverage clusters absorb the majority of high-purity Reb-A and Reb-M outputs for carbonated soft drink reformulation. ANVISA's streamlined additive approval pathways compress clean-label certification timelines for multinational bottlers operating simultaneous production lines. Minas Gerais and Rio de Janeiro states host enzymatic bioconversion facilities displacing conventional extraction methods.
Argentina
Mendoza's industrial cluster shifts procurement toward liquid extract formats to reduce reformulation time in wine and soft drink production. The national food regulator maintains aligned but distinct purity thresholds from ANVISA, shaping cross-border formulation requirements for processors serving both markets. Buenos Aires manufacturing corridors specify heat-stable glycoside blends for bakery applications.
Paraguay
Eastern growing regions concentrate raw material sourcing, exposing processors to climate volatility and single-origin disruption risk. Agronomic expertise collapse constrains leaf supply expansion for downstream Brazilian and Argentine processors. Small-scale regional markets sustain traditional dried leaf consumption patterns outside industrial channels.
Peru
Lima's metropolitan area health food retailers serve premium organic and clean-label segments through specialty store channels. The national health authority participates in Mercosur harmonization discussions with ANVISA, creating pathways for unified labeling standards. Regulatory convergence would reduce compliance duplication for multinational producers.
Colombia
Andean growing regions present recovery potential through agronomic training programs aimed at restoring leaf supply diversity. Current constraints limit processor expansion beyond the Paraguay-Brazil supply axis. Colombian cultivation recovery would enable supply chain resilience against concentrated sourcing risks.
South America Stevia Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with commodity traders leveraging existing South American infrastructure to secure supply contracts ahead of extraction-focused competitors. The market structures around aqueous purification capabilities and glycoside grading expertise, with capital-intensive facility requirements limiting mid-scale processor entry. Three archetypes dominate: integrated commodity traders with regional logistics networks, specialized extraction partnerships with agricultural cooperatives, and premium purity specialists competing on Reb-A concentration grades. Capacity expansion and direct contracting with regional cooperatives constitute the primary competitive moves, displacing spot market purchases with multi-year supply agreements.
Within the integrated commodity tier, Cargill Incorporated and Ingredion Incorporated exemplify players leveraging established South American infrastructure to anchor bulk procurement relationships. Cargill's existing regional networks consolidate advantage in leaf supply and intermediate glycoside distribution, while Ingredion positions through specialized extraction partnerships with regional cooperatives. GLG Life Tech Corp occupies a position among purity-grade specialists, differentiating output for premium beverage contracts based on Reb-A concentration benchmarks.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Tate & Lyle PLC |
| Archer Daniels Midland Company |
| GLG Life Tech Corp |
| Ingredion Incorporated |
| Tereos Pure Circle Solutions |
| HYET Sweet |
| Evolva Holding SA |
| Stevia First Corporation |
| Others |
Value Network & Pricing Analysis
Leaf-to-extract lead times stretching 90-120 days in Paraguay's eastern growing regions concentrate pricing power among processors with established South American commodity infrastructure, while inventory carrying costs in Brazil's southeastern manufacturing corridor compress margins for mid-scale entrants lacking direct cooperative contracts.
Pricing Analysis
Price spreads between São Paulo's beverage clusters and Mendoza's bottling cooperatives reflect three-tier pricing structure across premium, standard, and economy levels, with Reb-A purity grades and ANVISA clean-label certification status driving differentiation. Cost compression in standard-grade powder formulations is intensifying because enzymatic bioconversion facilities in Minas Gerais are displacing conventional extraction capacity. Food manufacturers in Brazil's southeastern corridor exhibit lowest price sensitivity due to multi-year supply agreements, while health food retailers in Lima's metropolitan area face acute margin pressure from fragmented procurement volumes.
Supply Chain Analysis
Inventory buffers of 45-60 days at Argentine processors hinge on concentrated leaf sourcing from Paraguay's eastern regions and Brazil's southeastern corridor, with Colombian Andean cultivation remaining underdeveloped. Aqueous extraction infrastructure draws from substantial water and energy inputs, with electricity pricing volatility in Argentina's industrial zones feeding into processor cost structures. Single-origin vulnerability from Paraguay's climate exposure constitutes the dominant structural risk. Distribution runs through specialized extraction partnerships and commodity traders with established South American networks, consolidating bulk procurement relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across glycoside grading expertise, regional regulatory frameworks, and cultivation recovery timelines creates multiple entry niches for specialists targeting ANVISA-Mercosur convergence arbitrage and Colombian supply diversification.
For Market Incumbents: Fortify leaf supply security through backward integration into Paraguayan cooperative contracts and Colombian agronomic training programs ahead of cultivation recovery. Expand aqueous purification capacity in Rio de Janeiro state to capture enzymatic bioconversion demand from beverage conglomerates reformulating for Mercosur sugar reduction mandates. Lock in multi-year agreements with São Paulo manufacturing clusters before regulatory harmonization commoditizes cross-border formulation advantages.
For New Entrants and Emerging Players: Differentiate on Reb-M and Reb-D bioconversion capabilities targeting premium beverage contracts in Minas Gerais and Rio de Janeiro states. Target Peru's health food retail segment through specialty store channels in Lima's metropolitan area, where organic and clean-label positioning commands pricing premiums absent from Brazilian commodity flows. Pursue direct contracting with Colombian Andean cooperatives as cultivation recovery restores supply diversity beyond the Paraguay-Brazil axis.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-convergence play because ANVISA-Mercosur harmonization will reshape competitive access across integrated production networks. Acquisition targets should emphasize processors with established aqueous purification infrastructure and cooperative relationships in Paraguay or Colombia. Monitor enzymatic bioconversion adoption rates among Brazilian beverage conglomerates as the inflection indicator for premium glycoside demand shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Leaf Supply | Captures margin from Paraguayan cultivation before Colombian recovery diversifies sourcing. |
| Enzymatic Bioconversion Capacity Buildout | Positions processors for Reb-M and Reb-D demand from Minas Gerais beverage clusters. |
| ANVISA Clean-Label Certification Investment | Accelerates market access for reformulated products in São Paulo's manufacturing corridor. |
| Colombian Cooperative Partnership Development | Builds supply resilience against climate volatility in Paraguay's eastern growing regions. |
| Liquid Extract Distribution Channel Expansion | Aligns with Argentine bottling cooperatives shifting procurement toward simplified batch integration. |
Research Methodology
Initial hypotheses were tested against primary input from extraction facility operators, beverage procurement directors, agricultural cooperative managers, and ANVISA regulatory affairs specialists, and refined through secondary validation across customs records, ANVISA additive guideline filings, Mercosur technical standard harmonization documents, and SEC disclosures from integrated commodity traders. Bottom-up volume estimates from regional processing capacity and top-down demand projections from beverage reformulation mandates were triangulated to constrain forecast variance.
Variance decomposition across product type, application, end user, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macroeconomic drivers and industry-specific inputs including enzymatic bioconversion adoption curves and ANVISA-Mercosur regulatory convergence timelines. Modeled outputs incorporate glycoside purity grade substitution elasticities and leaf supply concentration risk premiums.
Material uncertainties — agronomic expertise recovery in Colombia, electricity pricing volatility in Argentina's industrial zones, and Mercosur harmonization implementation delays — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory timelines and cultivation expansion trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Saccharin Market
Sweeteners
Middle East and Africa Plant-Derived and Synthetic Sugar Market
Sweeteners
Italy Food Sweetener Market
Sweeteners
Xylitol Injection Market
Sweeteners
Sugar Free Lifesavers Market
Sweeteners
Agave Syrup Market
Sweeteners
Middle East and Africa Sugar Substitutes Market
Sweeteners
Japan Allulose Market
Sweeteners
Maltodextrin Market
Sweeteners
Maltol and Ethyl Maltol Market
Sweeteners
Granulated Sugar Market
Sweeteners
Dry Molasses Market
Sweeteners
Rare Sugar Market
Sweeteners
Australia Food Sweetener Market
Sweeteners
Specialty Sweeteners Market
Sweeteners
Smoked Sugar Market